
 Global Crude Sulfate Turpentine Market | 2026-2036
Global Crude Sulfate Turpentine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crude Sulfate Turpentine Market Foresight
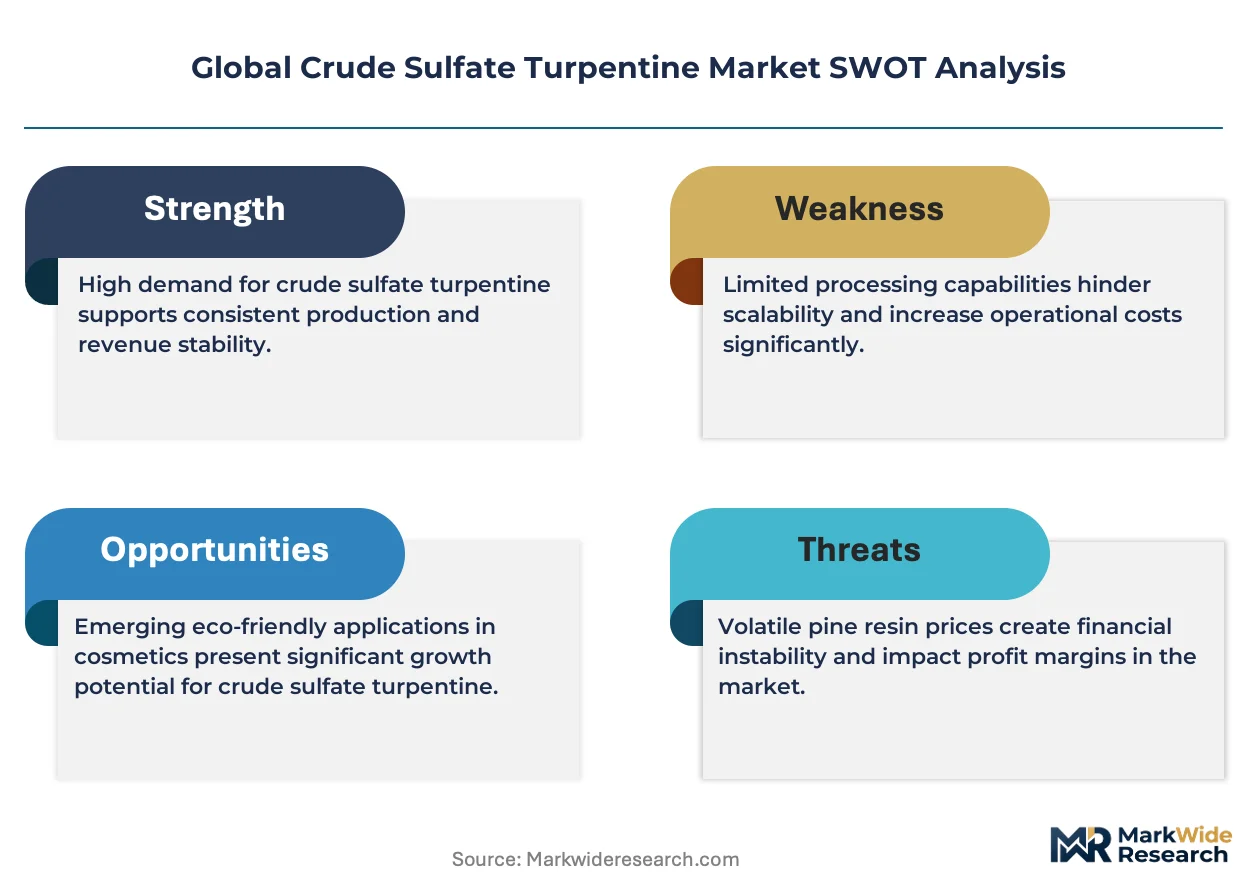
Modular refining configurations separating alpha-pinene and beta-pinene at source are realigning buyer choice across derivative markets. Kraton Corporation leverages captive sulfate turpentine streams from pulp integration to sustain downstream terpene resin supply security. Georgia-Pacific Chemicals anchors Gulf Coast production scale, while Ingevity Corporation specializes in high-purity fractionation for fragrance and flavor applications. DRT competes through European distillation assets serving continental solvent demand.
Crude sulfate turpentine is a volatile organic liquid recovered as by-product from the kraft pulping process, typically containing 30-60% alpha-pinene, 20-35% beta-pinene, and trace camphene and limonene fractions, with specific gravity ranging 0.86-0.88 and boiling point 150-170°C, serving primarily as feedstock for fragrance chemicals, pine oil derivatives, and synthetic resins. Light crude sulfate turpentine dominates volume flows due to lower processing burden and broader solvent compatibility, while refined sulfate turpentine commands margin concentration in fragrance industry channels where purity specifications exceed 95% terpene content. Fractional distillation capacity expansion is accelerating in proximity to integrated pulp mills, as vacuum distillation routes face energy cost pressures limiting geographic transferability.
EPA volatile organic compound regulations under the Clean Air Act constrain solvent-grade turpentine formulation in United States architectural coatings, while REACH registration requirements in Europe mandate full substance characterization for chemical intermediate applications. FDA oversight of fragrance material safety influences United States pharmaceutical and cosmetic sector qualification protocols for refined grades. Stakeholders must monitor pulp mill closure cycles and biorefinery conversion timelines, as sulfate turpentine supply elasticity remains tethered to kraft paper demand trajectories with limited standalone production economics.
Market Dynamics
Kraft pulp mill consolidation in the southeastern United States is concentrating crude sulfate turpentine supply under fewer integrated operators, tightening feedstock access for standalone refiners and reshaping downstream contracting terms.
Growth Catalysts
- Synthetic fragrance chemical demand:Personal care and household product manufacturers are expanding alpha-pinene derivative procurement for aroma compound synthesis, pulling refined sulfate turpentine volumes into higher-margin channels.
- REACH substance characterization:European chemical intermediate registration requirements are filtering out non-compliant suppliers, consolidating qualified refiner positions across continental solvent markets.
- Modular fractionation deployment:Vacuum distillation units installed at pulp mill sites are reducing transport costs and enabling real-time alpha-pinene and beta-pinene separation for derivative-specific sales.
Market Restraints
- Kraft pulp demand cyclicality:Containerboard and tissue production downturns directly compress sulfate turpentine by-product availability, creating supply elasticity without standalone production economics.
- EPA VOC thresholds:Clean Air Act limits on volatile organic compound content in architectural coatings are constraining solvent-grade turpentine formulation volumes in United States construction chemicals.
- Petroleum-derived terpene substitution:Synthetic pinene from crude oil cracking competes on price stability, particularly in adhesive and rubber processing applications where purity tolerances permit.
Strategic Opportunities
- Brazilian pulp capacity expansion:Suzano and other kraft producers in Mato Grosso do Sul are commissioning integrated turpentine recovery systems, creating new Atlantic basin supply nodes for export-oriented refiners.
- Biobased solvent mandates:United States federal procurement preferences under the BioPreferred program are opening institutional purchasing channels for pine oil derivatives in cleaning and degreasing applications.
- Pharmaceutical-grade limonene extraction:Supercritical CO2 processing of crude sulfate turpentine camphene fractions is converging with chiral chemistry demand for drug synthesis precursors.
Industry Challenges
- Distillation energy cost escalation:Vacuum fractionation operations face margin compression from natural gas price volatility, particularly for European refiners dependent on spot LNG procurement.
- FDA fragrance allergen documentation:Cosmetic and pharmaceutical sector qualification protocols require extensive toxicological dossiers, extending sales cycle timelines for refined grade market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crude Sulfate Turpentine Market |
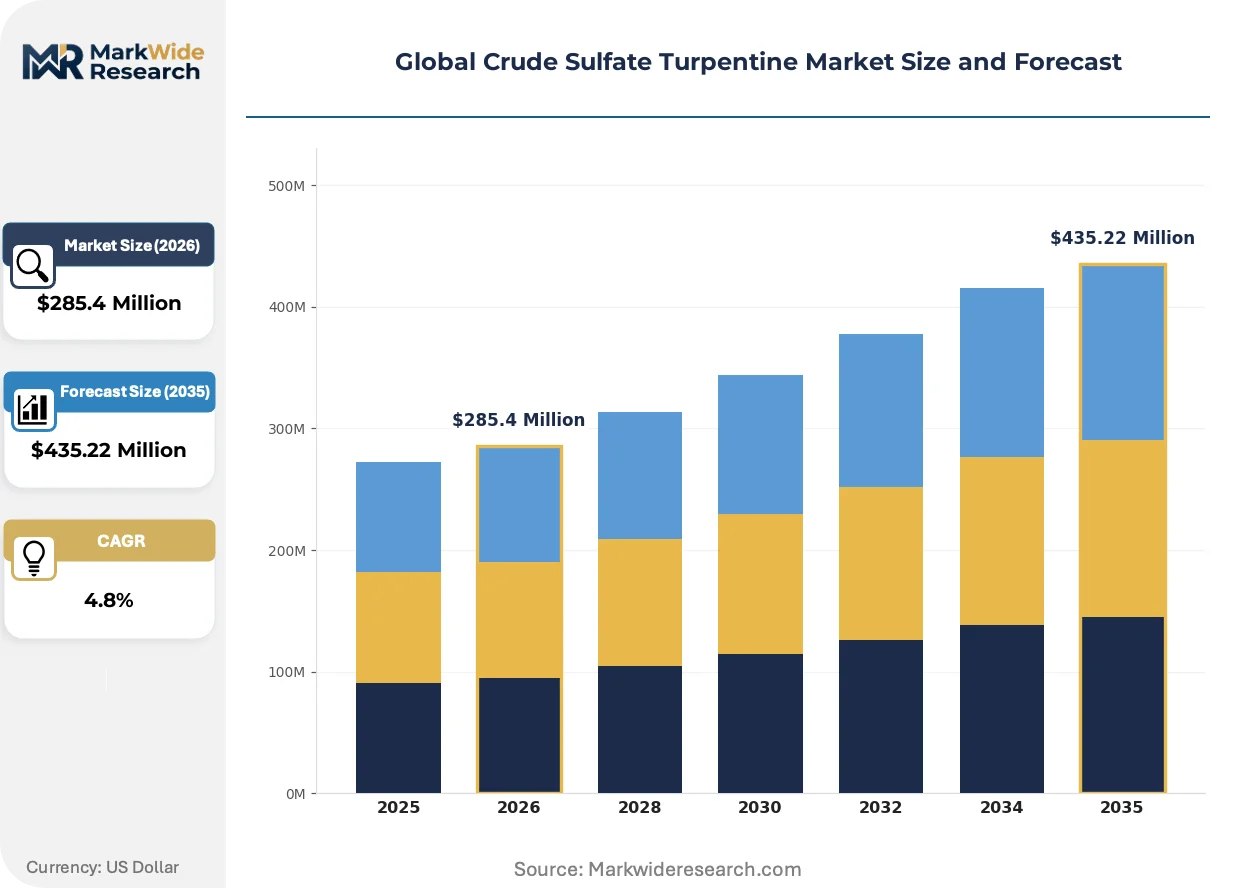
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Crude Sulfate Turpentine, Heavy Crude Sulfate Turpentine, Refined Sulfate Turpentine, Distilled Sulfate Turpentine Application: Solvents, Fragrance Industry, Paints & Coatings, Adhesives, Chemical Intermediates Production Process: Steam Distillation, Sulfate Pulping, Vacuum Distillation, Fractional Distillation End User Industry: Pulp & Paper Manufacturers, Paints & Varnishes Producers, Pharmaceutical Companies, Agrochemical Producers, Rubber Manufacturers |
| Companies Covered | Kraton Corporation, Pine Chemical Group, International Flavors & Fragrances Inc., Georgia-Pacific Chemicals, Ingevity Corporation, DRT, Stora Enso, WestRock Company, Lawter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crude Sulfate Turpentine Market Shifts & Advancements
Process intensification at pulp mill sites is collapsing the traditional separation between raw material recovery and downstream refining, compressing supply chain stages and altering competitive positioning across terpene derivative markets.
Molecular sieve adsorption technology for camphene and limonene isolation is converging with high-purity fragrance chemical specifications, enabling integrated pulp-chemical operators to bypass merchant refiner tolling arrangements. Fragrance houses in Grasse and Geneva are qualifying direct-supply alpha-pinene streams with terpene content exceeding 98 percent, shortening qualification cycles from 18 months to under 6 months. This bypass dynamic is compressing margins for standalone fractionators lacking captive pulp supply.
REACH authorization timelines for existing chemical substances are extending substance characterization requirements to camphene derivatives previously marketed under generic classifications. European downstream formulators are consolidating supplier panels to reduce registration cost duplication, favoring refiners with in-house analytical capabilities and ECHA pre-submission dossiers. Fragrance intermediate buyers in Germany and the Netherlands are now requiring full supply chain substance identity documentation as a contract precondition.
Long-term offtake contracting is displacing spot market purchases among North American adhesive manufacturers seeking supply security amid pulp mill closure announcements. Major tape and label producers in Ohio and Illinois are signing 3- to 5-year alpha-pinene supply agreements with indexed pricing tied to kraft pulp futures rather than spot terpene benchmarks. This contract shift is visible most acutely in pressure-sensitive adhesive applications where formulation consistency requirements limit supplier switching flexibility.
Global Crude Sulfate Turpentine Market Segmentation
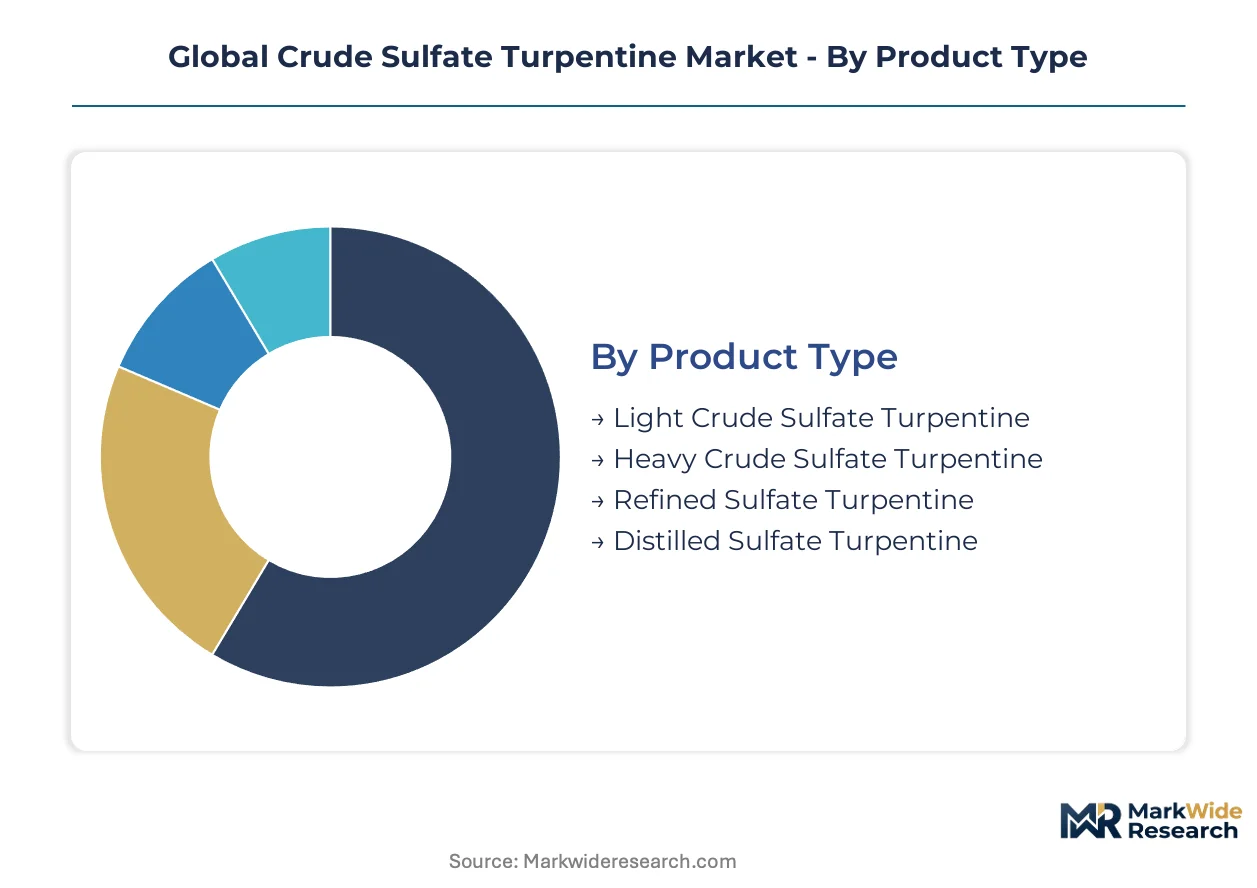
Crude sulfate turpentine markets fragment across processing intensity and purity thresholds, with capital requirements varying dramatically between basic recovery operations and pharmaceutical-grade fractionation. Understanding these segment boundaries clarifies where integrated pulp operators capture margin versus where merchant refiners retain positioning.
Product Type:
Capital intensity escalates sharply from raw recovery through high-purity refinement, with vacuum distillation units requiring substantially greater upfront investment than basic steam stripping infrastructure.
- Light Crude Sulfate Turpentine:Contains 30-45% alpha-pinene with lower specific gravity (0.86-0.87) and reduced sulfur compound burden, enabling direct solvent formulation without extensive pretreatment. Demand concentrates in southeastern United States architectural coatings channels where EPA VOC thresholds have forced formulation adjustments away from heavier fractions.
- Refined Sulfate Turpentine:Achieves terpene content exceeding 95% through multi-stage vacuum fractionation, commanding qualification for fragrance intermediate synthesis. Grasse and Geneva fragrance houses are expanding procurement of this grade for synthetic aroma chemical production, pulling volumes away from commodity solvent applications.
- Heavy Crude Sulfate Turpentine:Higher boiling point fractions (170-190°C) with elevated sulfur and resin acid content require hydrotreating investment for most derivative applications.
- Distilled Sulfate Turpentine:Intermediate purity grade (75-90% terpenes) serving adhesive and rubber processing where sulfur tolerance permits.
Most installed capacity flows through Light Crude Sulfate Turpentine. Expansion is steepest in Refined Sulfate Turpentine.
Application:
Margin structure inverts across this dimension, with fragrance and pharmaceutical channels capturing value multiples over commodity solvent sales despite smaller volume footprints.
- Fragrance Industry:Alpha-pinene and beta-pinene derivatives serve as precursors for synthetic musks, citrus notes, and woody aroma chemicals. Personal care manufacturers in France and Switzerland are qualifying direct-supply streams with terpene content exceeding 98 percent, compressing sales cycle timelines from 18 months to under 6 months.
- Solvents:Pine oil derivatives and terpene-based degreasers compete with petroleum alternatives in institutional cleaning and metal finishing. United States federal procurement preferences under the BioPreferred program are opening institutional purchasing channels for biobased formulations.
- Adhesives:Pressure-sensitive tape and label producers in Ohio and Illinois are signing 3- to 5-year alpha-pinene supply agreements with indexed pricing tied to kraft pulp futures.
- Paints & Coatings:Architectural formulation demand faces EPA Clean Air Act constraints on volatile organic compound content.
- Chemical Intermediates:Camphene derivatives and limonene fractions feed synthetic resin and polymer additive production.
Fragrance Industry commands the highest unit margins. Volume scale remains concentrated in Solvents.
Production Process:
Energy cost exposure varies substantially, with vacuum routes facing margin compression from natural gas price volatility while steam-based recovery maintains lower operating leverage.
- Fractional Distillation:Multi-stage separation of alpha-pinene, beta-pinene, and trace fractions (camphene, limonene) enables derivative-specific sales with purity tailoring. Modular units installed at pulp mill sites are reducing transport costs and enabling real-time separation for fragrance versus industrial channels.
- Sulfate Pulping:Primary recovery mechanism integrated with kraft pulp operations, capturing turpentine as by-product from digester venting. Brazilian producers in Mato Grosso do Sul are commissioning integrated recovery systems, creating new Atlantic basin supply nodes.
- Steam Distillation:Basic separation for light crude grades with lower capital threshold but limited purity achievement.
- Vacuum Distillation:Reduced operating temperatures prevent terpene degradation during high-purity fractionation, though energy intensity limits geographic transferability.
Most existing infrastructure employs Sulfate Pulping integration. Investment is flowing fastest into Fractional Distillation colocation.
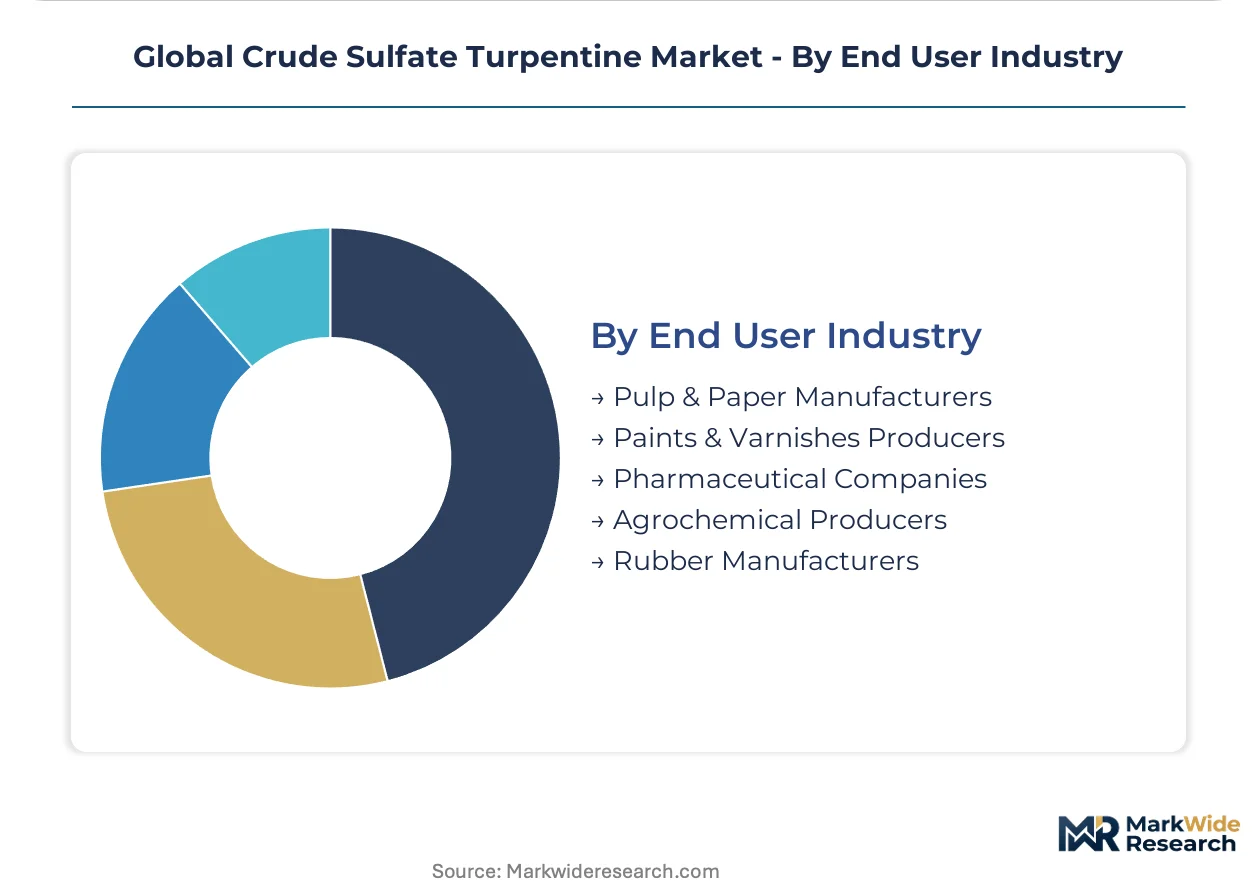
End User Industry:
Customer concentration and contract structure diverge, with pulp-integrated supply dominating paper sector procurement while merchant refiners serve fragmented specialty chemical buyers.
- Pulp & Paper Manufacturers:Captive recovery operations at kraft mills supply internal chemical divisions or toll external refiners. Southeastern United States consolidation is concentrating supply under fewer integrated operators, tightening feedstock access for standalone processors.
- Pharmaceutical Companies:Supercritical CO2 processing of camphene fractions is converging with chiral chemistry demand for drug synthesis precursors, requiring extensive FDA toxicological dossiers and extending qualification timelines.
- Paints & Varnishes Producers:Formulation consistency requirements limit supplier switching flexibility in pressure-sensitive applications.
- Agrochemical Producers:Terpene-derived intermediates serve as chiral building blocks for pesticide active ingredients.
- Rubber Manufacturers:Synthetic pinene from crude oil cracking competes on price stability where purity tolerances permit.
Pulp & Paper Manufacturers anchor volume offtake. Pharmaceutical Companies are gaining share fastest on value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered commercial sulfate turpentine recovery during the 1930s kraft pulping expansion across the Southeast pine belt, establishing integrated production economics that later diffused to Brazil and Scandinavia.
United States
Kraft pulp mill consolidation across Georgia, Alabama, and Florida is concentrating feedstock supply under fewer integrated operators. EPA Clean Air Act amendments continue tightening volatile organic compound thresholds for solvent-grade formulations in architectural coatings. The southeastern pine belt clusters around Savannah, Georgia and Mobile, Alabama now host the majority of fractional distillation capacity additions.
Brazil
Suzano and other kraft producers in Mato Grosso do Sul are commissioning integrated turpentine recovery systems for Atlantic basin export. ANVISA registration requirements for fragrance intermediates are filtering supplier qualification protocols for pharmaceutical-grade limonene extraction. The Três Lagoas industrial corridor is emerging as the primary concentration for pulp-chemical integration investments.
Finland
Stora Enso's integrated operations anchor Nordic sulfate turpentine supply for European fragrance and adhesive markets. ECHA REACH authorization timelines are extending substance characterization requirements to camphene derivatives previously marketed under generic classifications. The Kemi-Tornio region maintains concentrated recovery infrastructure tied to northern bleached softwood kraft production.
France
Grasse fragrance houses are expanding procurement of refined sulfate turpentine derivatives with terpene content exceeding 98 percent. EU Green Deal biobased chemical mandates are opening institutional purchasing channels for pine oil formulations in institutional cleaning. The Provence-Alpes-Côte d'Azur region qualifies direct-supply alpha-pinene streams with compressed sales cycle timelines.
China
Domestic kraft pulp capacity expansion in Guangxi and Hainan is creating new sulfate turpentine supply nodes for Asian derivative markets. GB standards for volatile organic compound emissions in architectural coatings are constraining solvent-grade formulation volumes. The Beihai industrial zone is attracting fractional distillation investments proximal to integrated pulp mill operations.
Global Crude Sulfate Turpentine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the purity-grade spectrum, with fragrance-channel qualification commanding multiples over industrial solvent sales. The vendor base concentrates around integrated pulp-chemical operators and standalone fractionators lacking captive feedstock security. Three archetypes dominate: captive pulp-integrated refiners, merchant toll processors, and fragrance-specialized fractionators. Capacity colocation at pulp mill sites and long-term offtake contracting with indexed pricing represent the dominant competitive moves reshaping downstream supply security.
Among North American integrated operators, Kraton Corporation, Georgia-Pacific Chemicals, and Ingevity Corporation exemplify distinct positioning archetypes. Kraton Corporation represents the captive supply model leveraging pulp integration for downstream terpene resin security. Georgia-Pacific Chemicals anchors Gulf Coast production scale within the integrated chemical division structure. Ingevity Corporation occupies the high-purity specialization position serving fragrance and flavor qualification channels. European competition centers on DRT's continental distillation assets, where REACH compliance capabilities filter qualified supplier positions. These four entities collectively illustrate the margin stratification between commodity solvent supply and pharmaceutical-grade fractionation tiers.
| Leading Market Players |
|---|
| Kraton Corporation |
| Pine Chemical Group |
| International Flavors & Fragrances Inc. |
| Georgia-Pacific Chemicals |
| Ingevity Corporation |
| DRT |
| Stora Enso |
| WestRock Company |
| Lawter |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap refiners in the southeastern United States pine belt anchor supply discipline through captive pulp integration, converting kraft by-product streams into pricing power over merchant toll processors lacking equivalent feedstock security. This ownership pattern concentrates margin capture at the distillation stage while forcing standalone operators into indexed long-term contracts to defend volume positions.
Pricing Analysis
Long-term offtake contracting with kraft pulp futures indexing dominates transaction structures, separating fragrance-grade premiums from commodity solvent baselines. Price differentiation rests on terpene purity thresholds and REACH dossier completeness, with European buyers paying substantial premiums for ECHA-pre-registered supply. Cost compression in solvent-grade channels intensifies as petroleum-derived pinene alternatives capture adhesive market share. Fragrance houses exhibit lowest price sensitivity due to formulation lock-in, while architectural coatings producers face acute budget constraints under EPA VOC compliance costs.
Supply Chain Analysis
Remanufacturing and fractionation residue recovery flows are minimal in this market, as terpene degradation limits reprocessing economics. Supply concentrates in the United States, Brazil, and Finland, with each node tethered to kraft pulp capacity expansion cycles. Raw material dependencies center on pine feedstock availability, natural gas for vacuum distillation energy, and specialized molecular sieve adsorption media. Single-source vulnerability runs through southeastern United States pulp mill consolidation, where closure announcements trigger immediate supply reallocations. Distribution runs through integrated chemical divisions and qualified merchant refiners serving fragrance and adhesive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Atlantic basin supply nodes and Asian derivative demand centers, with Brazilian kraft expansion undercutting United States energy costs while European REACH compliance creates qualification premiums unavailable elsewhere.
For Market Incumbents: Anticipate kraft pulp demand cyclicality by securing backward integration into Brazilian capacity expansions before feedstock competition intensifies. Consolidate distillation assets around Savannah and Mobile to capture logistics savings on Atlantic exports. Prioritize ECHA pre-submission dossiers for camphene derivatives ahead of authorization timeline extensions. For New Entrants and Emerging Players: The premium-to-economy price gap in fragrance intermediates offers entry space for supercritical CO2 extraction specialists targeting pharmaceutical-grade limonene. Target the Três Lagoas corridor for greenfield fractionation colocation with Suzano's integrated recovery systems. Pursue direct-supply qualification with Grasse fragrance houses to bypass merchant refiner tolling margins. For Investors and Strategic Acquirers: Pulp-chemical integrated operators are the most active acquirer in this space, seeking captive terpene resin security for adhesive and rubber applications. Five-to-ten year viability hinges on biorefinery conversion timelines at legacy kraft mills. Monitor ANVISA registration acceleration in Brazil as the signal for Atlantic basin supply node maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Operations | Kraton Corporation's captive sulfate turpentine streams eliminate feedstock price volatility for terpene resin production. |
| Modular Fractionation Deployment | Vacuum distillation units at Georgia-Pacific's Gulf Coast sites reduce transport costs for real-time alpha-pinene separation. |
| REACH Dossier Investment | Ingevity Corporation's ECHA pre-submission capabilities filter qualified supplier positions across European fragrance markets. |
| Long-term Supply Agreement | Ohio and Illinois adhesive producers index alpha-pinene pricing to kraft pulp futures for formulation consistency security. |
| Pharmaceutical-grade Extraction | Supercritical CO2 processing of camphene fractions converges with FDA toxicological dossier requirements for drug synthesis precursors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with kraft pulp mill operations directors, fragrance house procurement managers, adhesive formulators, and terpene resin technical directors with secondary validation through SEC 10-K filings, customs trade data, ACC and Cefic chemical industry reports, and ECHA registration databases. Bottom-up capacity modeling and top-down demand estimation were triangulated against actual production disclosures.
Historical reference periods anchored the projection horizon through backward linkage to kraft pulp demand cycles and forward linkage to biorefinery conversion timelines. Segmentation dimensions modeled include product grade tier, end-use industry application, production process technology, and regional production hub clustering. CAGRs were derived from volume trajectory analysis incorporating fragrance chemical demand elasticity, EPA VOC regulatory stringency, and petroleum-derived substitute pricing.
Caveats apply where kraft pulp mill closure announcements, biorefinery conversion accelerations, or REACH authorization delays could materially shift the outlook. Practitioners should monitor Brazilian ANVISA registration velocity and United States pulp mill consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Aluminum Sulfide Market