
 Guanidine Nitrate Market | 2026-2036
Guanidine Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Guanidine Nitrate Market Foresight
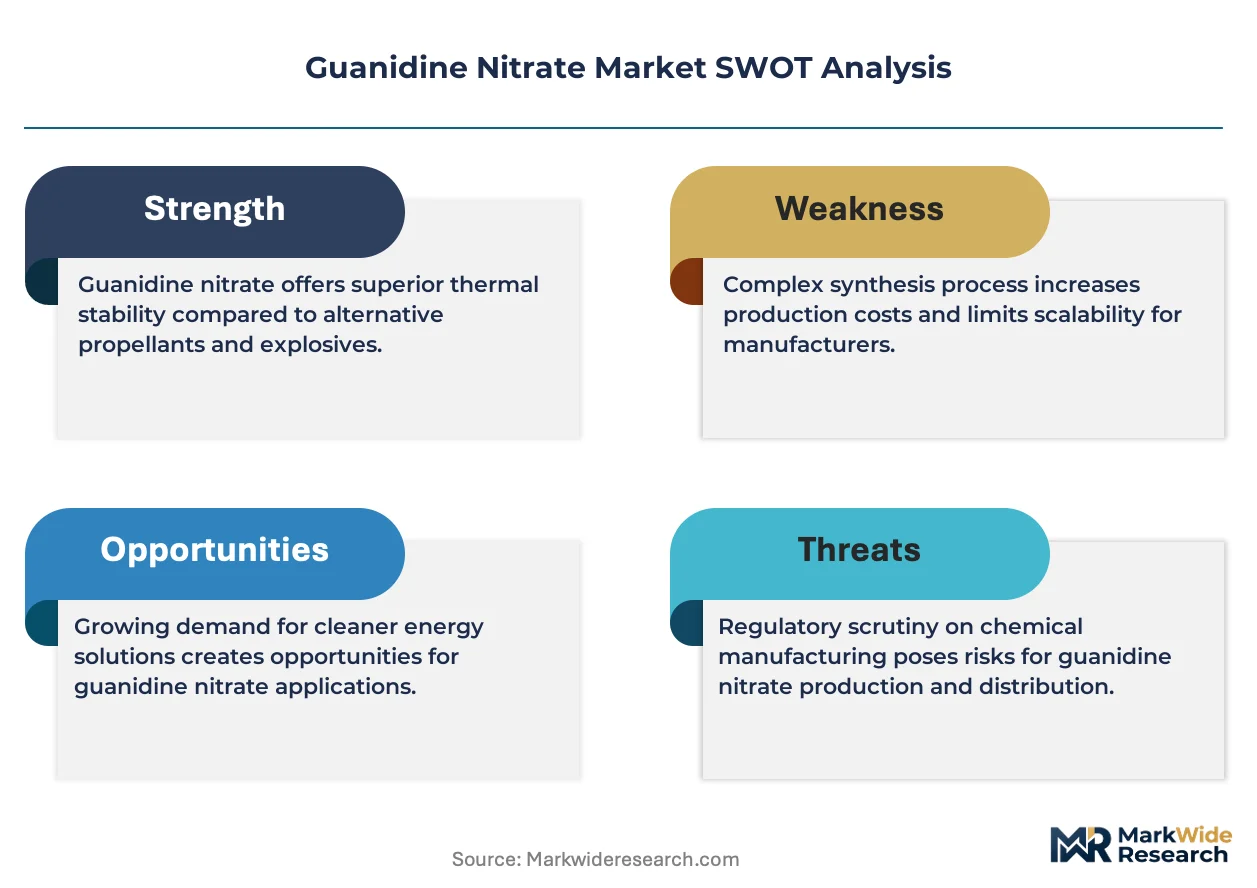
Pharmaceutical-grade purity thresholds is collapsing the gap between industrial and medical applications, forcing reformulation investments across the value chain. AlzChem AG leverages its European manufacturing base to sustain premium positioning in regulated segments. BASF SE anchors global supply security through backward integration into melamine-derived feedstocks. Ningxia Jiafeng Chemicals competes on scale, dominating granular-form output for explosives manufacturers in Asia.
Guanidine nitrate is an organic salt with the formula CH₆N₄O₃, synthesized through the neutralization of guanidine carbonate with nitric acid and typically supplied at purity levels ranging from 98% to 99.5% depending on end-use. It functions primarily as a high-nitrogen precursor in explosives manufacturing, a stabilizer in fertilizer formulations, and a reagent in pharmaceutical synthesis. Industrial grade occupies the largest volume share due to entrenched demand from mining and defense sectors, while pharmaceutical grade represents the fastest-expanding margin pool as regulatory filing requirements intensify. Powdered form leads in explosives applications where dissolution kinetics matter, whereas granular formulations dominate agricultural channels for controlled-release properties.
EPA oversight of explosive precursor chemicals and REACH registration requirements for nitrate compounds shape product standards and market access in North America and Europe respectively. China's SAMR enforces GB standards on fertilizer-grade purity, creating divergent compliance pathways across major producing regions. India's CDSCO and BIS jointly govern pharmaceutical-grade imports, adding certification layers for foreign suppliers. Stakeholders must monitor how ECHA's evolving substance evaluation timelines and China's dual carbon goals for chemical production reshape cost structures and sourcing geography.
Market Dynamics
Pharmaceutical-grade purity specifications are collapsing the historical separation between industrial and medical applications, forcing simultaneous compliance with EMA standards and REACH nitrate compound registrations across European supply chains.
Growth Catalysts
- Explosives precursor demand:Mining sector consumption in China's Shandong province anchors volume offtake, with state-owned defense contractors maintaining long-term supply agreements for propellant formulations.
- REACH registration compliance:ECHA substance evaluation timelines for nitrate compounds are accelerating formal purity documentation, creating certified-supplier premiums for compliant producers.
- Controlled-release fertilizers:Granular guanidine nitrate stabilization chemistry is displacing conventional urea amendments in high-value agricultural applications across water-stressed growing regions.
Market Restraints
- Melamine feedstock volatility:BASF SE's captive melamine supply insulates partially, but spot market exposure for non-integrated producers amplifies margin compression during petrochemical cycle peaks.
- Shandong supply concentration:AlzChem AG and domestic Chinese producers control approximately two-thirds of granular-form capacity, creating geographic single-point vulnerability for explosives manufacturers.
- Nitrate substitution in propellants:Ammonium dinitramide and other chlorine-free oxidizers are capturing next-generation defense contracts where thermal stability requirements exceed guanidine nitrate performance thresholds.
Strategic Opportunities
- India CDSCO pharmaceutical pathways:BIS certification requirements for fertilizer-grade imports create dual-registration economies for suppliers achieving pharmaceutical-grade status simultaneously.
- Carbon-accounted production:China's dual carbon goals for chemical manufacturing are privileging producers with integrated nitric acid recovery, opening preferential procurement channels for state-backed mining entities.
- Continuous-flow synthesis:Microreactor process intensification is reducing batch-to-batch purity variation, enabling just-in-time pharmaceutical contract manufacturing relationships previously inaccessible to commodity producers.
Industry Challenges
- Cross-grade contamination protocols:Facilities producing both industrial and pharmaceutical grades face EPA explosive precursor oversight intersecting with FDA current Good Manufacturing Practice requirements, demanding segregated production lines and duplicate quality systems.
- Specialized analytical chemistry capacity:ICP-MS trace metal analysis and nitrosamine impurity profiling require capital equipment investments beyond standard QC capabilities, constraining smaller producers from pharmaceutical-grade qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guanidine Nitrate Market |
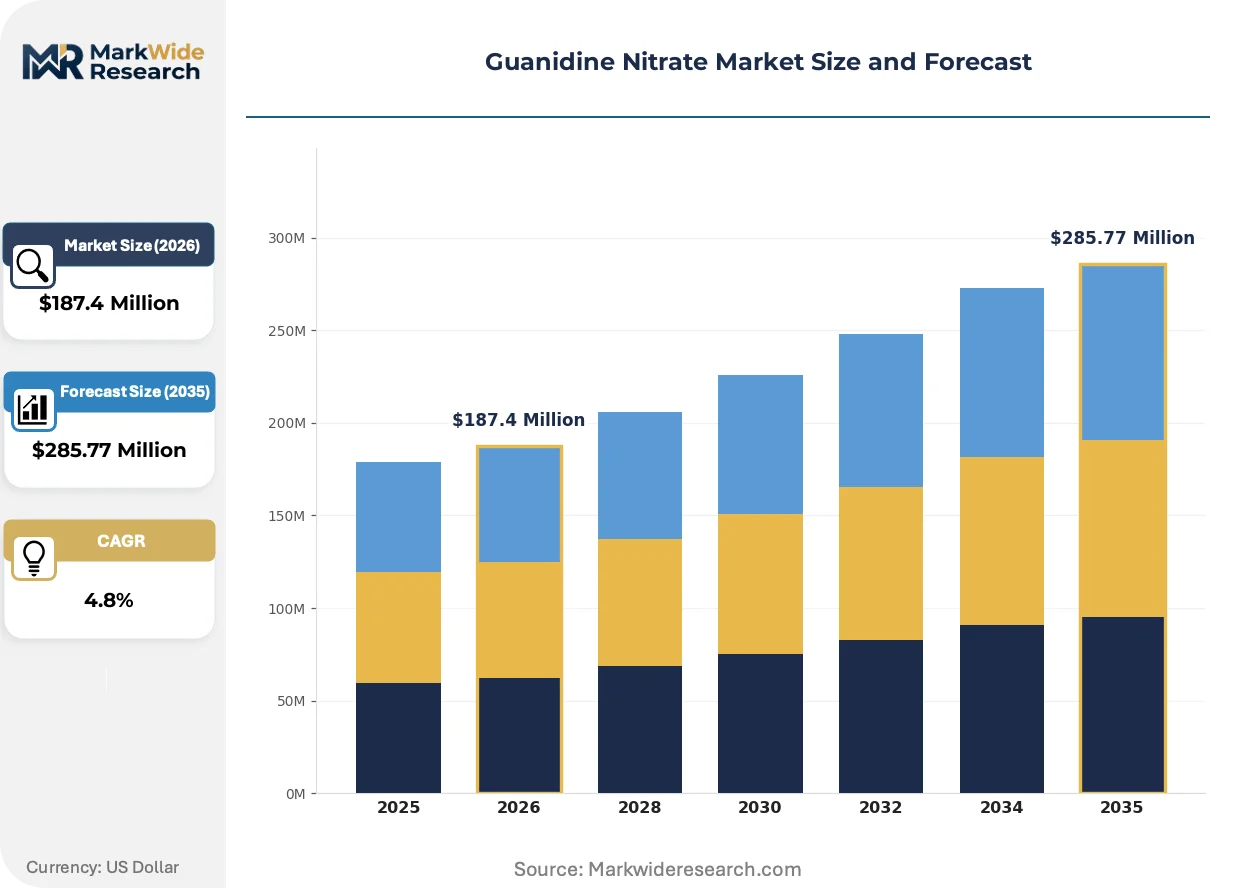
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Agricultural Grade, Pharmaceutical Grade, Food Grade Application: Explosives, Fertilizers, Pharmaceuticals, Food Additives End User: Manufacturers, Farmers, Healthcare Providers, Food Processors Form: Granular, Powdered, Liquid, Pellets |
| Companies Covered | AlzChem AG, Evonik Industries AG, BASF SE, Ningxia Jiafeng Chemicals, Canpex Chemicals, Jiangsu Wugan Biological Technology, Ningxia Soochow Agrochemical, Vihita Chem, Aarti Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guanidine Nitrate Market Shifts & Advancements
Process intensification and regulatory digitization are restructuring competitive advantage around real-time purity verification and carbon-accounted supply chain documentation rather than scale economies alone.
Continuous-flow microreactor synthesis is bifurcating the producer base between batch-legacy facilities and continuous-mode investments. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting flow chemistry for guanidine nitrate derivatives to satisfy EMA nitrosamine risk assessment requirements. This technology compression is marginalizing multi-purpose batch reactors unable to demonstrate residence-time control for impurity suppression.
REACH substance evaluation timelines for nitrate category compounds are forcing retrospective purity dossier compilation across European registrants. ECHA's 2024-2026 evaluation wave specifically targets high-tonnage nitrate salts, compelling producers to generate chronic toxicity data previously absent from industrial-grade registrations. Pharmaceutical-grade suppliers with existing toxicology packages are capturing regulatory-driven switching from industrial-grade users seeking evaluation risk mitigation.
Certificate-of-analysis unbundling from physical delivery is compressing procurement cycles for explosives manufacturers. Mining sector buyers in Australia and Canada now accept digital COA transfer ahead of shipment arrival, enabling just-in-time inventory positions previously impractical under paper-based verification. This channel digitization privileges producers with integrated LIMS-to-customer-ERP connectivity, disadvantaging smaller suppliers dependent on manual documentation workflows.
Guanidine Nitrate Market Segmentation
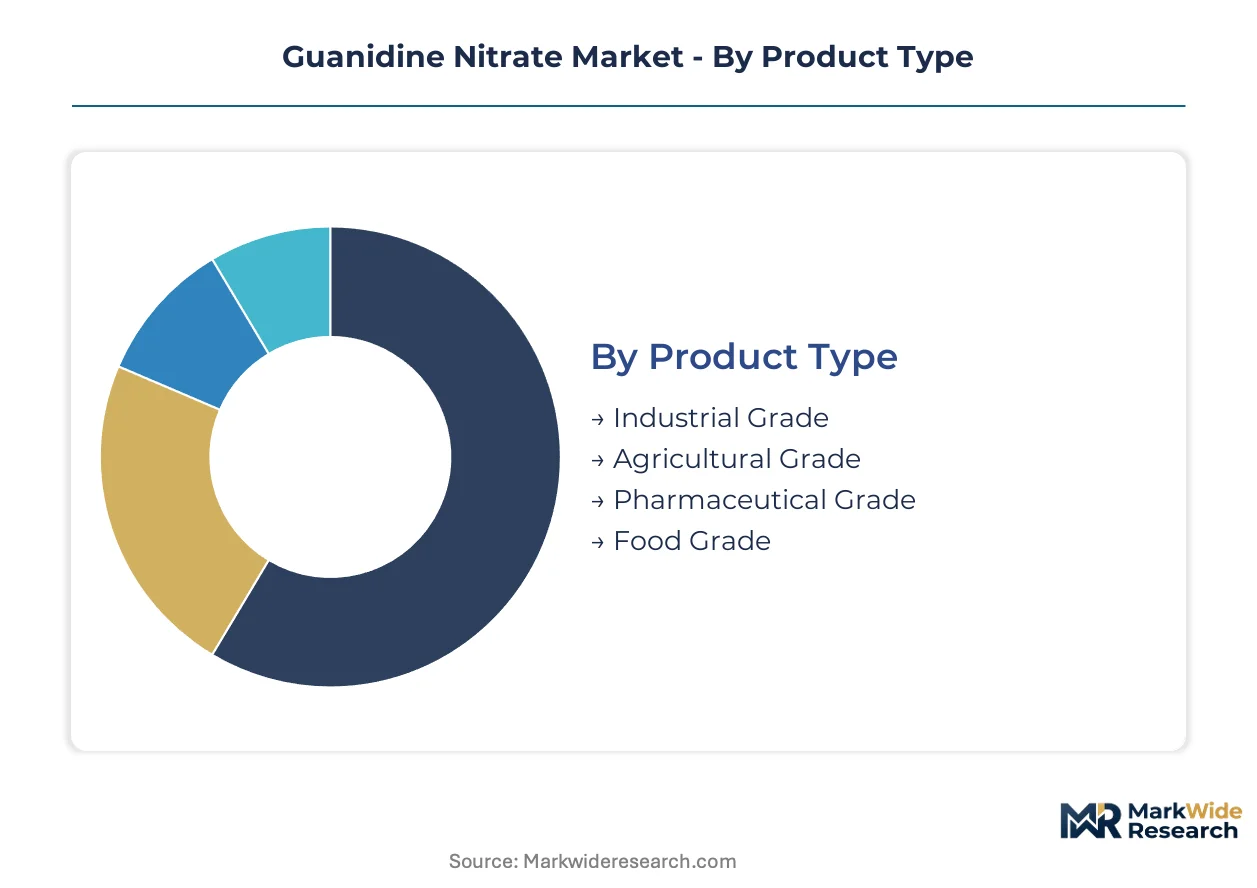
Segment boundaries in guanidine nitrate are dissolving as pharmaceutical-grade purity requirements migrate downstream into explosives and fertilizer channels. Producers now face simultaneous compliance obligations across historically separated quality tiers, reshaping capital allocation and facility design.
Product Type:
Substitution pressure from ammonium dinitramide and chlorine-free oxidizers hits industrial grade hardest, while pharmaceutical grade builds defensive moats through EMA nitrosamine documentation and REACH substance evaluation compliance.
- Industrial Grade:Supplied at 98-99% purity, this segment serves mining explosives and defense propellants where cost sensitivity dominates specification. China's Shandong province anchors volume offtake through state-owned defense contractors maintaining long-term supply agreements for propellant formulations. Ammonium dinitramide is capturing next-generation defense contracts where thermal stability requirements exceed guanidine nitrate performance thresholds.
- Pharmaceutical Grade:99.5%+ purity with full ICP-MS trace metal certification and nitrosamine impurity profiling. ECHA substance evaluation timelines for nitrate compounds are accelerating formal purity documentation, creating certified-supplier premiums for compliant producers in Germany and Switzerland.
- Agricultural Grade:Stabilizer chemistry for controlled-release fertilizer formulations, displacing conventional urea amendments in water-stressed growing regions.
- Food Grade:Minimal commercial presence; regulatory complexity from FDA and EFSA food additive approvals constrains viable supply sources.
Industrial grade retains volume leadership; pharmaceutical grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity explosives demand from premium pharmaceutical and specialty fertilizer offtake, with divergent margin structures driving producer specialization decisions.
- Explosives:High-nitrogen precursor for mining and defense propellants, where dissolution kinetics favor powdered form. Australia's mining sector now accepts digital certificate-of-analysis transfer ahead of shipment arrival, compressing procurement cycles.
- Fertilizers:Granular stabilization chemistry dominates agricultural channels for controlled-release properties across water-stressed growing regions. China's SAMR enforces GB standards on fertilizer-grade purity, creating divergent compliance pathways.
- Pharmaceuticals:Reagent in active pharmaceutical ingredient synthesis, with EMA nitrosamine risk assessment requirements driving continuous-flow microreactor adoption.
- Food Additives:Negligible commercial penetration due to regulatory burden from FDA and EFSA approval pathways.
Explosives commands absolute volume; pharmaceuticals generates the highest margin per kilogram.
End User:
Customer type determines specification stringency, with healthcare providers and food processors imposing documentation burdens that manufacturers and farmers rarely encounter.
- Manufacturers:Explosives and chemical synthesis buyers prioritizing batch-to-batch consistency and supply security. Mining sector procurement digitization privileges producers with integrated LIMS-to-customer-ERP connectivity.
- Healthcare Providers:Pharmaceutical-grade specifications are gaining traction in Germany, where EMA purity standards and REACH compliance requirements are tightening simultaneously.
- Farmers:Price-sensitive agricultural offtake concentrated in China's Shandong province and water-stressed growing regions adopting controlled-release formulations.
- Food Processors:Minimal engagement due to regulatory complexity and alternative stabilizer availability.
Manufacturers absorb the largest tonnage; healthcare providers deliver the premium pricing tier.
Form:
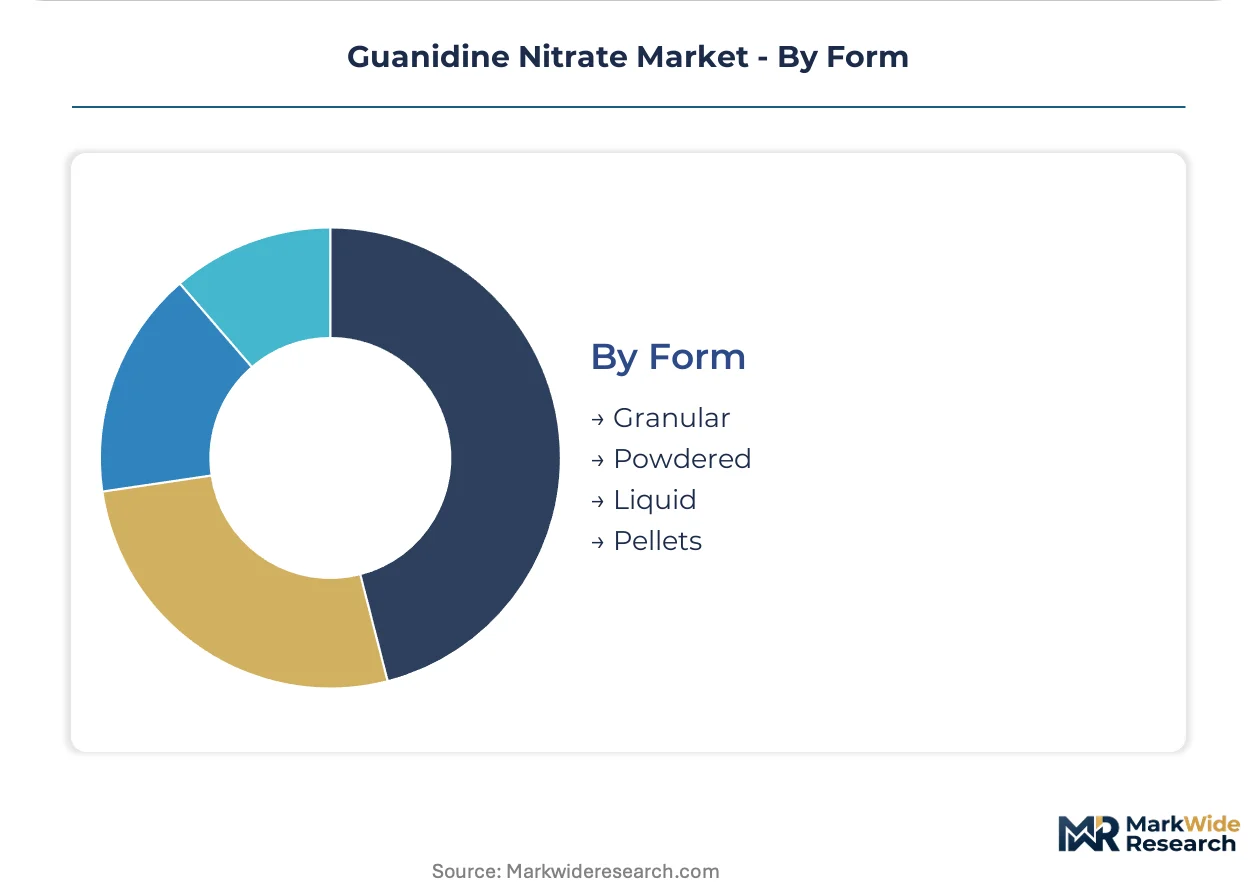
Supply concentration in granular production—controlled by AlzChem AG and domestic Chinese producers—creates geographic single-point vulnerability for explosives manufacturers dependent on physical flow properties.
- Granular:Dominates fertilizer applications for controlled-release properties and explosives channels where handling characteristics matter. Approximately two-thirds of capacity concentrates in Shandong province.
- Powdered:Preferred in explosives manufacturing where dissolution kinetics determine detonation characteristics. Mining applications in Australia and Canada drive demand.
- Liquid:Niche pharmaceutical and specialty chemical applications requiring direct feed into continuous-flow synthesis.
- Pellets:Emerging agricultural format with limited commercial scale; compaction economics favor granular alternatives.
Granular form retains volume leadership; liquid form holds the steepest expansion curve through pharmaceutical contract manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across producing regions, with China's Shandong province running structural surpluses while European buyers absorb premium pharmaceutical-grade volumes. Deficit markets in Australia and Canada rely on Asian supply chains for mining explosives applications.
China
Shandong province anchors granular-form production for explosives and fertilizer channels, with state-owned defense contractors locking in multi-year propellant supply agreements. SAMR enforces GB standards on fertilizer-grade purity, creating compliance separation from pharmaceutical export streams. Domestic producers and AlzChem AG jointly control approximately two-thirds of regional capacity.
Germany
Healthcare providers drive pharmaceutical-grade specification tightening, with EMA nitrosamine risk assessments intersecting REACH substance evaluation timelines for nitrate compounds. ECHA's 2024-2026 evaluation wave specifically targets high-tonnage nitrate salts, compelling chronic toxicity data generation. AlzChem AG leverages its European manufacturing base to capture certified-supplier premiums.
United States
Mining sector procurement digitization accelerates inventory compression, with Australian and Canadian buyers now accepting digital certificate-of-analysis transfer ahead of physical arrival. EPA oversight of explosive precursor chemicals shapes product standards for defense contractors. Midwest and Mountain West mining clusters favor powdered-form dissolution kinetics.
India
CDSCO and BIS jointly govern pharmaceutical-grade import certification, adding documentation layers for foreign suppliers while creating dual-registration economies for compliant producers. BIS certification requirements for fertilizer-grade imports favor suppliers achieving pharmaceutical-grade status simultaneously. Western and Southern pharmaceutical manufacturing corridors concentrate demand.
Australia
Mining explosives consumption drives absolute volume offtake, with procurement digitization enabling just-in-time inventory positions previously impractical under paper-based verification. Digital COA transfer ahead of shipment arrival compresses working capital cycles. Queensland and Western Australia mining belts absorb the largest tonnage.
Guanidine Nitrate Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and regional specialists serving distinct specification tiers. The producer base separates between batch-legacy facilities and continuous-flow microreactor investments, with regulatory digitization and carbon-accounted production emerging as differentiation vectors. Three archetypes dominate: European pharmaceutical-grade specialists with REACH dossier depth, Chinese scale producers serving explosives and agricultural channels, and Indian diversified chemical houses leveraging dual-registration economies. Capacity expansion and strategic partnerships represent the dominant competitive moves, with backward integration into melamine-derived feedstocks and nitric acid recovery systems determining cost position.
Among German chemical conglomerates, BASF SE exemplifies the integrated archetype through captive feedstock supply, while AlzChem AG occupies the European pharmaceutical-grade specialist position. Ningxia Jiafeng Chemicals represents the Chinese scale-driven tier dominating granular-form output. These three anchors illustrate how geographic specialization and specification tiering fragment competitive dynamics across the value chain.
| Leading Market Players |
|---|
| AlzChem AG |
| Evonik Industries AG |
| BASF SE |
| Ningxia Jiafeng Chemicals |
| Canpex Chemicals |
| Jiangsu Wugan Biological Technology |
| Ningxia Soochow Agrochemical |
| Vihita Chem |
| Aarti Industries Limited |
| Others |
Supply & Pricing Matrix
Sixty-day inventory cycles for explosives-grade material concentrate pricing power with Shandong province producers, while pharmaceutical buyers absorb premiums for REACH-compliant documentation. This lead-time asymmetry between mining and healthcare channels reinforces tiered margin structures across the value chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with state-owned defense contractors locking in multi-year propellant agreements. Three-tier pricing structure across pharmaceutical, industrial, and agricultural grades separates EMA-certified suppliers from commodity producers. Cost compression in industrial grade intensifies because ammonium dinitramide substitution threatens legacy explosives contracts. Mining sector procurement teams exhibit highest price sensitivity, while CDSCO-registered pharmaceutical buyers accept certified-supplier premiums.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for European pharmaceutical buyers sourcing from Shandong province. Supply concentrates in China, Germany, and India, with melamine feedstock dependencies tethering cost structures to petrochemical cycle volatility. Single-source vulnerability concentrates in granular-form production, where AlzChem AG and domestic Chinese producers control two-thirds of capacity. Distribution runs through state-backed mining procurement consortia in Australia and defense contractors in China's Shandong corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital certificate-of-analysis ecosystems are collapsing procurement friction between producers and explosives manufacturers, creating platform economics where LIMS-ERP interoperability determines supplier stickiness.
For Market Incumbents: Consolidate backward integration into melamine-derived feedstocks to insulate margin position from petrochemical volatility. Capture certified-supplier premiums by accelerating REACH substance evaluation dossier completion ahead of ECHA's nitrate salt evaluation wave. Channel control through integrated nitric acid recovery systems privileges preferential procurement from state-backed Chinese mining entities.
For New Entrants and Emerging Players: Continuous-flow microreactor service layers remain under-developed by batch-legacy incumbents, opening pharmaceutical contract manufacturing relationships previously inaccessible to commodity producers. Penetrate India's Western and Southern pharmaceutical corridors through simultaneous CDSCO and BIS dual-registration. Go-to-market leverage rests on carbon-accounted production credentials aligned with China's dual carbon goals.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded pharmaceutical-grade assets lacking REACH dossier depth. Long-term viability favors producers with demonstrated residence-time control for nitrosamine impurity suppression. Signal to monitor: ECHA evaluation timeline acceleration forcing retrospective toxicology data generation across European registrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melamine Feedstocks | BASF SE's captive supply model demonstrates margin insulation during petrochemical cycle peaks. |
| Continuous-Flow Microreactor Adoption | German pharmaceutical contract manufacturers deploy flow chemistry to satisfy EMA nitrosamine risk assessments. |
| Dual CDSCO-BIS Registration | Indian regulatory overlap creates economies for suppliers qualifying pharmaceutical and fertilizer grades simultaneously. |
| Carbon-Accounted Production Certification | China's dual carbon goals privilege producers with integrated nitric acid recovery for state mining procurement. |
| Digital COA-to-ERP Integration | Australian mining buyers now accept digital certificate transfer ahead of shipment, compressing working capital cycles. |
Research Methodology
Desk research of customs trade flows, ECHA registration databases, and SAMR GB standard filings preceded structured interviews with explosives procurement managers at Australian mining operators, pharmaceutical quality directors in Germany and India, and Shandong province plant managers. Primary fieldwork with these stakeholders combined with secondary validation from SEC 10-K chemical segment disclosures and ACC industrial chemical reports. Bottom-up capacity modeling triangulated against top-down demand estimates from mining sector capex projections and pharmaceutical API synthesis trends.
Variance decomposition across grade tier, end-use industry, and regional production hub segmentation dimensions shaped analytical framework development throughout the projection horizon. CAGRs derived from segment-level volume trajectories weighted by purity-premium realization rates. Forecast inputs incorporated REACH substance evaluation timeline scenarios and China's dual carbon policy implementation pace for chemical manufacturing.
Forecasts assume regulatory continuity in EMA nitrosamine assessment protocols, EPA explosive precursor oversight, and SAMR fertilizer-grade enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ammonium dinitramide substitution rates in defense propellants and ECHA evaluation acceleration timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Sodium Formate Market