
 Ammonium Molybdate Market | 2026-2036
Ammonium Molybdate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Molybdate Market Analysis
Chinese molybdenum concentrate processing is hardening as the dominant supply-side capacity anchor for ammonium molybdate derivatives. Jinduicheng Molybdenum Group leverages captive mining assets to sustain cost-competitive feedstock access across Asia. Molymet anchors South American distribution through integrated refining infrastructure in Chile. Climax Molybdenum competes on metallurgical-grade purity standards for North American specialty chemical buyers.
Ammonium molybdate comprises a family of inorganic compounds with the general formula (NH4)xMoyOz, most commonly encountered as ammonium heptamolybdate tetrahydrate with 54-58% MoO3 content, serving primarily as a soluble molybdenum source for catalysis, corrosion inhibition, and micronutrient delivery. Powder formulations dominate agricultural offtake due to superior dissolution kinetics in bulk blending operations, while solution grades command premium positioning in electronics plating baths where lot-to-lot consistency governs yield. Water treatment applications represent the fastest-expanding demand pool as utilities retrofit legacy phosphorus-based corrosion programs with molybdate alternatives.
EPA drinking water standards and REACH chemical registration requirements in Europe are tightening purity specifications and trace-metal disclosure obligations for molybdate suppliers. China's MEE enforces discharge limits on molybdenum-bearing effluents, compelling domestic producers to adopt closed-loop crystallization and zero-liquid-discharge architectures. Stakeholders must monitor evolving fertilizer-grade certification protocols across Brazil, India, and the European Union to anticipate qualification barriers and margin compression in commodity versus specialty tiers.
Market Dynamics
China's MEE discharge mandates are forcing crystallization technology upgrades across molybdate production clusters, compressing margins for legacy open-loop operators while rewarding integrated refiners with captive wastewater treatment assets.
Growth Catalysts
- Water treatment retrofit mandates:US EPA corrosion inhibitor guidelines are accelerating molybdate substitution for phosphorus-based programs in municipal utilities. Closed-loop cooling systems in Texas and California chemical plants are standardizing on molybdate formulations.
- Fertilizer certification expansion:Brazil's MAPA micronutrient labeling requirements are creating qualified supplier status for high-purity ammonium molybdate grades. Specialty blenders in Mato Grosso are specifying 54% MoO3 minimum content for premium product lines.
- Electronics plating specification tightening:JIS H 8625 standards for molybdenum electroplating are concentrating procurement among solution-grade suppliers with lot-traceability systems. Osaka-area semiconductor packaging facilities are requiring sub-10ppm heavy metal certification.
Market Restraints
- Molybdenum concentrate supply concentration:Chinese state-owned mining groups control approximately two-thirds of global roasted molybdenum feedstock, exposing derivative producers to export quota volatility and concentrate pricing power asymmetry.
- REACH registration cost burden:ECHA substance evaluation fees for ammonium heptamolybdate are exceeding EUR 150,000 per legal entity, excluding mid-tier traders from direct EU market access and forcing distributor-dependent models.
- Sodium molybdate substitution in agriculture:Lower-cost sodium salt alternatives are capturing commodity fertilizer applications where solubility requirements permit, compressing ammonium salt volumes in bulk micronutrient blends.
Strategic Opportunities
- Zero-liquid-discharge technology licensing:Chinese producers with MEE-compliant crystallization systems are packaging wastewater treatment know-how for export to Indian and Indonesian greenfield projects facing tightening discharge norms.
- Printed circuit board via-fill applications:Semi-additive molybdenum plating processes for high-density interconnect substrates are emerging as a volume driver, with Taiwan and South Korea PCB manufacturers qualifying ammonium molybdate electrolytes.
- Carbon border adjustment positioning:EU CBAM scope expansion toward inorganic chemicals is creating first-mover advantage for producers with verified low-carbon concentrate sourcing and renewable energy-powered refining.
Industry Challenges
- Crystallization process engineering talent scarcity:Zero-liquid-discharge system design requires hybrid chemical engineering and wastewater treatment expertise concentrated among Chinese state enterprise veterans, limiting technology transfer velocity.
- Multi-jurisdiction certification synchronization:Fertilizer-grade registrations across Brazil MAPA, India FCO, and EU Fertilizing Products Regulation demand divergent analytical protocols and stability testing timelines, fragmenting product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Molybdate Market |
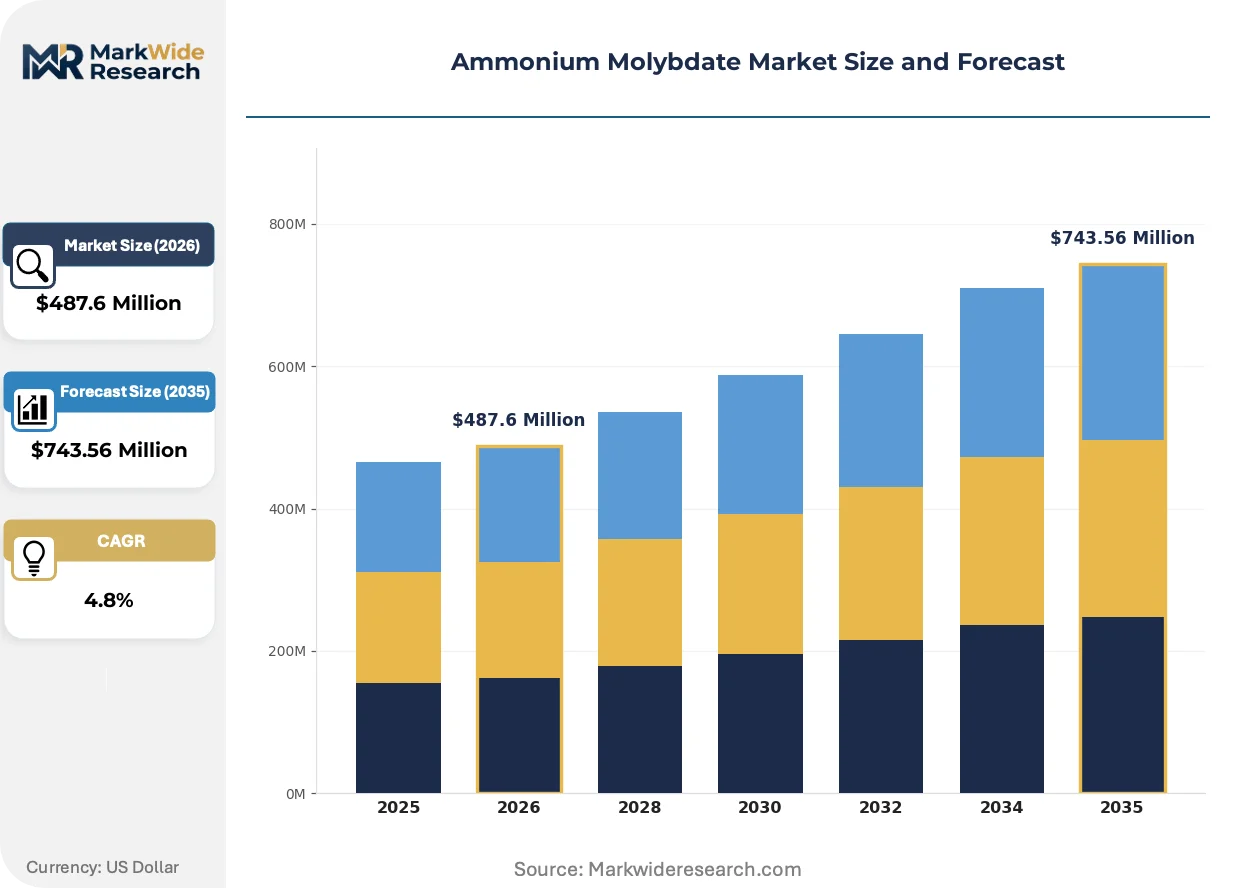
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
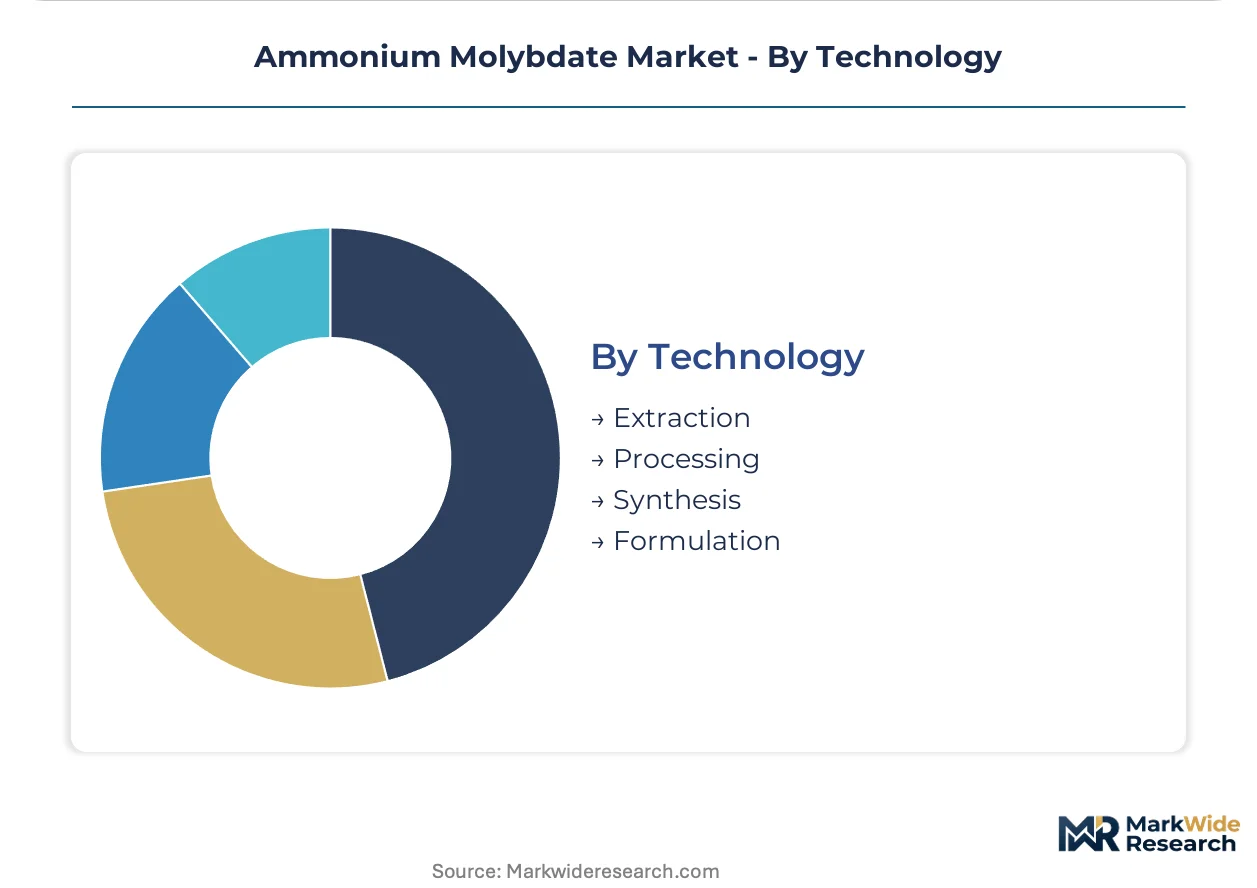
| Segmentation | Application: Agriculture, Chemical Processing, Water Treatment, Electronics Product Type: Granules, Powder, Solution, Tablets End User: Fertilizer Manufacturers, Chemical Industries, Research Laboratories, Water Utilities Technology: Extraction, Processing, Synthesis, Formulation |
| Companies Covered | Climax Molybdenum, H.C. Starck, Molymet, China Molybdenum, Cobase Enterprises Inc., Jinduicheng Molybdenum Group, Freeport-McMoRan, Thompson Creek Metals Company, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Molybdate Market Emerging Trajectories
Process intensification and regulatory compliance automation are converging to reshape production economics, with digital twin technologies and closed-loop water systems becoming baseline competitive requirements rather than differentiators.
Continuous crystallization technology is integrating into ammonium heptamolybdate production lines, replacing batch tank operations with steady-state precipitation systems that reduce labor intensity and improve particle size distribution consistency. Chilean and Chinese integrated refiners are piloting these units for metallurgical-grade output, with the technology enabling 24-hour operational cycles that compress unit costs and tighten specification bands for electronics-grade derivatives.
REACH Annex XVII restriction proposals for molybdenum compounds in consumer applications are forcing downstream disclosure systems and exposure scenario documentation throughout European supply chains. Industrial chemical distributors are consolidating supplier bases to reduce compliance audit burden, with specialty-grade ammonium molybdate volumes concentrating among registrants with complete toxicological dossiers and CSR-ready supply chain transparency.
Specification-driven procurement is consolidating buyer-seller relationships around certified analytical packages rather than spot price optimization, with automotive catalyst and electronics plating customers requiring COA-matched delivery lots with ICP-MS trace metal verification. South Korean and Japanese chemical trading houses are restructuring as technical service providers, embedding laboratory validation and just-in-time inventory management into long-term supply agreements for precision-grade molybdate salts.
Ammonium Molybdate Market Segmentation
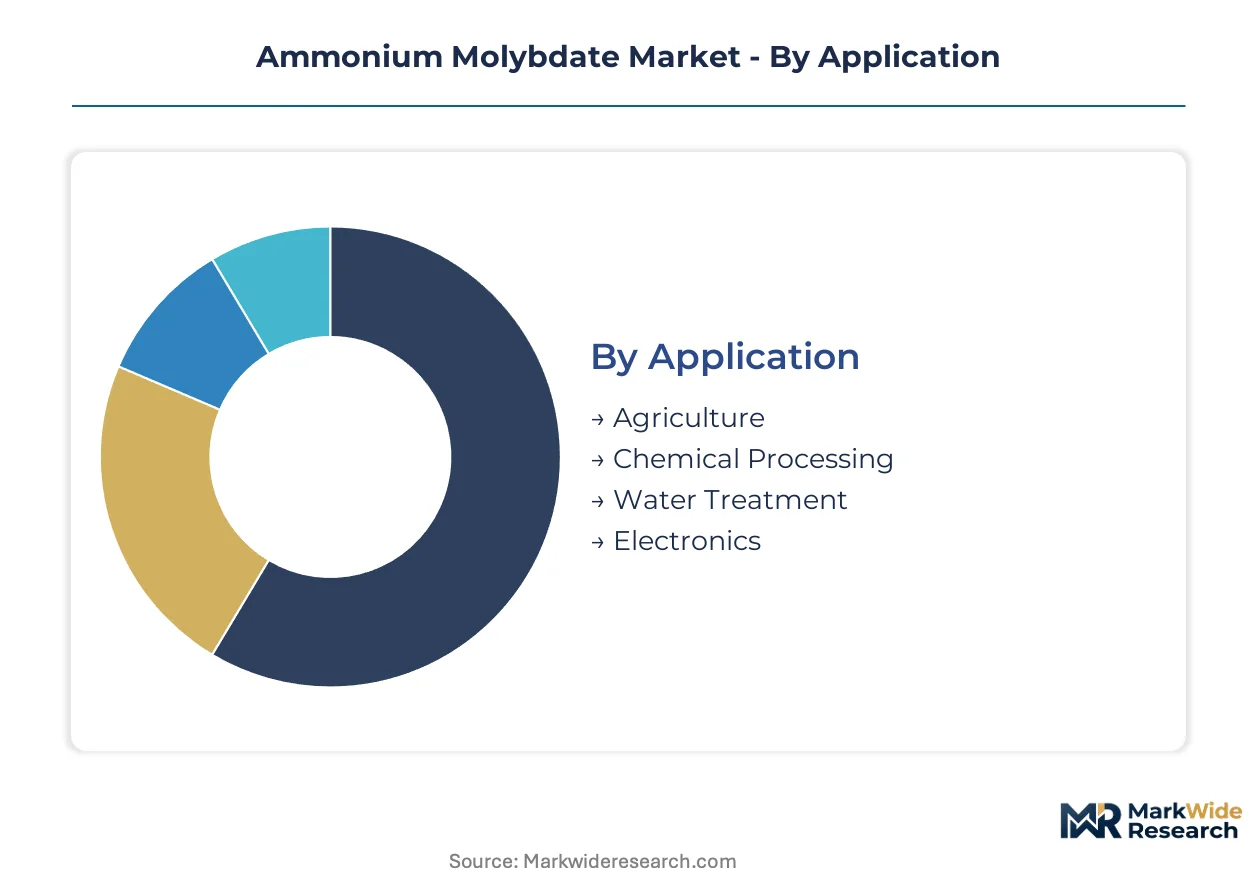
Segmentation in ammonium molybdate markets follows specification-grade boundaries rather than commodity volume tiers. Certification requirements from Brazil's MAPA, China's MEE, and EU REACH create divergent margin structures across application and product type categories.
Application:
Certification burdens fragment this category sharply: agriculture demands MAPA and FCO micronutrient registrations, water treatment requires EPA corrosion inhibitor compliance, while electronics plating follows JIS H 8625 traceability mandates.
- Agriculture:Powder formulations dominate bulk blending operations for soybean and corn micronutrient programs across Mato Grosso and Iowa. Specialty fertilizer manufacturers in Brazil are expanding procurement of high-purity grades with 54% MoO3 minimum content to meet MAPA labeling requirements.
- Water Treatment:Municipal utilities in Texas and California are retrofitting closed-loop cooling systems with molybdate alternatives to phosphorus-based corrosion programs. China's MEE discharge mandates are accelerating crystallization technology upgrades among suppliers serving this segment.
- Chemical Processing:Catalysis applications in East Asian chemical clusters around Shanghai and Busan concentrate demand for metallurgical-grade material with controlled particle size distribution.
- Electronics:Semiconductor packaging facilities in Osaka require sub-10ppm heavy metal certification and lot-traceability systems for electroplating baths.
Leading the category by volume: Agriculture. Expanding most quickly: Water Treatment.
Product Type:
Cost tiers separate these segments: solution grades command 40-60% premiums over powder due to dissolution consistency requirements in precision applications.
- Powder:Superior dissolution kinetics drive agricultural offtake in bulk blending operations. Fertilizer manufacturers specify powder for cost-efficient micronutrient delivery across Brazil's Cerrado region.
- Solution:Lot-to-lot consistency governs yield in electronics plating baths. Taiwan and South Korea PCB manufacturers are qualifying ammonium molybdate electrolytes for semi-additive molybdenum plating processes in high-density interconnect substrates.
- Granules:Controlled-release formulations serve specialty fertilizer applications requiring extended nutrient availability windows.
- Tablets:Laboratory and analytical reagent markets in research facilities favor pre-measured dosing convenience.
Highest margin capture: Solution. Steepest volume expansion: Powder.
End User:
Customer procurement sophistication varies dramatically: water utilities run multi-year framework agreements, while research laboratories purchase spot quantities through distributor networks.
- Fertilizer Manufacturers:Specialty blenders in Mato Grosso are specifying certified analytical packages with ICP-MS trace metal verification. These buyers consolidate supplier relationships around long-term supply agreements rather than spot price optimization.
- Chemical Industries:Catalysis and corrosion inhibition applications in Chinese and Chilean integrated refiners demand continuous crystallization technology for 24-hour operational cycles.
- Water Utilities:US EPA drinking water standards are tightening purity specifications for molybdate suppliers serving municipal retrofit programs.
- Research Laboratories:Analytical-grade requirements for spectrophotometric methods and reagent preparation favor small-batch procurement through chemical trading houses.
Dominant procurement scale: Fertilizer Manufacturers. Fastest qualification velocity: Water Utilities.
Technology:
Supply concentration clusters around processing and synthesis capabilities: Chinese state-owned mining groups control two-thirds of global roasted molybdenum feedstock access.
- Extraction:Captive mining assets at Jinduicheng Molybdenum Group sustain cost-competitive feedstock access across Asian derivative production.
- Processing:Chilean and Chinese integrated refiners are piloting continuous crystallization units for metallurgical-grade output, replacing batch tank operations with steady-state precipitation systems.
- Synthesis:Ammonium heptamolybdate tetrahydrate production with 54-58% MoO3 content requires controlled pH precipitation and thermal crystallization sequences.
- Formulation:Solution-grade preparation for electronics plating demands ultrapure water systems and sub-micron filtration to achieve heavy metal specifications.
Technology leadership resides: Processing. Capability scarcity concentrates: Extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese molybdenum concentrate deposits anchor the upstream supply architecture for ammonium molybdate derivatives worldwide. Processing capacity clusters around state-owned mining assets while downstream demand concentrates in agricultural, electronics, and water treatment applications across four major economies.
China
Shanghai and Busan chemical processing clusters absorb metallurgical-grade output for catalysis applications. MEE discharge mandates force crystallization technology upgrades among domestic producers. Jinduicheng Molybdenum Group leverages captive mining assets in Shaanxi Province to sustain cost-competitive feedstock access for Asian derivative production.
United States
Texas and California chemical plants standardize on molybdate formulations for closed-loop cooling systems. EPA corrosion inhibitor guidelines accelerate molybdate substitution for phosphorus-based programs in municipal utilities. Climax Molybdenum competes on metallurgical-grade purity standards for specialty chemical buyers in the Gulf Coast refining corridor.
Brazil
Specialty fertilizer manufacturers in Mato Grosso expand procurement of high-purity grades with 54% MoO3 minimum content. MAPA micronutrient labeling requirements create qualified supplier status for certified analytical packages. Agricultural offtake concentrates in the Cerrado region for soybean and corn micronutrient programs.
Japan
Osaka-area semiconductor packaging facilities require sub-10ppm heavy metal certification for electroplating baths. JIS H 8625 standards for molybdenum electroplating concentrate procurement among solution-grade suppliers with lot-traceability systems. Electronics plating specification tightening governs yield requirements for high-density interconnect substrates.
Chile
Molymet anchors South American distribution through integrated refining infrastructure serving water treatment retrofit mandates. Continuous crystallization pilots replace batch tank operations with steady-state precipitation systems for metallurgical-grade output. Domestic producers package MEE-compliant wastewater treatment know-how for export to regional greenfield projects.
Ammonium Molybdate Market Vendor Landscape
Global majors compete with regional champions across feedstock access and specification-grade positioning. Chinese state-owned mining groups control approximately two-thirds of global roasted molybdenum feedstock, exposing derivative producers to export quota volatility. Three archetypes populate the competitive map: integrated miners with captive concentrate supply, specialty chemical refiners with certification depth, and trading houses with technical service bundling. Capacity expansion and technology licensing dominate competitive moves as producers retrofit crystallization systems for regulatory compliance.
Among integrated mining enterprises, Jinduicheng Molybdenum Group and China Molybdenum occupy positions anchored by captive ore bodies. Climax Molybdenum exemplifies the specialty-grade refiner archetype competing on purity standards. Molymet represents the regional infrastructure play with South American distribution control. These three names illustrate how feedstock proximity, certification investment, and geographic coverage stratify competitive positioning across agricultural, electronics, and water treatment end-uses.
| Leading Market Players |
|---|
| Climax Molybdenum |
| H.C. Starck |
| Molymet |
| China Molybdenum |
| Cobase Enterprises Inc. |
| Jinduicheng Molybdenum Group |
| Freeport-McMoRan |
| Thompson Creek Metals Company |
| American Elements |
| Others |
Supply Flow & Price Mechanics
Roasted molybdenum concentrate spot prices on the Platts Molybdenum Oxide Benchmark cascade through ammonium molybdate derivative tiers, compressing margins for non-integrated processors while amplifying pricing power for miners with captive refining assets. Chinese state-owned mining groups leverage feedstock control to dictate contract terms across agricultural, electronics, and water treatment grades.
Pricing Analysis
Certification-bundling separates quoted prices: MAPA-registered agricultural grades include analytical validation and lot-traceability documentation, while unbundled powder for bulk blending ships with basic COA only. Three-tier pricing structure across electronics-grade solution, MAPA-certified agricultural powder, and commodity water treatment granules reflects purity and compliance investment. Pricing pressure stems from sodium molybdate substitution in commodity fertilizer blends, eroding ammonium salt volumes. Fertilizer manufacturers in Brazil exhibit highest price sensitivity due to MAPA compliance costs, while Osaka-area semiconductor packaging facilities accept premiums for sub-10ppm heavy metal certification.
Supply Chain Analysis
Container freight rates from Shanghai to Santos and Busan to Los Angeles amplify landed cost differentials for South American and North American buyers sourcing from Chinese processing clusters. Supply concentrates in China, Chile, and the United States, with Chinese state-owned groups controlling two-thirds of global roasted molybdenum feedstock. Production draws from molybdenum concentrate, ammonia feedstock, and ultrapure water systems. Single-source vulnerability concentrates in Shaanxi Province mining assets, exposing derivative producers to export quota volatility. Distribution runs through integrated refiner direct sales for volume accounts and specialty chemical distributors for qualified smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonium molybdate competitive dynamics have shifted into a vertical-integration race, with feedstock access and zero-liquid-discharge compliance emerging as the decisive levers for margin defense.
For Market Incumbents: Hedge against Chinese concentrate export quota volatility by securing long-term offtake agreements with Chilean and North American mining assets. Invest in continuous crystallization technology to meet MEE discharge mandates while locking in qualified supplier status for Brazil MAPA and EU REACH registrations before mid-tier competitors complete dossier submissions. For New Entrants and Emerging Players: Launch via technical service bundling into Indian and Indonesian water treatment retrofit markets facing tightening discharge norms but lacking domestic crystallization expertise. Target zero-liquid-discharge technology licensing as the most penetrable entry vector, leveraging Chinese state enterprise veteran talent for process engineering transfer. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated refiners with captive wastewater treatment assets in Chile and certified low-carbon concentrate sourcing positions ahead of EU CBAM scope expansion. Watch for MEE enforcement intensity in Shandong and Henan provinces as the inflection signal for Chinese supply disruption and regional price spike potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Concentrate Supply | Jinduicheng-style mining asset control insulates margin from export quota volatility. |
| Zero-Liquid-Discharge Technology Licensing | MEE-compliant crystallization know-how transfers capture Indian and Indonesian greenfield demand. |
| MAPA Certification Investment | Brazilian qualified supplier status commands premium positioning in Cerrado micronutrient programs. |
| Continuous Crystallization Pilot Scale-Up | Steady-state precipitation systems tighten specification bands for electronics-grade derivatives. |
| Long-Term Supply Agreement with Water Utilities | Texas and California municipal retrofit programs lock in multi-year framework revenue visibility. |
Methodological Framework
Trade statistics from China Customs, Chilean copper-molybdenum export filings, and Brazil MAPA micronutrient registration databases formed the secondary backbone, cross-referenced with primary interviews across specialty fertilizer procurement managers, water utility corrosion engineers, and electronics plating technical directors. Bottom-up volume estimates from end-use consumption patterns and top-down supply-side capacity assessments were triangulated to reconcile demand and production figures.
Historical trendline analysis of molybdenum concentrate pricing, agricultural micronutrient consumption intensity, and electronics plating chemical demand established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted consumption projections, with forecast inputs including MEE enforcement trajectories, MAPA certification timelines, and REACH Annex XVII restriction proposals.
Concentrate export quota volatility, REACH substance evaluation fee escalation, and sodium molybdate substitution acceleration are the dominant revision risks that could compress ammonium molybdate demand assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
US Hydrochloric Acid Market