
 Europe Carbon Black Market | 2026-2036
Europe Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Carbon Black Market Intelligence
Buyer concentration among European tire manufacturers is shifting as original equipment makers consolidate supplier lists while specialty compounders fragment demand across smaller batch orders. Orion Engineered Carbons leverages its furnace black technology leadership to serve premium tire contracts. Birla Carbon sustains manufacturing scale across multiple European production sites. Cabot Corporation differentiates through conductive grade formulations for industrial rubber applications.
Carbon black is a colloidal carbon material produced by incomplete combustion or thermal decomposition of hydrocarbons, with primary particle sizes ranging from 10 to 500 nanometers and surface areas between 20 and 250 square meters per gram, functioning as a reinforcing filler and pigment in rubber and polymer systems. Tire grade carbon black occupies the largest volume share across European consumption due to steady replacement tire demand and OEM supply agreements. Specialty grade formulations represent the fastest-expanding margin pool as electronics and battery manufacturers specify ultra-pure conductive variants. Plastics applications anchor steady offtake from automotive interior and exterior component producers seeking UV stability and color consistency.
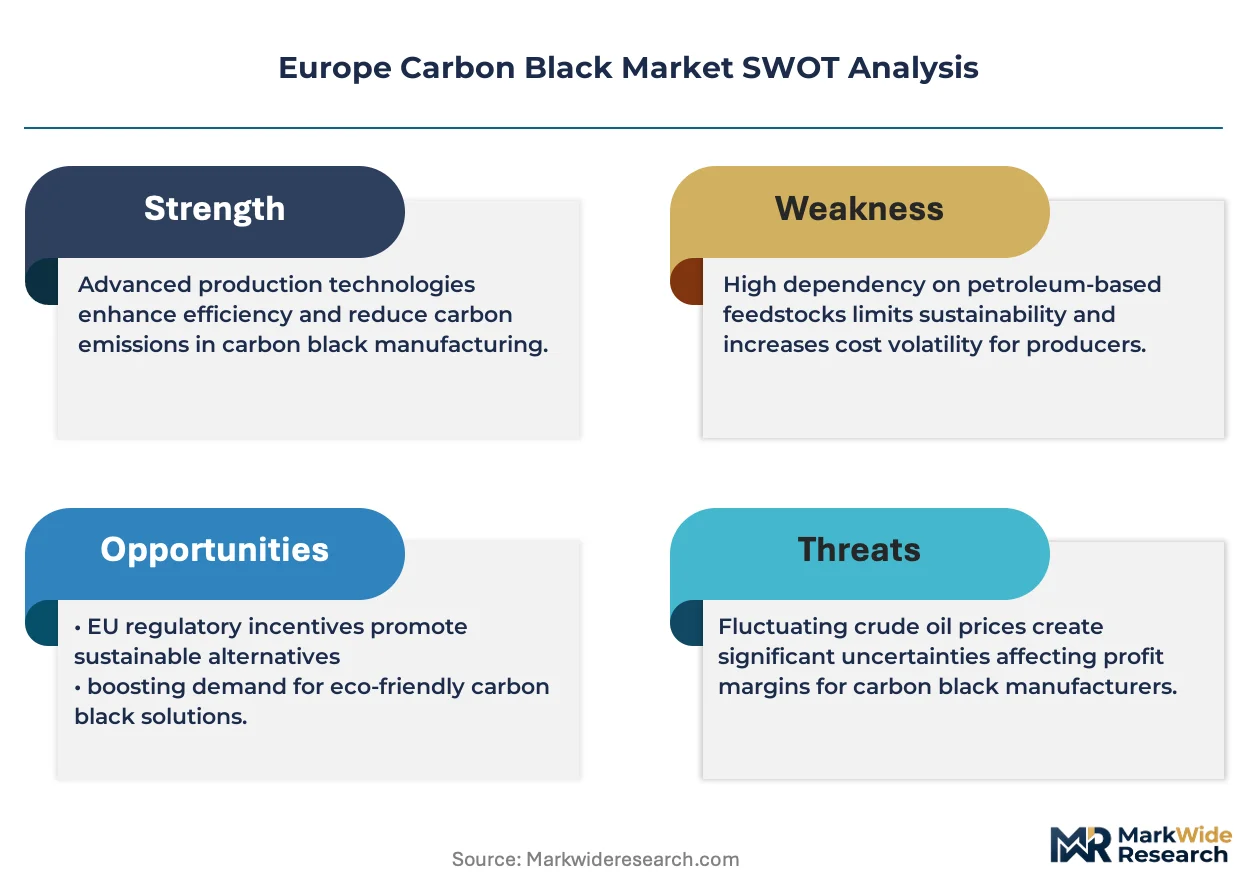
REACH registration requirements and the EU Green Deal carbon border adjustments constrain feedstock sourcing and production emissions across European carbon black facilities. ECHA substance evaluation protocols force reformulation of traditional oil-based furnace processes toward circular and bio-based carbon sources. The F-Gas Regulation indirectly shapes competitor positioning by altering refrigeration and chemical process economics. Stakeholders must monitor regulatory tightening on aromatic oil feedstocks and assess captive pyrolysis investments before compliance deadlines harden.
Market Dynamics
REACH substance evaluation protocols are forcing European carbon black producers to abandon traditional oil-based furnace processes and rebuild supply chains around circular and bio-based feedstocks before compliance deadlines harden.
Growth Catalysts
- EU Green Deal carbon border adjustments:Manufacturers investing in low-emission production gain preferential access to European tire OEM supply chains, accelerating capital deployment into sustainable furnace technologies.
- Electric vehicle battery housing demand:Specialty conductive grades specified by automotive Tier-1 suppliers for thermal management and electromagnetic shielding applications are expanding addressable volume.
- Poland and Germany tire manufacturing clusters:Concentrated OEM expansion in these production hubs is pulling sustainable carbon black procurement commitments from regional compounders.
Market Restraints
- Aromatic oil feedstock volatility:Traditional carbon black production depends on residual oils from petroleum refining, exposing margins to European refinery capacity fluctuations and carbon pricing.
- ECHA registration timelines:Novel bio-based and circular feedstock pathways face extended substance evaluation periods, delaying commercial scale-up of compliant production alternatives.
- Pyrolysis carbon black technical limitations:Tire-derived secondary feedstock produces inconsistent particle size distributions, constraining penetration into premium tire reinforcement grades.
Strategic Opportunities
- Spain and Italy specialty compounders:Fragmented mid-tier rubber processors in Southern Europe remain undersupplied with REACH-compliant sustainable grades, creating white space for targeted distribution partnerships.
- Plastics UV stabilization applications:Automotive exterior component producers are specifying high-dispersion masterbatch grades for color consistency, opening volume outside traditional tire demand.
- F-Gas Regulation process economics:Refrigerant phase-down mandates are altering chemical process cooling costs, favoring producers with heat-recovery furnace designs in regulatory arbitrage positioning.
Industry Challenges
- Process engineering talent scarcity:Furnace black production requires specialized combustion and particle formation expertise that is aging out of the European workforce faster than training programs replace it.
- Legacy asset retrofit complexity:Existing production sites face capital-intensive rebuilds to accommodate pyrolysis oil preprocessing and emissions capture systems without extended downtime.
- Batch-to-batch certification delays:Specialty grade customers demand ISO 17025-compliant testing documentation that extends order-to-delivery cycles and strains quality laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Carbon Black Market |
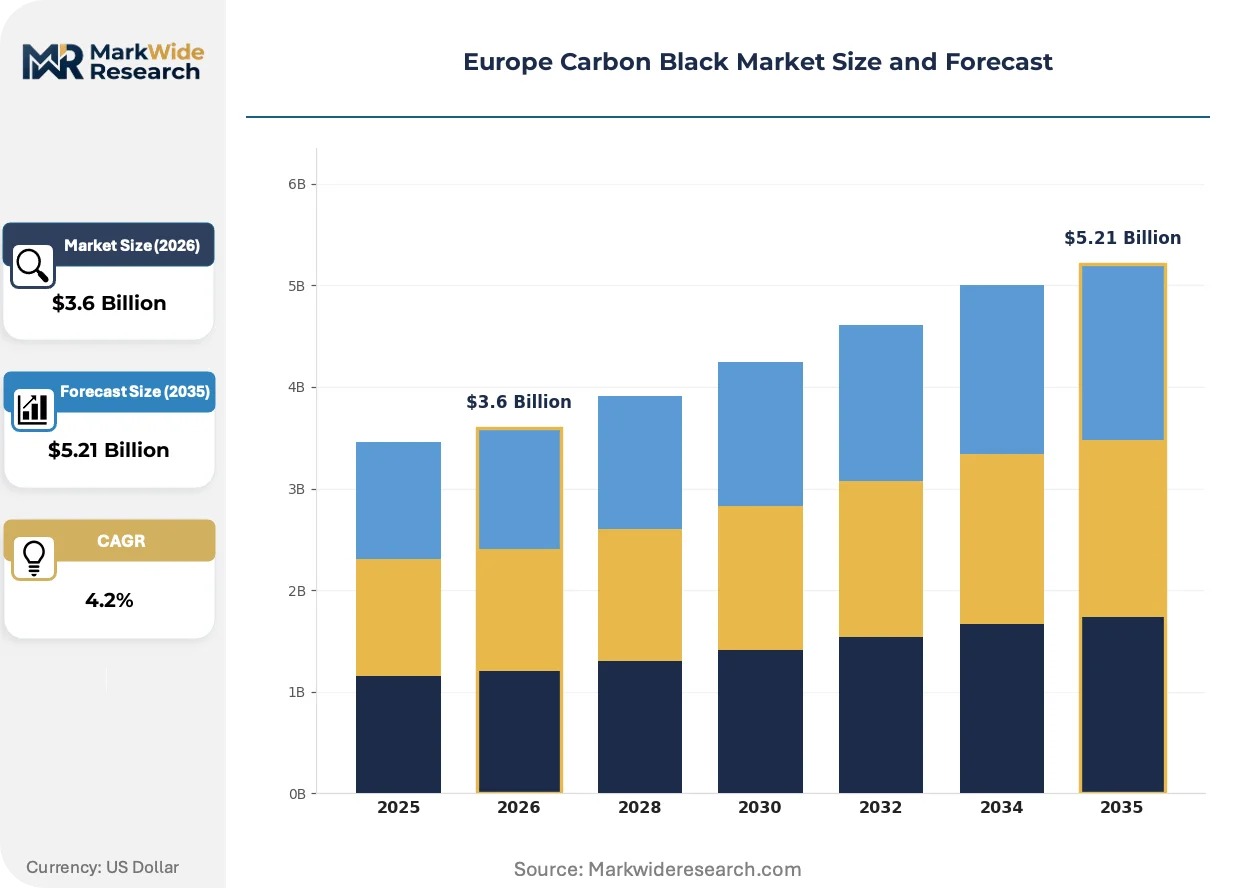
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.21 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tire Grade, Industrial Grade, Specialty Grade, Conductive Grade Application: Tires, Plastics, Coatings, Inks End User: Automotive, Electronics, Construction, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Omsk Carbon Group, Mitsubishi Chemical Corporation, Birla Carbon, Black Bear Carbon B.V., Imerys Graphite & Carbon, Cabot Corporation, Tokai Carbon Co., Ltd., Continental Carbon Company, Orion Engineered Carbons, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Carbon Black Market Strategic Shifts & Innovations
Pyrolysis-derived feedstock processing and plasma-based production methods are fragmenting the traditional furnace black technology monopoly, while REACH compliance automation and conductive grade purity standards are redefining competitive capability requirements.
Plasma arc carbon black production is decentralizing the geographic concentration of European manufacturing capacity. This technology converts methane or biogas directly into high-purity carbon black without furnace combustion, enabling modular plant deployment closer to feedstock sources. German industrial gas suppliers are piloting distributed production units at chemical parks in Ludwigshafen and Marl, compressing logistics costs for specialty grade customers.
F-Gas Regulation amendments are tightening process cooling requirements across chemical manufacturing, indirectly reshaping carbon black plant economics. The regulation's phase-down of hydrofluorocarbon refrigerants forces producers to adopt ammonia-based or heat-recovery cooling systems, favoring facilities with integrated energy recovery designs. Dutch and Belgian production sites with cogeneration infrastructure are capturing operating cost advantages against older standalone furnaces.
Specification-driven procurement consolidation is compressing supplier lists among European tire OEMs. Buyers are unbundling compound development from volume supply contracts, awarding formulation partnerships to technical specialists while directing commodity tonnage to lowest-compliant bidders. This bifurcation is most visible in Germany, where Volkswagen Group and Continental AG operate parallel sourcing tracks for premium versus replacement tire compounds.
Europe Carbon Black Market Segmentation
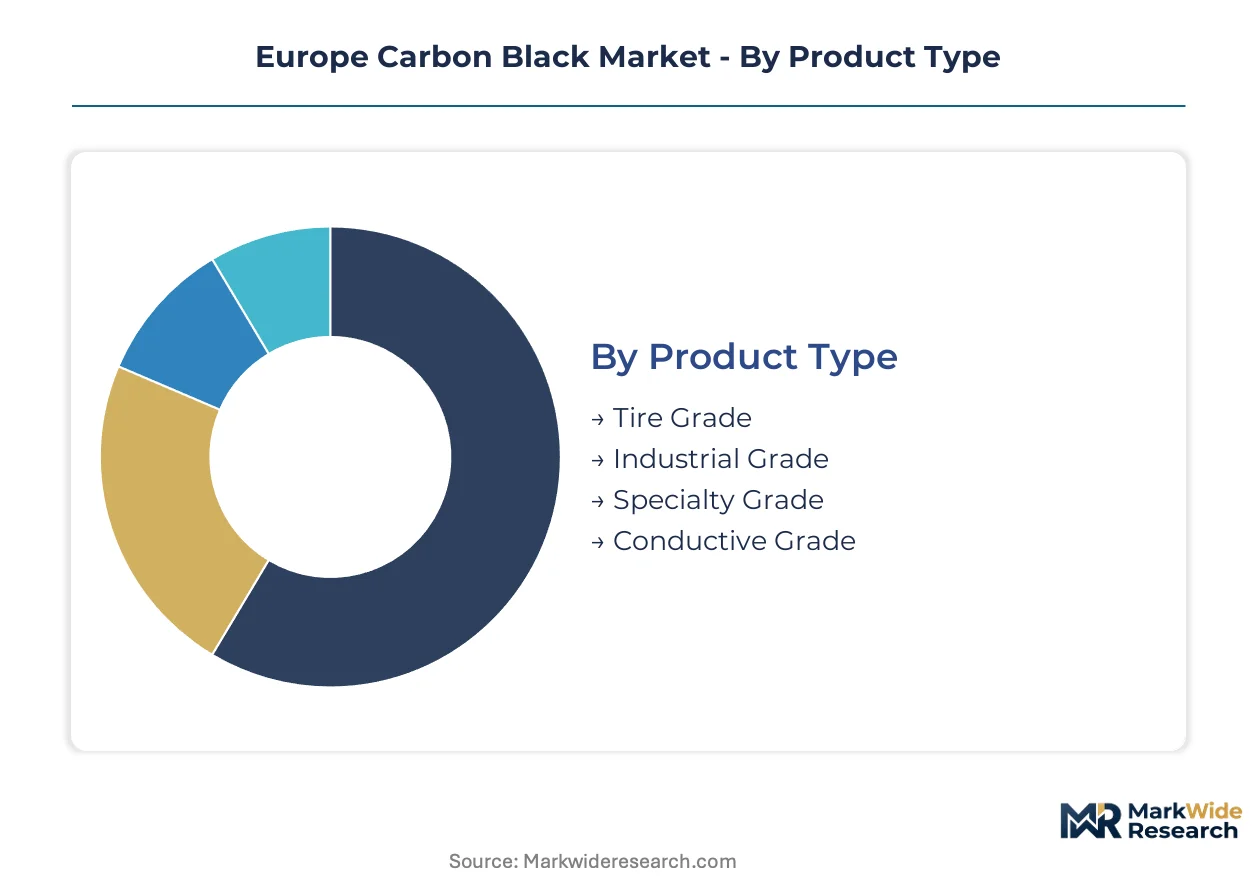
European carbon black procurement increasingly segments around REACH compliance tiers rather than traditional performance metrics. Buyers now distinguish sustainable-certified grades from legacy furnace production, reshaping how suppliers structure product portfolios and geographic coverage.
Product Type:
The customization-standardization spectrum runs from commodity tire grades with minimal formulation variance to specialty conductive variants engineered to precise conductivity and purity specifications.
- Tire Grade:Furnace-produced carbon black with ASTM N100-N900 classifications provides tread reinforcement and abrasion resistance. German and Polish tire OEMs are consolidating procurement around REACH-compliant sustainable variants for premium contracts.
- Specialty Grade:Ultra-pure formulations with controlled particle size distributions below 30 nanometers serve electromagnetic shielding and thermal management applications. Electric vehicle battery housing manufacturers in Germany specify these grades for Tier-1 automotive supply chains.
- Industrial Grade:Mid-tier reinforcement filler for conveyor belts and mechanical rubber goods across European manufacturing.
- Conductive Grade:Surface-area-optimized variants for plastics compounding and antistatic applications in electronics manufacturing.
Leading the category by volume: Tire Grade. Expanding most quickly: Specialty Grade.
Application:
Cost tier stratification separates high-volume tire compounds from premium coatings and ink formulations where dispersion quality commands price premiums.
- Tires:Tread, sidewall, and carcass compounds consume the majority of European carbon black volume. OEM supply agreements with Continental AG and Michelin anchor demand for N234 and N550 grades.
- Plastics:Masterbatch applications for automotive exterior components require UV stabilization and color consistency. Italian and Spanish compounders drive offtake for high-dispersion grades in bumper and trim manufacturing.
- Coatings:Pigment-grade carbon black with controlled jetness specifications for industrial and automotive finishes.
- Inks:Publication and packaging ink formulations demanding specific rheological properties.
Highest volume concentration: Tires. Steepest margin expansion: Plastics.
End User:
Customer type segmentation distinguishes consolidated automotive procurement from fragmented electronics and construction demand patterns.
- Automotive:Tier-1 suppliers and tire OEMs dominate volume with specification-driven procurement. Volkswagen Group and Stellantis operations across Germany, Italy, and Poland consolidate supplier lists around REACH-compliant sustainable grades.
- Electronics:Battery manufacturers and EMI shielding component producers specify ultra-pure conductive grades with batch certification requirements.
- Construction:Roofing membrane and sealant compounders across Spain and Italy generate steady offtake for industrial-grade reinforcement.
- Consumer Goods:Plastics processors serving appliance and packaging applications with color masterbatch requirements.
Consolidated procurement leaders: Automotive. Fastest specification tightening: Electronics.
Distribution Channel:
Supply concentration varies from direct mill relationships for tire OEMs to fragmented distributor networks serving mid-tier compounders.
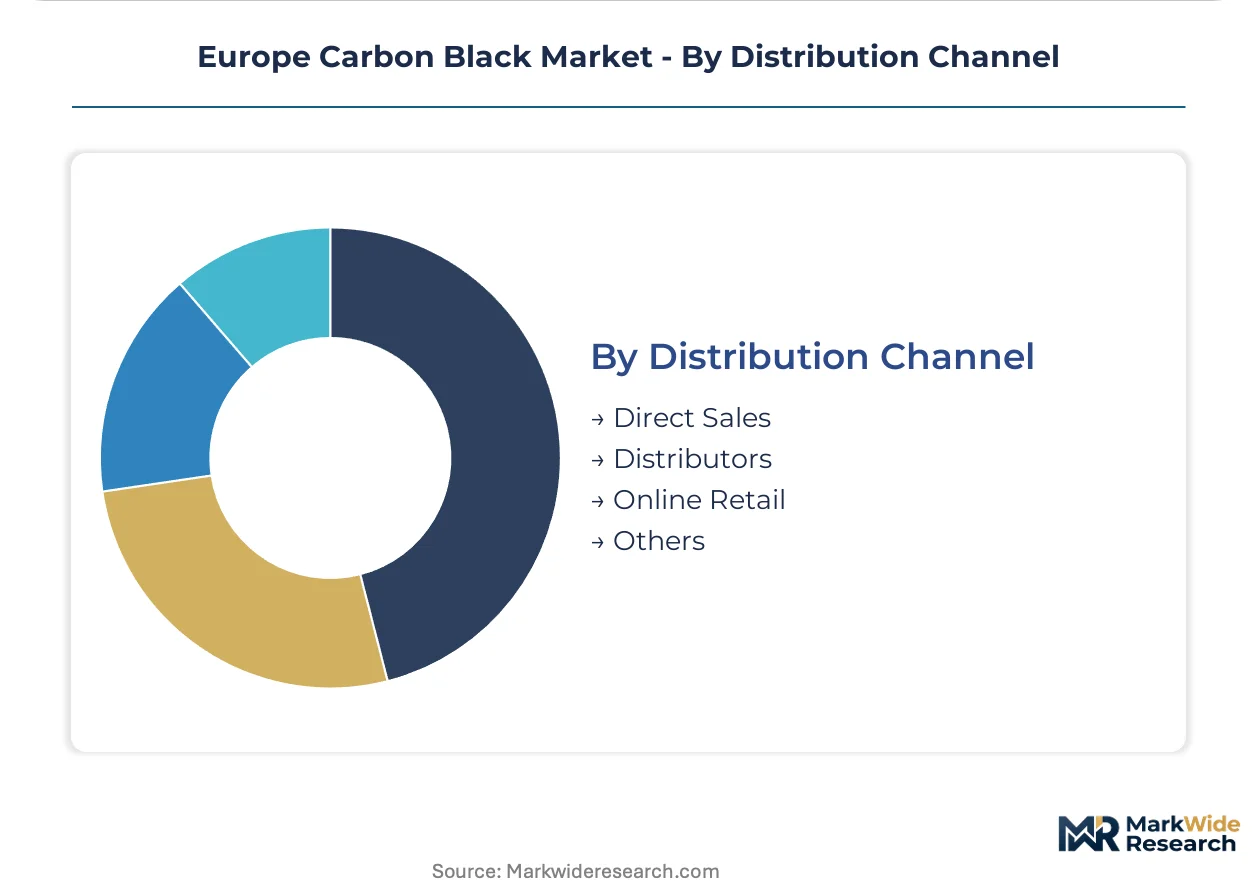
- Direct Sales:Long-term supply agreements between carbon black producers and major tire manufacturers. Orion Engineered Carbons and Birla Carbon maintain dedicated account teams for German and Polish OEM procurement offices.
- Distributors:Regional chemical distributors serve fragmented specialty compounders in Southern Europe with smaller batch requirements and technical support needs.
- Online Retail:Emerging channel for standard-grade masterbatch and small-volume industrial orders.
- Others:Agent-mediated sales for specific geographic or application niches.
Dominant channel by tonnage: Direct Sales. Growing fastest: Distributors serving REACH-compliant specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tire OEM procurement concentrates in German and Polish manufacturing clusters, pulling sustainable carbon black demand toward Central Europe while specialty compounders fragment orders across Southern Europe.
Germany
Volkswagen Group and Continental AG anchor premium tire compound demand with REACH-compliant sustainable grade specifications. The EU Green Deal carbon border adjustments tighten feedstock compliance timelines for suppliers serving Bavarian and North Rhine-Westphalia production sites. Ludwigshafen and Marl chemical parks host pilot plasma arc production units that compress logistics costs for specialty grade customers.
Poland
Tire manufacturing expansion by Bridgestone and Michelin subsidiaries drives procurement consolidation around N234 and N550 furnace grades. ECHA substance evaluation protocols force reformulation timelines on compounders supplying OEM plants near Poznań and Wrocław. The country's industrial zones attract pyrolysis feedstock preprocessing investments to meet impending aromatic oil restrictions.
Italy
Automotive exterior component producers in Lombardy and Emilia-Romagna specify high-dispersion masterbatch grades for UV stabilization applications. The F-Gas Regulation phase-down alters process cooling economics for compounders serving Fiat and Stellantis supply chains. Milan-Turin industrial corridors remain undersupplied with REACH-certified sustainable grades, creating distribution partnership opportunities.
Spain
Fragmented mid-tier rubber processors across Catalonia and Valencia generate steady offtake for industrial-grade reinforcement in roofing membranes and mechanical goods. ECHA registration timelines delay commercial scale-up of bio-based feedstock alternatives for domestic compounders. Barcelona chemical parks lack integrated pyrolysis capacity, forcing reliance on imported compliant material.
Netherlands
Rotterdam port logistics and Antwerp chemical corridor proximity position Dutch facilities for feedstock arbitrage across Northwest European markets. Cogeneration infrastructure at Dutch production sites captures operating cost advantages against older standalone furnaces under tightening F-Gas cooling requirements. Specialty conductive grade demand from electronics manufacturers concentrates near Eindhoven's high-tech cluster.
Europe Carbon Black Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue circular feedstock and plasma-based production methods. Three distinct competitive archetypes populate the European market: integrated multinational suppliers with furnace black technology leadership, mid-scale regional compounders specializing in REACH-compliant formulations, and technology-driven challengers commercializing pyrolysis and bio-based alternatives. Capacity expansion and strategic partnerships dominate competitive moves, with incumbents retrofitting legacy assets and newcomers securing feedstock agreements ahead of compliance deadlines.
Among integrated multinational suppliers, Orion Engineered Carbons, Birla Carbon, and Cabot Corporation exemplify distinct positioning archetypes. Orion represents furnace black technology leadership serving premium tire contracts through dedicated account structures. Birla Carbon anchors manufacturing scale across multiple European production sites with geographic coverage depth. Cabot Corporation occupies conductive grade formulation specialization for industrial rubber and plastics applications. These three entities collectively illustrate how compliance tier differentiation and application-specific technical capability define competitive separation in procurement consolidation environments.
| Leading Market Players |
|---|
| Omsk Carbon Group |
| Mitsubishi Chemical Corporation |
| Birla Carbon |
| Black Bear Carbon B.V. |
| Imerys Graphite & Carbon |
| Cabot Corporation |
| Tokai Carbon Co., Ltd. |
| Continental Carbon Company |
| Orion Engineered Carbons |
| Others |
Cost & Logistics Intelligence
Residual oil index movements cascade through European carbon black supply chains, compressing margins at legacy furnace operations while REACH-compliant sustainable grades command premium positioning against aromatic oil volatility. Tire OEMs in Germany and Poland leverage volume concentration to negotiate contract tiering that reflects feedstock certification costs.
Pricing Analysis
Volume-margin splits separate commodity tire grades from specialty conductive variants, with pricing stratifying across REACH-certified sustainable, transitional low-aromatic, and legacy high-emission tiers. Price differentiation rests on ECHA registration status and carbon intensity certification, with German automotive OEMs showing lowest price sensitivity for battery housing grades. Cost compression in standard tire reinforcement is intensifying because pyrolysis feedstock inconsistencies force quality discounts.
Supply Chain Analysis
Dual-sourcing requirements from Continental AG and Michelin procurement offices force compounders to qualify multiple furnace black suppliers across Germany, Poland, and the Netherlands. Feedstock dependencies center on residual oils from Rotterdam refinery complexes, tire-derived pyrolysis streams, and emerging bio-based naphtha alternatives. Single-source vulnerability concentrates in plasma arc technology licensing from German industrial gas suppliers. Distribution runs through direct mill relationships for tire OEMs and regional chemical distributors for Southern European compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe carbon black market operates as a cost-of-compliance story where REACH substance evaluation protocols erect capital-intensive barriers that protect incumbent positions against unqualified competitors.
For Market Incumbents: Lock in pyrolysis feedstock preprocessing capacity at Polish and German production sites before ECHA registration deadlines harden. Secure dedicated account structures with Volkswagen Group and Stellantis procurement offices to defend against plasma arc technology challengers. Prioritize heat-recovery furnace retrofits that capture F-Gas Regulation arbitrage advantages against older standalone assets. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Germany open a window for distributed plasma arc production units at Ludwigshafen and Marl chemical parks. Target specialty conductive grade supply to Eindhoven electronics manufacturers and Milan-Turin automotive exterior compounders underserved by REACH-certified distribution. Pursue toll-manufacturing partnerships with established distributors lacking sustainable grade portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional compounders with partial ECHA registration progress in Spain and Italy. Long-term viability hinges on feedstock flexibility across circular, bio-based, and conventional streams. Watch pyrolysis oil preprocessing yield consistency as the inflection signal separating scalable from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Feedstock Preprocessing Investment | ECHA registration timelines force early-mover advantage in tire-derived secondary feedstock qualification. |
| Plasma Arc Production Deployment | Modular units at German chemical parks compress logistics costs for specialty grade battery housing customers. |
| Heat-Recovery Furnace Retrofit | F-Gas Regulation phase-down mandates favor integrated energy recovery designs at Dutch and Belgian sites. |
| REACH-Compliant Distribution Partnership | Southern European compounders in Spain and Italy remain undersupplied with sustainable certified grades. |
| Conductive Grade Purity Certification | Electric vehicle battery manufacturers specify ultra-pure variants with ISO 17025-compliant batch documentation. |
Research Approach
Multi-period observation of ECHA registration progress, EU Green Deal implementation milestones, and tire OEM procurement consolidation anchored the trend analysis, supplemented by interviews with furnace black plant managers, REACH compliance officers at compounders, automotive Tier 1 procurement leads, and specialty carbon black distribution partners. Secondary validation drew from customs trade data, Cefic chemical industry reports, SEC 10-K filings of listed producers, and EU emissions trading scheme disclosures. Bottom-up volume estimates from individual production site capacities triangulated against top-down tire and plastics consumption models.
Segment-weighting across tire grade, specialty grade, industrial grade, and conductive grade categories shaped the analytical framework, with further disaggregation by REACH compliance tier and end-use industry concentration. CAGRs were derived from regression analysis of historical pricing and volume relationships, adjusted for regulatory phase-in schedules and feedstock substitution elasticities. Key inputs included aromatic oil price volatility indices, pyrolysis capacity buildout announcements, and electric vehicle production forecasts from German and Polish automotive clusters.
The model assumes a particular technology adoption path favoring gradual plasma arc scaling; alternative pathways for methane pyrolysis or bio-based furnace feedstocks would alter the outlook for incumbent asset valuations. Deviation in ECHA substance evaluation timelines or EU carbon border adjustment implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Ammonium Thiosulfate Market