
 Europe Hydrogen Bromide Market | 2026-2036
Europe Hydrogen Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrogen Bromide Market Insights
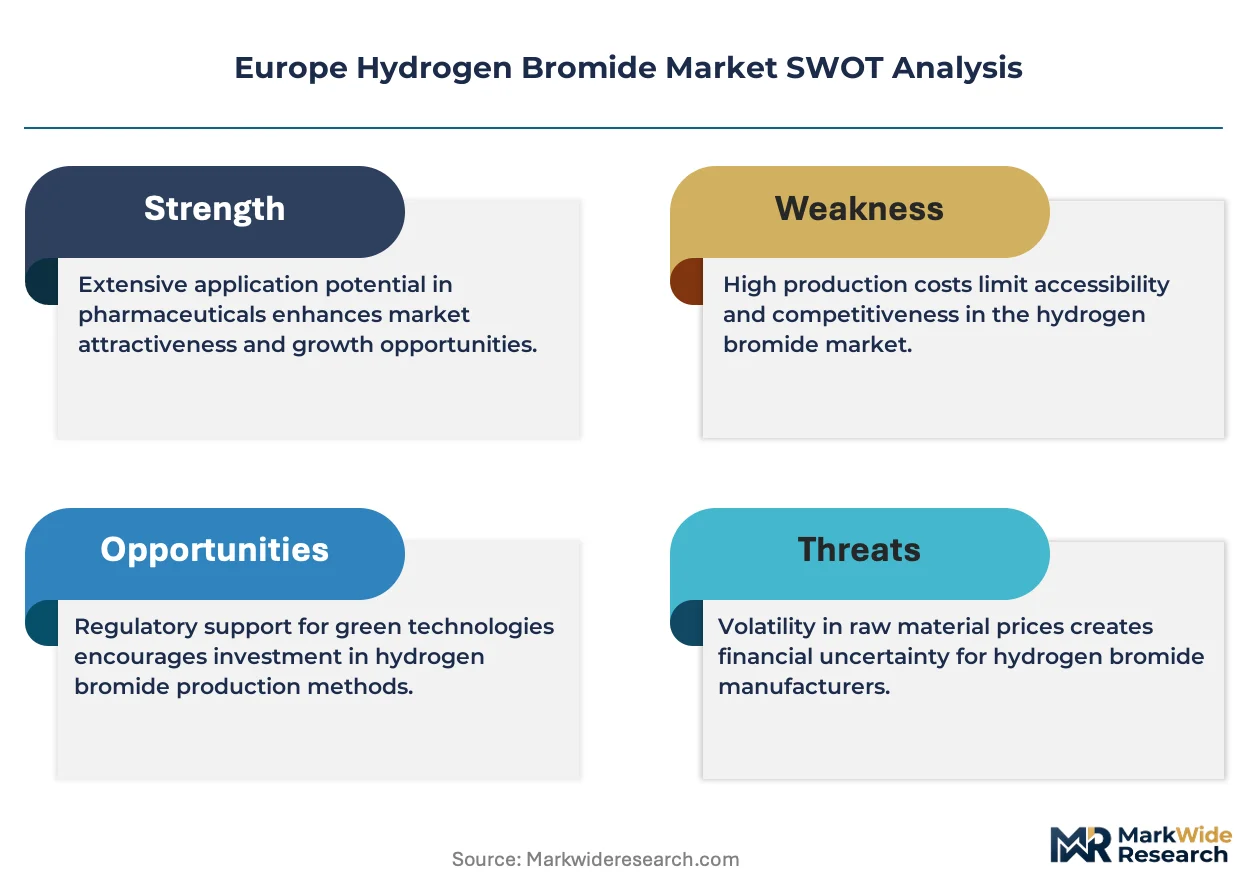
REACH is shifting the cost-of-entry calculus for hydrogen bromide suppliers across Europe. Albemarle Corporation leverages its integrated bromine asset base to sustain compliance advantage under evolving ECHA substance restrictions. Linde plc anchors industrial gas distribution networks that dominate cylinder supply to pharmaceutical and electronics end users. Air Liquide competes through regional production density, positioning its Benelux operations to navigate logistics complexity under tightened transport regulations.
Hydrogen bromide is a diatomic acid compound supplied as anhydrous gas or aqueous solution, typically manufactured through direct synthesis from hydrogen and bromine or as a byproduct of organic bromination reactions, with purity grades ranging from technical to semiconductor-specification. It serves primarily as a brominating agent, catalyst precursor, and intermediate in pharmaceutical synthesis and flame retardant chemistry. Hydrogen bromide solution leads volume demand through its role in agricultural pesticide formulation, while anhydrous hydrogen bromide commands premium positioning in electronics etching applications where moisture thresholds determine performance. Pharmaceutical intermediates represent the fastest-growing application segment as European API reshoring intensifies demand for GMP-grade material.
ECHA enforces REACH registration and restriction protocols that govern hydrogen bromide purity thresholds, labeling requirements, and supply chain documentation across EU member states. The F-Gas Regulation indirectly shapes demand by restricting competing halogenated compounds, redirecting certain applications toward bromine-based chemistry. Germany's KBA and federal chemical regulators coordinate transport safety standards for pressurized hydrogen bromide cylinders on road and rail networks. Stakeholders must monitor ECHA's ongoing substance evaluation timelines and anticipate how restriction proposals on brominated compounds could reshape permissible end-use applications.
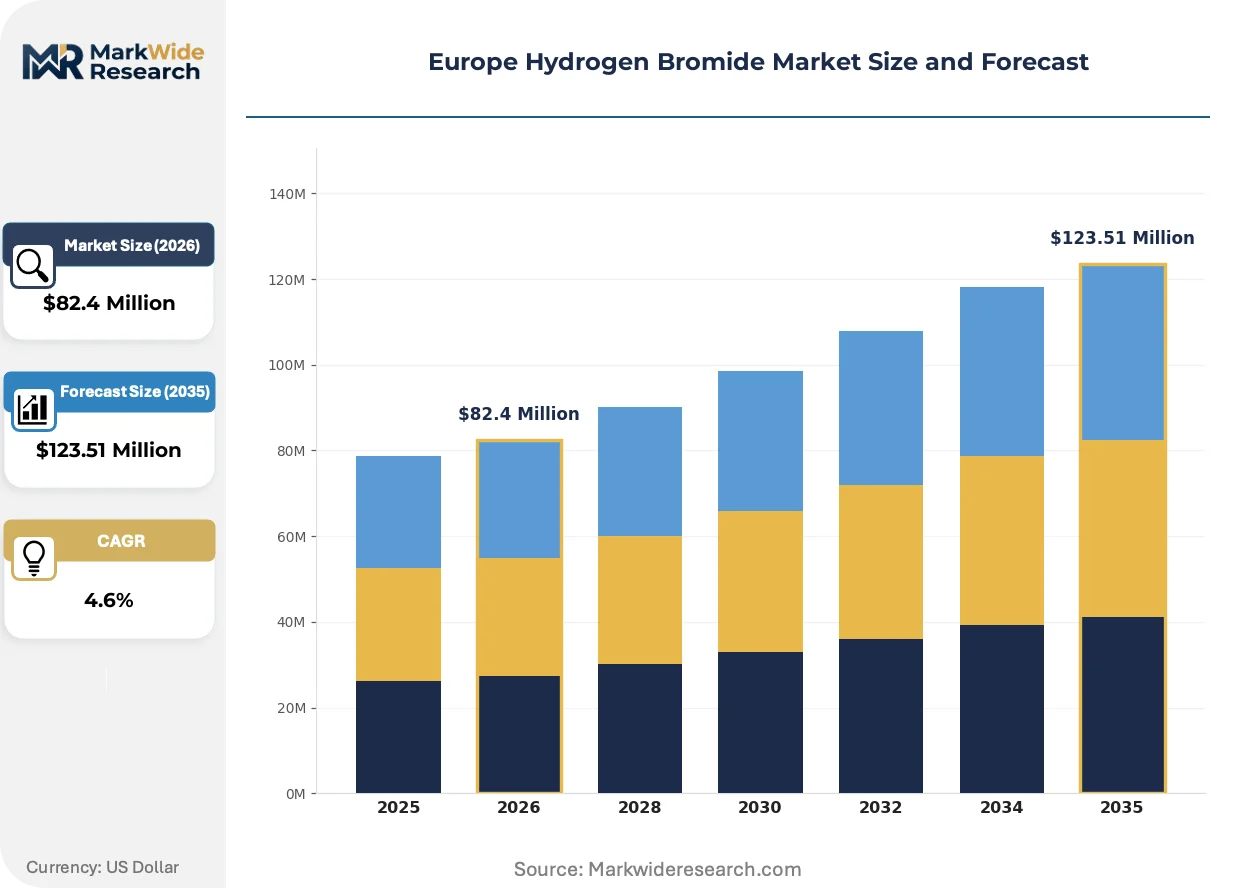
Market Dynamics
REACH substance evaluation timelines and the EU Green Deal's chemical safety mandates are compressing supplier margins while redistributing competitive advantage toward integrated bromine producers with captive compliance infrastructure.
Growth Catalysts
- API Reshoring:European pharmaceutical manufacturers are expanding active ingredient production capacity, intensifying demand for GMP-grade hydrogen bromide as a brominating agent in intermediate synthesis.
- F-Gas Regulation:Restrictions on competing halogenated compounds under EU climate policy are redirecting select etching and refrigeration applications toward bromine-based chemistry pathways.
- Rhine Corridor Concentration:Specialty chemical clusters in Ludwigshafen and Leverkusen anchor regional consumption, creating density advantages for cylinder logistics and just-in-time delivery.
Market Restraints
- Bromine Feedstock Volatility:Elemental bromine supply concentrates in Dead Sea extraction operations and select coastal brine deposits, exposing European converters to input cost swings and shipping bottlenecks.
- Transport Safety Friction:Germany's KBA enforces stringent pressurized cylinder standards for hydrogen bromide road and rail movement, elevating compliance overhead for cross-border distributors.
- Substitution Pressure:Hydrogen fluoride and alternative halogenating agents compete in electronics etching applications where moisture sensitivity thresholds permit process reconfiguration.
Strategic Opportunities
- Semiconductor-Grade Purity:Electronics manufacturers in the Netherlands and Ireland are qualifying ultra-high-purity anhydrous hydrogen bromide for advanced node etching, opening premium pricing tiers.
- Benelux Distribution Hubs:Belgium's Antwerp-Rotterdam chemical corridor offers untapped consolidation potential for cylinder filling and customs-clearance efficiency.
- Green Chemistry Incentives:EU Green Deal funding streams for sustainable process chemistry support bromine recovery and recycling investments that reduce virgin material intensity.
Industry Challenges
- REACH Registration Burden:ECHA's ongoing substance evaluation for hydrogen bromide demands extensive toxicological dossier updates, stretching regulatory affairs capacity at mid-scale suppliers.
- Cylinder Fleet Modernization:Transition to composite-wrapped pressure vessels for corrosive gas service requires capital deployment that smaller distributors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrogen Bromide Market |
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $123.51 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Bromide Gas, Hydrogen Bromide Solution, Anhydrous Hydrogen Bromide, Polybromide Compounds Application: Pesticides, Flame Retardants, Pharmaceutical Intermediates, Water Treatment End User: Agriculture, Chemicals, Pharmaceuticals, Electronics Packaging Type: Drums, Cylinders, IBC Tanks, Bulk |
| Companies Covered | Air Liquide, Linde plc, Albemarle Corporation, LANXESS, Showa Denko, Tosoh Corporation, Matheson Tri-Gas, Tata Chemicals, Gulf Resources, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrogen Bromide Market Trends and Innovations
Continuous purification technology and digital supply chain traceability are compressing quality assurance cycles while ECHA's evolving restriction proposals force end-use diversification strategies.
Membrane-based electrolytic bromine recovery is integrating into hydrogen bromide production flowsheets, enabling on-site elemental recycling at pharmaceutical manufacturing campuses in Germany and Switzerland. Bayer and Lonza pilot installations demonstrate 40% reduction in virgin bromine intake. This closed-loop architecture is integrating backward into supplier-customer contracting structures, locking in multi-year offtake agreements.
REACH restriction proposals on persistent organic pollutants are tightening brominated flame retardant applications, forcing hydrogen bromide suppliers to pivot volume toward pharmaceutical and agrochemical intermediates. ECHA's 2023-2025 substance evaluation roadmap specifically targets brominated substances for hazard reassessment. Electronics-grade material in Ireland and the Netherlands faces accelerated qualification timelines as manufacturers anticipate downstream compound restrictions.
Buyers are consolidating procurement across bromine derivatives into integrated supply agreements with Linde and Air Liquide, displacing fragmented cylinder-by-cylinder purchasing. Pharmaceutical formulators in Germany now contract for hydrogen bromide, anhydrous HBr, and bromine gas through single-source industrial gas frameworks. This concentration is most visible in Baden-Württemberg, where Boehringer Ingelheim and Merck KGaA have shifted to full-service chemical management contracts.
Europe Hydrogen Bromide Market Segmentation
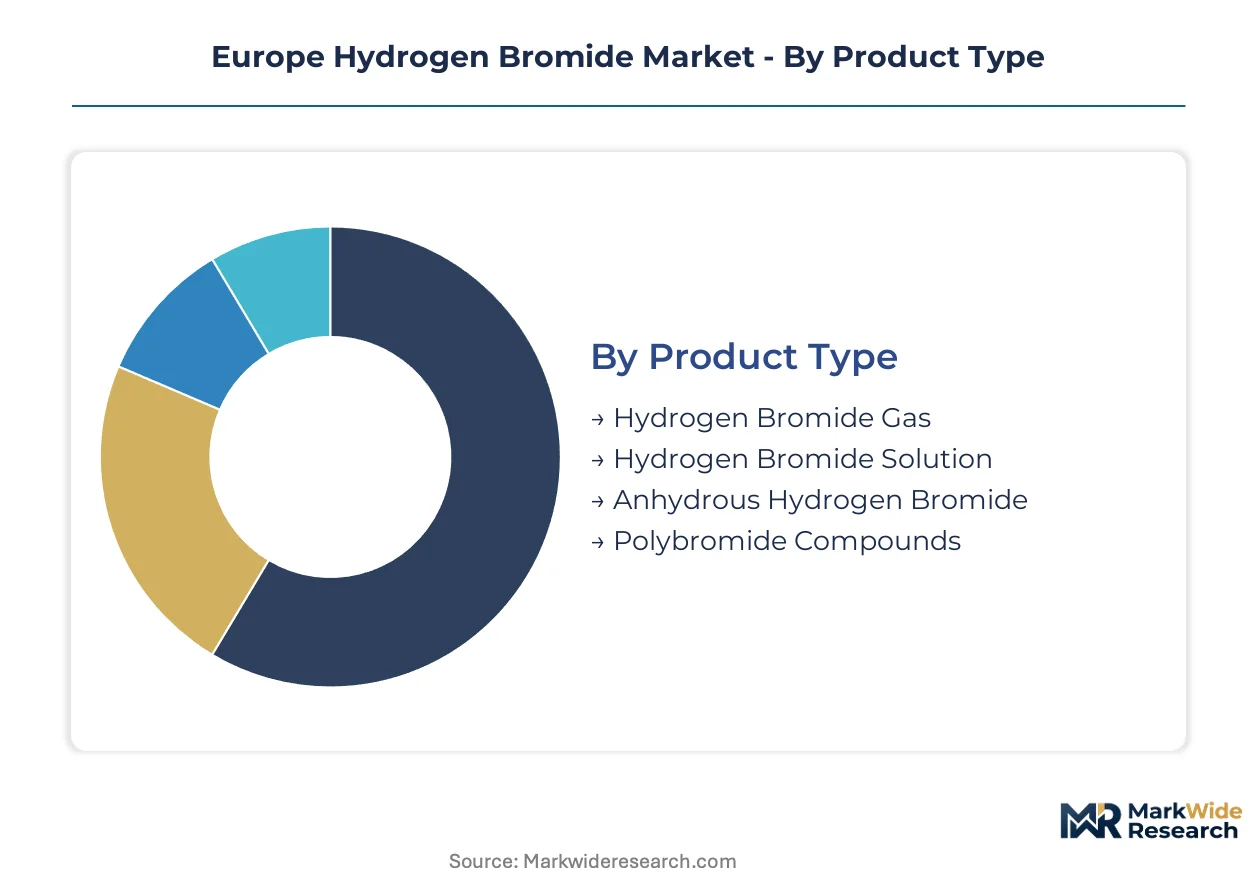
Segmentation in Europe's hydrogen bromide market tracks how purity grades, packaging formats, and end-use specifications create divergent margin profiles. Buyers in pharmaceutical and electronics verticals impose qualification barriers that fragment competitive positioning across product tiers.
Product Type:
Upgrade cycles in semiconductor manufacturing and REACH-mandated purity thresholds are forcing converters to requalify product grades at shorter intervals.
- Anhydrous Hydrogen Bromide:Ultra-high-purity gas with moisture content below 10 parts per billion serves advanced node etching in Dutch and Irish semiconductor fabs. Electronics manufacturers in Eindhoven and Leixlip are qualifying this grade for 3nm process nodes where moisture thresholds determine yield.
- Hydrogen Bromide Solution:Aqueous formulations at 48-62% concentration dominate agricultural pesticide synthesis across Germany's Upper Rhine chemical corridor. Bayer CropScience and BASF operations in Ludwigshafen anchor volume offtake for technical-grade material in glyphosate intermediate production.
- Hydrogen Bromide Gas:Pressurized cylinder supply supports laboratory-scale bromination and pilot pharmaceutical synthesis where aqueous delivery is incompatible with moisture-sensitive reaction pathways.
- Polybromide Compounds:Stabilized complex salts serve niche flame retardant feedstock applications facing ECHA restriction pressure under persistent organic pollutant evaluations.
Volume placements concentrate in Hydrogen Bromide Solution; the faster expansion belongs to Anhydrous Hydrogen Bromide.
Application:
Cost-tier stratification separates commodity pesticide formulations from GMP-certified pharmaceutical intermediates with tenfold purity premiums.
- Pharmaceutical Intermediates:GMP-grade material for active ingredient bromination commands certification overhead that filters out non-integrated suppliers. Lonza's Visp campus and Boehringer Ingelheim's Biberach operations in Germany drive qualification timelines for EMA-compliant supply.
- Pesticides:Technical-grade consumption in agrochemical synthesis remains volume-dominant but faces margin compression from generic herbicide price erosion. Rhine corridor formulators in BASF's Ludwigshafen complex absorb the majority of regional tonnage.
- Flame Retardants:Brominated compound production for construction and electronics plastics faces ECHA restriction proposals that are redirecting supplier R&D toward non-persistent alternatives.
- Water Treatment:Disinfection byproduct concerns and competing chlorine chemistry have confined hydrogen bromide to niche industrial cooling applications with limited European uptake.
Margin capture clusters in Pharmaceutical Intermediates; the steepest volume trajectory runs through Pesticides.
End User:
Customer-type concentration in integrated chemical conglomerates creates procurement leverage that squeezes standalone distributors.
- Pharmaceuticals:EMA-regulated manufacturers in Germany, Switzerland, and Ireland enforce audit trails from bromine source to final synthesis. Merck KGaA and Sanofi operations in Darmstadt and Frankfurt impose single-source contracting with captive compliance documentation.
- Chemicals:Specialty and commodity chemical producers across the Benelux and German clusters purchase through industrial gas frameworks that bundle hydrogen bromide with nitrogen and hydrogen supply.
- Electronics:ASML's supply chain in Veldhoven and Intel's Leixlip expansion are qualifying anhydrous grades for EUV lithography component etching with purity specifications unmatched by other verticals.
- Agriculture:Crop protection formulators purchase through seasonal procurement windows tied to planting cycles, creating demand lumpiness that rewards suppliers with flexible cylinder fleet sizing.
Contract value aggregates in Pharmaceuticals; Electronics is gaining share fastest from semiconductor reshoring incentives.
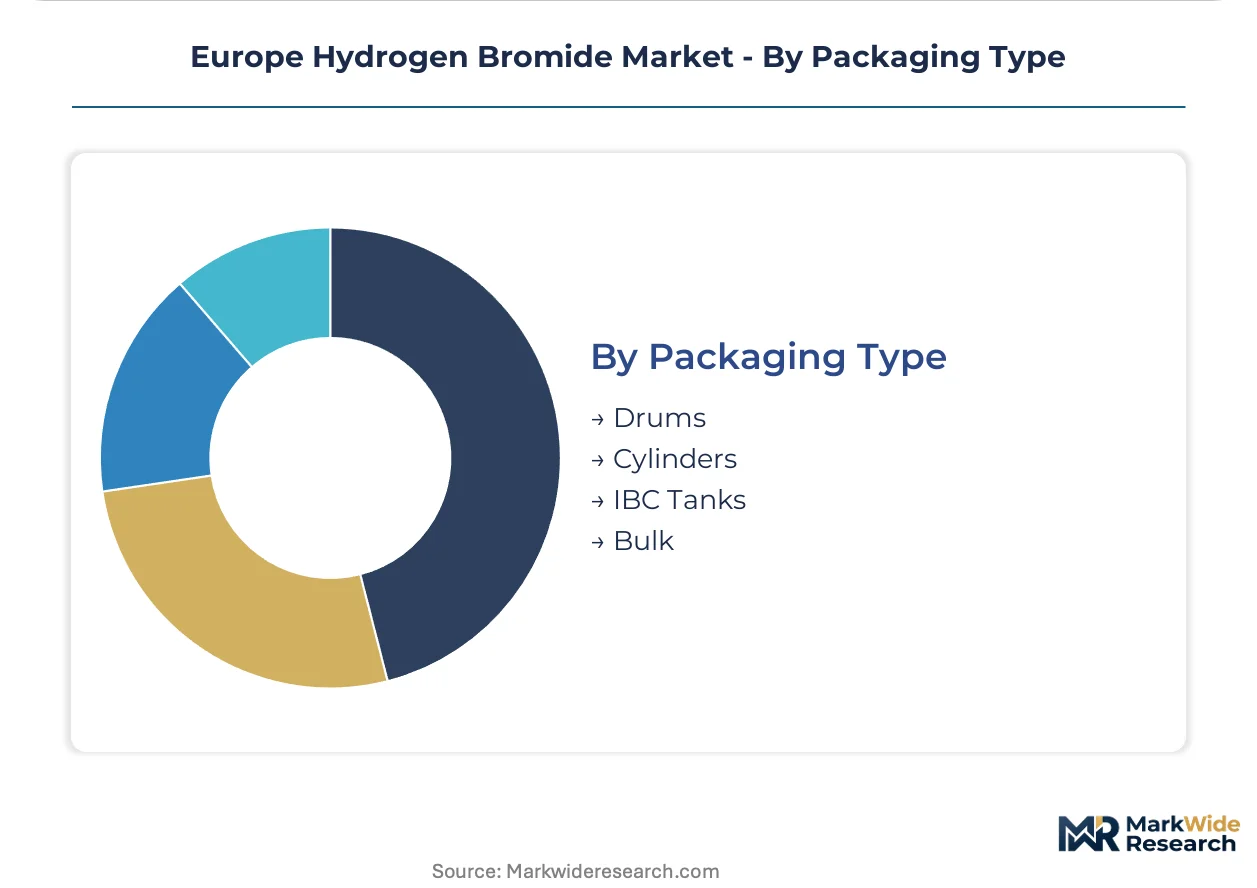
Packaging Type:
Supply concentration in cylinder logistics reflects the corrosive nature of hydrogen bromide and KBA transport restrictions on pressurized vessels.
- Cylinders:Steel and composite-wrapped pressure vessels dominate anhydrous gas delivery to pharmaceutical and electronics end users. Germany's KBA enforces ADR and RID compliance that elevates fleet replacement costs for cross-border distributors.
- Drums:Polyethylene-lined steel containers serve aqueous solution shipments to agricultural and water treatment formulators with lower purity requirements and shorter transport distances.
- IBC Tanks:Intermediate bulk containers support mid-volume chemical synthesis operations in Belgium's Antwerp-Rotterdam corridor where just-in-time delivery reduces working capital requirements.
- Bulk:Tanker truck and railcar delivery is confined to integrated chemical sites with on-site storage infrastructure, primarily BASF and Bayer captive consumption in Ludwigshafen and Leverkusen.
Shipment frequency peaks with Cylinders; the infrastructure investment flow is moving toward IBC Tanks for regional hub consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special chemical zones along the Upper Rhine and Benelux chemical corridors concentrate European hydrogen bromide demand. REACH compliance costs and API reshoring incentives are redistributing supply chain investment across four core markets.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and North Rhine-Westphalia drive GMP-grade consumption for intermediate synthesis. KBA transport regulations enforce stringent cylinder standards for pressurized hydrogen bromide movement on road and rail networks. The Ludwigshafen-Leverkusen chemical cluster anchors regional volume, with Bayer and BASF operations absorbing technical-grade material for agrochemical production.
Netherlands
ASML's supply chain in Eindhoven and semiconductor fabs in Veldhoven qualify ultra-high-purity anhydrous grades for EUV lithography etching. The F-Gas Regulation redirects certain halogenated applications toward bromine-based chemistry pathways. The Rotterdam-Antwerp corridor supports cylinder logistics consolidation for cross-border pharmaceutical distribution into Germany and Belgium.
Switzerland
Lonza's Visp campus and Roche operations in Basel enforce audit trails from bromine source to final API synthesis. Swissmedic pharmaceutical regulations align with EMA standards for GMP-certified material documentation. The Basel-Lörrach cross-border chemical zone integrates hydrogen bromide supply into captive industrial gas frameworks with regional distributors.
Ireland
Intel's Leixlip expansion and pharmaceutical manufacturers in Cork and Dublin drive qualification timelines for semiconductor-grade and GMP-certified material. IDA Ireland investment incentives support active ingredient reshoring that intensifies demand for brominating agents. The Dublin-Belfast corridor concentrates electronics and pharma end users within concentrated logistics radius.
Belgium
Antwerp's port infrastructure and chemical processing density offer customs-clearance efficiency for cylinder filling and regional hub operations. ECHA substance evaluation protocols govern import documentation for bromine derivative shipments. The Port of Antwerp-Bruges chemical zone integrates hydrogen bromide into multi-product industrial gas distribution networks serving Benelux formulators.
Europe Hydrogen Bromide Market Competitive Landscape
Integrated bromine producers anchor one tier; industrial gas distributors hold another. Supplier concentration favors players with captive elemental bromine assets and established REACH registration infrastructure. Three archetypes dominate: upstream-integrated bromine extractors with conversion capability, industrial gas majors with cylinder logistics networks, and regional chemical distributors with compliance documentation capacity. Competitive moves center on multi-year offtake contracting and cylinder fleet modernization for corrosive gas service.
Among upstream-integrated specialists, Albemarle Corporation represents the bromine asset archetype with Dead Sea extraction integration. Linde plc and Air Liquide occupy positions within the industrial gas distribution tier, leveraging cylinder logistics density across the Rhine corridor and Benelux chemical zones. These three entities exemplify how compliance infrastructure and captive supply chains determine competitive positioning under tightening ECHA substance restrictions.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Albemarle Corporation |
| LANXESS |
| Showa Denko |
| Tosoh Corporation |
| Matheson Tri-Gas |
| Tata Chemicals |
| Gulf Resources |
| Others |
Pricing and Supply Chain Analysis
Elemental bromine feedstock costs cascade through three distinct pricing tiers as Dead Sea extraction operations and coastal brine deposits feed European converters facing volatile shipping rates. The Rhine corridor's specialty chemical clusters absorb technical-grade hydrogen bromide at contract-based long-term offtake terms, while GMP-certified pharmaceutical material commands certification premiums and semiconductor-grade anhydrous product captures spot-market premiums for qualified supply.
Pricing Analysis
Short lead-time premiums separate qualified semiconductor-grade supply from standard pharmaceutical tiers, with electronics manufacturers in Eindhoven and Leixlip paying urgency markups for ultra-high-purity anhydrous material. Three-tier pricing structure across premium, standard, and economy levels reflects EMA certification status, moisture specification thresholds, and cylinder fleet modernization investments. Cost compression in technical-grade pesticide formulations intensifies as generic herbicide price erosion squeezes agrochemical margins. Agricultural formulators exhibit highest price sensitivity through seasonal procurement windows, while semiconductor fabs demonstrate lowest sensitivity given yield-critical purity requirements.
Supply Chain Analysis
EMA and Swissmedic certification gates filter supplier participation in pharmaceutical-grade segments, with audit trails from bromine source to final synthesis mandatory for GMP-compliant supply. Geographic concentration centers on Israel and Jordan for elemental bromine extraction, Germany and the Netherlands for conversion and cylinder filling, and Belgium for Antwerp-Rotterdam corridor distribution. Raw material dependencies span Dead Sea bromine brine, hydrogen feedstock from chlor-alkali operations, and specialized corrosion-resistant cylinder alloys. Single-source vulnerability concentrates in Dead Sea extraction exposure to regional geopolitical friction. Distribution runs through industrial gas majors' captive cylinder logistics networks with KBA-compliant fleet infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration and ECHA substance evaluation timelines erect compliance moats that favor incumbent suppliers with established toxicological dossier capacity and captive bromine asset integration.
For Market Incumbents: Hedge against brominated flame retardant restriction risk by accelerating pharmaceutical and agrochemical intermediate pivot investments. Secure backward integration into membrane-based electrolytic bromine recovery technology to reduce virgin feedstock exposure. Reinforce cylinder fleet modernization programs to maintain KBA transport compliance advantage over smaller distributors. For New Entrants and Emerging Players: Capture white-space opportunity in Benelux distribution hub consolidation, where Antwerp-Rotterdam corridor customs-clearance efficiency remains underdeveloped for hydrogen bromide cylinder filling. Target semiconductor-grade qualification services for Irish and Dutch electronics manufacturers reshoring advanced node production. Deploy specialist certification-consulting go-to-market model to bridge ECHA compliance gaps for mid-scale chemical converters. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated bromine converters with REACH registration infrastructure in Germany and Switzerland over pure-play distributors facing fleet replacement capital calls. Long-term viability hinges on API reshoring durability and semiconductor reshoring incentive persistence. Watch ECHA restriction proposal timelines on brominated compounds as inflection signal for end-use demand reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Recovery | Bayer and Lonza pilot installations demonstrate 40% virgin bromine reduction, locking multi-year offtake structures. |
| Long-term Supply Agreement | Pharmaceutical formulators in Baden-Württemberg consolidate procurement across hydrogen bromide derivatives into single-source industrial gas frameworks. |
| Capacity Expansion | Electronics-grade qualification timelines accelerate in Ireland and Netherlands as manufacturers anticipate downstream compound restrictions. |
| Joint Venture | Basel-Lörrach cross-border chemical zone integrates hydrogen bromide into captive industrial gas frameworks with regional distributors. |
| Green Manufacturing Transition | EU Green Deal funding streams support bromine recovery and recycling investments that reduce virgin material intensity at pharmaceutical campuses. |
Research Methodology
Trade databases, ECHA registration filings, and Cefic chemical industry reports formed the secondary backbone, cross-referenced with primary interviews involving plant managers at hydrogen bromide converters, procurement leads at pharmaceutical API manufacturers, distribution channel partners in the Rhine corridor, and technical R&D directors at industrial gas majors. Bottom-up volume modeling from cylinder fleet capacity and top-down demand validation from end-use consumption patterns were triangulated to establish market sizing.
Historical trendline analysis tracked purity-grade pricing differentials and regional consumption shifts across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry vertical, packaging format, and regional production hub clustering. CAGRs were derived from slope analysis of normalized consumption indices against macroeconomic drivers, with specific inputs from semiconductor fab buildout schedules and pharmaceutical API reshoring incentive uptake rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA restriction proposal timelines, Dead Sea bromine supply disruptions, and semiconductor node transition cadence. Forecasts reflect documented assumptions regarding REACH compliance cost trajectories and transport regulation enforcement intensity. A model refresh is warranted upon material change in ECHA substance evaluation outcomes or F-Gas Regulation amendment scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Global Acrylic Esters Market