
 Global Performance Coating Market | 2026-2036
Global Performance Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Performance Coating Market Foresight
Automotive OEMs is recalibrating demand patterns across the performance coating value chain as electric vehicle architectures require specialized thermal management and corrosion protection layers. PPG Industries leverages its electrodeposition expertise to anchor supply relationships with battery enclosure manufacturers. Akzo Nobel NV sustains R&D intensity in low-temperature cure technologies for lightweight substrates.
Performance coatings constitute engineered thin-film barriers applied to substrates through processes including electrocoating, thermal spraying, and UV curing, typically ranging from 25 to 500 microns in dry-film thickness to deliver corrosion resistance, wear protection, or aesthetic finish in harsh operating environments. Waterborne coatings leads formulation innovation as environmental compliance tightens, while powder coatings occupies the fastest-growing margin pool through zero-VOC profiles and over-spray recyclability. UV-curable coatings competes on throughput speed in electronics and wood finishing lines.
EPA regulations in the United States restrict hazardous air pollutant emissions from coating operations, while REACH and the EU Green Deal in Europe mandate substitution of chrome-based pretreatments and perfluorinated compounds. China's MEE enforces national VOC emission standards for industrial coating processes. Stakeholders must monitor regulatory divergence between jurisdictions when configuring product portfolios and manufacturing footprints.
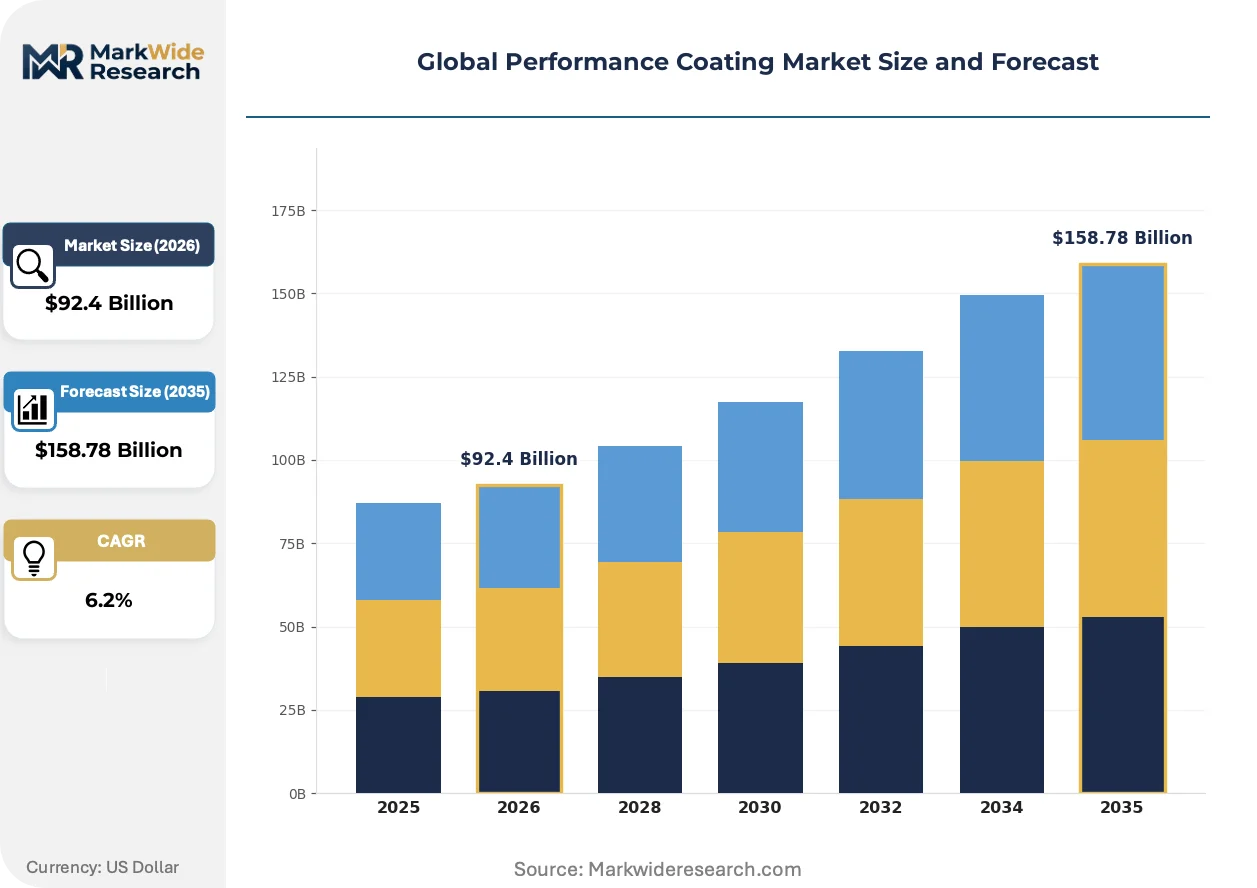
Market Dynamics
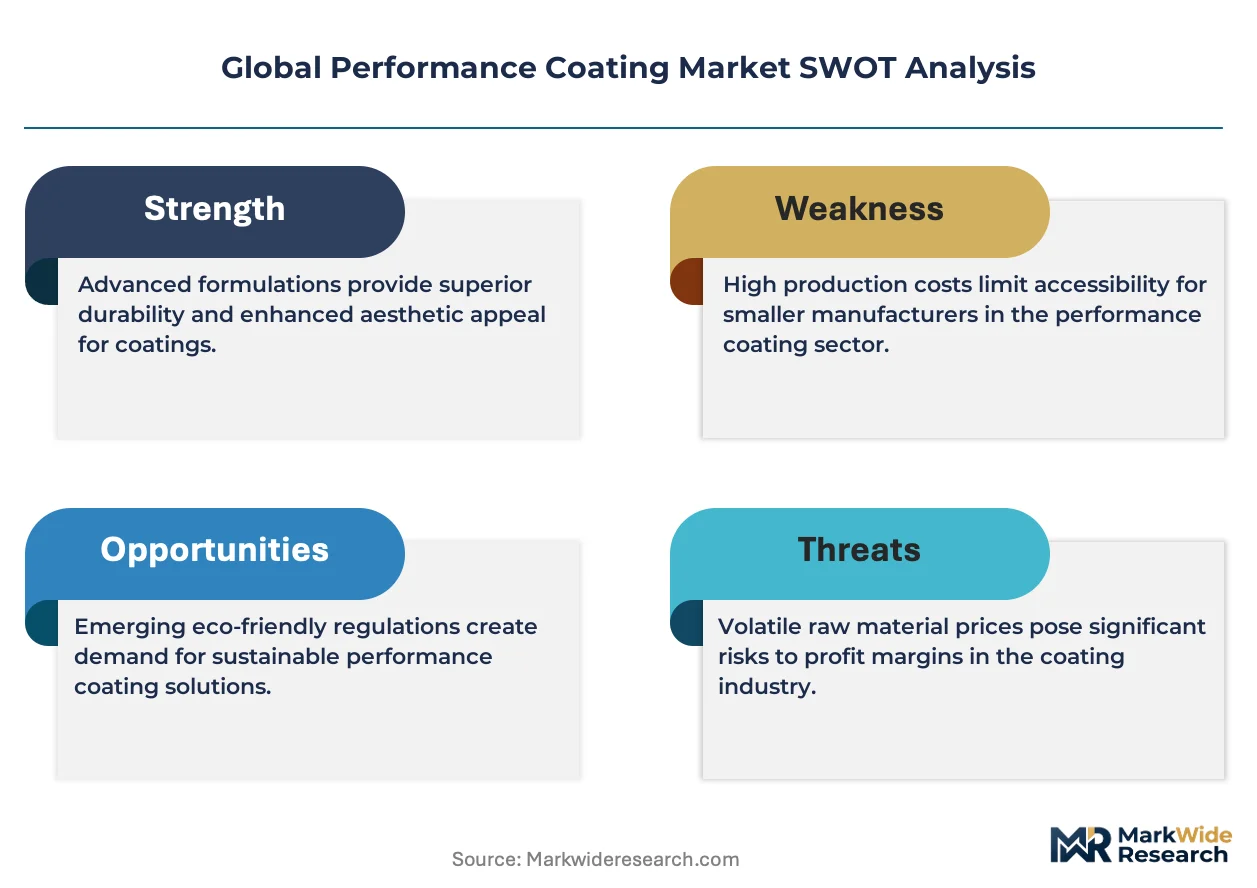
Automotive electrification is compressing coating specification cycles as battery thermal management and dielectric isolation requirements displace traditional corrosion-focused formulations across OEM supply chains.
Growth Catalysts
- EV Battery Enclosure Demand:Electric vehicle manufacturers require specialized ceramic and epoxy coatings for thermal runaway protection, pulling formulation innovation toward higher temperature tolerances.
- REACH Chrome Substitution Mandate:ECHA's restriction on hexavalent chromium pretreatments accelerates trivalent and chrome-free conversion coating adoption across European automotive and aerospace finishing lines.
- China Shipbuilding Concentration:Yangtze River Delta and Pearl River Delta clusters concentrate demand for marine anti-fouling and ballast tank coatings through state-backed fleet expansion programs.
Market Restraints
- Titanium Dioxide Volatility:Pigment cost swings compress margins for architectural and industrial coating producers, forcing reformulation toward alternative opacifiers.
- Specialty Resin Supply Concentration:Fluoropolymer and silicone resin production concentrates among German and Japanese chemical conglomerates, creating single-source vulnerability for high-performance formulations.
- Low-Temperature Cure Limitation:Energy-curable systems face substrate adhesion failures on polypropylene and other low-surface-energy plastics, restricting penetration in lightweight automotive interiors.
Strategic Opportunities
- India Industrial Infrastructure:PLI scheme incentives for domestic manufacturing create localized coating demand for machinery, electrical equipment, and consumer durable production facilities.
- Offshore Wind Corrosion Protection:Subsea monopile and transition piece specifications require novel splash-zone coating systems with 25-year maintenance-free warranties.
- UV-LED Curing Convergence:Mercury lamp phase-outs under Minamata Convention obligations intersect with LED efficiency gains, enabling retrofit opportunities across existing wood and electronics finishing lines.
Industry Challenges
- Formulation Chemist Scarcity:Retirement waves among experienced polymer scientists strain R&D pipeline velocity for custom resin development programs.
- Multi-Jurisdiction Certification Timelines:Divergent VOC testing protocols between EPA Method 24, ISO 11890, and China's GB standards extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Performance Coating Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne Coatings, Solventborne Coatings, Powder Coatings, UV-Curable Coatings End User: Aerospace, Automotive OEMs, Electronics, Marine Application: Protective Coatings, Decorative Coatings, Industrial Coatings, Automotive Finishes Technology: Electrocoating, Spraying Technology, Brush Application, Roller Application |
| Companies Covered | BASF SE, PPG Industries, Akzo Nobel NV, The Sherwin-Williams Company, Jotun A/S, Daikin Industries Ltd, Hempel Group, Axalta Coating Systems, Nippon Paint Holdings Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Performance Coating Market Shifts & Advancements
Coating functionality is migrating from passive protection toward active performance as smart materials and digital manufacturing integrate into specification requirements.
Self-healing polymer networks incorporating microencapsulated healing agents are consolidating repair autonomy into automotive clearcoats and aerospace leading-edge protection. Mercedes-Benz and Boeing maintenance divisions specify these systems for abrasion-prone surfaces, compressing warranty claim exposure and extending recoat intervals beyond conventional polyurethane benchmarks.
EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) for surface coating operations tightens methylene chloride and perchloroethylene limits, forcing metal finishing shops toward waterborne and high-solids alternatives. Aerospace OEMs in Wichita and Savannah clusters accelerate thermal spray and physical vapor deposition adoption to sidestep solvent-based compliance costs entirely.
Specification authority is concentrating among sustainability procurement officers who weight Environmental Product Declarations and Health Product Declarations above traditional performance metrics. Healthcare and education construction verticals in California and New York now mandate third-party verified low-emitting materials, displacing incumbent suppliers lacking ISO 14025 documentation.
Global Performance Coating Market Segmentation
Performance coating procurement diverges sharply across end-use verticals, with aerospace demanding certified thermal spray specifications while automotive OEMs prioritize line-speed compatibility. Formulation chemistry and application method together determine margin structure and regulatory compliance pathways.
Product Type:
Buyers differentiate primarily by VOC compliance burden and energy curing requirements, with environmental mandates reshaping procurement specifications across industrial verticals.
- Waterborne Coatings:Acrylic and polyurethane dispersions replace solventborne systems in automotive refinishing and general industrial maintenance. European REACH enforcement and EPA NESHAP limits accelerate specification shifts in Germany and Michigan manufacturing clusters.
- Powder Coatings:Thermoset epoxy and polyester formulations deliver zero-VOC profiles with near-complete overspray recovery. Appliance manufacturers in Turkey and Mexico favor these systems for cabinet and frame finishing where edge coverage and chip resistance outweigh color complexity constraints.
- Solventborne Coatings:High-solids alkyds and two-component polyurethanes retain foothold in marine and heavy equipment segments where substrate adhesion and humidity tolerance override environmental priorities.
- UV-Curable Coatings:Acrylate oligomer formulations dominate wood furniture and electronics conformal coating lines in Guangdong and Vietnam assembly plants.
Volume sits with waterborne systems; growth tilts toward powder coatings.
End User:
Specification authority concentrates among OEM engineering teams who validate coating performance through accelerated weathering and corrosion testing protocols.
- Automotive OEMs:Electrification demands ceramic thermal barrier coatings for battery enclosures and dielectric layers for high-voltage architectures. Volkswagen and BYD procurement teams now embed coating suppliers at vehicle platform development stages.
- Aerospace:Chromate-free pretreatments and polysulfide sealants face FAA airworthiness certification timelines stretching 18-24 months. Boeing and Airbus supply chains in Wichita and Toulouse concentrate demand for qualified thermal spray and PVD finishes.
- Electronics:Conformal coatings for PCB protection in smartphones and EV power electronics require ultra-thin parylene and acrylic applications in Shenzhen and Seoul manufacturing hubs.
- Marine:Anti-fouling biocide regulations from IMO and national flag authorities drive copper-free and silicone-hydrogel coating adoption in Shanghai and Busan shipyards.
Procurement scale favors automotive OEMs; specification complexity peaks in aerospace.
Application:
Functional requirements separate protective specifications from aesthetic priorities, with industrial maintenance demanding recoatability over appearance metrics.
- Protective Coatings:Zinc-rich primers and epoxy intermediate coats shield steel infrastructure in offshore wind installations and petrochemical facilities. North Sea and Gulf of Mexico project specifications now require 25-year maintenance-free warranties for splash-zone systems.
- Industrial Coatings:Machinery and electrical equipment finishes prioritize chemical resistance and electrical insulation in Indian and Indonesian manufacturing expansion zones.
- Decorative Coatings:Architectural metal finishes for curtain wall and fenestration systems emphasize color consistency and chalking resistance in Dubai and Singapore high-rise construction.
- Automotive Finishes:Basecoat-clearcoat systems integrate self-healing clearcoats and effect pigments for premium segment differentiation.
Protective applications command premium pricing; industrial coatings drive volume throughput.
Technology:
Capital equipment intensity and substrate geometry dictate method selection, with complex geometries favoring immersion processes over line-of-sight techniques.
- Electrocoating:Cathodic epoxy electrodeposition delivers uniform edge coverage for automotive body-in-white and appliance components. PPG and Axalta operate dedicated e-coat tanks adjacent to major OEM assembly plants in Spartanburg and Saarlouis.
- Spraying Technology:HVLP and airless systems dominate field maintenance and architectural metal finishing where portability and substrate size preclude tank processes.
- Brush Application:Maintenance touch-up and small-batch industrial repair retain manual methods for accessibility and equipment minimization.
- Roller Application:Flat panel and flooring coatings in prefabricated construction modules favor roller deposition for speed and film build control.
Electrocoating anchors automotive volume; spraying technology spans the broadest substrate range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate marine and electronics coating demand through state-backed shipbuilding expansion and PCB manufacturing clusters. Germany's automotive belt and US Gulf Coast petrochemical corridors anchor formulation R&D and protective coatings procurement respectively.
China
Shanghai and Jiangsu province shipyards drive marine anti-fouling consumption through state fleet modernization programs. MEE national VOC emission standards enforce waterborne system adoption across industrial coating processes. Shenzhen and Dongguan electronics clusters pull conformal coating demand for smartphone and EV power electronics manufacturing.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify low-temperature cure systems for lightweight substrate compatibility. REACH hexavalent chromium restrictions accelerate trivalent conversion coating qualification timelines. Stuttgart and Munich engineering centers embed coating suppliers at electric vehicle platform development stages.
United States
EPA NESHAP hazardous air pollutant limits force metal finishing shops toward waterborne and high-solids alternatives. Gulf Coast offshore wind installations in Texas and Louisiana require 25-year splash-zone coating warranties. Wichita and Savannah aerospace clusters concentrate demand for FAA-certified thermal spray and PVD finishes.
India
PLI scheme incentives for domestic manufacturing create localized machinery and electrical equipment coating demand. BIS standards enforcement tightens formulation quality requirements for industrial maintenance applications. Gujarat and Maharashtra industrial corridors attract protective coatings procurement for new production facilities.
Japan
METI dual carbon goals accelerate powder coating adoption in appliance and automotive component manufacturing. JIS standards govern automotive refinishing specification authority. Nagoya and Osaka industrial zones sustain fluoropolymer resin demand for high-performance electronics and chemical processing equipment.
Global Performance Coating Market Competitive Landscape
Top-tier vendors anchor formulation innovation and OEM supply chain integration, while mid-tier specialists occupy regional maintenance and industrial niches. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive resin production, independent coating formulators with application expertise, and regional distributors with local service networks. Dominant competitive moves include backward integration into specialty resin production and geographic expansion through dedicated e-coat tank installations adjacent to major OEM assembly plants.
Among integrated chemical conglomerates, BASF SE and PPG Industries exemplify the scale-driven archetype with electrodeposition expertise and global manufacturing footprints. Akzo Nobel NV occupies a position within the premium formulation tier, representing sustained R&D intensity in environmental compliance technologies. These three entities anchor the competitive structure through their respective strengths in resin chemistry, OEM supply relationships, and low-temperature cure innovation.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries |
| Akzo Nobel NV |
| The Sherwin-Williams Company |
| Jotun A/S |
| Daikin Industries Ltd |
| Hempel Group |
| Axalta Coating Systems |
| Nippon Paint Holdings Co. Ltd |
| Others |
Supply & Pricing Matrix
UV-LED curing equipment retrofits across Guangdong wood finishing lines and Jiangsu automotive plants compress energy costs and capital recovery timelines while redistributing formulation procurement power toward resin suppliers with captive photoinitiator production. This technology transition simultaneously tightens margin pools for mercury-lamp-dependent applicators and elevates pricing leverage for oligomer manufacturers in Japan and Germany.
Pricing Analysis
Short lead-time premiums of 15-25% apply to qualified thermal spray and PVD specifications for Wichita aerospace clusters facing FAA certification deadlines, while spot inventory discounts emerge for standard waterborne primers in oversupplied European distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates OEM-embedded formulation partnerships from regional maintenance distributors and commodity architectural suppliers. Cost compression in powder coating feedstocks intensifies because titanium dioxide volatility and epoxy resin tightness squeeze mid-tier formulators. Maintenance contractors in Indian industrial corridors exhibit highest price sensitivity due to bid-competitive procurement, while battery enclosure manufacturers accept premium positioning for thermal runaway protection systems.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for specialty resin and pigment intermediates, with last-mile delivery contracting to localized blending facilities adjacent to OEM assembly plants. Fluoropolymer production concentrates in Japan and Germany, while epoxy resin manufacturing feeds from South Korea and China, creating geographic interdependence for high-performance formulations. Single-source vulnerability for silicone resin and photoinitiator feedstocks elevates supply chain risk exposure. Distribution runs through authorized distributor networks with technical service bundling for aerospace and automotive specification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The performance coating sector is consolidating around backward integration into specialty resin production and captive electrodeposition tank installations, with formulation expertise and OEM supply chain embedding as the decisive competitive levers.
For Market Incumbents: Anchor electrodeposition capacity adjacent to Volkswagen and BYD platform development stages to lock in battery enclosure thermal management specifications, while accelerating trivalent chromium conversion coating qualification ahead of ECHA enforcement timelines. Defensive patent positioning around low-temperature cure technologies for polypropylene substrates counters emerging entrants targeting lightweight automotive interiors. For New Entrants and Emerging Players: Launch via UV-LED curing system retrofits in Vietnam electronics assembly and Turkish appliance manufacturing, where mercury lamp phase-out deadlines create immediate equipment replacement demand. White-space concentration sits with chrome-free pretreatment formulations for European aerospace maintenance facilities facing REACH substitution mandates, with technical service partnerships as the preferred go-to-market mechanism. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking electrodeposition expertise and regional distribution density. Long-term viability favors targets with captive resin production and embedded OEM platform relationships. Monitor ECHA restriction proposal timelines for hexavalent chromium as the inflection signal for chrome-free formulation valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive fluoropolymer and silicone production secures margin control against German and Japanese chemical conglomerates. |
| Electrodeposition Tank Co-location | Dedicated e-coat installations adjacent to Spartanburg and Saarlouis OEM plants embed supply relationships at platform stage. |
| Chrome-Free Pretreatment Qualification | Trivalent conversion coating certification ahead of ECHA restrictions captures European automotive and aerospace specification shifts. |
| UV-LED Curing Equipment Retrofit | Mercury lamp replacement services in Guangdong and Vietnam assembly plants align with Minamata Convention obligations. |
| Offshore Wind Splash-Zone Formulation | 25-year warranty coating systems for North Sea and Gulf of Mexico monopiles access infrastructure procurement pipelines. |
Research Methodology
Multi-period observation of VOC regulatory enforcement timelines, electrodeposition capacity expansions, and raw material price indices anchored the trend analysis, supplemented by interviews with automotive OEM coating procurement managers, aerospace specification engineers, marine shipyard superintendents, and industrial maintenance contractors. Secondary validation drew from EPA NESHAP filings, ECHA restriction proposals, China MEE emission standard updates, customs trade data for titanium dioxide and epoxy resin flows, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices linked formulation chemistry segments to end-use demand vectors across automotive electrification, offshore wind installation, and electronics manufacturing verticals. Segmentation dimensions modeled include coating technology type, cure energy requirement, substrate compatibility class, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and substitution rate assumptions for chrome-free and waterborne systems. Forecast inputs incorporated REACH implementation timelines and PLI scheme incentive disbursement patterns.
Regulatory enforcement delays, raw material supply disruptions, and electric vehicle platform cancellation decisions are the dominant revision risks to projection assumptions. Forecasts reflect documented assumption sets without claiming predictive certainty. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Anti-Friction Coatings Market
Coatings
Protective and Marine Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Coating Equipment Market
Coatings
Automotive Conformal Coatings Market
Coatings
Compound Coating Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Marking Coatings Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Conductive Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Water Based Enamel Market