
 Aerospace and Defense Chemical Distribution Market | 2026-2036
Aerospace and Defense Chemical Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Chemical Distribution Market Analysis
Consolidation among defense prime contractors is realigning procurement patterns for chemical distributors serving long-term platform programs. Boeing Distribution Services Inc. leverages its captive airframe OEM relationship to control specification-driven chemical flows. Univar Solutions Inc. sustains broad SKU coverage across North American defense industrial bases. Spectrum Aerospace GmbH anchors European distribution through Hamburg and Munich logistics nodes.
Aerospace and defense chemical distribution encompasses the sourcing, blending, certification, and logistics management of specialty chemicals including MIL-PRF-qualified solvents, structural adhesives with controlled cure profiles, chromate-free conversion coatings, and polysulfide sealants rated for jet fuel immersion. These materials require lot traceability, shelf-life monitoring, and compliance with aerospace material specifications prior to release to manufacturing or MRO operations. Solvents and sealants represent mature volume categories with stable margin pools, while chromate-free coatings and advanced structural adhesives capture faster expansion as airframers eliminate hexavalent chromium processes. The maintenance, repair, and overhaul application segment generates recurring demand with less program-cycle volatility than OEM manufacturing.
FAA airworthiness directives and EPA hazardous substance rules govern material qualification and handling protocols for U.S. distributors, while REACH and EU RoHS restrict substance composition across European supply chains. Defense contractors now require distributors to maintain AS9120 certification and DFARS-compliant country-of-origin documentation for specialty chemicals. Stakeholders must monitor evolving MIL-SPEC reform initiatives and alternative substance qualification timelines to anticipate specification shifts before existing product lines face obsolescence.
Market Dynamics
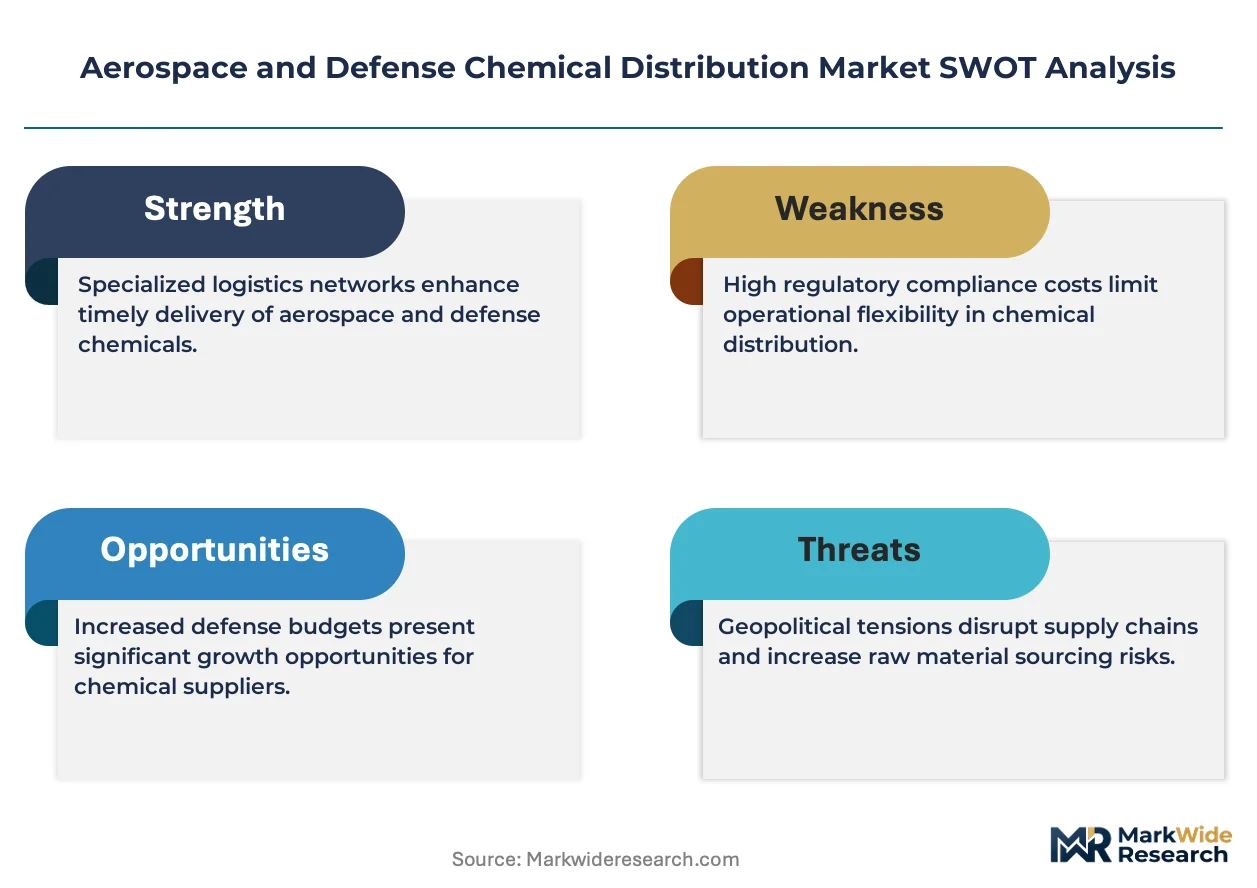
Defense prime contractor consolidation is compressing procurement channels, forcing chemical distributors to qualify for fewer but larger platform contracts with extended qualification timelines and stricter AS9120 documentation requirements.
Growth Catalysts
- Military aircraft modernization:NATO member states are expanding fleet upgrade programs, generating sustained demand for MIL-PRF-qualified solvents and structural adhesives with controlled cure profiles for composite bonding applications.
- REACH substance restrictions:ECHA's evolving authorization lists are accelerating substitution of hexavalent chromium processes, creating new qualification pathways for chromate-free conversion coating distributors.
- Polysulfide sealant specifications:Jet fuel immersion-rated sealants are capturing expanded share of MRO chemical spend as aging commercial and military fleets require more frequent resealing operations.
Market Restraints
- Raw material concentration:Specialty polymer feedstocks for structural adhesives concentrate among a limited set of German and Japanese chemical manufacturers, exposing distributors to supply interruption risk.
- Extended certification timelines:FAA airworthiness directives and EPA hazardous substance rules require 18-36 month qualification cycles for new chemical formulations, freezing product line refresh rates.
- DFARS compliance costs:Country-of-origin documentation requirements for defense-contracted chemicals add administrative overhead that disadvantages smaller regional distributors.
Strategic Opportunities
- India defense industrial base expansion:The country's PLI scheme for aerospace components is attracting foreign OEM joint ventures, creating first-mover openings for chemical distributors establishing local blending and certification capabilities.
- Digital lot traceability platforms:Blockchain-enabled shelf-life monitoring and automated specification matching are enabling distributors to capture premium positioning through compliance transparency.
- Sustainable aviation fuel infrastructure:New fuel system chemistries compatible with SAF blends represent an emerging specification category with limited incumbent qualification.
Industry Challenges
- Specialized formulation chemist scarcity:MIL-SPEC expertise and aerospace material specification interpretation skills concentrate among retiring workforce cohorts, constraining distributor technical service expansion.
- Legacy ERP integration:Defense contractor procurement systems require EDI-compliant documentation flows that force distributors to reconfigure inventory management platforms.
- Multi-jurisdiction certification maintenance:Simultaneous compliance with FAA, EASA, and national military airworthiness standards fragments quality management system resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Chemical Distribution Market |
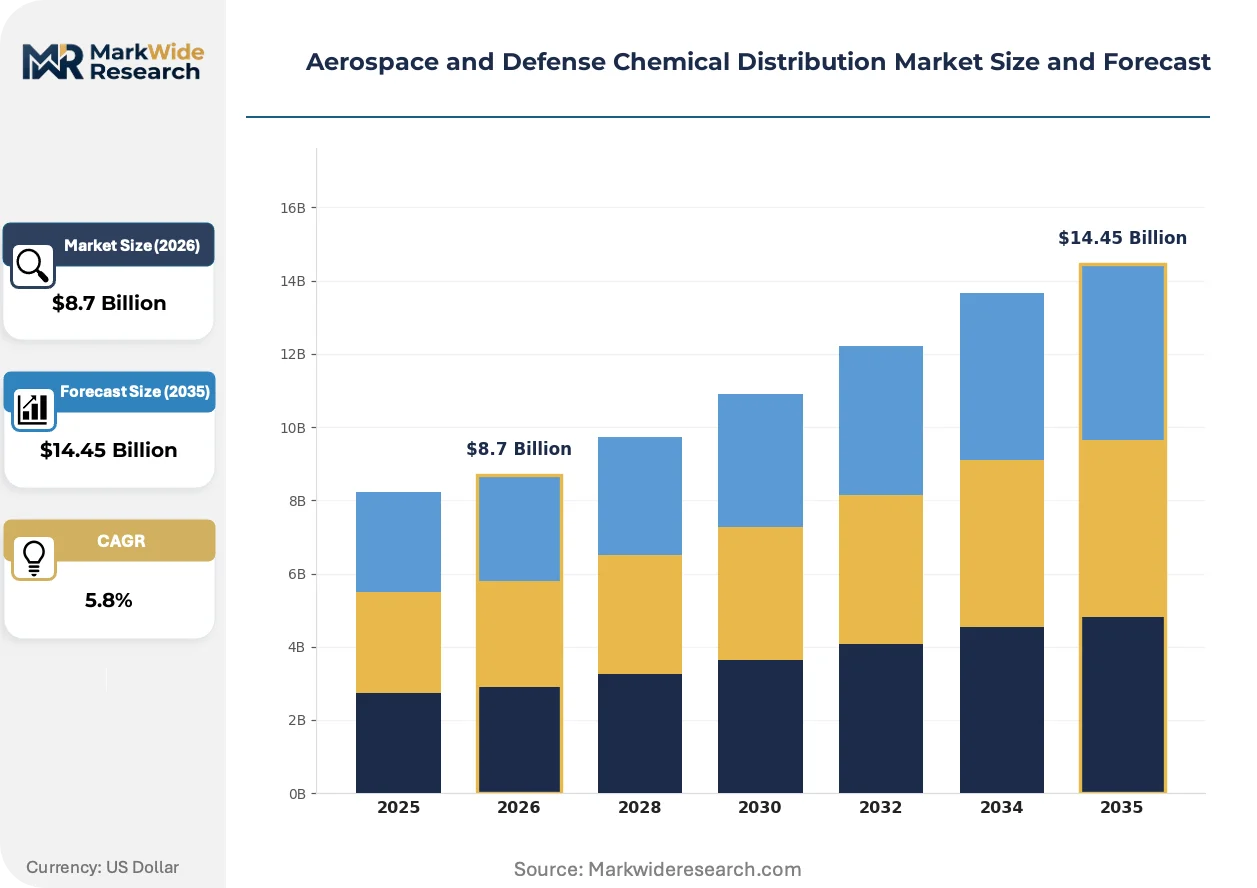
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Adhesives, Coatings, Sealants Application: Manufacturing, Maintenance, Repair, Overhaul End User: Aerospace OEMs, Defense Contractors, Component Suppliers, Service Providers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Aviall, Inc., Spectrum Aerospace GmbH, Univar Solutions Inc., AVIOCOM B.V., GracoRoberts, Boeing Distribution Services Inc., Jaco Aerospace, Aviation Chemical Solutions, Inc., Wesco Aircraft Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Chemical Distribution Market Emerging Trajectories
Specification-driven chemical distribution is converging with digital compliance infrastructure, compressing the traditional separation between material sourcing, certification documentation, and manufacturing floor delivery.
Single-platform chemical management systems are unifying procurement, inventory tracking, and specification compliance into integrated distributor offerings. Tier-1 defense contractors in Germany and the United States are piloting these systems for multi-site MRO operations. This consolidation is unifying previously separate purchasing, quality assurance, and logistics functions under distributor-managed dashboards.
EPA hazardous substance rules are tightening volatile organic compound thresholds for surface preparation solvents used in airframe manufacturing. The agency's 2024-2028 National Emission Standards for Hazardous Air Pollutants timeline is forcing reformulation of legacy degreasing chemistries. U.S.-based distributors serving Boeing and Lockheed Martin supply chains are accelerating qualification of low-VOC alternatives ahead of enforcement windows.
Defense contractors are consolidating chemical spend under fewer distributor relationships with integrated technical service capabilities. Long-tail SKU procurement through fragmented local suppliers is contracting in favor of national contracts with AS9120-certified distributors offering on-site inventory management. This concentration is most visible in the United Kingdom, where BAE Systems and Rolls-Royce Defense have reduced qualified chemical vendor pools by over half since 2020.
Aerospace and Defense Chemical Distribution Market Segmentation
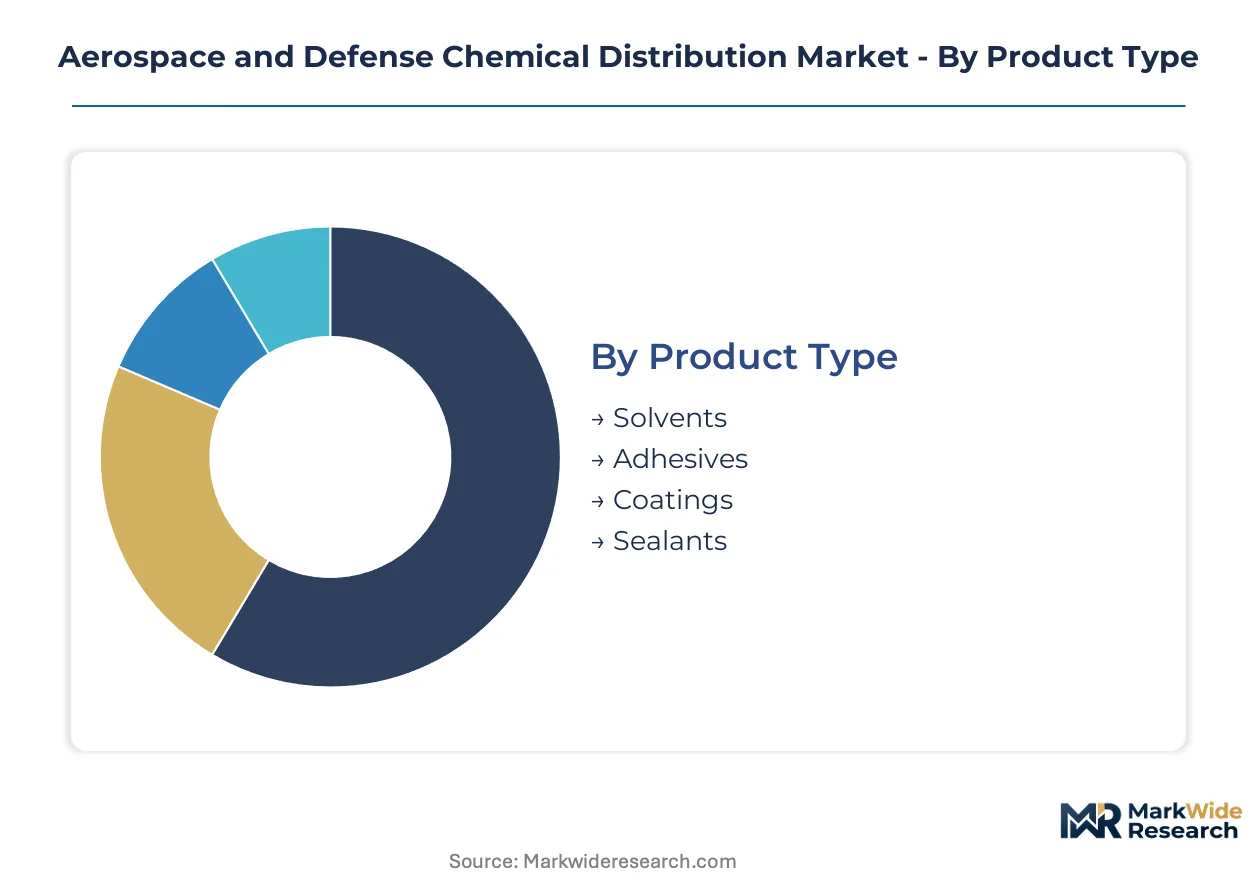
Segmentation in aerospace and defense chemical distribution reveals how capital intensity, certification requirements, and procurement concentration reshape competitive positioning across product lines and customer tiers. Distributors must align infrastructure investments with segment-specific qualification timelines and inventory turnover profiles.
Product Type:
Solvents and sealants demand the heaviest upfront investment in explosion-proof warehousing and VOC-compliant handling infrastructure, while adhesives and coatings require specialized blending equipment and extended shelf-life monitoring systems.
- Solvents:MIL-PRF-qualified formulations for surface preparation and degreasing require carbon adsorption recovery systems and EPA NESHAP-compliant storage. Demand concentrates at Boeing and Lockheed Martin manufacturing sites in the United States as EPA 2024-2028 emission standards force reformulation of legacy chemistries.
- Adhesives:Structural bonding systems with controlled cure profiles necessitate climate-controlled inventory and batch-specific viscosity testing. German distributors serving Airbus Defense and Space operations in Hamburg sustain above-average throughput for composite bonding applications in military transport programs.
- Coatings:Chromate-free conversion coatings for corrosion protection.
- Sealants:Polysulfide formulations rated for jet fuel immersion.
Solvents absorb the bulk of installed warehousing capacity; chromate-free coatings are expanding most quickly as REACH authorization lists accelerate hexavalent chromium substitution.
Application:
Volume concentration varies sharply between program-cycle-dependent manufacturing and recurring MRO demand, with qualification intensity highest for flight-critical manufacturing applications.
- Manufacturing:OEM airframe assembly consumes specification-driven chemical flows with lot traceability mandated by FAA airworthiness directives. Boeing and Airbus operations in the United States and Germany dominate procurement volumes for structural adhesives and surface preparation solvents.
- Maintenance:Line maintenance operations at commercial and military bases.
- Repair:Depot-level structural restoration requiring requalification of damaged components.
- Overhaul:Complete airframe refurbishment cycles generate recurring sealant and coating demand with less program volatility than OEM manufacturing, particularly at military MRO facilities in the United Kingdom and Italy.
Overhaul applications generate the most predictable revenue streams; manufacturing commands the highest margin premiums through specification lock-in.
End User:
Procurement sophistication escalates from component suppliers to prime contractors, with AS9120 certification and DFARS documentation requirements filtering distributor eligibility tier by tier.
- Aerospace OEMs:Boeing and Airbus operations impose the strictest qualification protocols.
- Defense Contractors:BAE Systems, Rolls-Royce Defense, and Raytheon consolidate chemical spend under fewer distributor relationships with integrated technical service capabilities, reducing qualified vendor pools by over half since 2020.
- Component Suppliers:Tier-2 and tier-3 manufacturers with fragmented procurement patterns.
- Service Providers:Independent MRO facilities with variable specification adherence.
Defense contractors concentrate the largest contract values; component suppliers offer the broadest addressable base for distributor expansion.
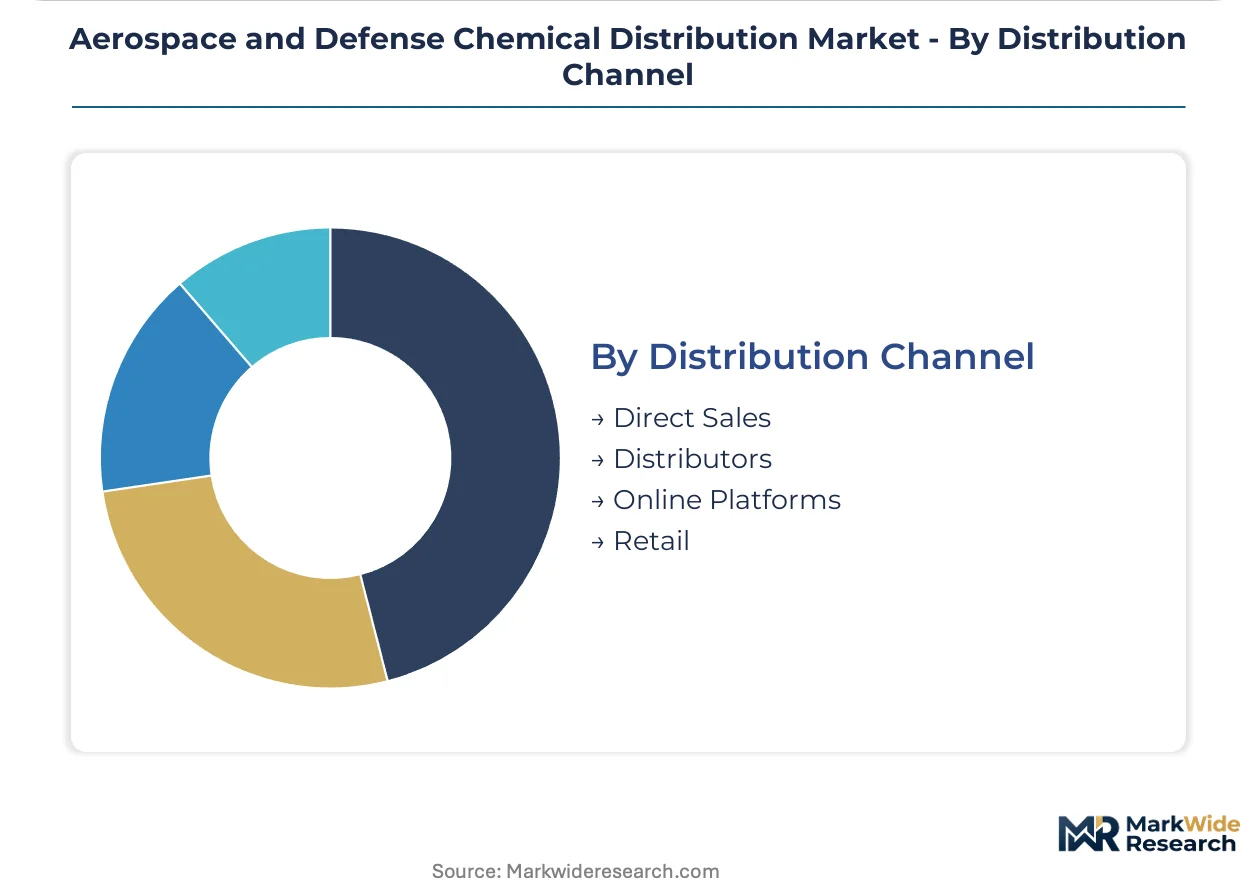
Distribution Channel:
Channel economics diverge between high-touch direct relationships with defense primes and scalable platform models for fragmented downstream demand.
- Direct Sales:Boeing Distribution Services leverages captive OEM relationships to control specification-driven chemical flows through dedicated technical account management and on-site inventory programs.
- Distributors:Univar Solutions and regional AS9120-certified intermediaries sustain broad SKU coverage across North American defense industrial bases with EDI-compliant documentation flows.
- Online Platforms:Digital procurement portals for standard-grade consumables.
- Retail:Limited to non-critical maintenance consumables with minimal certification requirements.
Distributor networks capture the majority of defense-contracted volume; online platforms are gaining traction fastest for standard-grade solvent replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty polymer feedstock production anchors aerospace chemical supply chains across NATO defense programs, with Hamburg and Munich logistics clusters processing chromate-free conversion coatings for Airbus Defense and Space operations.
United States
Boeing and Lockheed Martin manufacturing sites in Washington State and Texas drive concentrated demand for MIL-PRF-qualified solvents and structural adhesives. EPA 2024-2028 National Emission Standards for Hazardous Air Pollutants are forcing reformulation of legacy degreasing chemistries ahead of enforcement windows. Seattle-Tacoma industrial corridor distributors maintain carbon adsorption recovery systems for VOC-compliant handling infrastructure.
Germany
Airbus Defense and Space operations in Hamburg sustain above-average throughput for composite bonding applications in military transport programs. REACH authorization lists from ECHA are accelerating substitution of hexavalent chromium processes, creating new qualification pathways for chromate-free coating distributors. Munich logistics nodes serve as the primary European distribution anchor for polysulfide sealants rated for jet fuel immersion.
United Kingdom
BAE Systems and Rolls-Royce Defense operations have reduced qualified chemical vendor pools by over half since 2020, consolidating spend under fewer distributor relationships. UK military airworthiness standards from the Military Aviation Authority fragment quality management system resources alongside FAA and EASA requirements. Bristol and Derby manufacturing clusters generate recurring MRO chemical demand with less program-cycle volatility than OEM manufacturing.
India
The country's Production Linked Incentive scheme for aerospace components is attracting foreign OEM joint ventures, creating first-mover openings for chemical distributors establishing local blending capabilities. DGFT export-import documentation requirements add administrative overhead for defense-contracted chemicals. Bangalore and Hyderabad defense industrial corridors are emerging as qualification hubs for AS9120-certified distribution networks.
Japan
Specialty polymer feedstock manufacturers concentrate structural adhesive precursor supply, exposing distributors to interruption risk from limited German and Japanese chemical sources. METI industrial standards govern material qualification timelines for defense applications. Nagoya aerospace manufacturing cluster demands lot traceability and shelf-life monitoring for chromate-free conversion coatings in commercial-military hybrid programs.
Aerospace and Defense Chemical Distribution Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital lot traceability platforms and sustainable aviation fuel-compatible chemistries. The vendor base stratifies across captive OEM distribution arms, broad-coverage national distributors, and regional AS9120-certified specialists. Three archetypes dominate: specification-locked incumbents with airframe manufacturer relationships, inventory-heavy intermediaries with EDI-compliant documentation flows, and technical service integrators with on-site quality management. Consolidation and qualification capability expansion represent the dominant competitive vectors.
Among Germany-based specialists, Spectrum Aerospace GmbH exemplifies the regional AS9120-certified archetype anchoring European distribution through Hamburg and Munich logistics nodes. Univar Solutions Inc. represents the broad-coverage national distributor model sustaining SKU depth across North American defense industrial bases. Boeing Distribution Services Inc. occupies the captive OEM distribution position, leveraging specification control to manage chemical flows through dedicated technical account programs.
| Leading Market Players |
|---|
| Aviall, Inc. |
| Spectrum Aerospace GmbH |
| Univar Solutions Inc. |
| AVIOCOM B.V. |
| GracoRoberts |
| Boeing Distribution Services Inc. |
| Jaco Aerospace |
| Aviation Chemical Solutions, Inc. |
| Wesco Aircraft Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Chromate-free conversion coating qualification pathways are compressing cost economics for European distributors while simultaneously concentrating procurement authority under fewer AS9120-certified intermediaries with technical service capabilities. REACH authorization timelines from ECHA are forcing simultaneous reformulation investment across multiple supplier tiers, reshaping where margin capture accrues in the value chain.
Pricing Analysis
Technical service bundling separates premium distributor positioning from transactional commodity supply, with on-site inventory management and specification interpretation commanding 15-25% uplifts over standard SKU fulfillment. Price differentiation rests on certification depth—AS9120-qualified distributors with DFARS documentation capabilities capture manufacturing-tier premiums, while non-certified regional players compete on spot solvent pricing. Cost compression in standard-grade solvent categories is intensifying because EPA NESHAP compliance investments are amortizing across thinner volume bases. Component suppliers with fragmented procurement patterns exhibit highest price sensitivity; defense prime contractors with consolidated vendor pools prioritize specification adherence over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for expired shelf-life materials and requalification of returned sealant lots is concentrating investment among distributors serving multi-site MRO operations in the United States and Germany. Specialty polymer feedstock supply draws from German and Japanese chemical manufacturers, exposing distributors to interruption risk from limited precursor sources. Single-source vulnerability in structural adhesive precursors is amplifying qualification timelines for alternative formulations. Distribution runs through AS9120-certified intermediaries with EDI-compliant documentation flows, bypassing fragmented local suppliers unable to meet defense contractor procurement system requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with distributors pursuing backward control over blending capabilities to capture margin pools previously accruing to specialty chemical manufacturers.
For Market Incumbents: To counter consolidation-driven procurement compression among defense prime contractors, incumbents should deepen captive relationships with Boeing and Airbus through dedicated technical account programs while acquiring regional AS9120-certified specialists in India and Germany to preempt emerging competitor positioning. Certification investment in chromate-free coating formulation capabilities represents the critical defensive lever. For New Entrants and Emerging Players: Tier-2 component suppliers in India's Bangalore and Hyderabad defense industrial corridors offer the most penetrable entry point, with DGFT documentation complexity creating first-mover advantages for distributors establishing local blending and certification capabilities. A go-to-market angle emphasizing digital lot traceability platforms with blockchain-enabled shelf-life monitoring can differentiate against legacy ERP-dependent incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in technical service integrators with on-site quality management capabilities and established defense prime contractor relationships. The five-to-ten year viability window favors acquisition targets with AS9120 certification and proven EDI integration with Boeing or Lockheed Martin procurement systems. The signal to watch is MIL-SPEC reform initiative timelines that could obsolete existing product lines and trigger distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blending Capabilities | Captures margin pools from specialty chemical manufacturers while reducing feedstock concentration risk. |
| AS9120 Certification Investment | Qualifies distributors for defense prime contractor procurement consolidation and multi-year platform contracts. |
| Digital Lot Traceability Platform Deployment | Enables blockchain-enabled shelf-life monitoring that commands premium positioning through compliance transparency. |
| Geographic Expansion into India Defense Corridors | Establishes local blending capabilities ahead of PLI scheme-driven foreign OEM joint venture formation. |
| Chromate-Free Coating Formulation Qualification | Positions distributors for REACH-driven hexavalent chromium substitution across European NATO supply chains. |
Methodological Framework
Independent corroboration across primary interviews with defense procurement officers, chemical distribution technical directors, and aerospace material specification engineers, combined with secondary validation through FAA airworthiness directive filings, ECHA authorization list updates, and customs trade data, underwrites the qualitative findings. Bottom-up volume estimates from distributor SKU throughput analysis triangulate against top-down defense spending allocation models.
Comparable-period anchoring to historical military aircraft modernization cycles and REACH regulatory phase-in timelines structures the projection methodology across the analysis window. Segmentation dimensions include product type, application tier, end-user sophistication, and distribution channel format, with CAGRs derived from weighted average of program-cycle demand and recurring MRO replacement rates. Forecast inputs incorporate EPA NESHAP enforcement windows and ECHA substance restriction timelines.
Several conditions sit outside the modeled scope, including unannounced MIL-SPEC reform initiatives, sudden REACH substance ban accelerations, and geopolitical disruption to German-Japanese polymer feedstock flows. Forecasts reflect documented assumptions about qualification timeline stability and defense budget continuity. Practitioners should monitor FAA airworthiness directive issuance rates and ECHA authorization list expansion velocity for early signals of specification obsolescence risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market