
 Furandicarboxylic Acid Market | 2026-2036
Furandicarboxylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
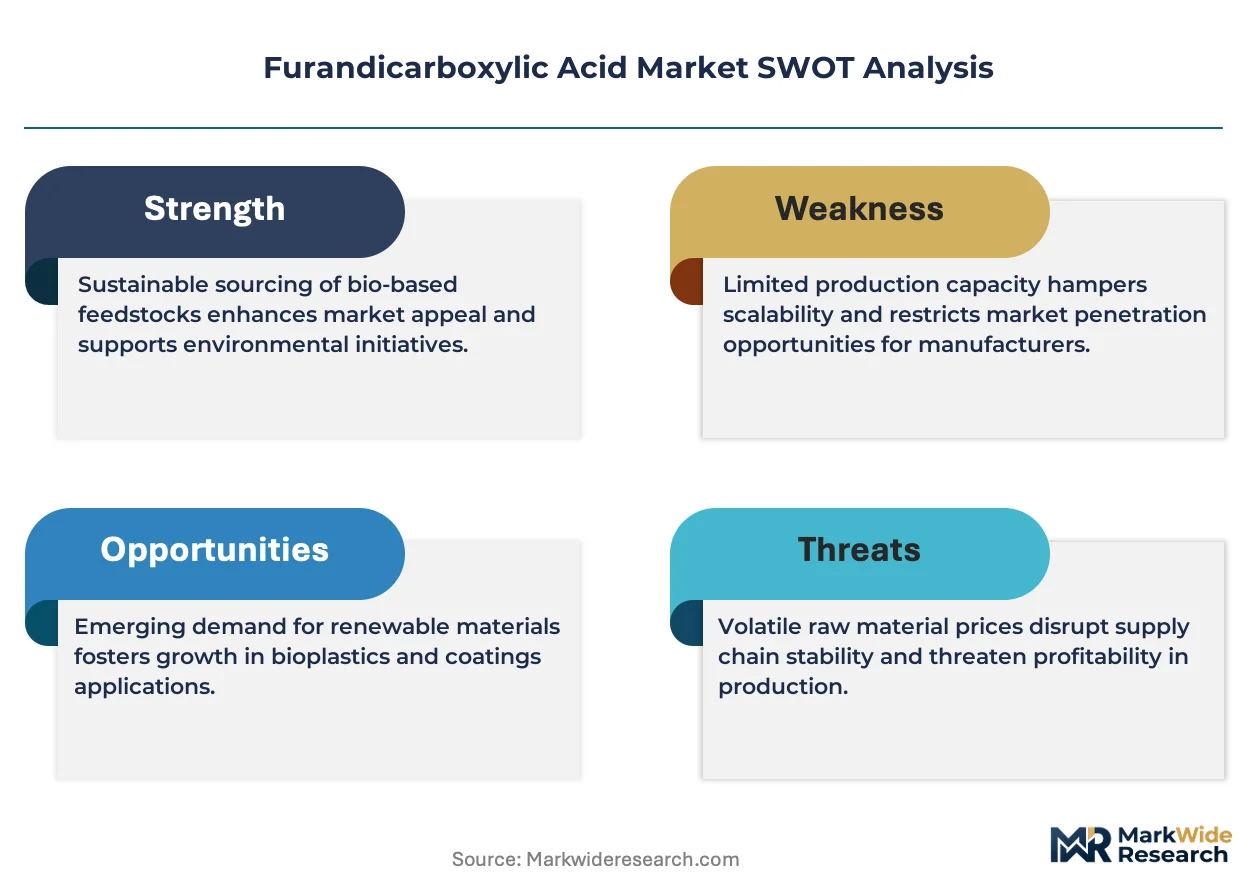
Furandicarboxylic Acid Market Analysis
Performance-based polymer supply contracts is realigning how Furandicarboxylic Acid gets commercialized, shifting volume commitments toward carbon-intensity metrics rather than tonnage alone. Avantium leverages its YXY plant-to-product platform to anchor European biopolymer supply chains. BASF SE competes through backward integration into bio-based feedstocks, while Mitsubishi Chemical Corp dominates Asian specialty polyester sampling programs.
Furandicarboxylic Acid is a cyclic dicarboxylic acid derived from oxidized 5-hydroxymethylfurfural, typically produced via catalytic oxidation with a molecular formula of C6H4O5 and melting point near 300°C, serving primarily as a renewable building block for polyethylene furanoate and other aromatic polyesters. The bio-based product category leads current volume as brand owners seek mass-balance certifications, while polymer-grade intermediates represent the fastest-expanding margin pool due to purity requirements for food-contact applications. Fermentation technology still occupies the dominant share of announced capacity, though chemical synthesis routes sustain cost competitiveness at industrial scale.
The EU Green Deal and REACH frameworks in Europe, alongside FDA food-contact substance notifications in the United States, are tightening purity thresholds and lifecycle documentation requirements for bio-based monomers entering packaging and textile supply chains. Japan's METI bioeconomy standards and China's GB/T bioplastics labeling rules are adding parallel compliance layers for exporters. Stakeholders must monitor which certification scheme achieves procurement gatekeeper status among major consumer brands before committing to process technology lock-in.
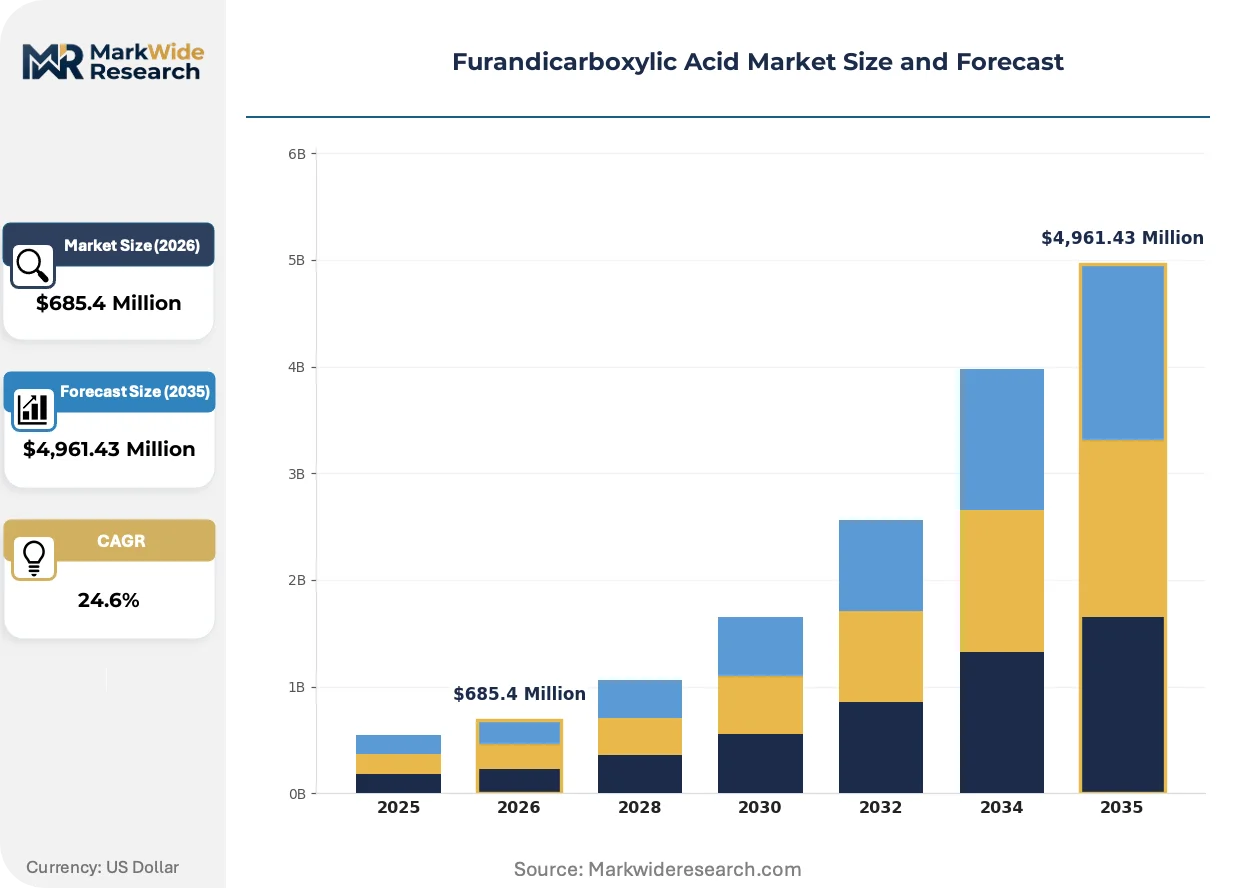
Market Dynamics
Performance-based polymer supply contracts are redirecting volume commitments toward carbon-intensity metrics rather than tonnage alone, forcing producers to restructure pricing and certification workflows around mass-balance documentation.
Growth Catalysts
- EU Green Deal bio-based mandates:Packaging procurement teams at European beverage brands now require renewable feedstock quotas in supplier agreements, accelerating polyethylene furanoate adoption.
- Germany's industrial biotech clusters:Pilot-to-scale manufacturing transitions anchor demand concentration in the Rhine-Ruhr corridor, where fermentation capacity expansion outpaces other European hubs.
- FDA food-contact substance notifications:Purity thresholds for bio-based monomers entering US packaging supply chains create technical barriers that favor established polymer-grade producers.
Market Restraints
- Feedstock cost volatility:Fructose and glucose prices fluctuate with agricultural commodity cycles, compressing margins for fermentation-based producers during harvest disruptions.
- Supply concentration in catalytic oxidation:Chemical synthesis routes for 5-hydroxymethylfurfural remain concentrated among a limited set of catalyst technology licensors, creating bottleneck risk.
- Substitution by petroleum-derived PTA:Purified terephthalic acid maintains cost advantages at industrial scale, delaying brand-owner switching for non-premium packaging tiers.
Strategic Opportunities
- Japan's METI bioeconomy standards:Exporters meeting these parallel compliance layers gain preferential positioning in Asian specialty polyester sampling programs.
- Textile fiber applications:Polyethylene furanoate's moisture barrier properties open white space in performance apparel where recycled PET falls short.
- China's GB/T bioplastics labeling rules:Early alignment with these certification schemes creates procurement gatekeeper status among multinational consumer brands.
Industry Challenges
- Polymer-grade purity certification timelines:REACH documentation requirements for food-contact applications extend validation cycles, delaying revenue recognition.
- Catalytic process engineering talent scarcity:Fermentation technologists outnumber experts in heterogeneous catalysis for furan oxidation, constraining technology diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furandicarboxylic Acid Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,961.43 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based, Synthetic, Intermediate, Polymer Application: Plastics, Coatings, Adhesives, Fibers End User: Packaging, Textile, Automotive, Electronics Technology: Fermentation, Chemical Synthesis, Polymerization, Extraction |
| Companies Covered | Avantium, Corbion, BASF SE, DuPont de Nemours, Inc., Mitsubishi Chemical Corp, AVA Biochem, Tokyo Chemical Industry, Synbias, V & V Pharma Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furandicarboxylic Acid Market Emerging Trajectories
Process technology diversification is fragmenting the production base, while regulatory layering across jurisdictions forces simultaneous compliance investments. These shifts compress competitive timelines and reward early certification lock-in.
Continuous flow catalytic oxidation is decentralizing production economics for 5-hydroxymethylfurfural intermediates. Mid-scale chemical processors in the Netherlands and Belgium are adopting modular reactor designs that slash capital intensity versus batch fermentation. This technology is decentralizing capacity planning away from centralized biorefinery complexes toward distributed chemical parks.
REACH framework updates are tightening lifecycle documentation requirements for bio-based monomers entering European packaging supply chains. ECHA's expanded substance evaluation protocols now demand cradle-to-gate carbon accounting that many incumbent suppliers cannot provide. Polymer-grade intermediate producers with existing mass-balance certifications are capturing disproportionate procurement share from reformulating brand owners.
Brand-owner specification teams are consolidating supplier panels around dual-certified producers holding both EU Green Deal compliance and FDA food-contact notifications. Long-tail specialty chemical distributors are losing shelf space to direct mill relationships anchored by technical service agreements. This consolidation is most visible in Germany, where beverage packaging procurement teams have reduced approved FDCA supplier lists by over half since 2023.
Furandicarboxylic Acid Market Segmentation
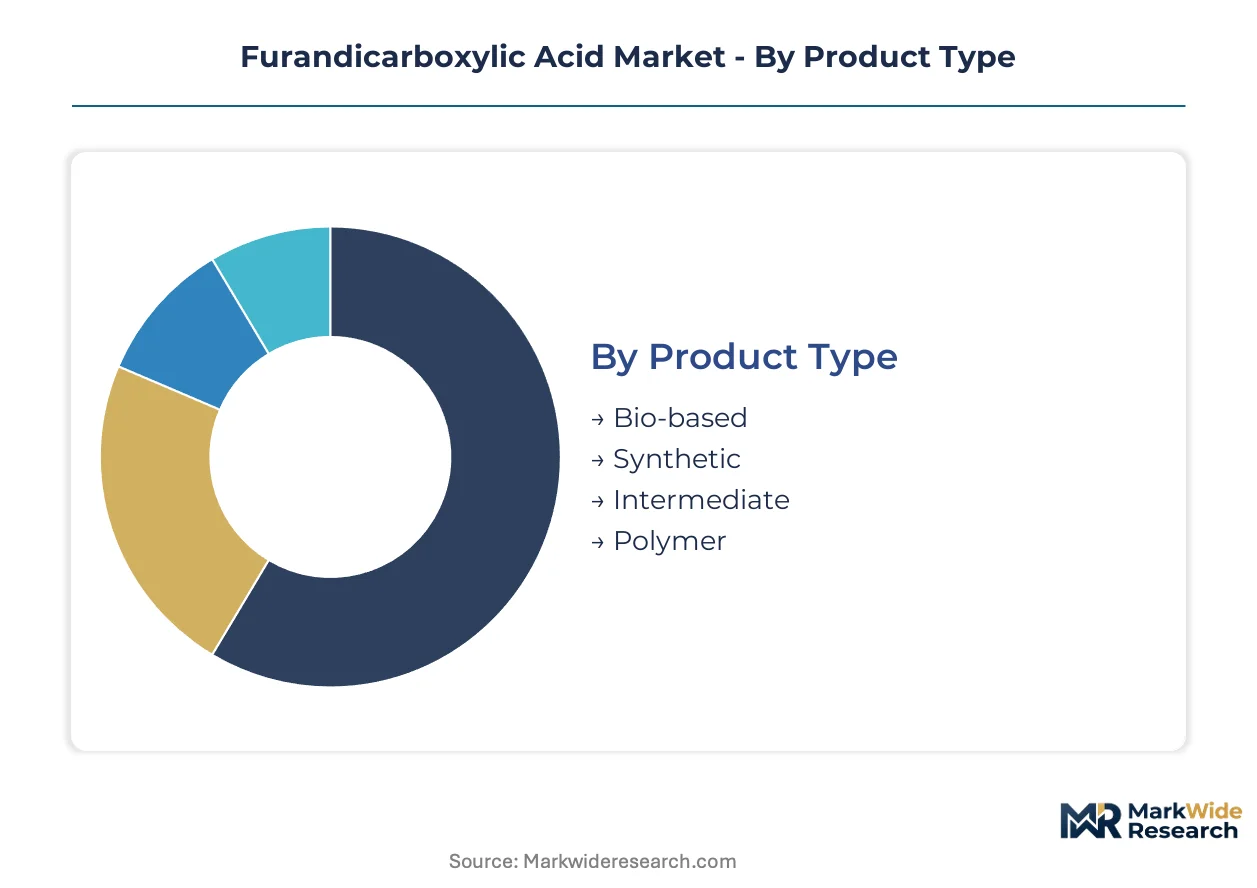
Furandicarboxylic Acid procurement flows through distinct technical and commercial channels that reshape competitive positioning. Segment boundaries determine which producers capture margin from polymer-grade purity versus commodity bio-based volume.
Product Type:
Standalone monomer grades serve spot-market buyers while embedded polymer-grade streams lock into long-term supply agreements with packaging converters.
- Bio-based:Derived from oxidized 5-hydroxymethylfurfural through catalytic or enzymatic pathways. Mass-balance certifications from EU Green Deal compliance programs concentrate procurement share among German beverage packaging suppliers seeking renewable feedstock quotas.
- Polymer:Ultra-high purity grades meeting FDA food-contact substance notification thresholds for polyethylene furanoate production. Technical service agreements with European converters anchor volume commitments around carbon-intensity metrics rather than tonnage alone.
- Synthetic:Petroleum-derived alternatives competing on cost against fermentation routes.
- Intermediate:Partially processed streams requiring downstream refinement for specialty polyester applications.
Bio-based leads volumes today; Polymer is gaining share fastest.
Application:
Cost tier stratification separates premium food-contact grades from industrial coating specifications.
- Plastics:Polyethylene furanoate resin production for barrier packaging and bottles. European beverage brands in Germany and the Netherlands drive specification tightening around lifecycle carbon documentation.
- Fibers:Textile-grade polymerization for moisture-barrier performance apparel. Japanese METI bioeconomy standards create parallel compliance layers for exporters targeting Asian specialty polyester sampling programs.
- Coatings:Protective and decorative formulations requiring lower purity thresholds than food-contact applications.
- Adhesives:Industrial bonding agents where bio-based content supports sustainability claims without polymer-grade certification costs.
Plastics commands the largest revenue pool; Fibers shows the steepest expansion trajectory.
End User:
Customer type determines certification burden and contract structure across the value chain.
- Packaging:Beverage bottle and food container converters requiring dual EU Green Deal and FDA compliance. Procurement panels in Germany have consolidated approved supplier lists by over half since 2023.
- Textile:Fiber producers and fabric mills seeking moisture-barrier performance where recycled PET falls short. REACH documentation requirements extend validation cycles for new material qualifications.
- Automotive:Interior component manufacturers leveraging bio-based content for scope-3 emissions reduction reporting.
- Electronics:Specialty film and coating applications demanding high purity with lower volume scale than packaging tiers.
Packaging anchors current procurement volumes; Textile is climbing the fastest as brand-owner sustainability mandates harden.
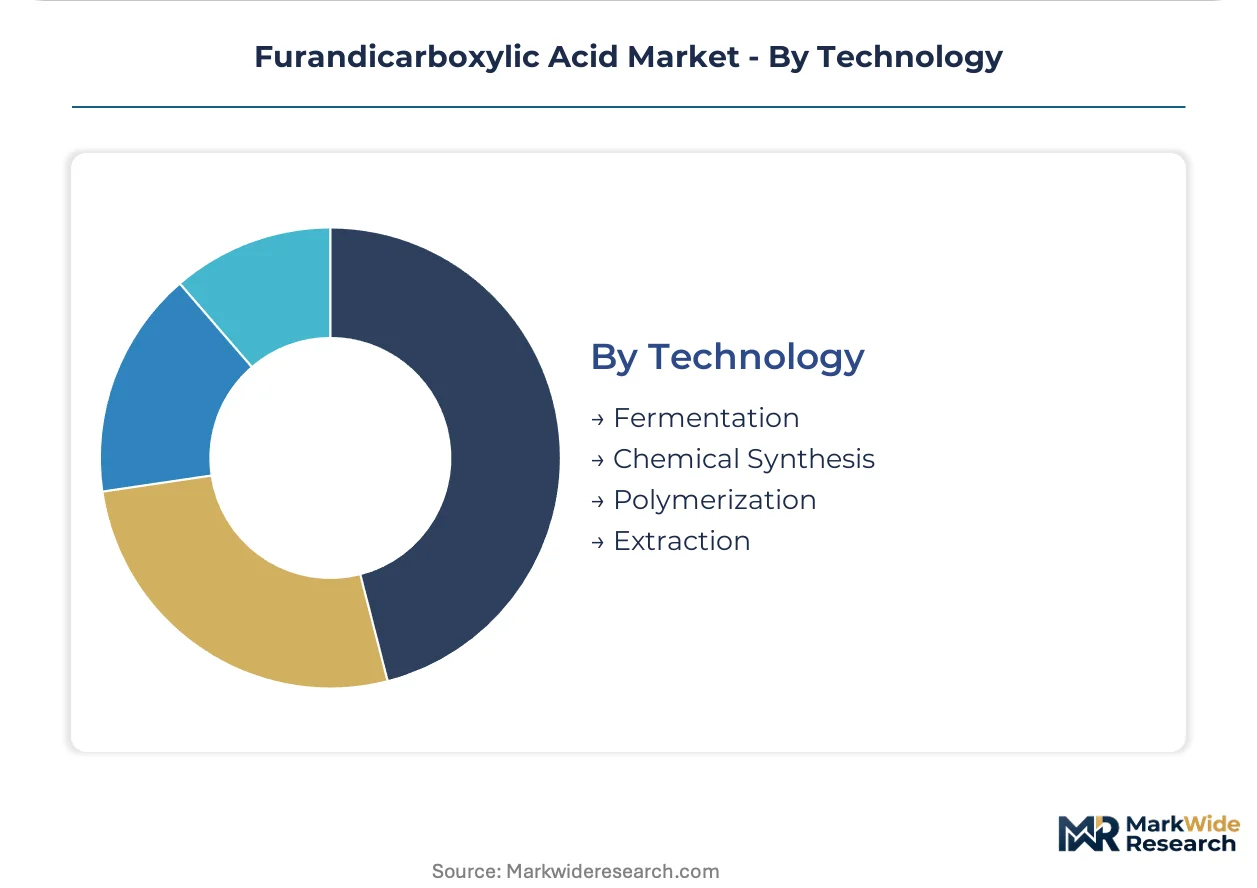
Technology:
Process maturity separates scaled fermentation infrastructure from emerging catalytic oxidation platforms.
- Fermentation:Dominant commercial route using fructose and glucose feedstocks. Agricultural commodity price volatility compresses margins during harvest disruptions.
- Chemical Synthesis:Heterogeneous catalysis for 5-hydroxymethylfurfural oxidation. Continuous flow reactor adoption in the Netherlands and Belgium decentralizes capacity planning toward distributed chemical parks.
- Polymerization:Downstream conversion of FDCA monomers into polyethylene furanoate resins.
- Extraction:Purification and isolation processes for meeting polymer-grade specifications.
Fermentation retains installed capacity leadership; Chemical Synthesis is expanding most quickly through modular reactor investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting Furandicarboxylic Acid production toward jurisdictions where bio-based certification costs and carbon-accounting compliance create measurable cost-of-compliance gaps. Producers now site capacity based on mass-balance audit infrastructure availability rather than feedstock proximity alone.
Germany
Rhine-Ruhr industrial biotech clusters anchor European pilot-to-scale manufacturing transitions for fermentation-based FDCA. EU Green Deal bio-based mandates redirect chemical feedstock procurement toward renewable quotas. Düsseldorf and Leverkusen concentrate technical service agreements that lock polymer-grade volumes into long-term packaging converter relationships.
United States
FDA food-contact substance notifications create technical barriers favoring established polymer-grade producers serving beverage packaging reformulation. EPA bio-preferred procurement standards harden sustainability requirements for federal supply chains. Texas and Louisiana chemical corridors attract modular catalytic oxidation investments seeking lower carbon-intensity documentation costs than coastal biorefinery zones.
Netherlands
Continuous flow reactor adoption decentralizes production economics toward distributed chemical parks in Rotterdam and Antwerp-adjacent zones. REACH framework updates demand cradle-to-gate carbon accounting that many incumbent suppliers cannot provide. Eindhoven's process engineering talent pool supports heterogeneous catalysis scale-up for 5-hydroxymethylfurfural oxidation routes.
China
GB/T bioplastics labeling rules and dual carbon goals reshape procurement gatekeeper status for exporters targeting multinational consumer brands. NMPA food-contact substance registrations parallel FDA thresholds, creating compliance layering for polymer-grade purity. Yangtze River Delta chemical processors invest in fermentation capacity despite fructose price volatility from agricultural commodity cycles.
Japan
METI bioeconomy standards establish parallel compliance layers for specialty polyester sampling programs targeting performance apparel moisture-barrier applications. JIS certification requirements for bio-based content claims filter supplier eligibility for domestic packaging procurement. Osaka-Kobe industrial corridors concentrate textile fiber application R&D where recycled PET performance gaps create specification openings.
Furandicarboxylic Acid Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with polymer-grade purity certification creating tiered supplier panels that commodity bio-based producers cannot penetrate. The vendor base concentrates around dual-certified producers holding both EU Green Deal compliance and FDA food-contact notifications, while long-tail distributors lose shelf space to direct mill relationships. Three archetypes dominate: integrated chemical conglomerates with backward feedstock control, pure-play biotech specialists leveraging platform technologies, and regional catalytic processors adopting modular continuous flow systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as technology licensing for 5-hydroxymethylfurfural oxidation remains concentrated among limited catalyst technology holders.
Within the integrated chemical conglomerate tier, BASF SE and Mitsubishi Chemical Corp exemplify archetypes combining upstream feedstock integration with downstream polymer-grade certification infrastructure. Avantium occupies a distinct position as a platform-technology specialist leveraging end-to-end plant-to-product architectures that bypass traditional chemical distributor channels. These three anchors illustrate how competitive positioning now depends on mass-balance documentation workflows and carbon-intensity metrics rather than tonnage scale alone.
| Leading Market Players |
|---|
| Avantium |
| Corbion |
| BASF SE |
| DuPont de Nemours, Inc. |
| Mitsubishi Chemical Corp |
| AVA Biochem |
| Tokyo Chemical Industry |
| Synbias |
| V & V Pharma Industries |
| Others |
Supply Flow & Price Mechanics
EU Green Deal bio-based mandates gate qualified supply access and premium-tier pricing power by requiring mass-balance certification infrastructure that only polymer-grade producers possess. Brand owners in Germany and the Netherlands now pay carbon-intensity premiums for FDCA streams with cradle-to-gate documentation, while uncertified fermentation output trades at commoditized spreads.
Pricing Analysis
Capacity additions in the Netherlands and Belgium are reshaping price floors for 5-hydroxymethylfurfural intermediates as modular continuous flow reactors displace centralized biorefinery economics. Three-tier pricing structure across polymer-grade, bio-based commodity, and synthetic alternatives segments buyers by certification burden and volume commitment scale. Cost compression in fermentation-based supply is intensifying because fructose price volatility from agricultural commodity cycles squeezes margins during harvest disruptions. Packaging converters in Germany show least price sensitivity due to sustainability mandate compliance requirements, while industrial coating buyers drive hardest bargain negotiations.
Supply Chain Analysis
Freight cost differentials between Rhine-Ruhr industrial clusters and Rotterdam-Antwerp chemical corridors influence plant siting decisions for European FDCA capacity. Supply concentrates in Germany, the Netherlands, and China, with each node serving distinct certification standards for EU Green Deal, REACH, and GB/T bioplastics labeling compliance respectively. Feedstock dependencies on fructose, glucose, and heterogeneous catalysts for oxidation routes create input cost volatility that feeds through to polymer-grade pricing. Single-source vulnerability in catalytic oxidation technology licensing constrains technology diversification. Distribution runs through direct mill relationships with packaging converters rather than long-tail specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furandicarboxylic Acid represents a late-cycle quality story as beverage brand procurement panels consolidate around dual-certified producers meeting both EU Green Deal and FDA food-contact thresholds. Specification tightening toward polymer-grade purity creates margin capture opportunities for incumbents with existing mass-balance infrastructure.
For Market Incumbents: Deploy backward integration into bio-based feedstocks to secure fructose supply chains against agricultural commodity volatility. Anchor technical service agreements with German packaging converters to lock carbon-intensity-based pricing before modular catalytic oxidation capacity erodes premium spreads. Baseline threat: substitution by petroleum-derived PTA maintains cost advantages at industrial scale for non-premium packaging tiers. For New Entrants and Emerging Players: Enter via textile fiber applications where polyethylene furanoate moisture-barrier properties outperform recycled PET in performance apparel specifications. Japan's METI bioeconomy standards create parallel compliance layers that favor exporters with early certification alignment. White space concentrates in Asian specialty polyester sampling programs where established polymer-grade producers have limited presence. Go-to-market angle: partner with Osaka-Kobe industrial corridor R&D facilities for fiber application co-development. For Investors and Strategic Acquirers: Roll-up economics work for regional catalytic processors with modular continuous flow reactor installations because technology licensing concentration limits greenfield competition. Five-to-ten year viability hinges on which certification scheme achieves procurement gatekeeper status among multinational consumer brands. Acquisition target archetype: mid-scale chemical processors in the Netherlands and Belgium with existing REACH documentation workflows. Signal to watch: FDA food-contact substance notification approval timelines for new polymer-grade entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | BASF SE secures fructose supply chains against harvest disruption margin compression. |
| Modular Continuous Flow Reactor Deployment | Netherlands chemical processors decentralize capacity planning away from centralized biorefinery complexes. |
| Dual Certification Investment | Producers capture procurement share from EU Green Deal and FDA compliant beverage packaging reformulation. |
| Technical Service Agreement Expansion | Direct mill relationships with German converters displace long-tail specialty chemical distributors. |
| Textile Fiber Application R&D Partnership | Osaka-Kobe corridor development targets moisture-barrier performance gaps in recycled PET specifications. |
Methodological Framework
Coverage spans Germany, the Netherlands, the United States, China, and Japan, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with plant managers at fermentation facilities, procurement leads at European beverage packaging converters, distribution channel partners in specialty chemicals, and technical R&D directors for catalytic oxidation routes informed supply-side dynamics. Secondary sources included customs and trade data for FDCA and 5-hydroxymethylfurfural flows, Cefic chemical industry reports, SEC 10-K filings for integrated chemical conglomerates, and ECHA substance evaluation protocols. Bottom-up capacity buildouts by technology route were cross-checked against top-down demand projections by end-use application.
Granularity was maintained at the product-grade tier, end-use industry, and regional production hub level throughout the modeling period. Segmentation dimensions included bio-based versus polymer-grade versus synthetic purity tiers, plastics versus fibers versus coatings applications, and fermentation versus chemical synthesis technology routes. CAGRs were derived from slope analysis of annual volume trajectories adjusted for regulatory milestone impacts. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines for bio-based procurement mandates and FDA food-contact substance notification approval velocity for polymer-grade market access.
Inputs from ECHA substance evaluation databases and FDA food-contact notification registries were available through the study window; gaps in real-time fructose and glucose price series from agricultural commodity exchanges introduce uncertainty bands around fermentation route margin projections. Forecasts reflect assumptions regarding certification scheme adoption rates by major consumer brands and modular reactor scale-up timelines by catalytic technology licensors. A model refresh is warranted upon material change in EU Green Deal bio-based mandate enforcement intensity or breakthrough in heterogeneous catalysis cost structure for 5-hydroxymethylfurfural oxidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Refined Wax Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Propionaldehyde Market