
 Calcined Petcoke Market | 2026-2036
Calcined Petcoke Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Petcoke Market Analysis
Anthracite coal is recalibrating calcined petcoke economics in select anode applications where carbon purity requirements allow material flexibility. Oxbow Corporation leverages its integrated petroleum coke supply chain to sustain cost advantages across Atlantic basin deliveries. Rain Carbon Inc. anchors its competitive position through specialized calcination technology leadership in high-carbon product grades. Indian Oil Corporation Ltd. dominates domestic supply security for Indian aluminum smelters through refinery-captive production.
Calcined petcoke is a high-temperature processed derivative of green petroleum coke with carbon content typically exceeding 98 percent and sulfur levels ranging from 1 to 6 percent depending on feedstock source, produced in rotary or shaft kilns at temperatures above 1,200 degrees Celsius to drive off volatile matter and enhance electrical conductivity for industrial applications. Its primary commercial purpose centers on serving as the carbon anode material in Hall-Héroult aluminum electrolysis cells, where consistent density and low reactivity directly influence smelting efficiency and metal purity. Needle coke commands premium positioning within the product type architecture due to its essential role in ultra-high-power graphite electrodes for electric arc steelmaking. Aluminum production absorbs the dominant volume share across application segments, while specialty coke grades carry concentrated margin pools tied to aerospace and advanced carbon product specifications.
The US EPA enforces sulfur-content thresholds under the Clean Air Act that constrain high-sulfur petcoke combustion applications and redirect material flows toward non-combustion industrial uses. China's MEE implements dual carbon goals that tighten refinery emission standards and accelerate low-sulfur calcined petcoke qualification requirements for domestic smelters. India's CEA and MoEFCC coordinate power-sector emission norms that increasingly restrict raw petcoke burning while preserving industrial calcination pathways. Stakeholders must monitor regulatory divergence between combustion bans and industrial-process exemptions as this policy tension determines accessible volume pools and regional price formation mechanics.
Market Dynamics
China's dual carbon goals are compressing high-sulfur calcined petcoke volumes while redirecting procurement toward low-carbon anode feedstocks, restructuring Atlantic-to-Pacific supply corridors and calciner investment patterns.
Growth Catalysts
- Aluminum capacity expansion:Indian aluminum smelters are commissioning new electrolysis lines that require smelter-grade anode material, creating dedicated demand corridors from domestic calciners.
- EU Carbon Border Adjustment Mechanism:European importers are qualifying low-sulfur calcined petcoke sources to avoid carbon-intensity penalties on aluminum embedded emissions.
- Needle coke substitution:Ultra-high-power graphite electrode manufacturers are diversifying feedstock portfolios toward premium sponge coke grades as needle coke supply tightens.
Market Restraints
- Green petroleum coke supply concentration:US Gulf Coast refineries dominate exportable high-sulfur green coke supply, creating single-point vulnerability for Atlantic basin calciners.
- Anthracite coal competition:Chinese anode producers are blending anthracite into carbon mixes where sulfur tolerance permits, compressing calcined petcoke volume share in select applications.
- Shaft kiln technical ceiling:Conventional shaft calcination cannot achieve the density uniformity required by aerospace carbon specifications, limiting addressable premium segments.
Strategic Opportunities
- India refinery-captive calcination:Indian Oil Corporation and Reliance Industries are integrating rotary kiln capacity at coastal refineries to serve domestic aluminum growth.
- Electric vehicle battery anodes:Synthetic graphite producers are qualifying calcined petcoke precursors for lithium-ion battery anode material, opening non-aluminum volume pools.
- EU Green Deal industrial decarbonization:European smelters are sourcing certified low-carbon calcined petcoke to meet Scope 3 emission reduction commitments.
Industry Challenges
- Rotary kiln refractory engineering:Extended campaigns above 1,300 degrees Celsius accelerate brick degradation, requiring specialized maintenance protocols and operational downtime.
- Multi-jurisdiction sulfur certification:Calciner operators must maintain parallel testing regimens for China's MEE standards, India's CEA norms, and EU REACH documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Petcoke Market |
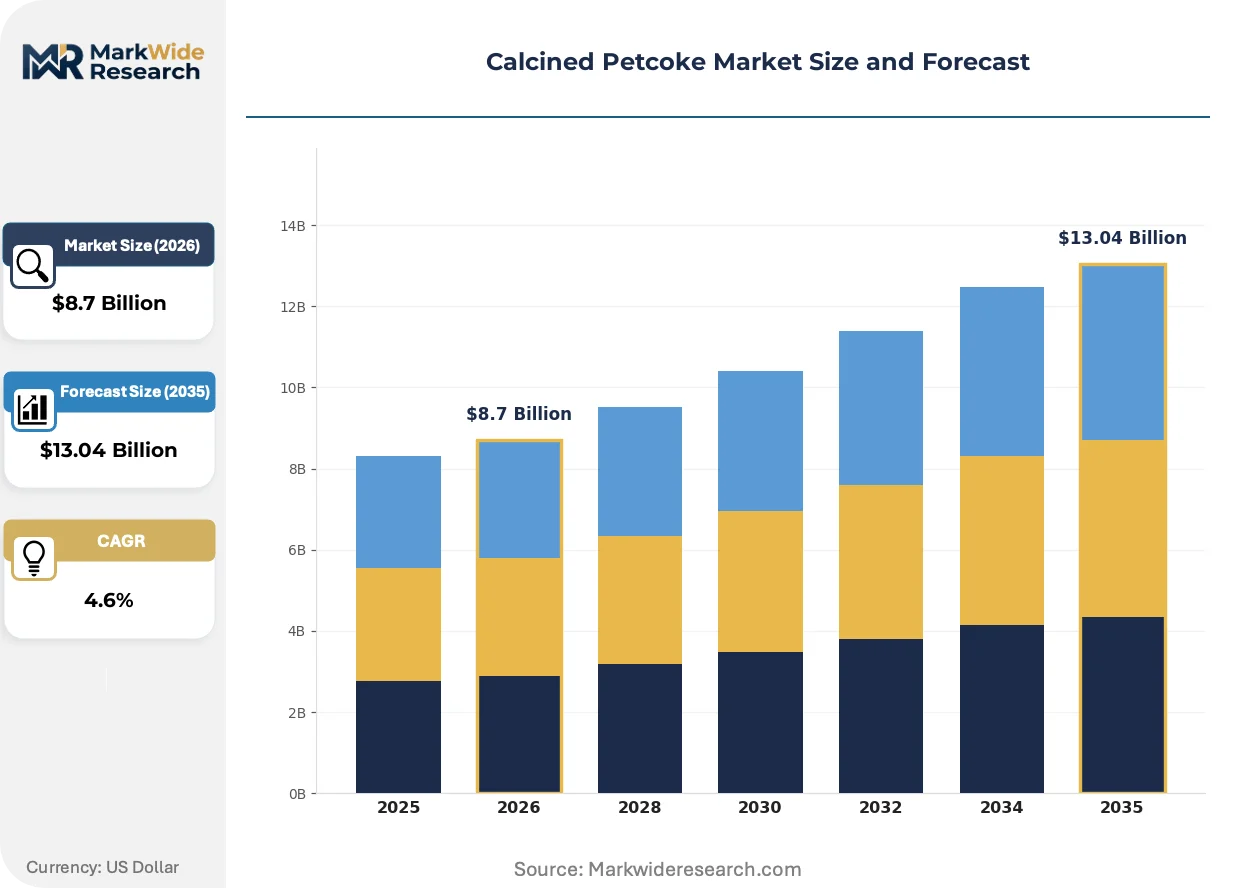
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Carbon, Low-Sulfur, Needle Coke, Specialty Coke Application: Aluminum Production, Steel Manufacturing, Titanium Dioxide Production, Carbon Products End User: Metals Industry, Energetics Sector, Manufacturing Companies, Aerospace Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Traders |
| Companies Covered | Oxbow Corporation, Valero Energy Corporation, Rain Carbon Inc., Indian Oil Corporation Ltd., Exxon Mobil Corporation, BP plc, Saudi Aramco, Reliance Industries Ltd., Phillips 66 Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Petcoke Market Emerging Trajectories
Calcination technology and feedstock qualification protocols are converging to meet dual pressures from aluminum decarbonization targets and battery material purity requirements.
Flash calcination systems are electrifying traditional thermal processing by replacing fuel-fired rotary kilns with plasma-assisted or resistance-heating configurations. European specialty carbon producers are piloting these installations to eliminate Scope 1 combustion emissions. This electrification is compressing the carbon intensity gap between calcined petcoke and synthetic graphite alternatives.
China's MEE is tightening refinery emission standards under dual carbon implementation timelines, accelerating low-sulfur green coke qualification requirements. Domestic smelters are rejecting historical high-sulfur supply relationships. This regulatory compression is redirecting procurement toward Middle Eastern and North American low-sulfur sources.
Long-term offtake contracting is displacing spot market purchasing among major aluminum producers. Smelters are locking five-to-seven-year supply agreements with calciners who can demonstrate feedstock traceability and carbon intensity certification. This contractual shift is most visible in European and North American procurement desks where Scope 3 accounting requirements demand supply chain transparency.
Calcined Petcoke Market Segmentation
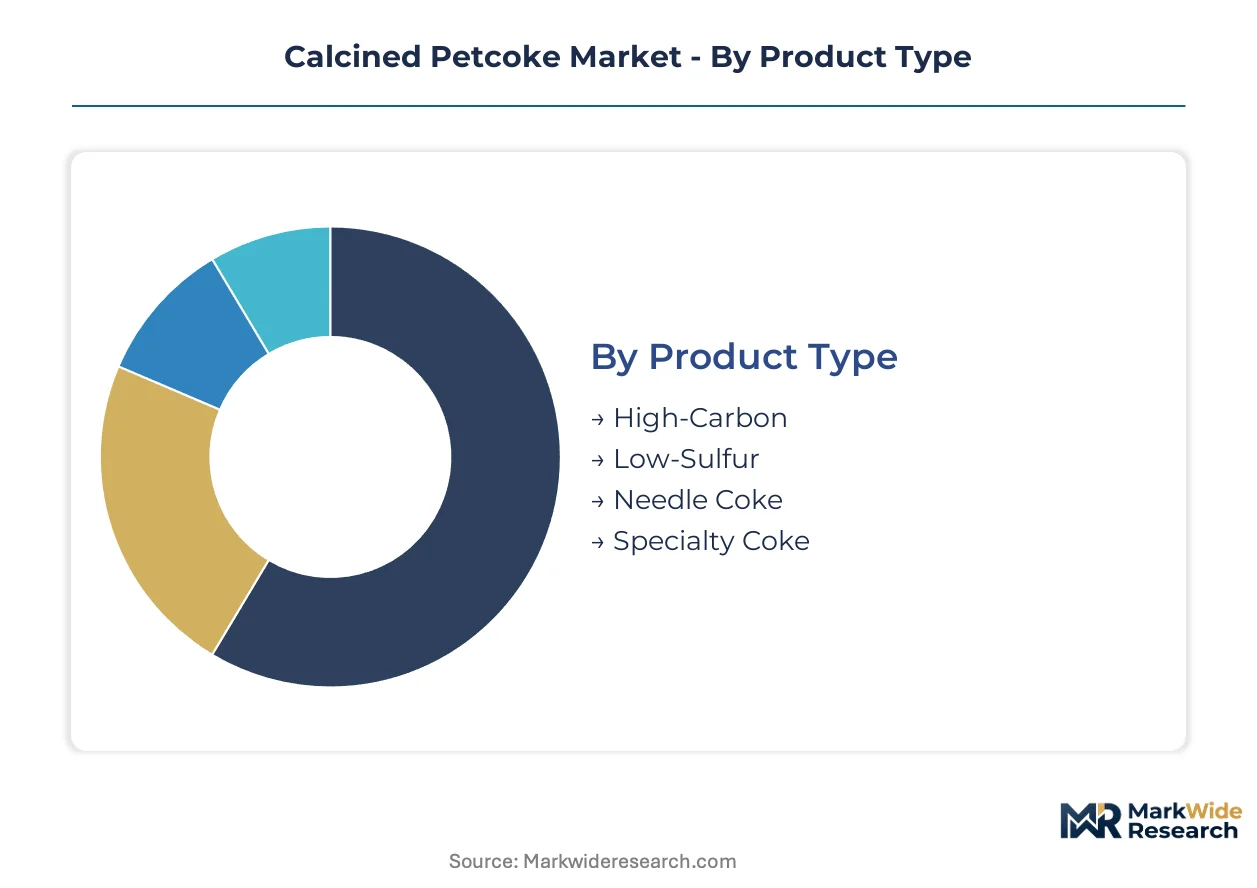
Calcined petcoke specifications diverge sharply across end-use requirements, with sulfur tolerance and carbon density thresholds determining procurement patterns. Material classification directly governs pricing tiers and supply chain qualification protocols.
Product Type:
Carbon purity and crystalline structure separate buyers by performance requirements and substitution risk.
- High-Carbon:Carbon content exceeding 99 percent with controlled volatile residue, serving primary aluminum smelters in India and the Middle East where anode density consistency drives electrolysis efficiency. Indian Oil Corporation's captive calciners target this specification for domestic smelter supply security.
- Low-Sulfur:Sulfur content below 2 percent, qualifying for EU Carbon Border Adjustment Mechanism compliance and China's MEE emission standards. European importers are redirecting procurement toward Middle Eastern and North American sources meeting this threshold.
- Needle Coke:Premium graphite electrode feedstock for electric arc furnace steelmaking.
- Specialty Coke:Aerospace and advanced carbon composite applications requiring ultra-low impurity profiles.
Volume sits with High-Carbon; growth tilts toward Low-Sulfur.
Application:
Process chemistry and thermal intensity dictate material selection across industrial verticals.
- Aluminum Production:Hall-Héroult cell anodes consume the dominant volume share, with smelter-grade specifications requiring consistent reactivity and density. Indian aluminum capacity expansions are creating dedicated demand corridors from domestic calciners.
- Steel Manufacturing:Ultra-high-power graphite electrodes for electric arc furnaces depend on needle coke and premium sponge coke grades. Manufacturers are diversifying feedstock portfolios as needle coke supply tightens.
- Titanium Dioxide Production:Chloride process feedstock requiring controlled sulfur and ash content.
- Carbon Products:Specialty graphite and carbon composite precursors for aerospace specifications.
Aluminum Production commands the installed base; Steel Manufacturing is climbing the fastest on electrode demand.
End User:
Technical sophistication and certification requirements fragment the buyer landscape.
- Metals Industry:Aluminum smelters and steel producers with long-term offtake contracting and Scope 3 traceability demands. European and North American procurement desks are locking five-to-seven-year supply agreements with carbon intensity certification.
- Aerospace Industry:Specialty carbon manufacturers requiring density uniformity beyond conventional shaft kiln capabilities. Flash calcination electrification is addressing this specification gap.
- Energetics Sector:Restricted combustion applications facing EPA and MEE emission constraints.
- Manufacturing Companies:Diversified industrial carbon users with flexible specification tolerance.
Metals Industry anchors procurement volume; Aerospace Industry shows the steepest expansion trajectory on advanced material qualification.
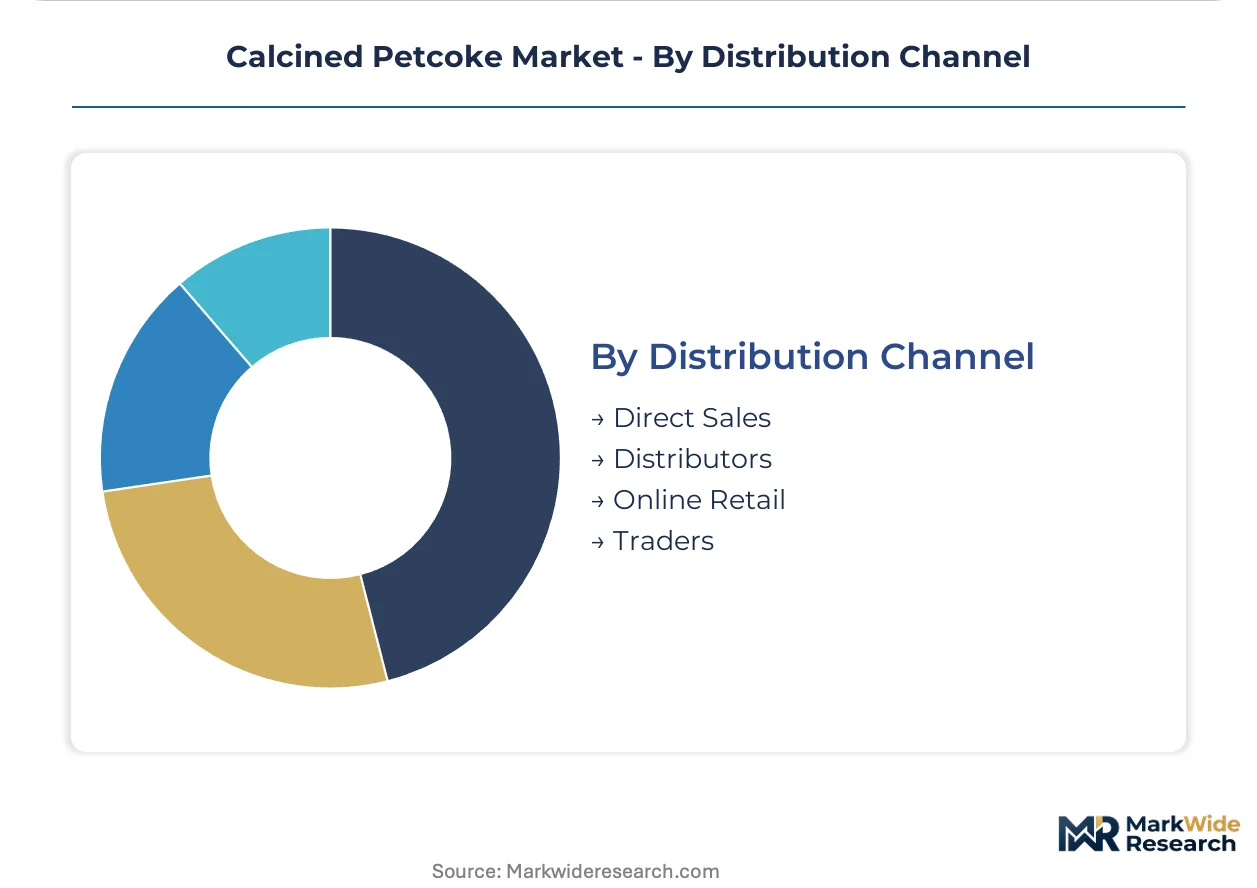
Distribution Channel:
Supply chain control and transaction scale determine channel selection.
- Direct Sales:Integrated relationships between calciners and major aluminum producers with refinery-captive supply chains. Indian Oil Corporation and Reliance Industries leverage this channel for domestic smelter integration.
- Traders:Atlantic basin spot market liquidity and freight arbitrage for high-sulfur grades facing combustion restrictions.
- Distributors:Regional inventory positioning for mid-volume manufacturing customers.
- Online Retail:Emerging platform-based procurement for standardized specification spot purchases.
Direct Sales holds the volume concentration; Traders are gaining share fastest on spot market dislocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Visakhapatnam Special Economic Zone anchors calcination capacity concentration on India's eastern seaboard, drawing refinery-integrated producers toward captive supply corridors serving domestic aluminum smelters.
China
Shandong Province hosts the densest calciner clustering, where rotary kiln operators face MEE emission standard compressions under dual carbon implementation timelines. Domestic smelters in Zhengzhou and Binzhou are rejecting historical high-sulfur supply relationships, redirecting procurement toward Middle Eastern low-sulfur sources.
United States
Louisiana and Texas Gulf Coast refineries dominate exportable green petroleum coke supply, creating single-point vulnerability for Atlantic basin calciners. EPA Clean Air Act enforcement constrains high-sulfur petcoke combustion applications, redirecting material flows toward industrial calcination pathways in the Ohio River Valley aluminum corridor.
India
Gujarat's Jamnagar refining complex and Odisha's aluminum smelter belt are forming integrated supply loops. Indian Oil Corporation's captive calciners at Paradip and Haldia target high-carbon specifications for Vedanta and Hindalco electrolysis expansions, while Reliance Industries integrates rotary kiln capacity at coastal refineries.
Germany
EU Carbon Border Adjustment Mechanism implementation is forcing European importers to qualify low-sulfur calcined petcoke sources for aluminum embedded emissions compliance. The Rhine-Ruhr industrial corridor hosts specialty carbon producers piloting flash calcination electrification to eliminate Scope 1 combustion emissions.
Saudi Arabia
Jubail Industrial City refineries are expanding low-sulfur green coke export capacity to capture Chinese procurement redirection. SABIC-integrated calciners serve both domestic aluminum growth and Asian spot market dislocation, leveraging freight advantages into Pacific basin deliveries.
Calcined Petcoke Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oil companies and independent calciners forming a tiered structure around feedstock access. Refinery-captive operators control upstream green coke supply, while merchant calciners compete on sulfur specification and logistics arbitrage. Two strategic archetypes dominate: integrated petroleum majors with backward control over coker units, and specialized calcination technology houses with rotary kiln density uniformity capabilities. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, as smelters lock five-to-seven-year supply agreements with carbon intensity certification.
Among refinery-integrated operators, Oxbow Corporation and Indian Oil Corporation Ltd. exemplify the captive supply archetype, with the former leveraging Atlantic basin logistics networks and the latter anchoring domestic supply security for Indian aluminum smelters. Rain Carbon Inc. occupies a position within the specialized calcination tier, representing technology leadership in high-carbon product grades for premium anode applications.
| Leading Market Players |
|---|
| Oxbow Corporation |
| Valero Energy Corporation |
| Rain Carbon Inc. |
| Indian Oil Corporation Ltd. |
| Exxon Mobil Corporation |
| BP plc |
| Saudi Aramco |
| Reliance Industries Ltd. |
| Phillips 66 Company |
| Others |
Supply Flow & Price Mechanics
China's MEE dual carbon implementation gates qualified supply for low-sulfur calcined petcoke while simultaneously unlocking premium-tier pricing access for certified producers serving European aluminum smelters facing EU Carbon Border Adjustment Mechanism compliance costs.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Indian aluminum smelters lock five-to-seven-year offtake agreements with domestic calciners to secure Vedanta and Hindalco expansion requirements. Long-term offtake contracting anchors the dominant pricing structure, with differentiation hinging on sulfur certification grade and carbon intensity documentation. Cost compression in high-sulfur grades is intensifying because Chinese smelters are rejecting historical supply relationships. Merchant calciners exhibit the highest price sensitivity, while refinery-captive operators with backward integration into coker units maintain pricing power.
Supply Chain Analysis
Certification requirements for China's MEE standards, India's CEA norms, and EU REACH documentation are fragmenting supplier qualification protocols and compressing addressable vendor pools. Green petroleum coke supply concentrates in the United States, Saudi Arabia, and India, with US Gulf Coast refineries dominating exportable high-sulfur volumes. Calcination operations draw from green coke feedstock, rotary kiln refractory materials, and specialized logistics for bulk carbon transport. Single-source vulnerability runs through US Gulf Coast refinery concentration for Atlantic basin calciners. Distribution runs through direct sales channels for integrated oil companies and trader-mediated spot markets for merchant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between combustion bans and industrial-process exemptions is forcing consolidation among merchant calciners lacking refinery-captive feedstock security.
For Market Incumbents: To counter Chinese procurement redirection toward Middle Eastern low-sulfur sources, Oxbow Corporation and Rain Carbon Inc. should deepen backward integration into coker units at Atlantic basin refineries while investing in multi-jurisdiction sulfur certification testing regimens to preserve European market access. For New Entrants and Emerging Players: Enter via electric vehicle battery anode material qualification, where synthetic graphite producers are sourcing calcined petcoke precursors outside traditional aluminum corridors. Target Indian refinery-captive calcination partnerships with Indian Oil Corporation or Reliance Industries, leveraging coastal rotary kiln capacity additions to serve domestic smelter growth without competing against established Atlantic basin logistics networks. For Investors and Strategic Acquirers: Long-term offtake contracting displacement of spot purchasing is the leading indicator that refinery-integrated calciners with carbon intensity certification capabilities will capture sustained margin premiums. Over a multi-year window, prioritize acquisition targets with captive green coke supply and demonstrated EU CBAM compliance documentation. Watch for MEE emission standard tightening announcements as the inflection signal for Chinese procurement redirection velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery-Captive Calcination Expansion | Indian Oil Corporation's Paradip and Haldia integration secures domestic aluminum smelter supply security against import volatility. |
| Flash Calcination Electrification | Rhine-Ruhr specialty carbon producers pilot plasma-assisted systems to eliminate Scope 1 emissions for aerospace qualification. |
| Long-Term Offtake Contracting | European smelters lock five-to-seven-year agreements with calciners demonstrating feedstock traceability and carbon intensity certification. |
| Multi-Jurisdiction Sulfur Certification | Calciner operators maintain parallel testing regimens for MEE, CEA, and REACH standards to preserve market access. |
| Low-Sulfur Feedstock Qualification | Saudi Aramco's Jubail expansion captures Chinese procurement redirection from high-sulfur historical suppliers. |
Methodological Framework
Multi-period observation of aluminum capacity commissioning timelines, refinery coker unit utilization rates, and sulfur emission standard implementation schedules anchored the trend analysis, supplemented by interviews with rotary kiln operations managers, aluminum smelter procurement leads, petroleum coke traders, and technical R&D directors at specialty carbon producers. Secondary validation drew from customs and trade data, SEC filings by integrated oil companies, EPA Clean Air Act enforcement records, and China MEE emission standard announcements. Bottom-up calciner capacity modeling and top-down aluminum production forecasts were triangulated to derive volume estimates.
Segment-weighting applied product type classifications across high-carbon, low-sulfur, needle coke, and specialty coke tiers, with application splits across aluminum production, steel manufacturing, titanium dioxide, and carbon products, further disaggregated by end-user sophistication and distribution channel control. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost pass-through. Industry-specific forecast inputs included Hall-Héroult cell anode consumption coefficients and electric arc furnace electrode replacement cycles.
Revisions become necessary when refinery coker unit shutdowns, MEE emission standard acceleration, or EU CBAM scope expansion materialize beyond baseline assumptions. Forecasts reflect documented expectations regarding aluminum capacity growth trajectories and low-sulfur green coke supply elasticity. A model refresh is warranted upon material change in Chinese dual carbon implementation timelines or Indian refinery expansion completion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Alunite Market