
 Chlorotoluenes Market | 2026-2036
Chlorotoluenes Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorotoluenes Market Analytics
Technical-grade maintenance contracts for purification and isomer separation is pivoting how chlorotoluene suppliers monetize long-term relationships. LANXESS leverages its integrated aromatics platform to sustain European pharmaceutical-grade supply chains. WeylChem International GmbH anchors custom synthesis services for agrochemical intermediates. TORAY INDUSTRIES, INC. dominates high-purity monochlorotoluene production for electronic chemical applications.
Chlorotoluenes comprise toluene ring structures substituted with one to three chlorine atoms, yielding ortho, meta, and para positional isomers with boiling points ranging from 158°C to 220°C depending on substitution pattern and isomer ratio; manufacturers employ catalytic chlorination with Lewis acid catalysts followed by fractional distillation to isolate specific isomers for downstream chemical synthesis. Monochlorotoluene leads product type volume due to its versatility as a solvent and intermediate, while dichlorotoluene claims the fastest growth trajectory driven by agrochemical precursor demand. Pharmaceutical end use concentrates margin pools where purity certifications command premium pricing, whereas paints application remains mature with thinner margin structures.
EPA oversight under the Toxic Substances Control Act shapes chlorotoluene manufacturing standards in the United States, while REACH registration requirements in Europe mandate comprehensive safety data documentation for import and production volumes above one tonne annually. China's MEE enforces wastewater discharge limits on chlorination facilities operating near the Yangtze River basin. India's Central Pollution Control Board monitors volatile organic compound emissions at Gujarat and Maharashtra chemical clusters. Stakeholders must track evolving per- and polyfluoroalkyl substance restrictions that could redirect solvent demand toward chlorotoluene alternatives in specific coating applications.
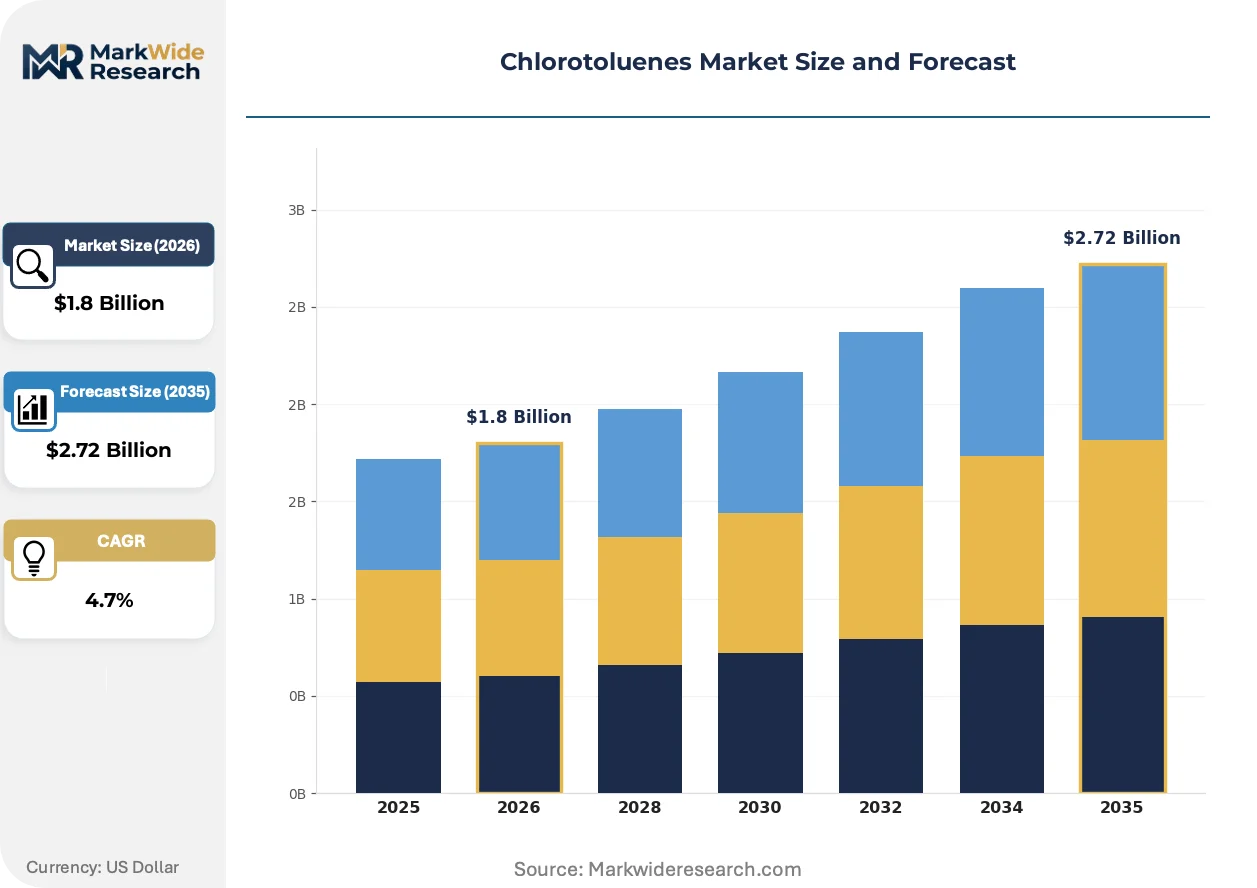
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins while concentrating procurement power among integrated aromatics producers with captive chlorination capacity. The shift from commodity solvent sales to long-term technical service contracts is redistributing value capture across the value chain.
Growth Catalysts
- Agrochemical precursor demand:Dichlorotoluene consumption for herbicide and fungicide intermediates is expanding manufacturing runs at dedicated chlorination facilities in East Asia.
- REACH registration completion:European pharmaceutical manufacturers now source documented high-purity monochlorotoluene with full safety data sheets, enabling qualified supplier status.
- Jiangsu province capacity expansion:Integrated chemical parks along the Yangtze River basin are consolidating chlorotoluene production with on-site wastewater treatment infrastructure.
Market Restraints
- Toluene feedstock volatility:Crude oil-linked aromatic feedstock costs create margin pressure for non-integrated chlorotoluene producers without backward integration into refinery operations.
- MEE discharge limits:China's Ministry of Ecology and Environment enforces tightening COD and AOX limits on chlorination effluent, requiring capital-intensive tertiary treatment upgrades.
- Fluorinated solvent substitution:Per- and polyfluoroalkyl substance restrictions in coatings are redirecting some electronics cleaning applications toward hydrofluoroether alternatives.
Strategic Opportunities
- Electronic chemical grade expansion:Semiconductor fabrication facilities in Taiwan and South Korea are qualifying ultra-high-purity monochlorotoluene for photoresist solvent applications.
- Custom synthesis services:Agrochemical innovators are outsourcing dichlorotoluene derivative production to contract manufacturers with dedicated isomer separation capabilities.
- India PLI scheme alignment:Pharmaceutical active ingredient production incentives are stimulating domestic chlorotoluene intermediate demand in Gujarat and Maharashtra clusters.
Industry Challenges
- Isomer separation expertise scarcity:Fractional distillation operations requiring precise ortho-meta-para ratio control face recruitment difficulties for experienced process engineers.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA pre-manufacture notifications and REACH dossier submissions create regulatory approval bottlenecks for new chlorotoluene derivatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorotoluenes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochlorotoluene, Dichlorotoluene, Trichlorotoluene, Others End Use Industry: Pharmaceuticals, Chemicals, Agriculture, Paints Application: Solvent, Intermediate, Chemical Synthesis, Adhesives Packaging Type: Drums, IBC Totes, Bulk Containers, Bottles |
| Companies Covered | LANXESS, WeylChem International GmbH, TORAY INDUSTRIES, INC., Valtris Specialty Chemicals, IHARANIKKEI CHEMICAL INDUSTRY CO., LTD., INEOS, BASF SE, Shandong Exceris Chemical Co. Ltd, Gujarat Alkalies and Chemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorotoluenes Market Evolving Landscape
Catalytic chlorination process intensification is reshaping capital efficiency and environmental performance benchmarks. Suppliers are reconfiguring asset footprints around continuous-flow reactor technology.
Membrane-based isomer separation is absorbing capital allocation from traditional crystallization and distillation trains. Pharmaceutical-grade producers in Germany and Switzerland are retrofitting hybrid separation units to reduce energy intensity. This technology is absorbing market share from conventional purification methods by enabling 99.9%+ purity at reduced solvent recovery costs.
EPA's evolving standards under the Toxic Substances Control Act are mandating expanded chemical data reporting for chlorinated aromatic imports. Manufacturers must now submit pre-manufacture notifications for new chlorotoluene derivatives above specified volume thresholds. Electronic chemical applications face the steepest compliance burden as downstream semiconductor fabricators demand full supply chain transparency.
Long-term offtake agreements are displacing spot market transactions for pharmaceutical-grade material. Indian and Chinese active ingredient manufacturers are locking in three-to-five-year supply contracts with fixed purity specifications and technical service inclusions. This pattern concentrates procurement relationships around integrated suppliers with dedicated quality assurance teams.
Chlorotoluenes Market Segmentation
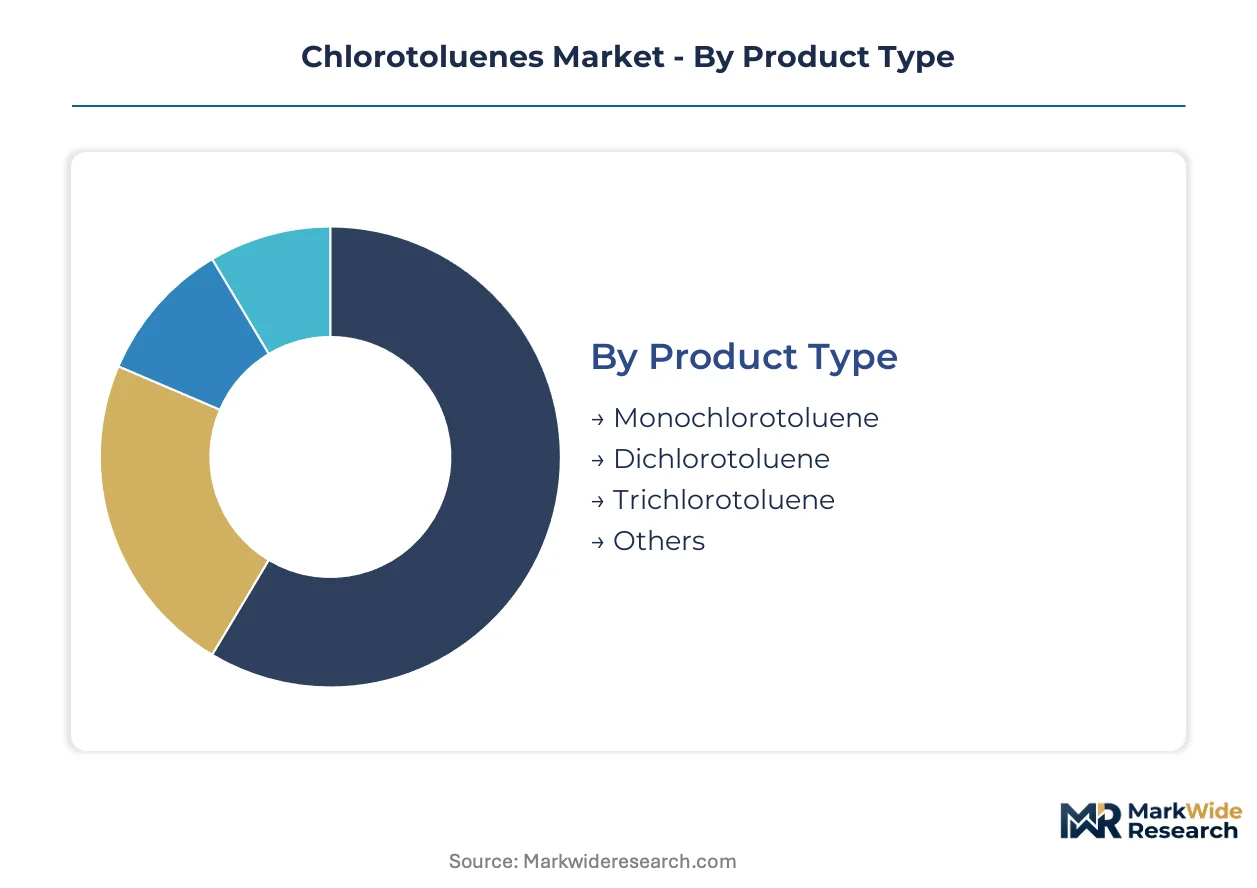
Chlorotoluene segmentation reflects divergent purity requirements across pharmaceutical, agrochemical, and electronics supply chains. Isomer ratio precision and certification grade determine supplier qualification status for each downstream application.
Product Type:
Chlorination degree defines boiling point ranges, isomer complexity, and addressable end-use markets for each product tier.
- Monochlorotoluene:Single chlorine substitution yields ortho, meta, and para isomers with boiling points between 158°C and 162°C. Pharmaceutical manufacturers in Gujarat and Maharashtra specify 99.5%+ purity for active ingredient synthesis. Electronic chemical applications in Taiwan and South Korea are qualifying ultra-high-purity grades for photoresist solvents.
- Dichlorotoluene:Double substitution creates six positional isomers requiring fractional distillation expertise. Agrochemical innovators are outsourcing derivative production to contract manufacturers with dedicated isomer separation capabilities for herbicide and fungicide intermediates.
- Trichlorotoluene:Triple-substituted specialty intermediate for high-performance polymer precursors.
- Others:Mixed chlorination grades and custom isomer ratios for niche synthesis applications.
Monochlorotoluene leads on scale; dichlorotoluene leads on momentum.
End Use Industry:
Margin structures diverge sharply between certified pharmaceutical supply and commodity solvent applications.
- Pharmaceuticals:Active ingredient manufacturers demand full REACH dossier documentation and EPA TSCA compliance. Long-term offtake agreements with fixed purity specifications are displacing spot market transactions for this segment.
- Chemicals:General synthesis and solvent applications represent mature volume demand with thinner margin structures.
- Agriculture:Herbicide and fungicide precursor demand is expanding manufacturing runs at dedicated chlorination facilities in Jiangsu province.
- Paints:Coating thinner applications face substitution pressure from hydrofluoroether alternatives under evolving per- and polyfluoroalkyl substance restrictions.
Pharmaceuticals commands premium pricing; agriculture shows steepest expansion trajectory.
Application:
Functional role determines specification stringency and customer stickiness for chlorotoluene suppliers.
- Solvent:Electronics cleaning and coating formulation applications require ultra-low moisture and particulate specifications. Semiconductor fabricators in Taiwan and South Korea demand full supply chain transparency documentation.
- Intermediate:Custom synthesis services for agrochemical derivatives require precise ortho-meta-para ratio control and dedicated isomer separation capabilities.
- Chemical Synthesis:General-purpose chlorination feedstock for commodity aromatic derivative production.
- Adhesives:Specialty solvent applications in industrial bonding formulations with moderate purity requirements.
Solvent applications concentrate procurement power; intermediate demand is climbing the fastest.
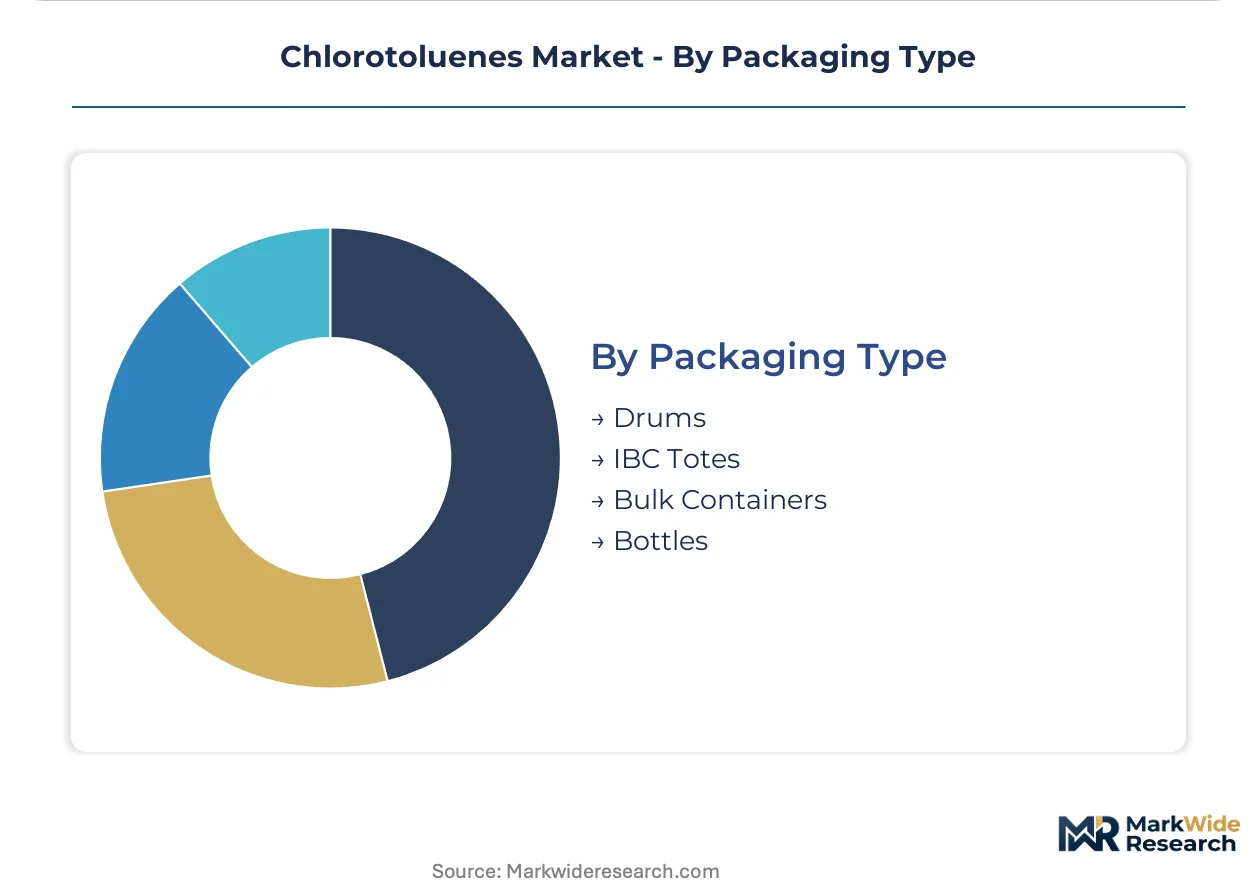
Packaging Type:
Container specification aligns with shipment scale, purity preservation, and customer operational requirements.
- Drums:Standard 200-liter steel drums dominate pharmaceutical-grade shipments requiring sealed integrity for high-purity material. LANXESS leverages integrated aromatics platforms to sustain European drum-supplied pharmaceutical chains.
- IBC Totes:Intermediate bulk containers serve mid-volume chemical synthesis customers with just-in-time inventory needs.
- Bulk Containers:Dedicated tanker and ISO tank shipments for integrated chemical parks with on-site storage infrastructure.
- Bottles:Laboratory-scale packaging for R&D sampling and analytical reference standard distribution.
Drums anchor pharmaceutical-grade logistics; IBC totes are gaining share fastest in chemical synthesis procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting chlorotoluene production toward jurisdictions with lower compliance costs and expanding captive demand. Producers are consolidating capacity in chemical parks with integrated wastewater treatment to offset tightening discharge limits elsewhere.
China
Jiangsu province chemical parks along the Yangtze River basin anchor East Asian chlorotoluene supply, with MEE enforcing COD and AOX discharge limits that favor integrated producers with on-site tertiary treatment. Monochlorotoluene output serves domestic pharmaceutical active ingredient manufacturers and electronics chemical distributors in Shanghai and Suzhou.
India
Gujarat and Maharashtra chemical clusters concentrate dichlorotoluene demand from agrochemical innovators outsourcing intermediate synthesis. The PLI scheme for pharmaceutical manufacturing stimulates domestic procurement of high-purity monochlorotoluene, while CPCB monitors VOC emissions at Ankleshwar and Vapi industrial estates.
Germany
REACH registration requirements and ECHA oversight shape pharmaceutical-grade supply chains serving European active ingredient manufacturers. LANXESS leverages its integrated aromatics platform from Leverkusen to sustain drum-supplied pharmaceutical relationships with full safety data documentation.
United States
EPA TSCA pre-manufacture notification requirements and evolving reporting standards govern chlorotoluene imports and derivative production. Valtris Specialty Chemicals and INEOS operate within this framework to supply agrochemical and coatings solvent applications from Gulf Coast petrochemical corridors.
Japan
TORAY INDUSTRIES anchors high-purity monochlorotoluene production for semiconductor photoresist solvents serving Taiwan and South Korean fabrication facilities. METI industrial chemical regulations and JIS standards govern electronic chemical grade specifications from Nagoya-area production sites.
Chlorotoluenes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated aromatics producers capturing pharmaceutical-grade premiums and regional chemical houses dominating commodity solvent volumes. Market structure tilts toward consolidation at the high-purity tier while fragmenting across general synthesis applications. Three archetypes dominate: captive chlorination operators with refinery integration, custom synthesis contract manufacturers with isomer separation expertise, and electronic chemical specialists with ultra-high-purity certification. Competitive moves center on backward integration into toluene feedstock and membrane-based purification technology licensing.
Within the integrated aromatics tier, LANXESS and INEOS exemplify European producers with captive chlorination capacity and REACH-compliant documentation systems. TORAY INDUSTRIES occupies a position as the electronic chemical grade specialist serving semiconductor supply chains. WeylChem International GmbH represents the custom synthesis archetype, anchoring agrochemical intermediate production with dedicated isomer separation capabilities. These three companies illustrate how geographic origin and corporate structure map to distinct competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| LANXESS |
| WeylChem International GmbH |
| TORAY INDUSTRIES, INC. |
| Valtris Specialty Chemicals |
| IHARANIKKEI CHEMICAL INDUSTRY CO., LTD. |
| INEOS |
| BASF SE |
| Shandong Exceris Chemical Co. Ltd |
| Gujarat Alkalies and Chemicals Limited |
| Others |
Value Network & Pricing Analysis
Toluene feedstock price volatility cascades through chlorotoluene supply chains, compressing margins for non-integrated producers while amplifying pricing power for refinery-linked operators in Jiangsu province and Gujarat state. Pharmaceutical-grade monochlorotoluene commands substantial premiums over technical-grade solvent material, with purity certifications and REACH documentation creating rigid tier boundaries.
Pricing Analysis
Distributor margins on pharmaceutical-grade drum shipments absorb certification and documentation costs before material reaches Gujarat active ingredient manufacturers. Three-tier pricing structure across electronic chemical, pharmaceutical, and technical solvent grades reflects isomer ratio precision and regulatory burden. Cost compression in commodity solvent tiers intensifies because hydrofluoroether substitution erodes coatings demand. Agrochemical intermediates show highest price sensitivity; semiconductor photoresist solvents show least.
Supply Chain Analysis
REACH registration and EPA TSCA pre-manufacture notification requirements gate supplier qualification for European and North American pharmaceutical procurement. Production concentrates in China, India, and Germany, with Jiangsu province and Gujarat state anchoring Asian capacity. Feedstock draws from crude oil-linked aromatic streams, Lewis acid catalyst supply, and specialized fractional distillation equipment. Single-source vulnerability runs through electronic chemical grade isomer separation expertise. Distribution runs through drum shipments for pharmaceutical grade, IBC totes for chemical synthesis, and bulk tanker for integrated chemical parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlorotoluenes function as a stable compounder, with agrochemical precursor demand and pharmaceutical active ingredient synthesis providing steady offtake visibility across economic cycles.
For Market Incumbents: Lock in long-term technical service contracts with Indian and Chinese pharmaceutical manufacturers before membrane-based purification technology commoditizes isomer separation. Deepen backward integration into refinery toluene streams to neutralize feedstock volatility. Expand captive chlorination capacity in Jiangsu province chemical parks with integrated MEE-compliant wastewater treatment. For New Entrants and Emerging Players: Custom synthesis contract manufacturers represent an underserved buyer archetype seeking dedicated dichlorotoluene isomer separation capabilities for agrochemical derivative production. White-space targets include Taiwan and South Korean semiconductor fabricators qualifying ultra-high-purity monochlorotoluene for photoresist solvents, and Indian agrochemical innovators outsourcing intermediate synthesis under PLI scheme alignment. A qualification-first go-to-market angle bypasses commodity solvent competition. For Investors and Strategic Acquirers: Asymmetric upside sits with custom synthesis specialists possessing fractional distillation expertise and existing REACH dossier documentation. Long-term viability centers on electronic chemical grade certification and pharmaceutical supply chain integration. Watch for inflection when semiconductor fabricators in Taiwan and South Korea accelerate photoresist solvent qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Based Purification Retrofit | German and Swiss pharmaceutical-grade producers reduce energy intensity while achieving 99.9%+ purity certification. |
| Backward Integration into Toluene Feedstock | Refinery-linked operators in Jiangsu province neutralize crude oil-linked aromatic cost volatility. |
| Long-Term Offtake Agreement Expansion | Indian active ingredient manufacturers lock in three-to-five-year pharmaceutical-grade supply with technical service inclusions. |
| Electronic Chemical Grade Qualification | TORAY INDUSTRIES anchors semiconductor photoresist solvent supply chains serving Taiwan and South Korean fabrication. |
| Joint Venture in Integrated Chemical Park | Consolidated chlorotoluene production with on-site MEE-compliant wastewater treatment reduces regulatory risk in Yangtze River basin. |
Research Methodology
Coverage spans East Asia, South Asia, Europe, and North America, with primary inputs from each region combined with secondary validation. Plant managers at Jiangsu province chlorination facilities, procurement leads at Gujarat pharmaceutical manufacturers, distribution channel partners handling drum and IBC tote logistics, and technical R&D directors developing membrane-based isomer separation provided interview inputs. Secondary sources include customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed aromatics producers, and EPA TSCA chemical data reporting disclosures. Bottom-up capacity and demand modeling triangulates against top-down industry association aggregates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include chlorination degree tier, end-use industry, packaging format, and regional production hub. CAGRs derive from regression against downstream demand drivers and capacity expansion announcements. Forecast inputs incorporate REACH registration completion timelines and MEE discharge limit enforcement trajectories.
Underlying measurement precision varies by segment; pharmaceutical-grade volume and purity-certified electronic chemical grade carry tighter precision than commodity solvent applications. Forecasts reflect assumptions about agrochemical outsourcing patterns and semiconductor fabrication capacity expansion. A model refresh is warranted upon material change in EPA TSCA reporting requirements or MEE wastewater discharge enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Sodium Bromate Market