
 Motorized Valves Market | 2026-2036
Motorized Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Motorized Valves Market Analytics
Modular actuator-valve bundling is realigning procurement patterns across energy and utility sectors. Emerson Electric Company leverages integrated digital positioners to anchor premium positioning in upstream oil applications. Danfoss competes through thermal management specialization that extends its footprint in district heating networks.
Motorized valves are electromechanically actuated flow control devices, typically rated for pressures from ANSI Class 150 to 2500 and temperatures spanning cryogenic to above 500°C, designed to automate fluid isolation or regulation in process piping. Stainless steel constructions dominate chemical processing due to corrosion resistance requirements, while PVC variants occupy cost-sensitive water treatment installations. Modulating control configurations are capturing margin pools in HVAC optimization projects where precision thermal regulation commands specification priority.
EPA effluent standards and EU F-Gas Regulation are tightening leakage tolerance thresholds that elevate motorized valve replacement cycles in cooling and refrigeration systems. China's GB standards and NMPA process equipment directives enforce actuator compatibility certification that filters import eligibility. Buyers must weigh smart actuator retrofit economics against full system replacement as cybersecurity protocols harden across critical infrastructure networks.
Market Dynamics
Smart actuator integration with IoT-enabled diagnostics is compressing replacement cycles and elevating specification requirements across municipal water, petrochemical, and HVAC infrastructure networks.
Growth Catalysts
- Water Infrastructure Modernization:EPA effluent standards and EU F-Gas Regulation are tightening leakage tolerance thresholds that accelerate motorized valve procurement in cooling and refrigeration systems across municipal and industrial water treatment.
- GB Standards Enforcement:China's NMPA process equipment directives mandate actuator compatibility certification that filters import eligibility and elevates domestic supplier qualification requirements.
- Petrochemical Corridor Expansion:Demand concentrates in China's refining zones and India's downstream expansion clusters where automated flow control supports continuous process reliability.
Market Restraints
- Stainless Steel Input Volatility:Corrosion-resistant alloy pricing fluctuations compress margin stability for chemical processing valve manufacturers dependent on ANSI Class 2500-rated constructions.
- Supply Concentration Risk:Premium digital positioner production clusters in Germany and the United States create procurement bottlenecks for mid-scale actuator bundling programs.
- Technical Limitation:Cryogenic-to-above-500°C temperature span requirements in LNG applications restrict material selection and extend qualification timelines for modular actuator-valve configurations.
Strategic Opportunities
- District Heating Network Expansion:Thermal management specialization in Northern European municipal systems creates specification openings for modulating control configurations in precision thermal regulation projects.
- India Refining Capacity Buildout:Downstream petrochemical investments in Gujarat and Maharashtra generate demand for ANSI Class 150-2500 rated motorized isolation valves in process piping automation.
- Cybersecurity Protocol Hardening:Critical infrastructure network protection mandates in the United States and Germany create retrofit economics advantages for smart actuator integration over full system replacement.
Industry Challenges
- Actuator-Smart Device Integration Complexity:Legacy SCADA system compatibility requirements in municipal water utilities extend commissioning timelines and elevate field engineering costs for IoT-enabled diagnostics deployment.
- Cross-Border Certification Timeline Compression:Dual carbon goals enforcement through China's MEE and compatibility with EU F-Gas Regulation create parallel approval pathways that delay market entry for bundled actuator-valve offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorized Valves Market |
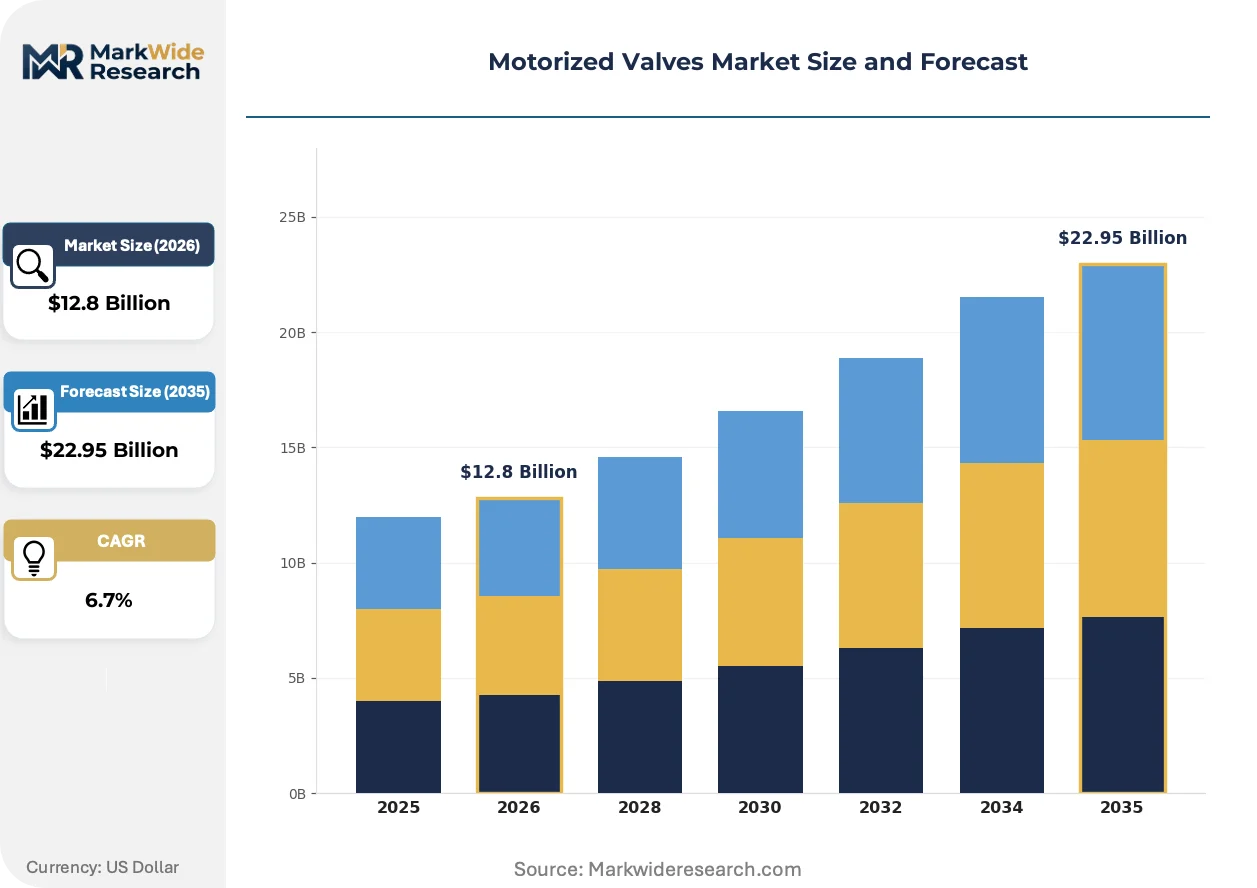
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Butterfly Valves, Plug Valves End User: Oil & Gas, Water Treatment, HVAC, Chemical Processing Control Type: On/Off Control, Modulating Control, Pressure Control, Flow Control Material: Stainless Steel, Bronze, PVC, Carbon Steel |
| Companies Covered | Emerson Electric Company, Danfoss, Flowserve Corporation, Rotork, IMI Precision Engineering, Samson, GEMÜ Group, Burkert, Belimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorized Valves Market Evolving Landscape
Digital positioner technology and predictive maintenance algorithms are redefining competitive positioning across upstream oil, district heating, and precision HVAC applications.
Intelligent valve positioners with embedded diagnostic sensors are automating condition monitoring and failure prediction in continuous process environments. Upstream oil operators in the United States and Germany are specifying these configurations for remote asset management. The technology is automating maintenance scheduling and compressing unplanned downtime intervals across dispersed production facilities.
EU F-Gas Regulation phase-down mandates are accelerating leakage detection integration in motorized valve specifications for cooling and refrigeration systems. Industrial refrigeration OEMs must now certify sub-1% annual leakage rates for systems above specific charge thresholds. Food processing and cold chain logistics facilities in Germany and France are prioritizing motorized ball and butterfly valves with sealed actuator housings to maintain compliance.
Integrated service contracts bundling hardware, installation, and predictive analytics are displacing transactional procurement in municipal water authorities. Equipment distributors in China and India are restructuring commercial teams around lifecycle revenue models. Water treatment infrastructure upgrades in Shanghai and Mumbai are specifying ten-year total cost of ownership frameworks rather than upfront capital expenditure minimization.
Motorized Valves Market Segmentation
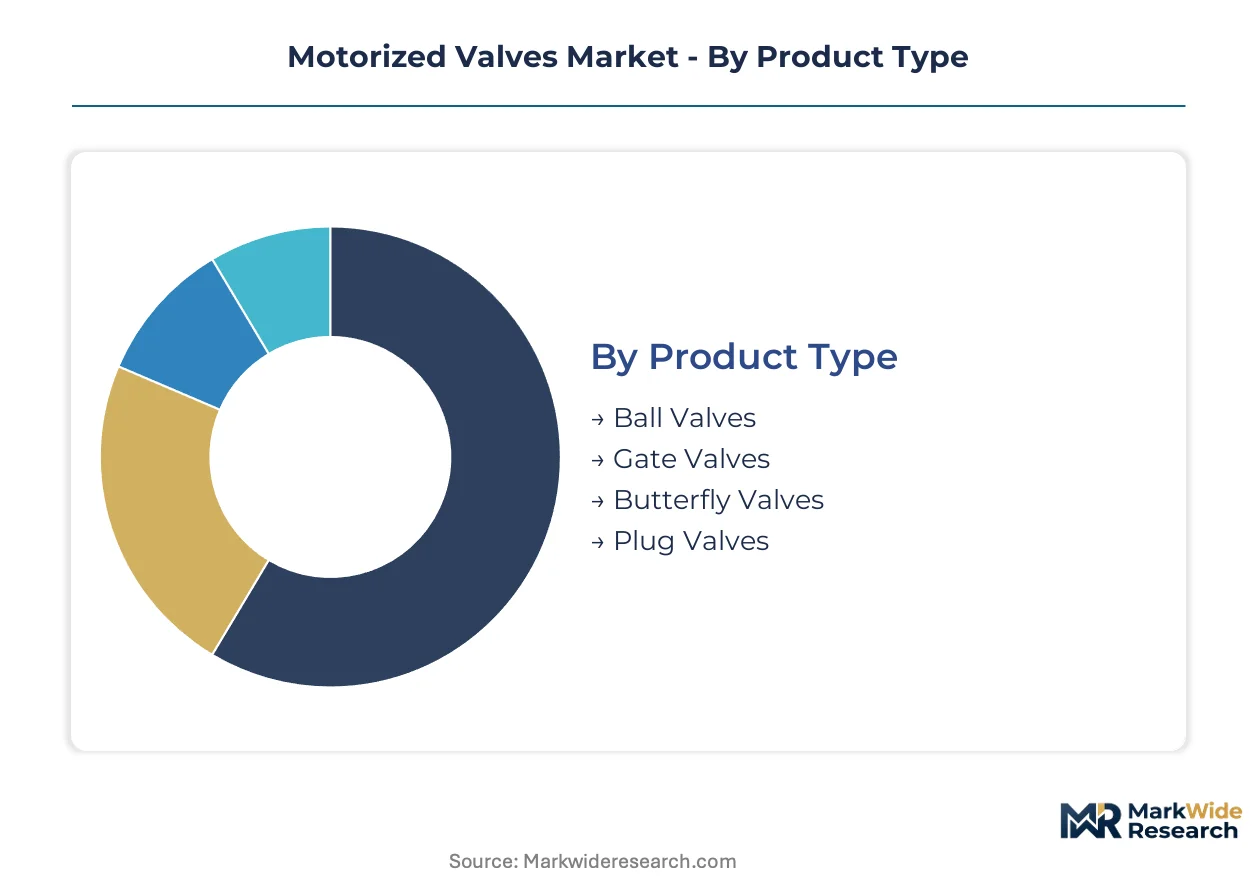
Segmentation in motorized valves reveals how specification requirements diverge across pressure ratings, temperature tolerances, and automation protocols. Procurement patterns cluster around material selection and control precision, with smart actuator integration reshaping category boundaries across municipal and industrial infrastructure.
Product Type:
Standardized quarter-turn designs dominate high-volume procurement, while engineered multi-turn configurations command premium positioning in severe service applications.
- Ball Valves:Spherical closure elements with full-port or reduced-port configurations deliver tight shutoff in ANSI Class 150-2500 pressure ranges. Demand concentrates in upstream oil gathering systems across Texas and North Dakota where remote automation reduces field operator exposure.
- Butterfly Valves:Compact wafer and lug-style constructions with elastomer-lined or metal-seated discs optimize space-constrained installations. Water treatment facilities in Shanghai and Mumbai specify these for large-diameter flow regulation where weight reduction simplifies infrastructure loading.
- Gate Valves:Multi-turn rising stem designs with wedge or parallel slide gates suit isolation duties in high-pressure steam systems.
- Plug Valves:Cylindrical or tapered plug elements with lubricated or non-lubricated seals handle abrasive slurry applications in mining and mineral processing.
Leading the category by volume: Ball Valves. Expanding most quickly: Butterfly Valves.
End User:
Capital intensity and regulatory stringency create divergent procurement rhythms across process industries versus building automation.
- Oil & Gas:Upstream production, midstream transmission, and downstream refining operations require fire-safe certified constructions meeting API 6D and API 607 standards. Petrochemical corridor investments in Gujarat and Maharashtra generate concentrated demand for ANSI Class 600-2500 rated motorized isolation valves.
- Water Treatment:Municipal distribution, wastewater effluent, and desalination facilities specify corrosion-resistant materials with extended cycle life. EPA effluent standards and EU F-Gas Regulation leakage thresholds accelerate replacement cycles in cooling tower and refrigeration system integrations.
- HVAC:Building automation systems prioritize modulating control precision for thermal optimization in commercial and institutional structures.
- Chemical Processing:Aggressive media compatibility requirements elevate stainless steel and alloy specifications for acid, caustic, and solvent handling.
Dominating procurement value: Oil & Gas. Climbing the fastest: Water Treatment.
Control Type:
Simple binary actuation yields to precision positioning as energy efficiency mandates tighten across process and building systems.
- Modulating Control:Proportional positioning with 4-20mA or digital feedback enables precise throttling for thermal regulation and flow balancing. District heating networks in Denmark and Sweden specify these configurations for supply temperature optimization that cuts carbon intensity.
- On/Off Control:Two-position actuation with limit switch feedback provides reliable isolation for safety shutdown and batch sequencing. LNG liquefaction trains in Qatar and Australia deploy these for cryogenic emergency isolation where fail-safe spring-return actuation is mandatory.
- Pressure Control:Self-operating or pilot-actuated configurations maintain downstream pressure stability in variable demand conditions.
- Flow Control:Velocity-responsive actuation adjusts valve position to maintain setpoint throughput in pump protection and metering applications.
Highest installed base: On/Off Control. Steepest expansion trajectory: Modulating Control.
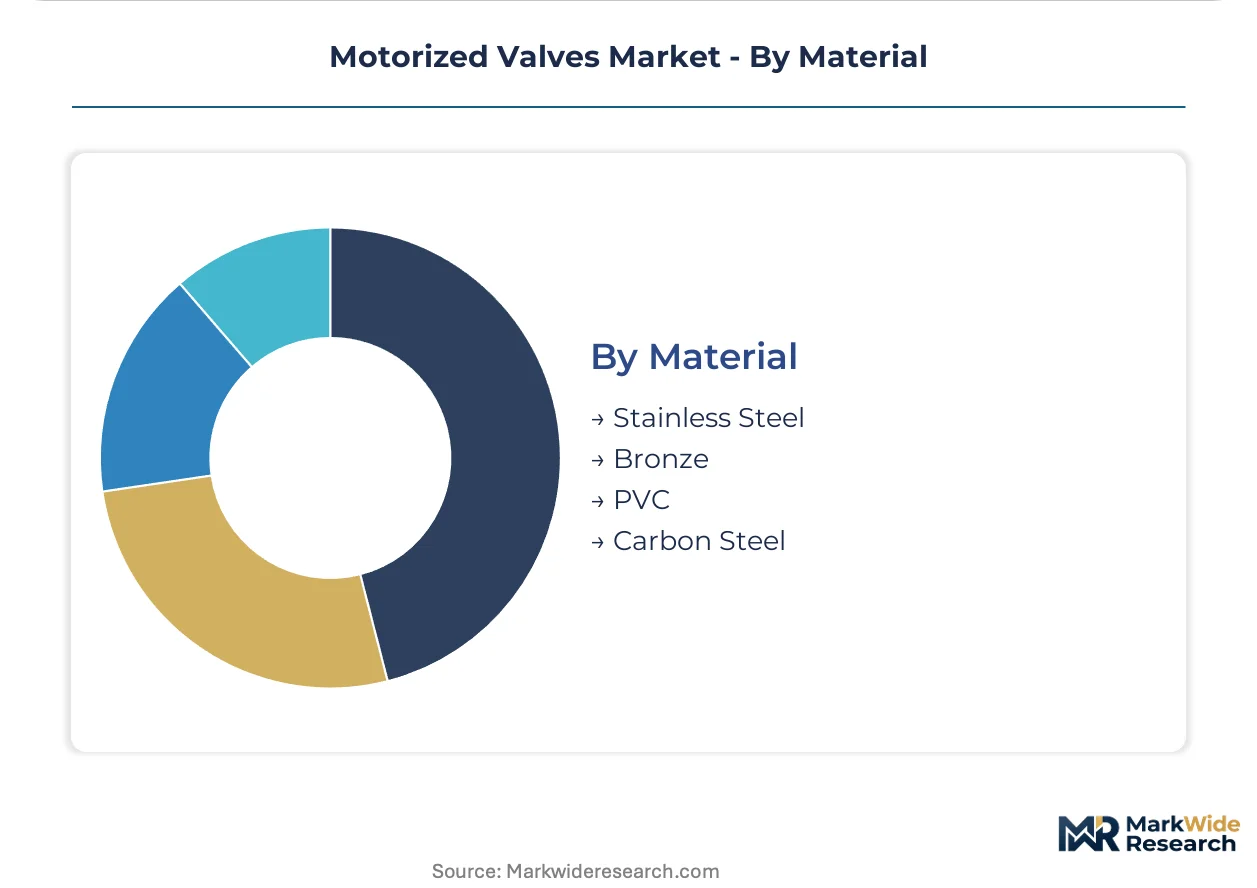
Material:
Corrosion resistance versus cost optimization drives material selection across chemical compatibility and pressure-temperature ratings.
- Stainless Steel:Austenitic and duplex grades deliver chloride stress corrosion resistance for offshore, chemical, and pharmaceutical applications. North Sea platform operators and FDA-regulated bioprocessing facilities specify 316L and super-duplex constructions for seawater and high-purity media.
- PVC:Thermoplastic constructions with EPDM or FPM seals offer chemical inertness at ambient temperatures for water treatment and irrigation. Cost-sensitive municipal procurement in India and Southeast Asia favors these for non-critical isolation in chlorinated water distribution.
- Bronze:Copper-tin alloys with dezincification resistance suit potable water and marine applications where galvanic compatibility matters.
- Carbon Steel:WCB and LCC castings with corrosion allowances handle high-pressure steam and hydrocarbon service in temperature ranges exceeding PVC limits.
Commanding premium pricing: Stainless Steel. Gaining share fastest: PVC.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's petrochemical corridor concentrate motorized valve procurement, while India's refining expansion zones and Germany's district heating networks generate complementary demand clusters across process automation infrastructure.
United States
Upstream oil gathering systems in Texas and North Dakota drive demand for ANSI Class 150-2500 rated ball valves with remote automation capabilities. EPA effluent standards tighten leakage tolerance thresholds that accelerate replacement cycles in municipal water treatment cooling systems. The Permian Basin and Bakken formation operators specify fire-safe certified constructions meeting API 6D standards for continuous process reliability.
Germany
District heating networks in Denmark and Sweden create specification openings for modulating control configurations in precision thermal regulation projects. EU F-Gas Regulation phase-down mandates accelerate leakage detection integration in cooling and refrigeration system specifications. Industrial refrigeration OEMs in Bavaria and Baden-Württemberg now certify sub-1% annual leakage rates for systems above specific charge thresholds.
China
Petrochemical corridor investments in refining zones concentrate demand for automated flow control supporting continuous process reliability. NMPA process equipment directives enforce actuator compatibility certification that filters import eligibility and elevates domestic supplier qualification requirements. Shanghai water treatment infrastructure upgrades specify ten-year total cost of ownership frameworks rather than upfront capital expenditure minimization.
India
Downstream petrochemical investments in Gujarat and Maharashtra generate demand for ANSI Class 150-2500 rated motorized isolation valves in process piping automation. BIS certification requirements and PLI scheme incentives reshape procurement patterns for industrial valve imports. Mumbai municipal water authorities are restructuring commercial teams around lifecycle revenue models for integrated service contracts.
Japan
Offshore platform operators in the North Sea specification chain drive super-duplex stainless steel demand for chloride stress corrosion resistance. METI energy efficiency mandates elevate modulating control precision requirements in building automation thermal optimization. Kanto region pharmaceutical facilities specify 316L constructions for FDA-regulated bioprocessing high-purity media handling.
Motorized Valves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the motorized valves landscape, creating a tiered structure where scale advantages clash with application-specific engineering depth. Emerson Electric Company and Danfoss anchor premium positioning through integrated digital ecosystems, while mid-scale fabricators compete on thermal management specialization. Strategic moves concentrate on smart actuator retrofit economics and cybersecurity protocol hardening for critical infrastructure networks.
Among diversified industrial conglomerates, Emerson Electric Company and Flowserve Corporation exemplify scale-driven archetypes with upstream oil and chemical processing exposure, while Rotork represents the focused actuator specialist tier. Danfoss occupies a distinct thermal management position within district heating and HVAC optimization segments. These three anchors illustrate how competitive positioning splits between full-system integrators and component-deep specialists across municipal water, petrochemical, and building automation verticals.
| Leading Market Players |
|---|
| Emerson Electric Company |
| Danfoss |
| Flowserve Corporation |
| Rotork |
| IMI Precision Engineering |
| Samson |
| GEMÜ Group |
| Burkert |
| Belimo |
| Others |
Value Network & Pricing Analysis
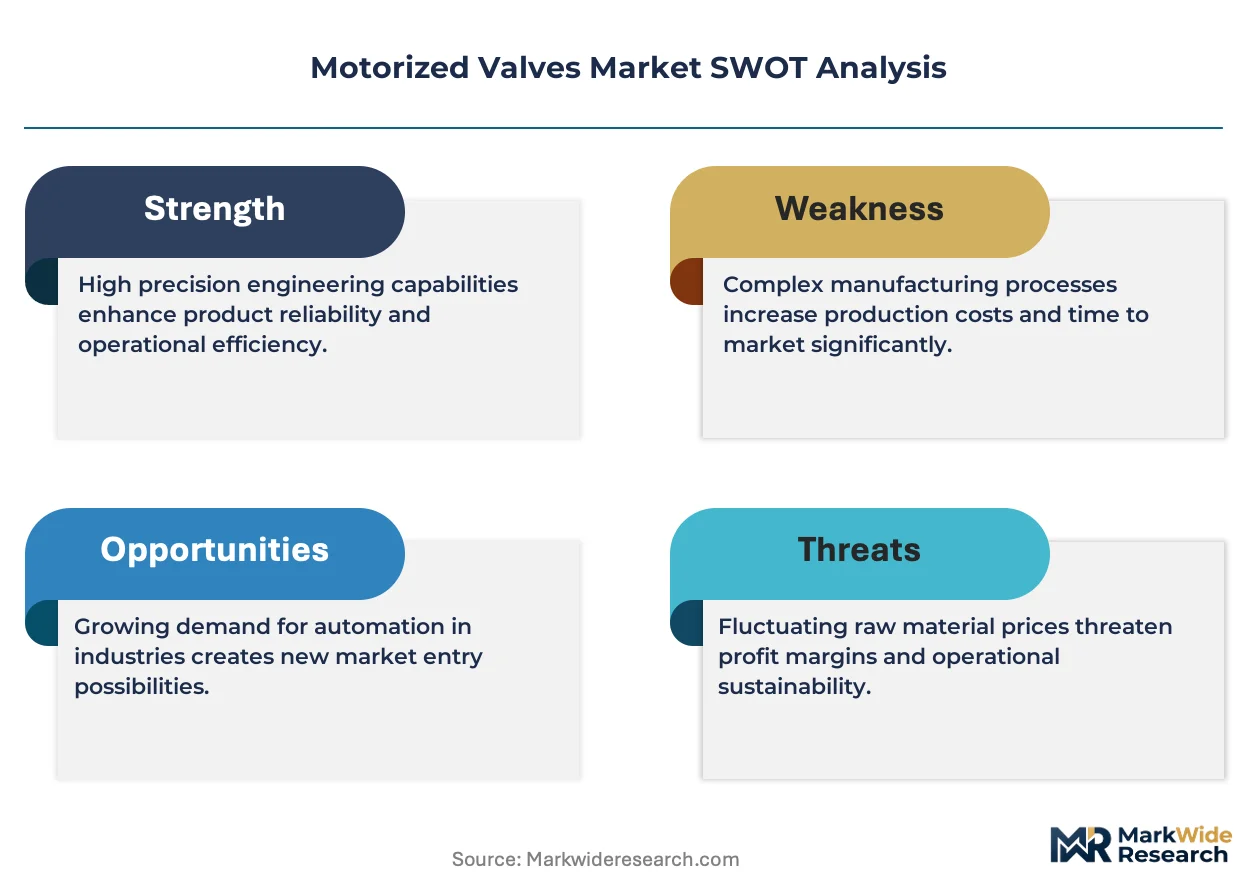
Stainless steel alloy pricing volatility cascades through motorized valve manufacturing tiers, with super-duplex and 316L grade fluctuations compressing margins for ANSI Class 2500-rated chemical processing constructions while PVC variants absorb cost pressure in municipal water procurement.
Pricing Analysis
Cost-down pressure on standard-grade actuators accelerates because mid-scale bundling programs face procurement bottlenecks from German and United States digital positioner production clusters. Three-tier pricing structure across premium, standard, and economy levels separates API 6D-certified fire-safe constructions from modulating control configurations and basic on/off PVC isolators. Price differentiation traces to certification grade and after-sales service bundling. Municipal water authorities in India and Southeast Asia exhibit highest price sensitivity, while North Sea platform operators prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Freight cost escalation from Germany and United States premium component hubs extends lead times for mid-scale actuator-valve bundling programs serving India's refining expansion zones. Manufacturing concentrates in China for domestic petrochemical corridor supply, Germany for district heating thermal management specialization, and India for cost-sensitive water treatment assemblies. Raw material flows draw from Indonesian nickel for stainless steel alloys, German precision electronics for digital positioners, and Chinese rare earth elements for smart actuator motors. Single-source vulnerability concentrates in cryogenic-qualified spring-return actuator supply. Distribution runs through integrated service contract models displacing transactional procurement in Shanghai and Mumbai municipal systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motorized valve manufacturing is consolidating around smart actuator integration capabilities, with NMPA certification requirements and cybersecurity protocol hardening forcing out component-only suppliers lacking digital ecosystem depth.
For Market Incumbents: Lock in district heating network relationships through thermal management specialization that extends beyond hardware supply into predictive analytics service contracts. Defend against pure-play actuator specialists by anchoring API 6D fire-safe certification dominance in Permian Basin upstream oil automation. Deepen backward integration into digital positioner production to reduce German and United States supply concentration exposure.
For New Entrants and Emerging Players: Begin with modulating control configurations for HVAC optimization projects where precision thermal regulation commands specification priority but incumbent bundling is weakest. Target India's Gujarat and Maharashtra refining corridors where BIS certification requirements and PLI scheme incentives reshape import eligibility. Pursue integrated service contract positioning with ten-year total cost of ownership frameworks rather than capital expenditure minimization.
For Investors and Strategic Acquirers: NMPA actuator compatibility certification enforcement is the leading indicator that domestic Chinese supplier qualification requirements will filter import eligibility and elevate acquisition premiums for certified local manufacturing assets. Five-to-ten year viability favors vertically integrated specialists with cryogenic-to-above-500°C temperature span qualification capabilities. Monitor EU F-Gas Regulation sub-1% leakage rate certification timelines as inflection signal for refrigeration system specification winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Actuator Retrofit Integration | Cybersecurity protocol hardening in United States and Germany critical infrastructure creates economics advantages over full system replacement. |
| Backward Integration into Digital Positioners | Reduces procurement bottlenecks from German and United States production clusters for mid-scale bundling programs. |
| Integrated Service Contract Restructuring | Ten-year total cost of ownership frameworks in Shanghai and Mumbai displace transactional procurement in municipal water. |
| Cryogenic Qualification Expansion | LNG liquefaction train specifications in Qatar and Australia mandate fail-safe spring-return actuation with extended material timelines. |
| Thermal Management Specialization | District heating networks in Denmark and Sweden specify modulating control precision for supply temperature optimization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and municipal water authority maintenance directors. Bottom-up and top-down triangulation validated against EPA effluent standard enforcement records, NMPA process equipment directive filings, EU F-Gas Regulation compliance databases, and API 6D certification registries.
Segment-level granularity modeled product type across ball, butterfly, gate, and plug valve configurations; end user across oil and gas, water treatment, HVAC, and chemical processing; control type across modulating, on/off, pressure, and flow configurations; and material across stainless steel, PVC, bronze, and carbon steel constructions. CAGRs derived from installed base replacement cycle analysis, petrochemical capacity buildout tracking, and smart actuator penetration curve modeling across the analysis window.
Underlying measurement precision varies by segment; stainless steel and modulating control categories carry tighter precision than PVC and on/off configurations due to certification registry completeness. Forecasts reflect assumptions on GB standards enforcement timelines, dual carbon goal implementation pace, and cybersecurity protocol adoption curves. Stakeholders should weight assumptions against their own operating context regarding raw material price volatility and cross-border certification pathway durations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pneumatic Positioner Market
Valves
Global Globe Valve Market
Valves
Directional Control Valves Market
Valves
Global Level Gauge Market
Valves
Pipeline Pigging System Market
Valves
Valve Driver Market
Valves
Pressure Reducing Valve Market
Valves
Manual Control Valve Market
Valves
Choke and Kill Manifold Market
Valves
Gas Equipment Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Middle East and Africa Machined Seals Market
Valves
Pipeline Equipment Market
Valves
Choke Valves Market
Valves
Global Pipeline Safety Market
Valves
Diaphragm Valve Market