
 Air Heated Vaporizer Market | 2026-2036
Air Heated Vaporizer Market Size, Share, and Industry Trends Forecast 2026-2036
Air Heated Vaporizer Market Analytics
Welding and cryogenic systems engineering talent is rotating toward air heated vaporizer fabrication as LNG infrastructure construction accelerates across North America and Asia. Chart Industries leverages its integrated cold box and heat exchanger manufacturing to sustain cost advantages in large-scale ambient vaporizer contracts. Linde PLC anchors its position through captive demand from its industrial gas distribution network, while Nikkiso Co., Ltd. competes on precision aluminum fin-tube fabrication for compact modular units.
An air heated vaporizer transfers thermal energy from ambient air to cryogenic liquids such as liquefied natural gas, liquid nitrogen, or liquid oxygen through extended surface aluminum or stainless steel fin-tube bundles, raising fluid temperature above vaporization point without combustion or electric heating elements. These systems serve essential functions in LNG regasification terminals, industrial gas supply stations, and medical oxygen distribution networks where operational safety and elimination of emissions from fuel combustion carry priority. Portable vaporizers lead current revenue contribution due to deployment flexibility across remote construction sites and temporary industrial gas requirements, though medical vaporizers represent the fastest-expanding category as hospital oxygen infrastructure hardens against supply chain disruption. Convection heating technology dominates installed base economics through superior thermal efficiency in moderate climates, while digital control systems are capturing margin pools via predictive frost detection and automated fan modulation.
EPA emissions standards and OSHA cryogenic handling regulations in the United States mandate vaporizer designs that eliminate combustion byproducts in enclosed industrial facilities, directly favoring air heated architectures over direct-fired alternatives. China's MEE enforces dual carbon compliance timelines that restrict new fuel-fired equipment approvals in coastal LNG receiving terminals, while the EU Green Deal and F-Gas Regulation phase down high-global-warming-potential refrigerants that historically competed with cryogenic air heated systems in certain cooling applications. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content requirements that could reshape competitive access across major LNG import markets.
Market Dynamics
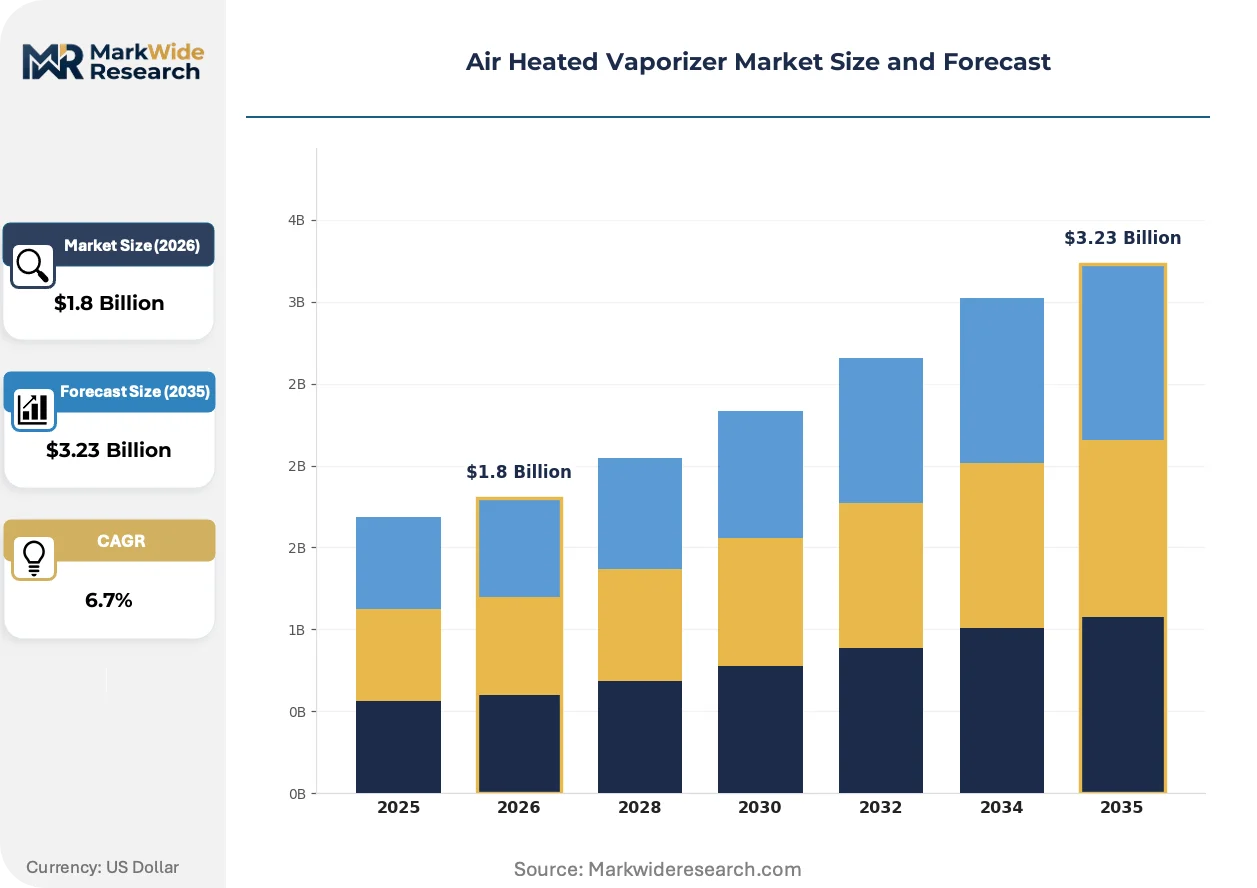
The transition from fuel-fired to zero-emission cryogenic infrastructure is compressing procurement timelines and rewiring supplier-customer relationships across LNG terminals and industrial gas networks. Ambient air heating architectures are capturing capital allocation previously directed toward combustion-based vaporization systems.
Growth Catalysts
- LNG export terminal construction:Cryogenic vaporization capacity additions along the US Gulf Coast petrochemical corridor are pulling aluminum fin-tube fabrication capacity into multi-year contracting arrangements.
- China's dual carbon goals:The MEE enforcement timelines restricting new fuel-fired equipment approvals in coastal receiving terminals are mandating ambient air heated alternatives for regasification infrastructure.
- Medical oxygen infrastructure hardening:Hospital supply chain resilience programs are expanding deployment of redundant cryogenic vaporization systems with passive ambient heating architectures.
Market Restraints
- Aluminum price volatility:Extended surface fin-tube bundles require substantial aluminum extrusion inputs, exposing fabricators to London Metal Exchange price swings that compress project margins.
- Climate dependency:Ambient air heated vaporizers suffer thermal efficiency degradation in extreme cold or high-humidity environments, limiting deployability in Nordic and tropical coastal zones without supplemental heating.
- Skilled welder scarcity:Cryogenic systems engineering talent pools are concentrating in North American and East Asian manufacturing clusters, constraining fabrication scale-up in emerging LNG import markets.
Strategic Opportunities
- Modular compact units:Precision aluminum fin-tube fabrication for containerized vaporizers is opening remote construction site and temporary industrial gas applications previously served by bulk tank vaporization.
- EU Green Deal alignment:The F-Gas Regulation phase-down of high-global-warming-potential refrigerants is eliminating competing cooling technologies in cold chain applications adjacent to cryogenic gas distribution.
- Predictive frost detection:Digital control systems integrating automated fan modulation are capturing service revenue pools through condition-based maintenance contracts.
Industry Challenges
- Cryogenic certification timelines:ASME Section VIII and PED compliance documentation for low-temperature pressure vessels extends project delivery schedules, constraining rapid-response contracting.
- Legacy system integration:Retrofitting ambient air heated vaporizers into existing fuel-fired infrastructure requires custom manifold reconfiguration and control system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Heated Vaporizer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Vaporizers, Desktop Vaporizers, Multi-Use Vaporizers, Medical Vaporizers Technology: Convection Heating, Conduction Heating, Hybrid Heating, Digital Control End User: Medical Facilities, Recreational Users, Retail Customers, Professionals Distribution Channel: Online Sales, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Chart Industries, Nikkiso Co., Ltd., Linde PLC, Air Liquide, Cryostar, INOX India Limited, Taylor-Wharton, Acme Cryo, Cryogas Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Heated Vaporizer Market Evolving Landscape
Digital twin architectures and predictive maintenance platforms are penetrating cryogenic equipment supply chains, compressing service intervals and shifting revenue models toward performance-based contracts. Fabricators are embedding sensor networks directly into fin-tube bundles.
Extended surface aluminum fin-tube technology is decomposing the traditional trade-off between thermal efficiency and footprint in ambient vaporizer design. LNG terminal operators in Qatar and Australia are specifying high-density fin configurations that reduce plot space requirements. This compression of physical infrastructure is decomposing the capital cost advantage historically held by fuel-fired vaporization systems.
The EPA emissions standards and OSHA cryogenic handling regulations in the United States are mandating combustion-free architectures in enclosed industrial facilities. This regulatory pressure is eliminating direct-fired vaporizer options from new construction specifications. Petrochemical processors in Texas and Louisiana are responding by standardizing on ambient air heated designs for nitrogen and oxygen supply systems.
Hospital procurement departments are consolidating oxygen infrastructure contracts under single-source agreements that bundle vaporization equipment with telemetry and remote monitoring services. Medical gas distributors are displacing transactional equipment sales with subscription-based uptime guarantees. This service unbundling is most visible in Germany and Japan, where healthcare system consolidation is concentrating buying power among regional hospital networks.
Air Heated Vaporizer Market Segmentation
Air heated vaporizer procurement channels diverge sharply by application criticality and regulatory oversight. Medical and industrial gas distributors route through certified supply chains, while construction and temporary deployment segments favor rental and direct procurement models.
Product Type:
Portable units flow through equipment rental networks and direct sales to construction contractors, while medical-grade systems anchor pharmacy and specialty distributor channels with full certification documentation.
- Portable Vaporizers:Containerized aluminum fin-tube systems deploy to remote construction sites and temporary industrial gas needs. Demand clusters along the US Gulf Coast petrochemical corridor where LNG export terminal construction requires mobile cryogenic capacity.
- Medical Vaporizers:Hospital-grade systems with redundant ambient heating architectures serve oxygen infrastructure hardening programs. German and Japanese hospital networks are consolidating procurement under subscription-based uptime guarantee contracts.
- Desktop Vaporizers:Fixed-installation units serve permanent industrial gas supply stations with moderate throughput requirements.
- Multi-Use Vaporizers:Modular platforms reconfigure between nitrogen, oxygen, and LNG service through manifold interchangeability.
Portable vaporizers dominate installed base. Medical vaporizers are where expansion concentrates.
Technology:
Cost tiers separate legacy convection systems from premium digital platforms, with frost detection and automated modulation commanding service-contract premiums.
- Convection Heating:Passive ambient air systems transfer thermal energy through extended surface fin-tube bundles without combustion or electric elements. This architecture captures capital allocation in moderate climates across US Gulf Coast and Chinese coastal terminals.
- Digital Control:Sensor-embedded fin-tube bundles enable predictive frost detection and automated fan modulation. Condition-based maintenance contracts are displacing transactional equipment sales in German healthcare networks.
- Conduction Heating:Direct contact heat transfer serves compact footprint requirements in space-constrained installations.
- Hybrid Heating:Combined ambient and supplemental heating extends deployability into extreme cold or high-humidity environments where pure convection degrades.
Convection heating anchors legacy installed base. Digital control platforms are climbing the fastest.
End User:
Volume concentration splits between high-throughput industrial terminals and distributed medical infrastructure, with procurement patterns diverging on certification requirements and service bundling.
- Medical Facilities:Hospital oxygen distribution networks require redundant cryogenic vaporization with passive ambient heating for supply chain resilience. China's dual carbon goals and EPA emissions standards are eliminating fuel-fired alternatives from new construction.
- Professionals:Industrial gas distributors and LNG terminal operators specify large-scale ambient vaporizer farms. Qatar and Australia terminal operators are compressing plot space through high-density fin configurations.
- Recreational Users:Niche segment with minimal relevance to cryogenic infrastructure applications.
- Retail Customers:Limited deployment in small-scale industrial gas cylinder filling stations.
Medical facilities anchor certification-intensive procurement. Professional industrial users drive volume scale.
Distribution Channel:
Customer type determines channel selection, with regulated medical infrastructure requiring documented supply chains and construction segments favoring speed and flexibility.
- Direct Sales:Large-scale LNG terminal and industrial gas network contracts route through manufacturer-direct relationships with multi-year fabrication commitments. Chart Industries and Linde PLC anchor this channel through integrated manufacturing and captive demand.
- Specialty Stores:Industrial gas equipment distributors serve mid-scale supply stations with certified vaporizer systems and installation support.
- Online Sales:Limited to standardized compact units and replacement components where certification documentation is pre-established.
- Pharmacies:Medical oxygen infrastructure in consolidated hospital networks, primarily in Germany and Japan where healthcare system concentration concentrates buying power.
Direct sales dominate large-project procurement. Specialty stores capture mid-market distributed demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Gulf Coast fabricators serving LNG export terminals, while Chinese coastal manufacturers absorb aluminum cost volatility through integrated supply chains. European medical gas distributors command service-contract premiums through consolidated hospital procurement.
United States
EPA emissions standards and OSHA cryogenic handling regulations mandate combustion-free vaporizer architectures in enclosed industrial facilities. The US Gulf Coast petrochemical corridor pulls aluminum fin-tube fabrication capacity into multi-year contracting arrangements for LNG export terminal construction.
China
Dual carbon goals and MEE enforcement timelines restrict new fuel-fired equipment approvals in coastal LNG receiving terminals. Yangtze River Delta fabricators scale precision aluminum extrusion capacity to serve regasification infrastructure substitution demand.
Germany
EU Green Deal alignment and F-Gas Regulation phase-down eliminate competing refrigerant technologies in adjacent cooling applications. Consolidated hospital networks in Bavaria and North Rhine-Westphalia bundle vaporization equipment with subscription-based uptime guarantees.
Japan
Hospital oxygen infrastructure hardening programs expand redundant cryogenic vaporization deployment. METI industrial gas safety standards favor passive ambient heating architectures in metropolitan medical supply networks across Kanto and Kansai regions.
Australia
High-density fin configurations reduce plot space requirements at Queensland and Western Australia LNG terminals. TGA medical device certification requirements channel hospital procurement through documented specialty distributor networks.
Air Heated Vaporizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated industrial gas conglomerates anchor the premium segment through captive demand and certification depth. Specialized aluminum fabricators occupy the mid-market through precision fin-tube manufacturing. Regional equipment assemblers compete on delivery speed for temporary deployment applications. Capacity expansion and strategic partnerships represent the dominant competitive moves across all tiers.
Among North American and European industrial gas conglomerates, Chart Industries and Linde PLC exemplify the integrated archetype through combined manufacturing and distribution control. Nikkiso Co., Ltd. occupies a specialist position within precision aluminum fabrication for compact modular configurations. These three entities represent distinct competitive vectors: scale-driven vertical integration, captive network demand, and precision manufacturing specialization.
| Leading Market Players |
|---|
| Chart Industries |
| Nikkiso Co., Ltd. |
| Linde PLC |
| Air Liquide |
| Cryostar |
| INOX India Limited |
| Taylor-Wharton |
| Acme Cryo |
| Cryogas Equipment |
| Others |
Value Network & Pricing Analysis
ASME Section VIII and PED certification requirements for cryogenic pressure vessels simultaneously gate supplier qualification and stratify price tiers across the Air Heated Vaporizer Market. Fabricators holding dual-certification command configured-to-order premiums while uncertified assemblers compete on standard unit spot pricing.
Pricing Analysis
The customization-premium spread separates configured-to-order ambient vaporizer farms for LNG terminals from standard portable units for construction rental fleets. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, aluminum grade specification, and telemetry integration. Cost compression in economy-tier portable units is intensifying because Chinese coastal fabricators absorb aluminum price volatility through integrated extrusion capacity. Industrial gas distributors demonstrate lowest price sensitivity due to captive demand and multi-year contracting, while construction contractors renting portable units exhibit highest sensitivity to daily rate fluctuations.
Supply Chain Analysis
Strategic aluminum stockpiling dominates inventory strategy for extended surface fin-tube fabricators exposed to London Metal Exchange volatility. Supply concentrates in the United States, China, and Germany where precision extrusion and cryogenic welding talent clusters. Raw material dependencies center on aluminum 6061-T6 extrusions, stainless steel 304L tubing, and brazing alloys. Single-source vulnerability runs through Yangtze River Delta aluminum processors serving global LNG terminal demand. Distribution runs through manufacturer-direct relationships for large projects and specialty industrial gas equipment distributors for mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-emission cryogenic infrastructure mandates are compressing procurement timelines and rewiring supplier-customer relationships across LNG terminals and industrial gas networks. China's MEE enforcement timelines and EPA emissions standards represent the regulatory inflection accelerating substitution of fuel-fired vaporizers.
For Market Incumbents: Shield market position by deepening backward integration into aluminum extrusion capacity and securing multi-year ASME certification maintenance contracts. The threat of modular compact unit specialists capturing remote construction site demand requires defensive capacity allocation toward containerized vaporizer platforms. Priority lever: captive control over precision fin-tube fabrication in Gulf Coast and Yangtze River Delta manufacturing clusters. For New Entrants and Emerging Players: Predictive frost detection and condition-based maintenance service layers represent the service-layer gap where integrated conglomerates under-serve mid-scale industrial gas distributors. The most penetrable white-space target lies in German and Japanese hospital networks consolidating procurement under subscription-based uptime guarantees. Go-to-market angle: digital control platform licensing bundled with remote monitoring telemetry rather than equipment-only sales. For Investors and Strategic Acquirers: China's dual carbon goals and EPA emissions standards reshapes the acquisition landscape toward certified cryogenic fabricators with established LNG terminal reference projects. Long-term viability across the analysis window favors specialists with precision aluminum fin-tube capabilities and documented regasification infrastructure deployments. Acquisition target archetype: mid-scale fabricators holding dual ASME-PED certification with underutilized capacity in coastal manufacturing zones. Signal to watch: carbon border adjustment mechanism implementation accelerating substitution demand in European LNG import markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of 6061-T6 fin-tube raw material insulates Chart Industries from LME price volatility. |
| Digital Control Platform Licensing | Predictive frost detection software subscriptions displace transactional equipment sales in German healthcare networks. |
| ASME Section VIII Certification Investment | Dual-certification fabricators capture LNG terminal procurement previously blocked by compliance documentation gaps. |
| Modular Compact Unit Capacity Expansion | Containerized vaporizer production opens remote construction site applications along US Gulf Coast petrochemical corridor. |
| Condition-Based Maintenance Service Contracts | Automated fan modulation telemetry generates recurring revenue from hospital oxygen infrastructure hardening programs. |
Research Methodology
Operator-level perspectives from LNG terminal project developers, industrial gas distribution procurement directors, cryogenic systems welding engineers, and hospital biomedical equipment managers anchored the qualitative base. Primary interview insights combined with secondary validation from customs trade data, ASME certification registries, EPA emissions compliance filings, and industrial gas equipment distributor catalogs. Bottom-up project pipeline tracking across US Gulf Coast and Chinese coastal regasification terminals triangulated with top-down aluminum extrusion capacity utilization analysis.
Sensitivity analysis tested forecast robustness against aluminum price volatility bands, certification timeline compression scenarios, and regulatory enforcement acceleration patterns across the projection horizon. Segmentation dimensions modeled include product type, heating technology architecture, end-user criticality tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, LNG export capacity addition schedules, and medical oxygen infrastructure hardening program deployment rates. Industry-specific inputs incorporated cryogenic pressure vessel order backlogs and hospital network consolidation patterns.
Underlying assumptions cover continued MEE dual carbon enforcement, EPA emissions standard maintenance, and aluminum supply chain stability, with deviation risk concentrated in tariff escalation affecting Yangtze River Delta fabrication exports. Forecasts reflect these conditions without explicit probability weighting. Revision becomes warranted when carbon border adjustment mechanism implementation crosses implementation thresholds in European LNG import markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Europe Medium Voltage Switchgear Market
Valves
Global Stainless Steel Control Valves Market
Valves
Pneumatic Needle Valves Market
Valves
North America Residential Ball Valves Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Europe Butterfly Valve Market
Valves
Portable Valve Actuator Market
Valves
Chemical Injection Skid Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Explosion Isolation Valves Market
Valves
Sanitary Valves Market
Valves
Valve Interlocks Market
Valves
Steam Trap Market
Valves
Middle East and Africa Machined Seals Market
Valves
Pipeline Strainers Market
Valves
Carbon Seal Rings Market