
 Emergency Shutdown Valves Market | 2026-2036
Emergency Shutdown Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Shutdown Valves Market Insights
Buyer consolidation among integrated supermajors and national oil companies is recalibrating procurement dynamics across the valve supply base. Emerson Electric leverages its integrated digital valve architecture to sustain long-term service contracts with concentrated upstream operators. Flowserve anchors its position through specialized severe-service engineering capabilities for high-pressure hydrocarbon environments. Baker Hughes competes by extending its portfolio beyond hardware into predictive diagnostics and lifecycle asset management.
Emergency shutdown valves are fail-safe flow isolation devices engineered to achieve SIL 3 safety integrity levels under IEC 61508, typically constructed with fire-safe sealing systems rated to API 6FA and actuated by spring-return pneumatic or hydraulic systems for millisecond closure times. Their primary purpose is to prevent catastrophic release of hazardous process fluids during overpressure, fire, or toxic leak events. Ball valves dominate high-cycle hydrocarbon applications where tight shutoff and quarter-turn speed are paramount, while gate valves occupy large-bore pipeline isolation roles where bi-directional sealing and low pressure drop govern selection. Stainless steel materials lead in corrosive sour gas service, though alloy specification intensity varies sharply across chemical versus oil and gas end uses.
The US Occupational Safety and Health Administration process safety management standard and EPA risk management program mandate documented emergency isolation capabilities at covered facilities, directly shaping valve specification and inspection protocols. API 6D pipeline valve standards and IEC 61511 functional safety frameworks further constrain product design and supplier qualification pathways across North American and European installations. Stakeholders must monitor evolving methane emission regulations and carbon border adjustment mechanisms, as these will increasingly tie valve procurement decisions to lifecycle emissions accounting and supplier ESG certification status.
Market Dynamics
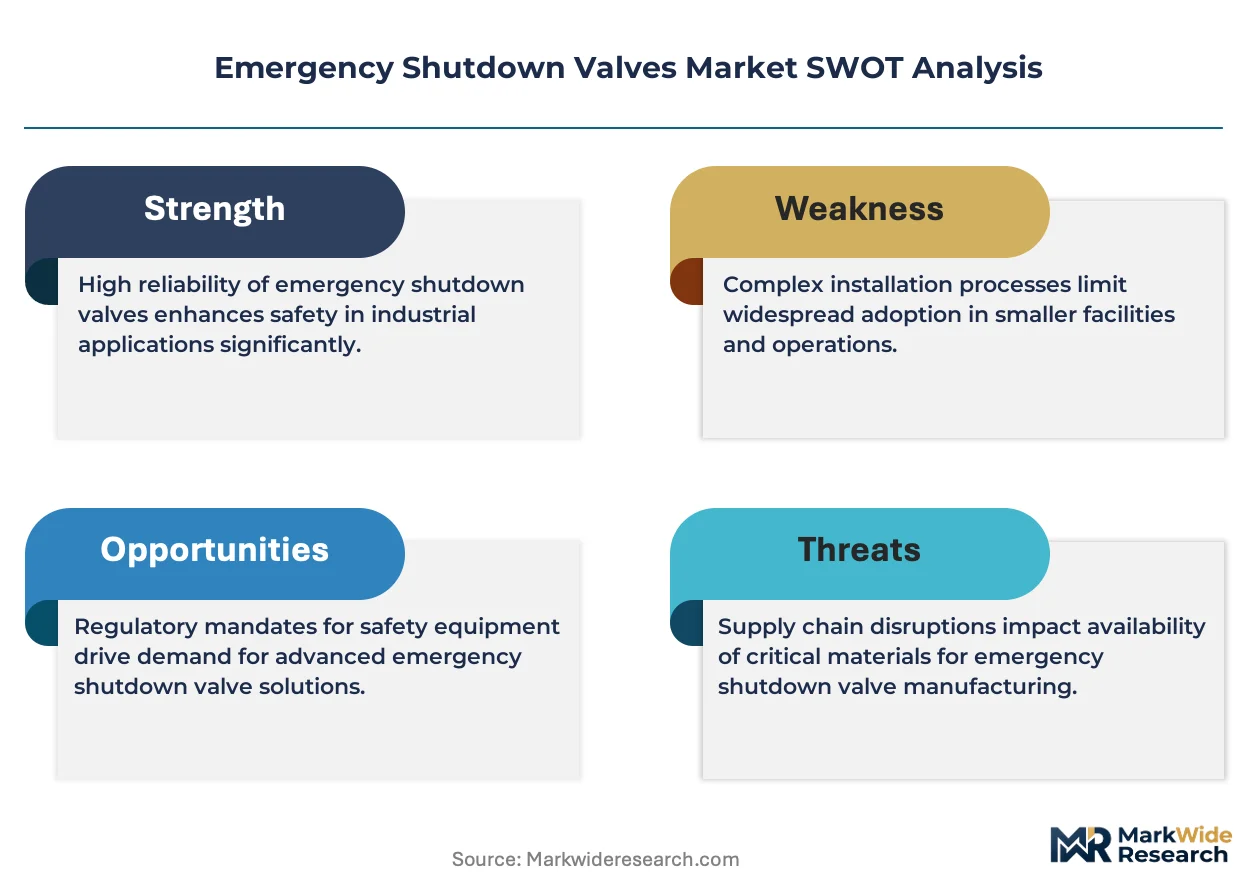
Upstream operator consolidation around certified suppliers capable of meeting IEC 61508 SIL 3 requirements is compressing the vendor base and elevating technical qualification barriers for new market entrants.
Growth Catalysts
- US Gulf Coast petrochemical corridor expansion:Refinery modernization and LNG export terminal buildouts are accelerating replacement cycles for legacy valve infrastructure across Texas and Louisiana processing facilities.
- OSHA process safety management mandates:Documented emergency isolation capabilities at covered facilities directly shape valve specification and inspection protocols, creating compliance-driven procurement.
- Fire-safe sealing systems rated to API 6FA:Tightening safety standards for hydrocarbon containment are pushing adoption of advanced metallurgy and actuator designs in high-pressure environments.
Market Restraints
- Alloy specification cost volatility:Nickel and chromium price swings directly impact stainless steel valve production economics, squeezing margins on sour gas service orders.
- Supplier concentration in severe-service engineering:Limited qualified vendors capable of high-pressure hydrocarbon valve fabrication create procurement bottlenecks for integrated supermajors.
- Extended IEC 61508 certification timelines:Functional safety assessment periods stretching 18-24 months delay product commercialization and lock out smaller competitors.
Strategic Opportunities
- Carbon border adjustment mechanism alignment:European valve procurement is increasingly tied to lifecycle emissions accounting and supplier ESG certification status, favoring low-carbon manufacturers.
- Predictive diagnostics convergence:Integration of edge computing with spring-return pneumatic actuators enables millisecond closure verification and condition-based maintenance contracts.
- Methane emission regulation tailwinds:EPA leak detection and repair mandates are expanding addressable demand for fail-safe isolation at compressor stations and storage facilities.
Industry Challenges
- SIL 3 functional safety engineering scarcity:Qualified professionals capable of IEC 61511 fault tree analysis command premium compensation, constraining vendor expansion.
- Legacy SCADA integration complexity:Digital valve architectures must interface with decades-old distributed control systems at brownfield refineries, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Shutdown Valves Market |
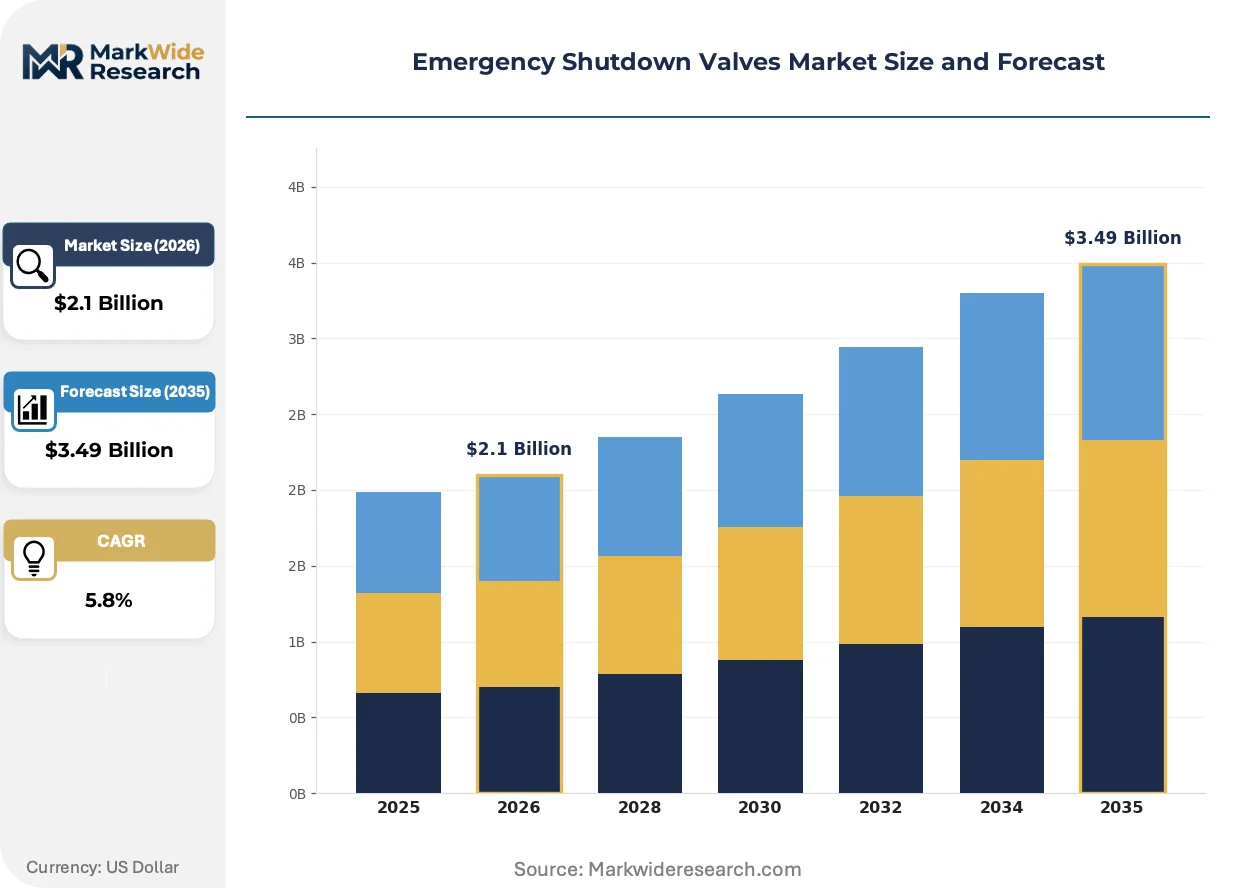
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Oil & Gas, Chemicals, Power Generation, Water Treatment Type: Ball Valves, Gate Valves, Butterfly Valves, Globe Valves Material: Stainless Steel, Cast Iron, Bronze, PVC Operation Mode: Manual, Pneumatic, Hydraulic, Electric |
| Companies Covered | Emerson Electric, Flowserve, Schneider Electric, IMI Critical Engineering, Velan Inc., Baker Hughes, Neles Corporation, ABB Ltd, KSB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Shutdown Valves Market Trends and Innovations
Digital valve architectures are absorbing diagnostic and control functions previously handled by separate instrumentation, collapsing the traditional hardware stack and reshaping supplier value capture models.
Smart positioners with embedded edge computing are absorbing vibration monitoring, stroke-time logging, and partial-stroke test execution directly into the valve assembly. Offshore platform operators in the North Sea are deploying these integrated units at replacement rates exceeding conventional pneumatic configurations. This consolidation is absorbing aftermarket service revenue from third-party instrumentation providers into valve OEM recurring contract streams.
REACH chemical substance restrictions and the EU F-Gas Regulation are phasing out certain hydraulic fluids and sealing compounds used in legacy actuator designs. European valve manufacturers are reformulating fire-safe sealing systems to maintain API 6FA ratings while eliminating restricted substances. The German chemical processing sector is experiencing the most acute compliance pressure, with facility operators accelerating specification updates to avoid supply discontinuity.
Supermajor procurement teams are unbundling valve hardware from lifecycle service agreements, creating separate competitive events for installation, commissioning, and predictive maintenance. This disintermediation is compressing margin capture for full-service suppliers while opening entry points for specialized service contractors. The pattern is most pronounced among US integrated operators consolidating spend through centralized engineering procurement centers.
Emergency Shutdown Valves Market Segmentation
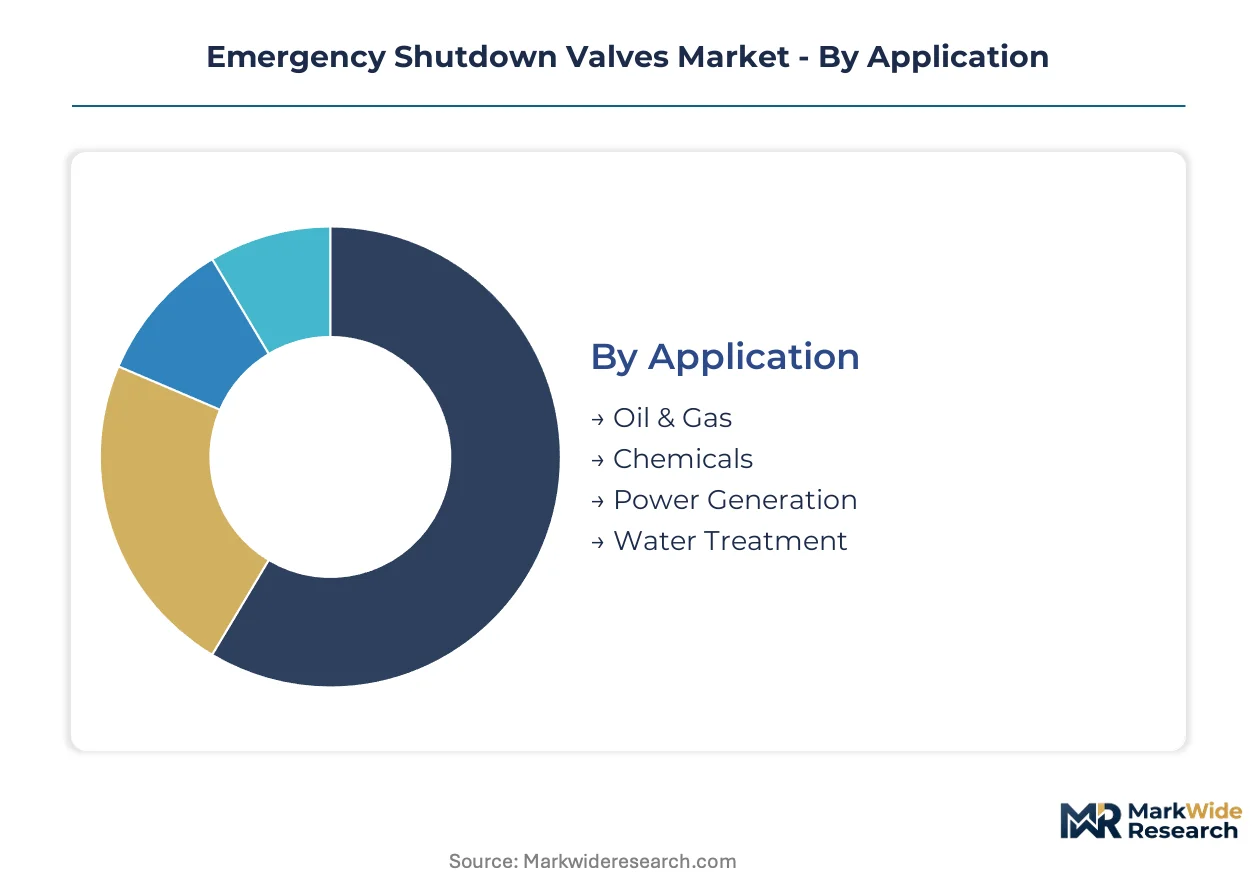
Emergency shutdown valve procurement stratifies sharply across application environments, with IEC 61508 SIL 3 certification requirements and fire-safe API 6FA ratings creating divergent specification intensity. Material selection and actuation mode further fragment the addressable market, as sour gas service, subsea installations, and brownfield retrofit contexts impose distinct engineering constraints on supplier qualification pathways.
Application:
Capital intensity peaks in hydrocarbon processing environments where containment failure carries catastrophic liability exposure and regulatory enforcement carries criminal penalties.
- Oil & Gas:Upstream production facilities, LNG export terminals, and refinery modernization programs across the US Gulf Coast concentrate demand for spring-return pneumatic actuation and millisecond closure verification. OSHA process safety management mandates and EPA risk management program requirements enforce documented emergency isolation capabilities at covered facilities, compressing procurement around certified suppliers.
- Chemicals:REACH chemical substance restrictions and the EU F-Gas Regulation are forcing reformulation of fire-safe sealing systems and hydraulic fluids in German chemical processing clusters. Facility operators accelerate specification updates to avoid supply discontinuity while maintaining API 6FA ratings.
- Power Generation:Combined-cycle gas turbine installations require fail-safe isolation at fuel gas skids and steam headers.
- Water Treatment:Municipal and industrial wastewater facilities deploy lower-specification actuation for non-hazardous fluid containment.
Oil & Gas absorbs the bulk of installed capacity; Chemicals is expanding most quickly as European regulatory pressure accelerates replacement cycles.
Type:
Valve architecture selection pivots on cycle frequency, bore diameter, and bidirectional sealing requirements across pipeline versus process unit applications.
- Ball Valves:Quarter-turn closure geometry achieves tight shutoff in high-cycle hydrocarbon service. North Sea offshore platform operators deploy smart positioners with embedded edge computing at replacement rates exceeding conventional pneumatic configurations, absorbing diagnostic functions into OEM recurring contract streams.
- Gate Valves:Large-bore pipeline isolation roles favor bi-directional sealing and low pressure drop characteristics. US interstate natural gas transmission corridors and LNG export terminal buildouts in Texas and Louisiana drive specification for through-conduit designs rated to API 6D.
- Butterfly Valves:Compact face-to-face dimensions suit space-constrained offshore module installations.
- Globe Valves:Throttling capability and precise flow modulation govern selection in chemical process control loops.
Ball Valves capture the largest share of replacement expenditure; Gate Valves are gaining share fastest as LNG infrastructure buildouts accelerate.
Material:
Alloy specification intensity varies sharply with process fluid corrosivity and sour gas hydrogen sulfide concentration.
- Stainless Steel:Austenitic and duplex grades dominate corrosive sour gas service where chloride stress cracking resistance governs specification. Nickel and chromium price volatility directly impacts production economics, squeezing margins on high-alloy orders for upstream operators.
- Cast Iron:Lower-pressure water treatment and general industrial applications favor cost-efficient ferrous metallurgy with epoxy coating systems.
- Bronze:Seawater and marine environments specify copper-nickel alloys for galvanic corrosion resistance.
- PVC:Corrosive chemical handling in secondary containment and utility services deploys thermoplastic construction for cost-sensitive applications.
Stainless Steel commands the highest unit values; Cast Iron ships the greatest unit volumes across non-critical installations.
Operation Mode:
Actuation technology selection determines response latency, power availability, and functional safety architecture.
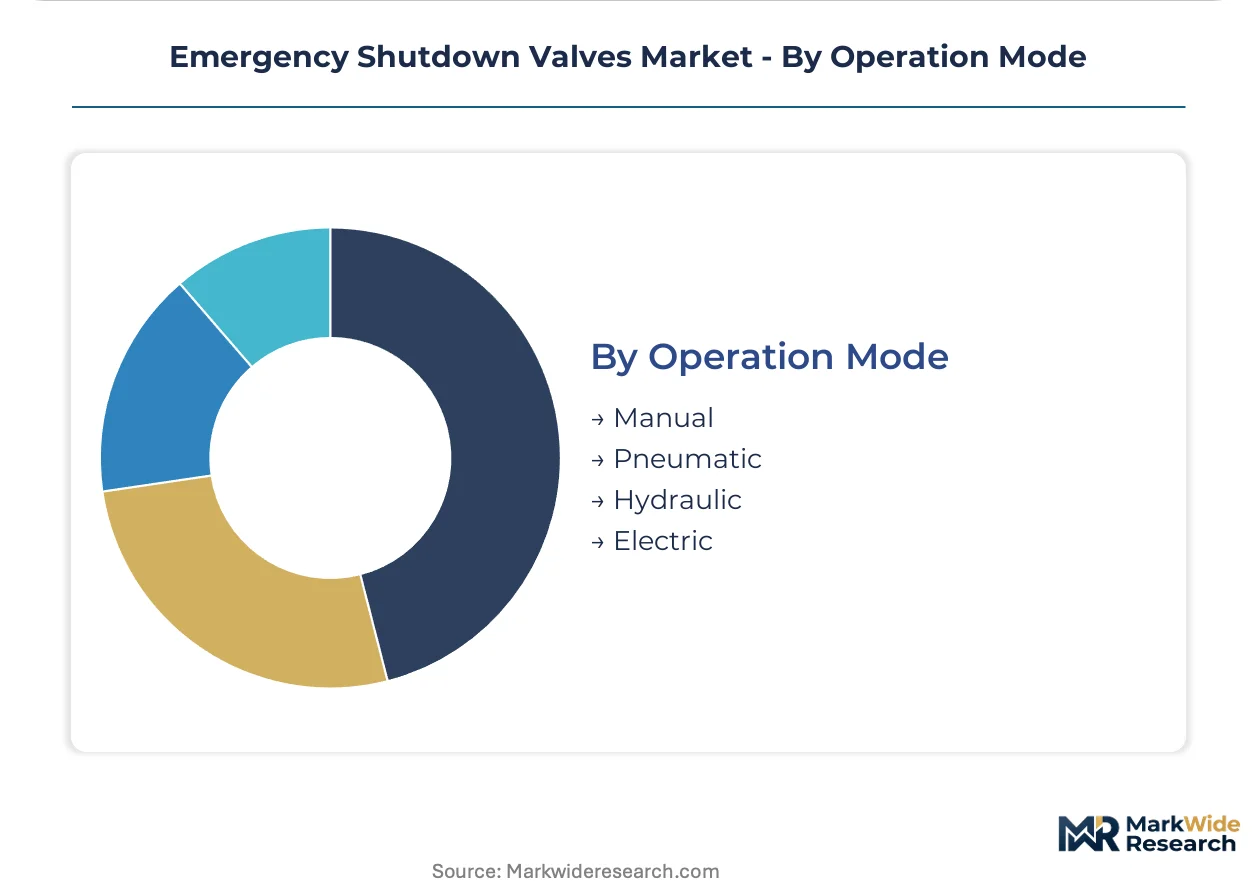
- Pneumatic:Spring-return configurations achieve millisecond closure times required for SIL 3 safety integrity. Integrated digital architectures with embedded stroke-time logging and partial-stroke test execution are displacing separate instrumentation stacks at US Gulf Coast petrochemical facilities.
- Hydraulic:High-force actuation for large-bore subsea and high-pressure onshore pipeline applications carries fluid reformulation costs under REACH and EU F-Gas restrictions.
- Electric:Battery-backed motor operators suit remote installations without instrument air infrastructure.
- Manual:Backup and maintenance isolation roles persist in low-criticality utility services.
Pneumatic actuation retains dominant installed base; Electric systems are climbing the fastest as digital integration and remote monitoring capabilities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators concentrate procurement spending in coastal industrial corridors where refinery modernization and LNG export infrastructure create synchronized replacement demand for certified safety systems.
United States
OSHA process safety management mandates and EPA risk management program requirements enforce documented emergency isolation capabilities at covered facilities across Texas and Louisiana. The Gulf Coast petrochemical corridor accelerates valve replacement cycles as integrated supermajors consolidate procurement through centralized engineering centers. Houston anchors supplier qualification activity for spring-return pneumatic systems rated to SIL 3.
Germany
REACH chemical substance restrictions and the EU F-Gas Regulation force reformulation of fire-safe sealing systems and hydraulic fluids in chemical processing clusters. The country's national chemical regulator pressures facility operators to maintain API 6FA ratings while eliminating restricted substances. The Rhine-Ruhr industrial region experiences acute compliance pressure as operators accelerate specification updates to avoid supply discontinuity.
China
Dual carbon goals and tightening industrial safety standards elevate demand for fail-safe isolation systems at coal-to-chemical complexes and LNG import terminals. The national standards administration enforces GB standards alignment with IEC 61508 functional safety frameworks for critical process equipment. The Yangtze River Delta concentrates procurement activity for stainless steel valve specifications in sour gas service.
Saudi Arabia
National oil company procurement consolidation around certified suppliers compresses the vendor base for high-pressure hydrocarbon valve fabrication. The national industrial regulator mandates SIL 3 safety integrity levels for upstream production facilities under expanding domestic content requirements. The Eastern Province anchors demand for severe-service engineering capabilities at gas processing and LNG export infrastructure.
Norway
North Sea offshore platform operators deploy smart positioners with embedded edge computing at replacement rates exceeding conventional pneumatic configurations. The national petroleum regulator enforces functional safety assessments stretching 18-24 months for subsea valve commercialization. Stavanger concentrates digital valve architecture adoption as integrated diagnostics absorb aftermarket service revenue into OEM recurring contract streams.
Emergency Shutdown Valves Market Competitive Landscape
United States producers anchor one tier of the supply base; European specialists hold certification-intensive positions in chemical and offshore applications. The vendor base compresses around suppliers capable of meeting IEC 61508 SIL 3 requirements, with integrated digital architectures displacing conventional hardware stacks. Three archetypes dominate: full-service system integrators, severe-service engineering specialists, and predictive diagnostics platform providers. Competitive moves concentrate on lifecycle service agreement unbundling and edge computing integration for condition-based maintenance contracts.
Among diversified industrial conglomerates, Emerson Electric and Schneider Electric occupy positions exemplifying integrated digital valve architectures that collapse traditional instrumentation stacks. Flowserve anchors the severe-service engineering tier for high-pressure hydrocarbon environments. Baker Hughes sits within the predictive diagnostics convergence, representing the extension beyond hardware into lifecycle asset management platforms.
| Leading Market Players |
|---|
| Emerson Electric |
| Flowserve |
| Schneider Electric |
| IMI Critical Engineering |
| Velan Inc. |
| Baker Hughes |
| Neles Corporation |
| ABB Ltd |
| KSB |
| Others |
Pricing and Supply Chain Analysis
EPA methane emission mandates and carbon border adjustment mechanisms gate both qualified supply and premium-tier pricing access, as European and US buyers now require documented lifecycle emissions accounting and supplier ESG certification status before contract award.
Pricing Analysis
Volume concentrates in standard-grade pneumatic actuation for brownfield refinery replacement, while margin pools in SIL 3-certified digital architectures with embedded diagnostics. Three-tier pricing structure across premium certified, standard compliant, and economy non-critical tiers separates IEC 61508 SIL 3 validated systems from general industrial valves. Cost compression in stainless steel alloy specifications is intensifying because nickel and chromium price volatility squeezes sour gas service orders. National oil companies show least price sensitivity given liability exposure, while municipal water treatment operators exhibit highest sensitivity to unit cost.
Supply Chain Analysis
Dual-sourcing requirements from integrated supermajors mandate multi-supplier qualification for critical safety systems, preventing single-vendor lock-in at LNG export terminals. Manufacturing concentrates in the United States, Germany, and China, with severe-service engineering capabilities anchored in Houston and the Rhine-Ruhr corridor. Raw material dependencies draw from nickel ore processing, chromium alloying feedstocks, and specialized fire-safe sealing compounds. Single-source vulnerability persists in IEC 61508 certification testing capacity, where qualified assessors stretch lead times. Distribution runs through OEM direct sales for large projects and authorized distributors for maintenance spares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where IEC 61508 SIL 3 certification timelines stretching 18-24 months create a barrier-to-entry moat for incumbent players with established assessment relationships.
For Market Incumbents: Extend lifecycle service agreement coverage to capture predictive maintenance revenue streams as supermajors unbundle hardware from commissioning contracts. Threat from specialized diagnostics platform providers intensifies as edge computing displaces separate instrumentation stacks. Certification investment in REACH-compliant hydraulic fluid formulations secures European chemical processing share against regulatory discontinuity. For New Entrants and Emerging Players: EPA methane leak detection mandates in the United States open a window for electric actuation specialists targeting compressor station retrofits without instrument air infrastructure. White-space concentrates in remote monitoring services for brownfield distributed control system integration, where legacy SCADA complexity delays incumbent deployment. Go-to-market through specialized service contractors bypasses consolidated procurement channels at centralized engineering centers. For Investors and Strategic Acquirers: Supermajor procurement consolidation around certified suppliers is the leading indicator that vendor base compression will accelerate acquisition premiums for SIL 3-capable engineering teams. Long-term viability favors platforms with recurring diagnostic revenue over pure hardware manufacturers. Acquisition target archetype: mid-cap severe-service specialists with IEC 61511 fault tree analysis capabilities. Signal to watch: carbon border adjustment mechanism enforcement expanding beyond pilot sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel and chromium sourcing insulates margins from commodity volatility in sour gas specifications. |
| Digital Valve Architecture Launch | Embedded edge computing at North Sea platforms absorbs aftermarket service revenue into OEM recurring streams. |
| REACH-Compliant Fluid Reformulation | Fire-safe sealing systems maintaining API 6FA ratings secure German chemical processing procurement continuity. |
| Long-Term Service Agreement Expansion | Predictive maintenance contracts with US Gulf Coast supermajors lock out third-party instrumentation providers. |
| Certification Capacity Partnership | Joint IEC 61508 assessment facilities reduce 18-24 month commercialization timelines for subsea valve launches. |
Research Methodology
Trade flow databases, API standards documentation, and SEC 10-K filings from publicly listed valve manufacturers formed the secondary backbone of this analysis. Primary interviews with maintenance directors at US Gulf Coast refineries, procurement leads at national oil companies, aftermarket service heads at OEMs, and plant engineers at German chemical processing clusters combined with secondary validation. Bottom-up and top-down triangulation cross-checked unit shipment estimates against capital expenditure disclosures at LNG export terminal projects.
Bottom-up modeling tracked valve replacement cycles across application segments while top-down analysis validated aggregate spending against petrochemical corridor investment announcements. Segmentation dimensions included actuation mode, material specification intensity, safety integrity level tier, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating project pipeline visibility and brownfield modernization schedules. Forecast inputs captured OSHA enforcement intensity and EU F-Gas Regulation phase-out timelines.
The model assumes a particular technology adoption path; alternative pathways for electric actuation with battery backup would alter the outlook if instrument air infrastructure investment stalls. Forecasts reflect assumptions about certification timeline compression and supermajor procurement consolidation velocity. Deviation in nickel price volatility or IEC 61508 assessor capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Explosion Vents Market
Valves
US Water & Wastewater Valves Market
Valves
Three Way Ball Valve Market
Valves
Air Heated Vaporizer Market
Valves
Hybrid Valve Market
Valves
Butterfly Valves Market
Valves
Water Draw Off Valves Market
Valves
Valve Grinder Market
Valves
Directional Control Valves Market
Valves
Wind Energy Fasteners Market
Valves
Gate Impellers Market
Valves
Middle East and Africa Machined Seals Market
Valves
Refrigeration Valves Market
Valves
Actuators and Valves Market
Valves
Rupture Discs Market
Valves
Fluid Power Cylinder Market