
 Electro Pneumatic Positioner Market | 2026-2036
Electro Pneumatic Positioner Market Size, Share, and Industry Trends Forecast 2026-2036
Electro Pneumatic Positioner Market Analysis
Aluminum housing alloys are restructuring cost-performance trade-offs across mid-range electro pneumatic positioner portfolios. Emerson Electric Co. leverages captive sensor manufacturing to tighten calibration tolerances in digital product lines. Siemens AG anchors European demand through integrated distributed control system compatibility. Yokogawa Electric Corporation specializes in explosion-proof certifications for hazardous environment deployments.
An electro pneumatic positioner converts an electrical control signal into proportional pneumatic pressure to drive valve actuators, typically operating on input ranges such as 4-20 mA or 0-10 V with air supply pressures of 20-100 psi. The device ensures precise throttling control in continuous process loops across refineries, chemical plants, and power stations. Digital and smart technology segments now capture the dominant margin pools as diagnostics-enabled positioners command premium pricing over analog alternatives. Rotary positioners retain structural importance in butterfly and ball valve applications, while linear variants dominate globe and gate valve installations in oil and gas upstream operations.
CE marking under the EU Machinery Directive and ATEX standards govern market access across European process industries, compelling positioner redesigns for intrinsic safety compliance. The EPA's methane emissions rules for oil and gas facilities in the United States are elevating demand for high-precision valve control to minimize fugitive releases. ISA standards and IEC 61508 functional safety specifications further constrain product architectures in safety instrumented systems. Stakeholders must weigh smart positioner upgrade cycles against extended analog equipment lifecycles when allocating capital across brownfield automation portfolios.
Market Dynamics
Smart positioner architectures are absorbing diagnostic and communication capabilities that previously required separate field instruments, collapsing the traditional three-device stack into single-unit deployments across process industries.
Growth Catalysts
- EPA Methane Rules:Fugitive emission mandates for oil and gas facilities elevate precision valve control requirements, forcing upgrades from analog to digital positioner architectures.
- Water Treatment Modernization:Utilities deploying advanced automation systems specify electro pneumatic positioners for remote valve actuation in distributed treatment networks.
- ATEX Intrinsic Safety:Hazardous environment certifications expand addressable market scope for explosion-proof positioner variants in chemical processing clusters.
Market Restraints
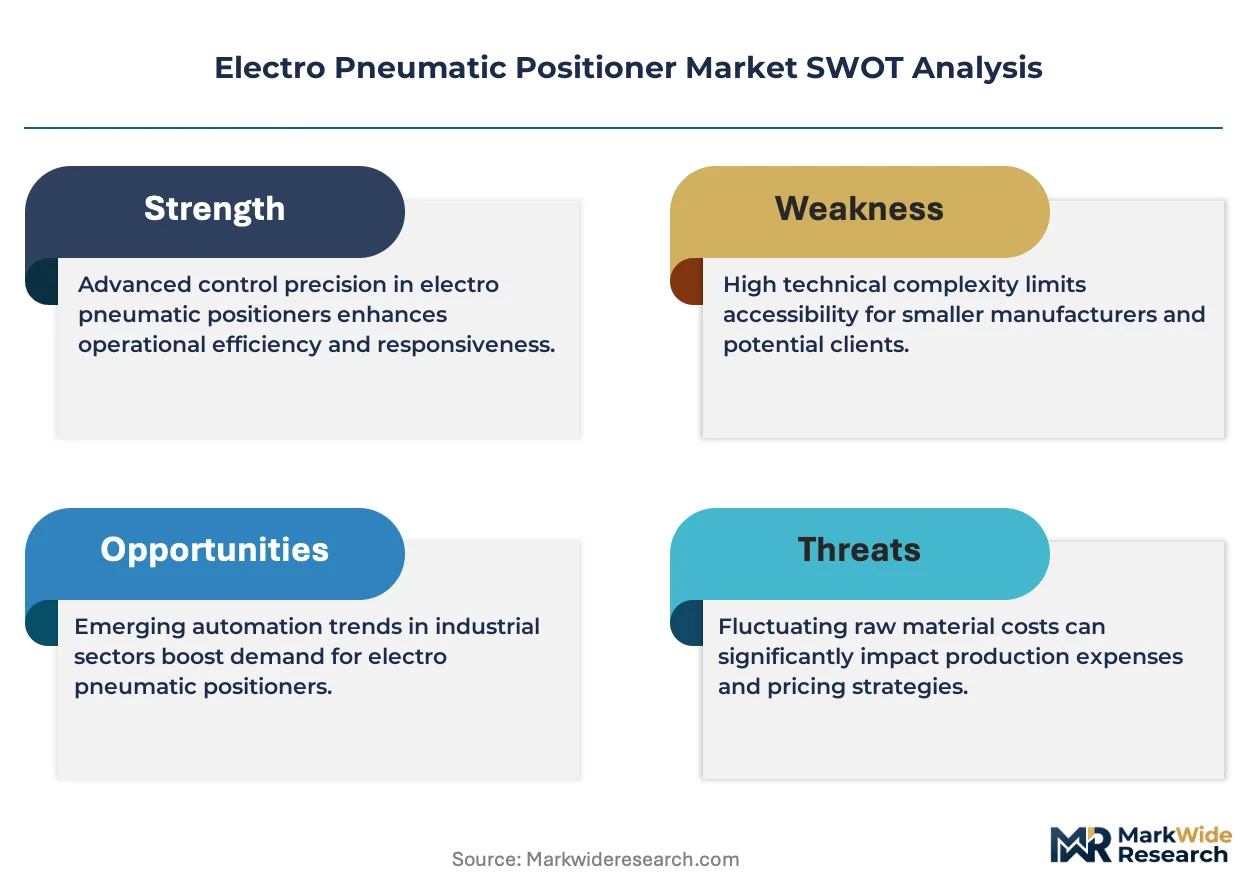
- Stainless Steel Input Volatility:Housing and enclosure material costs fluctuate with nickel pricing, compressing margin stability for mid-range product portfolios.
- Sensor Supply Concentration:Piezoelectric pressure sensor fabrication concentrates in East Asian foundries, creating single-source vulnerability for calibration-critical components.
- Analog Lifecycle Extension:Brownfield facilities defer smart upgrades, elongating replacement cycles and capping near-term volume expansion in mature industrial bases.
Strategic Opportunities
- India Process Automation:PLI scheme incentives for manufacturing automation create fresh demand for cost-optimized positioner specifications in petrochemical expansions.
- Hydrogen Infrastructure:High-pressure valve control requirements in emerging hydrogen transport networks favor specialized positioner designs with enhanced sealing specifications.
- IIoT Protocol Convergence:Integration of HART-IP and OPC UA communication stacks enables predictive maintenance service models that capture recurring revenue streams.
Industry Challenges
- Pneumatic Technician Scarcity:Compressed air system expertise ages out of the workforce faster than digital-automation training programs replenish qualified field service capacity.
- SIL Certification Timelines:IEC 61508 functional safety validation extends product development cycles, delaying revenue recognition for safety-instrumented system variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro Pneumatic Positioner Market |
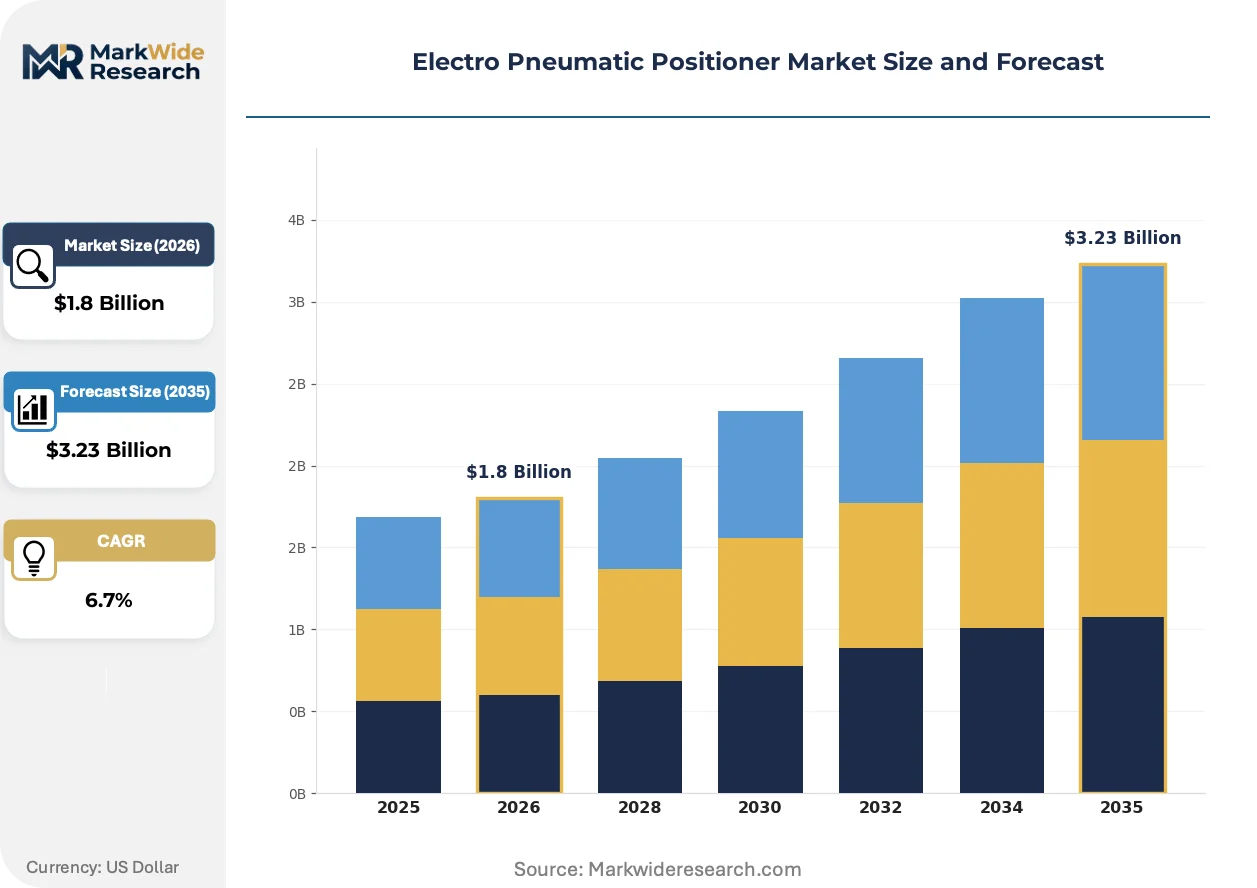
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Linear, Rotary Application: Process Control, Packaging, Material Handling, Aerospace End User: Oil & Gas, Power Generation, Water Treatment, Manufacturing Technology: Analog, Digital, Smart, Wireless |
| Companies Covered | Emerson Electric Co., Siemens AG, ABB Ltd., Flowserve Corporation, Schneider Electric SE, Honeywell International Inc., Yokogawa Electric Corporation, Festo SE & Co. KG, Rotork plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro Pneumatic Positioner Market Emerging Trajectories
Positioner technology is converging with edge computing and wireless telemetry, transforming standalone actuation devices into data-generating nodes within plant-wide digital twins.
Diagnostic-enabled smart positioners are absorbing vibration sensing, stroke-time analytics, and valve signature capture that once demanded separate monitoring hardware. Refinery operators deploy these consolidated units to reduce field device counts and wiring infrastructure. The technology is absorbing margin from traditional instrument suppliers while compressing commissioning timelines for greenfield projects.
REACH substance restrictions on perfluorinated compounds are forcing seal material redesigns for pneumatic positioner diaphragms and gaskets. Manufacturers reformulate elastomer specifications to maintain chemical compatibility without restricted substances. European process OEMs face compressed product recertification schedules to maintain CE marking compliance under evolving chemical safety frameworks.
Asset owners now specify positioner procurement through integrated automation framework agreements rather than standalone valve-actuator purchases. System integrators bundle positioner selection into DCS vendor relationships, displacing traditional distribution channels. This concentration is most visible in German chemical clusters where Siemens and Emerson anchor multi-year plant automation contracts.
Electro Pneumatic Positioner Market Segmentation
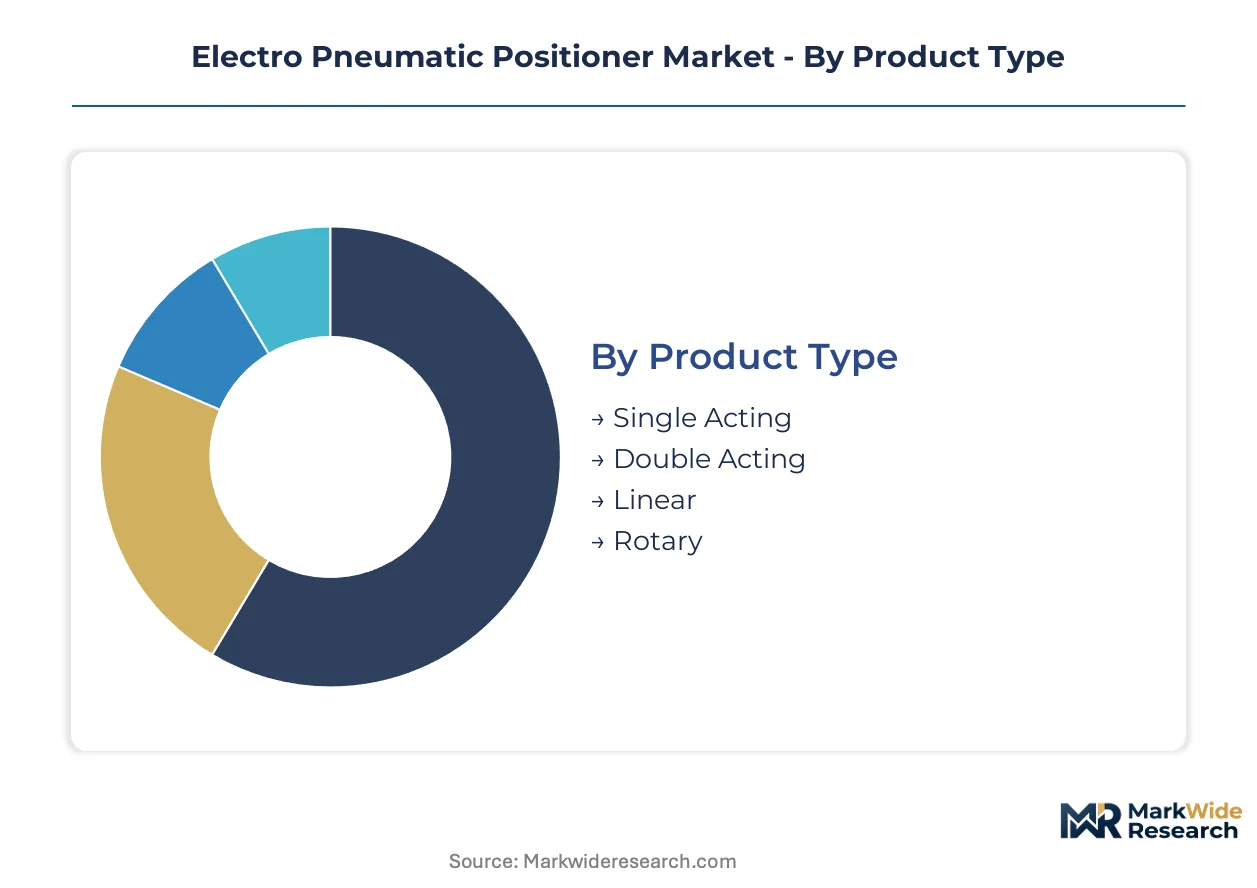
Electro pneumatic positioner procurement patterns diverge sharply across technical specifications and operational environments. Understanding these segment boundaries clarifies where premium pricing commands justify diagnostic capabilities versus where cost-optimized analog units retain viability.
Product Type:
Customization intensity varies from standardized rotary units for butterfly valve retrofit programs to engineered linear configurations for high-pressure steam applications.
- Single Acting:Spring-return actuation architecture suits fail-safe requirements in pneumatic systems where air supply interruption demands automatic valve positioning. Demand clusters in chemical processing facilities across Germany's Ruhr industrial cluster, driven by ATEX intrinsic safety mandates for hazardous atmosphere operations.
- Double Acting:Dual-pressure operation delivers higher torque output for heavy-duty valve automation without spring limitations. Oil and gas upstream operators in the Permian Basin specify these units for high-cycle wellhead choke valve control under EPA methane emission compliance pressure.
- Linear:Rack-and-pinion or scotch-yoke mechanisms translate pneumatic pressure into straight-line stem movement for globe and gate valve geometries.
- Rotary:Quarter-turn actuation dominates butterfly and ball valve installations where 90-degree rotation achieves full flow modulation.
Leading the category by volume: Rotary. Growing fastest: Smart-enabled Double Acting variants with integrated position feedback.
Application:
Margin capture potential escalates from commodity packaging automation to safety-critical process control loops where SIL certification validates functional integrity.
- Process Control:Continuous throttling applications in refining and petrochemical units demand sub-1% positioning accuracy for temperature and pressure cascade loops. Refinery operators in Rotterdam's port complex prioritize HART-IP enabled units for predictive maintenance integration.
- Material Handling:Conveyor diverter and sorting system actuation requires rapid stroke response rather than precision holding. Warehouse automation deployments in India's NCR manufacturing belt favor cost-optimized pneumatic positioning for package routing infrastructure.
- Packaging:Fill-level and sealing operations in food and beverage production lines specify washdown-compatible housing materials.
- Aerospace:Fuel system and environmental control valve actuation in aircraft assembly demands extreme temperature range specifications and traceable calibration certificates.
Process Control commands the dominant revenue share. Aerospace applications exhibit the steepest expansion trajectory as electric aircraft programs multiply valve control point counts.
End User:
Capital expenditure cycles and regulatory exposure create distinct procurement behaviors across industrial verticals.
- Oil & Gas:Upstream production, midstream transport, and downstream refining operations constitute the most specification-intensive demand pool. US Gulf Coast facilities face accelerated replacement timelines under EPA methane monitoring rules.
- Water Treatment:Municipal and industrial wastewater facilities deploy positioners for remote valve actuation in distributed collection networks. German utilities modernizing Rhine basin treatment plants specify smart positioners for SCADA integration.
- Power Generation:Combined cycle turbine valve control and emissions scrubber damper positioning require high-availability actuation.
- Manufacturing:General industrial automation spans automotive assembly, semiconductor fabrication, and pharmaceutical batch processing with varied precision requirements.
Oil & Gas anchors category value. Water Treatment is gaining share fastest as infrastructure stimulus programs accelerate automation retrofits.
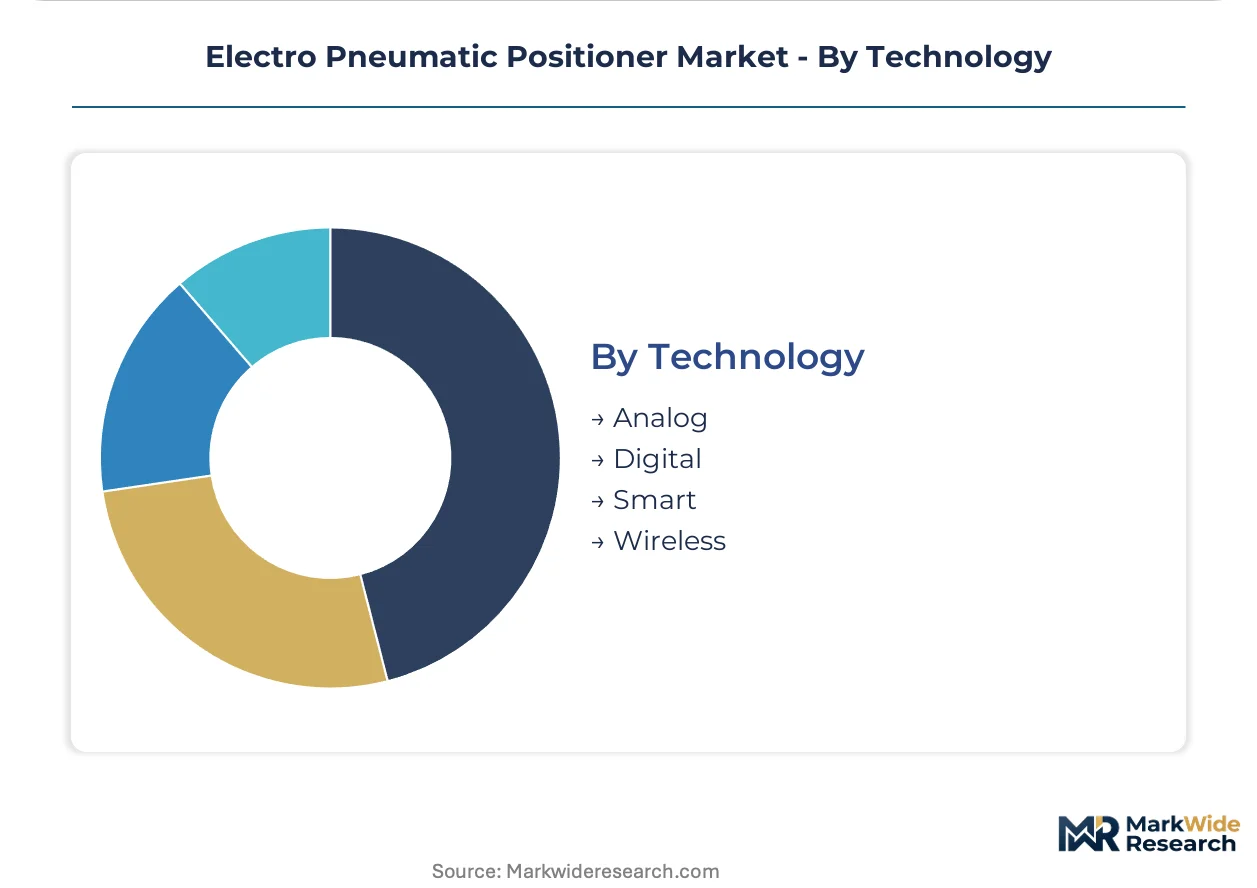
Technology:
Architecture migration from pneumatic-pneumatic to microprocessor-based intelligence restructures competitive positioning and service revenue models.
- Smart:Embedded diagnostics, self-calibration routines, and digital valve signature capture consolidate previously separate instrument functions. Siemens and Emerson anchor European demand through DCS-native integration protocols.
- Digital:Microprocessor-based positioning with LCD local interface and basic communication capabilities occupies the mid-market transition zone.
- Wireless:ISA100 or WirelessHART enabled units eliminate cabling infrastructure in remote tank farm and pipeline valve automation. North Dakota Bakken field operators deploy these for well pad isolation valve monitoring.
- Analog:Pneumatic-pnechanical positioning without electronic intelligence persists in budget-constrained brownfield maintenance.
Smart technology leads by installed value. Wireless variants are climbing the fastest as IIoT architecture investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electro pneumatic positioners concentrates in industrial automation clusters where process industries maintain dense valve control infrastructure. Germany anchors European procurement through its chemical and automotive manufacturing base. The United States drives North American volume via oil and gas methane compliance mandates.
United States
EPA methane emission rules for oil and gas facilities force digital positioner upgrades across Permian Basin wellheads and Gulf Coast refineries. The Infrastructure Investment and Jobs Act channels funding toward water treatment automation in municipal systems. Houston's petrochemical corridor specifies smart positioners with HART-IP integration for predictive maintenance deployment.
Germany
ATEX intrinsic safety certifications govern hazardous environment deployments across the Ruhr industrial cluster's chemical processing facilities. The EU Machinery Directive and REACH substance restrictions compel seal material redesigns for CE marking compliance. BASF and Bayer anchor demand in Ludwigshafen's chemical park through integrated DCS framework agreements with Siemens.
China
Dual carbon goals accelerate refinery automation upgrades in Shandong and Jiangsu provinces to minimize fugitive emissions. GB standards for industrial valve control align with IEC specifications for functional safety in petrochemical expansions. Sinopec's Zhenhai complex deploys smart positioners for hydrogen infrastructure pilot projects in the Yangtze River Delta.
India
PLI scheme incentives for manufacturing automation create fresh demand in Gujarat's petrochemical expansions and Maharashtra's process industries. BIS certification requirements for industrial equipment constrain import timelines for European positioner suppliers. Reliance Industries' Jamnagar complex anchors high-volume procurement for refinery digitization programs.
Japan
METI's industrial decarbonization roadmap elevates precision valve control requirements in Kansai region chemical complexes. JIS standards for process instrumentation align with IEC 61508 functional safety specifications for safety instrumented systems. Yokogawa Electric anchors domestic supply chains through captive sensor manufacturing in Tokyo's automation corridor.
Electro Pneumatic Positioner Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated automation vendors capturing premium process control accounts while component suppliers serve retrofit maintenance channels. The vendor base organizes around three strategic archetypes: DCS-native suppliers with captive positioner lines, standalone valve automation specialists, and pneumatic component diversifiers extending into smart actuation. Consolidation pressure intensifies as asset owners bundle procurement through multi-year plant automation contracts. Geographic expansion and technology licensing represent the dominant competitive vectors for mid-scale players seeking DCS integration partnerships.
Within the integrated automation tier, Emerson Electric Co., Siemens AG, and Yokogawa Electric Corporation exemplify divergent geographic anchoring strategies. Emerson represents North American DCS-native positioning through captive sensor manufacturing capabilities. Siemens occupies the European premium tier through distributed control system compatibility dominance. Yokogawa anchors Asia-Pacific hazardous environment specialization through explosion-proof certification expertise. Each exemplifies how regional industrial automation clusters cultivate distinct competitive positioning around regulatory compliance and system integration depth.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| ABB Ltd. |
| Flowserve Corporation |
| Schneider Electric SE |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| Festo SE & Co. KG |
| Rotork plc |
| Others |
Supply Flow & Price Mechanics
EPA methane emission mandates for oil and gas facilities are forcing specification upgrades from analog to smart positioner architectures, compelling suppliers to absorb sensor integration costs while maintaining price accessibility for budget-constrained brownfield operators. This demand-side pressure stratifies procurement across premium diagnostic-enabled units and cost-optimized legacy replacements.
Pricing Analysis
Volume concentrates in mid-range digital positioners while margin pools accrue to smart-enabled variants with embedded diagnostics and HART-IP communication stacks. Pricing stratifies across premium SIL-certified safety instrumented systems, standard ATEX-compliant hazardous environment units, and economy-grade analog replacements for maintenance events. Cost compression in the economy tier is intensifying because aluminum housing alloys are displacing stainless steel enclosures without sacrificing IP ratings. Municipal water utilities exhibit the highest price sensitivity due to public procurement constraints, whereas German chemical OEMs prioritize DCS-native integration over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries fabricating piezoelectric pressure sensors for calibration-critical digital positioner lines. Component sourcing draws from Germany for precision pneumatic valves, Japan for explosion-proof housing castings, and China for aluminum enclosure machining. Supply chain risk centers on nickel price volatility affecting stainless steel input costs for corrosion-resistant variants. Distribution runs through system integrators bundling positioner selection into multi-year DCS framework agreements, displacing traditional valve-automation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart positioner architectures are displacing analog equipment across process industries, with diagnostic-enabled units absorbing functions previously requiring separate field instruments. This technology transition compresses replacement cycles while elevating certification and integration requirements.
For Market Incumbents: Cement DCS-native protocol dominance by deepening embedded software integration with Siemens and Emerson automation platforms. Prioritize captive sensor manufacturing to tighten calibration tolerances and defend margin position against modular sensor suppliers. Address emerging hydrogen infrastructure specifications through enhanced sealing material R&D ahead of REACH substance restrictions.
For New Entrants and Emerging Players: Direct-to-utility digital channels offer the most penetrable route for cost-optimized positioner specifications in India's PLI-supported manufacturing automation expansions. Target Gujarat petrochemical brownfield retrofits where BIS certification timelines constrain European import competition. Develop wireless-enabled variants for North Dakota Bakken field well pad isolation valve monitoring where cabling infrastructure costs deter incumbent solutions.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale pneumatic component diversifiers given IIoT protocol convergence catalysts enabling predictive maintenance service revenue. Position for five-to-ten year holding windows as asset owners consolidate procurement through integrated automation framework agreements. Monitor hydrogen transport network pilot deployments as inflection indicator for specialized high-pressure valve control demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive piezoelectric fabrication tightens calibration tolerances for digital product lines. |
| Hydrogen Infrastructure Certification | Enhanced sealing specifications position suppliers for emerging high-pressure transport networks. |
| Wireless Protocol Stack Integration | ISA100 and WirelessHART enable predictive maintenance service models in remote valve automation. |
| ATEX Intrinsic Safety Expansion | Explosion-proof variants access German chemical processing clusters under EU Machinery Directive. |
| IIoT Platform Partnership | HART-IP and OPC UA integration anchors multi-year DCS framework agreements with system integrators. |
Methodological Framework
Multi-period observation of EPA regulatory filings, ATEX certification databases, and municipal water utility procurement records anchored the trend analysis, supplemented by interviews with plant engineers at German chemical facilities, maintenance directors at US Gulf Coast refineries, and automation procurement leads at Indian petrochemical complexes. Secondary validation drew from IEC 61508 functional safety documentation, SEC 10-K disclosures by listed automation vendors, and trade data from German mechanical engineering associations. Bottom-up unit demand estimates triangulated against top-down capital expenditure projections across process industry verticals.
Input-output matrices mapped electro pneumatic positioner shipments against valve actuator installations, DCS upgrade cycles, and emissions compliance deadlines across the projection horizon. Segmentation dimensions modeled include actuation architecture, technology tier, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical replacement patterns and announced greenfield automation investments. Forecast inputs incorporated nickel price volatility indices for stainless steel cost modeling and hydrogen infrastructure deployment timelines for specialized demand scenarios.
Inputs from regulatory agency filings and OEM procurement databases were available through the study window; gaps in private brownfield maintenance expenditure records introduce uncertainty bands around replacement cycle assumptions. Forecasts reflect documented regulatory mandates and announced capacity investments without projecting unannounced policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Deluge Valve Market
Valves
Global Stainless Steel Control Valves Market
Valves
Portable Valve Actuator Market
Valves
Pigging Valves Market
Valves
Choke Valves Market
Valves
Tank Hydrogen Valve Market
Valves
Valve Driver Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Blasting Stemming Plugs Market
Valves
Tubing Heads Market
Valves
Liner Regulators Market
Valves
Global Level Gauge Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Mobile Hydraulic Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Pipeline Strainers Market