
 Oil and Gas Well Conductor Installation Services Market | 2026-2036
Oil and Gas Well Conductor Installation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Well Conductor Installation Services Market Analysis
National oil companies are reorganizing procurement priorities toward integrated conductor installation packages that bundle structural maintenance with safety compliance. Baker Hughes leverages its hydraulic drilling technology portfolio to capture premium offshore contracts. Frank's International anchors its market position through specialized mechanical installation capabilities in harsh-environment basins. China Oilfield Services competes aggressively on cost structure for exploratory drilling programs across Asia-Pacific and African markets.
Oil and gas well conductor installation services encompass the engineering, placement, and securing of steel conductor pipes that provide structural support and pressure containment during initial drilling phases, typically ranging from 20 to 36 inches in diameter and set to depths of 100 to 300 feet below mudline. These services prevent shallow formation fluid influx, protect subsequent casing strings, and establish the foundation for blowout preventer stacks on offshore platforms and onshore pads. Conductor pipe installation commands the largest revenue share within service type segmentation due to its non-discretionary role in every well spud, while automated systems represent the fastest-expanding technology category as operators seek to reduce personnel exposure and improve placement precision in deepwater environments. Offshore platforms generate substantially higher per-well service values than onshore operations, though exploratory drilling applications exhibit greater volatility tied to upstream capital allocation cycles.
The US Bureau of Safety and Environmental Enforcement mandates strict well integrity verification protocols for Outer Continental Shelf operations, directly elevating demand for structural maintenance and safety compliance service bundles. Norway's Petroleum Safety Authority and the UK's Oil and Gas Authority enforce comparable conductor inspection and abandonment standards that shape contractor qualification requirements across the North Sea basin. Brazil's National Petroleum Agency imposes localization content rules that redirect service procurement toward domestic and joint-venture providers. Stakeholders must monitor regulatory divergence between prescriptive US rules and performance-based European frameworks when configuring regional service delivery models and certification investments.
Market Dynamics
Deepwater automation requirements and regulatory well integrity mandates are compressing contractor qualification timelines while elevating technical entry barriers across offshore basins.
Growth Catalysts
- US Bureau of Safety and Environmental Enforcement well integrity protocols:Mandatory structural verification for Outer Continental Shelf operations sustains demand for bundled safety compliance and conductor maintenance services.
- Pre-salt field development:Brazil's subsalt carbonate reservoirs require specialized conductor installation capabilities that command premium service pricing and long-term contract structures.
- Automated placement systems:Robotics integration reduces personnel exposure in deepwater environments while improving conductor setting precision beyond 1,500 meter water depths.
Market Restraints
- Specialized marine vessel scarcity:Heavy-lift installation units concentrate among North Sea and Gulf of Mexico operators, creating capacity bottlenecks during drilling campaign windows.
- High-grade steel alloy cost volatility:Sour service-resistant conductor materials fluctuate with nickel and chromium commodity indices, compressing fixed-price contract margins.
- Extended qualification timelines:Norway's Petroleum Safety Authority certification requirements delay new contractor market entry by 18-24 months.
Strategic Opportunities
- West African offshore provinces:Mauritania and Senegal basin development lacks established installation infrastructure, creating first-mover positioning for integrated service packages.
- Decommissioning regulatory mandates:UK Oil and Gas Authority well abandonment standards generate recurring conductor removal and site restoration revenue streams.
- Digital twin integration:Convergence of structural monitoring sensors with predictive analytics platforms enables condition-based maintenance contracts replacing scheduled interventions.
Industry Challenges
- Deepwater robotics technician scarcity:Automated conductor running tool operation requires specialized skill sets concentrated among Gulf of Mexico and Brazilian workforces.
- Legacy platform integration complexity:Brownfield conductor replacement on aging North Sea structures demands custom engineering incompatible with standardized installation procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Well Conductor Installation Services Market |
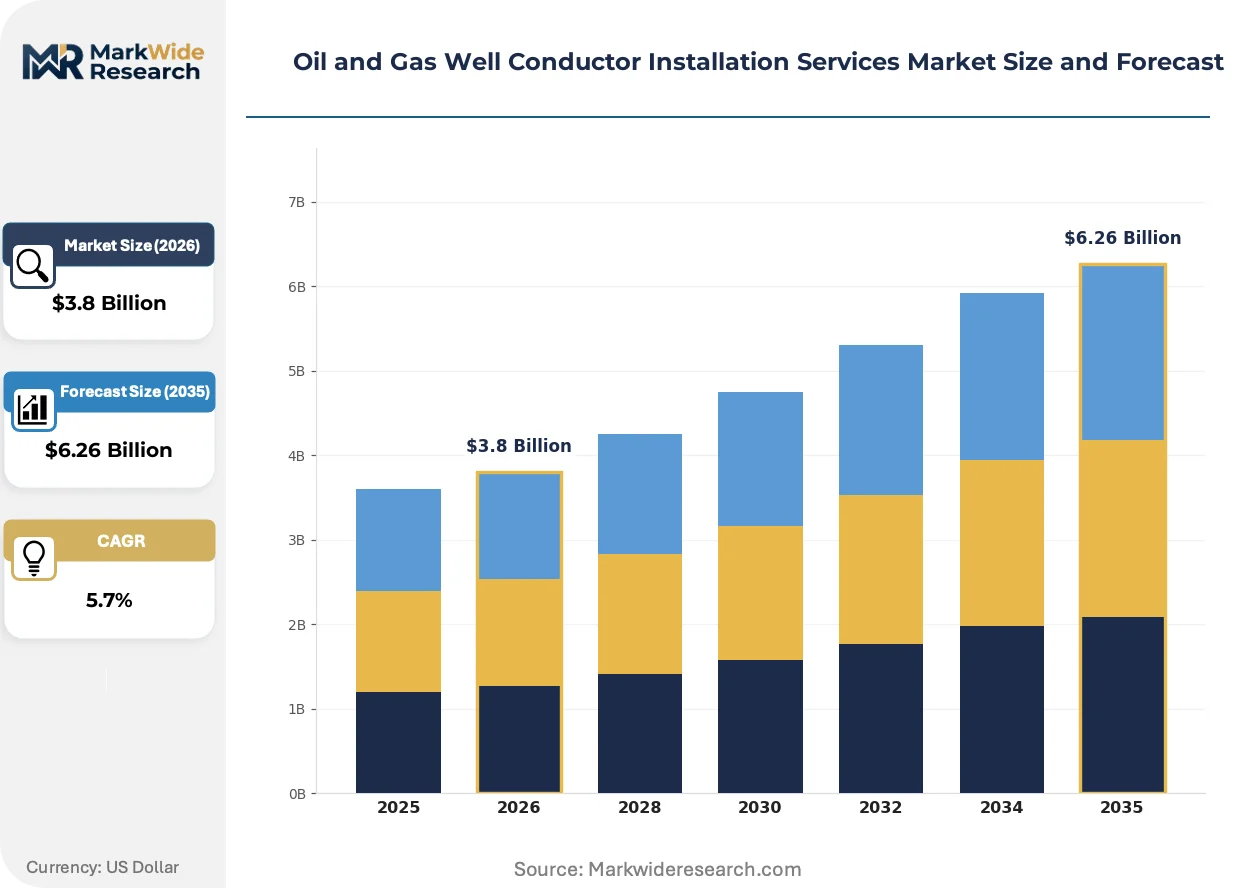
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Conductor Pipe Installation, Well Abandonment, Structural Maintenance, Safety Compliance Application: Onshore Operations, Offshore Platforms, Exploratory Drilling, Production Drilling Client Type: Independent Operators, National Oil Companies, Service Contractors, Joint Ventures Technology: Hydraulic Drilling, Mechanical Installation, Automated Systems, Manual Techniques |
| Companies Covered | Acteon Group, AOS Orwell, Baker Hughes, China Oilfield Services, Frank's International, Bechtel, Pinnergy, Sanguine Oilfield Services, Solidgro Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Well Conductor Installation Services Market Emerging Trajectories
Digitalization of subsea structural monitoring and modular installation system design are compressing project mobilization timelines while elevating predictive maintenance capabilities across offshore basins.
Remotely operated conductor running tools are fragmenting traditional vessel-based installation models. These systems enable seabed conductor setting without derrick barge deployment. Major operators in Brazil's pre-salt fields adopt hybrid robotic-conventional approaches. The technology is fragmenting contractor specialization between robotics integrators and legacy marine construction firms.
EU CSRD sustainability disclosure requirements now extend to offshore supply chain Scope 3 emissions reporting. Installation contractors must document steel sourcing carbon intensity and vessel fuel consumption. North Sea operators face the steepest compliance curves. Service providers are consolidating certification under ISO 14001 frameworks to maintain bidding eligibility.
Integrated project delivery contracts now bundle conductor installation with structural maintenance and integrity management. National oil companies in West Africa favor single-source accountability over fragmented subcontractor arrangements. This procurement evolution displaces discrete service sourcing. The shift is most visible in Ghanaian and Ivorian offshore licensing rounds.
Oil and Gas Well Conductor Installation Services Market Segmentation
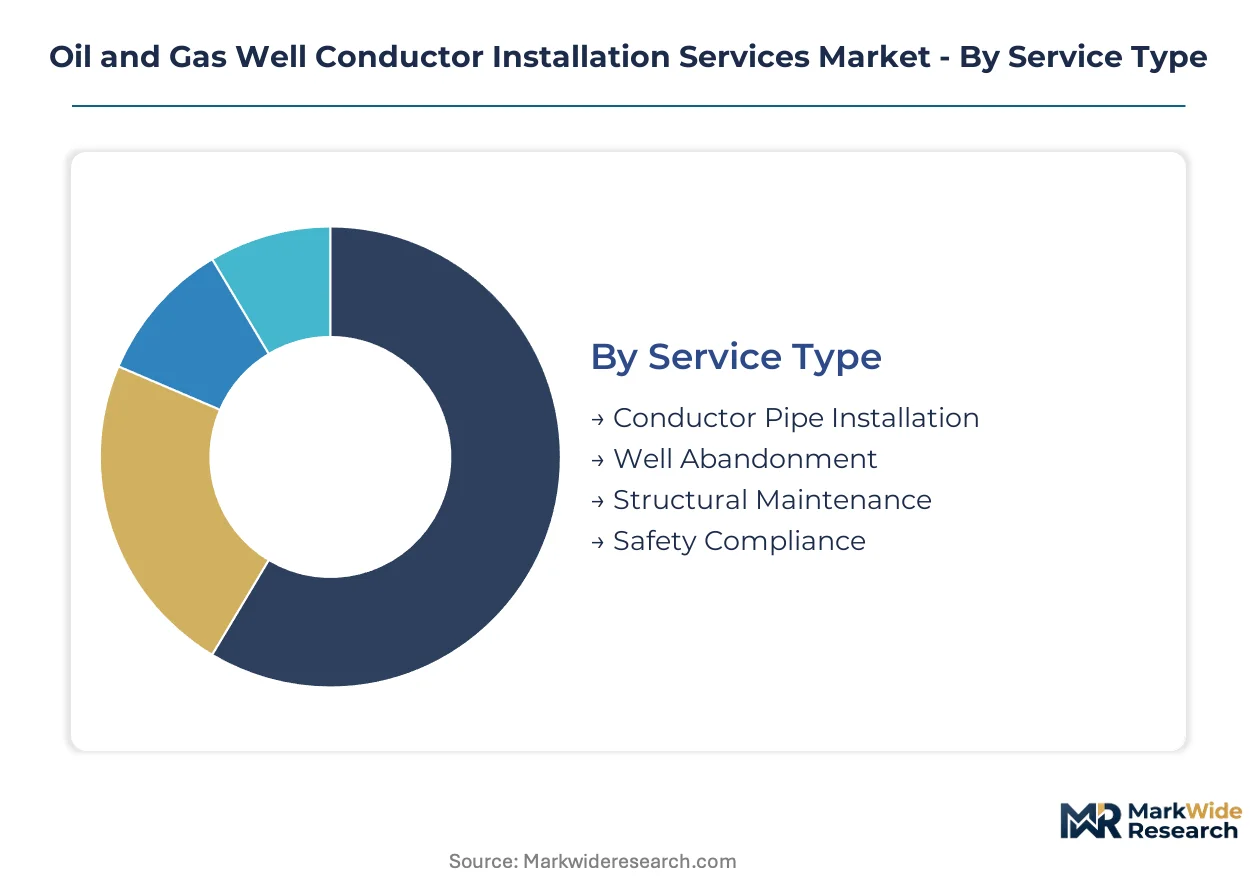
Segmentation reveals how procurement patterns split between mandatory baseline services and premium technology tiers. Geographic concentration of offshore basins drives differential demand across service categories.
Service Type:
Domestic demand concentrates in maintenance-heavy North Sea and Gulf of Mexico basins, while export-led growth follows national oil company expansion into West African and Brazilian pre-salt provinces.
- Conductor Pipe Installation:Steel conductor pipes ranging 20-36 inches diameter set to 100-300 feet below mudline provide structural foundation and pressure containment for blowout preventer stacks. Brazil's pre-salt fields and US Gulf deepwater projects sustain the highest per-well service values due to complex seabed conditions and regulatory verification requirements.
- Safety Compliance:Bundled structural verification and well integrity certification mandated by US Bureau of Safety and Environmental Enforcement and Norway's Petroleum Safety Authority protocols. North Sea operators face the steepest compliance cost escalation as performance-based European frameworks diverge from prescriptive US rules.
- Well Abandonment:Conductor removal and site restoration services driven by UK Oil and Gas Authority decommissioning mandates.
- Structural Maintenance:Integrity management for aging platform infrastructure, concentrated in brownfield North Sea assets.
Conductor Pipe Installation commands the established base. The steepest expansion runs through Safety Compliance.
Application:
Margin structures diverge sharply: offshore platforms generate 3-4x per-well service values versus onshore pads, while exploratory drilling exhibits volatile capital-cycle sensitivity absent from production drilling baselines.
- Offshore Platforms:Deepwater conductor setting beyond 1,500 meter depths requires specialized marine vessels and automated running tools. Brazil's pre-salt carbonate reservoirs and West African emerging basins absorb the majority of new capacity deployment.
- Exploratory Drilling:High-risk frontier basin spudding in Mauritania-Senegal provinces and Asia-Pacific deepwater blocks. Campaign windows concentrate demand into narrow temporal bands, creating vessel scarcity bottlenecks during active licensing rounds.
- Production Drilling:Recurring development drilling from established fields with predictable scheduling.
- Onshore Operations:Lower-complexity conductor setting with standardized equipment and compressed project timelines.
Offshore Platforms anchor revenue concentration. Exploratory Drilling climbs the fastest despite cyclical volatility.
Client Type:
Procurement authority is consolidating: national oil companies now favor integrated single-source contracts over fragmented subcontractor arrangements, displacing discrete service sourcing prevalent among independent operators.
- National Oil Companies:Brazilian, West African, and Middle Eastern state entities drive integrated package adoption. Brazil's National Petroleum Agency localization content rules redirect procurement toward domestic and joint-venture providers.
- Joint Ventures:Risk-sharing consortia in frontier basins combine operator capital with contractor technical capabilities. Ghanaian and Ivorian offshore licensing rounds exhibit this procurement evolution most visibly.
- Independent Operators:Price-sensitive spot contracting for single-well campaigns with limited bundled service appetite.
- Service Contractors:Subcontractor tier facing margin compression as national oil companies consolidate upstream procurement.
National Oil Companies dominate contract value. Joint Ventures gain share fastest through frontier basin expansion.
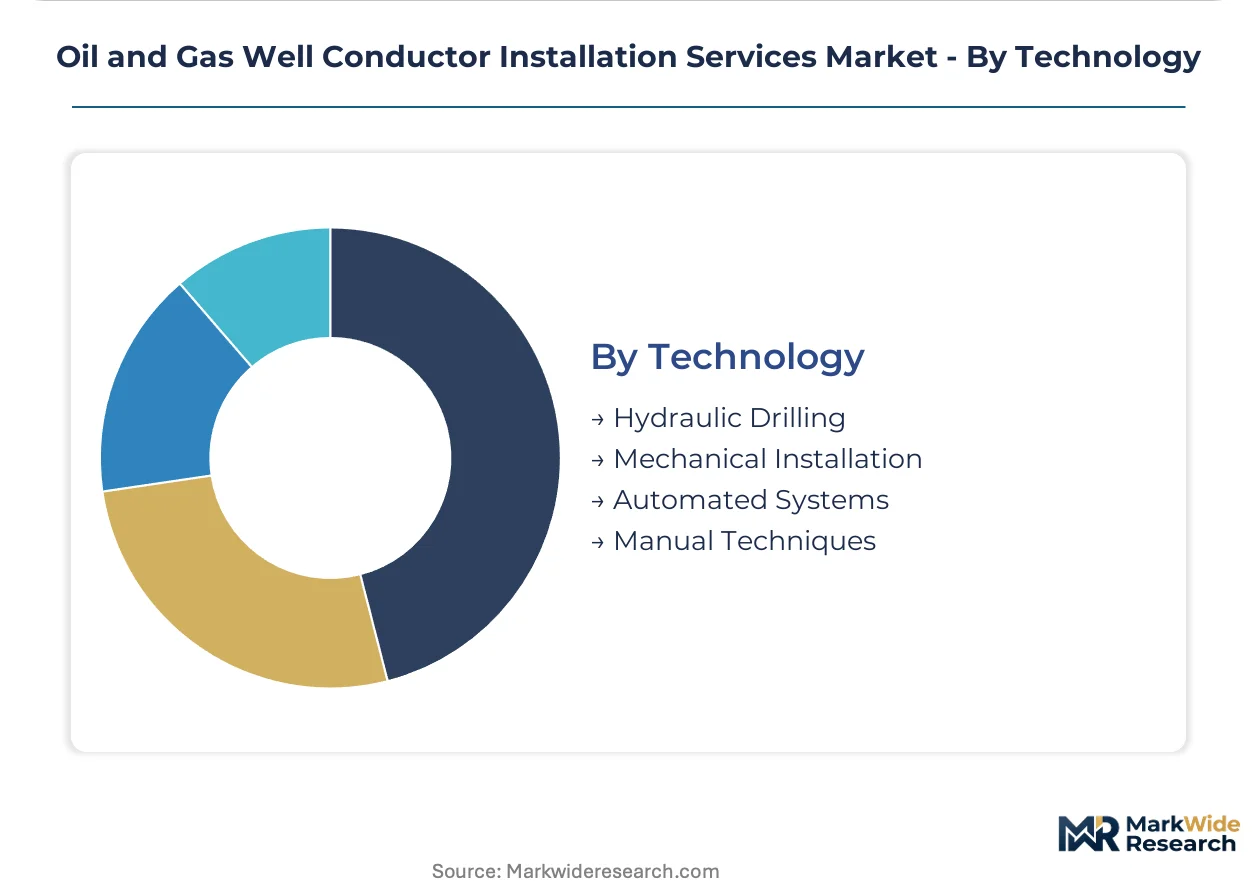
Technology:
Capital intensity stratifies sharply: automated systems demand 18-24 month qualification timelines and scarce robotics technician pools, while mechanical installation competes on execution speed in benign environments.
- Automated Systems:Remotely operated conductor running tools enable seabed setting without derrick barge deployment. Hybrid robotic-conventional approaches fragment contractor specialization between robotics integrators and legacy marine construction firms.
- Hydraulic Drilling:High-pressure fluid activation for conductor advancement in unconsolidated shallow formations. Premium positioning in deepwater basins where placement precision commands contract awards.
- Mechanical Installation:Conventional hammering and driving techniques for standard offshore and onshore applications.
- Manual Techniques:Labor-intensive methods constrained to shallow water and onshore contexts with limited automation penetration.
Hydraulic Drilling retains the installed base. Automated Systems expand most quickly as personnel exposure reduction becomes non-negotiable in deepwater environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports specialized conductor installation expertise to West African frontier basins, while US Gulf of Mexico contractors supply technology and safety compliance protocols to North Sea operators facing decommissioning mandates.
United States
The US Bureau of Safety and Environmental Enforcement enforces well integrity verification protocols for Outer Continental Shelf operations, sustaining demand for bundled safety compliance services. Deepwater automation requirements in the Gulf of Mexico compress contractor qualification timelines while elevating technical entry barriers. Houston anchors the domestic service provider cluster, with specialized marine vessel operators concentrated along the Louisiana-Texas corridor.
Brazil
Pre-salt carbonate reservoir development commands premium service pricing and long-term contract structures for specialized conductor installation capabilities. The National Petroleum Agency imposes localization content rules that redirect procurement toward domestic and joint-venture providers. Rio de Janeiro hosts the primary contractor ecosystem serving Petrobras-led subsalt field expansion.
Norway
Performance-based well integrity frameworks from the Petroleum Safety Authority diverge from prescriptive US rules, shaping distinct contractor qualification requirements. Extended certification timelines delay new market entry by 18-24 months, protecting incumbent service positions. Stavanger and Bergen concentrate brownfield structural maintenance capacity for aging North Sea platform infrastructure.
United Kingdom
The Oil and Gas Authority's well abandonment standards generate recurring conductor removal and site restoration revenue streams across mature basin assets. Decommissioning regulatory mandates accelerate procurement of integrated service packages combining installation with integrity management. Aberdeen maintains its position as the North Sea's primary service contracting hub.
Senegal
Mauritania-Senegal basin development lacks established installation infrastructure, creating first-mover positioning opportunities for integrated service packages. Frontier licensing rounds concentrate exploratory drilling demand into narrow temporal bands, generating vessel scarcity bottlenecks. Dakar serves as the logistics coordination point for emerging West African offshore campaigns.
Oil and Gas Well Conductor Installation Services Market Vendor Landscape
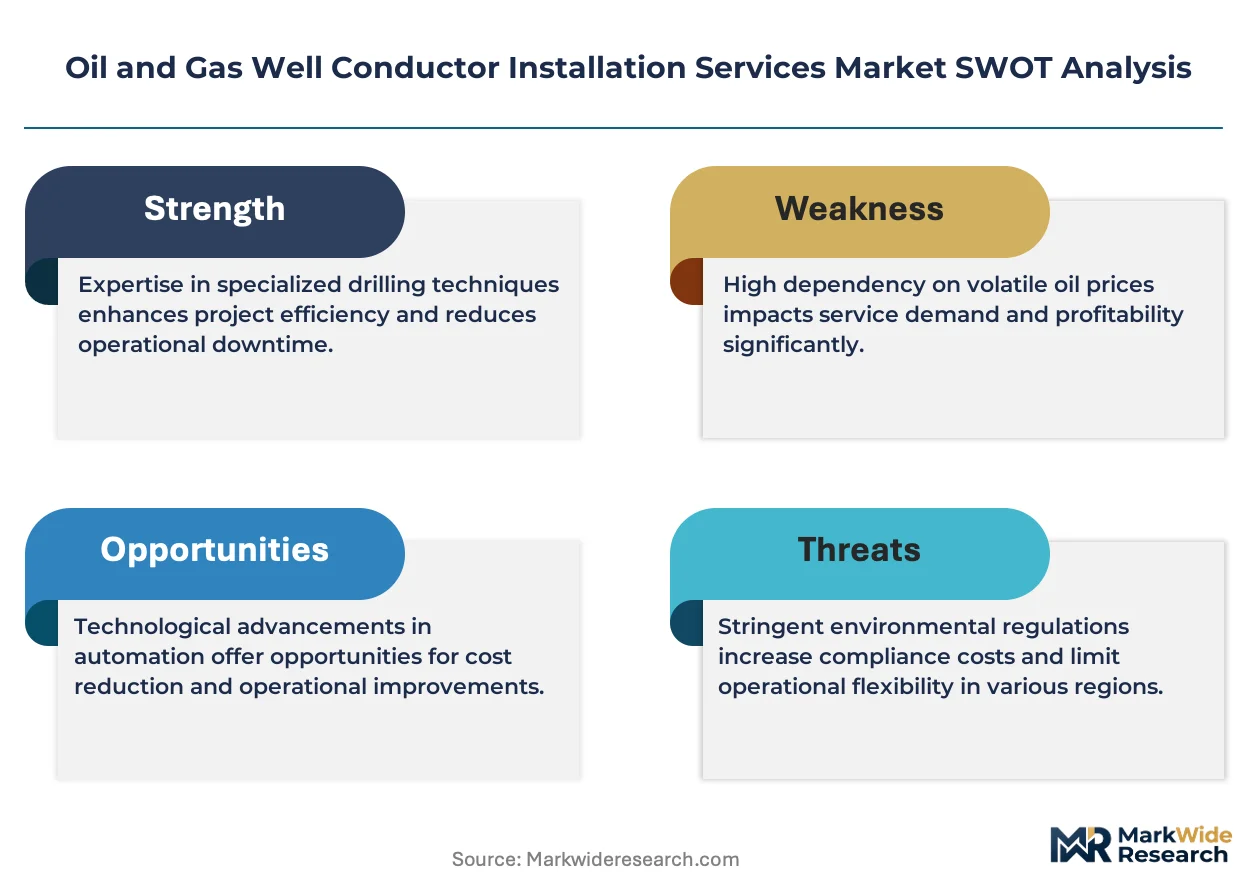
Player mix skews toward integrated energy service conglomerates with offshore technology portfolios, though specialized mechanical installation contractors retain defensible positions in harsh-environment basins. Tier-one participants bundle conductor placement with structural maintenance and safety compliance to capture national oil company procurement consolidation. Mid-tier specialists compete on execution speed in benign environments with standardized equipment. Dominant competitive moves include strategic partnerships for robotics integration and geographic expansion through joint ventures with local content requirements.
Within the integrated service tier, Baker Hughes leverages hydraulic drilling technology positioning for premium offshore contract capture, while Frank's International anchors market presence through specialized mechanical installation capabilities in harsh-environment basins. China Oilfield Services occupies the cost-competitive vector for exploratory drilling programs across Asia-Pacific and African markets. These three represent distinct strategic archetypes: technology-integrated conglomerate, harsh-environment specialist, and scale-driven regional challenger.
| Leading Market Players |
|---|
| Acteon Group |
| AOS Orwell |
| Baker Hughes |
| China Oilfield Services |
| Frank's International |
| Bechtel |
| Pinnergy |
| Sanguine Oilfield Services |
| Solidgro Energy |
| Others |
Supply Flow & Price Mechanics
18-to-24-month qualification timelines for automated conductor running tools concentrate pricing power among incumbent robotics integrators while compressing margins for mechanical installation specialists competing on speed. This lead-time asymmetry shapes how national oil companies allocate procurement budgets across premium automated tiers and commoditized conventional service layers.
Pricing Analysis
Current-generation automated systems command 40-60% premiums over prior-generation hydraulic drilling platforms, while next-generation digital-twin-integrated packages are pricing at exploratory contract levels. Three-tier pricing structure across premium automation, standard hydraulic, and economy mechanical tiers differentiates on certification grade and water-depth capability. Pricing pressure stems from high-grade steel alloy cost volatility tied to nickel and chromium indices, compressing fixed-price contract margins for vessel operators. Independent operators exhibit highest price sensitivity, while national oil companies absorb premium tiers for integrated single-source accountability.
Supply Chain Analysis
Specialized heavy-lift marine vessel availability through the Strait of Malacca and Singapore anchorage underwrites project mobilization timelines for Asia-Pacific and West African campaigns. Manufacturing concentration clusters in Norway, Singapore, and the US Gulf Coast for subsea robotics hardware, while steel conductor pipe fabrication draws from South Korean and Japanese mills. Supply chain risk centers on single-source vulnerability for sour service-resistant alloy formulations. Distribution runs through integrated project delivery contracts that bundle installation with structural maintenance, displacing discrete spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conductor installation services are approaching a platform-economics inflection as digital twin integration creates interoperability standards between structural monitoring sensors and predictive analytics platforms, shifting value capture from discrete project execution to recurring condition-based maintenance contracts.
For Market Incumbents: Shield market position through captive robotics technician training pipelines addressing deepwater automation skill scarcity concentrated in Gulf of Mexico and Brazilian workforces. Consolidate backward integration into high-grade steel alloy sourcing to buffer nickel and chromium commodity volatility. Prioritize certification investment under ISO 14001 frameworks to maintain bidding eligibility as EU CSRD sustainability disclosure requirements extend to offshore supply chain Scope 3 emissions reporting. For New Entrants and Emerging Players: Differentiate on hybrid robotic-conventional service architectures that fragment contractor specialization between legacy marine construction and emerging robotics integration. Target Mauritania-Senegal basin development where established installation infrastructure absence creates first-mover positioning for integrated packages. Pursue joint venture structures with domestic content partners to satisfy Brazil's National Petroleum Agency localization rules. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because well integrity mandates across US, Norwegian, and UK jurisdictions sustain non-discretionary demand for safety compliance services regardless of upstream capital allocation cycles. Acquisition targets should display integrated project delivery capabilities bundling installation with structural maintenance. Monitor vessel utilization rates in West African frontier basins as the inflection signal for capacity-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Integration Partnership | Hybrid automated-conventional capabilities capture Petrobras pre-salt premium contracts. |
| Localization Joint Venture | Brazilian content rules redirect procurement toward domestic-foreign partnership structures. |
| Digital Twin Platform Development | Condition-based maintenance contracts displace scheduled intervention revenue models. |
| Specialized Marine Vessel Acquisition | Heavy-lift unit scarcity in West Africa creates bottleneck leverage during campaign windows. |
| ISO 14001 Certification Consolidation | EU CSRD Scope 3 disclosure mandates filter bidding eligibility for North Sea operators. |
Methodological Framework
The analysis maps conductor pipe installation, safety compliance, well abandonment, and structural maintenance segments, each validated through offshore project engineers, marine vessel operators, national oil company procurement leads, and regulatory compliance officers. Primary fieldwork combined structured interviews with secondary validation through US Bureau of Safety and Environmental Enforcement filings, Norway Petroleum Safety Authority audit reports, Brazil National Petroleum Agency licensing databases, and UK Oil and Gas Authority decommissioning records. Bottom-up project pipeline enumeration triangulates against top-down operator capex disclosures.
Consistency checks against vessel fleet utilization databases and offshore drilling contract registries validated volume and value outputs across the projection horizon. The analytical framework models service type, application, client type, and technology segmentation dimensions alongside water-depth capability tiers. CAGRs derive from regression-adjusted operator spending patterns and regulatory mandate implementation schedules. Forecast inputs incorporate marine vessel day-rate trajectories and steel alloy commodity index correlations.
Material uncertainties — upstream capital allocation volatility, regulatory timeline slippage, and robotics technician supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions documented in segment-level growth drivers without claiming predictive certainty. Practitioners should keep alternative scenarios live as pre-salt field development pace and West African licensing round timing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Tight Gas Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market