
 Enhanced Gas Recovery (EGR) Market | 2026-2036
Enhanced Gas Recovery (EGR) Market Size, Share, and Industry Trends Forecast 2026-2036
Enhanced Gas Recovery (EGR) Market Foresight
ISO 16530-2 well integrity standards for CO2 service is redrawing competitive boundaries in EGR equipment supply. The Linde Group leverages its cryogenic gas separation heritage to dominate merchant CO2 supply chains for injection projects. Abu Dhabi National Oil Company anchors regional demand through its Al Reyadah carbon capture facility, which feeds directly into EGR operations at the Rumaitha and Bab fields.
Enhanced gas recovery encompasses techniques that inject gases such as carbon dioxide or nitrogen into depleted or low-pressure natural gas reservoirs to mobilize trapped hydrocarbons and restore formation pressure. CO2 injection achieves miscibility at reservoir conditions above 31 degrees Celsius and 7.38 MPa, enabling displacement efficiencies exceeding water flooding in tight sandstone formations. CO2 injection technology leads deployment value due to carbon credit monetization and regulatory mandates, while thermal gas recovery occupies a mature niche concentrated in heavy-oil adjacent gas caps. Offshore deployment represents the fastest-growing structural segment as subsea compression and tieback architectures reduce platform capex intensity.
EPA Underground Injection Control Class VI permitting governs CO2 sequestration wells in the United States, extending project timelines but creating durable barriers against unqualified entrants. China's MEE enforces GB 31571 emission limits that push Sinopec and PetroChina toward integrated carbon capture and EGR investments. The EU F-Gas Regulation constrains synthetic fluorinated gas use, indirectly favoring natural CO2 sourcing for European EGR projects. Stakeholders must monitor Class VI permit approval velocity as the primary signal of North American project scalability.
Market Dynamics
Carbon capture integration mandates are compressing project development timelines while elevating technical barriers for equipment suppliers across the EGR value chain. Regulatory frameworks in the United States and China now tie injection permits to verified sequestration accounting, forcing operators to consolidate vendor relationships around certified service providers.
Growth Catalysts
- EPA Class VI Permitting:Underground injection control rules create durable compliance moats for qualified operators, locking out undercapitalized competitors while securing long-term CO2 supply agreements for permitted facilities.
- Permian Basin Depletion:Mature sandstone reservoirs in West Texas and southeastern New Mexico offer ideal miscible flooding conditions, concentrating operator investment in proven geology with existing pipeline infrastructure.
- Carbon Credit Monetization:45Q tax credits and comparable incentive structures transform CO2 sourcing economics, enabling injection projects to recover hydrocarbons while generating verified carbon removal revenues.
Market Restraints
- Merchant CO2 Supply Concentration:Industrial gas majors control cryogenic separation capacity, creating input bottlenecks for independent operators lacking backward integration into CO2 production.
- Well Integrity Certification Delays:ISO 16530-2 compliance testing extends equipment qualification timelines, freezing out suppliers without established CO2 service track records.
- Subsea Compression Capex Intensity:Offshore tieback architectures require specialized high-pressure pumping systems that strain balance sheets of mid-cap exploration companies.
Strategic Opportunities
- Abu Dhabi Carbon Capture Integration:Al Reyadah facility output feeds directly into EGR operations at Rumaitha and Bab fields, establishing a template for national oil company carbon capture-to-recovery linkages.
- EU F-Gas Regulatory Tailwind:Synthetic fluorinated gas constraints favor natural CO2 sourcing for European injection projects, opening merchant supply contracts for industrial gas distributors.
- Nitrogen Injection Technology Convergence:Cryogenic air separation advances enable cost-competitive N2 flooding in reservoirs below CO2 miscibility thresholds, expanding addressable geology.
Industry Challenges
- Geochemical Corrosion Expertise Gap:CO2-brine-rock interactions demand specialized metallurgy knowledge that reservoir engineering programs rarely emphasize, forcing operators to outsource well completion design.
- Monitoring, Reporting, and Verification Integration:Continuous sequestration accounting requires subsurface monitoring technology stacks that legacy SCADA systems cannot accommodate without wholesale replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enhanced Gas Recovery (EGR) Market |
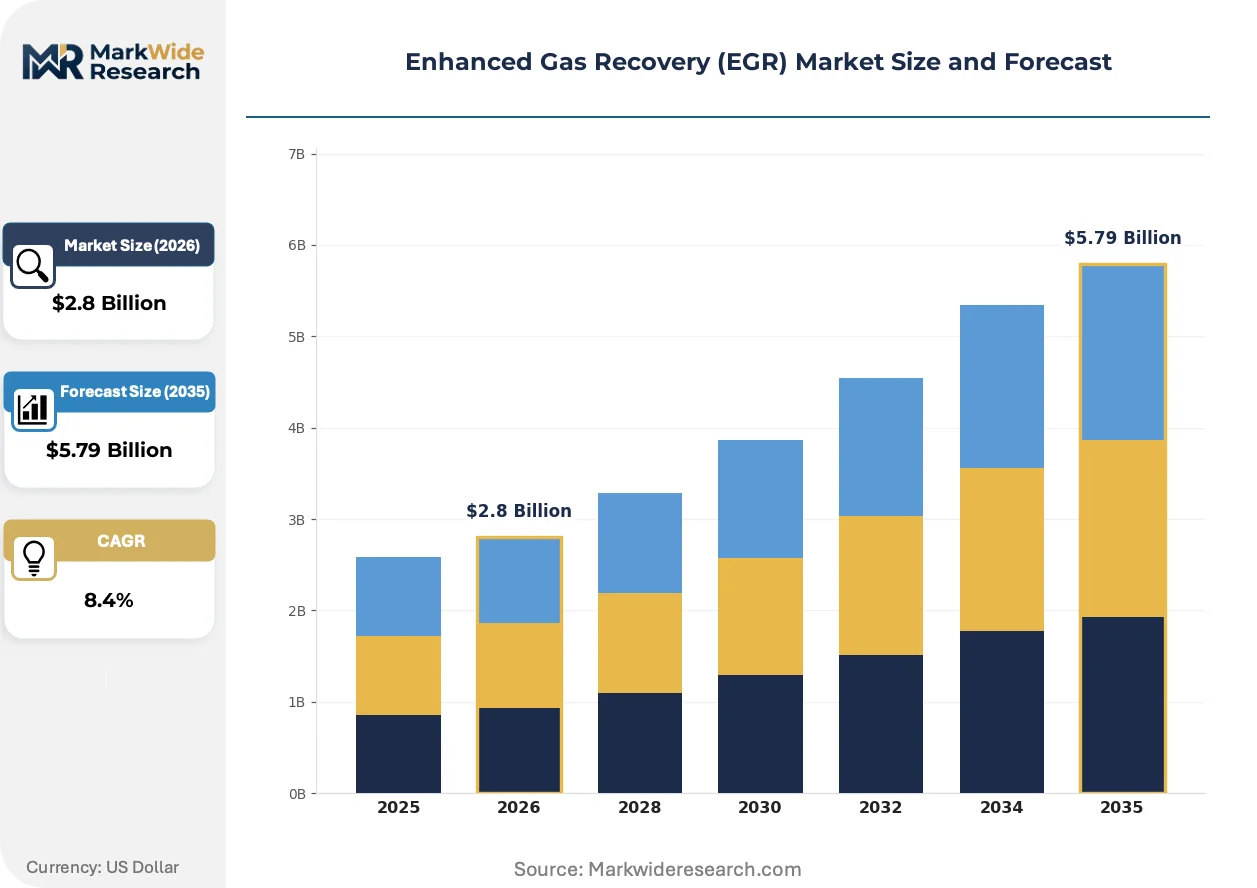
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CO2 Injection, N2 Injection, Water Flooding, Thermal Gas Recovery Application: Natural Gas Fields, Oil Reservoirs, Enhanced Oil Recovery, Unconventional Resources End User: Petroleum Companies, Government Agencies, Research Institutions, Energy Producers Deployment: Onshore, Offshore, Subsea, Integrated Solutions |
| Companies Covered | Abu Dhabi National Oil Company (ADNOC), The Linde Group, Praxair, Inc., NALCO Energy Services, Tiorco, LLC, Dow Chemical Company, Linde Engineering, Air Products, Messer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enhanced Gas Recovery (EGR) Market Shifts & Advancements
Subsea processing architectures are compressing platform capital requirements while redistributing technical risk across equipment suppliers and installation contractors. Three developments are restructuring competitive positioning.
Modular CO2 compression skids are fragmenting the market for integrated injection systems. These containerized units enable rapid field deployment without custom fabrication, attracting independent operators in the Permian Basin seeking to avoid long-lead engineering contracts. The technology is fragmenting procurement patterns by allowing piecemeal capacity additions aligned with reservoir response rather than upfront megaproject commitments.
China's MEE enforcement of GB 31571 emission limits is accelerating Sinopec and PetroChina toward integrated carbon capture investments. The standard tightens allowable venting from gas processing facilities, effectively mandating CO2 capture for continued operating permits. Onshore mature fields in Sichuan and Ordos basins face the steepest compliance ramps, driving demand for domestic compression equipment suppliers.
Reservoir surveillance contracting is unbundling from full-field development agreements. Operators now procure 4D seismic and distributed fiber optic monitoring as standalone services, displacing bundled turnkey contracts that buried diagnostic costs in drilling budgets. This shift is most pronounced in the United States Gulf of Mexico, where independent producers lack captive geoscience departments and favor à la carte technical purchasing.
Enhanced Gas Recovery (EGR) Market Segmentation
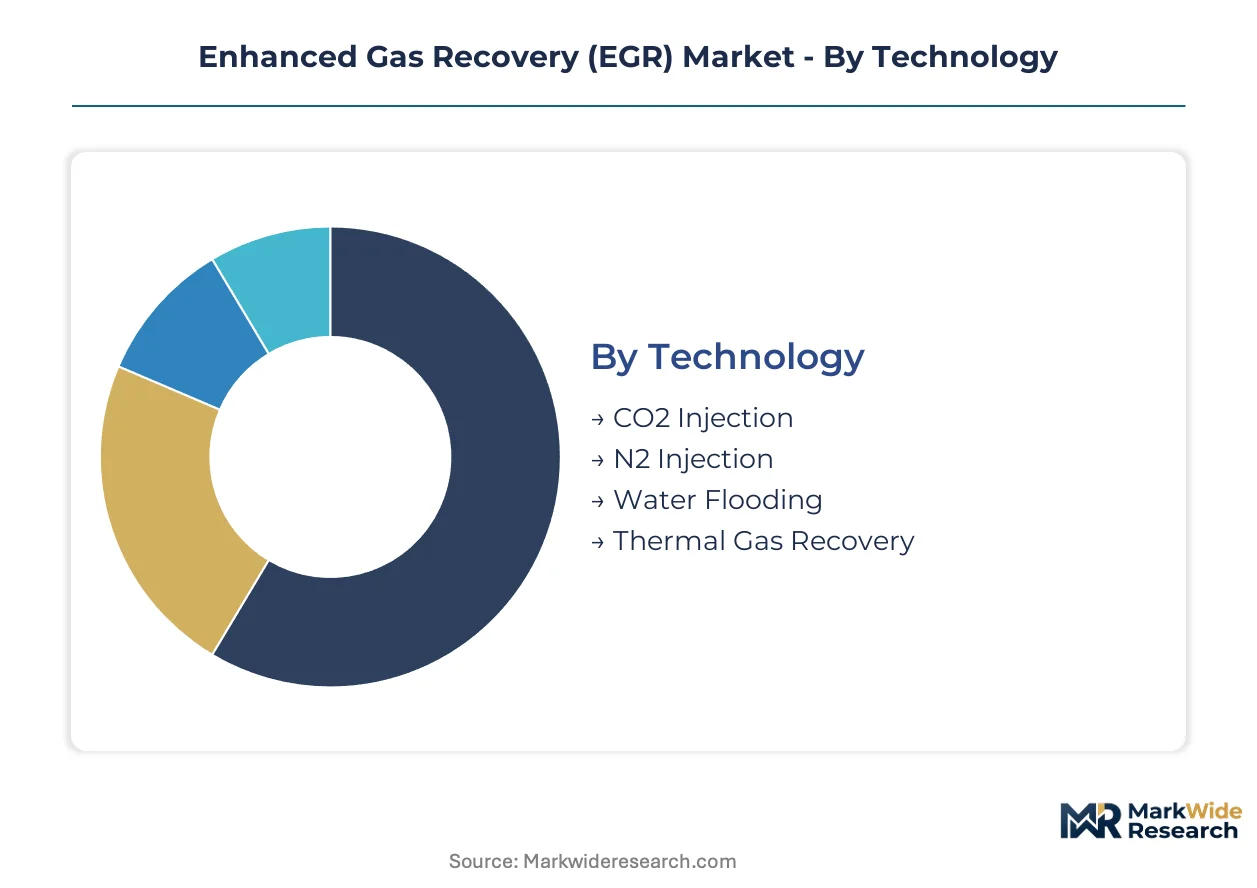
EGR market segmentation reveals distinct technology-application pairings that concentrate investment in specific geographies. Understanding these patterns exposes where capital flows, where regulatory pressure intensifies, and where equipment suppliers can anchor recurring revenue streams.
Technology:
CO2 injection dominates domestic North American deployment through 45Q credit monetization, while nitrogen flooding retains export-led demand in regions lacking carbon capture infrastructure.
- CO2 Injection:Achieves miscibility above 31°C and 7.38 MPa, enabling displacement efficiencies exceeding water flooding in tight sandstone. Permian Basin operators concentrate demand here, driven by EPA Class VI permitting that locks in long-term sequestration accounting.
- N2 Injection:Cryogenic air separation advances enable cost-competitive flooding in reservoirs below CO2 miscibility thresholds. Middle Eastern and North African fields favor this technology where carbon capture infrastructure remains underdeveloped.
- Water Flooding:Mature pressure maintenance technique with established equipment supply chains.
- Thermal Gas Recovery:Heavy-oil adjacent gas cap applications in Venezuela and Canadian oil sands regions.
CO2 injection commands the established base. The steepest expansion runs through N2 injection as cryogenic costs decline.
Application:
Natural gas field applications cluster in cost-tiered deployment models—premium integrated systems for offshore, standard modular skids for onshore mature basins.
- Natural Gas Fields:Depleted sandstone reservoirs in the United States Gulf Coast and Sichuan Basin anchor equipment procurement. China's MEE enforcement of GB 31571 emission limits tightens compliance requirements for continued operating permits.
- Oil Reservoirs:Associated gas recovery from mature oil fields generates parallel CO2 injection demand. Middle Eastern national oil companies integrate EGR with carbon capture facilities at scale.
- Enhanced Oil Recovery:CO2-EOR-to-EGR transition projects in West Texas leverage existing pipeline infrastructure.
- Unconventional Resources:Shale gas pressure maintenance applications remain technically challenging due to fracture complexity.
Natural gas fields absorb the majority of current capital. Unconventional resources present the longest development runway.
End User:
Petroleum companies drive volume procurement through centralized engineering standards, while government agencies shape demand through carbon capture integration mandates.
- Petroleum Companies:Integrated majors and independents deploy divergent sourcing strategies—captive CO2 supply for ExxonMobil and Shell, merchant contracts for Permian independents. Sinopec and PetroChina accelerate domestic compression equipment procurement under regulatory pressure.
- Government Agencies:Direct investment in demonstration projects and carbon accounting infrastructure. Abu Dhabi National Oil Company's Al Reyadah facility establishes template for national oil company carbon capture-to-recovery linkages.
- Research Institutions:Subsurface monitoring technology validation and geochemical corrosion studies.
- Energy Producers:Power sector entrants seeking vertical integration into carbon management value chains.
Petroleum companies command the established base. Government agencies are gaining share fastest through direct infrastructure investment.
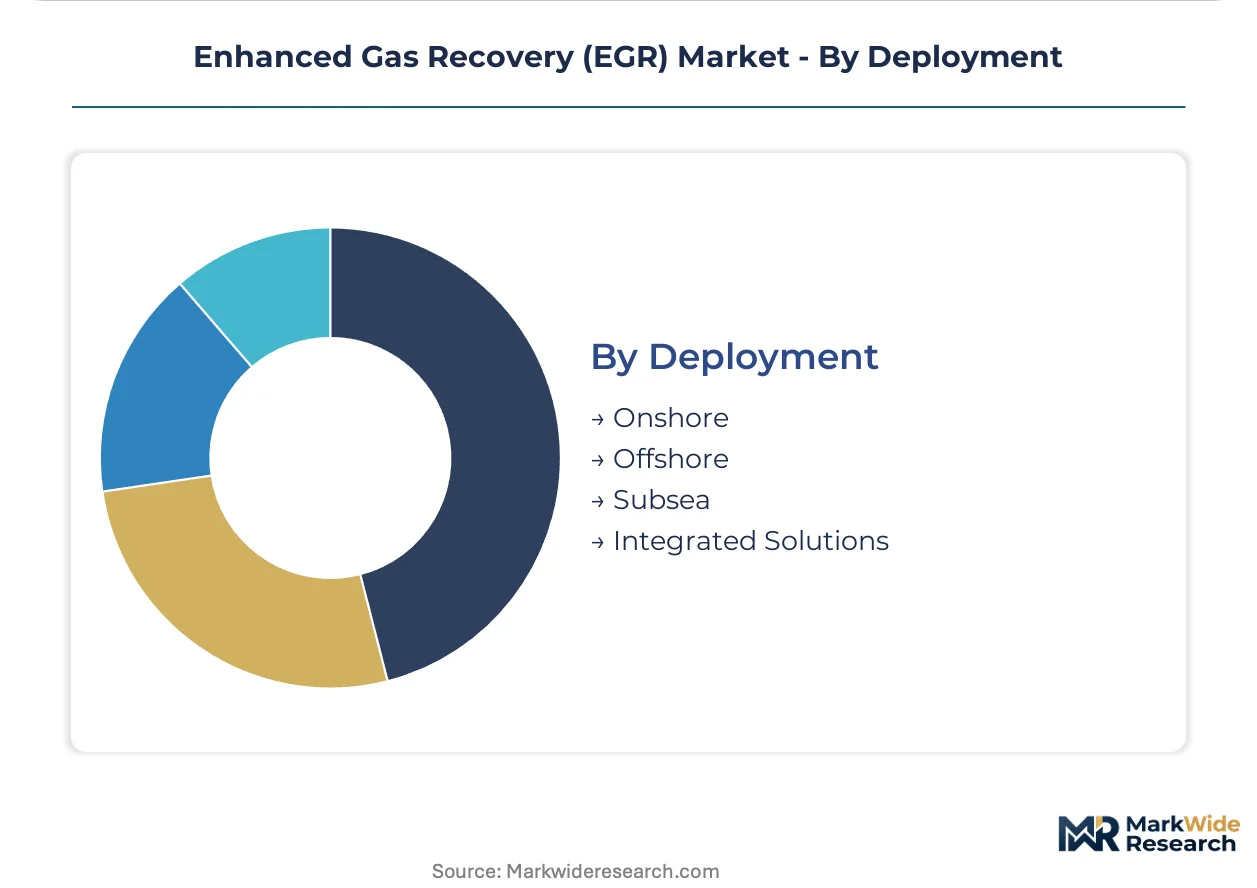
Deployment:
Onshore deployment concentrates in customer-type tiering—integrated solutions for majors, modular skids for independents—while offshore commands premium pricing through technical complexity.
- Onshore:Modular CO2 compression skids fragment procurement patterns in the Permian Basin, enabling rapid field deployment without custom fabrication. Containerized units attract independents seeking to avoid long-lead engineering contracts.
- Offshore:Subsea compression and tieback architectures reduce platform capex intensity while redistributing technical risk across equipment suppliers. United States Gulf of Mexico independents favor à la carte technical purchasing for reservoir surveillance.
- Subsea:High-pressure pumping systems strain mid-cap exploration company balance sheets.
- Integrated Solutions:Full-field development bundling persists among national oil companies with captive engineering capacity.
Onshore deployment commands the established base. Offshore represents the steepest expansion trajectory as subsea processing architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum companies with depleted sandstone portfolios drive procurement concentration across four major EGR investment clusters. National oil companies and Permian independents anchor capital deployment, with regulatory compliance timelines shaping regional project velocity.
United States
Permian Basin operators deploy modular CO2 compression skids to accelerate field redevelopment without long-lead engineering contracts. EPA Class VI permitting creates durable compliance moats that lock out undercapitalized competitors while securing decades-long sequestration accounting. West Texas and southeastern New Mexico host the densest concentration of miscible flooding projects tied to 45Q credit monetization.
China
Sinopec and PetroChina accelerate domestic compression equipment procurement under tightening emission enforcement. MEE protocols enforcing GB 31571 limits mandate CO2 capture for continued operating permits at gas processing facilities. Sichuan and Ordos basin mature fields face the steepest compliance ramps, driving integrated carbon capture-to-recovery investments.
United Arab Emirates
ADNOC anchors regional demand through direct carbon capture integration at scale. The Al Reyadah facility feeds processed CO2 directly into EGR operations at Rumaitha and Bab fields, establishing a template for national oil company linkage models. Abu Dhabi engineering standards now require sequestration verification for all new injection permits.
Germany
Industrial gas distributors expand merchant CO2 supply contracts as EU F-Gas Regulation constrains synthetic fluorinated alternatives. REACH compliance frameworks and CE marking requirements elevate technical barriers for equipment imports into North Sea adjacent projects. Lower Saxony and North Rhine-Westphalia host the primary onshore gas storage complexes evaluating injection conversion.
Saudi Arabia
Saudi Aramco evaluates nitrogen flooding architectures for reservoirs below CO2 miscibility thresholds in the Eastern Province. The country's national oil company channels capital toward enhanced recovery demonstration projects aligned with domestic carbon management targets. Ghawar field adjacent gas caps present the largest single-asset EGR opportunity in the region.
Enhanced Gas Recovery (EGR) Market Competitive Landscape
Player mix skews toward integrated industrial gas majors and national oil company affiliates with captive carbon capture infrastructure. Market structure concentrates around three tiers: cryogenic separation specialists controlling merchant CO2 supply, engineering subsidiaries bundling compression and injection systems, and regional service contractors unbundling reservoir surveillance from full-field development. Strategic moves center on backward integration into CO2 production and modular skid standardization to compress deployment timelines.
Among industrial gas conglomerates, The Linde Group and Air Products occupy positions exemplifying cryogenic heritage leverage into merchant supply chain dominance. Abu Dhabi National Oil Company represents the national oil company archetype with fully integrated capture-to-recovery linkages. Praxair, Inc. sits within the tier of North American distributors capitalizing on 45Q credit economics to anchor long-term offtake agreements with Permian operators.
| Leading Market Players |
|---|
| Abu Dhabi National Oil Company (ADNOC) |
| The Linde Group |
| Praxair, Inc. |
| NALCO Energy Services |
| Tiorco, LLC |
| Dow Chemical Company |
| Linde Engineering |
| Air Products |
| Messer Group |
| Others |
Supply & Pricing Matrix
Long-term take-or-pay contracts between Permian Basin operators and merchant CO2 suppliers lock in decade-long price visibility while securing pipeline access against spot market volatility. These arrangements tie injection project economics to 45Q credit monetization thresholds, forcing independent operators to accept fixed-price commitments that transfer volume risk to industrial gas majors.
Pricing Analysis
Cost-plus contracts indexed to Henry Hub natural gas benchmarks dominate CO2 supply agreements in North American EGR deployment. Price differentiation rests on ISO 16530-2 certification tier and cryogenic separation purity grade, with Class VI-permitted operators commanding premium terms. Pricing pressure stems from merchant supply concentration among industrial gas conglomerates. Mid-cap exploration companies exhibit highest price sensitivity due to balance sheet constraints, while integrated majors with captive carbon capture infrastructure face minimal exposure.
Supply Chain Analysis
Strategic stockpiling of cryogenic separation equipment characterizes procurement patterns as lead times for ISO-certified compression skids extend beyond project sanctioning windows. Supply concentrates in the United States, Germany, and China for high-pressure pumping systems and specialized metallurgy. Raw material dependencies include nickel-based alloys for CO2 service, subsea umbilical cabling, and distributed fiber optic sensing arrays. Single-source vulnerability runs through cryogenic gas separation technology licensors. Distribution runs through engineering-procurement-construction contractors bundling equipment packages for national oil company clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around petroleum companies with captive carbon capture infrastructure, fragmenting procurement influence among merchant-dependent independents. This asymmetry reshapes vendor relationship economics across the EGR value chain.
For Market Incumbents: Shield long-term offtake positions by accelerating backward integration into cryogenic CO2 production capacity before 45Q credit thresholds trigger demand surges. Prioritize ISO 16530-2 certification investment to lock out unqualified equipment competitors. Defend against modular skid suppliers by embedding reservoir surveillance services into compression system contracts.
For New Entrants and Emerging Players: Lead with nitrogen injection technology convergence targeting Middle Eastern reservoirs below CO2 miscibility thresholds where carbon capture infrastructure remains underdeveloped. White-space opportunities concentrate in Sichuan Basin domestic equipment procurement under MEE enforcement pressure. Go-to-market leverage rests on rapid-deployment containerized compression skids bypassing long-lead engineering contracts.
For Investors and Strategic Acquirers: Reservoir surveillance technology specialists with distributed fiber optic monitoring capabilities represent the most defensible acquisition archetype as operators unbundle diagnostic services from full-field development agreements. Long-term viability hinges on continuous sequestration accounting mandates expanding across regulatory jurisdictions. Signal to watch: EPA Class VI permit approval velocity crossing threshold levels that unlock scalable project finance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CO2 Production | Captive supply secures against merchant concentration and 45Q credit capture. |
| ISO 16530-2 Certification Investment | Compliance moat locks out unqualified competitors from CO2 service contracts. |
| Modular Compression Skid Standardization | Containerized units attract Permian independents seeking rapid deployment. |
| Reservoir Surveillance Unbundling | Standalone 4D seismic and fiber optic services displace bundled turnkey contracts. |
| Subsea Processing Architecture Partnership | Tieback systems redistribute technical risk across equipment suppliers and contractors. |
Research Methodology
Cross-validation between primary interviews with reservoir engineering directors, carbon capture project developers, and EPA permitting consultants and secondary validation through FERC filings, EIA injection well databases, and industrial gas company SEC disclosures anchors the qualitative findings. Bottom-up project pipeline tracking triangulates against top-down market sizing from compression equipment procurement records.
Sensitivity analysis across technology adoption curves, regulatory compliance timelines, and carbon credit monetization thresholds shapes the analytical framework. Segmentation dimensions modeled include injection technology type, deployment architecture, and end-user integration depth. CAGRs derive from equipment procurement velocity and project sanctioning rates. Industry-specific forecast inputs incorporate Class VI permit approval trajectories and cryogenic separation capacity expansion schedules.
Underlying assumptions cover continued 45Q credit authorization, EPA enforcement consistency, and industrial gas major capacity investment, with deviation risk concentrated in regulatory reversal or carbon accounting standard changes. Revision becomes warranted when MEE enforcement intensity or EU F-Gas Regulation amendment crosses thresholds that restructure regional project economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Enclosed Flares Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Oilfield Roller Chain Market