
 Flanges Market | 2026-2036
Flanges Market Size, Share, and Industry Trends Forecast 2026-2036
Flanges Market Analysis
Composite polymer materials is repositioning carbon steel flanges in corrosive chemical processing environments where weight reduction and chemical resistance justify premium pricing. Parker Hannifin leverages its integrated sealing technology portfolio to bundle gasket-flange solutions for hydraulic system OEMs. Nippon Steel Corporation anchors its position through captive metallurgical R&D that produces ultra-low-temperature nickel alloy grades for LNG terminal construction. Thyssenkrupp AG differentiates via precision forging capabilities that reduce machining waste in large-diameter pressure vessel flanges.
A flange is a mechanical disc, collar, or rim with precisely drilled bolt holes that mates two pipe sections, valves, pumps, or equipment nozzles through compressive gasket sealing, typically manufactured by forging, casting, or plate cutting with face finishes measured in roughness average (Ra) values to ensure leak-tight joints at rated pressures. ANSI-classified weld neck flanges command the dominant share in high-pressure oil and gas applications where hub taper geometry distributes bending stress into adjoining pipe walls. Socket weld configurations represent the fastest-growing connection type in smaller-bore process piping within chemical plants where space constraints favor compact joint geometry. Steel material grades retain the largest volume position, though super-duplex and Inconel alloys capture disproportionate margin pools in offshore subsea manifolds.
ASME Boiler and Pressure Vessel Code Section VIII governs design margins and hydrostatic testing protocols that determine flange selection for US-process industries, while DIN 2501 dimensional standards regulate European pipeline interoperability and procurement specifications. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS B 2220 compliance for domestic infrastructure projects, creating certification barriers for non-Japanese forging houses. China's National Institute of Standards and Technology equivalents under SAMR mandate GB/T 9112 thread specifications that diverge from ISO patterns, fragmenting sourcing strategies for multinational EPC contractors. Stakeholders must monitor divergent national standard evolution and pre-position dual-certified forging capacity before tender deadlines for cross-border pipeline projects.
Market Dynamics
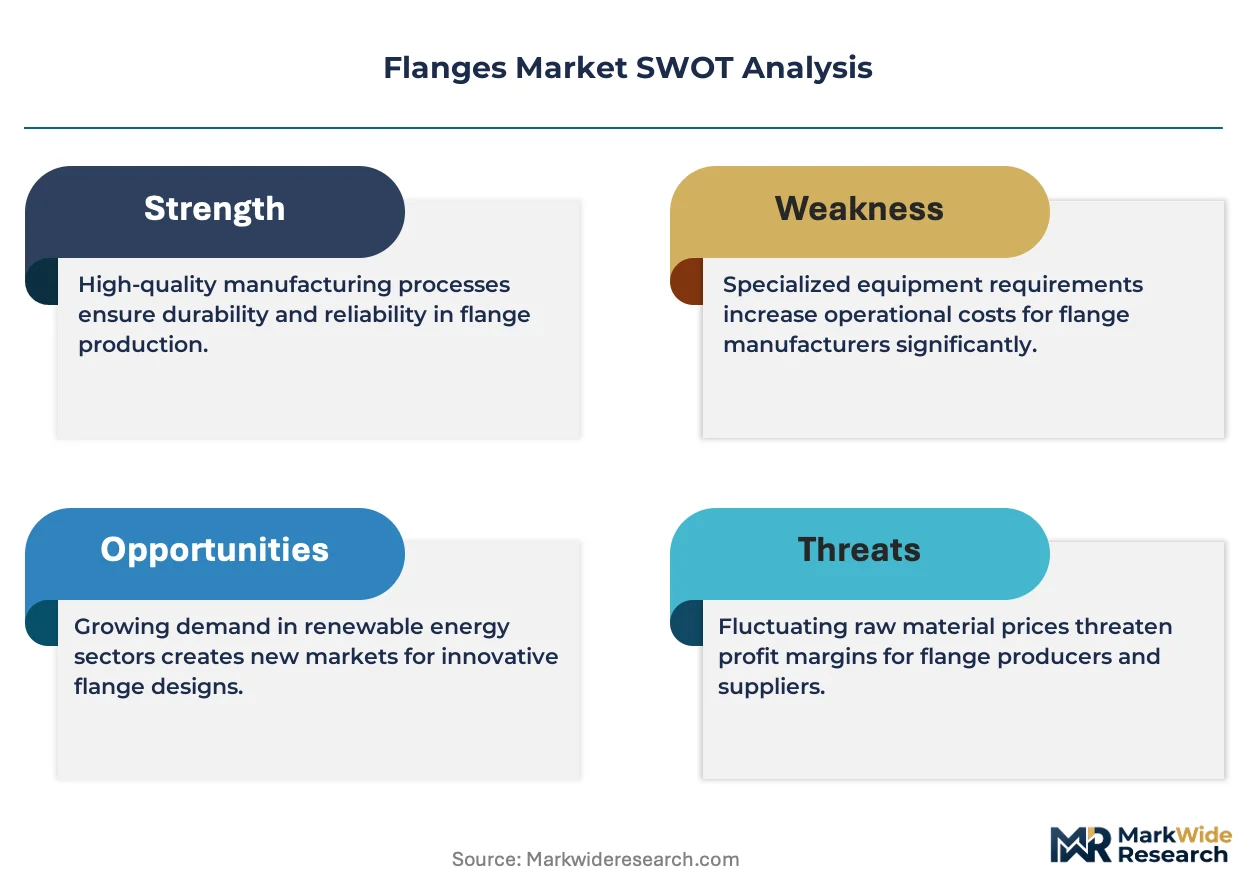
ASME Section VIII code revisions are compressing certification timelines for North American fabrication shops while simultaneously fragmenting sourcing strategies across incompatible national standards regimes.
Growth Catalysts
- Pipeline infrastructure expansion:Oil and gas operators in the United States Gulf Coast petrochemical corridor are accelerating procurement of high-pressure weld neck flanges for brownfield refinery upgrades.
- REACH chemical safety frameworks:European process industries are substituting composite polymer flanges for carbon steel in corrosive chemical environments to satisfy material compatibility mandates.
- LNG terminal construction:Ultra-low-temperature nickel alloy grades are capturing demand from cryogenic storage projects requiring metallurgical performance beyond standard specifications.
Market Restraints
- Alloy raw material volatility:Nickel and molybdenum price swings compress margin stability for super-duplex and Inconel forging operations.
- Supply concentration in legacy forging centers:Large-diameter pressure vessel flange capacity clusters in established industrial corridors with limited geographic diversification.
- GB/T 9112 specification divergence:China's thread standards fragment sourcing strategies for multinational EPC contractors bidding cross-border pipeline tenders.
Strategic Opportunities
- Offshore subsea manifolds:High-performance alloy flanges command disproportionate margin pools in deepwater production systems where failure tolerance approaches zero.
- Integrated sealing solutions:Bundled gasket-flange packages create stickier OEM relationships in hydraulic system supply chains.
- Sour service specialization:Hydrogen sulfide-resistant alloy grades open premium positioning in Middle Eastern sour gas processing installations.
Industry Challenges
- Dual-certification capacity requirements:Forging houses must pre-position ASME and DIN 2501 compliant production lines before tender deadlines for transatlantic projects.
- Precision forging capex intensity:Large-diameter flange manufacturing requires capital-intensive equipment to reduce machining waste while maintaining Ra surface finish tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flanges Market |
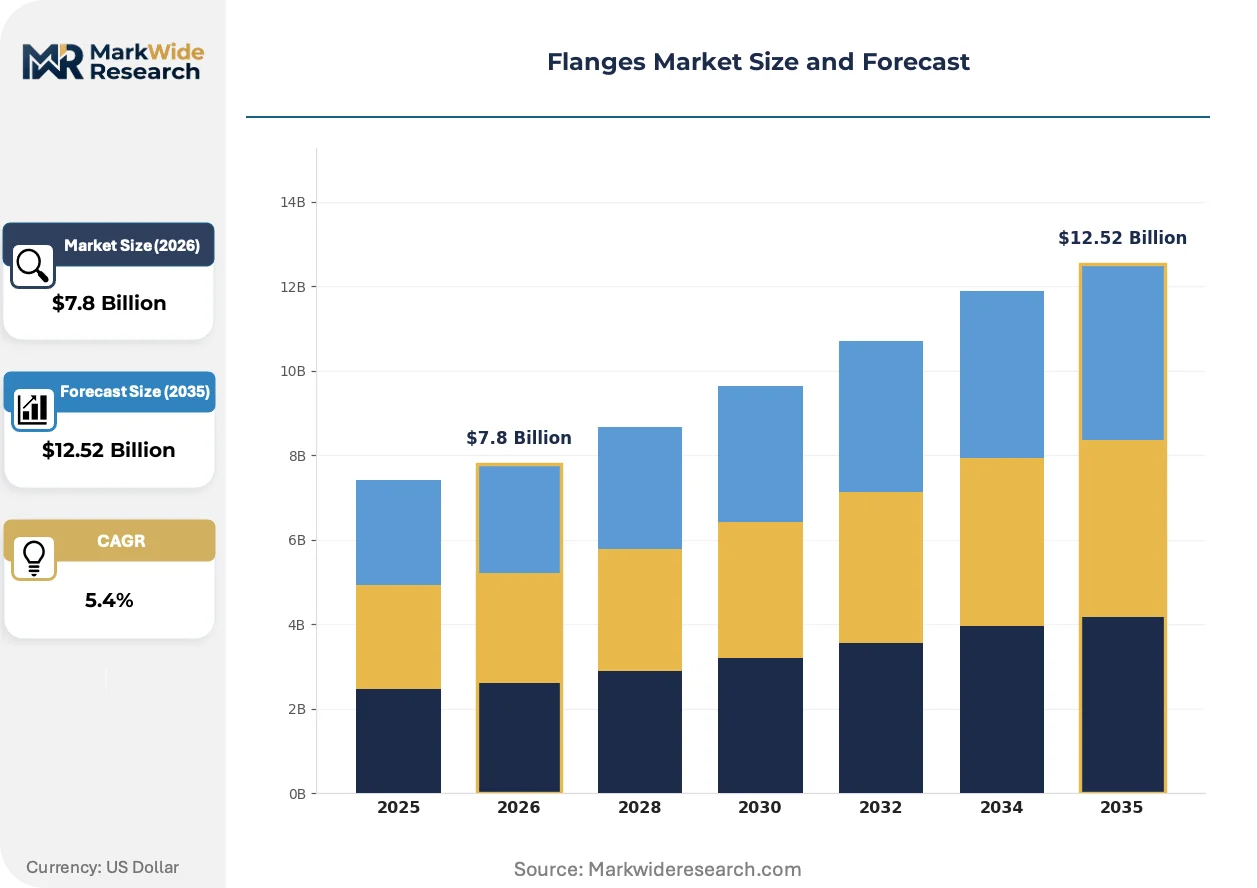
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Copper, Plastic Flange Standard: ANSI, ASME, DIN, JIS End User: Oil & Gas, Construction, Chemical Processing, Water Treatment Connection Type: Weld Neck, Blind, Slip On, Socket Weld |
| Companies Covered | Parker Hannifin, ASC Engineered Solutions, Nippon Steel Corporation, Thyssenkrupp AG, Tata Steel, ArcelorMittal, AFG Holdings (Ameriforge), Texas Flange, Georg Fischer (GF Piping Systems), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flanges Market Emerging Trajectories
Material science advances and regulatory fragmentation are simultaneously expanding performance boundaries and complicating procurement standardization across process industries.
Additive manufacturing is modularizing flange production workflows for complex geometries previously requiring multi-stage machining operations. Specialty alloy fabricators serving aerospace-adjacent process equipment are adopting directed energy deposition to consolidate weld neck hub geometries into near-net shapes. This capability is compressing lead times for prototype and low-volume sour service components.
Japan's METI enforcement of JIS B 2220 compliance is creating certification barriers for non-Japanese forging houses bidding domestic infrastructure projects. Domestic fabricators with established JIS accreditation are capturing preferential positioning in public tender processes. European and North American suppliers are responding by licensing Japanese certification partnerships rather than pursuing independent accreditation.
Specification bundling is consolidating vendor relationships as EPC contractors reduce supplier management overhead on mega-projects. Integrated flange-gasket-sealing system providers are displacing discrete component procurement in United States Gulf Coast petrochemical construction. This concentration is most visible in lump-sum turnkey contracts where single-source accountability reduces interface risk.
Flanges Market Segmentation
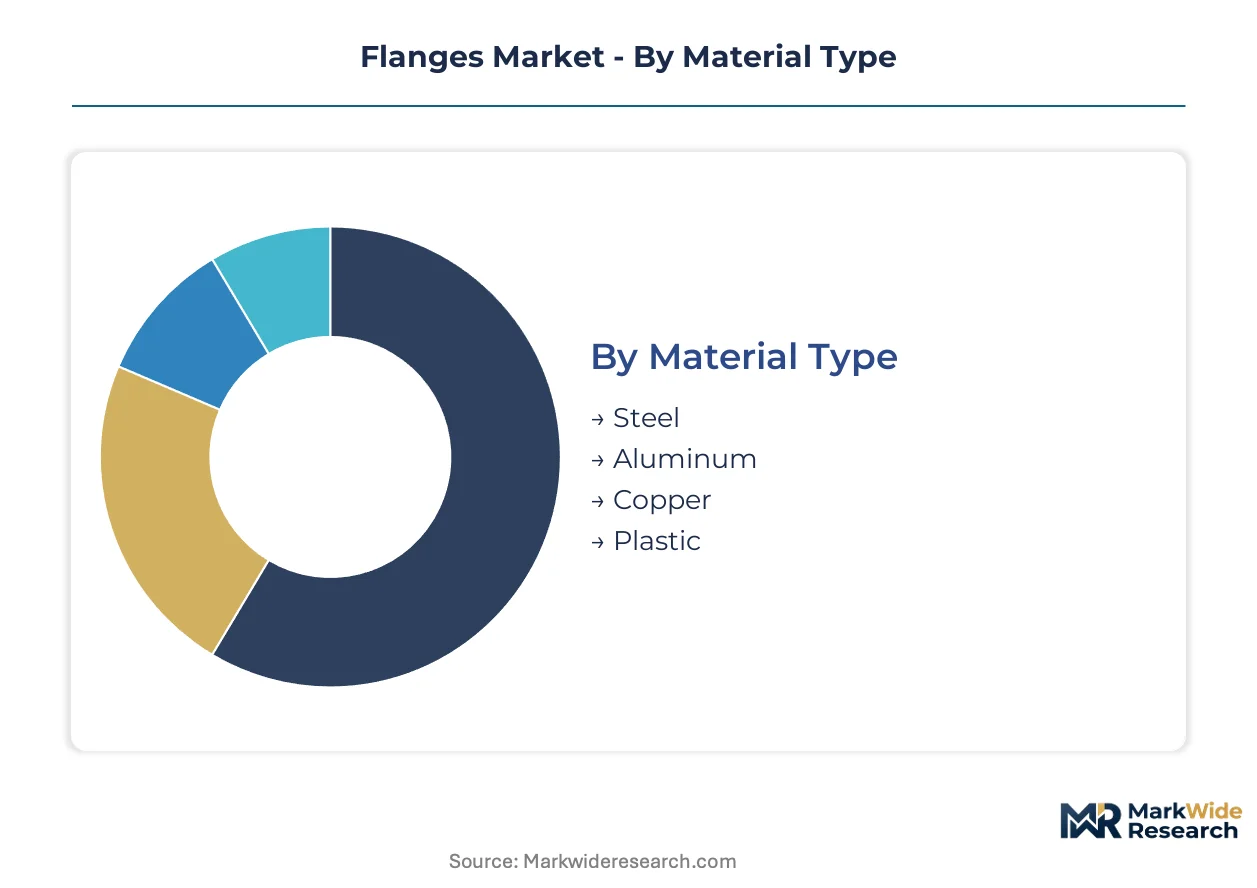
Flange procurement decisions cascade through material selection, dimensional standard, end-use application, and mechanical connection geometry. Each segmentation layer imposes distinct certification burdens and margin structures that shape vendor positioning across process industries.
Material Type:
Steel dominates volume shipments while specialty alloys capture premium positioning in demanding service environments.
- Steel:Carbon and alloy steel grades retain the largest installed base across oil and gas pipeline infrastructure. Procurement concentrates in United States Gulf Coast petrochemical corridor where brownfield refinery upgrades require high-pressure weld neck configurations certified to ASME Section VIII.
- Aluminum:Lightweight aluminum flanges serve aerospace-adjacent process equipment and marine applications where weight reduction offsets material cost premiums. Demand clusters in coastal fabrication centers serving LNG terminal construction with cryogenic performance requirements.
- Copper:Copper alloys provide thermal conductivity and corrosion resistance in heat exchanger and plumbing applications.
- Plastic:Composite polymer materials displace carbon steel in corrosive chemical processing environments where REACH chemical safety frameworks mandate material compatibility.
Mature deployment sits with Steel. Newer deployment is concentrated in Plastic.
Flange Standard:
Regulatory jurisdiction determines specification adoption, fragmenting sourcing strategies for multinational EPC contractors.
- ANSI:American National Standards Institute classifications govern North American high-pressure oil and gas applications. ANSI-classified weld neck flanges command dominant share where hub taper geometry distributes bending stress into adjoining pipe walls.
- ASME:Boiler and Pressure Vessel Code Section VIII governs design margins and hydrostatic testing protocols for US process industries. Updated code revisions compress certification timelines for fabrication shops while tightening material documentation requirements.
- DIN:German DIN 2501 dimensional standards regulate European pipeline interoperability and procurement specifications.
- JIS:Japanese JIS B 2220 compliance is enforced by METI for domestic infrastructure projects, creating certification barriers for non-Japanese forging houses.
Established procurement sits with ANSI. Expanding most quickly is JIS as Asian infrastructure investment accelerates.
End User:
Application severity dictates alloy grade selection and inspection protocol intensity across process industries.
- Oil & Gas:Pipeline infrastructure expansion accelerates procurement of high-pressure weld neck flanges for sour service applications. Demand concentrates in Middle Eastern sour gas processing installations requiring hydrogen sulfide-resistant alloy grades.
- Construction:Commercial and industrial building systems utilize standard carbon steel slip-on configurations for HVAC and fire suppression piping.
- Chemical Processing:Corrosive environments drive substitution toward composite polymer flanges and super-duplex alloys. REACH frameworks mandate material compatibility verification for European process industries.
- Water Treatment:Municipal and industrial water infrastructure employs coated carbon steel and ductile iron flanges for moderate-pressure distribution networks.
Volume concentration sits with Oil & Gas. Steepest expansion trajectory is Chemical Processing as regulatory compliance tightens material specifications.
Connection Type:
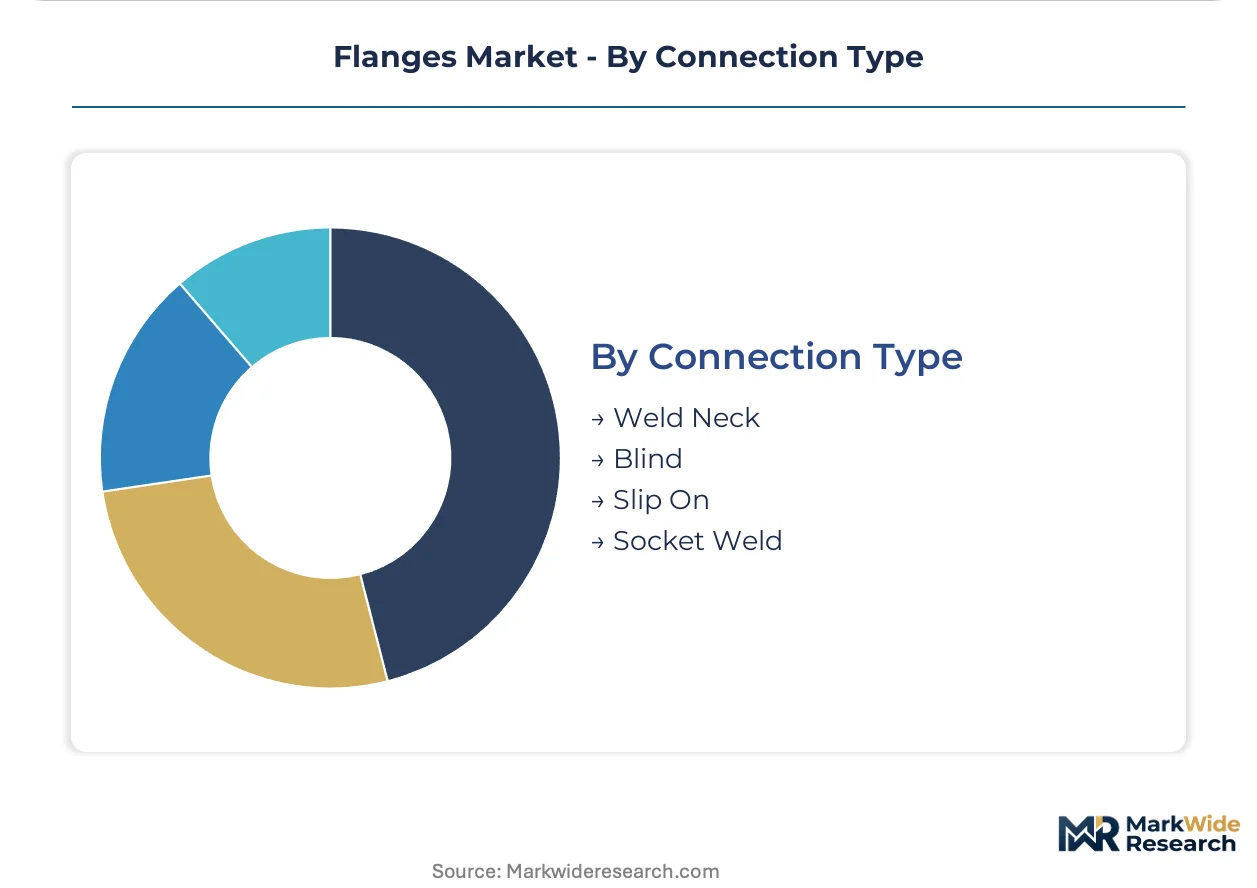
Joint geometry determines stress distribution, space requirements, and field welding complexity across piping systems.
- Weld Neck:Hub taper geometry distributes bending stress into adjoining pipe walls, making this configuration mandatory for high-cycle and high-pressure service. Dominant share in oil and gas pipeline infrastructure where failure tolerance approaches zero.
- Blind:Solid disc construction terminates piping runs and provides pressure boundary isolation for maintenance access. Standard specification across process industries for vessel and pipeline isolation points.
- Slip On:Simplified hub geometry reduces material cost and machining requirements for low-pressure applications. Common in commercial construction and water treatment infrastructure.
- Socket Weld:Compact joint geometry favors smaller-bore process piping within chemical plants where space constraints limit fitting envelope. Gaining share fastest in hydraulic system OEM supply chains through bundled gasket-flange solutions.
Established specification sits with Weld Neck. Climbing the fastest is Socket Weld as modular equipment skids proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States Gulf Coast petrochemical corridor, where brownfield refinery upgrades and LNG terminal construction drive specialized alloy flange procurement. Regulatory divergence across ASME, DIN, and JIS standards fragments sourcing strategies for multinational EPC contractors.
United States
Pipeline infrastructure expansion accelerates high-pressure weld neck flange procurement for sour service applications. ASME Section VIII code revisions compress certification timelines for domestic fabrication shops. Houston and Beaumont anchor the Gulf Coast concentration where hydrogen sulfide-resistant alloy grades command premium positioning.
Germany
DIN 2501 dimensional standards regulate European pipeline interoperability and procurement specifications for chemical processing installations. ECHA REACH frameworks mandate material compatibility verification, displacing carbon steel with composite polymer alternatives. The Ruhr industrial corridor hosts precision forging capacity for large-diameter pressure vessel applications.
China
SAMR-mandated GB/T 9112 thread specifications diverge from ISO patterns, fragmenting sourcing strategies for cross-border pipeline tenders. Domestic infrastructure investment accelerates demand for socket weld configurations in modular equipment skids. Yangtze River Delta fabrication centers scale production for both domestic and export markets.
Japan
METI enforcement of JIS B 2220 compliance creates certification barriers for non-Japanese forging houses bidding domestic infrastructure projects. Ultra-low-temperature nickel alloy grades capture demand from LNG terminal construction. Kansai and Chubu industrial regions concentrate captive metallurgical R&D for cryogenic performance specifications.
Saudi Arabia
Sour gas processing installations drive demand for hydrogen sulfide-resistant alloy grades in Middle Eastern energy infrastructure. National procurement frameworks prioritize ASME-certified suppliers for petrochemical expansion projects. Eastern Province industrial cities anchor the regional concentration for high-pressure weld neck flange deployment.
Flanges Market Vendor Landscape
Capacity expansion dominates the current landscape as forging houses pre-position dual-certified production lines before tender deadlines. The vendor base stratifies across integrated metallurgical conglomerates, precision forging specialists, and regional fabrication shops. Three archetypes occupy distinct positions: steel producers with captive flange divisions, standalone forging houses with ASME/DIN dual accreditation, and bundled sealing system providers. Geographic expansion and strategic partnerships represent the dominant competitive vectors as players navigate incompatible national standards regimes.
Among integrated industrial conglomerates, Nippon Steel Corporation and Thyssenkrupp AG exemplify the metallurgical-forward archetype, leveraging captive R&D and precision forging capabilities respectively. Parker Hannifin occupies a position within the bundled solutions tier, representing the gasket-flange integration model for hydraulic system OEMs. These three anchors illustrate how competitive positioning diverges across material science depth, manufacturing precision, and system integration vectors.
| Leading Market Players |
|---|
| Parker Hannifin |
| ASC Engineered Solutions |
| Nippon Steel Corporation |
| Thyssenkrupp AG |
| Tata Steel |
| ArcelorMittal |
| AFG Holdings (Ameriforge) |
| Texas Flange |
| Georg Fischer (GF Piping Systems) |
| Others |
Supply Flow & Price Mechanics
REACH chemical safety frameworks in Europe gate both qualified supply and premium-tier pricing access, as material compatibility mandates disqualify uncertified carbon steel fabricators while justifying polymer flange premiums in corrosive processing environments.
Pricing Analysis
Volume concentrates in carbon steel weld neck configurations for Gulf Coast refinery procurement, while margin pools accrue to super-duplex and Inconel alloy grades for offshore subsea manifolds where failure tolerance approaches zero. Price differentiation hinges on ASME Section VIII certification tier and sour service alloy grade specification, with hydrogen sulfide-resistant materials commanding substantial premiums. Cost compression in standard carbon steel grades is intensifying because Chinese GB/T 9112-certified imports fragment procurement options for multinational EPC contractors. Chemical processing operators exhibit highest price sensitivity due to REACH-driven material substitution mandates, whereas LNG terminal developers demonstrate lowest sensitivity given cryogenic performance requirements.
Supply Chain Analysis
Single-source vulnerability sits with large-diameter pressure vessel forging capacity concentrated in Germany's Ruhr corridor, Japan's Chubu region, and the United States Gulf Coast. Raw material procurement draws from nickel and molybdenum suppliers subject to commodity price volatility, specialty alloy scrap recyclers, and precision forging equipment manufacturers dominated by German and Japanese capital goods producers. Tariff exposure on alloy imports from non-FTA jurisdictions compounds margin instability for North American fabrication shops. Distribution runs through EPC contractor lump-sum turnkey contracts where bundled flange-gasket-sealing system providers displace discrete component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-certification capacity scarcity props pricing power for forging houses pre-positioning ASME and DIN 2501 compliant production lines before transatlantic tender deadlines.
For Market Incumbents: Deploy precision forging capex to reduce machining waste in large-diameter pressure vessel flanges while maintaining Ra surface finish tolerances. Backward integration into captive nickel alloy metallurgical R&D defends margin position against Nippon Steel Corporation's ultra-low-temperature grade dominance. Certification investment in JIS B 2220 accreditation through Japanese partnership licensing counters METI enforcement barriers. For New Entrants and Emerging Players: Launch via socket weld configuration specialization for modular equipment skids proliferating in chemical plant retrofits. Target composite polymer flange fabrication for European REACH compliance mandates where incumbent steel producers lack material science depth. White-space exists in sour service alloy grades for Middle Eastern hydrogen sulfide processing installations underserved by established forging centers. For Investors and Strategic Acquirers: ASME Section VIII code revision announcements are the leading indicator that certification timeline compression will consolidate fabrication shop viability across the analysis window. Acquisition targets with established dual-accreditation capacity in legacy industrial corridors offer defensive positioning. Monitor GB/T 9112 specification divergence as signal for Chinese domestic market capture versus export competitiveness trade-offs.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | Pre-positions forging houses for transatlantic EPC contractor lump-sum turnkey contracts. |
| Backward Integration into Alloy Metallurgy | Captures margin pools in ultra-low-temperature nickel grades for LNG terminal construction. |
| Integrated Sealing System Bundling | Creates sticky OEM relationships in hydraulic supply chains through gasket-flange packages. |
| Polymer Material Science Investment | Opens REACH-compliant positioning in corrosive chemical processing environments. |
| Precision Forging Technology Deployment | Reduces machining waste in large-diameter pressure vessel Ra surface finish production. |
Methodological Framework
Independent corroboration across forging house operations directors, EPC contractor procurement leads, and downstream chemical plant maintenance engineers underwrites the qualitative findings in this study. Primary interviews with ASME-certified fabrication shop managers, DIN 2501 compliance officers, and METI accreditation specialists combined with secondary validation from customs trade data, ASME Boiler and Pressure Vessel Code revision documentation, and ECHA REACH substance restriction filings. Bottom-up triangulation across material grade shipment volumes and top-down reconciliation against end-use capital expenditure patterns anchor the demand assessment.
Rate-of-change decomposition across material type, flange standard, end-use application, and connection geometry segments structures the analytical framework throughout the projection horizon. CAGRs derive from weighted average of historical shipment trajectories and forward-looking capacity expansion announcements across the modeling period. Industry-specific forecast inputs include brownfield refinery upgrade timelines in the United States Gulf Coast and LNG terminal construction permitting velocity in Asian markets.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing in complex weld neck hub geometries would alter the outlook for prototype and low-volume sour service component lead times. Deviation in nickel and molybdenum commodity price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Rupture Discs Market
Valves
Cathodic Protection Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Penstock Market
Valves
Europe Valves Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Pressure Reducing Valve Market
Valves
Global Valve Positioners Market
Valves
US Water & Wastewater Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Choke and Kill Manifold Market
Valves
Pipeline Pigging System Market
Valves
Steam Trap Valve Market
Valves
North America Residential Ball Valves Market