
 North America Residential Ball Valves Market | 2026-2036
North America Residential Ball Valves Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Ball Valves Market Analytics
The foundry-to-finish capability gap between integrated manufacturers and assembly-only suppliers is redrawing competitive boundaries in the North America residential ball valves landscape. Emerson Electric Co leverages captive brass forging operations to sustain margin stability across volatile copper cycles. Apollo Valves anchors its position through deep distributor relationships with regional plumbing wholesalers. Danfoss A/S differentiates via advanced automation in its North American valve assembly plants.
Residential ball valves are quarter-turn flow control devices utilizing a perforated sphere to start, stop, or throttle water and gas distribution in household plumbing systems, typically rated for pressures between 150 and 600 psi depending on material class and port configuration. Brass and stainless steel material segments command premium positioning due to corrosion resistance mandates under federal drinking water standards, while PVC variants occupy economy-tier retrofit applications. Standard ball valve types dominate new construction volumes, whereas multi-port configurations represent the fastest-growing category for complex residential hydronic and manifold systems.
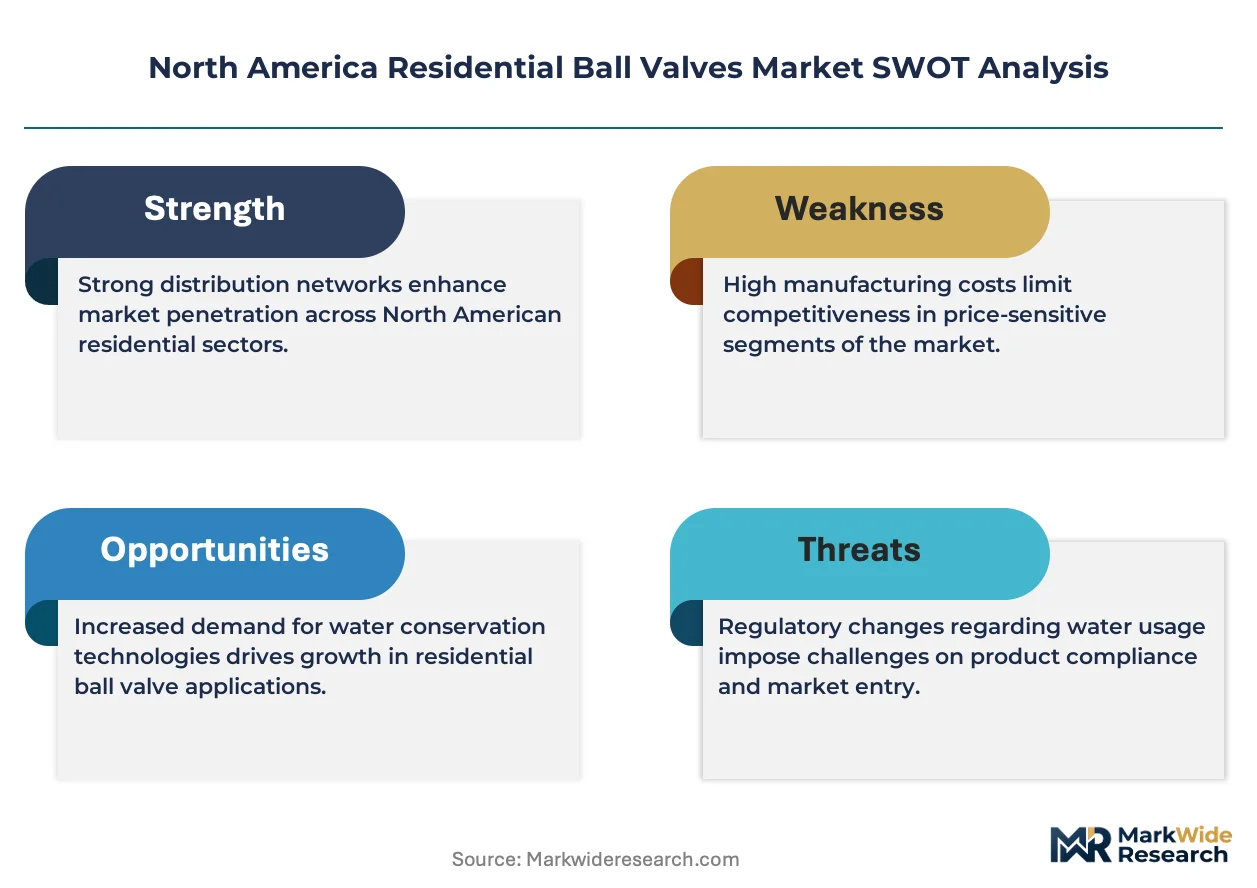
EPA Lead and Copper Rule provisions, NSF/ANSI 61 drinking water system component standards, and ASME B16.34 pressure vessel codes collectively shape product certification requirements and market access thresholds across the United States and Canada. Contractors and HVAC specialists must verify compliance documentation before specifying valves for municipal water connections. Stakeholders should monitor pending EPA regulatory revisions for lead content thresholds and state-level plumbing code adoptions that could accelerate material substitution timelines.
Market Dynamics
Lead-free alloy mandates under EPA Lead and Copper Rule revisions are forcing material transitions across brass foundries, compressing legacy supply chains while opening procurement advantages for integrated manufacturers with captive forging capabilities.
Growth Catalysts
- Sun Belt Housing Construction:Single-family home starts in Texas, Florida, and California are outpacing national averages, driving contractor demand for brass and stainless steel valve variants in new plumbing installations.
- NSF/ANSI 61 Certification Requirements:Municipal water connection standards are tightening compliance documentation, favoring suppliers with established third-party certification pipelines over uncertified imports.
- Lead-Free Alloy Technology:Bismuth and silicon brass formulations are achieving machinability parity with legacy leaded stock, enabling seamless manufacturing transitions without retooling penalties.
Market Restraints
- Copper Price Volatility:Brass input costs fluctuate with London Metal Exchange copper futures, squeezing margin stability for assembly-only suppliers lacking backward integration into forging operations.
- Regional Supply Concentration:Domestic brass forging capacity clusters in Ohio and Pennsylvania, creating geographic vulnerability to localized labor disruptions or energy price spikes.
- Technical Limitation:Lead-free alloys exhibit reduced lubricity during high-speed machining, slowing production throughput and elevating per-unit labor costs versus historical leaded stock.
Strategic Opportunities
- Hydronic Manifold Systems:Multi-port ball valve configurations for residential radiant heating represent an underpenetrated application segment with specification pull from HVAC contractors.
- Canada Provincial Adoption:Ontario and British Columbia plumbing code harmonization with NSF/ANSI 61 creates regulatory tailwinds for certified US manufacturers seeking cross-border expansion.
- Direct Contractor Platforms:Digital procurement channels are bypassing traditional plumbing wholesaler intermediaries, enabling price transparency and inventory aggregation for mid-sized mechanical contractors.
Industry Challenges
- Metallurgical Talent Scarcity:Foundry engineering expertise in lead-free alloy casting is concentrated among retiring workforces, complicating quality consistency during material transitions.
- Certification Timeline Compression:EPA regulatory revision schedules are accelerating third-party testing deadlines, straining laboratory capacity and delaying product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Ball Valves Market |
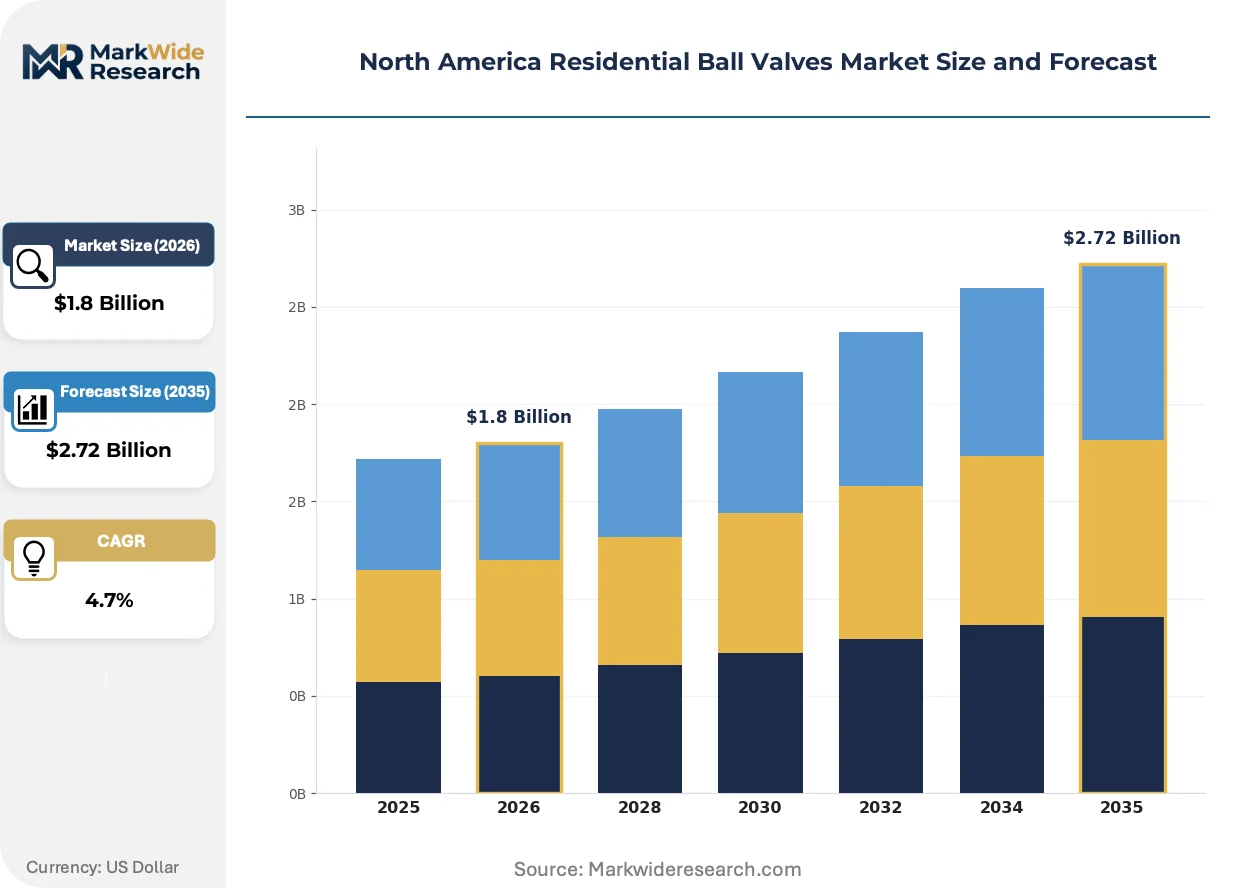
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valve Type: Standard Ball, Trunnion Ball, V-Port Ball, Multi-Port Ball Material: Brass, Stainless Steel, PVC, Bronze End User: Contractors, Plumbers, HVAC Specialists, Homeowners Installation Type: Above Ground, Underground, In-Wall, Retrofit |
| Companies Covered | ASC Engineered Solutions, Danfoss A/S, Apollo Valves, Parker Hannifin, Zurn Industries LLC, Legend Valves, Emerson Electric Co, Crane Co, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Ball Valves Market Evolving Landscape
Material science advances and procurement digitization are converging to reshape competitive positioning, with regulatory compliance emerging as the primary axis of supplier differentiation rather than price alone.
Silicon brass formulations are supplanting traditional bismuth alloys in high-pressure residential applications due to superior tensile strength and corrosion resistance. Regional plumbing wholesalers in California and Texas are specifying silicon brass for municipal connection valves ahead of code mandates. This material transition is compressing the viable supplier base to foundries with metallurgical R&D capabilities, marginalizing pure assemblers.
EPA Lead and Copper Rule provisions are tightening maximum lead content thresholds in wetted valve surfaces, triggering preemptive product redesigns across the supply base. Manufacturers with in-house spectrographic testing laboratories are accelerating compliance verification cycles versus outsourced testing dependencies. The standard ball valve segment faces the steepest recertification burden given its commodity-scale production volumes and thin margin structures.
Mechanical contractors are consolidating purchase orders through digital procurement platforms that aggregate real-time inventory across multiple distributor warehouses. This channel shift is disintermediating legacy plumbing wholesaler relationships that historically controlled specification influence. The behavioral change is most visible in Texas metropolitan markets where contractor consolidation has produced larger buying entities with sufficient volume to negotiate direct manufacturer pricing.
North America Residential Ball Valves Market Segmentation
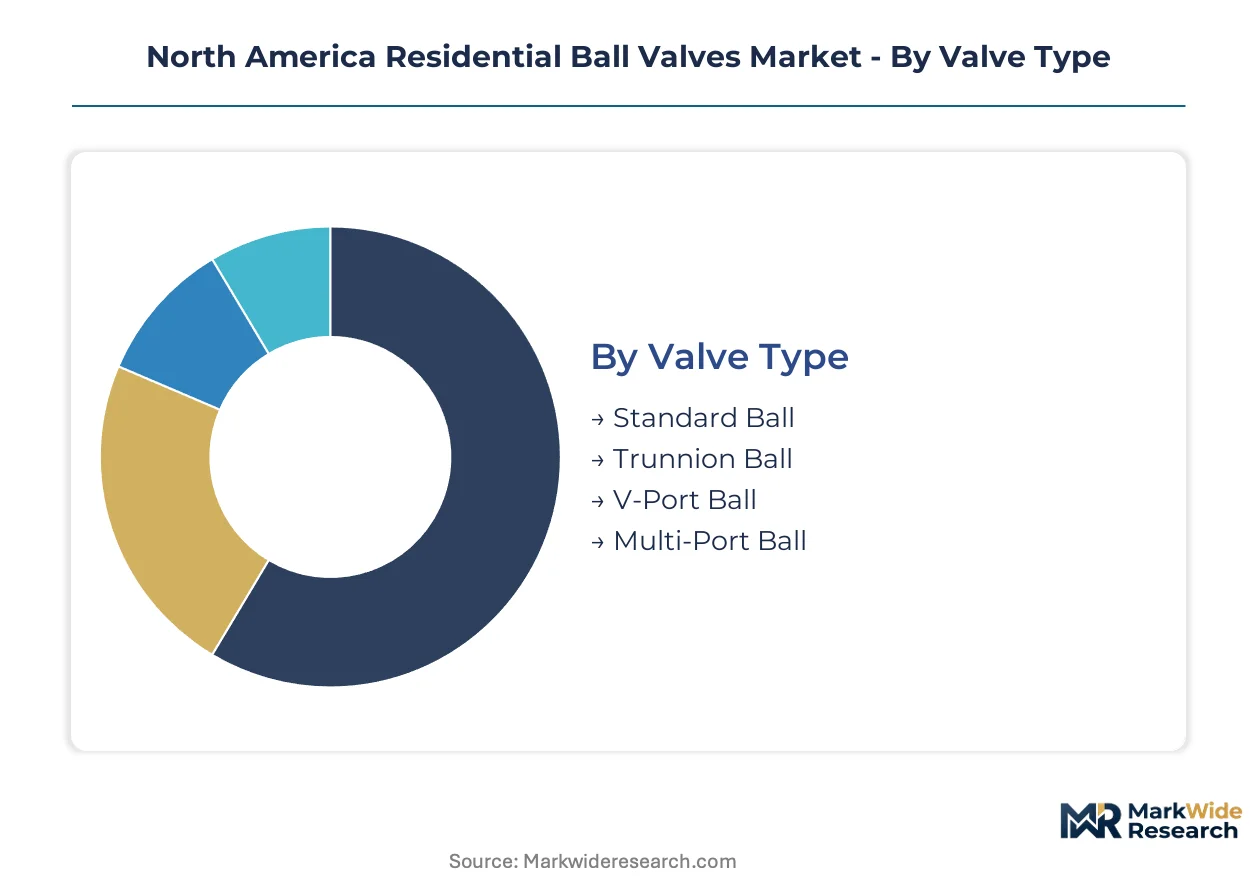
Material mandates and installation complexity create divergent substitution risks across the North America residential ball valves landscape. Segment boundaries shift as lead-free alloy transitions compress viable supplier bases while hydronic applications pull multi-port configurations into mainstream specification.
Valve Type:
Standard ball configurations face mounting pressure from multi-port alternatives in complex residential hydronic systems, while trunnion designs confront limited applicability in low-pressure household plumbing.
- Standard Ball:Quarter-turn shutoff devices with full-bore spherical closure elements dominate new construction specifications. Demand concentrates with Texas and Florida contractors installing municipal water connections in single-family subdivisions, though margin compression from commodity-scale production limits supplier differentiation.
- Multi-Port Ball:Configurations with L-port or T-port flow paths enable manifold distribution for radiant heating and recirculation systems. California HVAC specialists are specifying these for hydronic retrofits ahead of statewide efficiency mandates, creating specification pull from mechanical contractors consolidating purchase volumes.
- Trunnion Ball:Anchored sphere designs with bottom shaft support suit high-pressure commercial applications with limited residential penetration.
- V-Port Ball:Contoured orifices enable throttling control primarily in industrial process applications outside core residential demand.
Standard ball retains volume leadership; multi-port ball holds the steepest expansion curve.
Material:
Cost tier stratification separates premium metallurgy from economy polymer alternatives, with certification thresholds determining viable market participation.
- Brass:Copper-zinc alloys dominate wetted surface applications under EPA Lead and Copper Rule compliance frameworks. Bismuth and silicon formulations are achieving machinability parity with legacy leaded stock, enabling seamless foundry transitions without retooling penalties for Ohio and Pennsylvania forging operations.
- Stainless Steel:Austenitic grades deliver superior corrosion resistance for aggressive water chemistries and coastal installations. Florida plumbing codes are increasingly specifying 316-grade variants for salt-air exposure zones, compressing procurement to suppliers with captive melting capabilities.
- PVC:Thermoplastic construction occupies economy-tier irrigation and drainage retrofit segments with limited potable water certification.
- Bronze:Copper-tin alloys retain niche positioning for marine and fire suppression applications with marginal residential penetration.
Brass commands absolute volume share; stainless steel is climbing the fastest on coastal specification mandates.
End User:
Customer type concentration varies with project scale, from individual homeowner replacements to consolidated mechanical contractor procurement.
- Contractors:Production home builders and mechanical firms specify valves through distributor relationships or direct digital procurement platforms. Texas metropolitan markets exhibit the strongest contractor consolidation, producing buying entities with sufficient volume to negotiate manufacturer-direct pricing and bypass traditional wholesaler intermediaries.
- HVAC Specialists:Hydronic heating contractors drive multi-port and manifold-adjacent valve demand with technical specification authority. Ontario and British Columbia plumbing code harmonization with NSF/ANSI 61 is creating regulatory tailwinds for certified suppliers targeting cross-border expansion through mechanical specifier relationships.
- Plumbers:Service and repair technicians source through local wholesale counters with limited brand loyalty in emergency replacement scenarios.
- Homeowners:DIY purchasers represent fragmented demand through retail hardware channels with price-sensitive selection criteria.
Contractors retain volume leadership; HVAC specialists hold the steepest expansion curve.
Installation Type:
Geography and building vintage determine installation method distribution, with above-ground new construction contrasting against concealed and replacement applications.
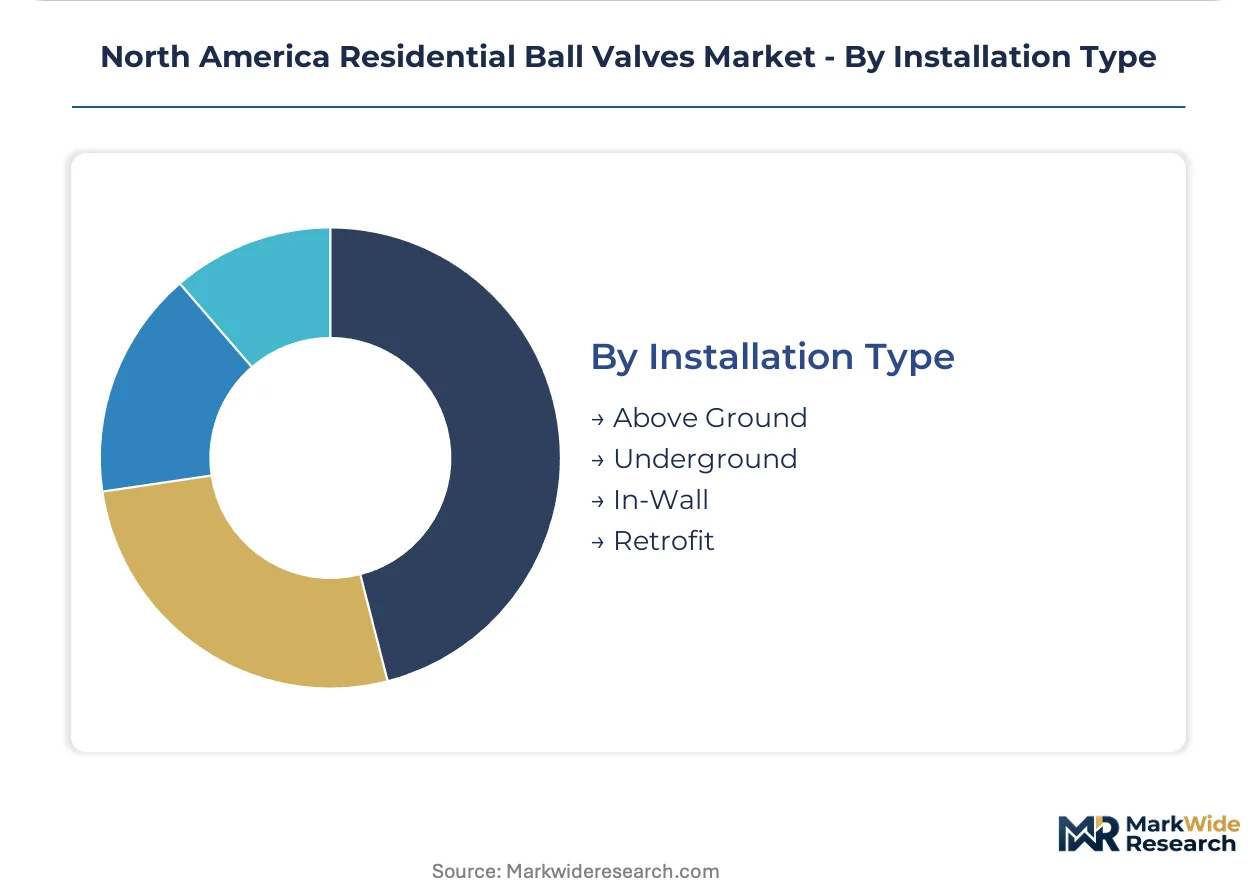
- Above Ground:Exposed installations in basements, utility rooms, and exterior wall penetrations dominate new construction volumes. Sun Belt housing starts in Arizona, Nevada, and Georgia are outpacing national averages, driving contractor demand for accessible shutoff configurations in slab-on-grade foundations.
- Retrofit:Replacement installations in existing structures require compatibility with legacy piping systems and confined workspace constraints. California's aging housing stock and water conservation mandates are accelerating fixture replacement cycles, favoring suppliers with compact valve designs and push-fit connection technologies.
- Underground:Buried service line applications require specialized corrosion protection with limited residential prevalence.
- In-Wall:Concealed installations demand access panel provisions and represent higher callback risk for installation defect liability.
Above ground retains volume leadership; retrofit holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America residential ball valves trade flow tilts toward domestic sourcing, with limited cross-border valve shipments reflecting the region's mature foundry infrastructure and stringent NSF/ANSI 61 certification barriers that favor local production over import substitution.
United States
Texas, Florida, and California housing starts outpace national averages, driving contractor procurement of brass and stainless steel variants for municipal water connections. EPA Lead and Copper Rule revisions are accelerating lead-free alloy transitions across Ohio and Pennsylvania forging clusters. Dallas-Fort Worth and Houston metropolitan areas exhibit the strongest contractor consolidation, producing buying entities with sufficient volume to negotiate direct manufacturer pricing.
Canada
Ontario and British Columbia plumbing code harmonization with NSF/ANSI 61 is creating regulatory tailwinds for certified US manufacturers seeking cross-border expansion. Health Canada drinking water guidelines are tightening wetted surface material standards ahead of federal mandate timelines. Toronto and Vancouver construction markets are pulling multi-port valve configurations for hydronic heating retrofits in aging residential stock.
Mexico
Northern border state manufacturing is expanding valve assembly operations for re-export to US markets, though domestic residential demand remains concentrated in informal construction segments with limited certification compliance. Mexican plumbing code adoption of NSF/ANSI 61 varies by municipality, creating patchwork procurement standards. Monterrey and Tijuana industrial corridors are attracting brass forging investment from US-based suppliers seeking tariff-advantaged production.
North America Residential Ball Valves Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive forging capabilities, while assembly-only suppliers face margin compression from copper price volatility and lead-free alloy transition costs. The supplier base stratifies into three archetypes: diversified industrial conglomerates with valve divisions, specialized plumbing component fabricators, and regional distributors with private-label assembly operations. Dominant competitive moves include backward integration into brass foundry operations and strategic partnerships with municipal specification authorities to secure code-compliant product positioning.
Among diversified industrial participants, Emerson Electric Co and Danfoss A/S exemplify scale-driven archetypes with multinational manufacturing footprints. Apollo Valves occupies a position within the specialized fabricator tier, anchoring distributor relationships with regional plumbing wholesalers. These three entities represent contrasting strategic postures: conglomerate resource depth versus focused channel intimacy versus European engineering heritage translated into North American assembly automation.
| Leading Market Players |
|---|
| ASC Engineered Solutions |
| Danfoss A/S |
| Apollo Valves |
| Parker Hannifin |
| Zurn Industries LLC |
| Legend Valves |
| Emerson Electric Co |
| Crane Co |
| Flowserve Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between brass foundries and integrated valve manufacturers lock in copper alloy access while insulating procurement costs from London Metal Exchange volatility. These contracts concentrate pricing power with Ohio and Pennsylvania forging operations that supply the Sun Belt construction corridor.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Certification grade under NSF/ANSI 61 and volume scale separate premium silicon brass from standard bismuth formulations and economy PVC retrofit variants. Pricing pressure stems from lead-free alloy transition costs compressing margins at commodity-scale standard ball valve producers. Homeowners and DIY purchasers exhibit highest price sensitivity; HVAC specialists specifying hydronic manifold systems demonstrate lowest sensitivity due to performance-critical applications.
Supply Chain Analysis
Great Lakes waterway transit underwrites raw material flows from Chilean copper concentrate through Ohio River Valley brass foundries. Domestic supply concentrates in Ohio, Pennsylvania, and Indiana forging clusters drawing from imported copper cathode and domestic zinc smelter output. Single-source vulnerability sits with concentrated bismuth and silicon additive suppliers in China and Kazakhstan. Distribution runs through regional plumbing wholesaler networks with emerging disintermediation via contractor-facing digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where aftermarket technical support and compliance documentation services expand faster than hardware unit growth. Recurring certification maintenance and metallurgical consulting layers outpace valve shipment volumes.
For Market Incumbents: Secure captive brass forging capabilities to defend against copper price volatility eroding assembly-only supplier margins. Deepen NSF/ANSI 61 certification pipelines to preempt EPA Lead and Copper Rule revision timelines that threaten uncertified product lines. Channel control through exclusive distributor relationships remains essential as digital procurement platforms disintermediate legacy wholesale networks. For New Entrants and Emerging Players: Aftermarket compliance documentation services for retrofit contractors represent an undersupplied layer where incumbents under-serve. Hydronic manifold specification support for California and Texas HVAC specialists offers the most penetrable entry vector. Pursue direct contractor platform partnerships bypassing traditional wholesaler gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier fabricators with captive foundry operations and established third-party certification infrastructure. The five-to-ten year viability window favors suppliers with metallurgical R&D capabilities enabling lead-free alloy transitions. Watch EPA regulatory revision schedules as the primary inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Forging | Captive supply of lead-free alloys insulates margin stability from LME copper volatility cycles. |
| NSF/ANSI 61 Certification Acceleration | Preemptive compliance with EPA Lead and Copper Rule revisions secures municipal specification access. |
| Hydronic Manifold System Partnership | Technical collaboration with HVAC contractors pulls multi-port configurations into residential heating retrofits. |
| Digital Procurement Platform Launch | Direct contractor channels bypass traditional plumbing wholesaler intermediaries in Texas metropolitan markets. |
| Silicon Brass Formulation R&D | Superior tensile strength versus bismuth alloys captures California municipal connection specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with brass foundry operations managers, regional plumbing wholesaler procurement directors, mechanical contractor purchasing agents, and EPA regulatory affairs specialists; alongside secondary validation through customs trade records, SEC manufacturing segment filings, NSF certification databases, and American Foundry Society technical publications. Bottom-up valve shipment data triangulated against top-down construction spending metrics.
Across the projection horizon, the analytical framework modeled demand by valve type, material formulation, end-user category, and installation method. CAGRs derived from housing start trajectories, alloy substitution curves, and regulatory compliance timelines. Copper price cycle assumptions and lead-free alloy penetration rates served as key sensitivity inputs.
Forecasts assume regulatory continuity in EPA drinking water standards and Health Canada guidelines; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as housing construction cyclicality and copper supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Valves in Oil and Gas Industry Market
Valves
Global Valves in Chemical Market
Valves
Mooring Inspection Market
Valves
Pulsation Dampeners Market
Valves
Ball Valves Market
Valves
Global Globe Valve Market
Valves
Global Flow Control Market
Valves
Explosion Vents Market
Valves
North America Irrigation Valves Market
Valves
Portable Valve Actuator Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Thermal Power Valve Market
Valves
GCC and MENA Valves Market
Valves
Liner Regulators Market
Valves
Sanitary Valves Market