
 Asia-Pacific Industrial Valves Market | 2026-2036
Asia-Pacific Industrial Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Valves Market Outlook
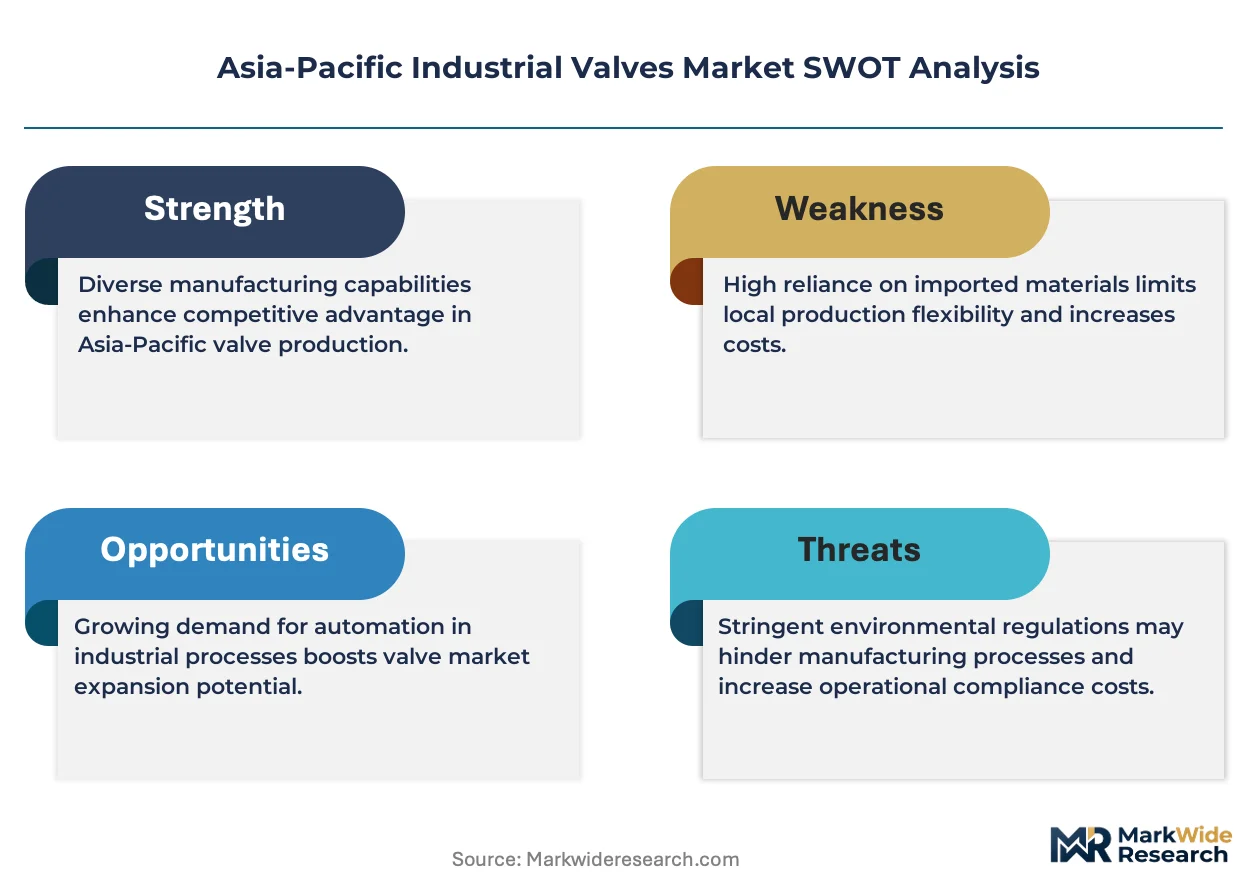
REACH compliance is decoupling low-cost suppliers from premium project pipelines across the Asia-Pacific Industrial Valves landscape. KITZ Corporation leverages its domestic Japanese manufacturing base to sustain precision casting advantages in high-pressure applications. Flowserve Corporation anchors its regional position through extensive service networks spanning Australian LNG terminals and Singaporean refining hubs. Neway Valve competes aggressively on stainless steel gate valves for Chinese nuclear expansion programs.
Industrial valves are mechanical devices that regulate, direct, or control fluid flow through pipes, tubes, or process equipment, typically constructed with pressure ratings exceeding ANSI Class 150 and designed to withstand temperatures from cryogenic ranges to over 538°C depending on metallurgy and sealing configuration. Their primary purpose is to ensure safe isolation, throttling, or check functionality across hydrocarbon, chemical, water, and steam systems. Ball valve demand leads the product type category due to quarter-turn operational efficiency and tight shutoff performance in oil and gas transmission lines. Stainless steel dominates material selection where corrosion resistance governs lifecycle economics in chemical processing and offshore environments. Gate valves retain structural importance in water treatment infrastructure where full-bore, low-pressure-drop characteristics remain non-negotiable.
Japan's METI enforces JIS standards that dictate pressure-temperature ratings and fugitive emission thresholds for valves deployed in domestic power and petrochemical facilities. China's MEE implements dual carbon compliance pathways that elevate demand for low-leakage packing systems and electric actuator retrofits. India's BIS certification requirements for critical boiler and pipeline valves create formal barriers against uncertified imports. Stakeholders must monitor how carbon border adjustments and localized content rules redistribute manufacturing footprints across Southeast Asian supply nodes.
Market Dynamics
China's dual carbon goals are compressing demand cycles for conventional pneumatic actuators while accelerating electric valve retrofits across petrochemical corridors. Japanese precision casters and Indian stainless fabricators face divergent cost pressures as carbon border adjustments reshape procurement footprints.
Growth Catalysts
- Electric Actuator Mandates:China's MEE enforces low-leakage standards that eliminate pneumatic systems from new refinery builds.
- Nuclear Expansion:Stainless steel gate valve demand concentrates in coastal Chinese provinces where reactor construction accelerates.
- REACH Compliance:ECHA chemical safety rules decouple uncertified Asian suppliers from European-linked project pipelines.
Market Restraints
- Nickel Price Volatility:Stainless steel input costs swing with Indonesian ore export quotas, compressing margin buffers for mid-tier fabricators.
- Single-Source Forging:High-pressure valve bodies depend on Japanese and Korean specialized foundries, creating geographic concentration risk.
- Legacy Pneumatic Lock-In:Existing compressed air infrastructure in Southeast Asian plants slows electric retrofit adoption despite MEE deadlines.
Strategic Opportunities
- Vietnamese Fabrication:Labor cost arbitrage and proximity to Chinese component supply chains attract valve assembly investments.
- Hydrogen Service Certification:JIS standards for high-pressure hydrogen valves create first-mover premiums for Japanese-qualified producers.
- Digital Twin Integration:Valve condition monitoring converges with predictive maintenance platforms in Australian LNG terminals.
Industry Challenges
- Welding Technician Scarcity:Certified orbital welders for nuclear-grade stainless joints command premiums that stretch project timelines.
- BIS Certification Backlogs:Indian boiler valve approvals face six-month queues, delaying critical infrastructure commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Valves Market |
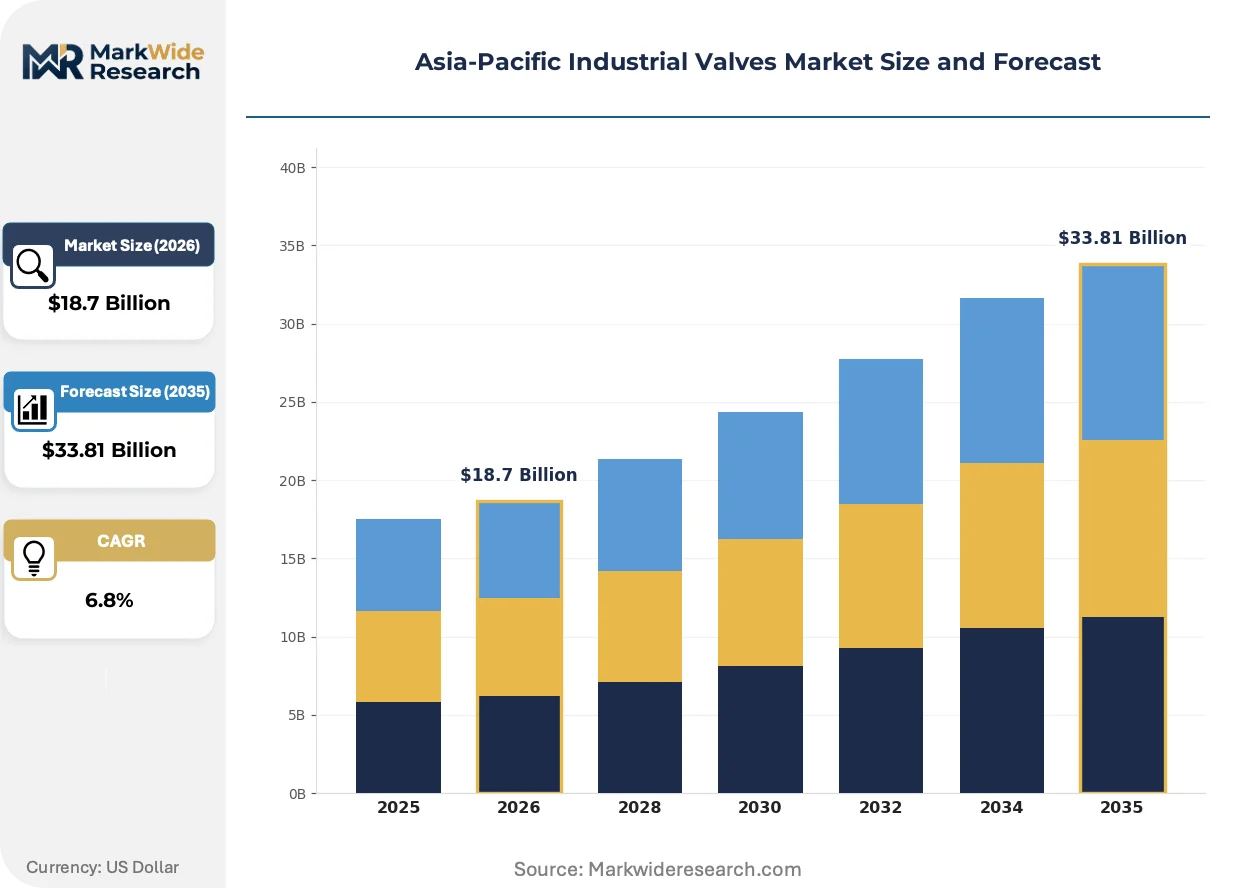
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valve, Gate Valve, Globe Valve, Check Valve Material: Stainless Steel, Cast Iron, PVC, Bronze Application: Oil & Gas, Water Treatment, Power Generation, Chemical Processing End User: Manufacturing, Energy, Construction, Mining |
| Companies Covered | Emerson Electric Co., KITZ Corporation, Flowserve Corporation, Neway Valve, IMI Critical Engineering, Crane Company, Velan Inc., Okano Valve Mfg. Co. Ltd, XHVAL Group Valve Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Valves Market Strategic Shifts
Intelligent valve architectures are displacing conventional mechanical-only designs across Asia-Pacific process industries. Three convergent developments are compressing product lifecycles and redistributing value toward software-integrated suppliers.
Smart positioners with embedded diagnostics are unifying valve control and asset management functions into single hardware platforms. Refinery operators in Singapore and Thailand deploy these systems to eliminate separate instrumentation loops. The technology is compressing maintenance intervals while shifting supplier relationships toward firmware update contracts.
Japan's METI revised JIS B 2005 standards to mandate fugitive emission testing for all valves above ANSI Class 600 in hydrogen service. The regulation forces domestic manufacturers to retool packing designs and sealing geometries. Korean petrochemical exporters must obtain METI certification to maintain access to Japanese hydrogen infrastructure projects.
Integrated service contracts now bundle valve supply with predictive maintenance analytics, displacing traditional break-fix arrangements. Australian LNG terminal operators favor suppliers offering guaranteed availability terms over upfront equipment discounts. This preference rotation concentrates procurement authority among engineering firms with in-house diagnostic capabilities.
Asia-Pacific Industrial Valves Market Segmentation
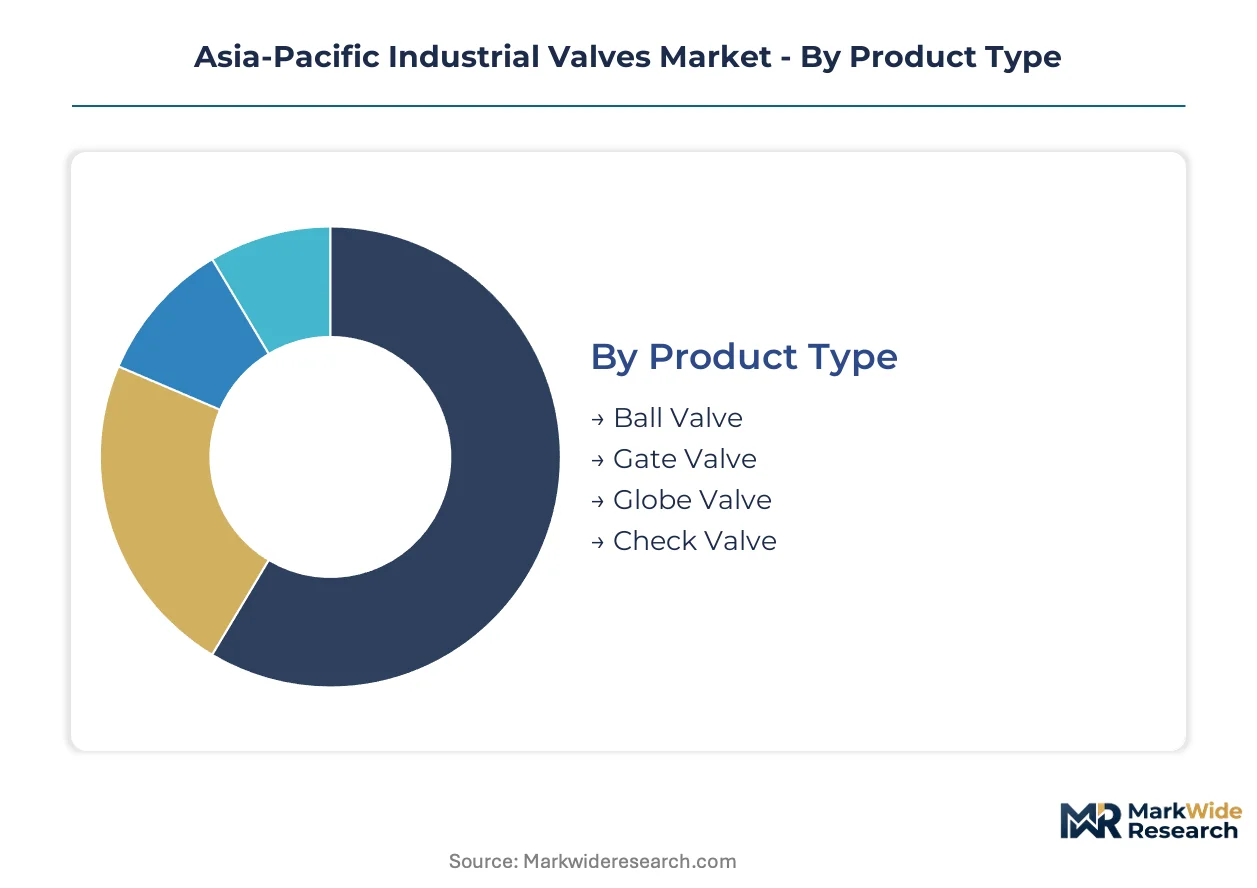
Industrial valve procurement in Asia-Pacific follows distinct technical and commercial logics that fragment supplier capabilities across pressure ratings, metallurgy, and actuation architectures. Segmentation reveals where fabrication expertise concentrates and where specification gaps create entry opportunities for specialized competitors.
Product Type:
Supply concentration in quarter-turn and multi-turn valve categories reflects divergent foundry capabilities and aftermarket service requirements across the region.
- Ball Valve:Quarter-turn design delivers tight shutoff with minimal operating torque, suited for high-cycle natural gas transmission. Demand clusters in Australian LNG export terminals and Chinese city gas distribution networks where pneumatic actuator retrofits face MEE emission deadlines.
- Gate Valve:Full-bore geometry minimizes pressure drop across steam and slurry lines, requiring precision casting for wedge and seat alignment. Nuclear expansion in Fujian and Zhejiang provinces drives stainless steel procurement from Japanese-qualified foundries with JIS B 2005 hydrogen service certification.
- Globe Valve:Throttling precision suits feedwater regulation in thermal power plants.
- Check Valve:Passive flow prevention reduces water hammer in municipal distribution systems.
Today's leader: Ball Valve. Tomorrow's challenger: Gate Valve.
Material:
Raw material sourcing geography and alloy price volatility reshape competitive positioning across corrosion-resistant and cost-optimized specifications.
- Stainless Steel:Austenitic and duplex grades withstand chloride attack in offshore platforms and chemical processing. Indonesian nickel ore export quotas compress margin buffers for mid-tier fabricators serving Indian petrochemical corridors near Gujarat.
- Cast Iron:Gray and ductile variants dominate low-pressure water infrastructure where lifecycle cost outweighs corrosion resistance. Municipal procurement in Vietnam and Thailand favors domestic foundries with BIS-adjacent quality protocols.
- PVC:Thermoplastic construction eliminates galvanic corrosion in aggressive chemical environments.
- Bronze:Naval brass alloys serve marine and desalination applications requiring biofouling resistance.
Stainless Steel commands premium positioning. Cast Iron retains volume dominance.
Application:
End-use sector maturity determines specification stringency and supplier qualification barriers across hydrocarbon, utility, and process industries.
- Oil & Gas:Exploration, production, and refining operations demand API 6D and API 600 compliance for pressure-containing equipment. Singaporean refining hubs and Australian LNG terminals anchor regional procurement with integrated service contract preferences.
- Water Treatment:Municipal and industrial purification systems require NSF-certified materials for potable contact. Chinese environmental enforcement accelerates smart valve deployments with embedded flow monitoring in Yangtze River basin treatment plants.
- Power Generation:Thermal, nuclear, and renewable energy facilities specify valves for steam, feedwater, and cooling circuits.
- Chemical Processing:Aggressive media handling necessitates alloy selection per ECHA REACH compliance pathways.
Oil & Gas sustains highest specification premiums. Water Treatment offers steepest expansion trajectory.
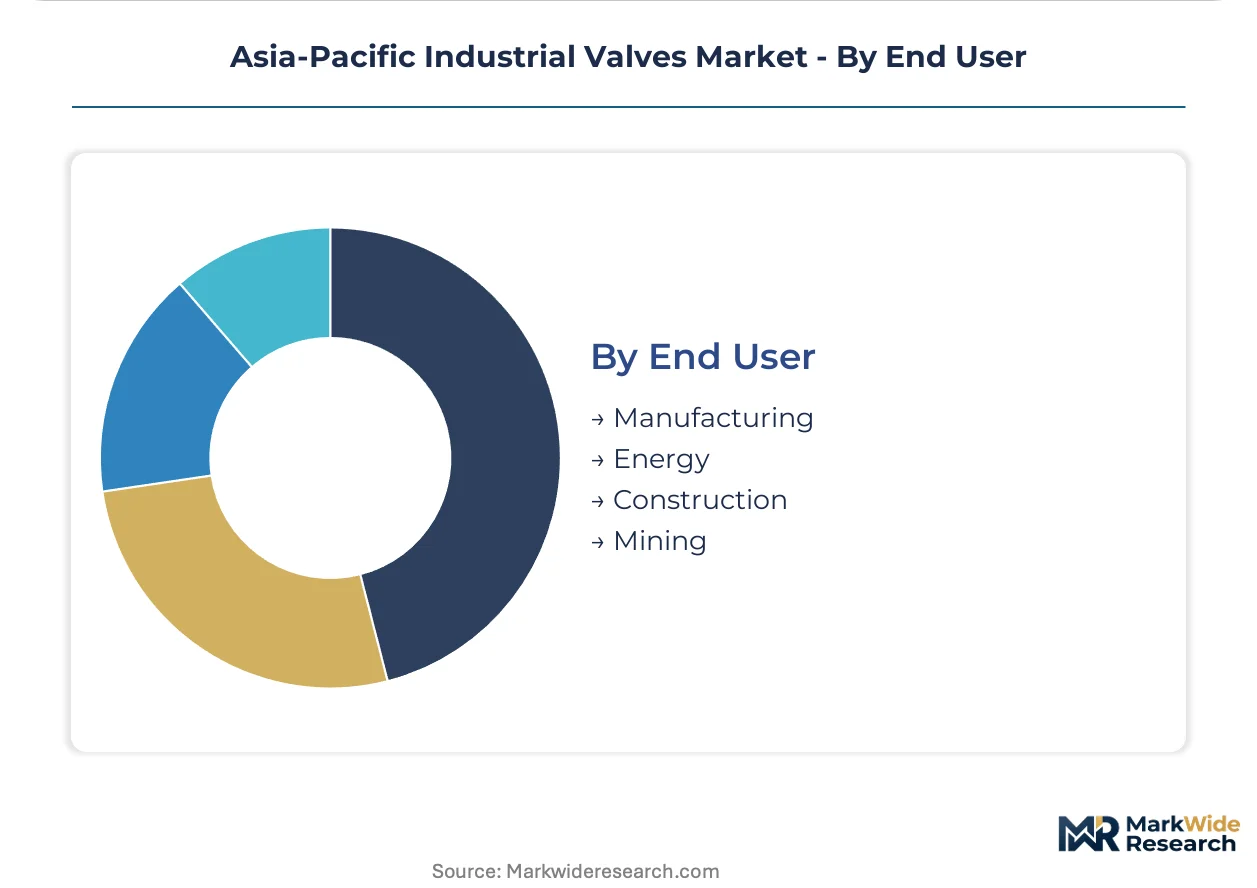
End User:
Capital investment cycles and maintenance outsourcing preferences segment demand between asset owners and engineering contractors.
- Energy:Upstream, midstream, and downstream operators prioritize guaranteed availability over upfront equipment cost. Australian LNG terminal operators favor predictive maintenance bundles from suppliers with in-house diagnostic platforms.
- Manufacturing:Process industries balance automation upgrade budgets against legacy pneumatic infrastructure. Southeast Asian chemical plants face compressed retrofit timelines under China's dual carbon influence.
- Construction:Building services and infrastructure projects specify valves for HVAC, fire protection, and plumbing systems.
- Mining:Slurry handling and dewatering operations require abrasion-resistant materials in remote site conditions.
Energy sector concentrates high-value procurement. Manufacturing segment drives retrofit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial valve manufacturing in Asia-Pacific traces its modern foundations to post-war Japan, where precision casting techniques developed for shipbuilding migrated into petrochemical equipment fabrication during the 1960s economic expansion.
China
Coastal provinces Fujian and Zhejiang drive stainless steel gate valve demand from nuclear reactor construction programs. MEE dual carbon enforcement eliminates pneumatic actuators from new refinery builds, forcing electric retrofit procurement cycles. Shanghai and Ningbo manufacturing clusters concentrate precision forging capacity for high-pressure hydrogen service valves.
Japan
Domestic precision casters sustain metallurgical advantages in ANSI Class 600-plus applications for power generation. METI revised JIS B 2005 standards to mandate fugitive emission testing for hydrogen infrastructure valves, compelling packing design retooling. Osaka and Nagoya industrial corridors anchor specialized foundry networks serving regional petrochemical exporters.
India
Petrochemical corridor demand concentrates near Gujarat and Maharashtra state boundaries where refinery expansion accelerates. BIS certification requirements for critical boiler and pipeline valves create formal import barriers with six-month approval queues. Jamnagar and Vadodara fabrication hubs face nickel price volatility from Indonesian ore export quota fluctuations.
Australia
LNG terminal operators anchor regional procurement with integrated service contract preferences over upfront equipment discounts. Predictive maintenance analytics convergence favors suppliers offering guaranteed availability terms. Perth and Darwin export facilities deploy digital twin integration for valve condition monitoring platforms.
Vietnam
Labor cost arbitrage attracts valve assembly investments from Chinese component supply chain proximity. Municipal water infrastructure procurement favors domestic foundries with BIS-adjacent quality protocols for cast iron specifications. Ho Chi Minh City and Hanoi industrial zones scale fabrication capacity for Southeast Asian distribution networks.
Asia-Pacific Industrial Valves Market Competitive Environment
The competitive structure tilts toward precision-casting specialists with certified metallurgical capabilities. Market concentration fragments across three tiers: Japanese precision foundries with JIS hydrogen certification, Chinese scale producers serving nuclear expansion programs, and regional assemblers exploiting Vietnamese labor arbitrage. Dominant competitive moves include METI certification acquisition for Japanese hydrogen infrastructure access and backward integration into Indonesian nickel sourcing to buffer stainless steel margin compression.
Among Japanese precision manufacturers, KITZ Corporation and Okano Valve Mfg. Co. Ltd occupy positions within the certified high-pressure tier, leveraging domestic foundry networks for JIS B 2005 compliance. Flowserve Corporation anchors the integrated service contract segment through Australian LNG terminal relationships. Neway Valve exemplifies the scale-driven Chinese archetype competing on stainless steel gate specifications for coastal nuclear programs. Velan Inc. and Crane Company represent North American-headquartered multinationals with regional fabrication footprints.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| KITZ Corporation |
| Flowserve Corporation |
| Neway Valve |
| IMI Critical Engineering |
| Crane Company |
| Velan Inc. |
| Okano Valve Mfg. Co. Ltd |
| XHVAL Group Valve Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese precision foundries anchor the upper tier of Asia-Pacific valve manufacturing, translating captive metallurgical expertise into pricing discipline that resists commoditization despite Chinese scale competition. Their ownership structure insulates long-term certification investments from quarterly margin pressure, while Korean and Chinese producers under state-backed or private-equity consolidation pursue volume-driven pricing to capture nuclear and petrochemical contracts.
Pricing Analysis
Three-tier pricing structure across JIS-certified premium, API-compliant standard, and unbranded economy levels governs procurement decisions in Asia-Pacific valve markets. Price differentiation hinges on METI hydrogen-service certification and stainless steel grade specifications, with Japanese-qualified producers commanding substantial premiums for nuclear-grade castings. Cost compression in mid-tier pneumatic actuator retrofits is intensifying because MEE electric-mandate deadlines force rushed procurement cycles. Municipal water authorities in Vietnam and Thailand exhibit highest price sensitivity, while Australian LNG terminal operators prioritize guaranteed availability terms over upfront equipment discounts.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai and Busan to Australian LNG terminals and Indian petrochemical corridors compresses margin buffers for just-in-time valve deliveries. Manufacturing concentrates in China, Japan, and India, with precision forging capacity anchored in Osaka-Nagoya industrial corridors and Jamnagar-Vadodara fabrication hubs. Raw material sourcing draws from Indonesian nickel ore exports, Japanese specialty steel mills, and Korean foundry feedstock. Single-source vulnerability permeates high-pressure hydrogen-service valve bodies dependent on Japanese and Korean specialized forging. Distribution runs through engineering-procurement-construction contractors with integrated service contract authority in Singaporean refining hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MEE dual carbon enforcement and Japan's METI hydrogen certification mandates continuously elevate technical barriers and reshape procurement priorities.
For Market Incumbents: Anchor defensive positioning through backward integration into Indonesian nickel sourcing to buffer stainless steel margin compression from ore export quota fluctuations. Deepen JIS B 2005 hydrogen-service certification moats against emerging Chinese scale competitors pursuing nuclear program contracts. Prioritize captive service network expansion across Australian LNG terminals where predictive maintenance bundling displaces pure equipment procurement. For New Entrants and Emerging Players: Enter via Vietnamese fabrication assembly exploiting labor cost arbitrage and proximity to Chinese component supply chains for Southeast Asian water infrastructure procurement. Target municipal cast iron specifications in Thailand and Philippines where BIS-adjacent quality protocols create accessible qualification pathways. Pursue digital twin integration partnerships with Australian terminal operators seeking valve condition monitoring capabilities without legacy service entanglements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Indian stainless fabricators facing BIS certification backlogs and nickel price volatility compression. Long-term viability favors precision-casting specialists with demonstrated METI hydrogen infrastructure access as Japanese reactor restarts and hydrogen economy buildouts accelerate. Watch JIS certification queue lengths as inflection indicator for competitive positioning shifts between Japanese incumbents and Korean challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Sourcing | Captive Indonesian ore supply buffers margin compression from export quota volatility. |
| JIS B 2005 Hydrogen Certification | METI mandate creates first-mover premiums for Japanese-qualified valve producers. |
| Electric Actuator Retrofit Programs | China's MEE deadlines force accelerated procurement cycles across petrochemical corridors. |
| Integrated Service Contract Bundling | Australian LNG terminal operators favor guaranteed availability over equipment discounts. |
| Vietnamese Assembly Footprint Expansion | Labor arbitrage and Chinese component proximity attract regional distribution investments. |
Study Parameters
Coverage spans China, Japan, India, Australia, and Vietnam, with primary inputs from each market's valve procurement decision-makers. The analysis combines structured interviews with plant engineers at petrochemical facilities, procurement leads at Australian LNG terminal operators, maintenance directors at Indian refineries, and aftermarket service heads at Japanese precision foundries. Secondary validation draws from customs trade data, METI regulatory filings, BIS certification records, and SEC disclosures from listed valve manufacturers. Bottom-up demand aggregation across end-use segments triangulates against top-down industrial capacity assessments.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. The analytical framework models segmentation dimensions including valve product type, material grade, application sector, and end-user procurement sophistication. CAGRs derive from fitted trend analysis incorporating nuclear expansion timelines, refinery retrofit cycles, and municipal water infrastructure investment patterns. Industry-specific inputs include MEE enforcement trajectory for electric actuator mandates and JIS certification queue dynamics for hydrogen-service valves.
The model holds under continued dual carbon policy enforcement and stable nickel ore export regimes; deviation in regulatory timelines or Indonesian mining policy would shift demand trajectories. Forecasts reflect documented assumptions about certification backlog resolution and freight cost normalization. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Axial and Radial Seals Market
Valves
Choke Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Pipeline Pigging Equipment Market
Valves
Europe Butterfly Valve Market
Valves
Global Gas Pressure Regulator Market
Valves
Gate Impellers Market
Valves
Butterfly Valves Market
Valves
Total Containment Vessels Market
Valves
Global Level Gauge Market
Valves
Portable Valve Actuator Market
Valves
Middle East and Africa Machined Seals Market
Valves
Pressure Control Equipment Market
Valves
Carbon Seal Rings Market
Valves
Choke and Kill Manifold Market
Valves
Valve Seat Inserts Market