
 North America Butterfly Valve Market | 2026-2036
North America Butterfly Valve Market Size, Share, and Industry Trends Forecast 2026-2036
North America Butterfly Valve Market Intelligence
Modular valve-actuator bundling is broadening procurement options for North American buyers seeking integrated flow control packages. Emerson Electric Co. leverages its automation portfolio to anchor premium bundled offerings across process industries. Flowserve Corporation competes through specialized sealing technologies for severe service conditions. Bray International sustains manufacturing scale advantages in standardized wafer and lug configurations.
A butterfly valve is a quarter-turn rotational motion valve employing a disc-mounted shaft to regulate, throttle, or isolate fluid flow in piping systems, typically rated for pressures from 150 to 600 psi and temperatures spanning -20°F to 450°F depending on seat material and body construction. Its compact face-to-face dimension and lower weight relative to gate or globe alternatives make it the default choice for large-bore water transmission and HVAC applications. Stainless steel material grades command margin premiums in chemical processing and offshore environments where chloride corrosion resistance proves critical. Wafer-style configurations represent the highest volume category due to cost efficiency in municipal water infrastructure, while double-flanged variants capture project value in power generation cooling systems.
EPA drinking water regulations, ASME B16.34 pressure vessel standards, and API 609 pipeline valve specifications collectively dictate product certification requirements and testing protocols for North American suppliers. The EPA's evolving Lead and Copper Rule mandates accelerate replacement schedules for legacy valve installations in municipal distribution networks. Buyers must weigh total lifecycle cost against upfront procurement expense as regulatory compliance timelines compress and material traceability requirements intensify.
Market Dynamics
The EPA's Lead and Copper Rule revisions are compressing municipal replacement timelines across the United States, forcing water utilities to accelerate valve procurement while navigating material certification requirements and supply bottlenecks for lead-free bronze alloys.
Growth Catalysts
- Water Infrastructure Modernization:The EPA's Lead and Copper Rule mandates drive replacement cycles for legacy distribution valves across aging municipal networks. Utilities face compressed procurement windows.
- Petrochemical Capacity Expansion:The US Gulf Coast corridor sustains demand for severe-service butterfly valves in ethylene crackers and LNG export terminals. Corrosion-resistant alloy specifications intensify.
- Smart Actuator Integration:Digital positioners and predictive diagnostics are electrifying traditional mechanical valve assemblies. Water treatment plants adopt remote monitoring capabilities.
Market Restraints
- Copper and Nickel Price Volatility:Bronze and stainless steel alloy costs fluctuate with London Metal Exchange pricing. Foundries pass through material premiums with 60-90 day lags.
- Domestic Foundry Concentration:Specialty valve casting capacity concentrates in Pennsylvania, Ohio, and Wisconsin. Geographic clustering creates weather and labor disruption exposure.
- Ball Valve Substitution:Zero-leakage metal-seated ball valves capture critical isolation applications in chemical processing. Tight shutoff specifications favor spherical closure elements.
Strategic Opportunities
- Mexico Industrial Water Treatment:Nearshoring manufacturing expansion drives cooling water system investments in Querétaro and Nuevo León. ASME-compliant valve demand rises.
- Hydrogen Pipeline Adaptation:Blending infrastructure for power generation requires high-cycle butterfly valves with modified sealing geometries. Embrittlement-resistant materials emerge.
- Buy America Compliance Services:The Bipartisan Infrastructure Law's domestic content rules create value-add bundling for certification documentation and melt-source traceability.
Industry Challenges
- Weld Procedure Qualification Bottlenecks:ASME Section IX certified welders for specialty alloy valve bodies remain scarce. Training cycles extend 18-24 months.
- Legacy System Integration Complexity:Municipal SCADA networks built on 1990s protocols resist modern digital valve actuator integration. Retrofit engineering costs escalate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Butterfly Valve Market |
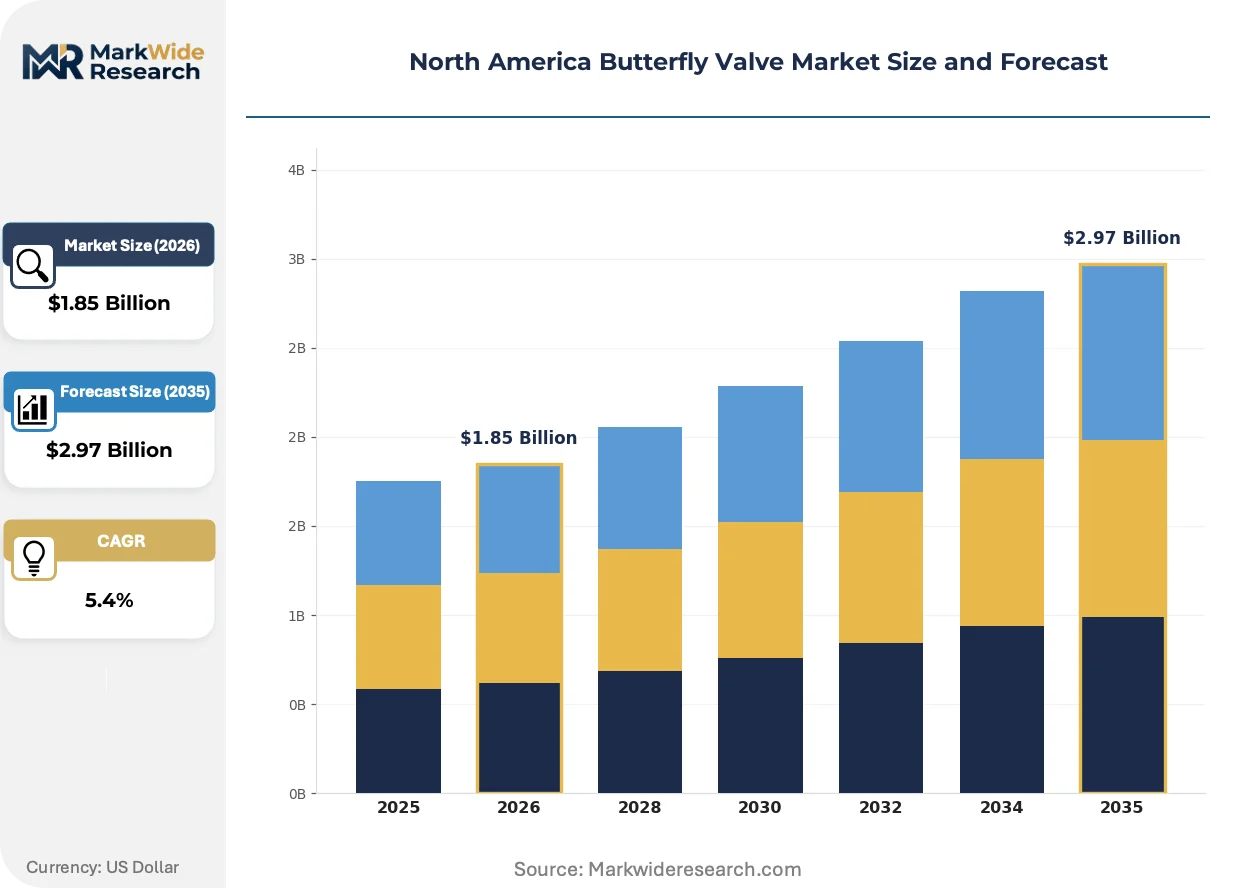
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flanged, Wafer, Lug, Double Flanged Material: Cast Iron, Stainless Steel, PVC, Carbon Steel End User: Water Treatment, Oil & Gas, Power Generation, Chemical Processing Size: 2 In, 4 In, 6 In, 8 In |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Bray International, NIBCO INC., Crane Co., AVK Group, ITT Inc., Velan Inc., Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Butterfly Valve Market Strategic Shifts & Innovations
Electrification of valve actuation and compressed compliance timelines are reshaping product specifications across North American water and process industries. Suppliers must now engineer for digital connectivity and material traceability simultaneously.
Electro-hydraulic actuator systems are electrifying traditional pneumatic and manual valve operations in remote water transmission stations. Mid-size utilities across Texas and Arizona adopt solar-powered actuation packages for isolated pump stations. This electrification is compressing maintenance visit frequencies while enabling centralized flow management from regional control centers.
The EPA's Lead and Copper Rule Improvements mandate full lead service line replacement within ten years, accelerating demand for certified low-lead bronze valve components. Foundries must retool pour chemistry and document melt sources under tightened alloy verification protocols. Municipal procurement departments in Illinois and Michigan face the steepest compliance curves as legacy inventory depletes.
Integrated valve-actuator-digital twin packages are displacing component-level procurement in large water treatment facilities. Engineering-procurement-construction firms specify pre-commissioned smart valve skids to reduce field integration risk. This bundling trend concentrates in California and Pacific Northwest desalination projects where remote operability requirements are most stringent.
North America Butterfly Valve Market Segmentation
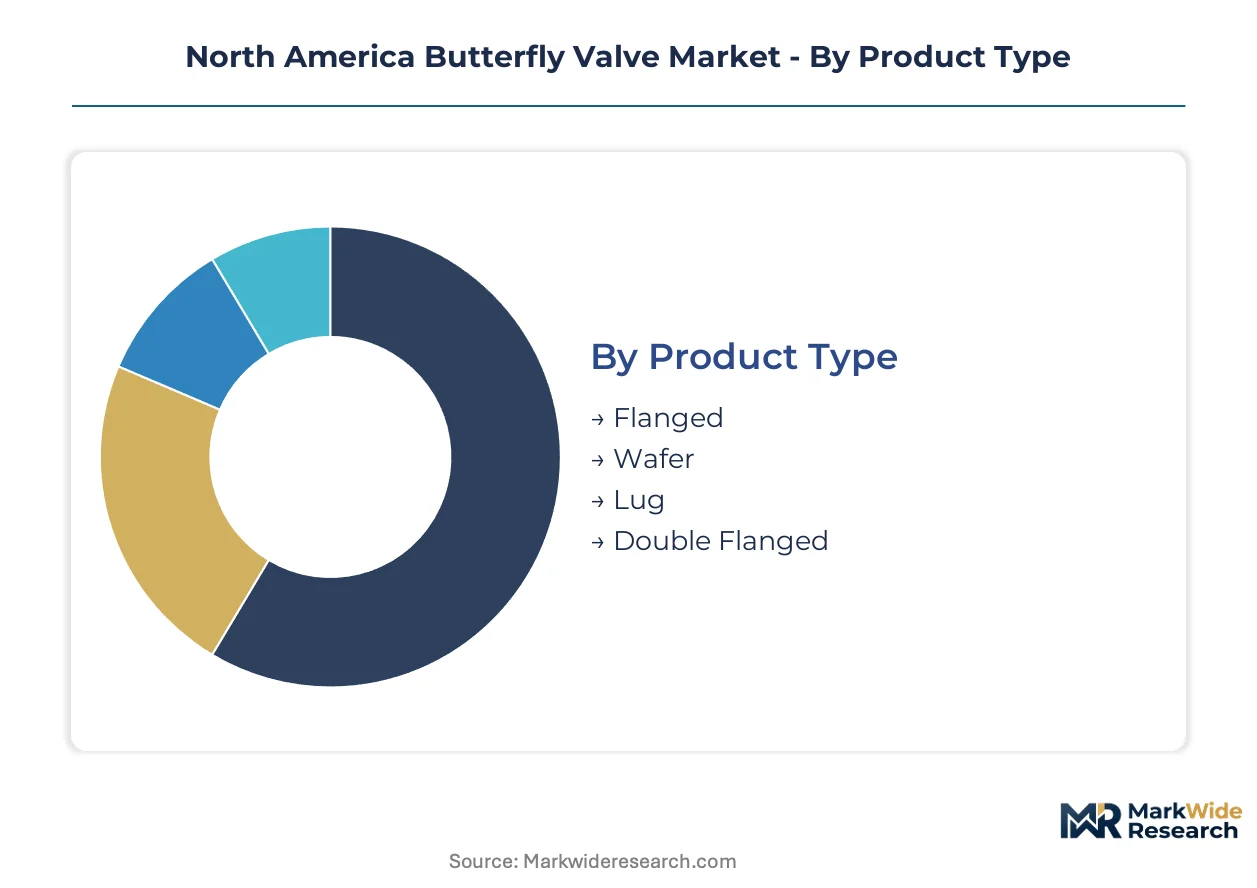
Butterfly valve procurement patterns diverge sharply across construction geometry, metallurgy, and end-use severity. Specification engineers weight first cost against lifecycle performance differently in municipal water networks versus Gulf Coast petrochemical complexes.
Product Type:
Foundry capacity for specialized castings clusters in Pennsylvania, Ohio, and Wisconsin, creating geographic supply bottlenecks during weather disruptions.
- Wafer:Thin profile between mating flanges minimizes weight and material cost for large-bore water transmission lines. Texas and Arizona utilities specify wafer configurations for isolated solar-powered pump stations where maintenance access is limited.
- Double Flanged:Bolted connection at both faces withstands thermal cycling and pressure pulsation in power generation cooling systems. California desalination projects specify pre-commissioned double-flanged skids with integrated digital positioners.
- Flanged:Single-flange mounting suits retrofit applications where pipeline alignment tolerances are relaxed. Standardized face-to-face dimensions ease replacement of legacy gate valves in Illinois municipal networks.
- Lug:Threaded inserts enable dead-end service and downstream piping removal without system shutdown. Chemical processors in Louisiana specify lug bodies for batch reactor isolation duties.
Wafer configurations absorb the bulk of installed capacity; double-flanged variants are expanding most quickly in severe-service specifications.
Material:
Cost stratification follows alloy complexity and corrosion resistance requirements, with foundry-grade cast iron anchoring the entry tier and super-austenitic stainless steels commanding project premiums.
- Cast Iron:Gray and ductile iron grades dominate municipal water distribution for pressures below 250 psi. EPA Lead and Copper Rule compliance is forcing chemistry shifts toward lead-free formulations at Midwest foundries.
- Stainless Steel:Austenitic 316 and duplex 2205 grades resist chloride attack in offshore platforms and coastal desalination plants. Nickel price volatility on the London Metal Exchange compresses foundry margins with 60-90 day passthrough lags.
- Carbon Steel:WCC and LCC castings suit high-pressure steam and hydrocarbon service with protective coatings. ASME B16.34 certification requirements limit supplier qualification to established pressure vessel foundries.
- PVC:Thermoplastic construction eliminates corrosion in aggressive water chemistries and ultraviolet-exposed outdoor installations. Querétaro and Nuevo León industrial parks specify PVC for cooling tower makeup systems in nearshoring manufacturing expansion.
Cast iron retains the largest installed base; stainless steel is gaining share fastest in corrosive service specifications.
End User:
Customer concentration varies by capital cycle timing, with water infrastructure mandates driving near-term procurement compression against longer petrochemical investment horizons.
- Water Treatment:Municipal utilities and industrial water facilities specify resilient-seated valves for raw water intake through finished water distribution. The EPA's ten-year lead service line replacement mandate accelerates procurement timelines for Illinois and Michigan municipalities.
- Oil & Gas:Pipeline transmission and LNG export terminals require fire-safe metal-seated designs with API 609 certification. US Gulf Coast ethylene cracker expansions sustain demand for cryogenic and high-cycle butterfly configurations.
- Chemical Processing:Aggressive media handling demands exotic alloy trim and specialized sealing geometries. Hydrogen blending infrastructure for power generation is emerging as a specification driver for embrittlement-resistant materials.
- Power Generation:Cooling water systems and scrubber applications specify double-flanged bodies for thermal expansion accommodation. Combined-cycle gas turbine plants in Texas favor quick-opening butterfly valves for heat recovery steam generator isolation.
Water treatment commands the dominant share of unit volume; oil and gas maintains the steepest expansion trajectory in project value terms.
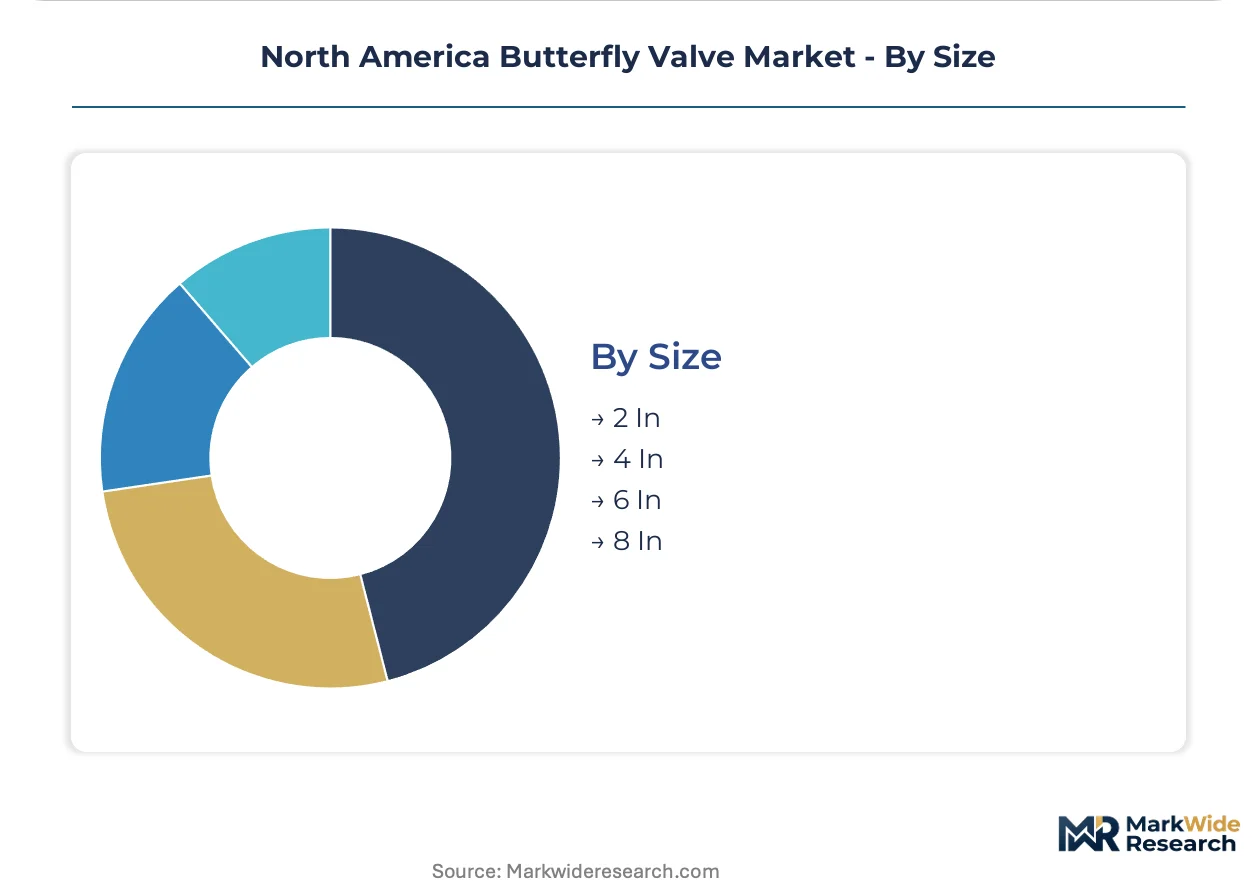
Size:
Dimensional standardization around ANSI flange classes simplifies procurement, though custom large-bore fabrications require specialized welding qualification extending 18-24 months.
- 6 In:Mid-range diameter balances flow capacity with actuator torque requirements across HVAC and secondary process lines. Standardized inventory positions at major distributors reduce lead times for maintenance replacements.
- 8 In:Large-bore specification for main transmission headers and cooling water supply manifolds. Weight and handling complexity favor crane-accessible installations in permanent facilities over remote pump stations.
- 4 In:Branch line and equipment isolation duty in chemical skids and package treatment plants. Compact face-to-face dimension enables dense piping layouts in modular construction.
- 2 In:Small-bore instrumentation and sampling connections where quarter-turn operation simplifies automation. Limited to low-torque resilient-seated designs due to disc inertia constraints.
Six-inch sizes carry the highest shipment volume; eight-inch specifications are climbing fastest in power generation and desalination project awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the US industrial Midwest while consumption spreads across municipal water networks and Gulf Coast petrochemical corridors. Canadian foundries supply specialty castings to northern utilities. Mexican manufacturing expansion drives cooling water infrastructure demand.
United States
The EPA's Lead and Copper Rule mandates compress replacement timelines for legacy bronze valves across aging municipal distribution networks. Water utilities in Illinois and Michigan face the steepest compliance curves as inventory depletes. The Gulf Coast petrochemical corridor sustains demand for severe-service configurations in ethylene cracker and LNG export terminal projects.
Canada
Provincial water infrastructure programs in Ontario and Quebec accelerate valve procurement for treatment plant modernization. Health Canada's guidelines on lead in drinking water align with US EPA timelines, forcing chemistry shifts at domestic foundries. Alberta's oil sands operations specify cryogenic butterfly valves for bitumen processing and steam-assisted gravity drainage systems.
Mexico
Nearshoring manufacturing expansion in Querétaro and Nuevo León drives cooling water system investments for automotive and electronics assembly plants. ASME-compliant valve demand rises as multinational engineering-procurement-construction firms specify standardized packages. The Comisión Federal de Electricidad's combined-cycle power plant builds favor quick-opening configurations for heat recovery steam generator isolation.
North America Butterfly Valve Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The market structure consolidates around three to four dominant integrated flow control providers while mid-scale fabricators capture standardized municipal specifications. Strategic archetypes include automation-anchored conglomerates, severe-service alloy specialists, and high-volume standardized manufacturers. Competitive moves center on modular valve-actuator bundling and domestic content certification services under Buy America compliance rules.
Among US-based diversified industrials, Emerson Electric Co. and Flowserve Corporation anchor premium-tier positioning through integrated automation portfolios and specialized sealing technologies. Bray International exemplifies the scale-driven standardized manufacturer archetype, sustaining manufacturing advantages in wafer and lug configurations for municipal water infrastructure. These three companies represent the dominant competitive vectors: bundled smart valve systems, severe-service alloy engineering, and cost-optimized standardized production.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Bray International |
| NIBCO INC. |
| Crane Co. |
| AVK Group |
| ITT Inc. |
| Velan Inc. |
| Schlumberger Limited |
| Others |
Cost & Logistics Intelligence
Compressed municipal procurement timelines under EPA Lead and Copper Rule mandates are forcing foundries to absorb expedited delivery premiums while buyers face alloy certification surcharges. This demand-side pressure concentrates pricing power among domestic suppliers with verified melt-source documentation and ASME-certified welding capacity.
Pricing Analysis
Margin tightening in standard-grade cast iron configurations reflects foundry concentration in Pennsylvania, Ohio, and Wisconsin coupled with weather-related production disruptions. Three-tier pricing structure across premium severe-service alloys, ASME-certified standard grades, and economy municipal specifications governs procurement. Price differentiation traces to certification tier and material traceability depth. Cost compression accelerates in wafer-style volumes as Bray International and NIBCO compete on scale. Municipal utilities exhibit highest price sensitivity; Gulf Coast petrochemical operators prioritize alloy performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Chicago, and Toronto anchor hub-and-spoke patterns serving municipal utilities and industrial contractors with 48-hour emergency replacement capability. Foundry-grade castings draw from concentrated US Midwest capacity with Canadian specialty alloy supplements. Raw material dependencies span London Metal Exchange-tracked nickel and copper for bronze formulations, plus ductile iron pig from domestic blast furnaces. Single-source vulnerability concentrates in ASME Section IX certified welders for specialty alloy valve bodies. Distribution runs through authorized distributor networks with integrated actuator bundling services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
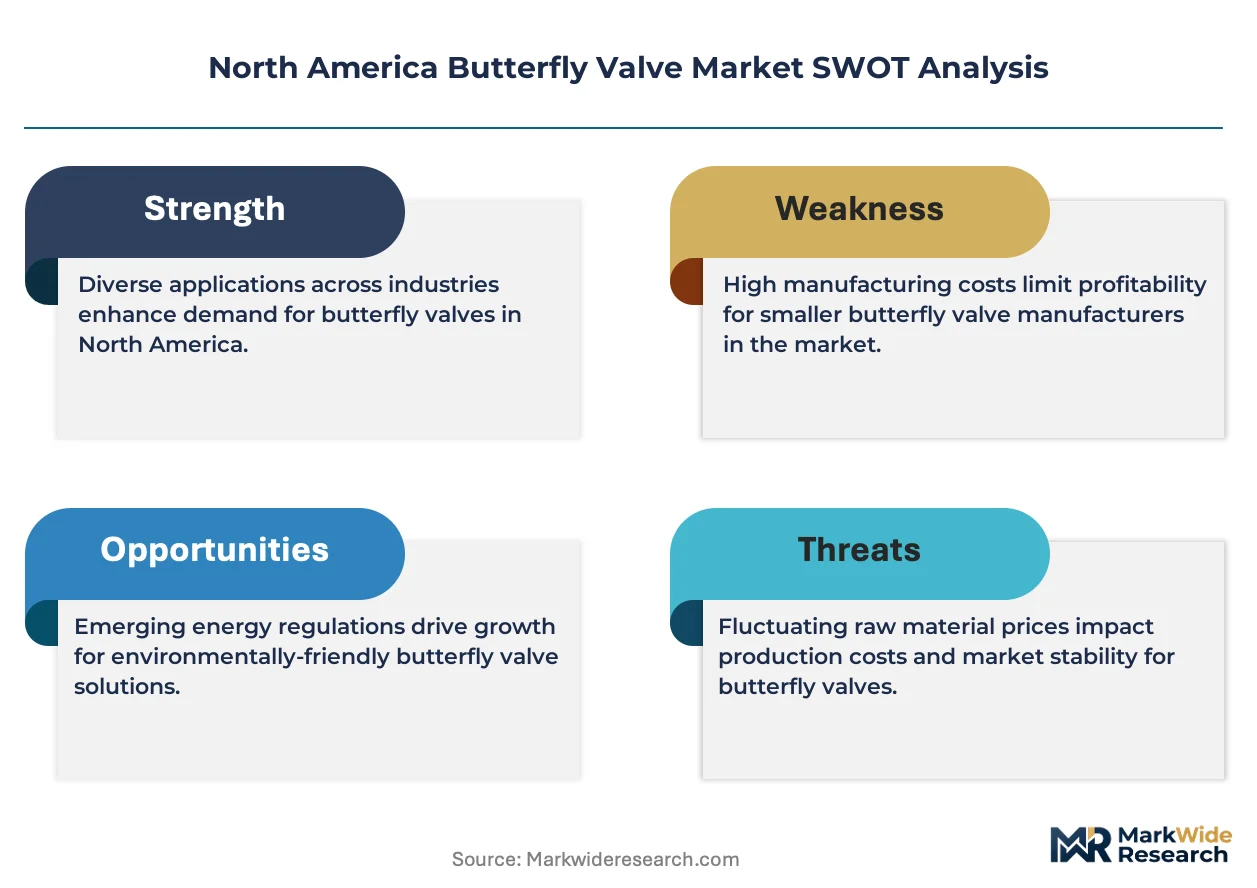
EPA compliance mandates and smart actuator integration requirements are consolidating procurement around suppliers with dual capabilities in material certification and digital connectivity, squeezing pure-play mechanical fabricators.
For Market Incumbents: Hedge against ball valve substitution in critical isolation applications by deepening severe-service alloy engineering and predictive diagnostics integration. Secure ASME welding capacity through captive training pipelines extending 18-24 month qualification cycles. Defend municipal share via Buy America compliance documentation bundling. For New Entrants and Emerging Players: Enter via Mexico industrial water treatment corridors where nearshoring manufacturing expansion outpaces established supplier presence. Target Querétaro and Nuevo León cooling system specifications with ASME-compliant PVC and carbon steel configurations. Pursue engineering-procurement-construction firm partnerships for standardized skid packages. For Investors and Strategic Acquirers: The window for entry favors mid-scale foundries with latent ASME certification and geographic proximity to Illinois-Michigan compliance hot zones. Long-term viability rests on hydrogen pipeline adaptation capabilities and embrittlement-resistant material portfolios. Watch EPA enforcement variance across state environmental agencies as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive bronze and stainless steel casting secures melt-source traceability for EPA compliance. |
| Smart Actuator Platform Integration | Digital positioner bundling displaces component-level procurement in Texas and Arizona utilities. |
| ASME Certification Expansion | Section IX welding qualification opens severe-service specifications in Gulf Coast petrochemical projects. |
| Hydrogen Service Material Development | Embrittlement-resistant sealing geometries position for power generation blending infrastructure. |
| Buy America Compliance Services | Documentation bundling captures Bipartisan Infrastructure Law procurement preference in municipal awards. |
Research Approach
Multi-period observation of municipal procurement awards, foundry capacity utilization, and alloy price movements anchored the trend analysis, supplemented by interviews with plant engineers at water treatment facilities, procurement leads at Gulf Coast petrochemical operators, distributor inventory managers, and ASME certification auditors. Secondary validation drew from EPA enforcement databases, ASME boiler and pressure vessel code updates, London Metal Exchange pricing records, and state-level infrastructure spending disclosures. Bottom-up shipment data triangulated against top-down utility capital expenditure surveys.
Segment-weighting across product type, material grade, end-use severity, and regional regulatory cluster shaped the analytical framework. CAGRs derived from regression-adjusted shipment trajectories incorporating lead service line replacement mandates and petrochemical capacity expansion schedules. Forecast inputs included foundry capacity constraints, copper-nickel price volatility assumptions, and smart actuator adoption curves in municipal SCADA modernization programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged ASME welder shortages or accelerated hydrogen infrastructure deployment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Three Way Ball Valve Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Pneumatic Slide Gates Market
Valves
Subsea Valves Market
Valves
Subsea Control System Market
Valves
United States Valves Market
Valves
Liner Regulators Market
Valves
North America Residential Ball Valves Market
Valves
Pigging Valves Market
Valves
Mechanical Shaft Seal Market
Valves
Ball Valves Market
Valves
Magnetic Coupler Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Stainless Steel Valve Tag Market
Valves
Global Pressure Relief Valves Market
Valves
Large Bore Vacuum Insulated Pipe Market