
 Europe Biostimulants Market | 2026-2036
Europe Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biostimulants Market Intelligence
Buyer concentration among European greenhouse cooperatives and large-scale horticulture groups is pivoting procurement toward long-term supply contracts with biostimulant suppliers. BASF SE leverages its crop science infrastructure to sustain formulation development across multiple active categories. Syngenta AG anchors its position through biologicals integration with conventional crop protection portfolios. Valagro specializes in seaweed extract platforms, occupying a differentiated niche among Mediterranean vegetable growers.
Biostimulants comprise substances and microorganisms applied to plants or soil to stimulate natural processes that enhance nutrient uptake, stress tolerance, and crop quality without direct pesticidal or fertilizing action; formulations typically contain humic acids, protein hydrolysates, or beneficial microbes in liquid or granular carriers designed for foliar spray, soil drench, or seed treatment delivery. Seaweed extracts and humic acids currently lead product type demand, reflecting established efficacy in abiotic stress mitigation and root development, while microorganisms represent the fastest-expanding category as fermentation technologies improve viability and shelf stability. Liquid formulations dominate volume sales due to compatibility with precision irrigation systems, though granular products retain margin strength in broad-acre cereal applications where soil incorporation prevails.
The EU Fertilising Products Regulation (FPR) and CE marking requirements under the EU Green Deal are reshaping product registration pathways, compelling manufacturers to demonstrate component safety and agronomic efficacy through standardized testing protocols. ECHA guidance on microbial strain characterization and EFSA evaluations of novel protein hydrolysate sources are elevating compliance costs for new market entrants. France's ANSM-equivalent agricultural input oversight and Germany's national fertilizer ordinance add member-state layers that suppliers must navigate for full territorial access. Stakeholders should monitor evolving FPR delegated acts on biostimulant-specific criteria, as these will determine which formulation categories achieve streamlined CE conformity versus case-by-case national approvals.
Market Dynamics
The EU Fertilising Products Regulation is compressing registration timelines for microbial and seaweed-based biostimulants while elevating compliance barriers for non-CE-marked formulations, forcing suppliers to restructure their European product portfolios around standardized safety and efficacy protocols.
Growth Catalysts
- CE Marking Streamlining:The EU Fertilising Products Regulation enables faster market entry for compliant microbial formulations, reducing the previous patchwork of national approvals that delayed product launches across member states.
- Mediterranean Horticulture Intensification:Spain's Almería greenhouse belt and Italy's Po Valley vegetable operations are expanding biostimulant integration into precision irrigation systems, driving volume demand for liquid seaweed extracts.
- Protein Hydrolysate Fermentation:Advances in enzymatic hydrolysis and anaerobic digestion are lowering production costs for amino acid-rich biostimulants, improving accessibility for broad-acre cereal growers in France and Germany.
Market Restraints
- ECHA Microbial Characterization Costs:The European Chemicals Agency's strain-level safety documentation requirements impose substantial analytical burdens on small and mid-sized biostimulant developers, consolidating innovation capacity among well-capitalized players.
- Seaweed Supply Geographic Concentration:Cold-water macroalgae harvesting concentrates in Norway and Ireland, exposing formulators to weather-driven biomass volatility and single-source dependency risks.
- Mineral Fertilizer Price Volatility:Ammonia and phosphate cost fluctuations distort farmer input budgeting, compressing discretionary spending on biological yield enhancers during nitrogen price spikes.
Strategic Opportunities
- Poland and Romania Arable Expansion:Eastern European grain producers remain underpenetrated by biostimulant suppliers, presenting first-mover advantages for humic acid and microbial inoculant providers establishing distribution partnerships with cooperatives.
- Carbon Farming Integration:The EU Green Deal's soil carbon sequestration incentives create direct payment linkages for biostimulant adoption, particularly for products demonstrating measurable soil organic matter improvements.
- Biological-Conventional Tank-Mix Compatibility:Formulators developing surfactant-stable biostimulants compatible with existing fungicide and herbicide application schedules can capture share from farmers reluctant to add separate spray passes.
Industry Challenges
- EFSA Novel Protein Source Evaluations:The European Food Safety Authority's extended assessment timelines for non-traditional biomass feedstocks delay product launches by 18-36 months, eroding competitive windows.
- Microbiologist and Fermentation Technician Scarcity:European universities produce insufficient graduates with combined agronomy and industrial microbiology training, constraining R&D pipeline velocity and manufacturing scale-up.
- Multi-National FPR Delegated Act Harmonization:Divergent interpretations of biostimulant-specific criteria across France's ANSM-equivalent oversight and Germany's fertilizer ordinance fragment compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biostimulants Market |
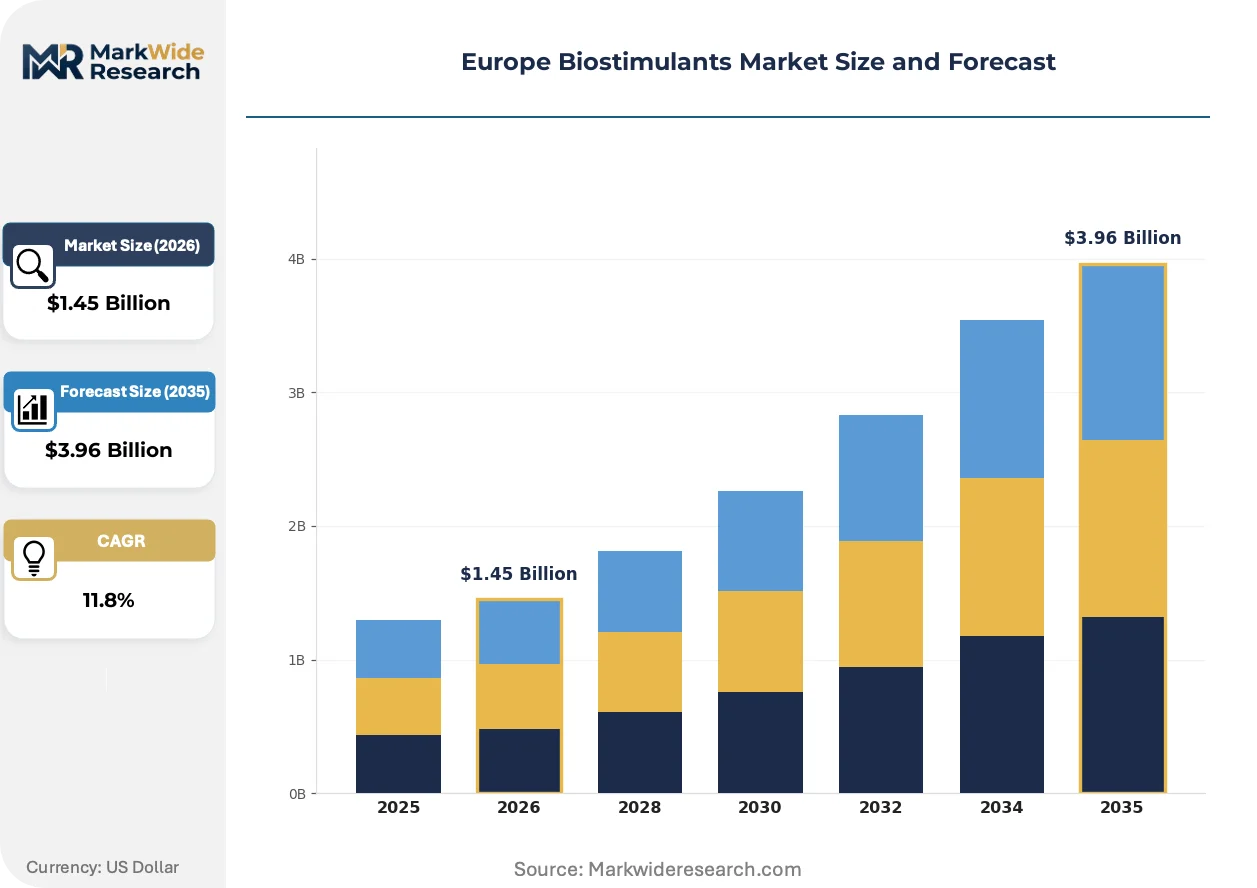
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.96 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Microorganisms, Protein Hydrolysates Application: Crops, Turf, Ornamental, Soil Form: Liquid, Granular, Powder, Concentrate End User: Agricultural Producers, Horticulturists, Greenhouse Growers, Nurseries |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, Valagro, Biolchim SPA, Koppert Biological Systems, UPL Limited, Agronutrition, BioAtlantis Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biostimulants Market Strategic Shifts & Innovations
Formulation science and regulatory harmonization are converging to reshape how biostimulant developers design, register, and deliver products to European growers, with particular pressure on microbial viability and precision application compatibility.
Microencapsulation technology for bacterial and fungal inoculants is modularizing shelf-stable product architectures, enabling suppliers to separate active organism preservation from carrier formulation. Greenhouse cooperatives in the Netherlands and Belgium are adopting these encapsulated platforms for automated dosing systems. The technology is compressing the historical trade-off between microbial count at manufacture and field efficacy, allowing year-round inventory positioning without cold-chain dependency.
France's national fertilizer ordinance and Germany's implementation of FPR delegated acts are creating divergent efficacy demonstration requirements, forcing suppliers to maintain parallel dossier preparations for full territorial access. The regulatory friction elevates compliance costs most acutely for protein hydrolysate and humic acid categories where novel source materials trigger extended safety reviews. Mediterranean vegetable growers in Spain and Italy face delayed access to innovations approved under streamlined CE pathways elsewhere.
Cooperative procurement desks at Spanish and Italian greenhouse clusters are consolidating supplier relationships around multi-season framework agreements with embedded technical advisory services. The distributor agronomist is displacing independent retail recommendations as the primary influence on product selection. This concentration is most visible in Almería's export-oriented tomato and pepper operations, where input standardization across member farms overrides individual grower experimentation.
Europe Biostimulants Market Segmentation
European biostimulant procurement patterns diverge sharply between high-volume commodity applications and premium precision agriculture deployments. Formulation chemistry, delivery mechanism, and end-user sophistication create distinct margin architectures across segment boundaries.
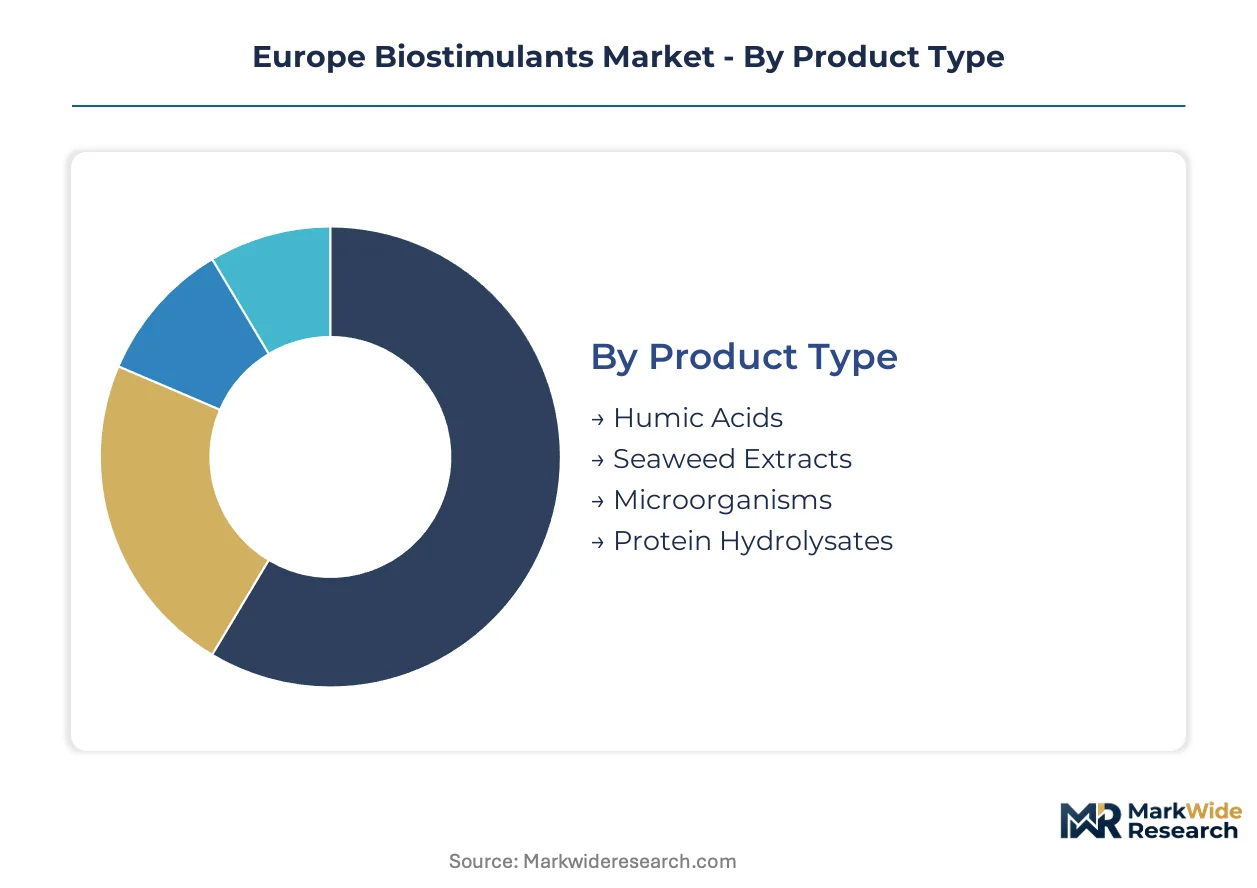
Product Type:
Seaweed extracts and humic acids anchor volume sales, while microorganisms command premium positioning amid ECHA registration complexity.
- Seaweed Extracts:Cold-water macroalgae formulations from Norwegian and Irish biomass dominate Mediterranean horticulture. Spain's Almería greenhouse belt integrates these into precision irrigation for abiotic stress mitigation in export vegetable production.
- Microorganisms:Bacterial and fungal inoculants require strain-level ECHA documentation, elevating compliance costs. France's ANSM-equivalent oversight and Germany's fertilizer ordinance impose parallel dossier demands, consolidating innovation among capitalized developers.
- Humic Acids:Leonardite-derived formulations serve broad-acre cereal growers in Poland and Romania with established efficacy in root development and nutrient chelation.
- Protein Hydrolysates:Enzymatic hydrolysis of agricultural byproducts yields amino acid-rich stimulants for specialty crop foliar programs.
Mature deployment sits with Seaweed Extracts. Newer deployment is concentrated in Microorganisms.
Application:
Revenue concentration tracks input intensity, with greenhouse vegetables outpacing field crops in per-hectare biostimulant expenditure.
- Crops:Arable applications in France and Germany focus on yield stabilization amid mineral fertilizer price volatility. Humic acid soil drenches and microbial seed treatments dominate broad-acre deployment for wheat and maize.
- Turf:Golf course and sports pitch maintenance in the UK and Netherlands drives demand for rapid green-up formulations with low phytotoxicity risk.
- Ornamental:Dutch floriculture operations prioritize flower quality and vase-life extension through protein hydrolysate foliar programs.
- Soil:Standalone soil amendment applications concentrate in carbon farming pilots under EU Green Deal soil sequestration incentives.
Margin strength clusters with Turf and Ornamental. Volume expansion is gaining share fastest in Soil applications.
Form:
Liquid formulations align with automated dosing infrastructure, while granular products retain relevance in mechanical spreading regimes.
- Liquid:Compatibility with drip irrigation and fertigation systems dominates Mediterranean greenhouse procurement. Dutch and Belgian cooperatives specify automated dosing compatibility in supply contracts.
- Granular:Soil incorporation requirements in French and German cereal production sustain demand for spreader-applied humic acid and microbial carriers.
- Powder:Reconstitution flexibility serves small-scale nursery operations with variable water quality and batch mixing protocols.
- Concentrate:Reduced freight costs and extended shelf stability appeal to Eastern European distributors serving dispersed arable holdings.
Precision agriculture penetration is deepest with Liquid. Cost-sensitive adoption concentrates in Concentrate.
End User:
Procurement centralization varies: greenhouse cooperatives aggregate demand, while arable producers retain fragmented purchasing patterns.
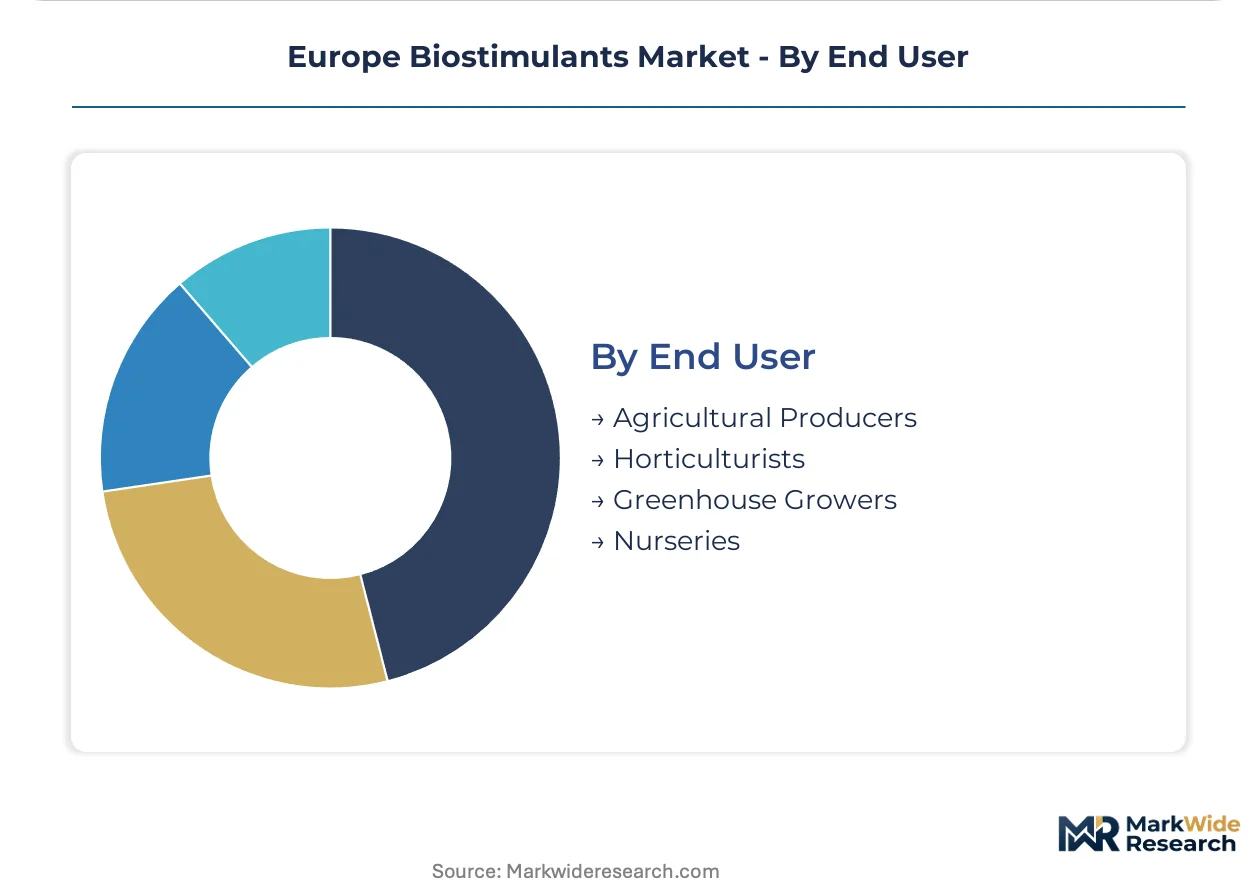
- Agricultural Producers:French and German cereal cooperatives negotiate seasonal framework agreements, compressing margins for suppliers without technical advisory bundling.
- Greenhouse Growers:Spain's Almería and Italy's Po Valley clusters consolidate multi-season supply contracts with embedded agronomist support, displacing independent retail channels.
- Horticulturists:Italian vegetable specialists integrate biostimulants with conventional crop protection tank mixes, demanding surfactant-stable formulations.
- Nurseries:Propagation-focused operations in the Netherlands prioritize root establishment and transplant shock mitigation in young plant production.
Contract sophistication is highest among Greenhouse Growers. Price sensitivity peaks with Agricultural Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for biostimulants concentrates in Mediterranean horticulture clusters and northwestern European cereal belts, with regulatory harmonization under the EU Fertilising Products Regulation creating divergent access conditions across member states.
Spain
Almería's greenhouse belt drives liquid seaweed extract consumption for precision-irrigated export vegetables. The national implementation of CE marking requirements accelerates product registration for compliant microbial formulations. Valencia's citrus cooperatives are expanding biostimulant integration into integrated pest management programs.
Italy
Po Valley vegetable operations and southern tomato processors anchor humic acid demand for soil conditioning and nutrient chelation. ANSM-equivalent agricultural oversight imposes parallel efficacy documentation beyond FPR baseline requirements. Sicily's organic citrus farms represent emerging adoption zones for protein hydrolysate foliar programs.
France
Broad-acre wheat and maize producers in the Paris Basin utilize microbial seed treatments amid mineral fertilizer price volatility. The national fertilizer ordinance mandates additional agronomic trial data for novel biostimulant categories. Bordeaux vineyard operations are standardizing biostimulant protocols for drought stress mitigation in premium wine production.
Germany
Lower Saxony and Bavaria cereal cooperatives negotiate seasonal framework agreements compressing supplier margins without technical advisory bundling. ECHA microbial strain characterization requirements elevate compliance costs for bacterial inoculant developers. Brandenburg's potato processing clusters are piloting carbon farming-linked biostimulant applications under EU Green Deal incentives.
Netherlands
Dutch floriculture and glasshouse vegetable operations demand surfactant-stable formulations compatible with automated dosing infrastructure. EFSA evaluations of novel protein hydrolysate sources extend assessment timelines for innovative feedstock-based products. Westland's tomato propagation facilities are consolidating supplier relationships around multi-season technical service contracts.
Europe Biostimulants Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue microbial specialization and regional distribution partnerships. The market exhibits moderate consolidation with multinational agrochemical conglomerates anchoring volume positions alongside mid-sized fermentation specialists. Three archetypes dominate: integrated crop science platforms, seaweed extraction specialists, and microbial inoculant developers. Competitive dynamics center on ECHA registration capacity building and cooperative procurement desk penetration.
Within the integrated platform tier, BASF SE and Syngenta AG exemplify crop science infrastructure leverage across multiple active categories. Valagro occupies a differentiated position among Mediterranean vegetable growers through seaweed extract specialization. These three entities represent contrasting strategic postures: multinational biologicals integration, conventional portfolio adjacency, and niche platform dominance.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| Valagro |
| Biolchim SPA |
| Koppert Biological Systems |
| UPL Limited |
| Agronutrition |
| BioAtlantis Ltd |
| Others |
Cost & Logistics Intelligence
Captive sourcing of Norwegian and Irish cold-water macroalgae biomass anchors pricing power for seaweed extract formulators, while microbial inoculant developers face cost compression from ECHA strain-characterization requirements that consolidate innovation among capitalized players with parallel dossier capacity across France and Germany.
Pricing Analysis
Volume-mass liquid seaweed extracts for Mediterranean greenhouse irrigation trade at compressed margins, while granular humic acid formulations for French and German cereal operations and CE-marked microbial inoculants with full ECHA documentation command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates certified organic formulations from conventional grades and unregistered economy alternatives. Pricing pressure stems from mineral fertilizer price volatility that compresses farmer discretionary spending during nitrogen cost spikes. Agricultural producers in Eastern Europe exhibit peak price sensitivity, whereas Dutch greenhouse cooperatives prioritize automated dosing compatibility over unit cost.
Supply Chain Analysis
Workforce scarcity for fermentation technicians and industrial microbiologists constrains manufacturing scale-up in Germany and the Netherlands, where ECHA documentation requirements demand specialized analytical capacity. Cold-water macroalgae harvesting concentrates in Norway and Ireland, while bacterial strain cultivation localizes in Germany and Denmark. Raw material dependencies include Norwegian kelp biomass, pharmaceutical-grade fermentation substrates, and leonardite deposits for humic acid extraction. Single-source vulnerability runs through concentrated seaweed biomass zones exposed to North Atlantic weather volatility. Distribution runs through cooperative procurement desks at Spanish and Italian greenhouse clusters that displace independent retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial viability technologies are displacing legacy liquid fermentation platforms, with microencapsulation and shelf-stable preservation systems redefining competitive moats for European biostimulant suppliers.
For Market Incumbents: Acquire ECHA-registered strain libraries and parallel dossier capabilities to defend against margin compression from regulatory complexity. BASF SE and Syngenta AG should extend biologicals integration into conventional crop protection tank-mix portfolios, while Valagro deepens captive sourcing agreements with Norwegian kelp harvesters to secure biomass priority access amid weather-driven supply volatility. For New Entrants and Emerging Players: Protein hydrolysate fermentation advances offer technology-first entry points into Eastern European arable markets where humic acid penetration remains incomplete. Poland and Romania present the most penetrable geographies for first-mover microbial inoculant providers establishing cooperative distribution partnerships. Carbon farming-linked soil amendment positioning under EU Green Deal incentives provides differentiated go-to-market framing distinct from yield-centric incumbent messaging. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated crop science platforms seeking biologicals adjacency, with IPO viability constrained by ECHA registration timeline uncertainty. Mid-cap microbial specialists with validated strain libraries and multi-country dossier submissions represent priority acquisition archetypes. The signal to watch is FPR delegated act harmonization progress, where breakthrough in France-Germany regulatory alignment would compress compliance costs and revalue registration assets.| Strategic Initiative | Industry Significance |
|---|---|
| ECHA Registration Capacity Buildout | Strain-level documentation capabilities differentiate suppliers under EU Fertilising Products Regulation compliance mandates. |
| Cooperative Procurement Desk Penetration | Spanish Almería and Italian Po Valley greenhouse clusters consolidate supplier relationships around multi-season framework agreements. |
| Microencapsulation Technology Deployment | Shelf-stable bacterial preservation enables year-round inventory positioning without cold-chain infrastructure dependency. |
| Carbon Farming Certification Linkage | EU Green Deal soil sequestration incentives create direct payment pathways for biostimulant adoption in measurable soil organic matter improvement. |
| Backward Integration into Biomass Sourcing | Captive kelp harvesting agreements in Norway and Ireland secure priority access to weather-vulnerable cold-water macroalgae supply. |
Research Approach
Multi-period observation of ECHA registration timelines, FPR delegated act implementation progress, and cooperative procurement contract structures anchored the trend analysis, supplemented by interviews with biostimulant formulation scientists, regulatory affairs directors at agrochemical platforms, greenhouse cooperative procurement managers, and fermentation technology specialists. Secondary validation drew from EU fertilizing product registration databases, ECHA guidance documents, SEC filings of listed crop science conglomerates, and customs trade data on seaweed biomass imports. Bottom-up volume estimates from segment-level adoption rates triangulated against top-down market sizing from input expenditure surveys.
Segment-weighting approaches modeled product type, application intensity, formulation chemistry, and end-user procurement centralization dimensions across the projection horizon. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns in precision agriculture, adjusted for regulatory approval velocity and farmer input budget elasticity. Industry-specific forecast inputs included mineral fertilizer price covariance coefficients and EU carbon farming payment schedule implementation timelines.
Several conditions sit outside the modeled scope, including unilateral member state regulatory divergences beyond FPR baseline requirements and breakthrough synthetic biology alternatives that displace fermentation-based biostimulants. Forecasts reflect assumptions regarding ECHA documentation timeline stability and continued EU Green Deal soil carbon incentive funding. Material deviation in FPR harmonization progress or mineral fertilizer price regime shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
United States Biopesticides Market