
 Global Protein Hydrolysis Enzymes Market | 2026-2036
Global Protein Hydrolysis Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Hydrolysis Enzymes Market Foresight
Specialty enzyme distribution is fragmenting as regional distributors lose ground to direct manufacturer relationships and digital procurement platforms. Novozymes leverages its integrated fermentation network to control supply chain costs across Asia-Pacific and European dairy markets. BASF anchors its position through backward integration into microbial strain development, reducing reliance on third-party biotechnology suppliers.
Protein hydrolysis enzymes catalyze the cleavage of peptide bonds in protein substrates, typically operating at temperatures between 40°C and 60°C with pH optima ranging from neutral to mildly alkaline depending on the enzyme class. These biocatalysts serve industrial applications by generating bioactive peptides, improving protein solubility, and reducing allergenic potential in food and pharmaceutical intermediates. Papain and bromelain dominate the plant-derived segment with established supply chains from tropical fruit processing regions, while microbial alternatives such as alcalase and flavourzyme capture expanding share in precision fermentation systems. Liquid formulations command premium positioning in automated food processing lines, whereas powder and granular forms sustain feed additive applications where storage stability and transport economics favor solid-state products.
FDA food additive regulations and EFSA enzyme safety evaluations shape product registration pathways and commercialization timelines for manufacturers targeting North America and Europe. China's NMPA and GB standards for food-grade industrial enzymes create additional compliance layers for imported biocatalysts, while India's FSSAI and BIS certification requirements govern domestic enzyme deployment in dairy and beverage sectors. Stakeholders must monitor evolving enzymatic process labeling standards and carbon intensity disclosure rules as procurement criteria harden across regulated end-use industries.
Market Dynamics
Precision fermentation capacity expansion is compressing production economics for microbial-derived enzymes, while EU REACH and China's GB standards simultaneously tighten purity and carbon disclosure requirements across the value chain.
Growth Catalysts
- EU Green Deal carbon accounting:Food processors in Germany and France now require enzymatic suppliers to document Scope 3 emissions, pulling demand toward fermentation-based biocatalysts with verifiable low-carbon production.
- Plant protein extraction:Pea and oat protein manufacturers in Denmark and the Netherlands deploy alcalase and flavourzyme to improve solubility and reduce bitter off-notes in alternative meat formulations.
- China NMPA pathway streamlining:Domestic biotech firms in Jiangsu and Shandong provinces accelerate food-grade enzyme registrations, cutting import dependency for papain and bromelain substitutes.
Market Restraints
- Tropical fruit supply volatility:Papain extraction from Carica papaya latex concentrates in southern India and Sri Lanka, exposing processors to monsoon-driven raw material disruptions and price spikes.
- EFSA enzyme safety evaluation timelines:Novel microbial strain approvals now require 18-24 month toxicology packages, delaying commercialization for precision fermentation startups targeting European dairy applications.
- Protease stability limitations:Liquid formulations above 25°C degrade within 90 days, forcing cold-chain logistics that inflate distribution costs to Southeast Asian beverage manufacturers.
Strategic Opportunities
- Brazilian bioactive peptide market:ANVISA's expanded health claim framework permits cardiovascular and satiety positioning for hydrolyzed whey and collagen ingredients in functional foods.
- Enzyme immobilization on magnetic nanoparticles:Reactor engineering firms in Switzerland and Japan pilot continuous-flow systems that slash enzyme consumption per kilogram of protein substrate processed.
- Direct-to-processor digital platforms:Specialty enzyme distributors in North America bypass traditional chemical intermediaries, offering real-time inventory visibility and lot-level CO2 tracking to mid-sized meat processors.
Industry Challenges
- Fermentation scale-up engineering talent:Microbial enzyme producers in Germany and California compete for bioprocess engineers capable of translating 10-liter lab yields to 100,000-liter industrial tanks without productivity collapse.
- Legacy dairy equipment compatibility:Automated CIP systems in Wisconsin and Wisconsin cheese plants require stainless-steel-compatible enzyme formulations that resist alkaline wash cycles without activity loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Hydrolysis Enzymes Market |
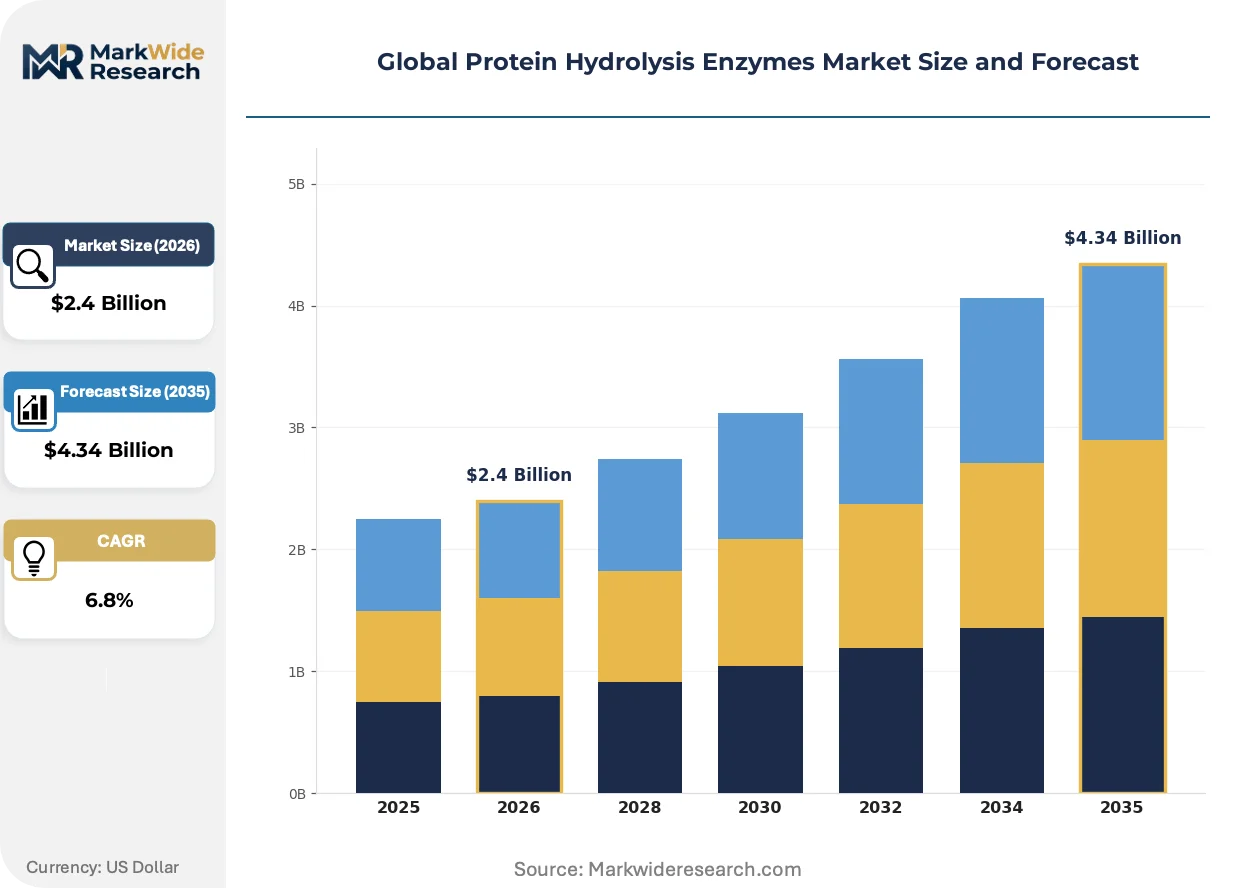
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcalase, Neutrase, Papain, Bromelain, Flavourzyme, Protamex Application: Food Processing, Feed Additives, Leather Treatment, Textile Processing, Pharmaceutical Manufacture, Detergents End User Industry: Dairy Processing, Animal Nutrition, Personal Care, Biotech Firms, Beverage Production, Cosmetics Form: Liquid, Powder, Granular, Immobilized |
| Companies Covered | Novozymes, BASF, DuPont, DSM, AB Enzymes, Dyadic International, Advanced Enzymes Technologies, Associated British Foods, Solvay Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Hydrolysis Enzymes Market Shifts & Advancements
Continuous bioprocessing architectures and AI-guided strain optimization are compressing development cycles, while regulatory disclosure mandates and direct procurement platforms restructure how enzymes reach end-users.
Cell-free enzyme production using in vitro transcription-translation systems is collapsing the capital requirements for pilot-scale manufacturing. Contract research organizations in Boston and Basel now offer 48-hour turnaround on custom protease variants. This acceleration enables food ingredient startups to test 50+ enzyme candidates before committing to fermentation facility construction.
REACH's 2025 restriction roadmap on persistent organic pollutants is forcing enzyme manufacturers to eliminate solvent-based extraction steps from bromelain production. German and Dutch processors now source pineapple stem-derived biocatalysts certified through aqueous recovery methods. The reformulation cost is concentrating supply relationships with Thai processors who invested early in green extraction infrastructure.
Ingredient buyers in Japan and South Korea now unbundle technical service from enzyme supply contracts, contracting directly with application laboratories at universities rather than manufacturer field teams. This disintermediation compresses pricing power for distributors who previously captured 15-20 point margins on technical support bundling. Dairy cooperatives in Hokkaido and Gyeonggi-do provinces lead this procurement restructuring.
Global Protein Hydrolysis Enzymes Market Segmentation
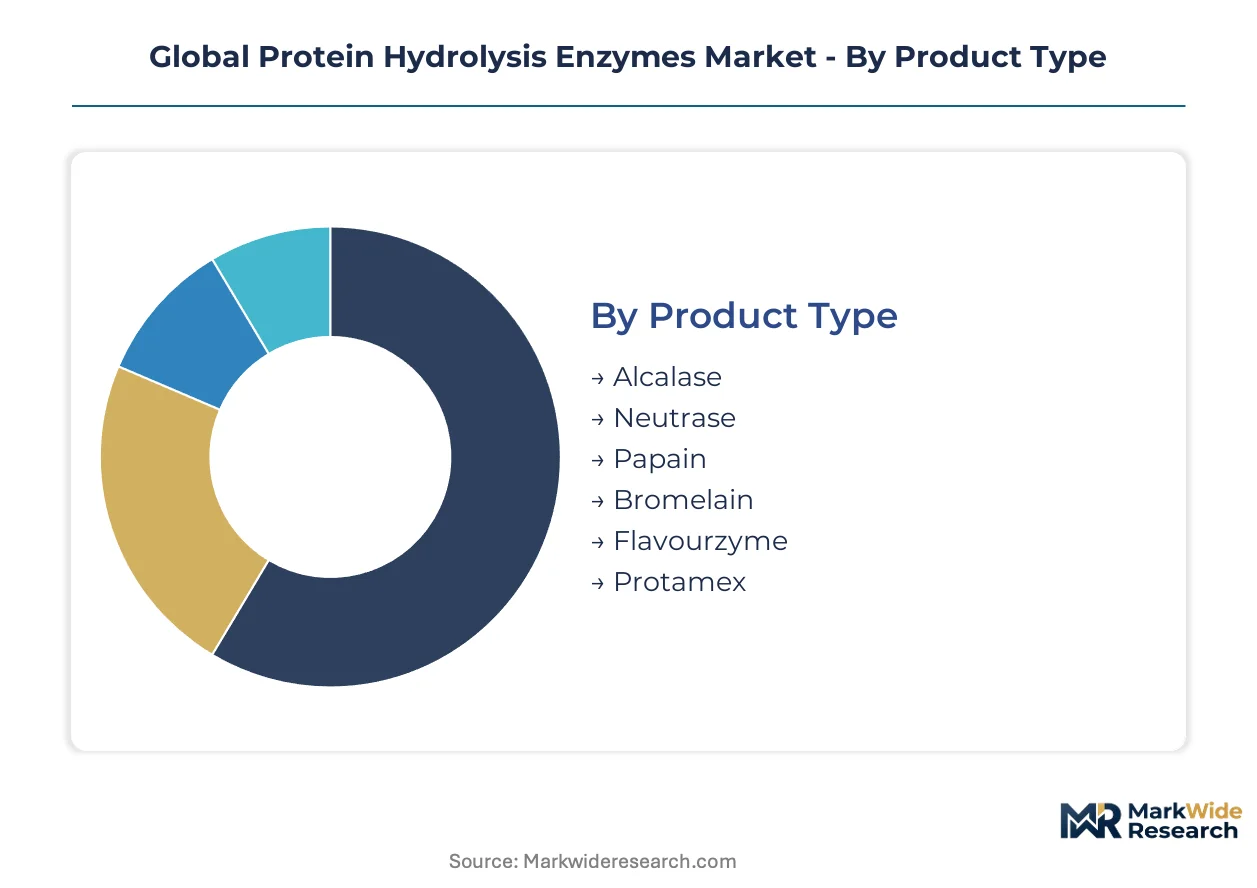
Protein hydrolysis enzymes fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct procurement patterns, formulation requirements, and margin structures that suppliers must navigate.
Product Type:
Microbial proteases turn inventory fastest due to precision fermentation scalability, while plant-derived enzymes tie up working capital through seasonal raw material procurement cycles.
- Alcalase:A subtilisin-type serine protease from Bacillus licheniformis with broad substrate specificity and pH stability from 6.5 to 8.5. Dairy processors in Denmark and the Netherlands deploy alcalase for whey protein hydrolysates targeting infant formula and sports nutrition applications where bitterness reduction commands formulation priority.
- Flavourzyme:A fungal protease-amylase complex from Aspergillus oryzae generating both exo- and endo-peptidase activity for controlled degree of hydrolysis. Pea protein manufacturers in Germany favor flavourzyme for plant-based meat analogs where clean-label positioning and umami enhancement overlap.
- Papain:Cysteine protease extracted from Carica papaya latex with temperature optima near 65°C and rapid autolysis above 70°C.
- Bromelain:Pineapple stem-derived cysteine protease with anti-inflammatory applications in pharmaceutical intermediates.
- Neutrase:Neutral metalloprotease from Bacillus amyloliquefaciens for mild protein modification without extreme pH shifts.
- Protamex:Bacillus protease complex optimized for soy and wheat protein hydrolysis in Asian sauce applications.
Alcalase dominates installed base across European dairy infrastructure. Flavourzyme is where expansion concentrates in plant protein processing.
Application:
Food processing commands premium pricing through regulatory compliance burdens, while detergent applications compete on cost-per-active-unit metrics with minimal value-added services.
- Food Processing:Enzymatic hydrolysis for protein solubility enhancement, allergen reduction, and bioactive peptide generation. German and French processors under EU Green Deal carbon accounting now require Scope 3 documentation, favoring fermentation-based biocatalysts with verifiable low-carbon production.
- Feed Additives:Soy and fish meal hydrolysis for monogastric digestibility improvement in poultry and swine nutrition. Chinese compound feed manufacturers in Jiangsu province scale microbial protease inclusion as domestic fermentation capacity expands.
- Leather Treatment:Dehairing and bating applications replacing sulfide-based chemical processes.
- Textile Processing:Silk degumming and wool anti-felting through controlled proteolysis.
- Pharmaceutical Manufacture:Insulin precursor cleavage and therapeutic peptide production.
- Detergents:Stain removal through protein soil degradation in household and industrial formulations.
Food processing anchors revenue concentration. Feed additives are climbing the fastest as precision fermentation compresses production economics.
End User Industry:
Dairy processing and beverage production operate on continuous-flow procurement with monthly replenishment cycles, while biotech firms negotiate project-based contracts with 12-18 month development timelines.
- Dairy Processing:Whey and casein hydrolysis for infant formula, sports nutrition, and medical foods. Wisconsin cheese plants require stainless-steel-compatible formulations resisting alkaline CIP cycles without activity loss.
- Animal Nutrition:Feed enzyme inclusion for protein digestibility and nitrogen excretion reduction. Brazilian integrated poultry operations drive volume through tropical climate-adapted formulations.
- Beverage Production:Chill haze prevention in beer and protein stabilization in plant-based drinks.
- Biotech Firms:Custom protease development for therapeutic peptide manufacturing.
- Personal Care:Keratin hydrolysis for hair conditioning and skin exfoliation.
- Cosmetics:Bioactive peptide inclusion in anti-aging formulations.
Dairy processing retains the deepest supplier relationships. Animal nutrition is gaining share fastest as Brazilian and Chinese livestock operations expand enzyme inclusion rates.
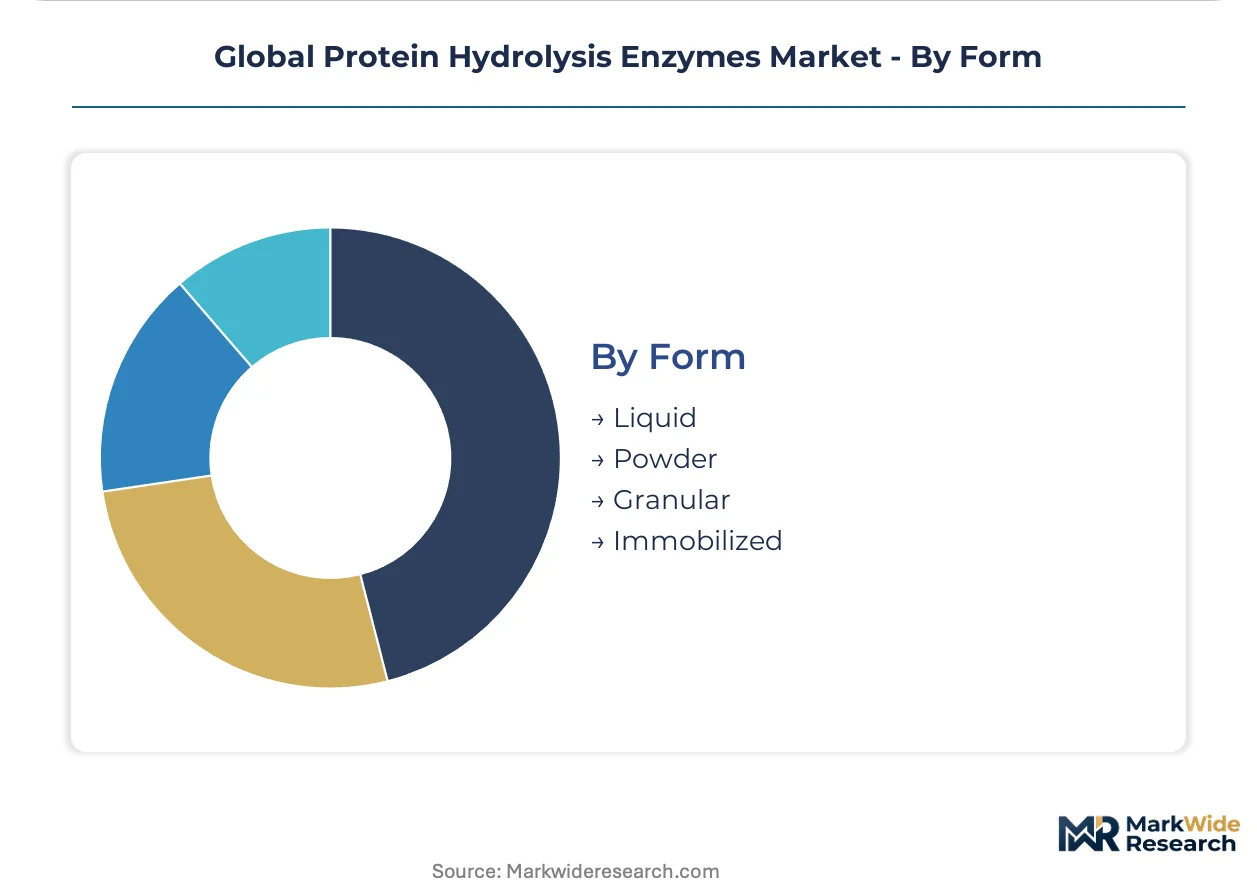
Form:
Liquid formulations require cold-chain logistics that inflate distribution costs above 25°C, while powder and granular forms trade handling efficiency against reconstitution time in automated processing lines.
- Liquid:Standardized enzyme activity in stabilized aqueous solutions for automated dosing systems. Southeast Asian beverage manufacturers absorb cold-chain premiums for liquid proteases enabling precise flow-control integration.
- Powder:Spray-dried enzyme concentrates with extended shelf stability for feed additive blending. Chinese compound feed mills in Shandong province favor powder forms for transport economics and storage flexibility.
- Granular:Agglomerated particles reducing dust generation in bulk handling operations.
- Immobilized:Enzyme attachment to solid supports enabling continuous-flow reactor operation. Swiss and Japanese reactor engineering firms pilot magnetic nanoparticle systems slashing enzyme consumption per kilogram of substrate processed.
Powder dominates feed sector procurement volumes. Immobilized forms are expanding most quickly as continuous bioprocessing architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Dutch dairy processing clusters, while Chinese manufacturers compress margins through domestic fermentation scale-up. This asymmetry reshapes procurement patterns across enzymatic supply chains.
Germany
Whey protein hydrolysate demand from infant formula and sports nutrition manufacturers drives alcalase consumption in Bavaria and Lower Saxony. EFSA enzyme safety evaluations enforce 18-24 month toxicology requirements for novel microbial strains. The Hamburg-Rotterdam corridor hosts precision fermentation facilities supplying carbon-documented biocatalysts under EU Green Deal Scope 3 mandates.
China
Jiangsu and Shandong provinces scale microbial protease output for soy and pea protein hydrolysis in plant-based meat applications. NMPA streamlines food-grade enzyme registrations, cutting import dependency for tropical-derived alternatives. Domestic biotech clusters in Suzhou and Qingdao now supply flavourzyme and alcalase substitutes to regional feed compounders.
United States
Wisconsin cheese plants require stainless-steel-compatible protease formulations surviving alkaline CIP cycles without activity degradation. FDA food additive regulations govern GRAS self-determination pathways for novel enzymes. The Madison-Milwaukee corridor anchors whey hydrolysate production for medical foods and sports nutrition brands.
Brazil
Integrated poultry operations in São Paulo and Paraná expand protease inclusion in tropical climate-adapted feed formulations. ANVISA's expanded health claim framework permits cardiovascular positioning for hydrolyzed whey and collagen in functional foods. Campinas hosts enzyme distribution hubs serving the Mercosur protein processing corridor.
Japan
Hokkaido dairy cooperatives unbundle technical service contracts, contracting directly with university application laboratories rather than manufacturer field teams. METI standards govern food-grade industrial enzyme purity specifications. The Kanto region pilots magnetic nanoparticle immobilization systems for continuous-flow protein hydrolysis reactors.
Global Protein Hydrolysis Enzymes Market Competitive Landscape
Integrated fermentation specialists and plant-derived extractors split the market along carbon-accounting and supply-security vectors. Consolidation characterizes the microbial segment where precision fermentation economics favor multi-hundred-thousand-liter capacity. Three archetypes dominate: vertically integrated biotech platforms controlling strain-to-fermentation pipelines, tropical raw material aggregators managing papaya and pineapple latex supply chains, and application-focused formulators serving dairy and beverage automation systems. Competitive moves center on backward integration into microbial strain development and direct-to-processor digital procurement platforms eliminating distributor margins.
Among Danish-anchored fermentation platforms, Novozymes occupies the integrated supply chain position, while BASF exemplifies chemical-industry diversification into biocatalysis. DuPont represents the nutrition-science conglomerate archetype, leveraging protein ingredient portfolios to bundle enzyme and hydrolysate offerings. These three sit within distinct strategic postures: Novozymes anchors the pure-play enzyme platform model, BASF occupies the diversified chemical-biotech intersection, and DuPont exemplifies downstream nutrition integration.
| Leading Market Players |
|---|
| Novozymes |
| BASF |
| DuPont |
| DSM |
| AB Enzymes |
| Dyadic International |
| Advanced Enzymes Technologies |
| Associated British Foods |
| Solvay Enzymes |
| Others |
Supply & Pricing Matrix
Tropical fruit latex extraction in southern India and Sri Lanka anchors upstream supply for plant-derived proteases, concentrating margin capture with processors who secured multi-year papaya and pineapple stem contracts before monsoon volatility intensified. This geographic lock on raw material flows through to premium pricing for bromelain and papain substitutes, while microbial fermentation platforms in Denmark and Germany compete on carbon-accounting documentation rather than extraction cost alone.
Pricing Analysis
Configured-to-order enzyme formulations command 40-60 point spreads over standard catalog grades, reflecting application-specific pH stability tailoring and stainless-steel compatibility certification for dairy CIP systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon disclosure depth and toxicology package completeness, with EU Green Deal Scope 3 documentation becoming the threshold for premium tier access. Cost compression in standard-grade microbial proteases is intensifying because Chinese domestic fermentation capacity is scaling flavourzyme and alcalase substitutes. Feed additive buyers in Jiangsu province exhibit highest price sensitivity, while infant formula manufacturers in Bavaria absorb premiums for bitterness-optimized whey hydrolysate enzymes.
Supply Chain Analysis
Extended payment terms now stretch to 90-120 days for tropical-derived enzyme distributors, with supply-chain finance facilities emerging from Thai pineapple processors who invested early in aqueous extraction infrastructure. Geographic supply concentrates in Denmark, Germany, and China for microbial proteases, and in India, Sri Lanka, and Thailand for plant-derived alternatives. Raw material dependencies center on Carica papaya latex, pineapple stem biomass, and Bacillus licheniformis fermentation feedstocks. Single-source vulnerability runs through southern Indian monsoon corridors, where papain extraction faces seasonal disruption risk. Distribution runs through direct manufacturer relationships and digital procurement platforms that are displacing regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service unbundling in Japan and South Korea signals a service-attach opportunity expanding faster than base enzyme supply, with university application laboratories capturing recurring contracts previously held by manufacturer field teams. Application-specific formulation support now generates annuity revenue streams that outpace commodity enzyme price erosion.
For Market Incumbents: Build regulatory data moats through early investment in 18-24 month EFSA toxicology packages for novel microbial strains, locking out precision fermentation startups from European dairy procurement. Anchor capacity addition in Jiangsu and Shandong provinces to match Chinese domestic biotech scale-up. Certification investment in EU Green Deal carbon accounting documentation defends margin position against low-cost fermentation substitutes from Suzhou clusters. For New Entrants and Emerging Players: Build out Brazilian bioactive peptide positioning under ANVISA's expanded cardiovascular health claim framework, where hydrolyzed whey and collagen functional food applications remain underpenetrated by established suppliers. Target feed additive formulators in Paraná poultry operations with tropical climate-adapted protease stability. Direct-to-processor digital platforms offer the cleanest go-to-market angle, bypassing 15-20 point distributor margins on technical service bundling. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platforms with demonstrated 10-liter to 100,000-liter scale-up engineering capability, as bioprocess talent scarcity concentrates value in strain-to-fermentation pipelines. Magnetic nanoparticle immobilization technology licensors in Switzerland and Japan represent acquisition targets with reactor engineering differentiation. Watch for NMPA registration acceleration in Shandong province as the signal indicating Chinese domestic supply sufficiency and import substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | BASF's captive microbial libraries reduce third-party biotech dependency and compress R&D cycle times. |
| Carbon Documentation Certification | Hamburg-Rotterdam corridor facilities secure EU Green Deal procurement preference from German dairy processors. |
| Direct-to-Processor Digital Platform | North American distributors bypass chemical intermediaries with real-time CO2 tracking for Wisconsin meat processors. |
| Aqueous Extraction Infrastructure | Thai pineapple processors meet REACH 2025 solvent restrictions ahead of bromelain supply consolidation. |
| Continuous-Flow Reactor Partnership | Swiss engineering firms slash enzyme consumption per kilogram through magnetic nanoparticle immobilization pilots. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, dairy procurement leads, feed compounder technical directors, and enzyme distribution channel partners; and secondary validation through customs and trade data, SEC 10-K filings, EFSA enzyme safety evaluation registers, and NMPA food-grade certification databases. Bottom-up triangulation across product-grade volume estimates and top-down cross-checks against regional production capacity disclosures anchored forecast integrity.
Forecast inputs considered precision fermentation scale-up curves, EU REACH restriction roadmap implementation timing, and tropical raw material harvest variability across the projection horizon. Segmentation dimensions modeled include enzyme source type, application industry, formulation state, and end-user processing scale. CAGRs derived from installed base growth rates and replacement demand patterns, with specific weighting for carbon-accounting procurement criteria emerging under EU Green Deal frameworks.
Stress conditions across monsoon disruption severity, NMPA registration timeline compression, and EFSA toxicology package approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on fermentation yield improvements and regulatory disclosure mandate adoption curves. Macroeconomic deviation in protein feedstock costs, regulatory expansion of enzyme safety evaluation requirements, or technological breakthrough in cell-free production systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Beta-Glucanase Market