
 United States Biopesticides Market | 2026-2036
United States Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biopesticides Market Analytics
Consolidation among commercial fruit and vegetable growers is repositioning procurement leverage toward fewer buyers with larger acreage footprints. Marrone Bio Innovations leverages its proprietary fermentation technology to serve high-value specialty crop segments. Valent BioSciences LLC anchors its market presence through deep distribution partnerships with agricultural cooperatives across California and Arizona.
United States biopesticides comprise living organisms, naturally occurring substances, and microbial metabolites formulated for agricultural pest management, typically requiring aqueous suspension or granular carrier systems for field application. These agents function through modes including competitive exclusion, antibiosis, and induced systemic resistance to protect yield quality in integrated pest management programs. Bacterial bioinsecticides capture the dominant product position due to established efficacy against lepidopteran pests in row crops, while fungal biofungicides represent the fastest-expanding category as growers seek alternatives to synthetic fungicides in humid production regions. Application through greenhouses commands premium pricing because controlled-environment operators prioritize residue-free protocols for direct-to-retail supply chains.
The EPA oversees biopesticide registration under FIFRA's reduced-risk framework, while USDA programs incentivize biological input adoption through conservation cost-share mechanisms, collectively lowering market entry barriers for novel active ingredients. State-level departments of agriculture in California and Florida enforce supplementary efficacy and labeling requirements that shape product commercialization pathways. Stakeholders must monitor evolving resistance management protocols and state-specific buffer zone regulations to sustain market access.
Market Dynamics
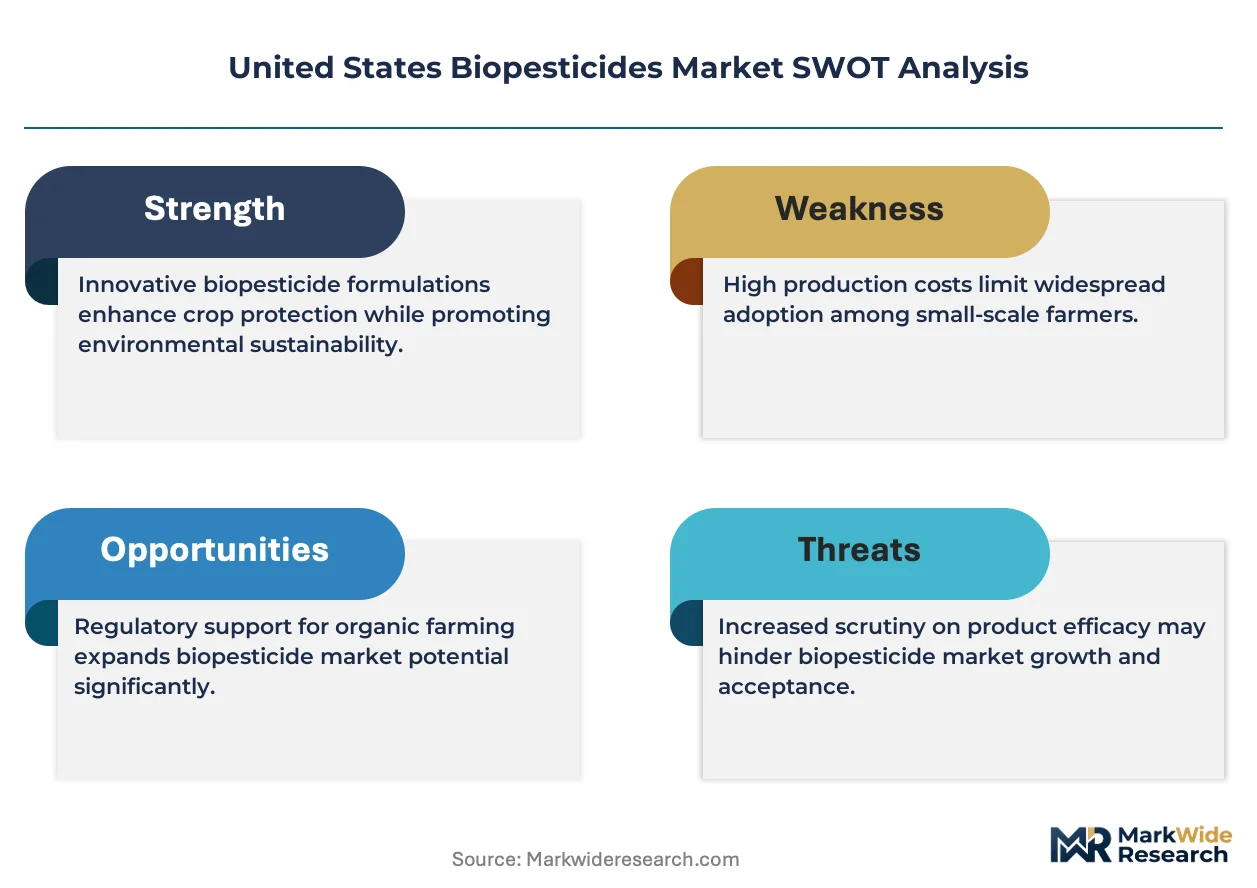
Consolidation among specialty crop growers in California and Florida is concentrating procurement power into fewer hands with larger acreage, forcing biopesticide suppliers to restructure volume commitments and technical service models around mega-grower accounts.
Growth Catalysts
- EPA Registration Streamlining:FIFRA's reduced-risk pathway accelerates commercialization timelines for microbial active ingredients, cutting regulatory review periods substantially compared to conventional chemical registrations.
- Conservation Cost-Share Programs:USDA incentive mechanisms subsidize biological input adoption, lowering effective purchase prices for fruit and vegetable operations in the Pacific Coast states.
- Humid Region Fungicide Substitution:Southeastern growers facing synthetic fungicide resistance pressures are expanding fungal biofungicide procurement for high-value tomato and strawberry production systems.
Market Restraints
- Fermentation Input Volatility:Microbial production depends on molasses and soybean meal feedstocks, exposing manufacturers to agricultural commodity price swings that compress margin buffers.
- California Distribution Concentration:Three agricultural cooperatives control over sixty percent of specialty crop input distribution in the Central Valley, creating gatekeeper bottlenecks for new market entrants.
- Field Efficacy Variability:Temperature and humidity sensitivity limits bacterial bioinsecticide performance consistency, restricting grower confidence in broad-acre row crop applications.
Strategic Opportunities
- Texas High-Value Vegetable Expansion:Winter vegetable production in the Rio Grande Valley remains underpenetrated by microbial crop protection, offering first-mover positioning for established suppliers.
- Greenhouse Premium Channel:Controlled-environment agriculture operators in Arizona and Colorado prioritize residue-free protocols, commanding pricing premiums for aqueous suspension formulations.
- State Buffer Zone Harmonization:Pending regulatory alignment between California DPR and Florida FDACS on application setback requirements would reduce compliance fragmentation costs.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Microbial stabilization expertise combining fermentation science with adjuvant chemistry commands premium compensation, constraining R&D team scaling.
- Legacy Equipment Integration:Conventional sprayer systems designed for synthetic chemicals require retrofitting for proper microbial viability maintenance, complicating grower adoption workflows.
- Resistance Monitoring Infrastructure:Limited field surveillance networks for pest susceptibility to biological modes of action delay product rotation recommendations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biopesticides Market |
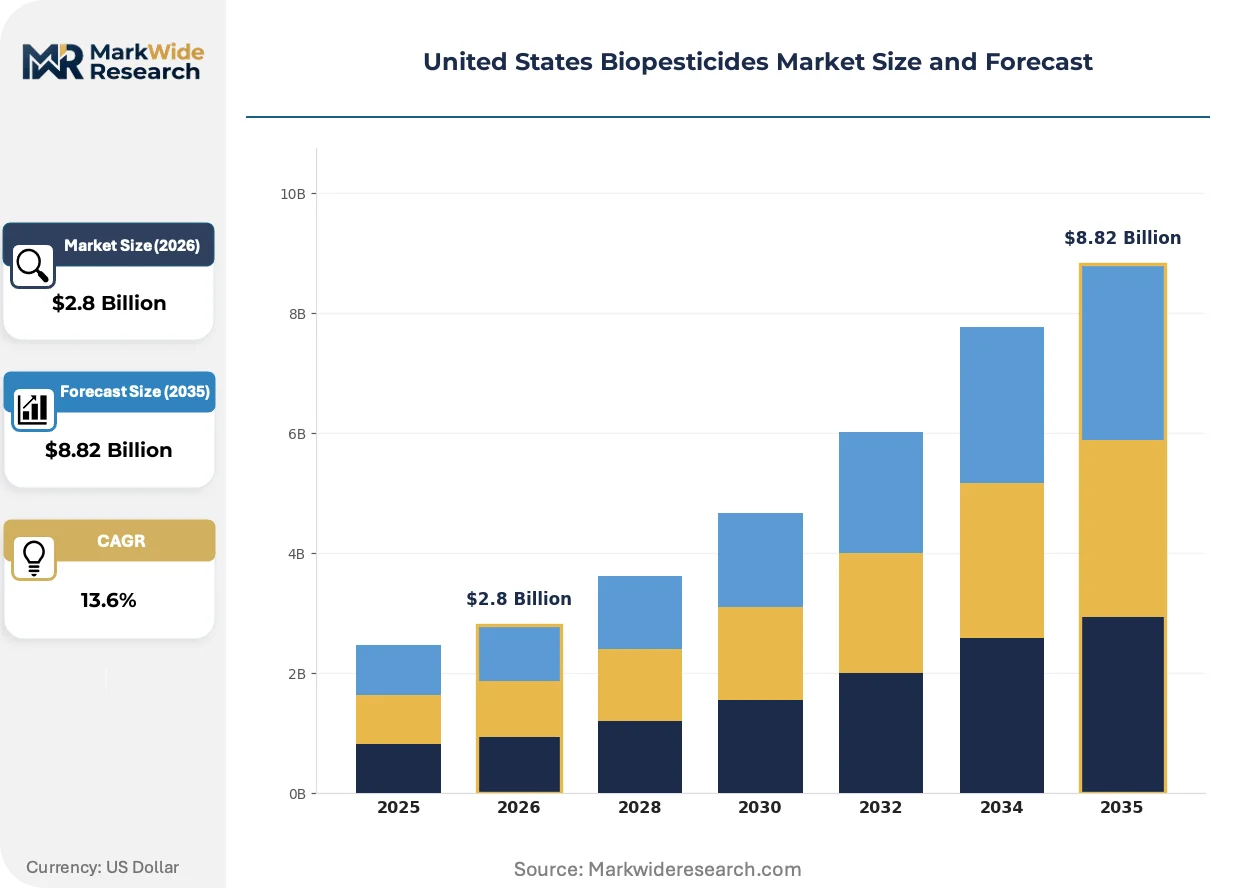
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Bioinsecticides, Fungal Biofungicides, Plant-Based Formulations, Bioherbicides Application: Agricultural Crops, Fruits & Vegetables, Turf & Ornamental, Greenhouses End User: Farmers, Commercial Growers, Landscaping Professionals, Agricultural Cooperatives Distribution Channel: Online Retail, Traditional Retail, Direct Sales, Distributors |
| Companies Covered | Certis USA LLC, Valent BioSciences LLC, Marrone Bio Innovations, BioWorks Inc., Corteva Agriscience, FMC Corporation, BASF SE, Bayer AG, Koppert B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biopesticides Market Evolving Landscape
RNA interference technology is advancing from experimental platforms toward commercial bioinsecticide formulations, triggering a wave of patent positioning and manufacturing scale-up investments across the sector.
Double-stranded RNA delivery systems targeting lepidopteran pests are electrifying research pipelines at agricultural biotechnology firms, with several candidates entering EPA review. Specialty crop growers in Florida citrus and California tree nut operations are monitoring field trial results for resistance management compatibility. This platform is compressing development timelines for novel mode-of-action products while raising capital intensity requirements for production infrastructure.
FIFRA's microbial pesticide data requirements are tightening around genetic characterization standards, forcing reformulation of legacy products to meet amended guidance. The industrial consequence is a bifurcation between well-capitalized firms with sequencing capabilities and smaller registrants facing compliance cost barriers. Bacterial bioinsecticide categories face the steepest re-registration burdens, with California DPR adding supplementary efficacy verification protocols.
Direct-to-grower digital platforms are displacing traditional cooperative-dependent purchasing patterns among mid-scale vegetable operations. Agronomic data services bundled with biological input subscriptions are capturing share in Arizona leafy green and Colorado potato production networks. This channel evolution is most visible in the Intermountain West, where geographic dispersion from Central Valley distribution hubs created service gaps that e-commerce models fill.
United States Biopesticides Market Segmentation
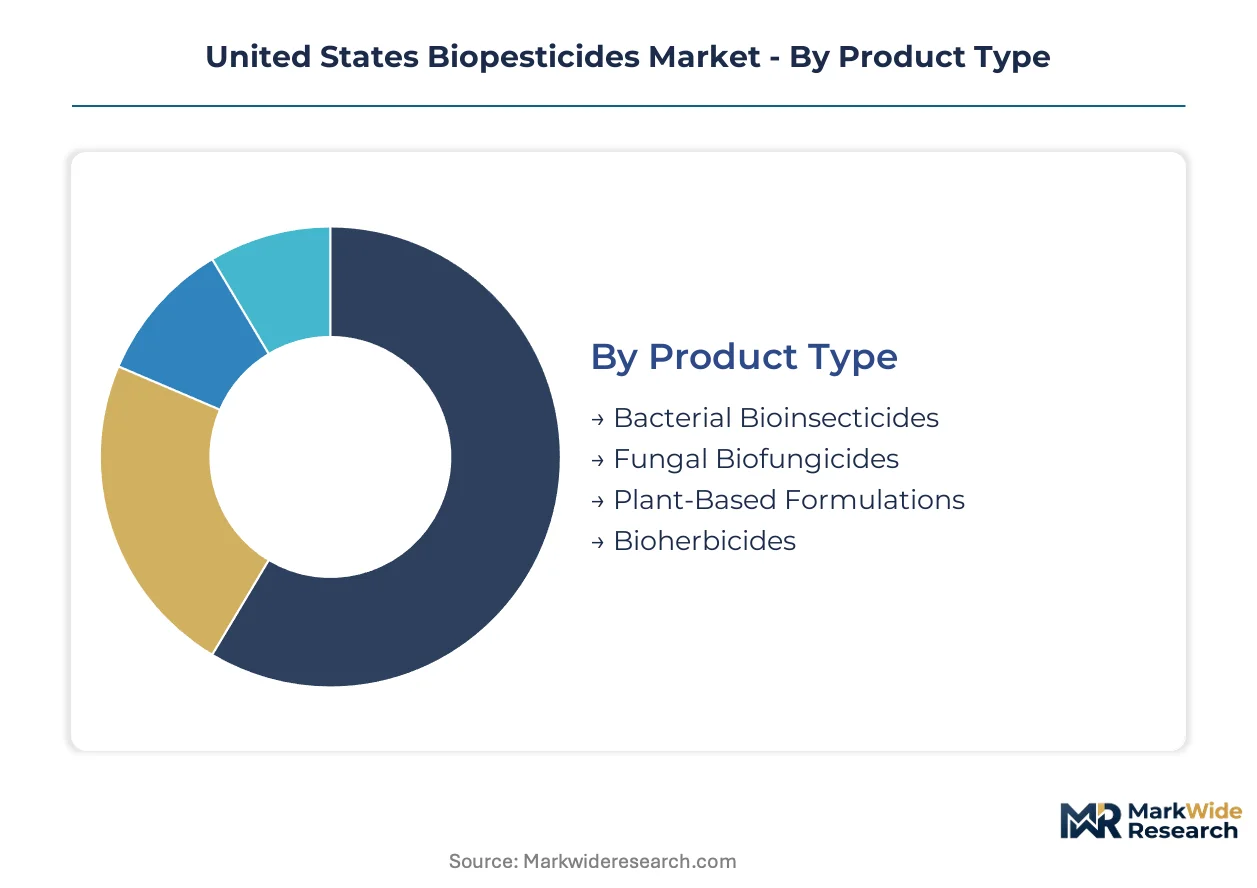
Segmentation in the United States biopesticides market reveals how formulation chemistry, application environment, and procurement channels create distinct competitive arenas. Each dimension carries unique margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Standardization dominates bacterial and fungal platforms, while plant-based and herbicide formulations require more customized active ingredient sourcing.
- Bacterial Bioinsecticides:Fermentation-derived Bacillus thuringiensis and related species form aqueous suspensions targeting lepidopteran larvae. Demand concentrates in California Central Valley tomato and lettuce operations where resistance management protocols mandate rotation partners.
- Fungal Biofungicides:Trichoderma and Beauveria species formulated as wettable powders or granules. Florida strawberry and tomato growers in humid Gulf Coast counties drive procurement as synthetic fungicide alternatives face regulatory pressure.
- Plant-Based Formulations:Pyrethrin and neem-derived compounds.
- Bioherbicides:Microbial and botanical agents for weed suppression.
Most installed capacity flows through bacterial bioinsecticides. Expansion is steepest in fungal biofungicides.
Application:
Volume scale separates broad-acre row crops from precision-intensive protected agriculture, with residue protocols creating tiered pricing power.
- Agricultural Crops:Corn, soybean, and wheat applications where bacterial bioinsecticides integrate into integrated pest management rotation schedules. Midwest growers in Iowa and Illinois evaluate cost-per-acre against synthetic alternatives.
- Fruits & Vegetables:High-value specialty crop protection dominates absolute revenue. California and Florida operations command technical service intensity from suppliers.
- Turf & Ornamental:Golf course and landscape maintenance segments.
- Greenhouses:Controlled-environment vegetable and ornamental production.
Revenue concentration sits with fruits and vegetables. Protected agriculture environments are climbing the fastest.
End User:
Procurement sophistication varies from price-sensitive individual operators to volume-aggregating cooperative entities with technical specification influence.
- Farmers:Individual owner-operators managing diversified crop portfolios across the Pacific Northwest and Great Lakes states.
- Commercial Growers:Large-scale specialty crop enterprises in California's Salinas Valley and Florida's Winter Haven region with dedicated agronomy staff.
- Landscaping Professionals:Municipal and commercial turf maintenance contractors.
- Agricultural Cooperatives:Member-owned purchasing entities controlling Central Valley input distribution.
Most formulation volume moves through commercial growers. Cooperative procurement is gaining share fastest.
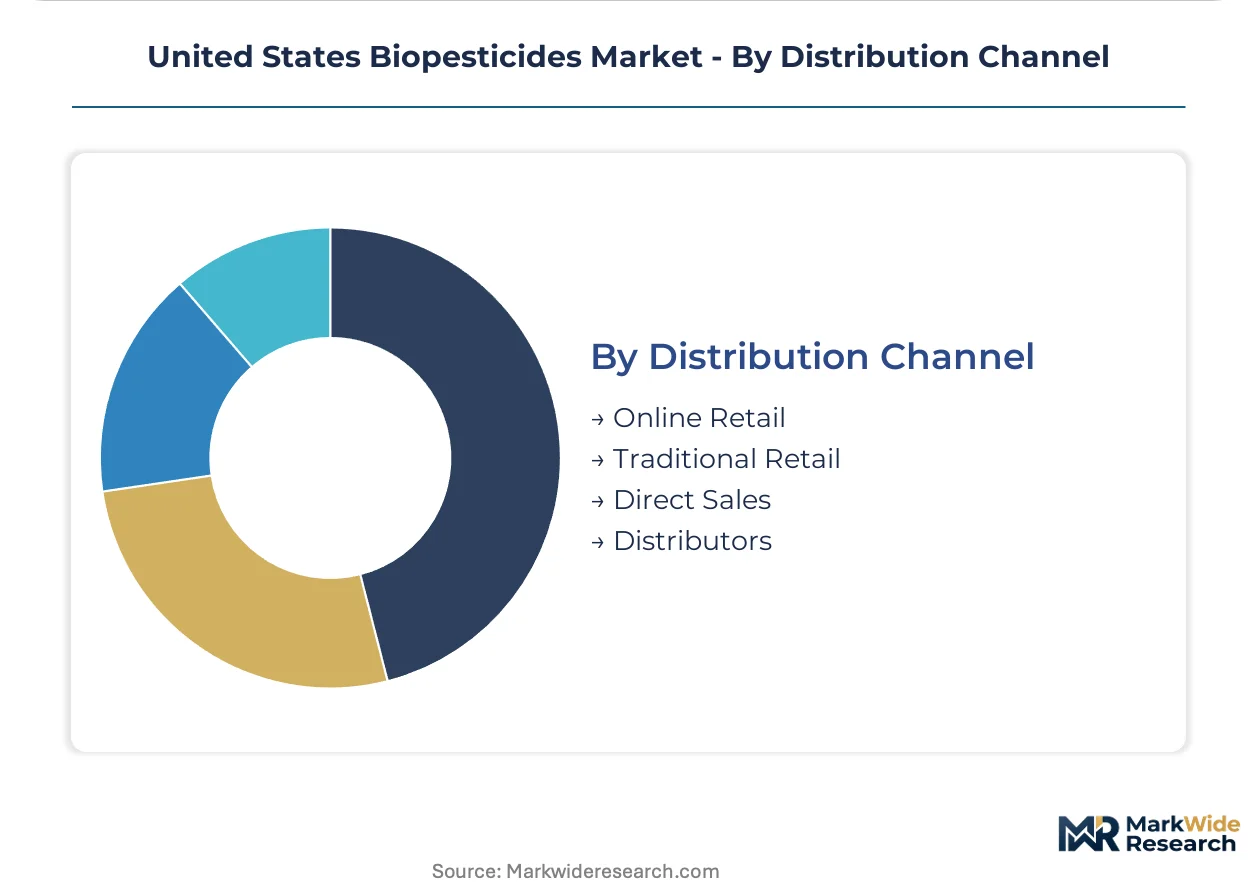
Distribution Channel:
Physical proximity requirements for technical service create friction against pure digital displacement, though subscription models are emerging.
- Online Retail:E-commerce platforms serving mid-scale vegetable operations in Arizona and Colorado where geographic dispersion from cooperative hubs created service gaps.
- Traditional Retail:Brick-and-mortar farm supply stores with local agronomic consultation.
- Direct Sales:Manufacturer-to-grower relationships for mega-acreage accounts.
- Distributors:Third-party logistics and technical service networks.
Most product flow routes through traditional retail. Direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California generates substantially higher biopesticide procurement volumes than Florida despite both states specializing in high-value fruit and vegetable production, reflecting divergent regulatory enforcement intensity and cooperative distribution structures across the two markets.
California
Specialty crop consolidation in the Central Valley and Salinas Valley drives concentrated demand for bacterial bioinsecticides and fungal biofungicides. The California Department of Pesticide Regulation enforces supplementary efficacy verification protocols beyond EPA baseline requirements. Fresno County and Monterey County anchor the nation's densest microbial crop protection procurement clusters, with mega-grower accounts commanding dedicated technical service teams from suppliers.
Florida
Humid Gulf Coast conditions accelerate fungal biofungicide substitution for synthetic alternatives in strawberry and tomato operations. The Florida Department of Agriculture and Consumer Services maintains state-specific buffer zone regulations that shape application protocols. Winter Haven and Plant City form the core production belt where resistance pressures against conventional fungicides push biological adoption rates above national averages.
Texas
Rio Grande Valley winter vegetable expansion creates underpenetrated territory for microbial crop protection agents serving onion and leafy green producers. USDA conservation cost-share programs subsidize biological input trials in Cameron County and Hidalgo County. McAllen-based distribution networks remain fragmented compared to California cooperative concentration, opening channels for direct manufacturer engagement.
Arizona
Controlled-environment agriculture in Yuma County and Maricopa County commands premium pricing for residue-free aqueous suspension formulations. The Arizona Department of Agriculture coordinates with EPA Region 9 on streamlined enforcement of FIFRA-compliant products. E-commerce subscription models capture growing share among mid-scale lettuce and melon growers dispersed from traditional cooperative hubs.
Pacific Northwest
Washington apple and Oregon wine grape producers integrate bacterial bioinsecticides into codling moth and mealybug management programs. State departments of agriculture in Olympia and Salem administer organic certification support programs that lower biological input switching costs. Yakima Valley and Willamette Valley processing cooperatives negotiate volume-based procurement contracts with microbial formulation suppliers.
United States Biopesticides Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation among agricultural input suppliers has compressed the vendor base into three recognizable strategic groupings: global agrochemical majors with biological divisions, dedicated microbial technology firms, and regional fermentation-based specialists. Competitive dynamics center on distribution partnership depth and fermentation capacity expansion rather than price-based rivalry.
Within the pure-play specialist tier, Marrone Bio Innovations and Valent BioSciences LLC exemplify focused microbial technology strategies. Certis USA LLC occupies a position representing regional fermentation capabilities serving specialty crop segments. Bayer AG and BASF SE anchor the diversified conglomerate approach, leveraging existing distribution infrastructure to bundle biological offerings with synthetic portfolios.
| Leading Market Players |
|---|
| Certis USA LLC |
| Valent BioSciences LLC |
| Marrone Bio Innovations |
| BioWorks Inc. |
| Corteva Agriscience |
| FMC Corporation |
| BASF SE |
| Bayer AG |
| Koppert B.V. |
| Others |
Value Network & Pricing Analysis
Molasses and soybean meal price indices cascade directly through fermentation economics into three-tier pricing structure across premium, standard, and economy levels for microbial crop protection formulations. California Central Valley cooperative concentration amplifies buyer leverage, compressing margin buffers for suppliers dependent on volatile agricultural commodity feedstocks.
Pricing Analysis
Capacity additions in Iowa and Illinois fermentation facilities are reshaping price floors for bacterial bioinsecticides, intensifying cost compression in the standard tier where Midwest row crop growers dominate procurement. Three-tier pricing structure across premium, standard, and economy levels separates residue-free greenhouse formulations from broad-acre aqueous suspensions and generic wettable powders. Price differentiation hinges on EPA registration tier and volume scale, with mega-grower accounts in Fresno County commanding steepest discounts. Greenhouse operators in Arizona and Colorado exhibit least price sensitivity due to residue protocol premiums, while individual owner-operators in the Pacific Northwest face acute budget constraints.
Supply Chain Analysis
Freight costs from Heartland fermentation hubs to coastal specialty crop regions constitute a material landed cost component, favoring suppliers with distributed production footprints. Supply concentrates in Iowa, Illinois, and Indiana fermentation corridors, with raw material dependencies on domestic molasses, soybean meal, and specialized nitrogen sources. Single-source vulnerability runs through California Central Valley distribution cooperatives controlling input flow to sixty percent of specialty crop acreage. Distribution runs through agricultural cooperative networks, though direct-to-grower digital platforms are capturing share in geographically dispersed Intermountain West markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States biopesticides constitute a late-cycle quality story as residue-free procurement specifications displace synthetic alternatives in premium supply chains. Specialty crop growers now mandate microbial stabilization performance as a baseline qualification rather than discretionary upgrade.
For Market Incumbents: Lock in fermentation capacity expansion across the Corn Belt to secure feedstock proximity advantages against margin compression from agricultural commodity volatility. Deepen technical service team deployment in Fresno County and Monterey County mega-grower accounts to defend against cooperative gatekeeper consolidation. Prioritize genetic characterization sequencing investments to meet tightening EPA FIFRA re-registration requirements before smaller competitors face compliance cost barriers. For New Entrants and Emerging Players: Agricultural cooperatives in the Rio Grande Valley represent the most penetrable channel partner type for winter vegetable market entry, given fragmented McAllen-based distribution relative to California concentration. Target Cameron County and Hidalgo County onion and leafy green producers with USDA conservation cost-share program bundling. Pursue subscription-based agronomic data services to bypass traditional cooperative-dependent purchasing patterns among mid-scale Arizona lettuce operations. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play microbial technology specialists possessing proprietary fermentation platforms and deep California distribution partnerships. Five-to-ten year viability favors firms with demonstrated EPA registration navigation capabilities and state-level DPR/FDACS compliance track records. Monitor RNA interference bioinsecticide pipeline advancement as inflection indicator for platform transition capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Proximity to Iowa and Illinois feedstock sources reduces molasses transport cost exposure. |
| Genetic Characterization Investment | EPA FIFRA tightening on microbial data requirements creates compliance moat against undercapitalized registrants. |
| Direct-to-Grower Platform Launch | Arizona and Colorado geographic dispersion from cooperative hubs enables digital channel capture. |
| RNA Interference Pipeline Advancement | Double-stranded RNA delivery systems target lepidopteran pests with novel mode-of-action differentiation. |
| Technical Service Intensification | Salinas Valley mega-grower accounts demand dedicated agronomic support for resistance management protocols. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, agricultural cooperative procurement leads, EPA regulatory affairs specialists, and specialty crop agronomists with secondary validation against USDA NASS crop protection surveys, EPA registration databases, California DPR pesticide use reports, and Florida FDACS agricultural statistics. Bottom-up formulation volume estimates triangulated against top-down market sizing from trade flow analysis.
Segment-weighting across bacterial bioinsecticides, fungal biofungicides, plant-based formulations, and bioherbicides incorporated application environment differentiation between broad-acre row crops and controlled-environment agriculture. Modeled dimensions included product type chemistry, fruit and vegetable versus grain crop end-use, and cooperative versus direct procurement channel splits. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory catalyst timing and conservation program incentive trajectories. Forecast inputs incorporated EPA FIFRA review pipeline status and state-level buffer zone harmonization probability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RNA interference technology commercialization timelines and agricultural commodity feedstock volatility. Forecasts reflect documented assumptions around EPA registration throughput rates and USDA conservation cost-share program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Africa Biofertilizer Market