
 India Biostimulants Market | 2026-2036
India Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
India Biostimulants Market Insights
Agronomist and plant physiology expertise is reorganizing competitive dynamics in the India biostimulants sector, as firms race to build technical advisory teams capable of demonstrating yield outcomes at the farm level. Coromandel International Ltd leverages its deep rural distribution network to push liquid formulations through cooperative channels. UPL Limited anchors its position through backward integration into seaweed extraction and microbial fermentation capacity. T.Stanes and Company Limited specializes in microbial stimulators tailored for South Indian coffee and spice plantations.
Biostimulants comprise organic and biological substances applied to plants or soil to enhance nutrient uptake efficiency, abiotic stress tolerance, and crop quality traits without direct nutritive value; formulations typically contain amino acids at concentrations between 8-12 percent, humic acids derived from leonardite oxidation, or live microbial consortia exceeding 10^8 CFU per gram. Their primary commercial purpose centers on reducing synthetic input dependency while securing yield stability under heat and drought stress. Seaweed extracts and humic substances command the largest volume positions due to established supply chains from Tamil Nadu and Gujarat coastal processing units. Microbial stimulators represent the fastest-expanding category as Indian regulators relax import barriers on beneficial fungi and rhizobacteria strains. Amino acid formulations concentrate margin pools in high-value horticulture segments where export certification requirements demand residue-free production protocols.
The Fertilizer Control Order under India's Ministry of Agriculture and Farmers Welfare, alongside BIS certification requirements and state-level agricultural department procurement guidelines, is formalizing quality standards that filter out unregistered suppliers and redirect institutional demand toward compliant manufacturers. DGFT import policy notifications shape the cost structure for seaweed raw materials and microbial母 strains sourced from East Asian fermentation facilities. Stakeholders must monitor how state-level organic mission programs integrate biostimulants into subsidized input baskets, as this channel access will determine which product formats achieve household penetration among smallholder farmers.
Market Dynamics
The Fertilizer Control Order amendments under India's Ministry of Agriculture are compressing supplier margins by mandating BIS certification and formal registration pathways, forcing unregistered operators to exit while redirecting institutional procurement toward compliant manufacturers with established quality documentation.
Growth Catalysts
- Export-driven horticulture:Maharashtra's grape and pomegranate growers are integrating biostimulants into precision protocols to meet residue-free certification requirements for European and Middle Eastern buyers.
- DGFT import liberalization:Relaxed barriers on beneficial fungi and rhizobacteria strains are accelerating microbial stimulator availability for South Indian coffee and spice plantations.
- State organic mission integration:Gujarat and Karnataka are incorporating biostimulants into subsidized input baskets, creating channel access for smallholder farmers through cooperative networks.
Market Restraints
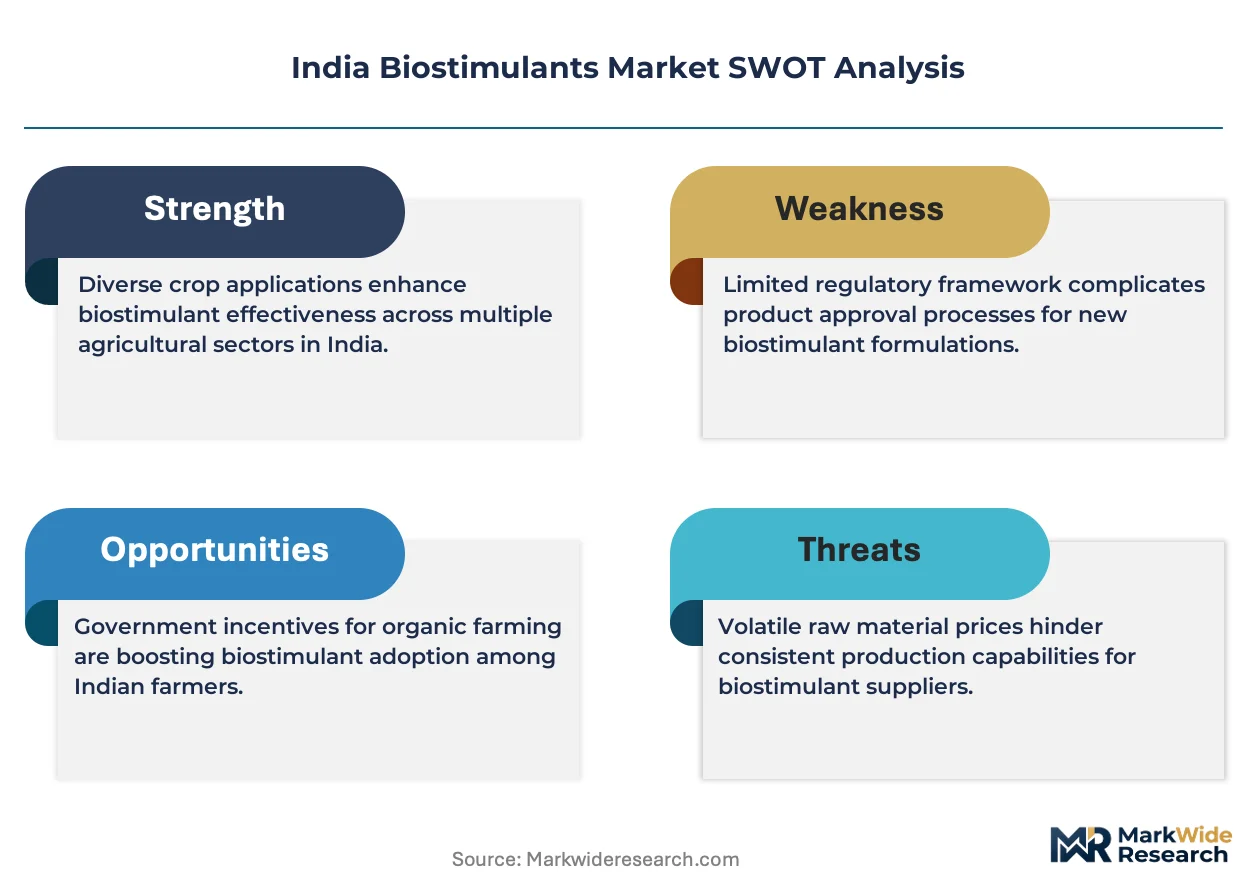
- Seaweed raw material concentration:Tamil Nadu and Gujarat coastal processing units dominate supply, exposing formulators to monsoon-driven harvest volatility and price spikes.
- Fermentation facility scarcity:Limited domestic capacity for microbial母 strain propagation forces reliance on East Asian suppliers, inflating working capital requirements.
- Leonardite sourcing bottleneck:Humic acid producers face input constraints as domestic leonardite deposits deplete, increasing dependence on Mongolian and Russian imports.
Strategic Opportunities
- Contract farming network expansion:Karnataka's horticulture export zones present untapped penetration potential for liquid formulation distributors with technical advisory capabilities.
- Precision agriculture convergence:Integration of biostimulants with drone-based application systems and soil sensor networks is opening premium service contracts in Gujarat's cotton belt.
- PLI scheme alignment:India's production-linked incentive framework for agrochemical manufacturing offers capital subsidy pathways for domestic microbial fermentation infrastructure.
Industry Challenges
- Agronomist talent scarcity:Field demonstration of yield outcomes requires specialized plant physiology expertise that remains concentrated with established firms, constraining new entrant scale-up.
- Registration timeline compression:BIS certification and FCO compliance documentation cycles extend 18-24 months, delaying product launches and locking capital in regulatory pipelines.
- Farmer education gaps:Smallholder adoption lags in regions lacking cooperative extension services, as biostimulant benefits require multi-season demonstration to overcome synthetic fertilizer preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biostimulants Market |
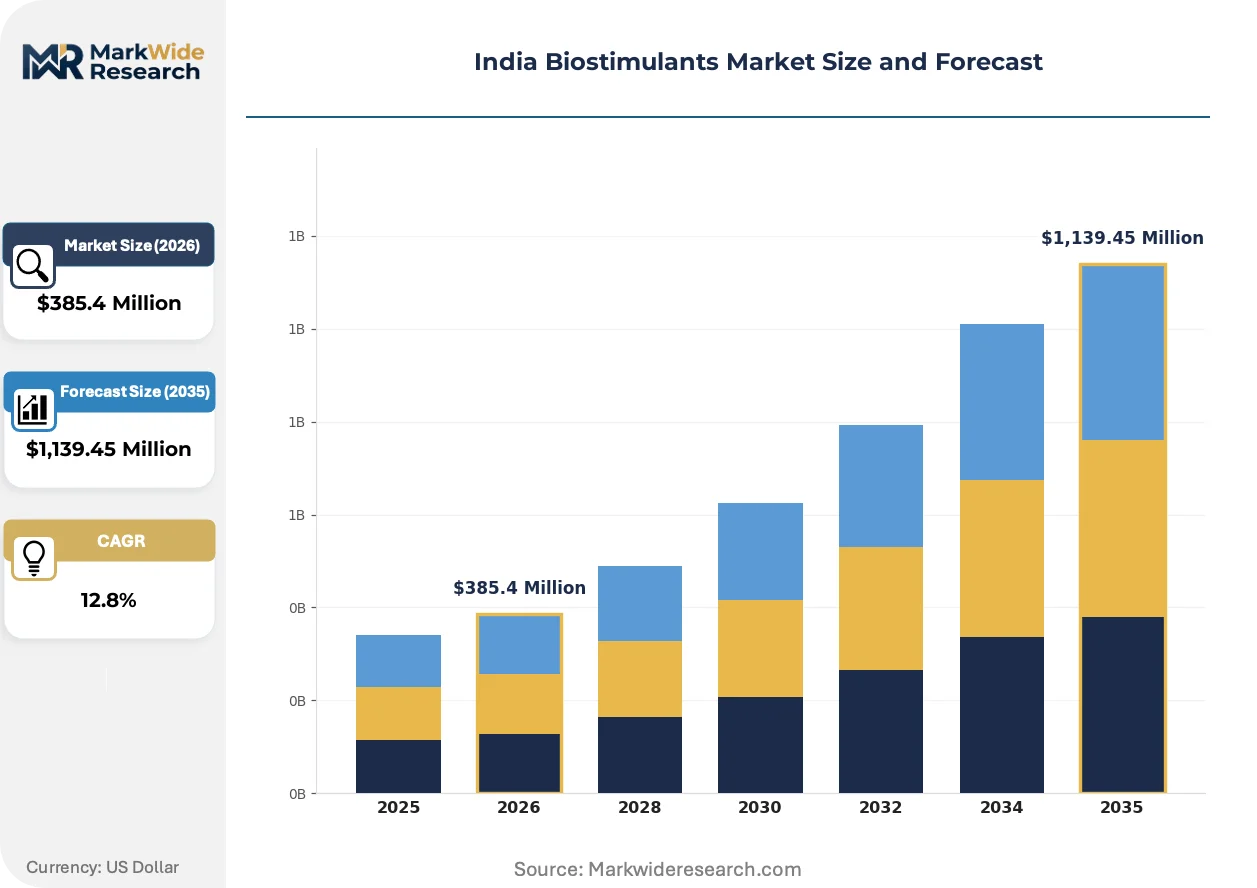
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,139.45 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Humic Substances, Seaweed Extracts, Microbial Stimulators Form: Liquid, Granular, Powder, Tablet Application: Cereals, Fruits, Vegetables, Turf & Ornamental Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Biostadt India Limited, Coromandel International Ltd, Southern Petrochemical Industries Corporation, T.Stanes and Company Limited, Valagro, Rallis India Ltd, Gujarat State Fertilizers & Chemicals Ltd, UPL Limited, Corteva Agriscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biostimulants Market Trends and Innovations
Formulation science and delivery mechanisms are diverging from standardized extracts toward targeted microbial consortia and nano-encapsulated actives, reshaping how manufacturers compete on efficacy demonstration rather than commodity supply.
Microbial stimulator technology is fragmenting the competitive landscape as multi-strain rhizobacteria formulations with phosphate-solubilizing and auxin-producing capabilities displace single-function seaweed extracts in high-value horticulture. Grape growers in Maharashtra and coffee estates in Karnataka are piloting these consortia under export contract specifications. The shift is compressing margins for pure-play extract suppliers while rewarding integrated fermentation capabilities.
BIS certification requirements under India's Fertilizer Control Order amendments are formalizing quality thresholds that filter unregistered suppliers from institutional procurement channels. State agricultural departments are redirecting subsidized input baskets toward compliant manufacturers with documented CFU counts and heavy metal limits. This regulatory tightening most affects microbial stimulator imports, where DGFT notifications now mandate strain-level registration with the Central Insecticides Board.
Farmer purchasing patterns are rotating from input dealers toward direct manufacturer engagement through embedded agronomist advisory models. Coromandel International and UPL Limited are deploying technical teams to cooperative societies in Gujarat and Maharashtra, displacing traditional distributor relationships with outcome-based service contracts. This channel compression is most visible in cotton and horticulture belts where precision agriculture protocols require integrated input recommendations rather than commodity transactions.
India Biostimulants Market Segmentation
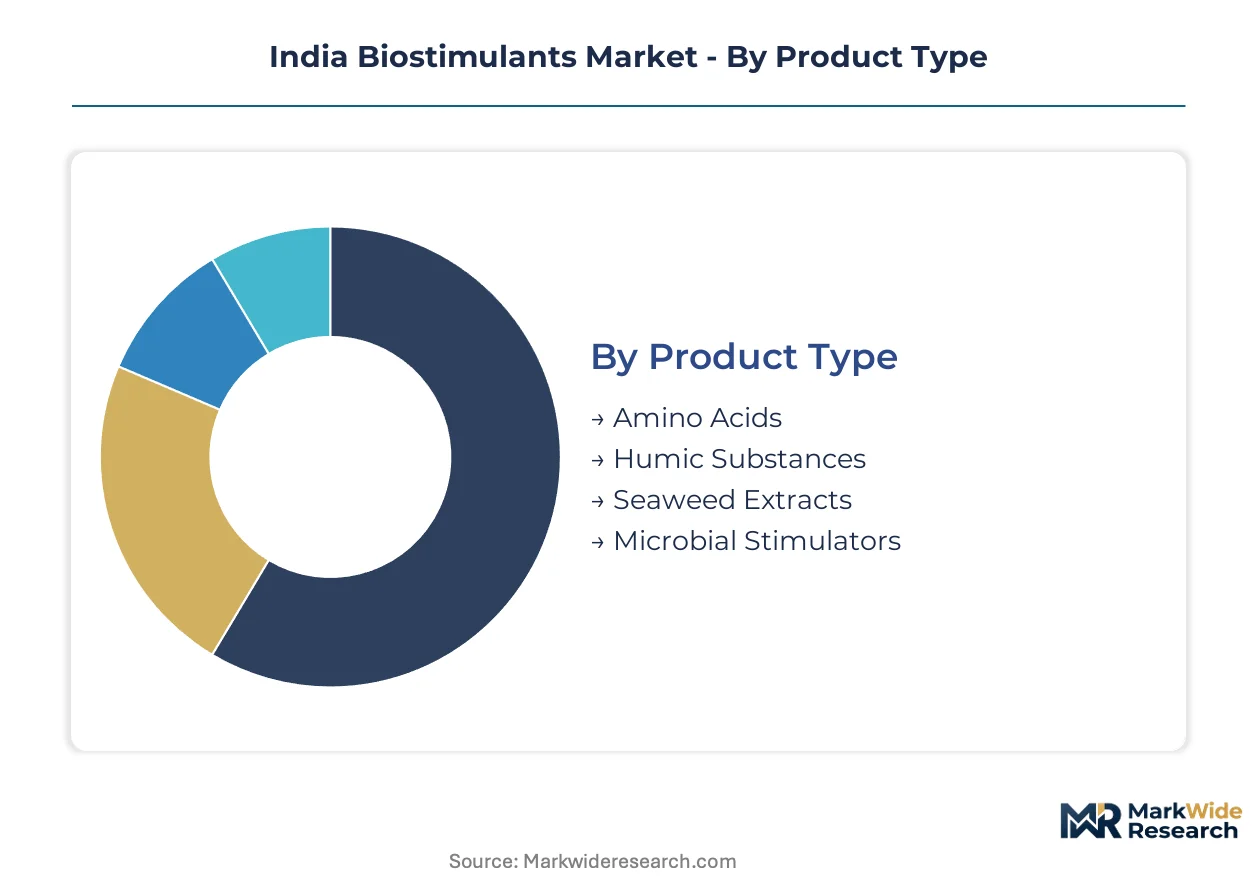
Biostimulant manufacturers compete across distinct product chemistry, physical form, crop application, and channel access dimensions. Each segmentation axis carries different margin profiles and regulatory exposure under India's evolving Fertilizer Control Order framework.
Product Type:
Margin pools concentrate in microbial stimulators and amino acid formulations where technical differentiation commands premium pricing, while seaweed extracts and humic substances operate on volume-driven, commodity-like economics.
- Microbial Stimulators:Multi-strain rhizobacteria consortia with phosphate-solubilizing and auxin-producing capabilities, typically exceeding 10^8 CFU per gram. Karnataka coffee estates and Maharashtra grape growers are piloting these under export contract specifications, though DGFT strain-level registration with the Central Insecticides Board creates compliance bottlenecks.
- Amino Acids:Protein hydrolysate formulations containing 8-12 percent free amino acids, often blended with micronutrients. Margin concentration sits in high-value horticulture segments where European and Middle Eastern residue-free certification requirements demand documented production protocols.
- Seaweed Extracts:Coastal processing units in Tamil Nadu and Gujarat dominate supply chains for these established formulations.
- Humic Substances:Leonardite-derived humic and fulvic acid products face sourcing constraints as domestic deposits deplete.
The dominant share belongs to seaweed extracts, while microbial stimulators are closing the gap fastest.
Form:
Physical format selection hinges on application equipment compatibility and farmer operational scale, with liquid formulations capturing cooperative channel volume and solid forms serving smallholder convenience.
- Liquid:Concentrated suspensions and solutions compatible with drip irrigation and foliar spray systems. Coromandel International pushes these through cooperative channels in Gujarat and Maharashtra where precision agriculture protocols require metered dosing.
- Powder:Dry concentrates offering transport cost advantages and extended shelf stability. These formats penetrate remote districts with limited cold chain infrastructure.
- Granular:Slow-release matrix formulations suited for basal application in field crops.
- Tablet:Pre-measured single-dose units targeting smallholder convenience and reducing application error.
Liquid formulations hold the volume lead, yet powder formats are gaining traction fastest in underserved hinterland markets.
Application:
Crop-specific demand patterns split between broad-acre field crops with price-sensitive purchasing and intensive horticulture with quality-premium capture potential.
- Fruits:Grape and pomegranate growers in Maharashtra integrate biostimulants into precision protocols to meet residue-free export certification. Stress tolerance and fruit set quality improvements justify repeated application cycles through the growing season.
- Vegetables:Protected cultivation and contract farming networks in Gujarat drive consistent demand for quality-enhancing inputs with documented heavy metal limits.
- Cereals:Wheat and rice applications focus on abiotic stress mitigation during heat and drought periods.
- Turf & Ornamental:Golf courses and urban landscaping represent a niche premium segment.
Fruits command the premium pricing tier, though vegetables are expanding their share most rapidly through contract farming network integration.
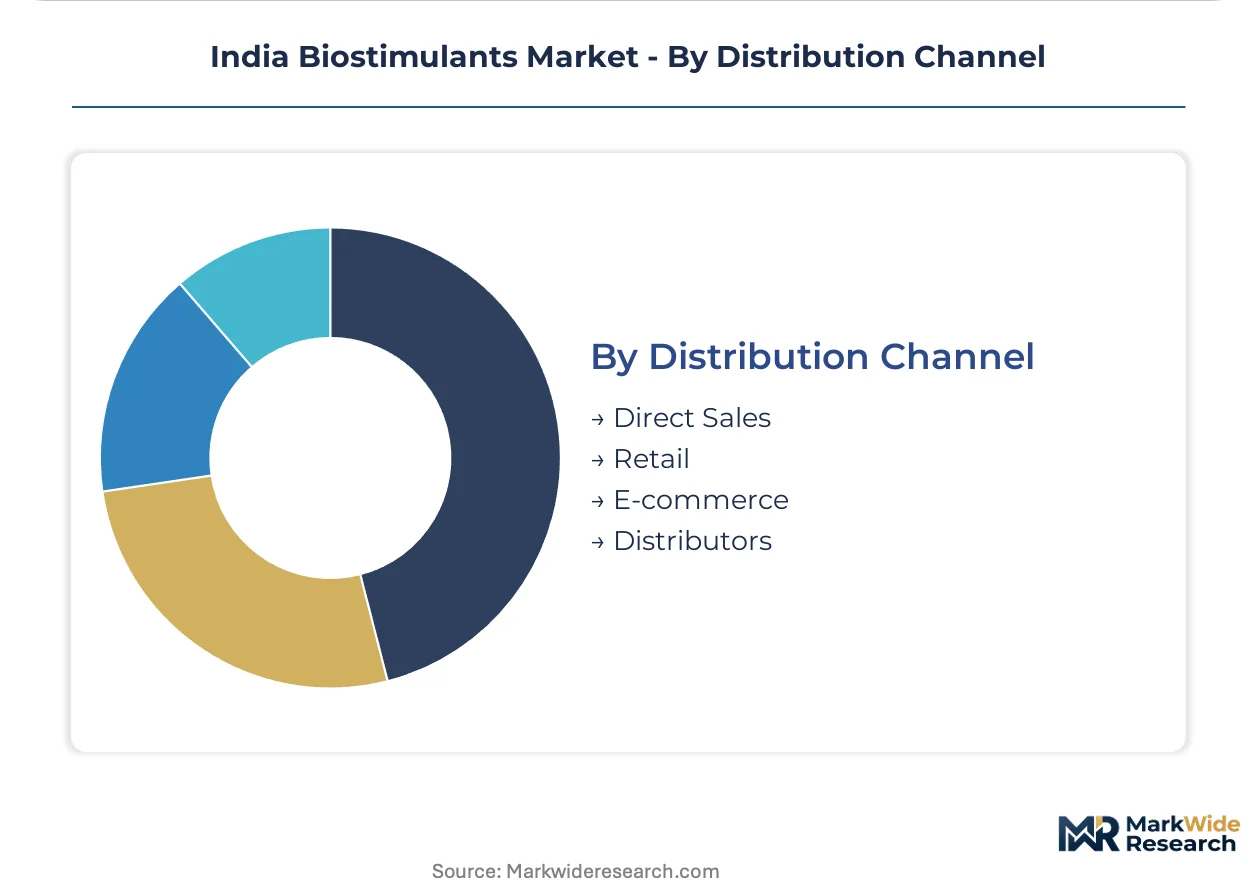
Distribution Channel:
Channel structure is compressing as manufacturers deploy embedded agronomist teams to displace traditional dealer relationships with outcome-based service contracts.
- Direct Sales:Manufacturer-to-farmer engagement through technical advisory teams deployed to cooperative societies. UPL Limited and Coromandel International are displacing traditional distributors with integrated input recommendations in cotton and horticulture belts.
- Distributors:Regional stockists maintaining local inventory and credit relationships, though their role diminishes where precision agriculture protocols require specialized technical support.
- Retail:Input dealer networks serving smallholders with commodity transactions and limited advisory capacity.
- E-commerce:Emerging platform-based procurement for progressive farmers with smartphone access and input financing availability.
Direct sales channels capture the highest growth trajectory, while distributor networks retain volume dominance in traditional procurement regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra consumes biostimulants through export-oriented horticulture protocols, while Gujarat deploys them within subsidized cooperative frameworks, and Karnataka integrates them into precision coffee estate management—each state applying the technology toward distinct agricultural outcomes.
Maharashtra
Grape and pomegranate growers dominate biostimulant procurement, driven by European and Middle Eastern residue-free certification requirements. The state agricultural department channels Fertilizer Control Order compliance documentation through Pune and Nashik regulatory offices. Processing clusters around Sangli and Solapur are expanding liquid formulation storage capacity to support precision application cycles through extended growing seasons.
Gujarat
Cotton belt contract farming networks generate concentrated demand for abiotic stress mitigation inputs during heat and drought periods. State organic mission programs incorporate biostimulants into subsidized input baskets distributed through Anand and Rajkot cooperative societies. Coastal processing units near Porbandar and Jamnagar maintain seaweed extract supply chains vulnerable to monsoon harvest volatility.
Karnataka
Coffee and spice plantations in Kodagu and Chikmagalur districts pilot multi-strain microbial consortia under export contract specifications. DGFT strain-level registration with the Central Insecticides Board creates compliance bottlenecks for beneficial fungi imports through Bengaluru customs corridors. Precision agriculture convergence with drone-based application systems is opening premium service contracts in the state's horticulture export zones.
Tamil Nadu
Coastal seaweed processing facilities between Rameswaram and Thoothukudi anchor national supply chains for extract-based formulations. BIS certification requirements under FCO amendments are filtering unregistered suppliers from institutional procurement channels serving Cauvery delta rice cultivation. Fermentation facility scarcity limits domestic microbial strain propagation, forcing reliance on East Asian suppliers through Chennai port infrastructure.
Andhra Pradesh
Chilli and mango growers in Guntur and Krishna districts are integrating biostimulants into protected cultivation protocols for quality-premium capture. State-level agricultural department procurement guidelines redirect demand toward BIS-compliant manufacturers with documented heavy metal limits. Godavari delta field crops present underpenetrated volume potential where cooperative extension services remain underdeveloped.
India Biostimulants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding cooperative channel access and fermentation infrastructure while specialists carve positions in crop-specific microbial formulations. The competitive terrain splits between distributors with embedded agronomist teams and pure-play manufacturers dependent on third-party technical partnerships. Two strategic archetypes dominate: backward-integrated extract processors with coastal supply control, and formulation houses with Central Insecticides Board registration capabilities. Capacity expansion into domestic microbial fermentation and acquisition of BIS certification documentation are the prevailing competitive moves.
Within the integrated leader tier, Coromandel International Ltd and UPL Limited occupy positions defined by distribution depth and captive supply infrastructure respectively. T.Stanes and Company Limited represents the specialist archetype, with its organizational structure indicating concentrated focus on South Indian plantation crops. These three entities exemplify how competitive positioning in this market derives from channel architecture and regulatory compliance velocity rather than product differentiation alone.
| Leading Market Players |
|---|
| Biostadt India Limited |
| Coromandel International Ltd |
| Southern Petrochemical Industries Corporation |
| T.Stanes and Company Limited |
| Valagro |
| Rallis India Ltd |
| Gujarat State Fertilizers & Chemicals Ltd |
| UPL Limited |
| Corteva Agriscience |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month BIS certification and FCO compliance documentation cycles lock working capital in regulatory pipelines, compressing supplier margins while amplifying pricing power for compliant manufacturers with established quality documentation and cooperative channel access.
Pricing Analysis
Long-term offtake agreements between coastal seaweed processors and Maharashtra grape exporters anchor the premium tier, while spot purchasing dominates smallholder procurement through retail dealer networks. Price differentiation rests on BIS certification grade and volume scale, with export-contract growers paying premiums for documented heavy metal limits and CFU count verification. Cost compression in the microbial stimulator category is intensifying as DGFT strain-level registration requirements extend import timelines. Cooperative societies in Gujarat and Karnataka exhibit the lowest price sensitivity due to subsidized input basket integration, whereas unaffiliated smallholders in Andhra Pradesh's Godavari delta remain highly price-responsive.
Supply Chain Analysis
Strategic stockpiling of leonardite-derived humic acid precursors characterizes manufacturer behavior as domestic deposits deplete, forcing reliance on Mongolian and Russian imports with extended replenishment horizons. Raw material sourcing concentrates in Tamil Nadu and Gujarat coastal processing units for seaweed extracts, East Asian fermentation facilities for microbial母 strains, and Central Asian mining operations for humic acid feedstock. Single-source vulnerability runs through the microbial stimulator pipeline where limited domestic propagation capacity creates import dependency. Distribution runs through cooperative societies and direct manufacturer engagement in cotton and horticulture belts, displacing traditional dealer relationships where precision agriculture protocols require integrated technical advisory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India biostimulants market functions as a regulatory entrenchment story where BIS certification velocity and FCO compliance documentation create switching costs that lock institutional procurement channels against unregistered competitors.
For Market Incumbents: Fortify cooperative channel control by embedding agronomist teams at society level to demonstrate multi-season yield outcomes, while accelerating captive microbial fermentation capacity under PLI scheme capital subsidies to reduce East Asian import dependency. The emerging threat of multi-strain rhizobacteria specialists displacing single-function extract suppliers demands backward integration into strain propagation infrastructure.
For New Entrants and Emerging Players: Technical advisory service gaps in Andhra Pradesh's Godavari delta and Karnataka's hinterland coffee districts present white-space penetration opportunities where incumbent agronomist coverage remains thin. Target tablet and powder formulation segments in remote districts lacking cold chain infrastructure, leveraging pre-measured convenience to reduce application error without requiring precision equipment compatibility. A direct-to-cooperative go-to-market model with embedded demonstration plots offers the fastest credibility pathway.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance documentation requirements are filtering unregistered suppliers and redirecting institutional demand toward acquirable manufacturers with established BIS certification and Central Insecticides Board registration capabilities. The signal to watch is state-level organic mission program expansion into subsidized biostimulant baskets, which would inflect channel access and household penetration trajectories among smallholder farmers.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Microbial Fermentation Buildout | PLI scheme capital subsidies reduce import dependency on East Asian strain suppliers. |
| BIS Certification Fast-Track Investment | Compressed 18-24 month documentation cycles lock institutional procurement channel access. |
| Cooperative Society Technical Partnership | Embedded agronomist teams displace dealer relationships with outcome-based service contracts. |
| Seaweed Processing Capacity Expansion | Tamil Nadu and Gujarat coastal units secure supply chain control against monsoon volatility. |
| Multi-Strain Rhizobacteria Formulation Development | Phosphate-solubilizing consortia displace commodity extracts in export-oriented horticulture. |
Research Methodology
Cross-validation between regulatory filing analysis and field-level procurement pattern observation anchors the qualitative findings in documented compliance behavior and actual purchasing channel migration. Primary interviews with BIS certification officers, state agricultural department procurement leads, cooperative society managers, and plantation agronomists combined with secondary validation through FCO amendment records, DGFT notification databases, and state organic mission program guidelines. Bottom-up triangulation across product format shipment data and top-down reconciliation against institutional subsidy disbursement records ensure coverage consistency.
Sensitivity analysis around DGFT import liberalization pace and state subsidy program expansion frames the projection uncertainty. The analytical framework segments by product chemistry, physical form, crop application, and distribution channel across the modeling period, with CAGRs derived from regression against historical horticulture export volume growth and precision agriculture equipment penetration rates. Strain registration timeline assumptions and cooperative society coverage expansion curves serve as key forecast inputs.
Forecasts assume regulatory continuity in BIS certification requirements and FCO amendment implementation; material policy shifts would require re-modeling channel access assumptions and procurement eligibility criteria. Specific risks include DGFT strain import restriction tightening, state-level organic mission program funding volatility, and monsoon-driven seaweed harvest disruption. Revision becomes warranted when microbial stimulator registration backlog crosses thresholds that materially extend product launch timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Global Citrus Bioflavonoids Market