
 Biological Seed Treatment Market | 2026-2036
Biological Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Seed Treatment Market Intelligence
Multi-source microbial procurement is repositioning how seed treatment formulators secure active ingredients. BASF SE leverages its strain development pipeline to control proprietary Bacillus variants. Bayer AG anchors its biological platform through integrated seed-applied solutions. Novozymes A/S competes as a specialized enzyme and microbe supplier without downstream seed assets.
Biological seed treatment applies living microorganisms, botanical extracts, or microbial metabolites to seeds prior to planting to suppress pathogens, enhance nutrient availability, or induce systemic resistance in emerging seedlings. Formulations typically contain colony-forming units exceeding 10^8 per gram and require controlled-temperature supply chains to preserve viability. Bacterial inoculants dominate commercial volumes due to established efficacy in legume nodulation and broad-spectrum disease suppression. Fungal inoculants occupy a narrower but expanding niche in specialty vegetable and horticulture sectors where Trichoderma-based products command premium positioning. Mycorrhizal fungi sustain the fastest growth trajectory among product categories as arbuscular mycorrhizal formulations gain traction in phosphorus-deficient soils and regenerative agriculture protocols.
The EPA regulates biological seed treatments under the Federal Insecticide, Fungicide, and Rodenticide Act, requiring efficacy data and non-target organism risk assessments for product registration. The EU REACH framework and F-Gas Regulation constrain synthetic chemical alternatives, indirectly expanding the addressable market for microbial substitutes. Stakeholders must monitor evolving residue tolerance standards and strain patent landscapes to anticipate competitive entry points and formulation differentiation opportunities.
Market Dynamics
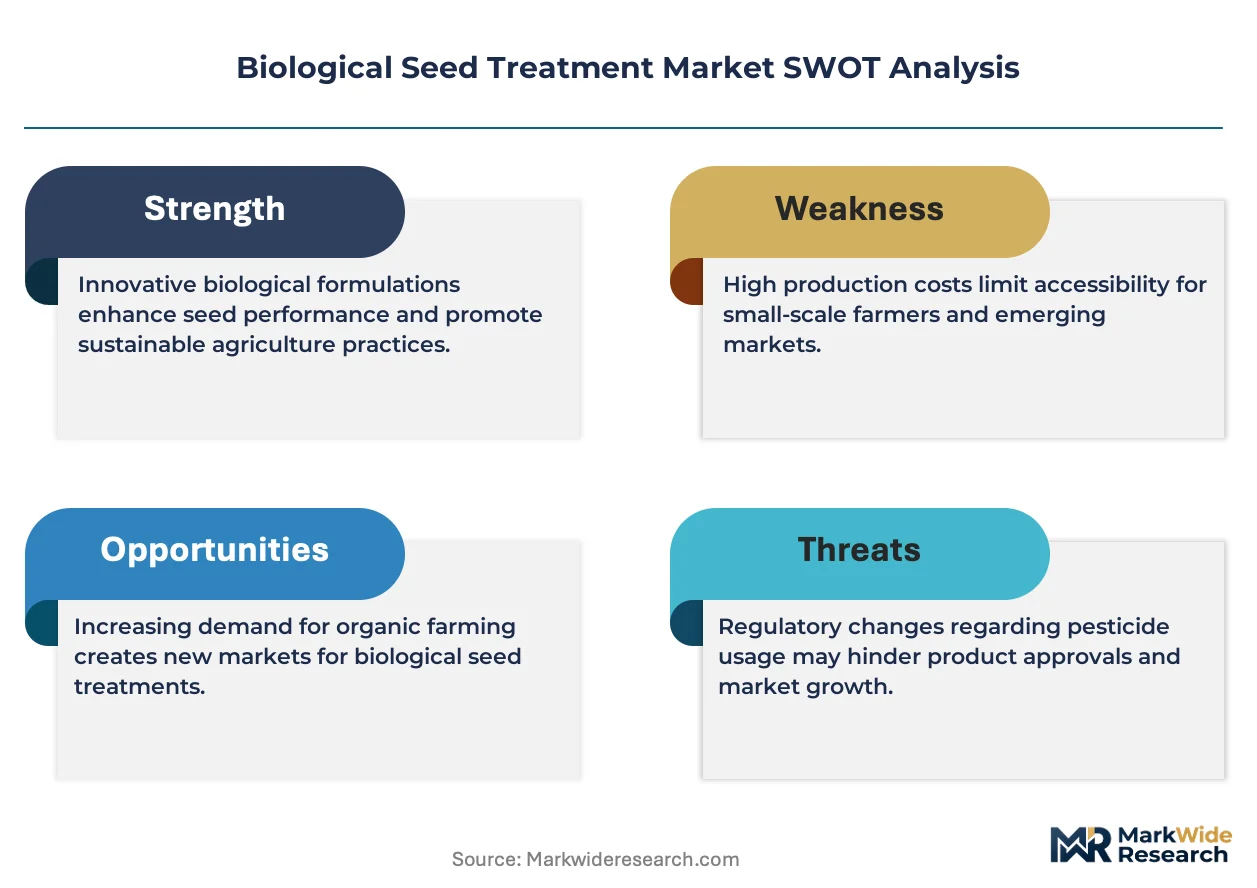
Synthetic fungicide phase-out mandates are compressing registration timelines for microbial alternatives while concentrating supply-side control among strain-development specialists with proprietary Bacillus and Trichoderma libraries.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:The EU Green Deal is accelerating microbial inoculant approvals by streamlining efficacy review protocols for rhizobia-based and Bacillus formulations.
- Row crop producers in the American Midwest:Corn and soybean farmers are expanding biological seed treatment programs to meet supply chain sustainability requirements from grain exporters and food processors.
- Brazil's soybean belt:The densest concentration of new demand for nitrogen-fixing inoculants is emerging across Mato Grosso and Rio Grande do Sul production zones.
Market Restraints
- Cold-chain infrastructure gaps:Controlled-temperature logistics for formulations exceeding 10^8 colony-forming units per gram remain underdeveloped in sub-Saharan Africa and Central Asian distribution corridors.
- Strain patent thickets:Proprietary Bacillus variant portfolios held by integrated agrochemical conglomerates are restricting independent formulator access to high-efficacy bacterial inoculants.
- Residue tolerance standard divergence:Inconsistent microbial metabolite thresholds between the EPA's FIFRA framework and the EU REACH regime are fragmenting product registration strategies.
Strategic Opportunities
- Phosphorus-deficient soil zones:Arbuscular mycorrhizal formulations are gaining traction in Australian wheat belts and Canadian prairie provinces where regenerative agriculture protocols are expanding.
- Specialty vegetable sectors:Trichoderma-based premium products command positioning in protected horticulture systems across the Netherlands and Spain's Almería greenhouse cluster.
- Dual carbon policy alignment:China's MIIT dual carbon goals and India's PLI scheme for sustainable agriculture are creating subsidy windows for microbial seed treatment adoption.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization and formulation stability expertise is concentrated among a narrow cohort of academic and industrial laboratories.
- Non-target organism risk assessment delays:EPA registration pathways require multi-year field studies on pollinator and soil microbiome impacts that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Seed Treatment Market |
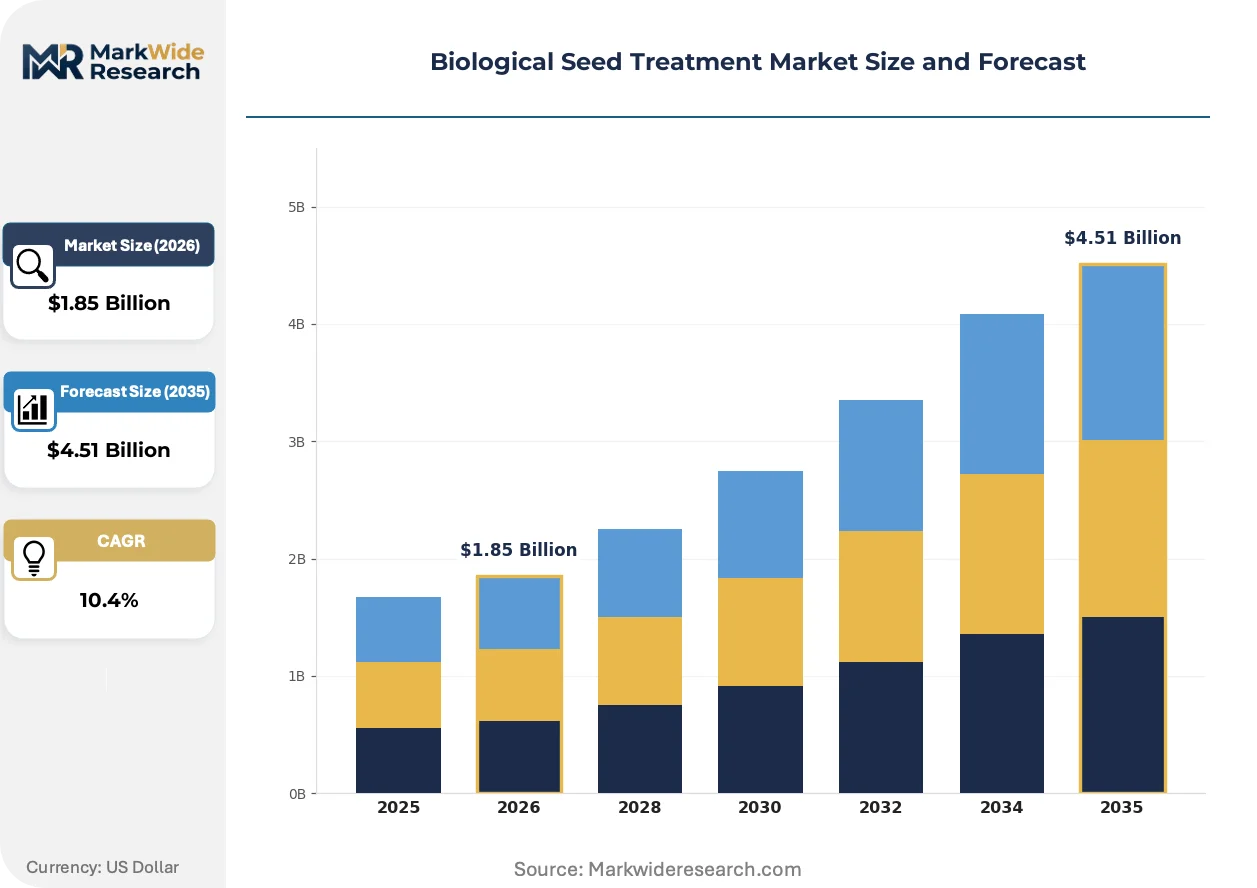
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Inoculants, Fungal Inoculants, Natural Extracts, Mycorrhizal Fungi Application: Cereal Crops, Vegetable Crops, Pulse Crops, Flowering Plants End Use Industry: Agriculture, Horticulture, Golf Course Management, Forestry Distribution Channel: Retail, E-commerce, Direct Sales, Distributors |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Corteva Agriscience, Novozymes A/S, Valent BioSciences, Koppert B.V., FMC Corporation, Marrone Bio Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Seed Treatment Market Strategic Shifts & Innovations
Biological seed treatment development is pivoting toward precision application systems and strain-specific formulation engineering that preserves viability through extended supply chain intervals.
Encapsulation technology is automating controlled-release delivery of living microorganisms to seed surfaces. Large-scale row crop operations in the American Midwest are adopting polymer-based micro-encapsulation systems at accelerating rates. This automation is compressing viability loss rates during storage and enabling extended distribution timelines for temperature-sensitive bacterial inoculants.
The EU F-Gas Regulation and REACH framework constraints on synthetic chemical alternatives are indirectly expanding addressable market scope for microbial substitutes. Formulators are repositioning product portfolios to capture residue-tolerance advantages under tightening EU Green Deal implementation schedules. Mycorrhizal fungi categories are registering the most pronounced demand elasticity in response to these regulatory compressions.
Farmer procurement patterns are rotating toward integrated seed-applied solution bundles that combine biological treatments with precision planting equipment and digital monitoring services. Traditional input distributors in Brazil and Argentina are consolidating biological specialty portfolios to defend channel position against direct manufacturer-to-farm relationships. This bundling behavior is most visible in soybean production systems where per-hectare treatment economics favor consolidated input procurement.
Biological Seed Treatment Market Segmentation
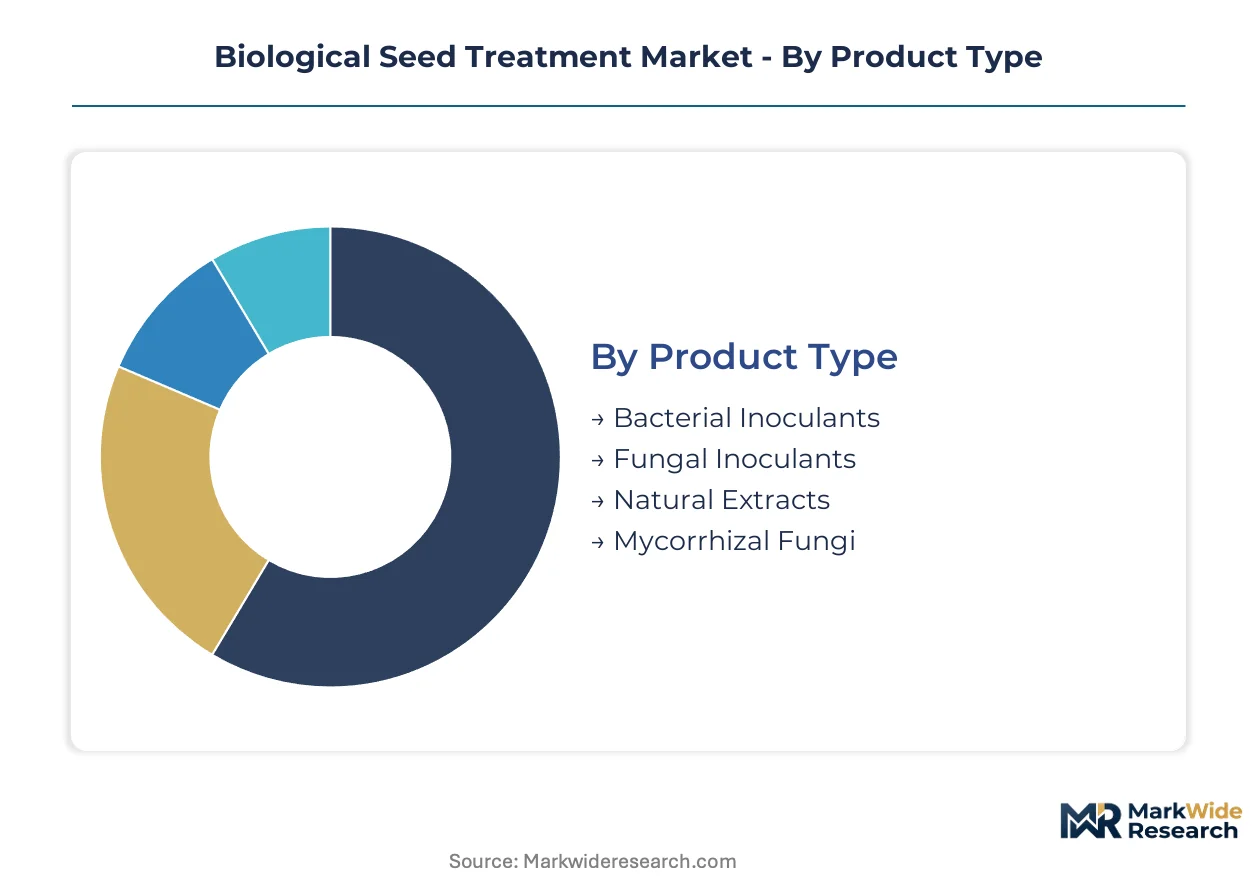
Biological seed treatment segmentation reflects divergent regulatory pathways across EPA FIFRA, EU REACH, and Brazil ANVISA jurisdictions. Product registration complexity varies sharply by active ingredient classification, with bacterial inoculants facing streamlined rhizobia protocols while mycorrhizal formulations encounter extended non-target organism assessments.
Product Type:
EPA FIFRA registration demands multi-year field studies for Bacillus and Trichoderma variants, whereas EU EFSA maintains accelerated review tracks for rhizobia-based nitrogen fixers. ANVISA in Brazil applies modified equivalence pathways for microbial strains with prior OECD country approvals.
- Bacterial Inoculants:Colony-forming units exceeding 10^8 per gram dominate commercial volumes through established legume nodulation efficacy. American Midwest corn and soybean producers drive demand as grain exporters impose sustainability verification requirements.
- Mycorrhizal Fungi:Arbuscular mycorrhizal formulations sustain the steepest expansion trajectory among all categories. Australian wheat belts and Canadian prairie provinces deploy these products for phosphorus-deficient soil remediation under regenerative agriculture protocols.
- Fungal Inoculants:Trichoderma-based products occupy premium positioning in specialty vegetable sectors with controlled-temperature supply chain requirements.
- Natural Extracts:Botanical metabolite formulations face divergent residue tolerance standards between EPA and EU REACH frameworks, fragmenting registration strategies.
Bacterial Inoculants sits at the top of the volume ranking, with Mycorrhizal Fungi climbing the fastest.
Application:
Cost tier differentiation separates high-input cereal systems from labor-intensive vegetable operations, with per-hectare treatment economics driving procurement consolidation.
- Cereal Crops:Large-scale mechanized planting enables precision application systems across American Midwest and Brazilian Mato Grosso production zones. Integrated seed-applied solution bundles compress per-unit treatment costs through volume procurement.
- Vegetable Crops:Protected horticulture systems in Spain's Almería greenhouse cluster and Dutch glasshouse operations command premium pricing for Trichoderma-based disease suppression. Labor-intensive cultivation tolerates higher input costs per hectare.
- Pulse Crops:Rhizobia-specific inoculation requirements create dedicated formulation demand with limited cross-crop applicability.
- Flowering Plants:Ornamental and seed production sectors maintain niche volume with specialized mycorrhizal requirements.
Cereal Crops commands the largest absolute volume, while Vegetable Crops expands most quickly through protected horticulture premiumization.
End Use Industry:
Customer type stratification separates commodity grain operations from high-value specialty producers, with channel configuration varying by procurement scale and technical service requirements.
- Agriculture:Row crop producers across Brazil's soybean belt and American Midwest constitute the densest demand concentration. Direct manufacturer relationships are displacing traditional input distributor channels for large-scale operations.
- Horticulture:Netherlands greenhouse clusters and Spanish protected agriculture systems drive specialized mycorrhizal and Trichoderma formulation demand. Technical advisory services accompany product procurement at premium price points.
- Golf Course Management:Turfgrass applications require distinct strain specifications with limited overlap to agricultural formulations.
- Forestry:Reforestation programs in Canada and Scandinavia deploy ectomycorrhizal inoculants for seedling establishment in degraded soils.
Agriculture maintains dominant volume share, with Horticulture gaining share fastest through greenhouse sector premiumization.
Distribution Channel:
Supply concentration shapes channel control, with integrated manufacturers consolidating biological specialty portfolios to defend position against direct-to-farm disruption.
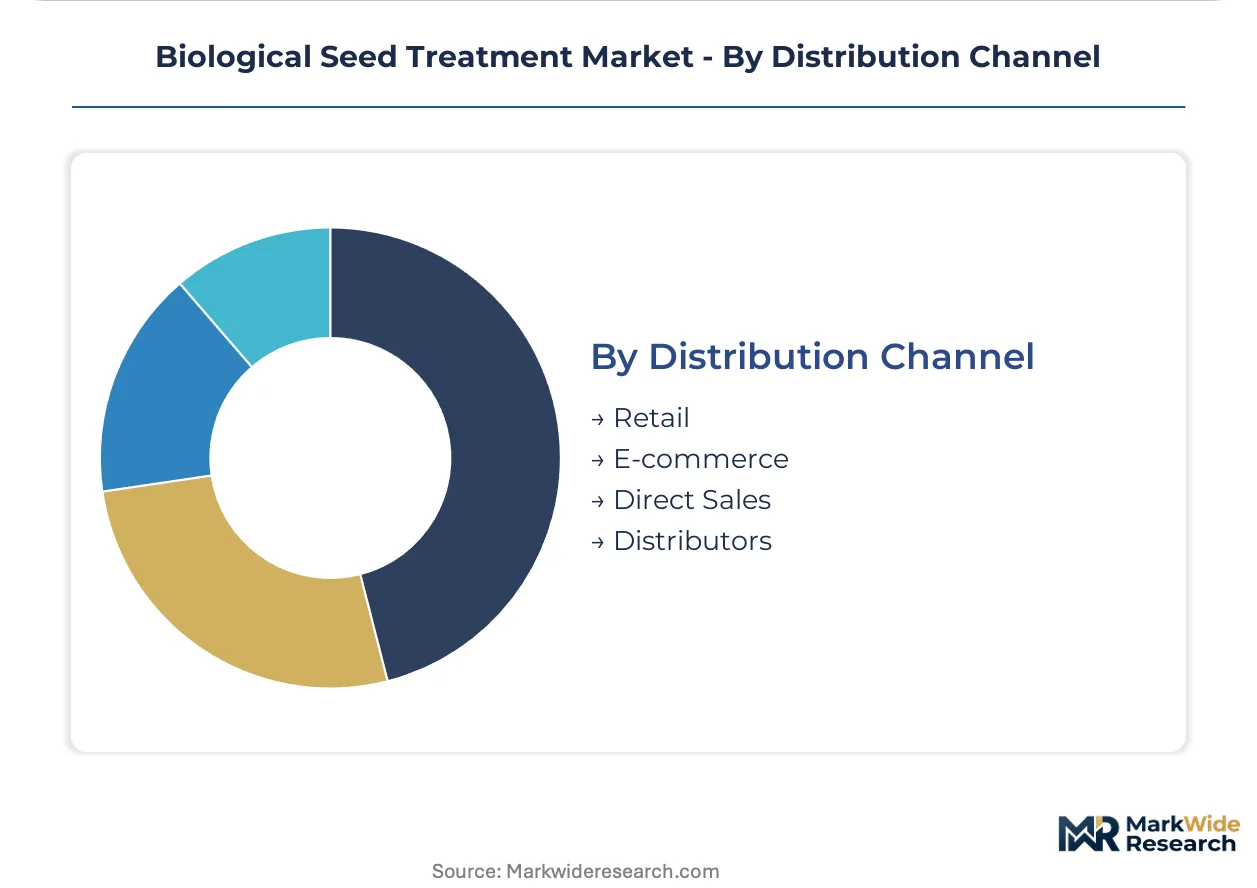
- Distributors:Traditional input distributors in Brazil and Argentina consolidate biological portfolios to maintain channel relevance against manufacturer bypass. Regional warehousing addresses cold-chain requirements for temperature-sensitive formulations.
- Direct Sales:Large-scale row crop operations procure integrated seed-applied bundles combining biological treatments with precision planting equipment. BASF and Bayer anchor this channel through proprietary strain pipelines.
- Retail:Farm supply cooperatives serve mid-scale producers with standardized bacterial inoculant formulations and limited technical support.
- E-commerce:Emerging channel for specialty vegetable producers and small-scale horticulture operations with direct-to-farm logistics.
Distributors retains the highest transaction volume, with Direct Sales expanding most quickly through integrated solution bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt concentrates the densest commercial activity for nitrogen-fixing inoculants, with demand cascading across Argentina's Pampas and North American corn-growing corridors.
United States
American Midwest corn and soybean producers drive volume through supply chain sustainability mandates from grain exporters. EPA FIFRA registration pathways require multi-year field studies for Bacillus variants. Iowa and Illinois production zones deploy precision application systems at accelerating rates.
Brazil
Mato Grosso and Rio Grande do Sul soybean operations constitute the densest concentration of rhizobia-based treatment demand. ANVISA applies modified equivalence pathways for microbial strains with prior OECD approvals. The Cerrado expansion frontier sees direct manufacturer-to-farm procurement consolidation.
Germany
Bavarian and North Rhine-Westphalia formulators anchor EU strain development pipelines for proprietary Bacillus libraries. ECHA REACH framework constraints on synthetic alternatives expand addressable scope for microbial substitutes. Cologne-Düsseldorf industrial clusters house specialized fermentation capacity.
Netherlands
Glasshouse operations in Westland and North Brabant command premium positioning for Trichoderma-based disease suppression. EU Green Deal Farm to Fork strategy accelerates microbial inoculant approvals through streamlined efficacy protocols. Wageningen University corridors concentrate microbiologist talent for strain characterization.
Australia
Wheat belts across Western Australia and New South Wales deploy arbuscular mycorrhizal formulations for phosphorus-deficient soil remediation. TGA-equivalent agricultural chemical frameworks regulate microbial metabolite residue thresholds. Perth-Adelaide distribution corridors address cold-chain gaps for temperature-sensitive formulations.
Biological Seed Treatment Market Key Industry Players
Global majors compete with regional champions across strain development capabilities and distribution reach. The market structures around three tiers: integrated agrochemical conglomerates with proprietary libraries, specialized enzyme and microbe suppliers without downstream assets, and regional fermentation specialists serving local registration pathways. Strategic moves concentrate on M&A for strain portfolios and capacity expansion in tropical fermentation zones.
Within the integrated agrochemical tier, BASF SE and Bayer AG exemplify players controlling proprietary Bacillus variants through in-house strain development pipelines. Novozymes A/S occupies a distinct position as a specialized supplier competing without captive seed assets. These three anchors represent divergent approaches to securing active ingredient supply—captive biotechnology, integrated seed-applied solutions, and pure-play microbial supply respectively.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| Novozymes A/S |
| Valent BioSciences |
| Koppert B.V. |
| FMC Corporation |
| Marrone Bio Innovations |
| Others |
Cost & Logistics Intelligence
Integrated agrochemical conglomerates with proprietary Bacillus strain libraries anchor supply-side concentration, compressing margin pressure onto independent formulators while enabling premium pricing for temperature-stable formulations.
Pricing Analysis
Input-cost pass-through from fermentation substrate volatility and cold-chain logistics runs through contract-based long-term offtake agreements. Pricing stratifies across premium, standard, and economy tiers based on strain certification tier and volume scale, with specialty vegetable producers showing least price sensitivity and commodity grain operations most. Cost compression in standard-tier bacterial inoculants is intensifying because Brazilian and American Midwest buyers consolidate procurement through integrated seed-applied bundles.
Supply Chain Analysis
Active ingredient supply rests on German and Danish fermentation specialists for proprietary Bacillus variants, Brazilian rhizobia producers for nitrogen-fixing inoculants, and Australian mycorrhizal cultivators for arbuscular formulations. Key inputs include molasses-based fermentation media, polymer encapsulation materials, and controlled-temperature packaging. Single-source vulnerability concentrates in strain patent portfolios held by integrated majors. Distribution runs through regional warehousing networks addressing cold-chain gaps in sub-Saharan Africa and Central Asian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in biological seed treatment hinges on encapsulation technology cost-down curves and regenerative agriculture premium-tier adoption shifting farmer willingness-to-pay upward.
For Market Incumbents: Lock in strain pipeline exclusivity through backward integration into tropical fermentation capacity in Brazil and Southeast Asia. Channel control via direct manufacturer-to-farm relationships defends against distributor disintermediation in Mato Grosso soybean operations. Certification investment in EU EFSA streamlined review protocols accelerates product launch windows against regulatory lag. For New Entrants and Emerging Players: Precision application system integration offers a technology-first wedge into American Midwest row crop markets underserved by bundled equipment-biology offerings. White-space targets include phosphorus-deficient Australian wheat belts and Canadian prairie provinces where arbuscular mycorrhizal demand outpaces specialist supply. Direct e-commerce logistics to small-scale horticulture operations in Spain's Almería cluster bypasses consolidated distributor channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fermentation specialists with ANVISA or TGA-equivalent registration pathways and captive strain libraries. Long-term viability frames around consolidation of microbiologist talent scarcity and cold-chain infrastructure buildout. The signal to watch is EPA registration timeline compression for non-target organism risk assessments as indicator of competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Pipeline Acquisition | Proprietary Bacillus libraries from German biotech specialists compress competitor formulation access. |
| Tropical Fermentation Scale-Up | Brazilian capacity expansion addresses ANVISA-equivalence demand density in Mato Grosso soybean zones. |
| Encapsulation Technology Licensing | Polymer micro-encapsulation systems extend viability windows for temperature-sensitive bacterial inoculants. |
| Direct-to-Farm Channel Buildout | Manufacturer bypass of Argentine distributors captures margin from integrated seed-applied solution bundling. |
| Regulatory Fast-Track Investment | EU EFSA streamlined efficacy protocols accelerate rhizobia-based product approvals under Farm to Fork schedules. |
Research Approach
Coverage spans North America, South America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with seed treatment formulators, strain development microbiologists, grain procurement officers at food processors, and cold-chain logistics operators. Secondary validation draws from EPA FIFRA registration databases, EU EFSA submission filings, ANVISA equivalence pathway records, and customs trade data on fermentation equipment imports. Bottom-up strain production capacity estimates triangulate against top-down farmer expenditure surveys.
Granularity-level modeling captures bacterial inoculants, mycorrhizal fungi, fungal inoculants, and natural extracts at product-type level; cereal crops, vegetable crops, pulse crops, and flowering plants at application level; and agriculture, horticulture, golf course management, and forestry at end-use level. CAGRs derive from segment-level volume trajectories cross-referenced against regulatory approval timelines and farmer adoption curve assumptions. Industry-specific inputs include colony-forming unit viability decay rates and encapsulation technology penetration curves.
The model holds under stable EPA and EU REACH regulatory frameworks; deviation in FIFRA registration timeline extensions or F-Gas Regulation acceleration would shift competitive entry velocity and pricing tier compression. Forecasts reflect assumptions on cold-chain infrastructure buildout rates and microbiologist labor supply elasticity. A small set of named triggers warrants ongoing watch: pollinator risk assessment delays, strain patent litigation outcomes, and regenerative agriculture subsidy program expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market