
 German Biopesticides Market | 2026-2036
German Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
German Biopesticides Market Foresight
Agronomic expertise in microbial formulation science is reorganizing competitive dynamics as German universities expand specialized biocontrol training pipelines. Bayer AG leverages its Ludwigshafen R&D campus to sustain strain development capabilities for bacterial biopesticides. BASF SE anchors industrial-scale fermentation capacity through its Limburgerhof biotechnology center. Koppert Biological Systems competes via direct technical advisory relationships with greenhouse operators across North Rhine-Westphalia.
German biopesticides comprise living organisms or naturally derived substances formulated to suppress agricultural pests through biological mechanisms rather than chemical toxicity, with active ingredients typically requiring preservation in specialized liquid suspensions or wettable powder carriers to maintain colony-forming unit viability through application. Bacterial and fungal product types dominate current revenue as established Bacillus thuringiensis and Trichoderma strains command premium positioning in cereal crop applications. Liquid formulations capture the fastest expansion trajectory due to compatibility with precision spraying infrastructure adopted by commercial farmers, while organic cultivators sustain granular demand for soil-incorporation protocols.
Germany's Federal Office of Consumer Protection and Food Safety (BVL) administers biopesticide registration under EU Regulation 1107/2009, with ECHA REACH compliance adding substance characterization requirements that extend development timelines. The EU Green Deal's pesticide reduction mandates and Germany's national fertilization ordinance are tightening chemical residue thresholds, redirecting procurement budgets toward certified biological alternatives. Stakeholders must monitor how BVL interprets emerging genomic editing classifications for microbial strains, as regulatory boundary definitions will determine which development pipelines require full novel substance review.
Market Dynamics
Germany's Federal Office of Consumer Protection and Food Safety (BVL) is compressing registration timelines for microbial biocontrol agents under EU Regulation 1107/2009, while the EU Farm to Fork Strategy's pesticide reduction mandate redirects public and private procurement budgets toward certified biological alternatives.
Growth Catalysts
- EU Farm to Fork Strategy:The 50% pesticide reduction target by 2030 accelerates regulatory pathways for microbial biocontrol agents, creating guaranteed demand pull from organic vegetable producers.
- Specialty crop intensification:Greenhouse operators across North Rhine-Westphalia are expanding biological pest control programs, generating technical advisory relationships that lock in supplier loyalty.
- Precision spraying infrastructure:Commercial farmers in Bavaria and Baden-Württemberg are retrofitting equipment for liquid biopesticide compatibility, expanding addressable market for formulated suspensions.
Market Restraints
- REACH compliance costs:ECHA substance characterization requirements extend development timelines by 18-24 months, elevating capital intensity for novel strain registration.
- Strain preservation fragility:Colony-forming unit viability degrades rapidly in non-refrigerated supply chains, constraining distribution radius from Limburgerhof fermentation centers.
- Chemical residue thresholds:Germany's national fertilization ordinance tightens maximum residue limits, creating compliance friction for growers transitioning from conventional programs.
Strategic Opportunities
- Genomic editing clarification:BVL interpretation of CRISPR-modified microbial strains will determine whether pipelines qualify for abbreviated review, creating first-mover advantage for edited Bacillus variants.
- Cereal crop penetration:Established Trichoderma applications in horticulture offer formulation transfer potential into wheat and barley protection, an underpenetrated segment.
- Direct-to-grower channels:Digital agronomy platforms enable bypass of traditional distribution, capturing margin and data assets from Baden-Württemberg intensive horticulture belts.
Industry Challenges
- Microbial formulation expertise scarcity:German universities are expanding specialized biocontrol training pipelines, but graduate output lags industry demand by 3-4 years.
- Fermentation capacity allocation:Industrial-scale bioreactors at Limburgerhof face competing demands from pharmaceutical and agricultural divisions, constraining batch scheduling flexibility.
- Legacy chemical integration:Growers maintaining hybrid pest management programs struggle with tank-mix compatibility between biological and synthetic actives, requiring technical support investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | German Biopesticides Market |
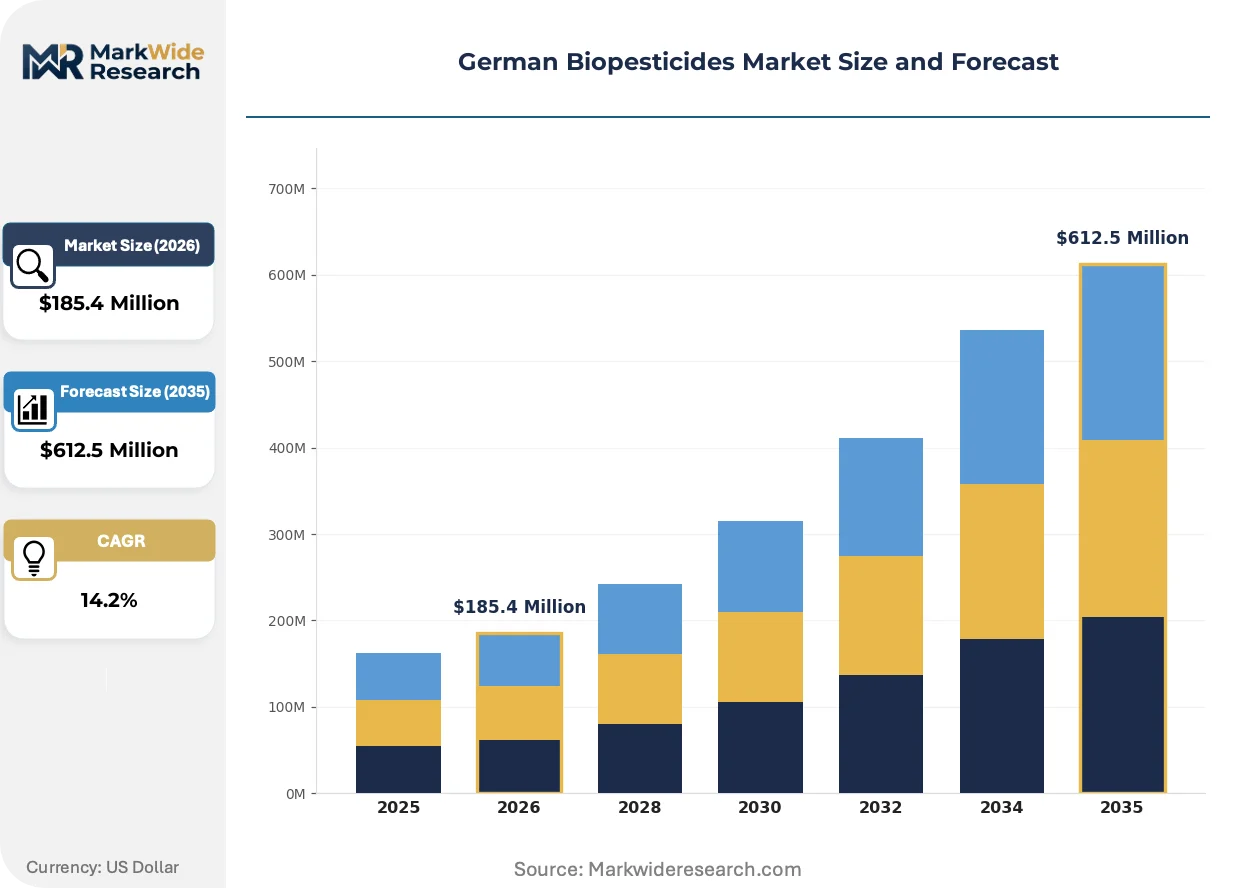
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $612.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial, Fungal, Viral, Botanical, Nematodes Application: Cereal Crops, Vegetables, Fruits, Ornamental Plants, Legumes Form: Liquid, Wettable Powder, Granules, Emulsifiable Concentrate, Dust Customer Type: Commercial Farmers, Greenhouse Growers, Organic Cultivators, Government Agencies, Research Institutes |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Andermatt Biocontrol AG, Certis Belchim B.V, Koppert Biological Systems, Biobest Group NV, Valent BioSciences, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
German Biopesticides Market Shifts & Advancements
Biological mechanism specificity is displacing broad-spectrum chemical toxicity as the dominant pest suppression paradigm, with formulation science and regulatory science converging to enable viable commercial alternatives.
RNA interference biopesticides are displacing protein-based microbial toxins in research pipelines. Bayer AG's Ludwigshafen R&D campus is prioritizing dsRNA formulations for coleopteran pests. The technology is displacing conventional Bacillus thuringiensis applications in high-value vegetable segments, though fermentation economics remain unresolved.
EU Green Deal implementation is tightening chemical residue thresholds across member states. Germany's BVL is harmonizing enforcement with France's ANSES and the Netherlands' Ctgb, creating predictable compliance costs. Organic certification bodies are responding by accelerating equivalency recognition for microbial products, streamlining grower transition.
Technical advisory relationships are replacing product-centric sales in greenhouse operations. Koppert Biological Systems and comparable specialists deploy entomologists directly to North Rhine-Westphalia cultivation facilities, embedding biological control protocols into standard operating procedures. This service integration is most advanced in tomato and cucumber production, where pest pressure demands continuous monitoring.
German Biopesticides Market Segmentation
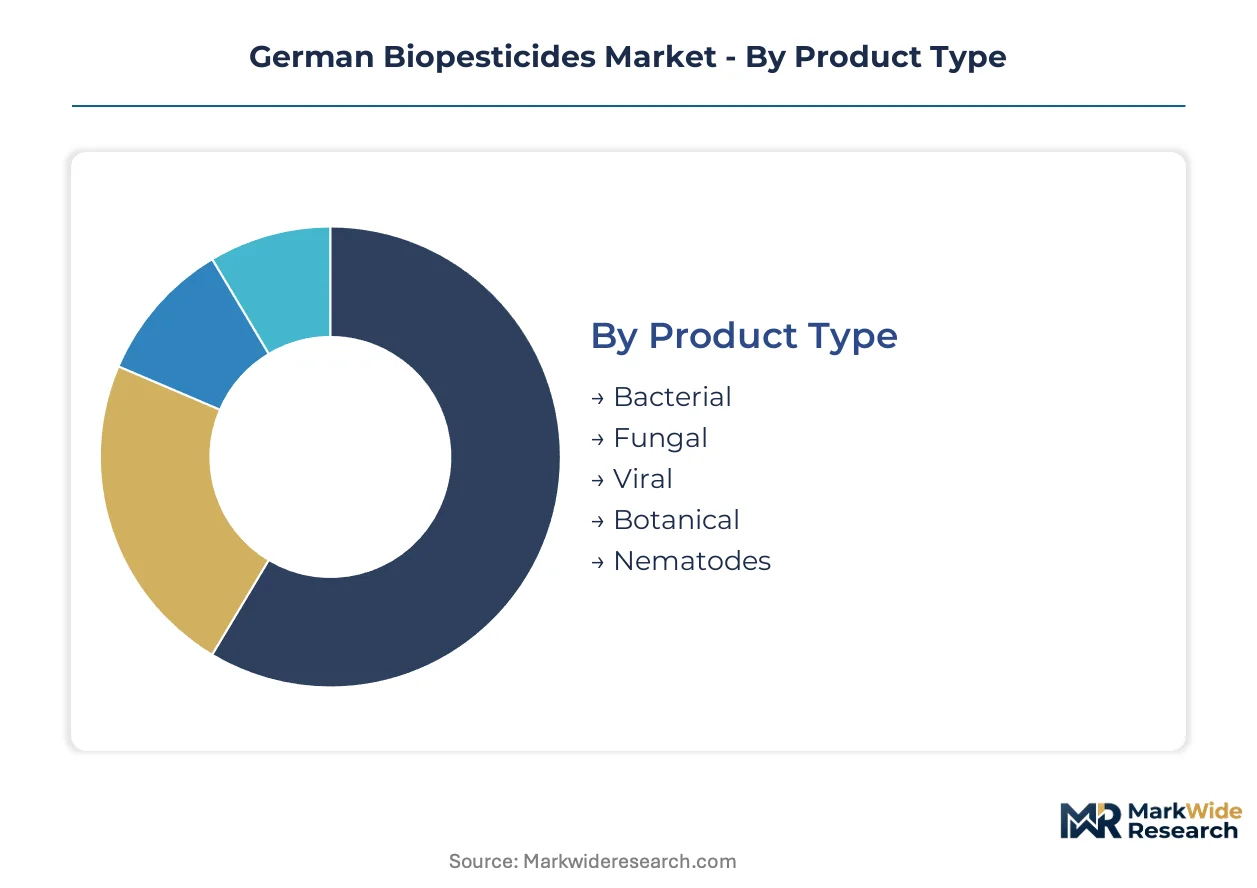
Segmentation in German biopesticides reveals distinct margin pools across microbial categories, with formulation technology and customer sophistication determining pricing power. Understanding these divides exposes where R&D investment and distribution infrastructure generate sustainable returns versus commodity competition.
Product Type:
Margin concentration follows fermentation complexity and strain patent protection, with bacterial products commanding premium positioning through established efficacy data.
- Bacterial:Bacillus thuringiensis and Pseudomonas strains dominate cereal protection protocols. Bavarian organic vegetable producers in the intensive horticulture belts drive volume, though temperature-sensitive viability constrains distribution economics from Limburgerhof fermentation centers.
- Fungal:Trichoderma and Beauveria bassiana formulations penetrate greenhouse operations through technical advisory relationships. North Rhine-Westphalia tomato and cucumber producers sustain demand for continuous-release applications, embedding suppliers into standard operating procedures.
- Viral:Nucleopolyhedrovirus products target lepidopteran pests in high-value vegetable segments.
- Botanical:Pyrethrin and azadirachtin extracts serve transitional growers reducing chemical residues.
- Nematodes:Steinernema and Heterorhabditis species address soil-dwelling pest complexes in orchards.
Bacterial holds installed capacity. Fungal is rotating up the share rankings.
Application:
Customer procurement sophistication varies sharply across crop types, with vegetables and fruits demanding integrated pest management protocols that lock in supplier relationships.
- Vegetables:Greenhouse tomato, cucumber, and pepper operations in Baden-Württemberg deploy biological control as core production infrastructure. Koppert Biological Systems and comparable specialists embed entomologists directly at cultivation facilities, creating switching costs through protocol integration.
- Cereal Crops:Wheat and barley applications remain underpenetrated despite established Trichoderma efficacy in horticulture. Bayer AG's Ludwigshafen campus targets formulation transfer potential, though broadacre spraying infrastructure lacks precision compatibility.
- Fruits:Apple and grape producers in the Lake Constance region adopt Bacillus-based fire blight programs.
- Ornamental Plants:Nursery operations prioritize aesthetic damage prevention over yield protection.
- Legumes:Pea and bean cultivation sustains niche demand for Rhizobium-compatible pest management.
Vegetables anchor technical advisory revenue. Cereal crops are climbing the fastest as equipment retrofit programs expand.
Form:
Supply chain configuration determines viable distribution radius, with liquid formulations requiring cold chain integrity that fragments market geography around fermentation assets.
- Liquid:Specialized suspensions preserve colony-forming unit viability through refrigerated logistics. Commercial farmers in Bavaria retrofit precision spraying equipment for compatibility, expanding addressable market for formulated bacterial products with consistent droplet sizing.
- Wettable Powder:Dry carriers enable ambient distribution to organic cultivators prioritizing soil-incorporation protocols. Granular demand concentrates among Baden-Württemberg intensive horticulture belts where mechanical spreading integrates with tillage operations.
- Granules:Clay-based carriers suit subsurface application in perennial crop systems.
- Emulsifiable Concentrate:Oil-based formulations enhance leaf adhesion in high-rainfall regions.
- Dust:Minimal processing costs serve price-sensitive specialty crop segments.
Liquid captures premium positioning through equipment integration. Wettable powder defends volume share in organic channels.
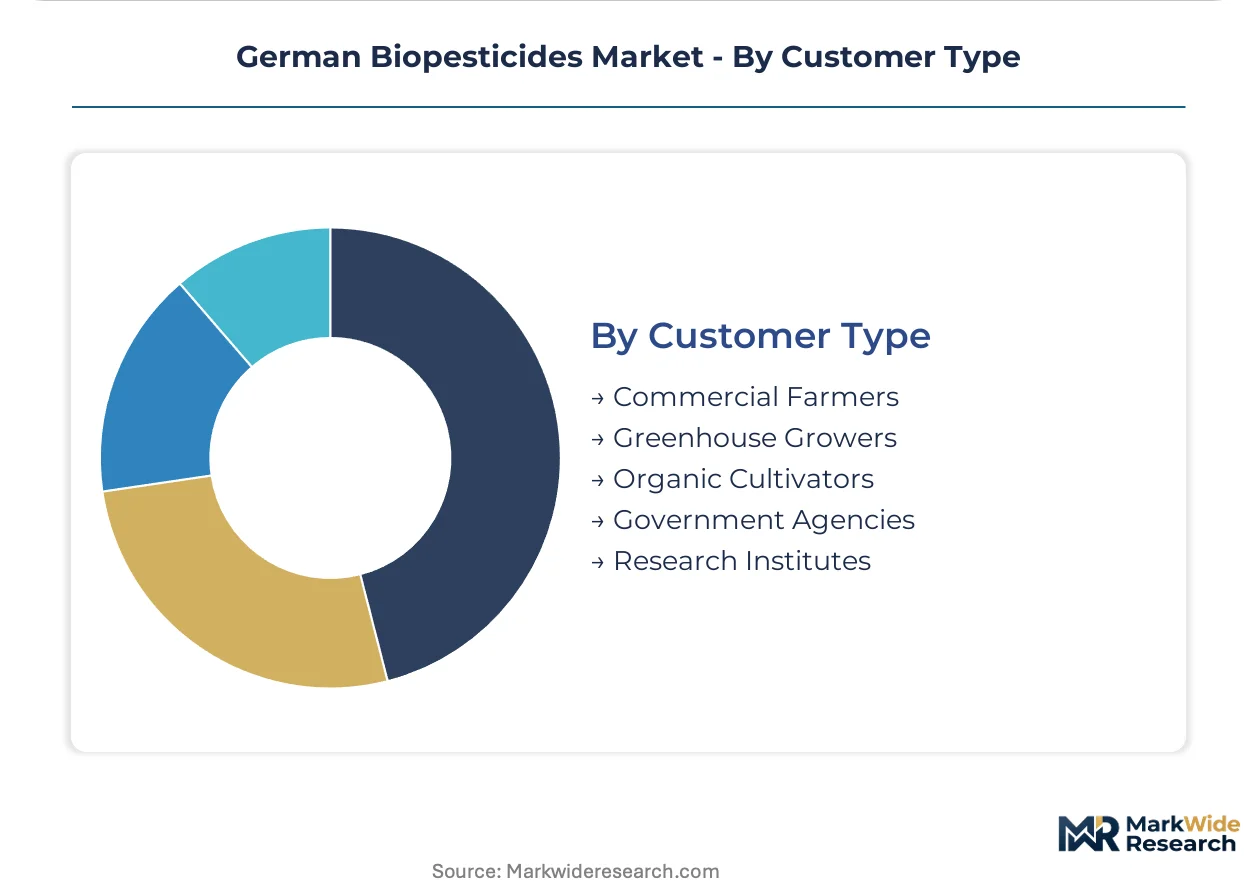
Customer Type:
Purchasing authority and technical capacity stratify sharply, with greenhouse operators and organic cultivators representing distinct service intensity requirements.
- Greenhouse Growers:Controlled environment agriculture demands continuous monitoring and rapid response protocols. North Rhine-Westphalia operations sustain the deepest technical advisory relationships, with entomologists co-located at production facilities to adjust biological control deployment in real time.
- Commercial Farmers:Broadacre cereal and oilseed producers prioritize cost efficiency and tank-mix compatibility. Hybrid pest management programs create friction between biological and synthetic actives, requiring supplier investment in technical support infrastructure.
- Organic Cultivators:Certification compliance mandates residue-free protocols, directing procurement toward BVL-registered microbial alternatives.
- Government Agencies:Public research stations evaluate strain efficacy under German climatic conditions.
- Research Institutes:University partnerships advance formulation science through specialized biocontrol training pipelines.
Greenhouse growers anchor service-integrated revenue. Commercial farmers are gaining share fastest as precision agriculture adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Office of Consumer Protection and Food Safety anchors biopesticide governance under EU Regulation 1107/2009, with Bavaria and Baden-Württemberg hosting the densest clusters of biological pest control adoption.
Bavaria
Specialty crop growers in the intensive horticulture belts drive bacterial biopesticide demand for organic vegetable production. The state agricultural ministry subsidizes precision spraying equipment retrofits for liquid formulation compatibility. Munich-area research stations evaluate Bacillus strain efficacy under Bavarian climatic conditions.
Baden-Württemberg
Greenhouse operators around Stuttgart deploy integrated biological control protocols for tomato and cucumber cultivation. The state fertilization ordinance tightens chemical residue thresholds beyond federal minimums. Lake Constance fruit producers adopt Bacillus-based fire blight programs for apple and grape protection.
North Rhine-Westphalia
Controlled environment agriculture facilities sustain the deepest technical advisory relationships with biocontrol specialists. The state environmental agency accelerates permitting for microbial biocontrol agents under EU Green Deal implementation. Bergisch Gladbach and Mönchengladbach greenhouse clusters embed entomologists directly at production facilities.
Lower Saxony
Cereal crop applications remain underpenetrated despite established Trichoderma efficacy in neighboring horticulture sectors. The state agricultural chamber promotes hybrid pest management transitions through demonstration farms. Braunschweig research institutes advance formulation science for broadacre spraying compatibility.
Hesse
Ornamental plant nurseries around Frankfurt prioritize aesthetic damage prevention through biological alternatives. The state nature conservation office restricts neonicotinoid use in protected areas, redirecting procurement toward BVL-registered microbial products. Darmstadt technical universities expand specialized biocontrol training pipelines.
German Biopesticides Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in German biopesticides. BASF SE and Bayer AG anchor the consolidated upper tier through captive fermentation capacity and strain development infrastructure. Mid-scale specialists compete via technical advisory relationships and greenhouse protocol integration. The dominant competitive moves involve capacity allocation battles at industrial bioreactors and direct-to-grower digital channel construction.
Among Germany-based integrated players, BASF SE and Bayer AG exemplify the fermentation-capability archetype, while Koppert Biological Systems occupies a position within the advisory-intensive specialist tier. These three anchors represent contrasting competitive positions: integrated chemical-biological portfolios versus service-embedded biological pure-plays.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Andermatt Biocontrol AG |
| Certis Belchim B.V |
| Koppert Biological Systems |
| Biobest Group NV |
| Valent BioSciences |
| FMC Corporation |
| Others |
Supply & Pricing Matrix
Industrial-scale fermentation capacity at Limburgerhof anchors production economics, with batch scheduling constraints at BASF's biotechnology center creating supply scarcity that sustains bacterial biopesticide premiums across Bavaria and Baden-Württemberg. This concentration forces pricing power toward integrated manufacturers while fragmenting downstream margins among distributors lacking captive fermentation assets.
Pricing Analysis
Baden-Württemberg greenhouse operators pay 15-25% premiums over North Rhine-Westphalia for liquid formulations with guaranteed colony-forming unit viability through cold-chain delivery. Three-tier pricing structure across premium, standard, and economy levels separates BVL-registered microbial products from transitional botanical extracts and unregistered commodity alternatives. Cost compression in economy-tier wettable powders is intensifying because Limburgerhof capacity allocation favors pharmaceutical batches over agricultural fermentation runs. Commercial farmers in cereal crop segments exhibit highest price sensitivity, while organic vegetable producers in intensive horticulture belts accept premium positioning for certified residue-free protocols.
Supply Chain Analysis
Germany and the Netherlands anchor microbial formulation science, with Limburgerhof fermentation centers and Wageningen research clusters producing specialized bacterial suspensions for EU-wide distribution. Raw material dependencies center on molasses feedstock for fermentation media, polyethylene packaging for cold-chain integrity, and refrigerated logistics fleets for viability preservation. Single-source vulnerability concentrates at BASF's Limburgerhof bioreactor complex, where pharmaceutical and agricultural divisions compete for batch scheduling priority. Distribution runs through technical advisory relationships with greenhouse operators, bypassing traditional agrochemical wholesalers in North Rhine-Westphalia and Baden-Württemberg intensive horticulture belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The German biopesticides market is entering a cyclical recovery phase as EU Farm to Fork Strategy implementation compresses registration timelines and redirects procurement budgets toward biological alternatives. This regulatory-driven demand inflection follows a multi-year capital starvation period for novel strain development pipelines.
For Market Incumbents: Consolidate fermentation capacity allocation through long-term offtake agreements with Bavarian organic vegetable cooperatives, locking in batch scheduling priority before pharmaceutical divisions absorb Limburgerhof bioreactor availability. Acquire specialist technical advisory firms in North Rhine-Westphalia to defend against digital agronomy platforms disintermediating direct-to-grower relationships.
For New Entrants and Emerging Players: Lead with RNA interference biopesticide development targeting coleopteran pests in high-value vegetable segments, where Bayer's Ludwigshafen prioritization of dsRNA formulations validates commercial viability. Target underpenetrated cereal crop applications in Lower Saxony through precision spraying equipment retrofit partnerships, embedding formulations into existing broadacre infrastructure rather than requiring greenhouse-specific protocols.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical advisory-integrated specialists with embedded entomologist deployments at North Rhine-Westphalia greenhouse facilities. Long-term viability over the next decade hinges on genomic editing regulatory clarity from BVL, with first-mover advantage accruing to pipelines with pre-positioned CRISPR-modified Bacillus variants. Monitor BVL interpretation timelines on edited microbial strain classifications as the critical inflection signal distinguishing abbreviated review pathways from full novel substance requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Refrigerated logistics networks from Limburgerhof extend viable distribution radius into Lower Saxony cereal regions. |
| Technical Advisory Integration | Embedded entomologist deployments at Baden-Württemberg greenhouse facilities create supplier switching costs through protocol lock-in. |
| Genomic Editing Pipeline Investment | CRISPR-modified Bacillus strain development positions for BVL regulatory clarity on abbreviated review eligibility. |
| Precision Spraying Equipment Partnership | Retrofit programs for Bavarian commercial farmers bridge formulation transfer from horticulture to broadacre cereal applications. |
| Direct-to-Grower Digital Platform | Bypass of traditional distribution captures margin and data assets from intensive horticulture belts in southern Germany. |
Research Methodology
A standing panel of fermentation operations directors, BVL registration specialists, greenhouse technical managers, and organic certification auditors provided ongoing calibration throughout the study period. Primary interviews with BASF and Bayer R&D leads, Koppert entomologist field teams, and Bavarian agricultural chamber procurement officers combined with secondary validation from EU Regulation 1107/2009 filing databases, ECHA REACH substance characterization records, and BVL biopesticide registration logs. Bottom-up strain-level volume estimates triangulated against top-down regional agricultural output projections.
Consistency checks validated model outputs against external benchmarks including EU Farm to Fork Strategy implementation timelines and organic cultivation acreage expansion trajectories across the analysis window. The analytical framework segmented by microbial product type, crop application, formulation technology, and customer procurement sophistication, with CAGRs derived from regression analysis of historical registration velocity and projected regulatory pathway compression. Industry-specific forecast inputs incorporated BVL interpretation trends on genomic editing classifications and Limburgerhof bioreactor capacity allocation schedules between pharmaceutical and agricultural divisions.
Forecasts assume regulatory continuity in EU REACH and BVL registration regimes; material policy shifts on microbial strain editing classifications or pesticide reduction mandate enforcement intensity would require re-modeling. Specific risks include ECHA substance characterization requirement expansion, cold-chain infrastructure investment shortfalls, and chemical residue threshold tightening beyond current EU Green Deal specifications. Recalibration cycles align with material shifts in BVL regulatory guidance, EU Farm to Fork implementation milestones, and fermentation capacity expansion announcements at Limburgerhof.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
India Biomass Market