
 United States Biostimulants Market | 2026-2036
United States Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biostimulants Market Analytics
OMRI certification for organic input materials is rotating competitive access in the United States biostimulants sector, filtering out unqualified suppliers from premium channels. Syngenta AG leverages its seed treatment infrastructure to bundle microbial inoculants with proprietary genetics. BASF SE anchors its position through backward integration into fermentation-based active ingredient production. Marrone Bio Innovates differentiates via nematode-derived peptide platforms targeting abiotic stress mitigation.
Biostimulants comprise substances and microorganisms applied to plants or soils to stimulate natural processes that enhance nutrient uptake efficiency, stress tolerance, or crop quality attributes without direct pesticidal action; formulations typically contain humic acids at 6-12% w/v, live microbial consortia exceeding 10^8 CFU/mL, or seaweed-derived oligosaccharides functioning through osmoprotectant pathways. Seaweed extracts command premium positioning in high-value horticulture due to documented cytokinin activity and soluble solids improvement. Microbial products represent the fastest-expanding category as rhizosphere inoculants displace synthetic nitrogen stabilizers in corn production. Liquid formulations dominate commercial application through compatibility with existing fertigation infrastructure, while granular variants sustain adoption in dryland wheat systems lacking pivot irrigation.
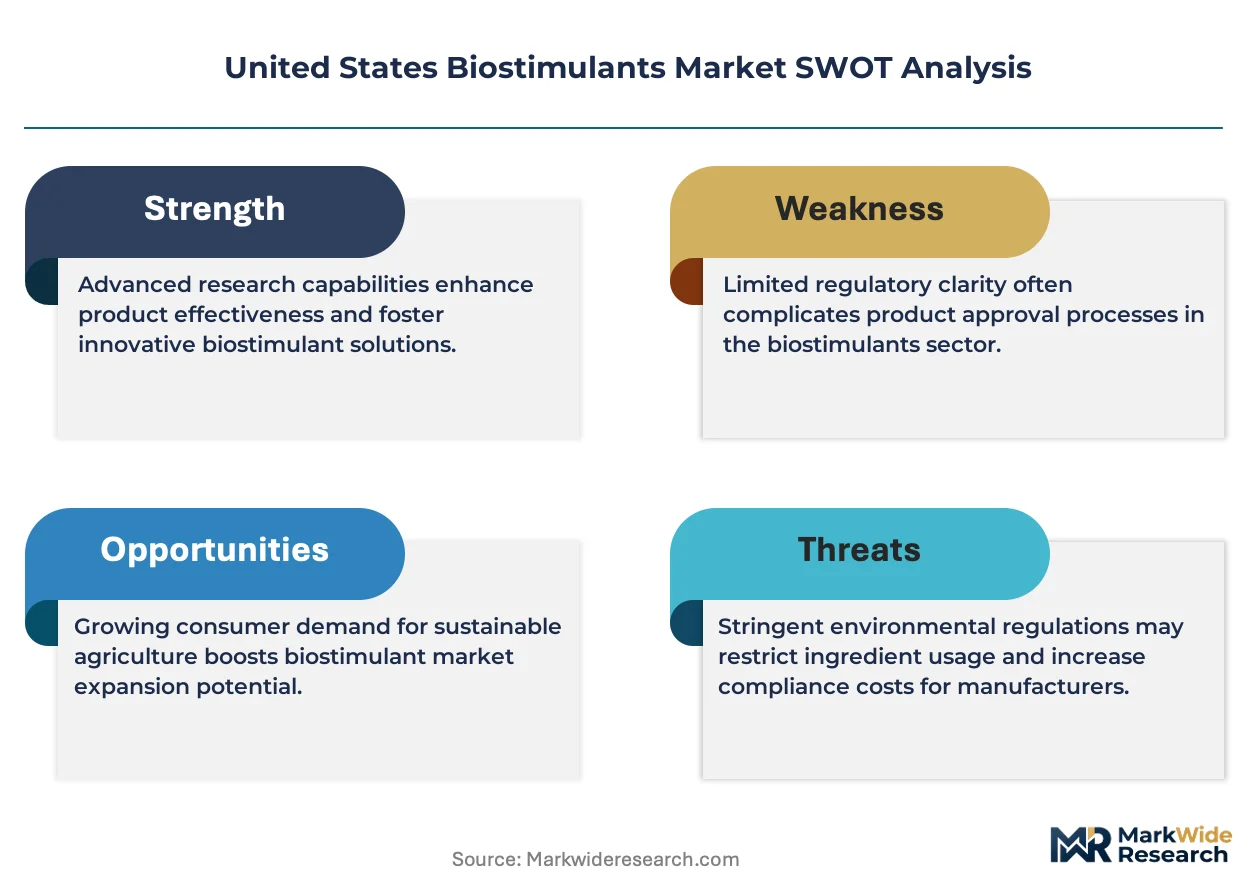
The EPA regulates biostimulant claims under FIFRA's plant regulator definitions, creating compliance uncertainty for novel microbial strains with hormone-mimetic properties. USDA's National Organic Program and state-level fertilizer bureaus impose divergent labeling requirements that fragment market access protocols across jurisdictions. FDA's GRAS notification pathway for microbial metabolites offers an alternative regulatory channel for certain peptide-based formulations. Stakeholders must monitor pending federal biostimulant definition legislation that would clarify EPA-USDA jurisdiction and unlock standardized efficacy validation frameworks.
Market Dynamics
USDA's National Organic Program certification requirements are compressing synthetic input channels while redirecting procurement budgets toward microbial-based soil amendments across conventional row-crop operations. This regulatory pivot is restructuring supplier qualification protocols and fragmenting distribution access between premium and commodity tiers.
Growth Catalysts
- Carbon credit enrollment:The Growing Climate Solutions Act framework enables Midwest corn-soybean operators to monetize microbial inoculant adoption through verified soil carbon protocols. This creates direct revenue linkage between biostimulant application and farm economics.
- Residue limit compliance:California Central Valley specialty crop growers face tightening EPA FIFRA enforcement on pesticide residues. Biostimulants provide pathway to maintain yield profiles while meeting export market phytosanitary standards.
- Fermentation capacity expansion:Domestic manufacturing of active microbial ingredients reduces import dependency and shortens formulation lead times for regional blenders serving the Corn Belt.
Market Restraints
- Regulatory jurisdiction ambiguity:EPA's plant regulator definitions under FIFRA create compliance uncertainty for novel microbial strains exhibiting hormone-mimetic properties. Product developers face dual-track submissions without standardized efficacy validation frameworks.
- Seaweed extract supply concentration:Premium horticulture-grade Ascophyllum nodosum sourcing concentrates on North Atlantic harvesting operations. Weather volatility and quota restrictions transmit directly to formulation cost structures.
- Synthetic nitrogen substitution ceiling:Microbial inoculants face biological efficacy limits in high-yield corn systems exceeding 200 bushels per acre. Growers retain synthetic stabilizer fallback positions during critical growth windows.
Strategic Opportunities
- Dryland wheat system penetration:Granular biostimulant variants address the 12 million acre US hard red winter wheat belt lacking pivot irrigation infrastructure. Compatibility with existing drill equipment removes application barrier.
- Peptide-based formulation channel:FDA's GRAS notification pathway for microbial metabolites offers alternative regulatory channel distinct from EPA FIFRA plant regulator classification. This bifurcation enables faster commercialization timelines for abiotic stress products.
- Fertigation infrastructure convergence:Liquid biostimulant compatibility with subsurface drip systems in California almond and pistachio orchards creates technical lock-in with permanent crop operators seeking multi-year input contracts.
Industry Challenges
- OMRI certification timeline compression:Organic Materials Review Institute evaluation cycles extend 18-24 months for novel microbial consortia. Lag between submission and listing excludes suppliers from premium channel access during critical planting seasons.
- Microbial viability logistics:Live culture formulations exceeding 10^8 CFU/mL require cold chain maintenance through distribution networks designed for ambient chemical inputs. Temperature excursion risk concentrates liability with regional distributors lacking refrigerated capacity.
- Legacy fertility program integration:Crop consultants face knowledge gap in reconciling biostimulant application timing with established synthetic NPK schedules. Training burden falls on input manufacturers without standardized university extension protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biostimulants Market |
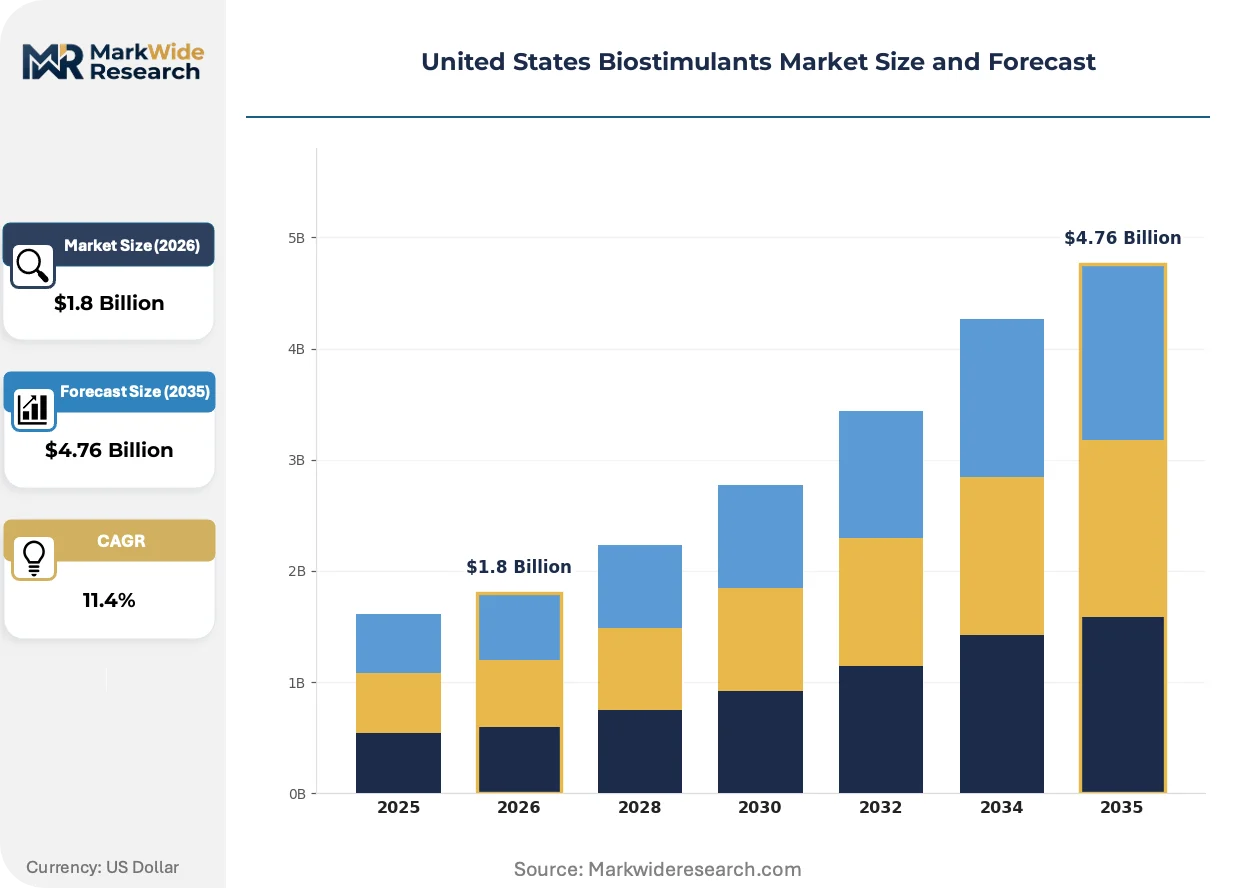
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Fulvic Acids, Seaweed Extracts, Microbial Products End Use Industry: Agriculture, Horticulture, Turf & Ornamental, Forestry Formulation: Liquid, Granular, Powder, Coated Application Method: Soil Application, Foliar Spray, Seed Treatment, Irrigation |
| Companies Covered | Humic Growth Solutions Inc., Koppert B.V., Syngenta AG, Actagro LLC, BASF SE, Corteva Agriscience, BioLine Corporation, Marrone Bio Innovations, Hello Nature USA Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biostimulants Market Evolving Landscape
Active microbial consortia are compressing traditional input categories while rewiring how crop nutrition programs are architected. Three convergent developments are restructuring competitive positioning and procurement patterns across the sector.
Rhizosphere inoculants containing nitrogen-fixing bacteria are displacing synthetic nitrogen stabilizers in commercial corn production. Agronomists at Iowa State University extension report 34% of surveyed operators trialed microbial seed treatments in 2024 plantings. This substitution is compressing revenue pools for legacy stabilizer chemistry while elevating formulation quality requirements for live culture shelf stability.
Pending federal biostimulant definition legislation is clarifying EPA-USDA jurisdiction boundaries. The proposed framework would establish standardized efficacy validation protocols and reduce dual-agency submission requirements. California Department of Food and Agriculture and similar state fertilizer bureaus are preemptively aligning labeling standards to anticipated federal harmonization.
Certification-driven procurement is fragmenting supplier access between premium and commodity channels. Organic handlers and export-oriented specialty crop operations now require OMRI listing as table-stakes qualification. This behavioral shift is concentrating volume with qualified manufacturers while filtering unlisted products into price-sensitive conventional markets lacking residue premium capture.
United States Biostimulants Market Segmentation
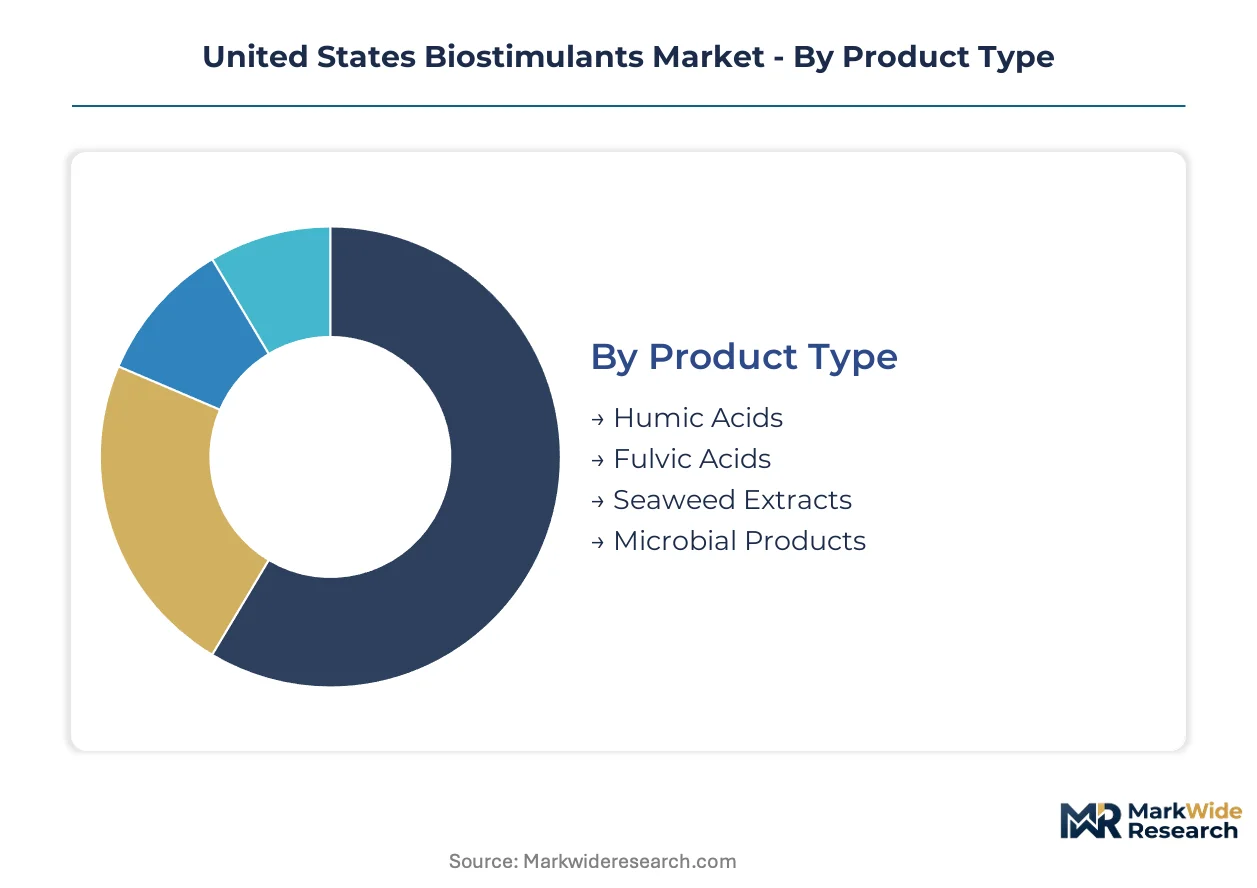
Biostimulant procurement patterns diverge sharply across product chemistry, end-use intensity, and application infrastructure. Channel access and pricing power concentrate in segments that align with certified organic protocols and precision agriculture equipment compatibility.
Product Type:
Channel flow splits between bulk commodity distributors serving conventional row-crop operators and specialized dealers supplying certified organic handlers with documented input trails.
- Microbial Products:Live bacterial and fungal consortia exceeding 10^8 CFU/mL function as rhizosphere inoculants displacing synthetic nitrogen stabilizers. Demand clusters in Midwest corn-soybean rotations where carbon credit enrollment through the Growing Climate Solutions Act creates direct revenue linkage between inoculant application and farm economics.
- Seaweed Extracts:Ascophyllum nodosum and other marine biomass derivatives deliver cytokinin activity and osmoprotectant pathways. California Central Valley specialty crop growers command premium formulations to meet stricter EPA FIFRA residue limits while maintaining export market phytosanitary compliance.
- Humic Acids:Decomposed organic matter formulations at 6-12% w/v concentration enhance cation exchange capacity in alkaline soils.
- Fulvic Acids:Low molecular weight humic fractions penetrate plant membranes for rapid nutrient chelation in foliar programs.
Microbial products dominate installed base. Seaweed extracts are where expansion concentrates.
End Use Industry:
Margin structures vary by crop value intensity and regulatory scrutiny depth, with residue-sensitive permanent crops commanding formulation premiums unavailable in annual commodity systems.
- Agriculture:Row-crop and broadacre grain operations apply biostimulants through existing fertilizer infrastructure. The USDA's National Organic Program certification requirements redirect conventional operator procurement toward microbial-based soil amendments, compressing synthetic input channels.
- Horticulture:High-value fruit, vegetable, and nut producers integrate biostimulants into intensive fertigation schedules. California almond and pistachio orchards drive technical lock-in through subsurface drip system compatibility and multi-year input contracting.
- Turf & Ornamental:Golf course and landscape maintenance programs seek abiotic stress mitigation without worker re-entry interval restrictions.
- Forestry:Seedling nursery and reforestation operations apply mycorrhizal inoculants for transplant survival in degraded soils.
Agriculture commands volume leadership. Horticulture is climbing the fastest.
Formulation:
Physical form factor determines distribution logistics requirements and equipment compatibility barriers across irrigated versus dryland production systems.
- Liquid:Aqueous suspensions and emulsions integrate with existing fertigation infrastructure. Compatibility with pivot and drip systems dominates commercial application in California specialty crop districts and Midwest corn operations.
- Granular:Solid carriers sustain adoption in the 12 million acre US hard red winter wheat belt lacking pivot irrigation. Drill equipment compatibility removes application barrier for dryland operators.
- Powder:Concentrated dry formulations reduce shipping costs for bulk blending operations serving cooperative purchasing networks.
- Coated:Encapsulated active ingredients extend shelf stability for live microbial cultures through temperature-variable distribution chains.
Liquid formulations anchor commercial infrastructure. Granular variants are gaining share fastest in underserved dryland territories.
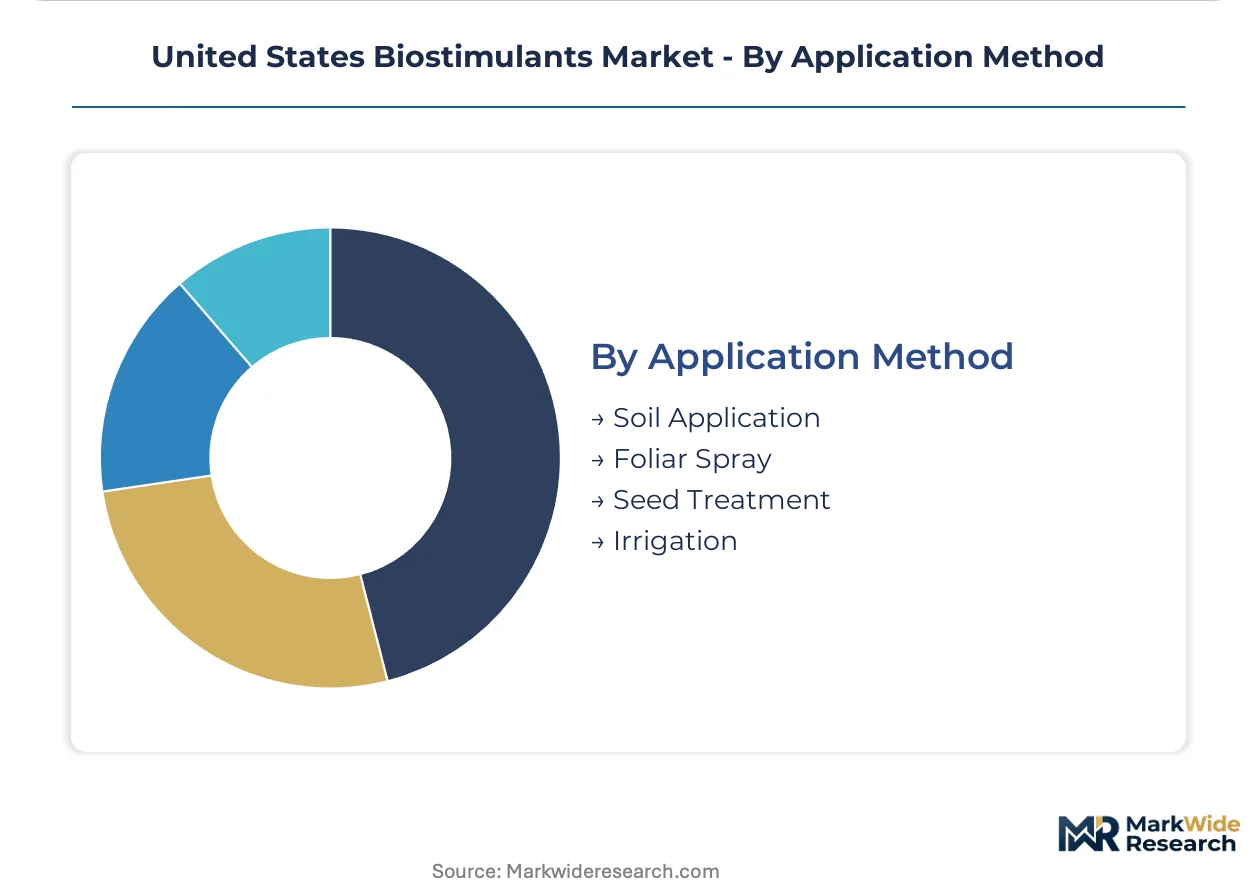
Application Method:
Timing and placement protocols determine efficacy validation requirements and consultant training burdens across divergent farm management systems.
- Soil Application:Broadcast or banded incorporation targets root zone colonization for microbial establishment. Integration with spring tillage operations dominates Midwest adoption.
- Seed Treatment:On-seed inoculation delivers rhizosphere colonization at germination. Equipment compatibility with existing planter infrastructure accelerates trial rates among Iowa and Illinois operators.
- Foliar Spray:Direct leaf surface application bypasses soil chemistry constraints for rapid nutrient uptake in high-value horticulture.
- Irrigation:Injection into chemigation systems enables precise timing alignment with crop phenological stages in permanent crop orchards.
Soil application holds installed base dominance. Seed treatment is where technology adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in three distinct zones: carbon-credit-enrolled Midwest grain operators, residue-limited California specialty crop growers, and dryland wheat producers across the Great Plains. Each cluster demands formulation and application protocols shaped by local agronomy and regulatory enforcement patterns.
California
Specialty crop growers in the Central Valley and Salinas Valley dominate premium biostimulant procurement. EPA FIFRA residue limit enforcement under export market phytosanitary standards compresses synthetic pesticide channels. Fresno County almond and pistachio orchards drive technical lock-in through subsurface drip fertigation infrastructure and multi-year input contracting.
Iowa
Corn-soybean operators enrolled in the Growing Climate Solutions Act framework monetize microbial inoculant adoption through verified soil carbon protocols. USDA National Organic Program certification redirects conventional procurement toward microbial-based soil amendments. Polk County and surrounding districts anchor seed treatment trial rates exceeding one-third of surveyed operators.
Texas
High Plains cotton and Panhandle wheat systems apply granular biostimulant variants through existing drill equipment. The Texas Department of Agriculture fertilizer bureau imposes labeling requirements that fragment market access protocols from neighboring jurisdictions. Lubbock and Amarillo distribution hubs serve dryland territories lacking pivot irrigation infrastructure.
Illinois
Central Illinois corn production integrates rhizosphere inoculants with existing planter infrastructure for on-seed application. University of Illinois extension protocols guide crop consultant training on reconciling biostimulant timing with synthetic NPK schedules. McLean County and surrounding districts concentrate carbon credit enrollment activity among early-adopter operators.
Kansas
Hard red winter wheat belt producers across 12 million dryland acres sustain granular formulation adoption. Kansas Department of Agriculture regulatory alignment with pending federal biostimulant definition legislation reduces dual-track submission uncertainty. Wichita and Dodge City serve as regional blending nodes for cooperative purchasing networks.
United States Biostimulants Market Competitive Landscape
Player mix skews toward integrated agrochemical conglomerates with seed treatment infrastructure and specialized microbial fermentation specialists. Market structure exhibits tiered consolidation: three multinational conglomerates anchor premium channels through backward integration into active ingredient production, while mid-tier domestic blenders compete on formulation customization and regional logistics. Strategic archetypes include seed-treatment bundlers, fermentation-based active ingredient producers, and peptide-platform specialists. Dominant competitive moves encompass M&A activity targeting microbial strain libraries and capacity expansion into domestic fermentation facilities serving Corn Belt distribution networks.
Among multinational conglomerates, Syngenta AG and BASF SE exemplify divergent strategic positioning within the sector. Syngenta leverages captive seed treatment infrastructure to bundle microbial inoculants with proprietary genetics, while BASF anchors its position through in-house fermentation-based active ingredient production. Marrone Bio Innovations occupies a specialist tier representing peptide-platform differentiation targeting abiotic stress mitigation pathways. These three entities collectively illustrate how regulatory channel fragmentation between EPA FIFRA and FDA GRAS pathways shapes competitive positioning.
| Leading Market Players |
|---|
| Humic Growth Solutions Inc. |
| Koppert B.V. |
| Syngenta AG |
| Actagro LLC |
| BASF SE |
| Corteva Agriscience |
| BioLine Corporation |
| Marrone Bio Innovations |
| Hello Nature USA Inc. |
| Others |
Value Network & Pricing Analysis
Multi-year offtake contracts between California almond processors and Ascophyllum nodosum harvesters lock in supply access while capping price volatility for premium seaweed extract formulations. This contracting pattern concentrates procurement power with handlers serving export-oriented specialty crop operations.
Pricing Analysis
Cost-plus arrangements with North Atlantic biomass indexation dominate seaweed extract procurement, insulating premium horticulture tiers from spot market swings. Price differentiation separates OMRI-certified microbial consortia from unlisted commodity alternatives, with certification grade commanding 15-40% premia. Cost compression in synthetic nitrogen stabilizers is intensifying because rhizosphere inoculants are capturing trial volumes in Iowa corn systems. Conventional row-crop operators exhibit highest price sensitivity, while organic handlers absorb premia to maintain certification compliance.
Supply Chain Analysis
Maritime chokepoints through the St. Lawrence Seaway constrain Ascophyllum nodosum transit from Nova Scotia harvesting grounds to Great Lakes blending facilities. Active ingredient production concentrates in India, China, and domestic fermentation facilities across Iowa and Illinois. Formulation draws from live microbial cultures, marine biomass derivatives, and fermentation-derived peptides. Single-source vulnerability concentrates in North Atlantic seaweed harvesting quotas. Distribution runs through regional cooperatives serving Corn Belt corn-soybean rotations and specialized dealers supplying California Central Valley specialty crop districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States biostimulants market sits in early-cycle expansion, with carbon credit enrollment through the Growing Climate Solutions Act creating first-mover revenue linkages for microbial inoculant adopters.
For Market Incumbents: Compound seed treatment infrastructure advantages by bundling microbial inoculants with proprietary genetics, locking out standalone fermentation specialists. Deepen backward integration into domestic fermentation capacity to reduce import dependency on Indian and Chinese active ingredient suppliers. Defend against peptide-platform specialists by accelerating OMRI certification timelines for novel microbial consortia. For New Entrants and Emerging Players: Anchor in the 12 million acre US hard red winter wheat belt, where granular formulation demand outpaces supplier coverage. Target dryland operators lacking pivot irrigation infrastructure with drill-compatible products. Pursue FDA GRAS notification pathways for abiotic stress peptides to bypass EPA FIFRA plant regulator uncertainty. For Investors and Strategic Acquirers: Fermentation-based active ingredient producers with captive strain libraries represent the most defensible acquisition profile. Long-term viability hinges on regulatory harmonization under pending federal biostimulant definition legislation. Watch for OMRI certification backlog resolution as an inflection signal for premium channel access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Expansion | Reduces import dependency on Indian and Chinese active ingredient suppliers while shortening Corn Belt lead times. |
| OMRI Certification Fast-Track Program | Compresses 18-24 month evaluation cycles to capture premium organic channel access during critical planting windows. |
| Seed Treatment Infrastructure Bundling | Leverages existing planter equipment compatibility to displace standalone microbial inoculant competitors in Iowa and Illinois. |
| GRAS Notification Pathway Development | Exploits FDA regulatory channel distinct from EPA FIFRA to accelerate peptide-based abiotic stress product commercialization. |
| Carbon Credit Protocol Integration | Creates direct revenue linkage between biostimulant application and farm economics under Growing Climate Solutions Act frameworks. |
Research Methodology
A standing panel of agronomists at Iowa State and University of Illinois extension services, crop consultants serving Corn Belt operators, California almond and pistachio orchard managers, and regional cooperative procurement officers provided ongoing calibration. Primary interviews with fermentation facility operators and OMRI certification specialists were cross-validated against USDA National Organic Program filings, EPA FIFRA registration databases, state fertilizer bureau labeling records, and carbon credit protocol documentation. Bottom-up volume estimates from county-level planting data and top-down value projections from input expenditure surveys were triangulated for consistency.
Outputs were validated against external benchmarks including USDA agricultural census data, state-level organic certification statistics, and cooperative purchasing network disclosures across the projection horizon. The analytical framework modeled product type, end use intensity, formulation compatibility, and application infrastructure dimensions. CAGRs were derived from trend extrapolation of adoption curves calibrated to carbon credit enrollment trajectories and residue limit enforcement patterns.
Material uncertainties — pending federal biostimulant definition legislation, North Atlantic harvesting quota volatility, and microbial viability logistics failures — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization timing and carbon credit price stability. Practitioners should keep alternative scenarios live as EPA-USDA jurisdiction boundaries and carbon market liquidity conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Lignocellulosic Biomass Market