
 Mexico Insulin Drugs and Delivery Devices Market | 2026-2036
Mexico Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Insulin Drugs and Delivery Devices Market Foresight
Hospital procurement of insulin delivery devices is decoupling from traditional bulk purchasing as home care channels gain preference among type 1 diabetes patients. Novo Nordisk A/S anchors the premium insulin analog segment through sustained R&D investment in glucose-responsive formulations. Eli Lilly and Company differentiates via manufacturing scale for biosimilar insulin production within Latin American supply networks. Sanofi S.A. competes through channel control of pen-needle distribution across Mexican pharmacy chains.
Insulin drugs and delivery devices comprise recombinant human insulin, insulin analogs, and mechanical or electronic systems for parenteral administration, typically requiring cold-chain storage at 2-8°C and subcutaneous delivery via 4-6mm pen needles. Their primary purpose is maintaining glycemic control in diabetes mellitus patients to prevent microvascular and macrovascular complications. The insulin pens segment leads volume due to patient familiarity and lower training burden, while connected health solutions within the technology dimension capture expanding margin pools as remote monitoring integrates with endocrinology practice workflows. Smart insulin delivery systems are gaining fastest traction among urban diabetes clinics in Monterrey and Tijuana that serve privately insured populations.
COFEPRIS governs pharmaceutical registration and medical device licensing in Mexico, with specific biocompatibility standards for pen needles and pump infusion sets that shape product entry timelines. The Secretaría de Salud implements national diabetes prevention programs that influence public-sector insulin procurement volumes and device subsidy eligibility. Stakeholders must monitor how upcoming Mexican pharmacovigilance requirements for connected devices will reshape liability structures and software validation obligations for manufacturers operating in this market.
Market Dynamics
Home care adoption is decoupling from hospital-centric diabetes management as Mexican patients seek self-administration options, fundamentally restructuring procurement channels and reimbursement flows across the insulin delivery ecosystem.
Growth Catalysts
- COFEPRIS biosimilar streamlining:The regulatory framework accelerates affordable insulin approvals, expanding patient access through simplified equivalence pathways.
- Urban diabetes clinic clustering:Mexico City and Guadalajara concentrate specialized endocrinology practices that drive device uptake among privately insured populations.
- Connected health integration:Remote monitoring platforms are embedding into endocrinology workflows, creating pull-through for smart delivery systems.
Market Restraints
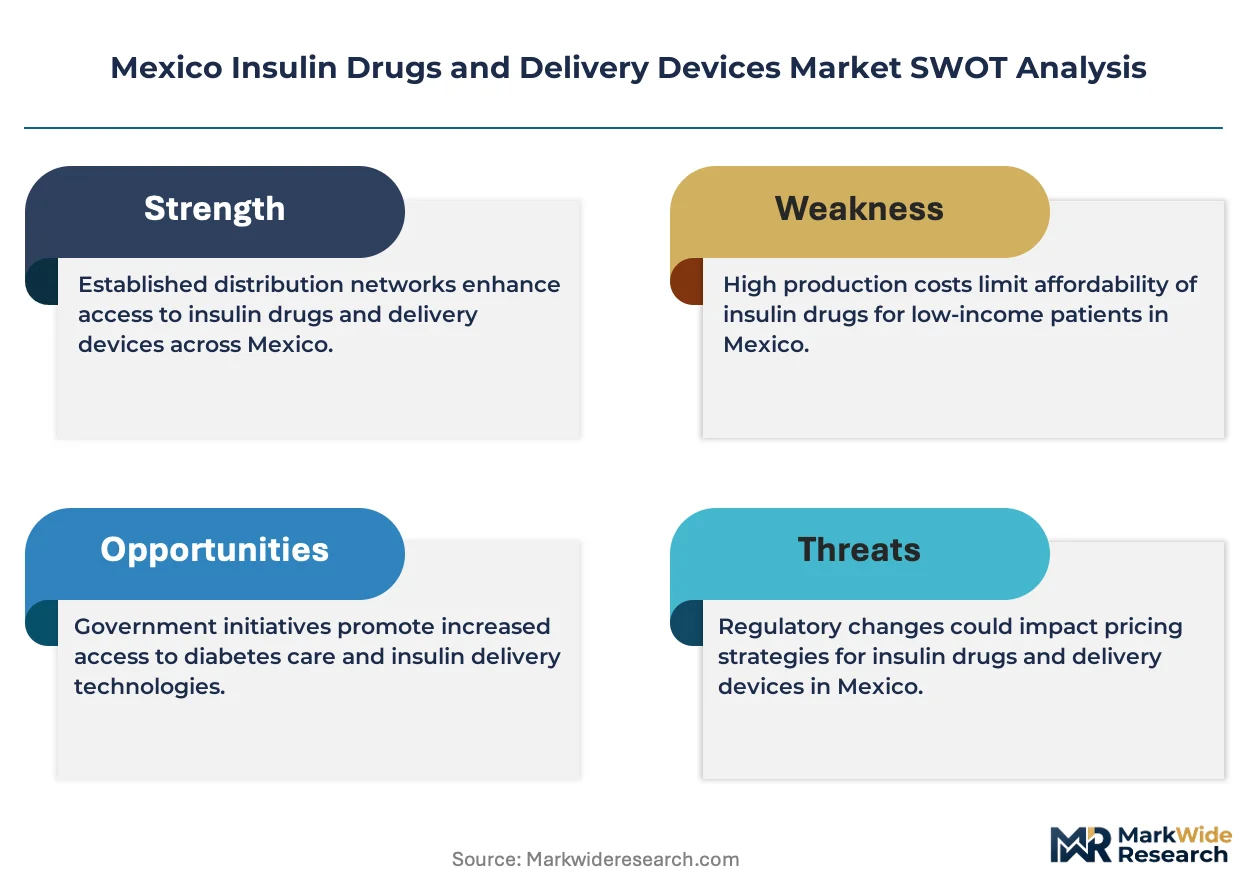
- Cold-chain infrastructure gaps:Rural distribution networks lack consistent 2-8°C storage capacity, limiting insulin reach beyond urban centers.
- Pen-needle supply concentration:Channel control by select distributors creates procurement bottlenecks for pharmacy chains outside major metros.
- Public-sector procurement delays:Secretaría de Salud subsidy eligibility timelines extend patient access windows for subsidized devices.
Strategic Opportunities
- Monterrey-Tijuana private corridor:These northern cities serve cross-border insured populations with capacity for premium connected device adoption.
- Pharmacovigilance software services:Upcoming COFEPRIS requirements for connected device liability create white space for validation and monitoring solutions.
- Telemedicine-delivery convergence:Virtual endocrinology consults are opening direct-to-patient channels bypassing traditional pharmacy intermediaries.
Industry Challenges
- Biocompatibility certification timelines:Pen needle and infusion set testing protocols under COFEPRIS extend product entry schedules.
- Legacy pump integration friction:Smart system adoption requires backward compatibility with existing patient hardware, complicating software validation.
- Specialized diabetes educator scarcity:Training capacity for connected device onboarding lags device availability in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Insulin Drugs and Delivery Devices Market |
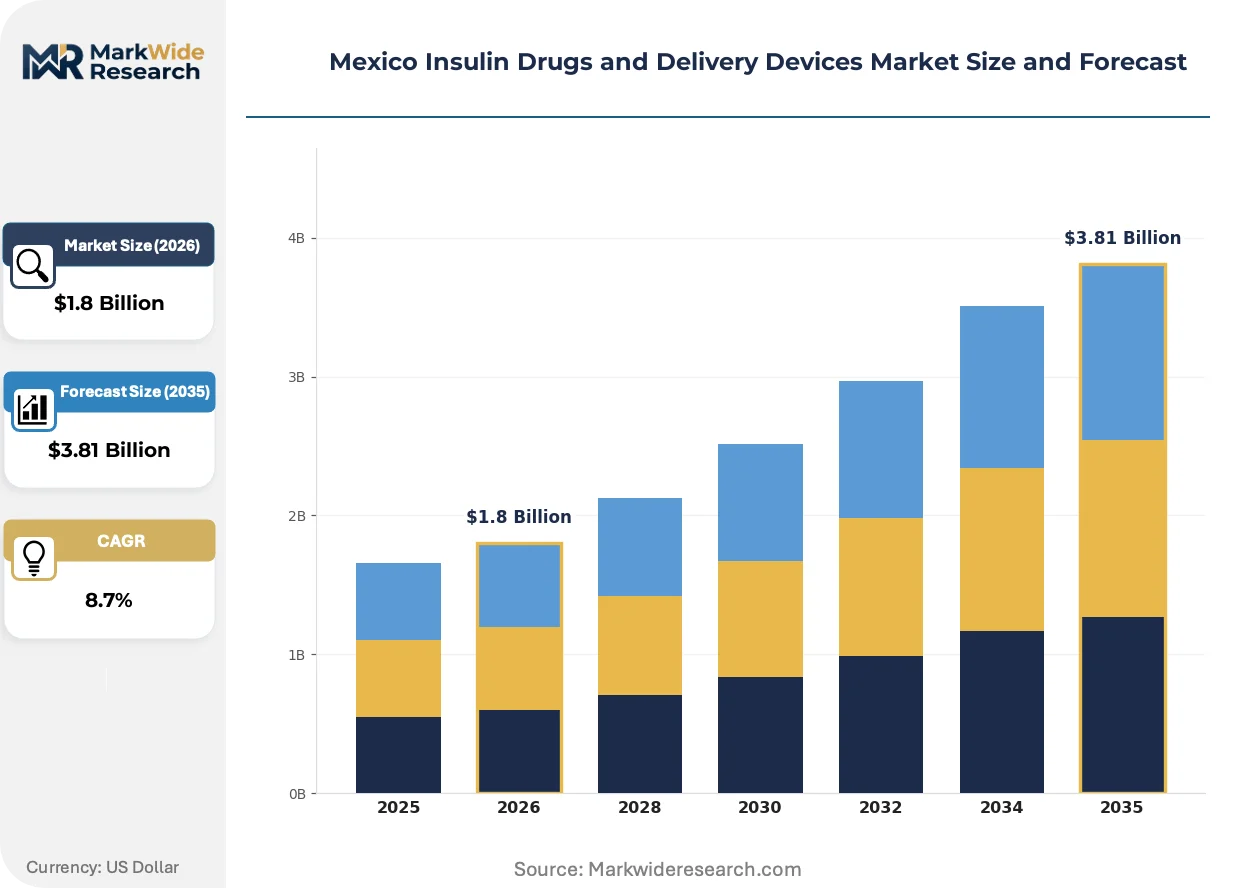
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Insulin Pens, Continuous Glucose Monitors, Insulin Pumps Delivery Mode: Subcutaneous Injection, Intravenous Administration, Intramuscular Injection, Inhalation End User: Hospitals, Home Care, Diabetes Clinics, Healthcare Providers Technology: Smart Insulin Delivery, Automated Dosing, Biodegradable Devices, Connected Health Solutions |
| Companies Covered | Biocon Limited, Boehringer Ingelheim, Novo Nordisk A/S, Merck and Co, AstraZeneca plc, Eli Lilly and Company, Pfizer Inc., Novartis, Sanofi S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Insulin Drugs and Delivery Devices Market Shifts & Advancements
Smart insulin delivery systems are consolidating technical architectures while regulatory frameworks and patient behavior patterns undergo parallel transformation across Mexican diabetes care.
Glucose-responsive insulin formulations are consolidating the premium analog segment through closed-loop integration with continuous glucose monitors. Private diabetes clinics in Guadalajara are piloting these systems for affluent type 1 populations. The technology is consolidating multiple device categories into single-platform ecosystems, compressing margins for standalone pen manufacturers.
COFEPRIS is tightening biocompatibility standards for pen needles and pump infusion sets through updated medical device licensing requirements. Manufacturers now face extended validation timelines for polymer and metal component approvals. The pen-needle segment bears the heaviest compliance burden, with domestic distributors restructuring supplier qualification protocols.
Patients are bypassing hospital pharmacy procurement through direct subscription models for insulin and consumables. Urban diabetes clinics in Mexico City are facilitating these arrangements via partnerships with delivery logistics providers. This channel shift is most pronounced among type 1 patients under private insurance, where copay structures favor home delivery over retail pharmacy pickup.
Mexico Insulin Drugs and Delivery Devices Market Segmentation
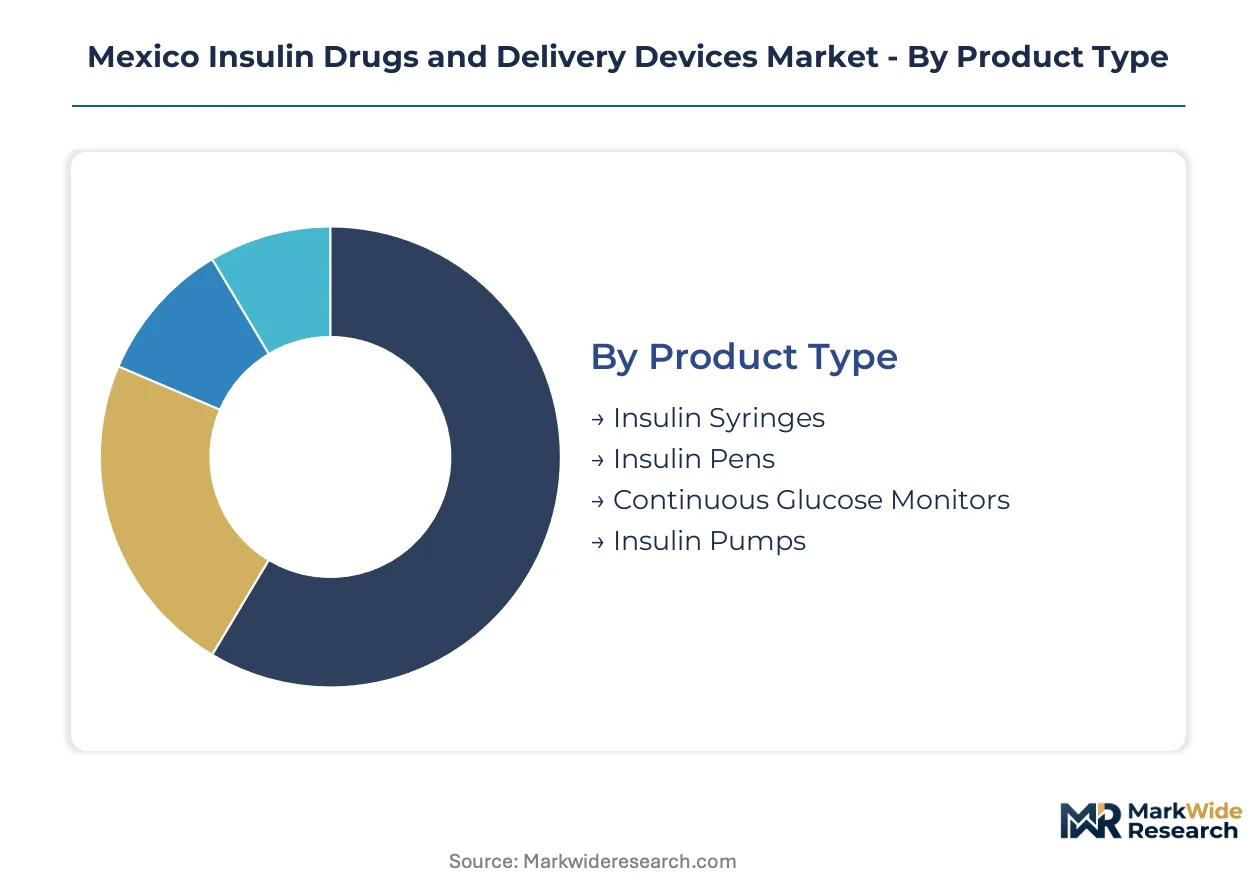
Segmentation in the Mexico insulin market reveals how procurement channels, patient self-administration preferences, and COFEPRIS regulatory pathways create distinct commercial battlegrounds. Each dimension carries unique margin structures and access requirements that shape manufacturer strategy.
Product Type:
Standardization dominates the low-cost syringe segment while customization concentrates in connected pen and pump ecosystems.
- Insulin Pens:Reusable and disposable pen systems accommodate 3mL insulin cartridges with 4-6mm needle lengths. Demand clusters in Mexico City and Guadalajara pharmacy chains where private insurance copay structures favor pen convenience over syringe economics. COFEPRIS biocompatibility testing for pen needles creates entry barriers that protect established distributors.
- Insulin Pumps:Electronic infusion devices deliver basal-bolus insulin through subcutaneous catheters with programmable dosing algorithms. Adoption concentrates among type 1 patients in Monterrey and Tijuana private clinics with capacity for specialized educator support and continuous glucose monitor integration.
- Insulin Syringes:Conventional 1mL tuberculin syringes with integrated 28-31 gauge needles serve cost-sensitive public-sector procurement.
- Continuous Glucose Monitors:Factory-calibrated sensors with 10-14 day wear periods transmit interstitial glucose data to receiver devices or smartphones.
Most installed capacity flows through Insulin Pens. Expansion is steepest in Insulin Pumps.
Delivery Mode:
Volume concentrates in subcutaneous routes while margin pools shift toward alternative administration technologies.
- Subcutaneous Injection:Abdominal, thigh, or deltoid tissue deposition via pen, syringe, or pump catheter remains the standard for basal and prandial insulin. This route dominates across all Mexican patient segments due to established training protocols and COFEPRIS-approved device availability.
- Inhalation:Pulmonary insulin delivery through dry powder or aerosolized formulations eliminates needle requirements. Regulatory complexity under COFEPRIS respiratory drug pathways and limited endocrinologist familiarity constrain uptake to experimental protocols in Mexico City academic centers.
- Intravenous Administration:Hospital-only insulin infusion for diabetic ketoacidosis management via IV drip or smart pump.
- Intramuscular Injection:Rare emergency use when subcutaneous absorption is compromised.
Subcutaneous Injection carries the heaviest patient volume. Inhalation is gaining share fastest among needle-averse type 2 populations.
End User:
Channel control fragments across institutional procurement, direct-to-patient subscription models, and clinic-mediated dispensing.
- Home Care:Self-administering patients purchase devices and consumables through retail pharmacy, e-commerce, or direct delivery subscriptions. This segment is decoupling fastest from hospital procurement as Mexico City clinics broker logistics partnerships for insulin and pen-needle home delivery.
- Hospitals:Acute care facilities manage inpatient glycemic control through IV insulin and temporary subcutaneous protocols. Secretaría de Salud procurement delays and bulk purchasing requirements compress margins for device manufacturers serving the public hospital network.
- Diabetes Clinics:Specialized endocrinology practices in Guadalajara and Monterrey prescribe and dispense premium devices.
- Healthcare Providers:Individual physician practices with limited device inventory and referral relationships.
Home Care channels process the highest device volume. Diabetes Clinics are expanding most quickly as telemedicine integration enables remote patient monitoring.
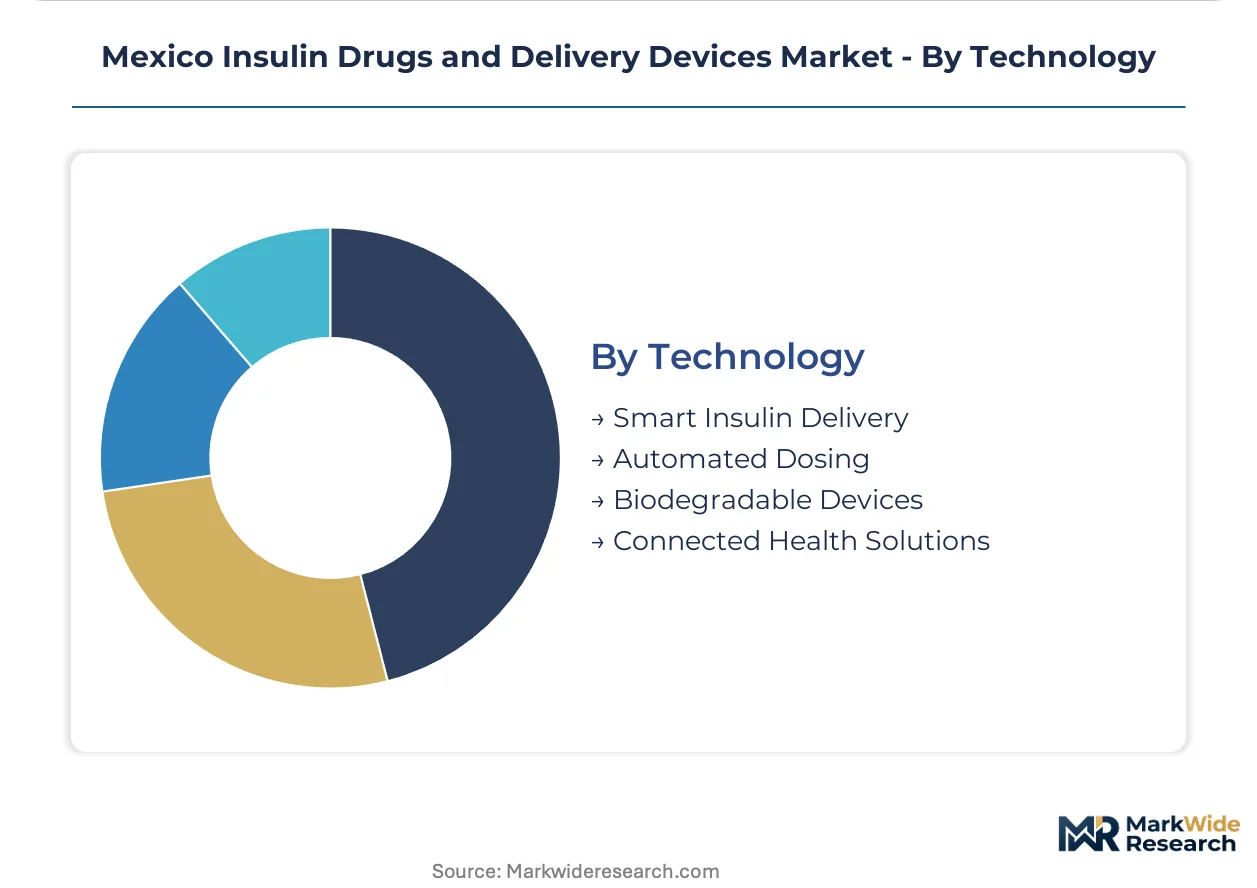
Technology:
Maturity gradients separate legacy mechanical systems from software-validated connected platforms.
- Connected Health Solutions:Cloud-integrated devices transmit dosing data, glucose readings, and adherence metrics to care teams. Remote monitoring platforms embed into Guadalajara endocrinology workflows, creating pull-through for subscription-based device and consumable bundles.
- Smart Insulin Delivery:Closed-loop systems algorithmically adjust insulin delivery based on continuous glucose monitor inputs. Pilot programs in Monterrey private clinics serve affluent type 1 populations with insurance coverage for integrated pump-sensor ecosystems.
- Automated Dosing:Dose calculators and bolus advisors within pen or pump interfaces reduce arithmetic burden.
- Biodegradable Devices:Experimental polymer-based needles and pump components targeting sustainability credentials.
Connected Health Solutions command the broadest installed base. Smart Insulin Delivery is climbing the fastest as COFEPRIS software validation pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in insulin manufacturing favor jurisdictions with streamlined biosimilar pathways, drawing production investment toward markets where COFEPRIS-style equivalence frameworks compress approval timelines and reduce compliance costs relative to FDA or EMA processes.
Mexico City Metro
Specialized endocrinology practices cluster in Polanco and Santa Fe districts, driving premium device uptake among privately insured type 1 populations. COFEPRIS headquarters proximity accelerates regulatory consultation for manufacturers seeking pen-needle biocompatibility certification. Home delivery subscription models for insulin and consumables are consolidating fastest in this corridor through clinic-logistics partnerships.
Nuevo León
Monterrey's private diabetes clinics serve cross-border insured populations from Texas with capacity for connected pump adoption and continuous glucose monitor integration. The state's industrial base supports cold-chain distribution infrastructure reaching northern tier cities. Local hospital networks are piloting closed-loop insulin systems for affluent patient segments.
Jalisco
Guadalajara concentrates Mexico's second-largest diabetes specialist workforce, with Providencia and Zapopan clinics driving reusable pen system volumes. Secretaría de Salud procurement programs channel subsidized syringes through public hospitals in the metropolitan zone. Telemedicine platforms embedded in endocrinology practices here are pulling through remote monitoring subscriptions.
Northern Border States
Tijuana and Ciudad Juárez clinics cater to binational patients with US insurance coverage, creating demand pockets for premium smart delivery systems unavailable through Mexican public channels. Maquiladora employment bases sustain commercial insurance penetration above national averages. Cross-border pharmacy arbitrage complicates local device pricing structures.
Bajío Region
León and Querétaro manufacturing clusters supply polymer components for pen needles and pump infusion sets to national distributors. The region's automotive logistics expertise translates into temperature-controlled distribution capabilities for insulin cold-chain requirements. Secondary city diabetes educator scarcity limits connected device penetration despite hardware availability.
Mexico Insulin Drugs and Delivery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational pharmaceutical incumbents commanding insulin analog formulation while domestic distributors control pen-needle channel access. The market structure concentrates in three tiers: premium patent-protected analogs, biosimilar substitution products, and commodity human insulin. Strategic archetypes include vertically integrated end-to-end diabetes care platforms, API-to-device manufacturers, and regional logistics specialists. Dominant competitive moves center on COFEPRIS biosimilar pathway navigation and direct-to-patient subscription channel construction bypassing traditional pharmacy intermediaries.
Within the multinational platform tier, Novo Nordisk A/S, Eli Lilly and Company, and Sanofi S.A. occupy positions exemplifying divergent strategic emphases. Novo Nordisk A/S represents the glucose-responsive R&D anchor, Eli Lilly and Company exemplifies manufacturing scale deployment for biosimilar production networks, and Sanofi S.A. anchors channel control strategies across Mexican pharmacy distribution. These three entities collectively illustrate how patent-protected innovation, cost-optimized supply, and distribution leverage create distinct competitive positions within the same regulatory environment.
| Leading Market Players |
|---|
| Biocon Limited |
| Boehringer Ingelheim |
| Novo Nordisk A/S |
| Merck and Co |
| AstraZeneca plc |
| Eli Lilly and Company |
| Pfizer Inc. |
| Novartis |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
Connected health platform consolidation is compressing standalone device margins while concentrating procurement leverage among integrated diabetes care providers in Mexico City and Guadalajara. This technology transition simultaneously raises software validation costs and reduces per-unit hardware economics across insulin delivery categories.
Pricing Analysis
Distributor margins on pen needles absorb the steepest compression as pharmacy chains consolidate procurement through direct manufacturer agreements. Three-tier pricing structure across premium analog formulations, biosimilar substitutions, and commodity human insulin segments reflects COFEPRIS certification tiers and cold-chain handling requirements. Pricing pressure stems from Secretaría de Salud bulk tender processes that favor lowest-compliant bids for public-sector volume. Price-sensitive public hospital procurement contrasts with premium-insured patient willingness to absorb connected device subscription premiums.
Supply Chain Analysis
Reverse logistics for insulin pump refurbishment and continuous glucose monitor sensor returns flow through specialized medical device reclaim centers in Mexico City and Monterrey. Active pharmaceutical ingredient production for biosimilar insulin concentrates in India and China, while pen-needle polymer components source from domestic Bajío region manufacturing clusters. Single-source vulnerability persists for glucose-responsive analog formulations where Novo Nordisk A/S controls proprietary production technology. Distribution runs through temperature-controlled logistics networks anchored by Mexico City cold-chain hubs serving pharmacy chains and direct-to-patient subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biosimilar manufacturing scale economies displacing premium analog volume and connected device subscription models capturing recurring revenue streams.
For Market Incumbents: Acquire specialized diabetes educator training capacity to accelerate connected device onboarding and reduce patient churn. Consolidate backward integration into pen-needle polymer component production within Bajío manufacturing clusters to offset distributor margin extraction. COFEPRIS software validation requirements for smart delivery systems threaten late-movers with extended product entry timelines. For New Entrants and Emerging Players: Begin with telemedicine-integrated direct-to-patient subscription channels in Monterrey and Tijuana serving cross-border insured populations. Monterrey private clinics present the most penetrable entry point for premium connected pump ecosystems given existing continuous glucose monitor infrastructure and specialized educator availability. Partner with established endocrinology practices to bypass pharmacy chain distribution bottlenecks. For Investors and Strategic Acquirers: Roll-up economics work for regional diabetes clinic networks because telemedicine integration enables scalable remote patient monitoring without proportional specialist headcount expansion. The five-to-ten year viability window favors platforms combining device dispensing with virtual care delivery. Target acquisition archetypes include Guadalajara-based specialty clinics with established connected health workflows. Monitor COFEPRIS pharmacovigilance rulemaking for connected device liability as an inflection signal for software services demand.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Biosimilar Pathway Navigation | Accelerated equivalence approvals expand affordable insulin access through streamlined regulatory frameworks. |
| Direct-to-Patient Subscription Launch | Home delivery partnerships with Mexico City clinics bypass traditional pharmacy intermediaries and capture patient data. |
| Connected Device Software Validation Investment | Upcoming pharmacovigilance requirements create first-mover advantage in liability-compliant smart delivery systems. |
| Diabetes Educator Training Capacity Buildout | Specialized onboarding capacity reduces patient churn and accelerates premium device adoption curves. |
| Cross-Border Clinic Network Partnership | Northern border facilities serving Texas-insured patients unlock premium pricing unavailable through Mexican public channels. |
Research Methodology
Direct dialogue with endocrinologists, COFEPRIS regulatory consultants, pharmacy chain procurement directors, and diabetes device distributors grounded the qualitative foundation. Secondary validation drew from COFEPRIS medical device registration databases, Secretaría de Salud procurement bulletins, hospital formulary records, and insulin import customs data. Bottom-up patient population estimates triangulated against top-down pharmaceutical sales audits across the analysis window.
Segmented outputs by product type, delivery mode, end user, and technology dimension informed the analytical framework throughout the projection horizon. CAGRs derived from insulin volume growth trajectories, device replacement cycles, and connected health adoption curves modeled against demographic diabetes prevalence trends. Forecast inputs incorporated COFEPRIS approval timeline assumptions and private insurance penetration rates across Mexican metropolitan zones.
Several conditions sit outside the modeled scope, including macroeconomic currency volatility affecting import-dependent device pricing and unforeseen regulatory reversals on biosimilar equivalence pathways. Forecasts reflect documented assumptions about cold-chain infrastructure expansion and telemedicine reimbursement stability. Practitioners should monitor COFEPRIS connected device guidance releases and Secretaría de Salud subsidy program revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Cancer Drug Market