
 South America Biofertilizers Market | 2026-2036
South America Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Biofertilizers Market Analytics
The gap between premium microbial consortia and commodity single-strain inoculants is expanding across South America. Rizobacter Argentina SA dominates rhizobia-based soybean inoculants through deep Argentine distribution networks. Novozymes A/S leverages advanced encapsulation technology to protect microbial viability under tropical storage conditions. Lallemand Inc. anchors yeast-derived biostimulant demand among Chilean grape and berry exporters seeking residue-free certification.
South America biofertilizers comprise living microorganisms or their derivatives formulated to enhance nutrient availability, fixation, or uptake in agricultural soils, typically delivered as liquid suspensions with colony-forming unit counts exceeding 10^9 CFU per milliliter or as peat-based solid carriers for direct seed application. Their primary commercial purpose centers on replacing or supplementing synthetic fertilizers to improve soil microbiome function while meeting rising export-market residue standards. Liquid biofertilizers capture the fastest growth trajectory due to compatibility with precision irrigation systems expanding across Brazilian center-pivot operations, while microbial inoculants maintain the largest volume share anchored by decades of rhizobia deployment in soybean monocultures. Agronomic crops concentrate margin pools through scale economies, though horticultural crops generate premium pricing from organic certification requirements in European-bound export chains.
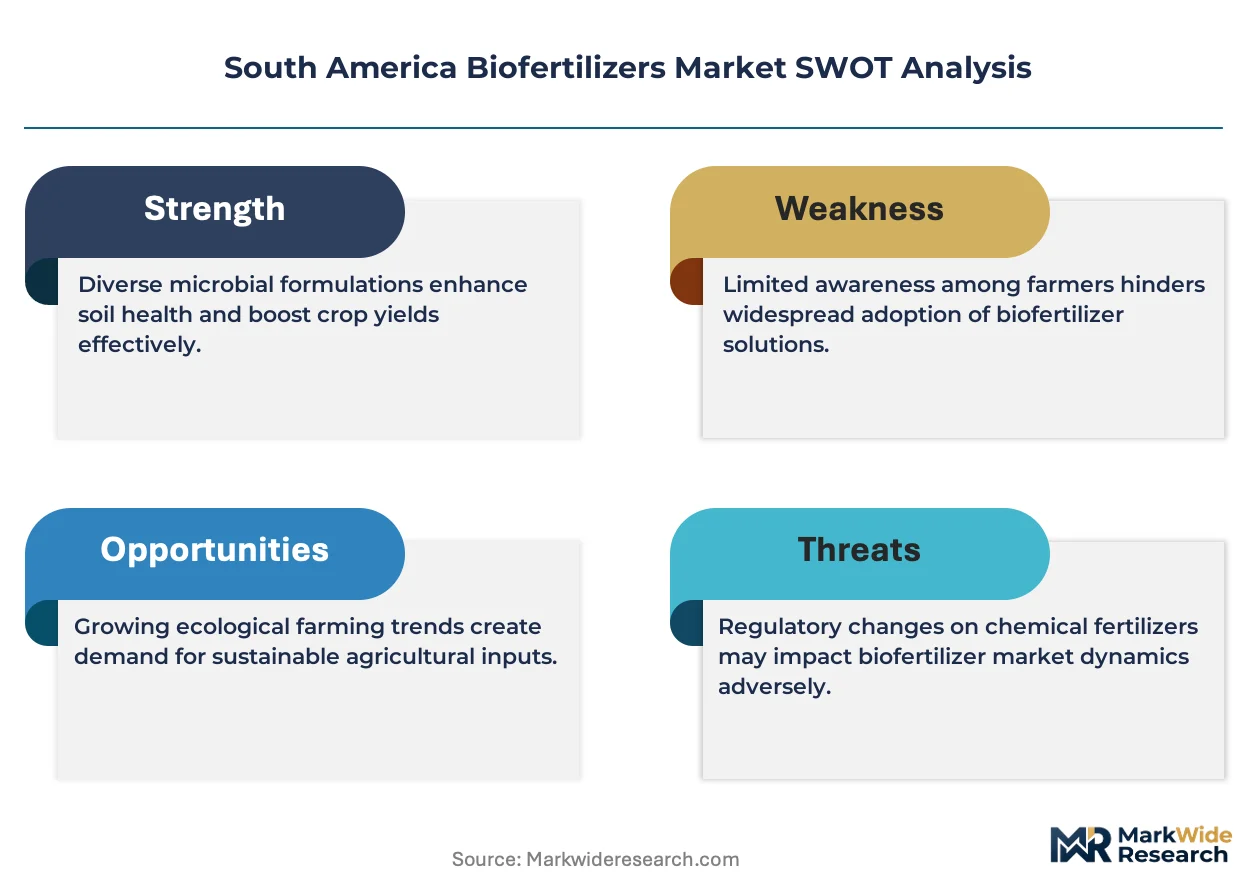
ANVISA regulates microbial product safety and efficacy claims in Brazil, while Argentina's national agricultural biosafety committee oversees field-release protocols for genetically modified and novel microbial strains. The EU Green Deal's deforestation-free supply chain regulations now extend to South American agricultural exports, pressuring growers toward verifiable low-input cultivation systems. Stakeholders must monitor how rapidly evolving carbon credit methodologies for biological nitrogen fixation reshape farmer payment structures and biofertilizer procurement decisions.
Market Dynamics
ANVISA's streamlined biostimulant registration pathways are compressing product approval timelines, while Brazil's ABC+ Low-Carbon Agriculture Plan ties biofertilizer adoption to carbon credit eligibility, fundamentally restructuring farmer procurement incentives across the continent.
Growth Catalysts
- EU Green Deal deforestation-free mandates:European import regulations now require verifiable low-input cultivation proof, pushing Brazilian soybean exporters toward certified microbial inoculants.
- Argentina's national agricultural biosafety committee protocols:Field-release frameworks for novel microbial strains are accelerating strain validation, shortening commercialization cycles for rhizobia suppliers.
- Precision irrigation expansion:Brazilian center-pivot operations in Mato Grosso are pulling liquid biofertilizer volumes through fertigation compatibility requirements.
Market Restraints
- Tropical storage viability gaps:Microbial shelf-life degradation under ambient heat conditions forces cold-chain investments that inflate landed costs for inland distributors.
- Peat carrier supply concentration:Estonian and Canadian peat extraction dominates solid inoculant substrate sourcing, exposing Argentine formulators to transatlantic shipping volatility.
- Synthetic nitrogen price cycles:Urea cost collapses triggered by Chinese export surges periodically compress biofertilizer substitution economics in price-sensitive cropping regions.
Strategic Opportunities
- Chilean grape export certification:Residue-free biostimulant demand from European-bound berry producers creates premium pricing pools for yeast-derived formulations.
- Carbon credit methodology maturation:Biological nitrogen fixation quantification protocols under Brazil's ABC+ framework will enable direct farmer payments tied to inoculant use.
- Encapsulation-CRISPR convergence:Advanced microbial protection technologies paired with strain engineering promise extended field persistence in drought-prone Cerrado soils.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization and quality control functions face recruitment gaps as academic pipelines lag commercial expansion in São Paulo and Buenos Aires.
- Multi-year certification timelines:ANVISA efficacy claim substantiation requires extensive field trials, locking working capital in pre-revenue product development cycles.
- Legacy synthetic fertilizer integration:Agronomist training and dealer incentive structures remain anchored to chemical product portfolios, complicating microbial advisory service rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Biofertilizers Market |
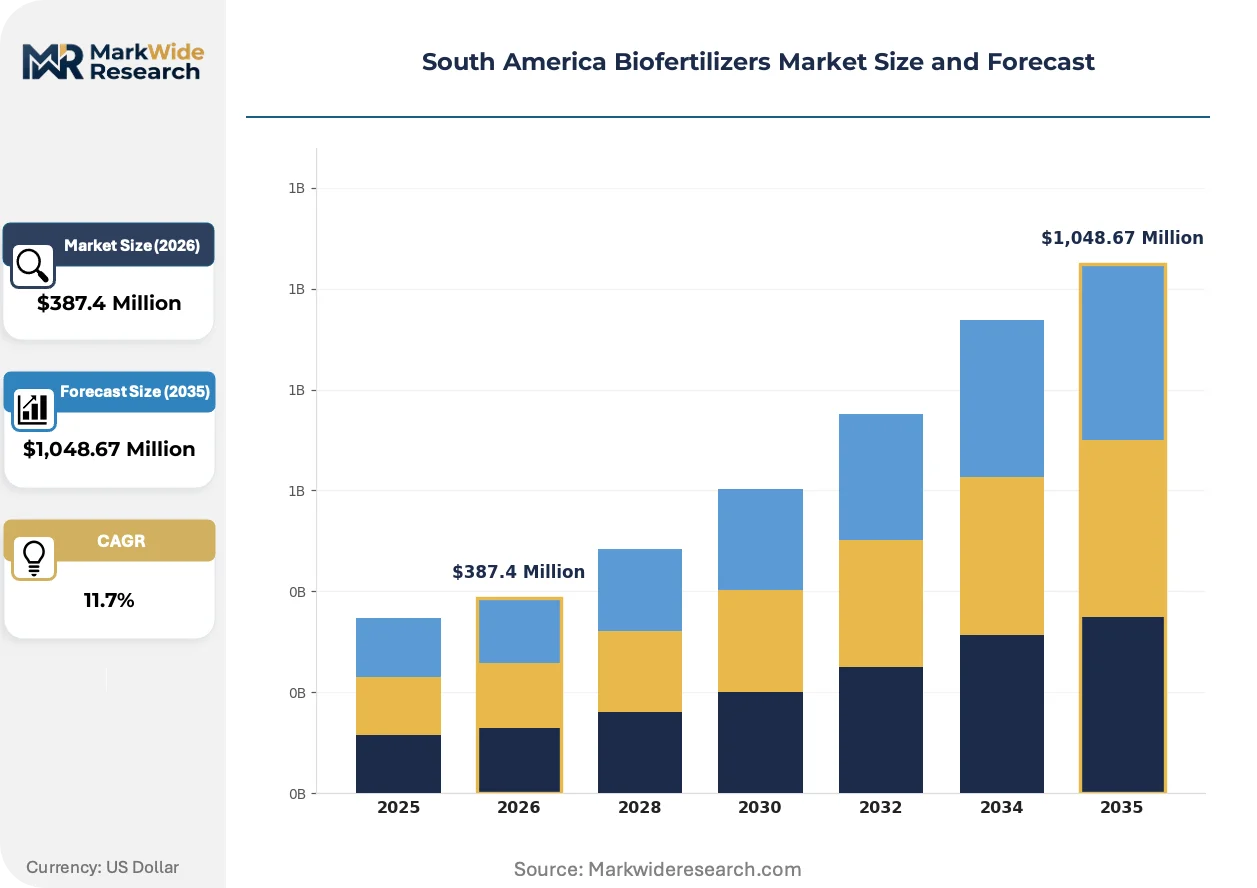
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,048.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Solid Biofertilizers, Biochar, Microbial Inoculants Application: Agronomic Crops, Horticultural Crops, Forestry, Turf and Ornamentals End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Distribution Channel: Online Sales, Specialty Retail, Agricultural Supply Stores, Distributors |
| Companies Covered | Nutrien Ltd, Lallemand Inc., Rizobacter Argentina SA, Novozymes A/S, Agrinos AS, Bioceres Crop Solutions Corp, Grupo Vittia, Bayer CropScience, BIOMAX, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Biofertilizers Market Evolving Landscape
Formulation science and regulatory alignment are converging to reshape competitive positioning, with survival hinging on tropical stability engineering and carbon-market connectivity rather than strain discovery alone.
Polymer-based microencapsulation is unifying thermal protection with controlled-release functionality for rhizobia and phosphate-solubilizing bacteria. Large-scale no-till operators in Paraná are piloting these formulations at accelerating rates. The technology is unifying previously separate supply chains for biologicals and precision application equipment into integrated service offerings.
Brazil's ABC+ Low-Carbon Agriculture Plan now mandates documented biological input use for carbon credit eligibility in funded projects. This regulatory architecture forces input suppliers to restructure technical service teams around measurement, reporting, and verification protocols. Soybean cooperatives in Mato Grosso are responding by consolidating procurement through certified biofertilizer bundles rather than spot chemical purchases.
Buyer concentration among export-oriented agricultural conglomerates is compressing supplier negotiation leverage and lengthening payment terms. Traditional agrochemical distribution networks are losing ground to direct manufacturer relationships with integrated farm operations. Chilean berry exporters demonstrate this shift most visibly, bypassing regional distributors to contract directly with biostimulant developers for residue-free certification compliance.
South America Biofertilizers Market Segmentation
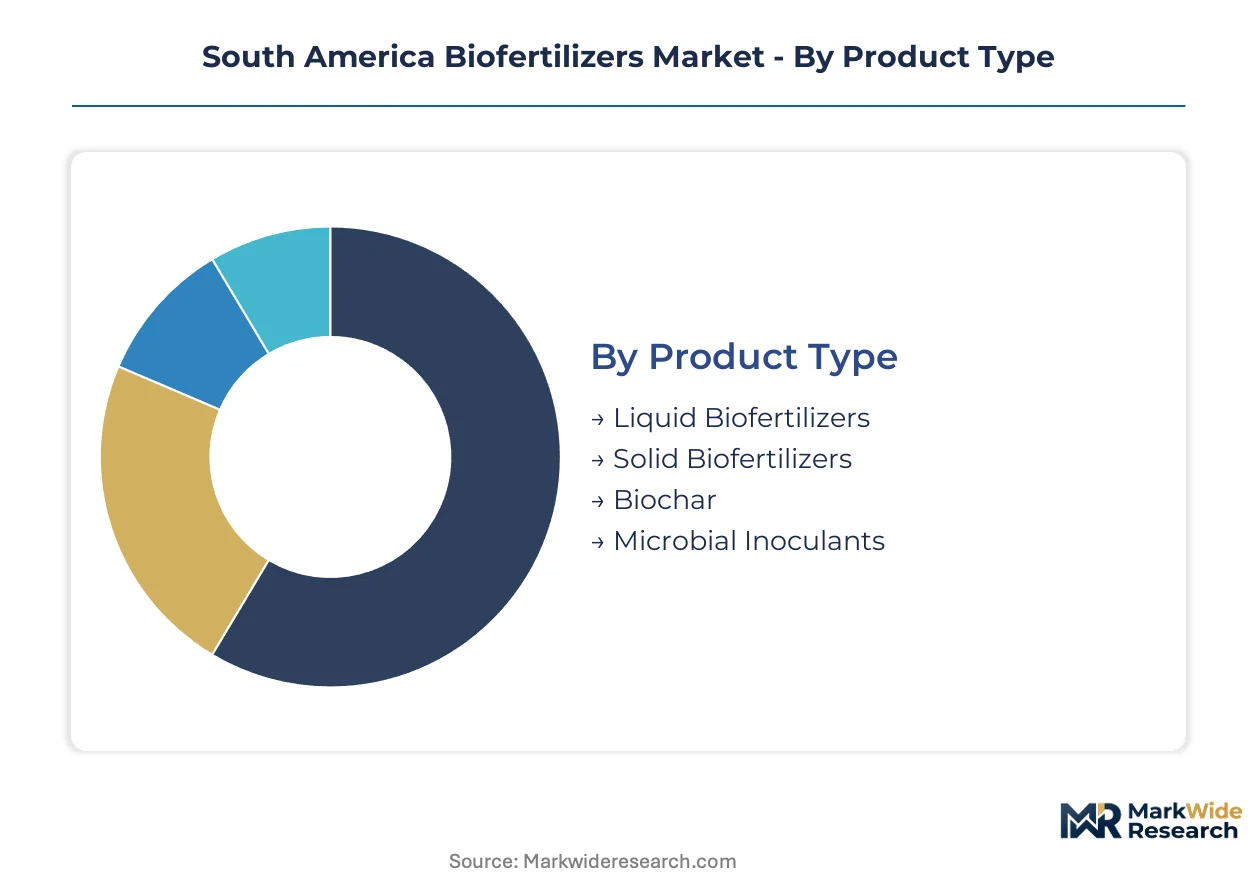
Biofertilizer procurement patterns across South America diverge sharply by product physics, crop economics, and buyer sophistication. Segmentation reveals where premium formulations command pricing power versus where commodity volumes dominate purchasing decisions.
Product Type:
Customization intensity runs highest in liquid formulations engineered for specific irrigation chemistries, while solid carriers standardize around proven peat-based delivery systems.
- Liquid Biofertilizers:Suspensions exceeding 10^9 CFU per milliliter formulated for fertigation compatibility. Brazilian center-pivot operators in Mato Grosso pull volumes through direct injection systems, though tropical storage degradation forces cold-chain investments that inflate landed costs.
- Microbial Inoculants:Living rhizobia, phosphate-solubilizing bacteria, or mycorrhizal fungi delivered via liquid or solid carriers. Soybean monocultures across Argentina's Pampas and Brazil's Cerrado anchor demand through decades of proven nitrogen fixation performance.
- Solid Biofertilizers:Peat, granular, or polymer-based carriers enabling direct seed application. Estonian and Canadian peat extraction concentration exposes formulators to transatlantic shipping volatility.
- Biochar:Carbon-rich soil amendment produced through pyrolysis of agricultural residues. Carbon credit eligibility under Brazil's ABC+ framework drives pilot adoption among low-carbon certification seekers.
Leading the category by volume: Microbial Inoculants. Expanding most quickly: Liquid Biofertilizers.
Application:
Margin pools concentrate in export-facing horticulture where residue-free certification commands premium pricing, while agronomic scale economies drive volume procurement consolidation.
- Agronomic Crops:Soybean, corn, and wheat production systems consuming bulk microbial inoculants. Large-scale no-till operators in Paraná and Mato Grosso states generate volume pull through cooperative procurement structures.
- Horticultural Crops:Grape, berry, and vegetable cultivation requiring residue-free biostimulant inputs. Chilean exporters to European markets pay premium pricing for yeast-derived formulations meeting EU Green Deal deforestation-free mandates.
- Forestry:Eucalyptus and pine plantation establishment using mycorrhizal inoculants. Brazilian pulp sector vertical integration into biological input sourcing accelerates direct manufacturer relationships.
- Turf and Ornamentals:Golf course, landscaping, and nursery applications. Urban greening initiatives in São Paulo and Buenos Aires metro areas generate specialized demand for aesthetic performance guarantees.
Highest margin capture: Horticultural Crops. Steepest volume trajectory: Agronomic Crops.
End User:
Buyer sophistication stratifies between integrated operations with in-house agronomy teams and fragmented smallholders dependent on dealer advisory networks.
- Farmers:Individual operators from subsistence-scale to mid-sized commercial holdings. Price sensitivity peaks in Argentina's interior provinces where urea cost cycles periodically compress biofertilizer substitution economics.
- Agricultural Cooperatives:Consolidated purchasing entities representing hundreds to thousands of members. Mato Grosso soybean cooperatives increasingly bundle certified biofertilizer procurement to meet ABC+ carbon credit documentation requirements.
- Commercial Growers:Corporate farming operations with dedicated input procurement functions. Direct manufacturer relationships bypass traditional distribution networks, compressing regional distributor margins.
- Research Institutions:Universities and agricultural extension services conducting strain validation trials. ANVISA efficacy claim substantiation protocols lock working capital in multi-year field study commitments.
Fastest-growing procurement consolidation: Agricultural Cooperatives. Most price-sensitive segment: Farmers.
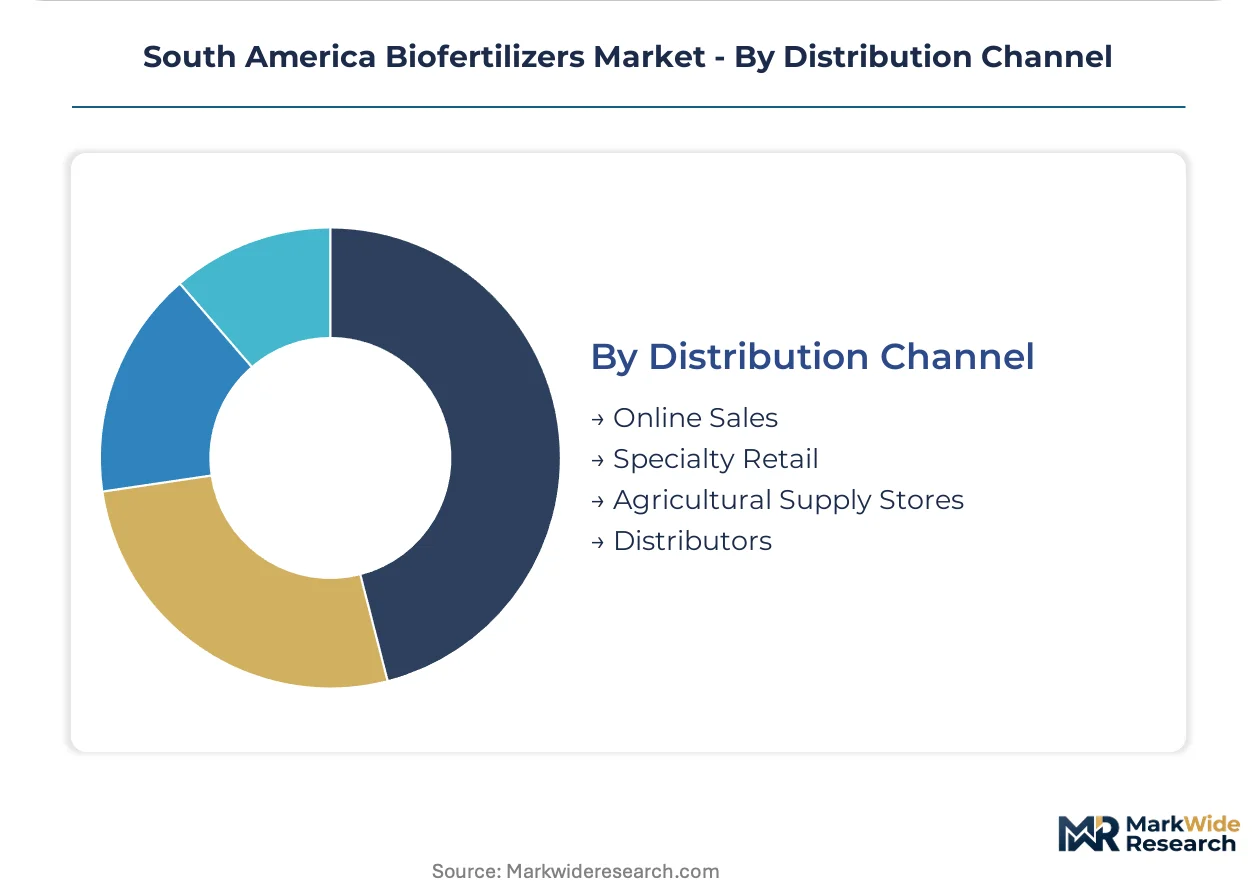
Distribution Channel:
Channel power shifts from legacy agrochemical dealer networks toward direct manufacturer relationships with volume buyers and digital platforms reaching underserved geographies.
- Distributors:Regional wholesale networks historically anchored to synthetic fertilizer portfolios. Legacy agronomist training and dealer incentive structures complicate microbial advisory service rollout.
- Agricultural Supply Stores:Local retail points serving smallholder communities. Inventory turnover constraints limit microbial product shelf-life management capabilities in tropical conditions.
- Specialty Retail:Biological-input-focused retailers with technical service capabilities. Chilean berry exporters demonstrate channel bypass most visibly, contracting directly with biostimulant developers.
- Online Sales:E-commerce platforms reaching remote farming regions with limited physical infrastructure. Precision irrigation equipment compatibility specifications drive technical content requirements in digital purchasing journeys.
Dominant volume channel: Distributors. Fastest channel share gain: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American biofertilizer commercialization through its concentration of formulation laboratories, regulatory consulting firms, and the headquarters of Brazil's largest agricultural cooperatives.
Brazil
Mato Grosso and Paraná states generate the continent's highest biofertilizer volumes through large-scale no-till soybean operations. ANVISA's streamlined biostimulant registration pathways compress product approval timelines for microbial formulations. São Paulo-based technical service teams coordinate carbon credit documentation under the ABC+ Low-Carbon Agriculture Plan for cooperative members.
Argentina
The Pampas region sustains decades-old rhizobia inoculant deployment across soybean monocultures, creating established farmer familiarity with biological inputs. Argentina's national agricultural biosafety committee oversees field-release protocols for novel microbial strains, accelerating strain validation cycles. Buenos Aires province hosts the deepest distribution networks for peat-based solid inoculants.
Chile
Central Valley grape and berry exporters drive premium biostimulant demand tied to EU Green Deal deforestation-free certification requirements. The country's national agricultural service enforces residue-free standards for European-bound produce. Metropolitan Santiago clusters yeast-derived formulation specialists serving export-oriented horticultural conglomerates.
Colombia
Coffee-growing highlands in Antioquia and Caldas departments pilot mycorrhizal inoculants for phosphorus-deficient Andean soils. The national agricultural institute promotes biological input adoption through extension programs. Bogotá serves as the regional hub for microbial quality control laboratories certifying products for Andean market entry.
South America Biofertilizers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and tropical stability engineering capabilities. The market structures around three tiers: multinational biological input specialists with encapsulation patents, regional rhizobia suppliers with deep cooperative relationships, and domestic formulators dependent on imported peat substrates. Strategic moves concentrate on backward integration into strain characterization laboratories and direct contracting with integrated farm operations bypassing legacy distribution networks.
Within the multinational tier, Novozymes A/S and Lallemand Inc. occupy positions defined by advanced microbial protection technologies and yeast-derived biostimulant expertise respectively. Rizobacter Argentina SA anchors the regional specialist tier through its Argentine S.A. structure and decades of Pampas distribution presence. These three exemplify how competitive positioning now hinges on tropical storage viability engineering and carbon-market connectivity rather than strain discovery alone.
| Leading Market Players |
|---|
| Nutrien Ltd |
| Lallemand Inc. |
| Rizobacter Argentina SA |
| Novozymes A/S |
| Agrinos AS |
| Bioceres Crop Solutions Corp |
| Grupo Vittia |
| Bayer CropScience |
| BIOMAX |
| Others |
Value Network & Pricing Analysis
ABC+ carbon credit documentation requirements from Brazilian soybean cooperatives are forcing formulators to absorb cold-chain infrastructure costs, compressing margins on liquid biofertilizer deliveries to Mato Grosso's interior while elevating pricing power for certified premium consortia.
Pricing Analysis
Yield-guarantee contracts anchor value-based pricing for microbial inoculants across Argentina's Pampas, with nitrogen fixation performance tiers separating premium multi-strain formulations from commodity rhizobia products. Certification level under ANVISA's biostimulant pathways and cold-chain delivery capability constitute the primary price differentiation drivers. Cost compression in standard peat-based carriers is intensifying because Estonian supply volatility forces inventory carrying cost increases. Smallholder farmers in Argentina's interior provinces exhibit highest price sensitivity, while Chilean berry exporters demonstrate lowest sensitivity due to EU Green Deal compliance premiums.
Supply Chain Analysis
Dual-sourcing mandates from Mato Grosso cooperatives now require qualified suppliers to maintain strain characterization partnerships with both São Paulo and Buenos Aires laboratories, fragmenting procurement leverage. Geographic supply concentration centers on Brazil, Argentina, and Estonia for peat substrates. Raw material dependencies include Canadian and Estonian peat extraction, tropical-stability polymer encapsulants, and CRISPR-edited rhizobia master cultures. Single-source vulnerability runs through transatlantic peat shipping lanes exposed to Baltic port congestion. Distribution runs through legacy agrochemical dealer networks losing share to direct manufacturer relationships with integrated farm operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over strain characterization laboratories to lock ANVISA approval pathways and compress multi-year certification timelines.
For Market Incumbents: Extend encapsulation technology patent portfolios into drought-resistant Cerrado-specific formulations before CRISPR-engineered competitors reach commercial scale. Consolidate backward integration into peat substrate alternatives such as biochar carriers to neutralize Estonian supply volatility. Lock exclusive technical service contracts with Mato Grosso cooperatives to defend against direct manufacturer bypass. For New Entrants and Emerging Players: Polymer-based thermal protection technologies unifying controlled-release with tropical storage stability offer entry leverage into Paraná's no-till operator networks underserved by legacy distributors. Target Colombia's coffee highlands for mycorrhizal pilots in phosphorus-deficient Andean soils where incumbent presence remains thin. Pursue digital platform partnerships with precision irrigation equipment suppliers to bypass dealer channel fragmentation. For Investors and Strategic Acquirers: The window for entry favors mid-cap biological input specialists with ANVISA-approved strain libraries and existing cooperative relationships across the analysis window. Acquisition target archetypes include regional formulators with validated carbon credit quantification methodologies under Brazil's ABC+ framework. Watch for biological nitrogen fixation protocol maturation as inflection indicator for farmer payment structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Characterization Labs | Captive ANVISA approval capabilities compress competitor entry timelines by locking regulatory pathways. |
| Direct Manufacturer Relationships with Cooperatives | Bypass of legacy dealer networks captures margin compression from buyer consolidation in Mato Grosso. |
| Encapsulation-CRISPR Technology Convergence | Extended field persistence in drought-prone Cerrado soils commands premium positioning against commodity inoculants. |
| Carbon Credit Methodology Certification | ABC+ documentation compliance enables bundled procurement contracts with export-oriented agricultural conglomerates. |
| Peat Substrate Alternative Development | Biochar and polymer carrier sourcing neutralizes transatlantic shipping volatility from Estonian supply concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with biofertilizer formulators, agricultural cooperative procurement managers, ANVISA regulatory consultants, and precision irrigation equipment distributors. ANVISA biostimulant registration databases, Brazilian agricultural export statistics, Argentine biosafety committee field-release protocols, and EU Green Deal deforestation-free supply chain documentation constituted core secondary sources. Bottom-up strain validation timelines and top-down cooperative procurement volume estimates were triangulated against manufacturer capacity disclosures.
Granularity-level modeling operated at product-type, crop-application, and end-user tiers, with additional dimensioning by state-level adoption patterns across Brazil's Center-West and Southern regions. CAGRs were derived from volume trajectory analysis across the projection horizon, incorporating biological nitrogen fixation quantification protocol maturation as industry-specific demand driver. Tropical storage degradation curves and carbon credit eligibility thresholds informed price elasticity assumptions throughout the modeling period.
Several conditions sit outside the modeled scope, including synthetic nitrogen price collapse scenarios triggered by Chinese export surges and abrupt ANVISA regulatory pathway revisions. Forecasts reflect assumptions regarding cooperative procurement consolidation continuity and ABC+ plan funding stability. A model refresh is warranted upon material change in biological nitrogen fixation carbon credit methodology adoption rates or peat substrate supply disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
North America Biological Organic Fertilizer Market