
 Seed Biostimulants Market | 2026-2036
Seed Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Biostimulants Market Analytics
Agricultural distributor networks is rewriting how biological inputs reach farmgate customers in major producing regions. BASF SE leverages its seed treatment formulation heritage to embed biostimulants directly into proprietary coating workflows. Syngenta Group anchors its position through integrated seed-applied biological platforms that bundle biostimulants with crop protection chemistries. Novozymes A/S specializes in microbial strain discovery, converting enzymatic capabilities into seed-compatible inoculant products.
Seed biostimulants comprise biologically active substances and microorganisms applied to seeds or seedlings to enhance nutrient use efficiency, abiotic stress tolerance, or crop quality traits without direct pesticidal action. These formulations typically incorporate defined cell counts of rhizobacteria, precise concentrations of seaweed-derived betaines, or standardized humic fractions measured by organic carbon content. Microbial inoculants command premium positioning due to patent-protected strain libraries and registration complexity that limits generic competition. Seaweed extracts occupy the fastest-expanding formulation niche as extraction technologies improve bioactive compound consistency.
The EU Fertilizing Products Regulation harmonizes biostimulant definitions across member states, while the EPA and USDA jointly oversee microbial product registration and organic compatibility claims in the United States. India's FSSAI and BIS frameworks are developing standards for agricultural biologicals that will determine import eligibility and domestic manufacturing incentives. Stakeholders must monitor how regulatory divergence between jurisdictions affects product registration timelines and label claim permissibility.
Market Dynamics
The EU Fertilizing Products Regulation is compressing product registration timelines while simultaneously fragmenting compliance pathways across member states, forcing manufacturers to maintain parallel dossier strategies for the same biological active substance.
Growth Catalysts
- Biological Primers:Specialty row-crop producers in Brazil are expanding seed treatment protocols that incorporate microbial primers ahead of planting, creating pull-through demand for compatible biostimulant formulations.
- REACH Harmonization:The EU Fertilizing Products Regulation is reclassifying biostimulant claims and creating unified compliance frameworks that reduce duplicate testing burdens across Germany, France, and Italy.
- Farmer Co-op Aggregation:Demand is concentrating in the North American corn-soy belt where agricultural cooperatives are pooling procurement volumes for biological seed treatments.
Market Restraints
- Strain Patent Concentration:Microbial inoculant supply depends on patent-protected strain libraries held by a limited cohort of discovery houses, constraining generic competition and inflating royalty structures.
- Extraction Cost Volatility:Seaweed-derived betaines face input cost pressure from marine biomass harvesting quotas and seasonal supply interruptions in North Atlantic sourcing zones.
- Label Claim Divergence:The EPA and USDA maintain non-harmonized microbial product registration pathways in the United States, creating label claim permissibility gaps that delay commercialization.
Strategic Opportunities
- India Standards Development:The FSSAI and BIS frameworks are developing agricultural biological standards that will determine import eligibility and domestic manufacturing incentives for microbial inoculants.
- Seed-Applied Bundling:Convergence between biostimulant coatings and crop protection chemistries is opening integrated platform architectures that lock in multi-year grower contracts.
- Direct-to-Farm Channels:Agricultural distributor networks are rewriting biological input reach, creating bypass opportunities around legacy agronomic service providers in major producing regions.
Industry Challenges
- Microbial Formulation Expertise:Seed-compatible inoculant development requires rare cross-functional capabilities spanning strain selection, desiccation tolerance engineering, and coating adhesion chemistry.
- Organic Carbon Standardization:Humic fraction products lack unified organic carbon content measurement protocols, forcing manufacturers to maintain multiple certification dossiers for equivalent material grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Biostimulants Market |
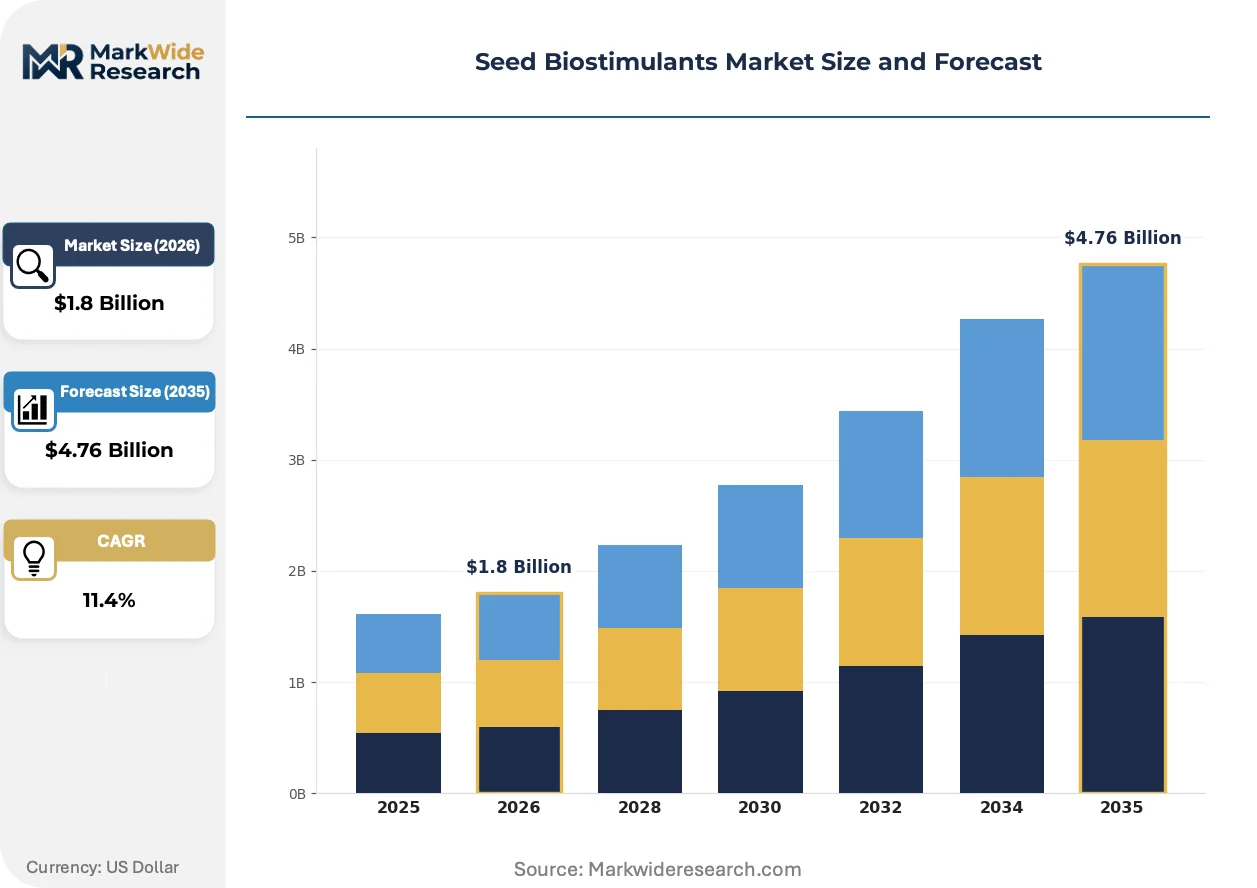
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Amino Acids, Seaweed Extracts, Microbial Inoculants End Use Industry: Agriculture, Horticulture, Turf & Ornamentals, Greenhouse Application: Root Development, Stress Management, Nutrient Uptake, Crop Yield Enhancement Formulation: Liquid, Granular, Powder, Pelleted |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, UPL Limited, Valagro, FMC Corporation, Corteva Agriscience, Novozymes A/S, Biolchim S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Biostimulants Market Evolving Landscape
Formulation science is advancing extraction technologies and microbial stabilization methods that expand the functional shelf-life of biological seed treatments. These developments are compressing the performance gap between synthetic and biological inputs.
Encapsulation technologies for live microbial strains are hybridizing desiccation protection with controlled-release kinetics, enabling storage-stable inoculants that activate upon soil contact. Large-scale corn and soybean operations in Iowa and Illinois are adopting these formulations at accelerating rates. The technology is hybridizing previously separate product categories—raw inoculants and polymer-coated seeds—into unified treatment workflows that reduce field application passes.
The EU Fertilizing Products Regulation is mandating CE-marking conformity assessments for all biostimulant products entering the European single market. Manufacturers must now compile full substance characterization data and efficacy validation studies under harmonized formats. Specialty row-crop producers in Spain and Poland are responding by demanding pre-certified biological inputs from suppliers with established EU regulatory affairs capabilities.
Farmer procurement patterns are fragmenting away from bundled agronomic service packages toward unbundled biological input purchasing. Agricultural cooperatives in the US corn-soy belt are disintermediating traditional crop advisor relationships by aggregating direct volume commitments with seed treatment formulators. This behavioral shift is most visible in Minnesota and Indiana, where co-op buying power is compressing distributor margins and forcing legacy channel participants to reposition around technical advisory services.
Seed Biostimulants Market Segmentation
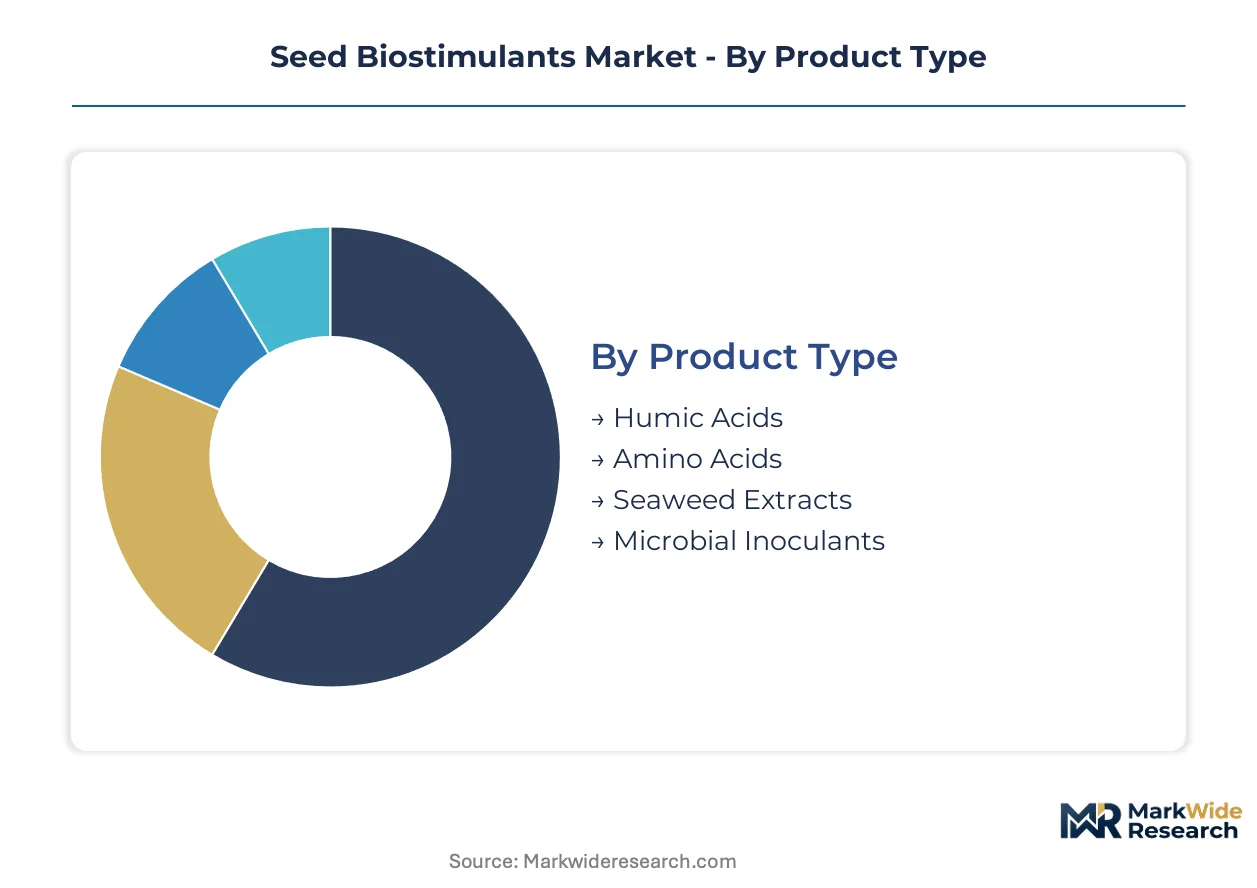
Seed biostimulant segmentation reveals distinct technical requirements across crop systems and application contexts. Each dimension carries specific formulation constraints that determine commercial viability and regulatory pathway complexity.
Product Type:
Use-case spectrum spans soil conditioning chemistry through live microbial delivery, with each category demanding incompatible manufacturing infrastructure and stability engineering.
- Microbial Inoculants:Defined cell-count preparations of rhizobacteria and mycorrhizal fungi requiring desiccation tolerance engineering and cold-chain logistics. Patent-protected strain libraries held by discovery houses in Denmark and the Netherlands command premium positioning in Brazil's soybean belt where biological primers are expanding.
- Seaweed Extracts:Standardized betaine and cytokinin concentrates from Laminaria and Ascophyllum biomass. Extraction technology improvements in Ireland and Norway are improving bioactive compound consistency for specialty row-crop producers seeking abiotic stress tolerance.
- Humic Acids:Organic carbon fractions from leonardite and peat sources measured by humic/fulvic acid ratios. Lack of unified organic carbon measurement protocols forces manufacturers to maintain multiple certification dossiers for equivalent material grades.
- Amino Acids:Hydrolyzed protein preparations from plant and animal origin with defined free amino acid profiles. Compatibility constraints with certain pesticide chemistries limit co-application flexibility in integrated treatment protocols.
Established volume favors microbial inoculants; emerging adoption favors seaweed extracts.
End Use Industry:
Customer maturity and procurement scale separate high-volume field agriculture from precision-controlled protected systems.
- Agriculture:Large-scale row-crop and broadacre operations in Iowa, Illinois, and Mato Grosso where farmer co-ops aggregate biological seed treatment procurement. Corn-soy rotation systems drive demand for nutrient use efficiency formulations.
- Horticulture:Specialty fruit and vegetable producers in Spain's Almería region and California's Central Valley. High-value crop economics justify premium biological input costs.
- Greenhouse:Controlled-environment producers in the Netherlands and Mexico employing precision irrigation and substrate systems. Recirculating nutrient solutions create unique microbial ecology management requirements.
- Turf & Ornamentals:Golf course superintendents and landscape contractors in Florida and Arizona. Seasonal application windows and aesthetic performance standards define product selection criteria.
Revenue concentration sits with agriculture; margin expansion potential concentrates in greenhouse.
Application:
Functional claims determine regulatory classification and label permissibility across jurisdictions.
- Nutrient Uptake:Phosphorus solubilization and nitrogen fixation enhancement through microbial metabolite production. EPA and USDA joint oversight in the United States creates registration pathway complexity for cross-claim products.
- Stress Management:Abiotic tolerance induction via osmoprotectant accumulation and antioxidant enzyme activation. EU Fertilizing Products Regulation harmonization is compressing efficacy validation requirements for drought and salinity claims.
- Root Development:Lateral root initiation and root hair density enhancement through auxin signaling modulation. Compatibility with existing seed coating chemistries determines commercial adoption in proprietary treatment workflows.
- Crop Yield Enhancement:Harvest index improvement through source-sink relationship optimization. Claim language restrictions in India under developing FSSAI and BIS frameworks limit permissible promotional content.
Regulatory clarity favors nutrient uptake; farmer pull-through favors stress management.
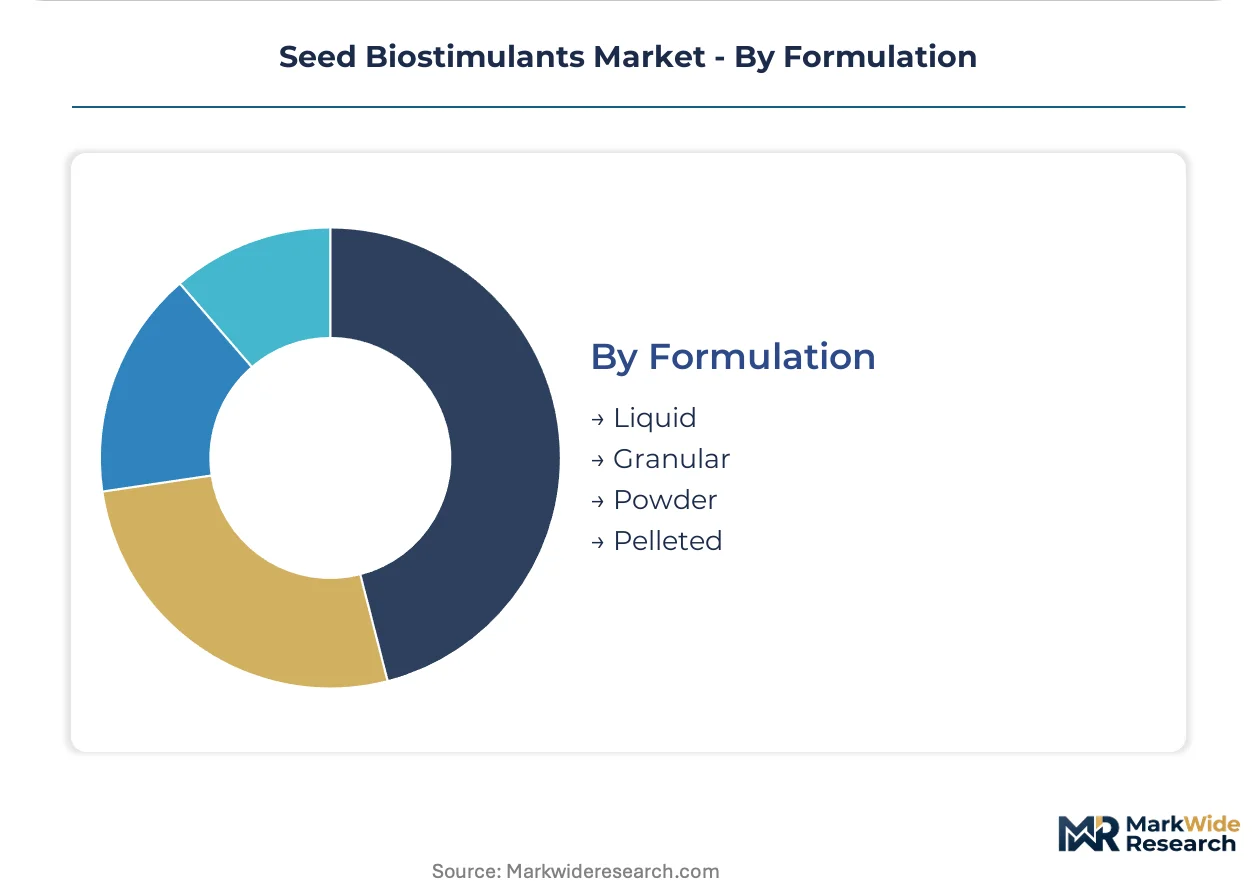
Formulation:
Physical state determines equipment compatibility, shelf stability, and field application flexibility.
- Liquid:Suspension concentrates and emulsifiable formulations with extended tank-mix stability. Dominates commercial seed treatment facilities in Minnesota and Indiana where co-op procurement aggregation is compressing distributor margins.
- Granular:Carriers impregnated with biological actives for in-furrow application. Favored in Brazilian no-till systems where equipment limitations restrict liquid handling capacity.
- Powder:Dry flowable preparations requiring dust control engineering. Compatibility with farmer-applied seed treatments in developing markets where commercial coating infrastructure is limited.
- Pelleted:Pre-formed seed coating matrices integrating biological and chemical actives. Emerging convergence between biostimulant coatings and crop protection chemistries in integrated platform architectures.
Processing infrastructure favors liquid; on-farm flexibility favors granular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazil's soybean belt while European manufacturers absorb compliance cost premiums under harmonized regulations. Farmer co-op procurement in the United States compresses distributor margins, shifting value capture toward formulators with direct channel access.
United States
EPA and USDA joint oversight creates registration pathway complexity for microbial products claiming nutrient uptake benefits. Farmer cooperatives in Minnesota and Indiana aggregate biological seed treatment volumes, disintermediating legacy crop advisor relationships. Iowa and Illinois corn-soy operations adopt encapsulation technologies at accelerating rates.
Brazil
Specialty row-crop producers in Mato Grosso expand seed treatment protocols incorporating biological primers ahead of planting. ANVISA frameworks govern agricultural biological registration, though state-level enforcement varies across producing regions. The Cerrado agricultural frontier drives pull-through demand for compatible biostimulant formulations in no-till systems.
Germany
EU Fertilizing Products Regulation mandates CE-marking conformity assessments for biostimulant products entering the European single market. REACH harmonization reduces duplicate testing burdens across member states while compressing registration timelines. Formulation expertise clusters in Ludwigshafen and Leverkusen anchor proprietary coating workflow development.
India
FSSAI and BIS frameworks develop agricultural biological standards determining import eligibility and domestic manufacturing incentives. Regulatory divergence from OECD jurisdictions affects product registration timelines and label claim permissibility. Maharashtra and Gujarat processing hubs respond by building regulatory affairs capabilities for microbial inoculant dossier preparation.
China
NMPA and MEE oversight structures govern microbial fertilizer registration and environmental release assessments for biological actives. Dual carbon goals accelerate substitution incentives for synthetic input reduction in major grain-producing provinces. Yangtze River Delta formulation facilities invest in desiccation tolerance engineering for seed-compatible inoculants.
Seed Biostimulants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying strain libraries and extraction technologies. The vendor base organizes around three strategic archetypes: multinational agrochemical conglomerates with seed treatment heritage, dedicated microbial discovery houses with patent-protected strain collections, and regional formulation specialists serving protected-crop segments. Consolidation pressure intensifies as integrated platform architectures lock in multi-year grower contracts through bundled biological-chemical coatings.
Within the multinational platform tier, Syngenta Group and BASF SE exemplify divergent strategic positions. Syngenta anchors integrated seed-applied biological platforms that bundle biostimulants with crop protection chemistries. BASF leverages formulation heritage to embed biostimulants directly into proprietary coating workflows. Novozymes A/S occupies the upstream discovery specialist position, converting enzymatic capabilities into seed-compatible inoculant products.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| UPL Limited |
| Valagro |
| FMC Corporation |
| Corteva Agriscience |
| Novozymes A/S |
| Biolchim S.p.A |
| Others |
Value Network & Pricing Analysis
Undercapacity in microbial strain fermentation capacity across Denmark and the Netherlands is compressing supplier margins while elevating royalty structures for patent-protected inoculants. This utilization squeeze forces formulation houses to prioritize high-volume contracts with integrated platform players over fragmented distributor networks.
Pricing Analysis
The customization-premium spread separates configured-to-order microbial inoculants from standard seaweed extract formulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under EU Fertilizing Products Regulation and volume scale through farmer co-op aggregation. Cost compression in standard-grade humic acids is intensifying because of organic carbon measurement protocol fragmentation. Smallholder procurement in developing markets exhibits highest price sensitivity; greenhouse operators in the Netherlands show lowest.
Supply Chain Analysis
Export-control regimes on desiccation-tolerance engineering technologies limit strain stabilization know-how flows from OECD discovery houses to emerging manufacturing hubs. Concentrated supply rests on Denmark, the Netherlands, and Ireland for microbial strain libraries and extraction infrastructure. Raw material dependencies include North Atlantic Ascophyllum biomass, leonardite deposits, and defined-cell-count rhizobacteria cultures. Single-source vulnerability concentrates in patent-protected strain access. Distribution runs through agricultural distributor networks rewriting biological input reach in Brazil's Mato Grosso and the US corn-soy belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward agricultural cooperatives aggregating procurement volumes, fragmenting legacy agronomic service relationships and compressing distributor margins across major producing regions.
For Market Incumbents: Pre-empt co-op direct-channel expansion by embedding biostimulants into proprietary seed coating workflows that lock in multi-year grower contracts. Defend against microbial discovery house royalty inflation through backward integration into strain libraries. Prioritize certification investment under EU Fertilizing Products Regulation CE-marking pathways. For New Entrants and Emerging Players: Build out regulatory affairs capabilities in India where FSSAI and BIS framework development creates first-mover eligibility advantages. Target greenhouse segment in Mexico and Spain's Almería region where high-value crop economics justify premium biological input costs. Pursue direct-to-farm channel partnerships bypassing legacy crop advisor networks. For Investors and Strategic Acquirers: Capital is best deployed toward upstream microbial discovery specialists with patent-protected strain collections and established desiccation tolerance engineering. Long-term viability over the projection horizon hinges on convergence between biostimulant coatings and crop protection chemistries. Watch for inflection when integrated platform architectures capture majority share of farmer co-op procurement aggregation.| Strategic Initiative | Industry Significance |
|---|---|
| Seed-Applied Bundling | Integrated platforms lock in multi-year grower contracts through combined biological-chemical coatings. |
| Regulatory Affairs Buildout | EU Fertilizing Products Regulation CE-marking capability determines European single market access. |
| Direct-to-Farm Channel Expansion | Co-op procurement aggregation in Iowa and Illinois disintermediates legacy distributor networks. |
| Strain Library Acquisition | Patent-protected microbial collections command premium positioning in Brazil's expanding biological primer protocols. |
| Extraction Technology Investment | Improved bioactive compound consistency from Irish and Norwegian facilities accelerates seaweed extract adoption. |
Research Methodology
A spread of perspectives from seed treatment formulators, agricultural cooperative procurement officers, microbial discovery house R&D directors, and regulatory affairs specialists converged on the working assumptions. Primary interview data combined with secondary validation from EPA microbial product registrations, EU Fertilizing Products Regulation dossier filings, ANVISA agricultural biological frameworks, and customs trade data for biological input imports. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Demand-supply balance dynamics across microbial inoculant fermentation capacity and seaweed biomass harvesting quotas shaped the forecast architecture. Segmentation dimensions modeled include product type, end-use industry, functional application claim, and physical formulation state. CAGRs derived from installed base growth rates and replacement cycle analysis. Industry-specific inputs incorporated farmer co-op procurement aggregation patterns and encapsulation technology adoption curves.
Stress conditions across regulatory registration timeline compression, marine biomass supply interruption, and strain patent expiration windows were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on co-op buying power expansion and EU harmonization implementation pace. Material shifts in EPA-USDA joint oversight harmonization or India FSSAI framework finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
China Biostimulants Market