
 Europe Anaerobic Digestion Market | 2026-2036
Europe Anaerobic Digestion Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anaerobic Digestion Market Analysis
Modular containerized digester packages is expanding as the dominant configuration pattern across European agricultural and industrial deployments. EnviTec Biogas leverages standardized plug-and-play reactor skids to reduce on-site construction duration for dairy and food-waste operators. Weltec Biopower anchors its competitiveness through in-house fabrication of membrane-covered lagoon systems, while PlanET Biogas specializes in farm-scale cascaded digesters that integrate liquid residue return loops.
Anaerobic digestion denotes the oxygen-free biological decomposition of organic substrates by consortia of hydrolytic, acidogenic, acetogenic, and methanogenic archaea at temperatures typically between 35°C and 55°C, yielding biogas with methane concentrations of 50–70% by volume. The process serves primarily to stabilize organic waste streams, recover renewable energy, and produce digestate for agricultural nutrient recycling. Mesophilic technology occupies the largest share of operating European capacity due to lower energy demand and broader feedstock tolerance, whereas thermophilic systems command premium margins in wastewater treatment and food-industry applications where pathogen reduction requirements apply. Agricultural waste and manure together constitute the dominant feedstock base across Germany and France, while food waste streams are concentrating in urban off-site centralized facilities in the United Kingdom and Benelux countries.
The EU Green Deal, F-Gas Regulation, and national transpositions of the Renewable Energy Directive collectively mandate methane capture obligations and green gas injection targets that harden demand for certified digestion infrastructure. EMA and national environmental agencies in Germany, France, and Italy enforce emission monitoring protocols that shape equipment specification and operator compliance costs. Stakeholders must monitor evolving biomethane tariff structures and carbon-border adjustment mechanisms to calibrate investment timelines and technology selection.
Market Dynamics
Modular digester packaging is compressing project timelines across European agricultural and industrial deployments, as standardized reactor skids displace bespoke civil construction. This configuration shift is tightening equipment vendor margins while expanding addressable market reach to smaller-scale operators previously excluded by capital barriers.
Growth Catalysts
- EU Green Deal methane mandates:Binding emission reduction targets for municipal wastewater facilities in Germany, France, and Italy are accelerating biogas capture infrastructure procurement.
- F-Gas Regulation compliance:Tightened fluorinated gas controls are redirecting industrial refrigeration waste streams toward certified digestion pathways for thermal energy recovery.
- Denmark thermophilic clustering:Higher organic loading rate tolerance in Danish and Dutch installations justifies premium capital intensity for pathogen-critical food waste applications.
Market Restraints
- Digestate nitrogen management:Strict EU Nitrates Directive implementation in nitrate-vulnerable zones limits land application rates and raises disposal costs for German and French farm-scale operators.
- Biomethane grid injection standards:National gas quality specifications vary across member states, fragmenting equipment certification requirements and delaying project commissioning.
- Feedstock supply concentration:Agricultural manure availability concentrates in northern European dairy belts, leaving Mediterranean deployments dependent on transported organic waste with elevated logistics exposure.
Strategic Opportunities
- Carbon-border adjustment positioning:EU CBAM phase-in creates certified biomethane premium capture potential for industrial heat users seeking Scope 1 emission reductions.
- Italy agricultural biogas retrofit:Underpenetrated southern Italian provinces present conversion opportunities for existing manure storage infrastructure toward energy recovery.
- Power-to-X convergence:Electrolyzer integration with biogas upgrading trains enables renewable hydrogen and synthetic methane co-production at Benelux hub facilities.
Industry Challenges
- Process microbiology expertise:Acute shortages of anaerobic consortia management specialists delay commissioning and destabilize thermophilic system performance.
- Digestate valorization pathways:Nutrient recovery technology selection and product registration timelines extend project payback periods beyond agricultural lender risk appetites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anaerobic Digestion Market |
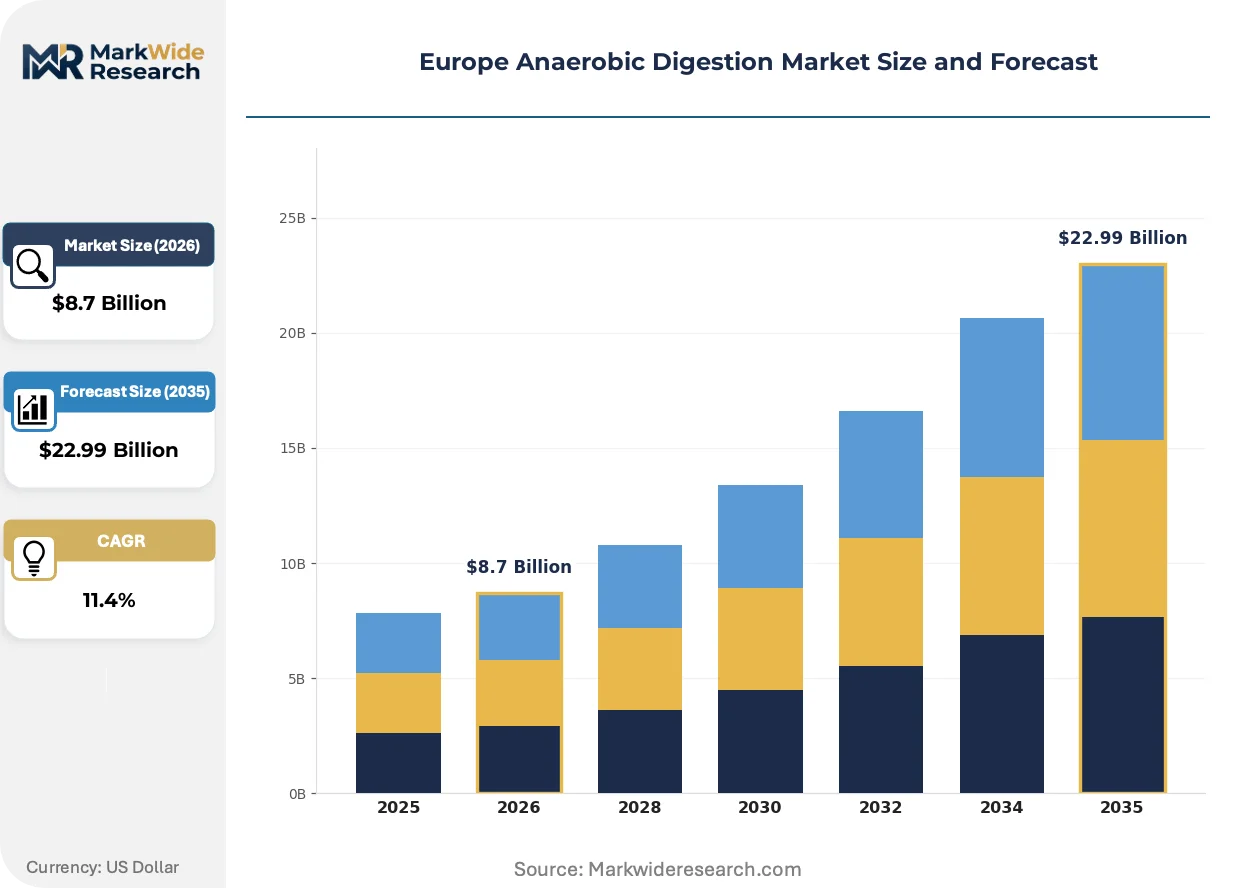
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mesophilic, Thermophilic, Hybrid, Batch Feedstock Type: Agricultural Waste, Food Waste, Manure, Energy Crops End User: Agriculture, Wastewater Treatment, Energy Producers, Food Industry Planning Type: On-site, Off-site, Centralized, Decentralized |
| Companies Covered | EnviTec Biogas, BTS Biogas, Weltec Biopower, PlanET Biogas, Agrikomp, Bioconstruct, Host Bioenergy Systems, Linde Engineering, Scandinavian Biogas Fuels, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anaerobic Digestion Market Emerging Trajectories
Containerized reactor deployment is reconfiguring competitive advantage toward manufacturing scale and logistics efficiency rather than civil engineering capability. Equipment vendors are repositioning around modular platform standardization.
High-solids thermophilic digestion is decentralizing organic waste processing economics by enabling smaller-footprint installations with reduced water demand. Food manufacturers in the Netherlands and Belgium are adopting these systems to handle concentrated production residues on-site. The technology is compressing viable project scale thresholds and drawing industrial waste streams away from centralized municipal facilities.
EU F-Gas Regulation phase-down schedules are tightening refrigerant containment requirements across cold chain logistics operators. This regulatory pressure is redirecting supermarket and distribution center waste heat and refrigeration condensate toward on-site biogas generation for thermal offset. German retail chains are retrofitting existing waste handling infrastructure to capture these compliance-driven energy recovery opportunities.
Long-term biogas offtake contracting is consolidating buyer power among utility-backed green gas aggregators. Agricultural and industrial producers in France and Germany are facing compressed negotiation leverage as procurement functions centralize within energy majors seeking certified biomethane volume commitments. This shift is visible in Rhineland-Palatinate and Brittany, where farm-scale operators now interface with structured purchasing desks rather than regional distribution utilities.
Europe Anaerobic Digestion Market Segmentation
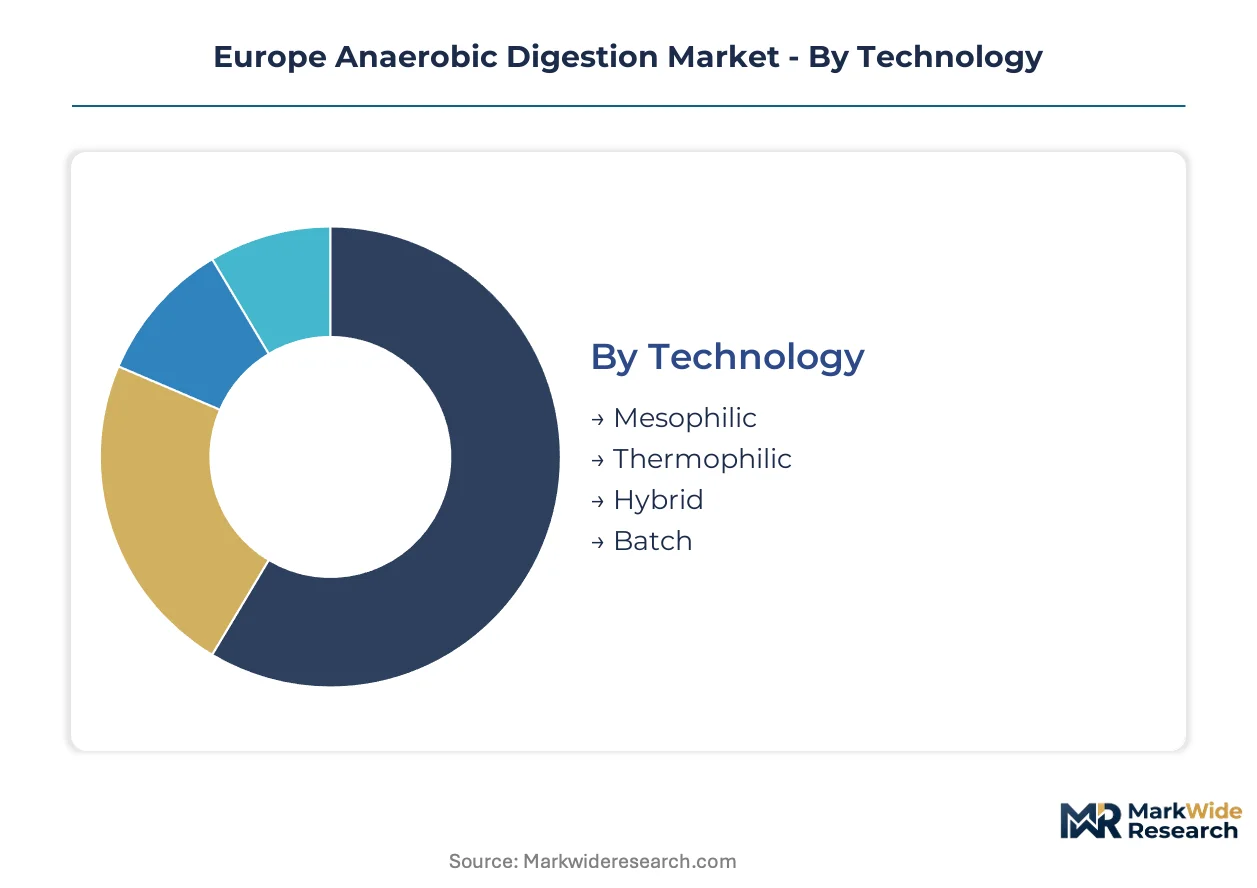
Segmentation in Europe's anaerobic digestion market reveals how regulatory certification burdens, feedstock logistics, and scale economics fragment equipment procurement patterns across member states. Technology selection and planning configuration determine which operators face EMA monitoring protocols versus national environmental agency oversight.
Technology:
Mesophilic systems carry lighter EMA certification burdens for standard agricultural deployments, while thermophilic and hybrid configurations trigger stricter pathogen-reduction validation under EU animal by-product regulations.
- Mesophilic:Operating at 35-40°C, these systems employ lower energy input and broader microbial consortia tolerance. Demand concentrates across German and French dairy operations where manure feedstock dominates and capital constraints favor proven reliability over performance optimization.
- Thermophilic:Sustained 50-55°C operation accelerates organic loading rates and ensures pathogen destruction mandated for food-industry residues. Dutch and Danish wastewater treatment facilities justify premium capital intensity through higher throughput per reactor volume and compliance with strict sanitation standards.
- Hybrid:Dual-temperature capability allows seasonal switching between mesophilic efficiency and thermophilic throughput. German industrial operators deploy these for variable food-waste streams with fluctuating contamination risk.
- Batch:Sequential loading without continuous flow suits small-scale Italian farm operations with intermittent manure availability and limited technical staffing.
Mesophilic sits at the top of the volume ranking, with thermophilic climbing the fastest.
Feedstock Type:
Feedstock selection dictates transport radius economics, contamination risk tiers, and whether operators qualify for agricultural or industrial waste handling permits under national transpositions of EU waste framework directives.
- Agricultural Waste:Crop residues and silage leachate from German and Polish grain operations supply high-cellulose substrates requiring longer retention times. Demand clusters in northern European arable belts with established collection logistics.
- Food Waste:Source-separated organic fractions from Benelux retail and hospitality chains deliver higher methane yields per tonne. UK urban off-site facilities concentrate processing capacity to capture supermarket compliance-driven diversion mandates.
- Manure:Dairy and swine slurry constitutes the dominant substrate across France, Germany, and Denmark with established on-farm infrastructure.
- Energy Crops:Dedicated maize and grass silage cultivation for biogas faces tightening sustainability criteria under revised Renewable Energy Directive implementations.
Manure commands the largest installed base, though food waste is expanding most quickly as separate collection infrastructure matures.
End User:
End-user category determines grid connection standards, with energy producers facing uniformified national biomethane injection specifications that fragment equipment certification across borders.
- Agriculture:Farm-scale operators in Brittany and Lower Saxony prioritize digestate nutrient return to closed-loop cropping systems. These installations face EU Nitrates Directive constraints on land application rates in designated vulnerable zones.
- Wastewater Treatment:Municipal facilities across Italy, France, and Germany deploy capture infrastructure to meet binding EU Green Deal methane reduction targets for sewage sludge processing.
- Energy Producers:Utility-backed green gas aggregators in Rhineland-Palatinate and northern France centralize procurement of certified biomethane volumes for grid injection.
- Food Industry:Dutch and Belgian manufacturers adopt high-solids thermophilic systems for on-site processing of concentrated production residues with pathogen concerns.
Agriculture retains the deepest installed footprint, while wastewater treatment is gaining share fastest under regulatory compliance pressure.
Planning Type:
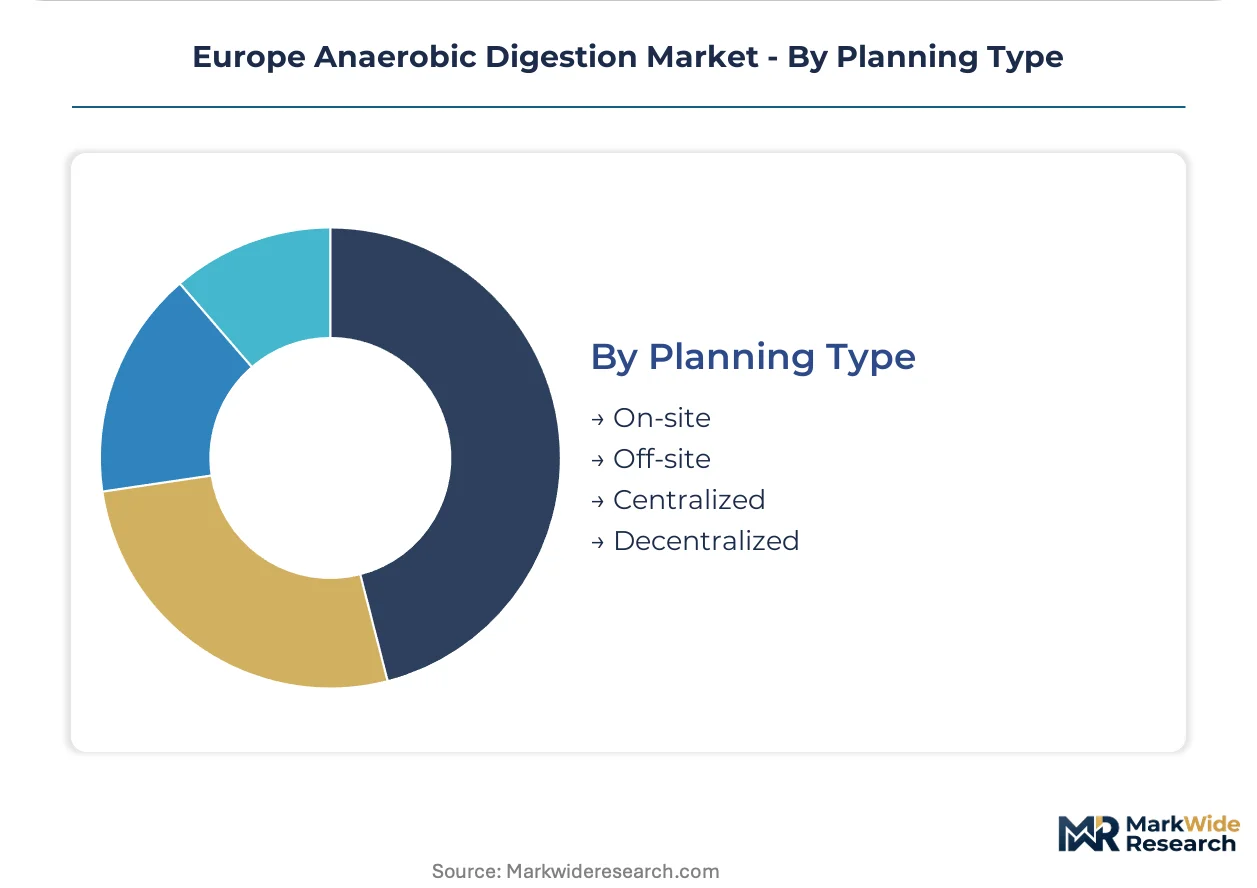
Planning configuration shapes capital deployment timelines, with centralized facilities requiring extended permitting under EU environmental impact assessment frameworks compared to containerized on-site alternatives.
- On-site:Integrated processing at point of generation eliminates transport costs for German dairy operations and Dutch food manufacturers with consistent waste streams and available land.
- Off-site:Third-party processing contracts suit smaller Italian agricultural holdings lacking technical capacity or sufficient scale for dedicated infrastructure investment.
- Centralized:Large-scale hub facilities in UK and Benelux urban corridors aggregate multiple food-waste streams for economies of scale in upgrading and grid injection.
- Decentralized:Modular containerized units across French and German agricultural regions reduce civil construction duration and expand addressable market to sub-megawatt operators.
On-site maintains volume leadership, with decentralized configurations showing the steepest expansion trajectory as standardized reactor skids compress project delivery timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anaerobic digestion infrastructure first achieved industrial scale in Germany during the 1990s Energiewende expansion, establishing the technical and regulatory templates that now propagate across the continent.
Germany
Dairy operations across Lower Saxony and Bavaria deploy mesophilic farm-scale digesters to process manure under the Renewable Energy Directive national transposition. The Federal Environment Agency enforces biogas capture standards at municipal wastewater facilities in the Ruhr industrial corridor.
France
Brittany's intensive livestock belt concentrates manure-to-energy installations facing EU Nitrates Directive land application constraints. ANSM and regional prefectures coordinate digestate management permits in nitrate-vulnerable zones across the northwestern agricultural heartland.
Italy
Southern provinces including Sicily and Calabria present underpenetrated retrofit opportunities for existing manure storage infrastructure. The Ministry of Environment implements EU Green Deal methane reduction mandates at municipal treatment plants in Lombardy and Emilia-Romagna.
Netherlands
Food manufacturers in the Rotterdam-Antwerp port cluster adopt high-solids thermophilic systems for concentrated production residues. The Dutch Human Environment and Transport Inspectorate enforces pathogen-reduction validation under EU animal by-product regulations.
Denmark
Thermophilic clustering dominates wastewater treatment and food-industry applications where higher organic loading rates justify capital intensity. The Danish Environmental Protection Agency certifies installations in the Copenhagen metropolitan region and Jutland dairy processing zones.
Europe Anaerobic Digestion Market Vendor Landscape
The competitive structure tilts toward equipment fabricators with manufacturing scale and modular platform standardization. German and Italian vendors anchor the mid-market with containerized reactor skids, while Nordic specialists command premium positioning in thermophilic system integration. Strategic moves concentrate on backward integration into membrane fabrication and geographic expansion through distributor partnerships in underpenetrated Mediterranean markets.
Within the modular equipment tier, EnviTec Biogas and PlanET Biogas exemplify standardized plug-and-play reactor configurations that compress on-site construction timelines. Weltec Biopower occupies a position among membrane-covered lagoon system fabricators. Scandinavian Biogas Fuels represents the thermophilic specialization archetype concentrated in Nordic wastewater and food-waste applications. These three anchors illustrate how competitive positioning fragments across manufacturing efficiency, lagoon system integration, and high-temperature process expertise.
| Leading Market Players |
|---|
| EnviTec Biogas |
| BTS Biogas |
| Weltec Biopower |
| PlanET Biogas |
| Agrikomp |
| Bioconstruct |
| Host Bioenergy Systems |
| Linde Engineering |
| Scandinavian Biogas Fuels |
| Others |
Supply Flow & Price Mechanics
Stainless steel reactor vessel costs originating from German and Italian fabrication hubs cascade through three distinct procurement tiers, with containerized skid packages commanding premium positioning against lagoon-based civil construction alternatives favored by French agricultural operators.
Pricing Analysis
Project-based EPC contracting anchored to long-term biomethane offtake agreements separates utility-backed aggregators from farm-scale operators lacking negotiation leverage. Price differentiation rests on certification grade for EU Green Deal compliance and membrane fabrication in-house versus outsourced. Pricing pressure stems from standardized reactor skid proliferation compressing equipment vendor margins. Agricultural cooperatives in Brittany and Lower Saxony exhibit acute price sensitivity, while Dutch food manufacturers prioritize pathogen-reduction validation over capital expenditure optimization.
Supply Chain Analysis
Single-source vulnerability sits with German membrane fabricators supplying lagoon cover systems across northern European dairy belts. Geographic supply concentration clusters in Germany, Denmark, and the Netherlands for thermophilic reactor components. Raw material dependencies encompass specialty-grade stainless steel, EPDM membrane sheeting, and precision biogas upgrading catalysts. Supply chain risk centers on regulatory restriction variability across national biomethane grid injection standards. Distribution runs through EPC contractor networks with established relationships to agricultural cooperatives and municipal wastewater authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southern Italian provinces present geographic-arbitrage potential against saturated German markets, with lower land costs and underpenetrated manure storage infrastructure offsetting elevated logistics exposure for equipment deployment.
For Market Incumbents: Cement manufacturing scale advantages through backward integration into membrane fabrication, insulating margin position against containerized skid commoditization. Prioritize certification investment for EU F-Gas Regulation compliance to defend positioning against emerging Polish and Romanian equipment vendors targeting price-sensitive Mediterranean deployments. Channel control through exclusive EPC partnerships in underpenetrated Sicilian and Calabrian agricultural zones reinforces territorial moats.
For New Entrants and Emerging Players: Small-scale Italian farm operations lacking technical staffing represent the most penetrable buyer archetype, with batch digester configurations suited to intermittent manure availability and limited capital access. Target decentralized modular deployments in French nitrate-vulnerable zones where digestate management constraints create urgency for integrated nutrient recovery solutions. Go-to-market execution through agricultural cooperative purchasing consortia bypasses direct competition with established German equipment vendors.
For Investors and Strategic Acquirers: Consolidation pressure builds where thermophilic process expertise concentrates among Nordic specialists with limited manufacturing scale. Long-term viability favors acquisition targets possessing hybrid temperature capability patents and established relationships with Dutch food-industry residue generators. Watch biomethane tariff restructuring announcements in Germany and France as inflection indicators for equipment procurement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Fabrication Backward Integration | German vendors capture margin from EPDM lagoon cover supply currently outsourced to specialty chemical producers. |
| Containerized Skid Standardization | Equipment vendors compress project delivery timelines from 18 months to 6 months for French dairy cooperatives. |
| Power-to-X Electrolyzer Integration | Benelux hub facilities co-produce renewable hydrogen alongside biomethane for industrial heat decarbonization. |
| Thermophilic Process Patent Licensing | Danish specialists monetize pathogen-reduction validation expertise for Dutch food waste applications. |
| Mediterranean Distributor Partnership Expansion | Mid-market German fabricators establish presence in underpenetrated southern Italian agricultural provinces. |
Methodological Framework
Bottom-up agricultural and wastewater treatment operator modeling reconciled against top-down equipment vendor shipment tracking forms the analytical core of this study. Primary interviews with biogas project developers, EPC contractors, municipal procurement officers, and agricultural cooperative managers combined with secondary validation against EU EMA certification databases, national environmental agency permitting records, and biomethane grid injection registries. Triangulation across these sources reconciles installed capacity estimates with manufacturer revenue disclosures.
Input-output matrices map feedstock availability, regulatory compliance costs, and technology selection patterns across the projection horizon. Segmentation dimensions encompass temperature regime, feedstock category, end-user vertical, and planning configuration. CAGRs derive from slope-logic analysis of historical deployment trajectories adjusted for EU Green Deal mandate acceleration effects. Industry-specific forecast inputs incorporate F-Gas Regulation phase-down schedules and evolving carbon-border adjustment mechanism certification requirements.
Underlying measurement precision varies by segment; wastewater treatment and utility-backed energy producer deployments carry tighter precision than fragmented Italian farm-scale installations. Forecasts reflect assumptions regarding regulatory enforcement consistency, biomethane tariff stability, and feedstock logistics infrastructure maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
Enzymatic Cleaning Market
Environmental Biotechnology
Bio-Detection Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Plastic-Eating Bacteria Market