
 Vietnam Biopesticides Market | 2026-2036
Vietnam Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Biopesticides Market Analytics
Agricultural input distribution through provincial cooperative unions is rewriting access patterns for biopesticide penetration across Vietnam's rice belts. Valent BioSciences LLC leverages its microbial fermentation expertise to anchor supply relationships with large-scale Mekong Delta farming collectives. Loc Troi Group sustains deep backward integration into domestic Bacillus thuringiensis production, controlling costs against imported microbial concentrates. Biotech Bio-Agriculture specializes in botanical extract formulations for high-value fruit exports, navigating phytosanitary barriers in European destination markets.
Biopesticides comprise naturally derived or microorganism-based crop protection agents formulated from living organisms, plant extracts, or naturally occurring biochemical compounds that disrupt pest physiology through modes distinct from synthetic chemicals. These agents typically require aqueous suspension or granular carrier systems and function through ingestion, infection, or growth regulation rather than direct neurotoxicity. Microbial biopesticides dominate current manufacturing output in Vietnam due to established fermentation infrastructure and lower registration barriers under national bio-input policies. Agricultural crop protection absorbs the majority of volume, while botanical formulations command premium positioning in export-oriented fruit and vegetable segments where residue thresholds are most stringent.
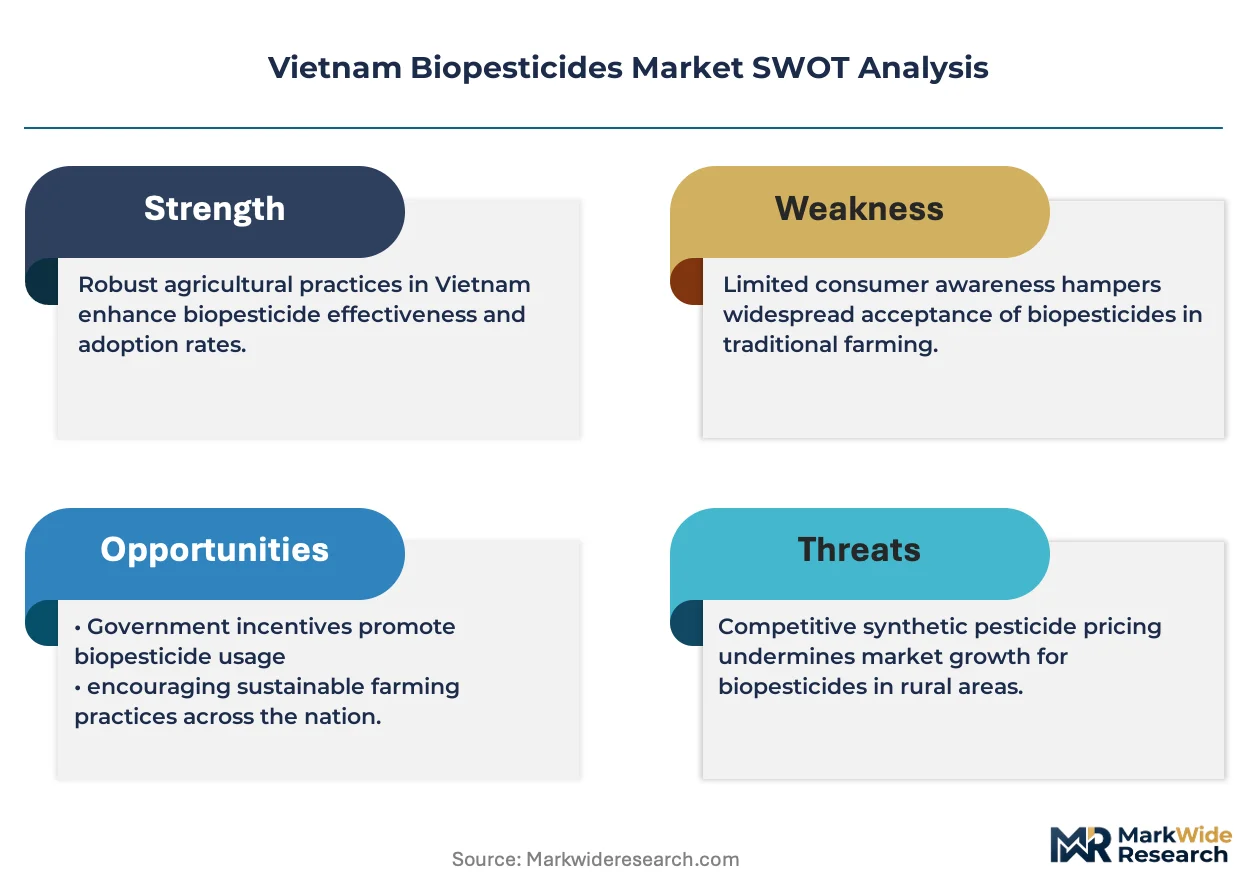
Vietnam's Ministry of Agriculture and Rural Development sets biopesticide registration and field efficacy standards, while the Plant Protection Department enforces residue monitoring for export-bound produce. The country's national green agriculture program tightens chemical pesticide reduction targets, forcing distributors to rebalance portfolios toward certified bio-inputs. Stakeholders must track evolving biopesticide equivalence protocols between Vietnam and its ASEAN trading partners to anticipate registration reciprocity shifts that could reshape competitive access.
Market Dynamics
Vietnam's biopesticide sector faces acute pressure from the Ministry of Agriculture and Rural Development's accelerated certification timelines, which compress product development cycles while EU residue standards for rice exports tighten compliance burdens on Mekong Delta cooperatives.
Growth Catalysts
- Green Agriculture Directives:Vietnam's national green agriculture program mandates chemical pesticide reduction targets, forcing distributors to rebalance portfolios toward certified bio-inputs and expanding addressable demand for microbial formulations.
- Rice Export Compliance:EU-bound Mekong Delta rice cooperatives face stringent residue thresholds, driving procurement shifts toward biopesticide protocols that satisfy phytosanitary barriers in European destination markets.
- Fermentation Infrastructure:Established domestic microbial fermentation capacity lowers manufacturing barriers for Bacillus thuringiensis and other bacterial concentrates, reducing import dependency for active ingredient supply.
Market Restraints
- Import Concentration Risk:Premium botanical extracts and specialized microbial strains remain concentrated among overseas suppliers, exposing formulators to currency volatility and shipping disruptions.
- Field Efficacy Variability:Biopesticide performance fluctuates with humidity, temperature, and application timing, creating adoption hesitation among risk-averse rice farmers accustomed to synthetic chemical reliability.
- Registration Timeline Friction:Vietnam's Plant Protection Department maintains multi-year field trial requirements for novel active ingredients, delaying commercialization of next-generation microbial strains.
Strategic Opportunities
- Red River Delta Vegetable Contracting:Domestic retail chains operating vegetable sourcing programs in northern Vietnam increasingly specify reduced chemical protocols, creating premium positioning for botanical biopesticide formulations.
- ASEAN Registration Reciprocity:Evolving equivalence protocols between Vietnam and neighboring ASEAN markets could streamline cross-border product registration, opening export channels for domestic manufacturers.
- Provincial Cooperative Distribution:Agricultural input distribution through provincial cooperative unions offers direct access to aggregated smallholder demand, bypassing fragmented traditional retail channels.
Industry Challenges
- Technical Field Support Gap:Biopesticide application requires precise timing and environmental monitoring that exceeds the training of conventional agrochemical extension services, creating adoption bottlenecks in remote rice-growing provinces.
- Legacy Synthetic Inventory:Distributor warehouses carry substantial synthetic chemical stockpiles with established farmer relationships, creating channel conflict and margin pressure during portfolio transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Biopesticides Market |
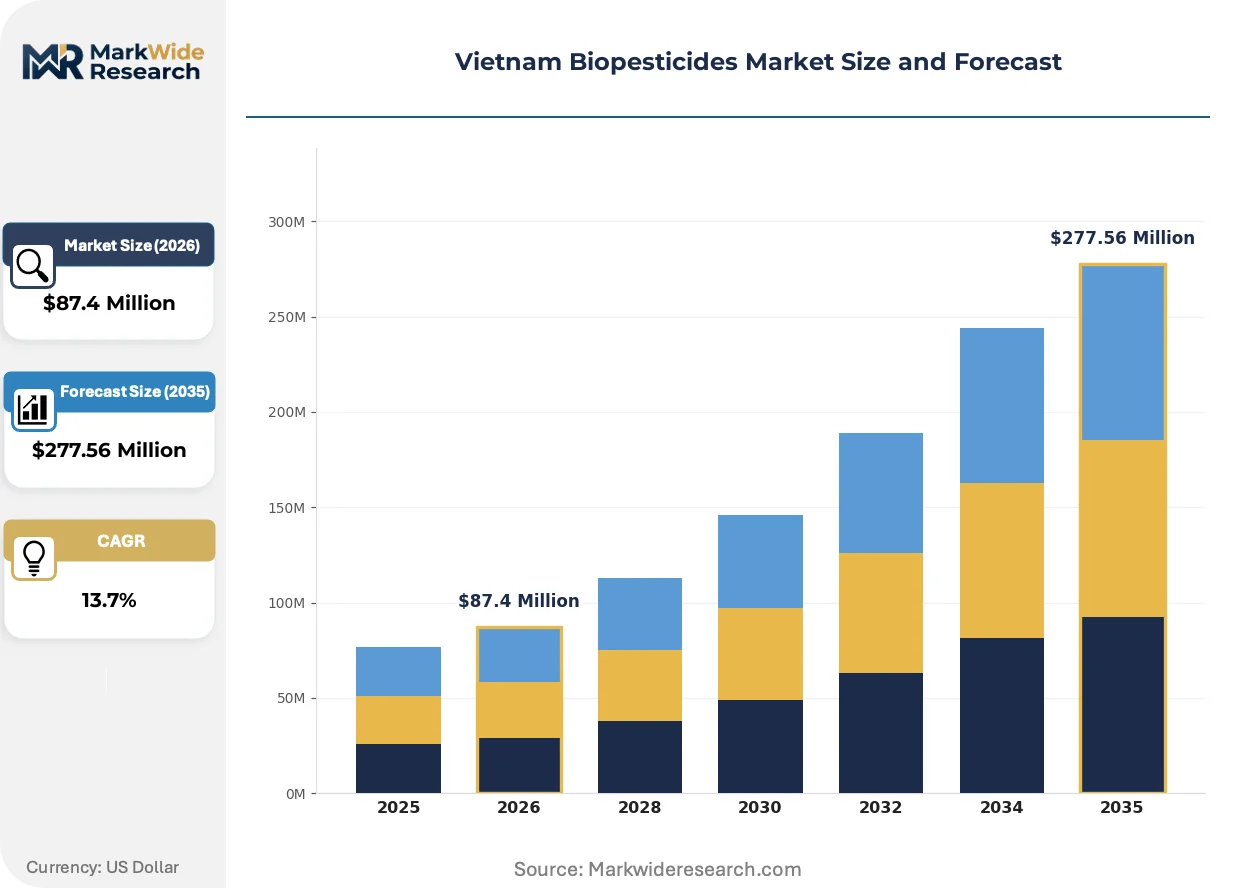
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $277.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Botanical, Biochemical, Plant-Incorporated Protectants Application: Agricultural Crop Protection, Turf and Ornamental, Forest Management, Food Storage End User: Farmers, Agricultural Cooperatives, Distributors, Research Institutions Distribution Channel: Retail Outlets, Online Platforms, Direct Sales, Export Markets |
| Companies Covered | Valent BioSciences LLC, Biotech Bio-Agriculture, Corteva Agriscience, Loc Troi Group, Vietnam Pesticide Joint Stock Company, Marrone Bio Innovations Inc., Vipesco, Hai Agrochem Joint Stock Company, UPL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Biopesticides Market Evolving Landscape
Digital agronomy platforms and precision application technologies are restructuring how Vietnamese farmers access biopesticide guidance, while regulatory pressure and export market requirements accelerate formulation sophistication.
Microbial consortia formulations combining multiple Bacillus species with fungal antagonists are virtualizing single-strain product architectures. Mekong Delta rice cooperatives pilot these combinations to broaden pest spectrum coverage and reduce application frequency. The technology is virtualizing traditional product category boundaries between bacterial and fungal biopesticides, forcing manufacturers to reconfigure R&D pipelines around synergistic strain compatibility rather than standalone active ingredient optimization.
Vietnam's Ministry of Agriculture and Rural Development has compressed bio-input certification timelines under national green agriculture directives, eliminating procedural delays that previously extended registration cycles. This regulatory acceleration pressures smaller domestic formulators to upgrade documentation capabilities and field trial infrastructure. Large-scale vegetable exporters in Lam Dong and Binh Thuan provinces respond by front-loading compliance investments to secure early-mover positioning in certified biopesticide sourcing.
Contract farming procurement for domestic retail chains now embeds biopesticide protocol specifications directly into grower agreements, displacing post-harvest residue testing as the primary compliance mechanism. Central retail banners including WinCommerce and Co.opmart enforce these upstream requirements through dedicated agronomist oversight. The Red River Delta exhibits the most pronounced behavioral shift, where vegetable cooperatives restructure input purchasing around retail-mandated reduced chemical lists rather than independent farmer preference.
Vietnam Biopesticides Market Segmentation
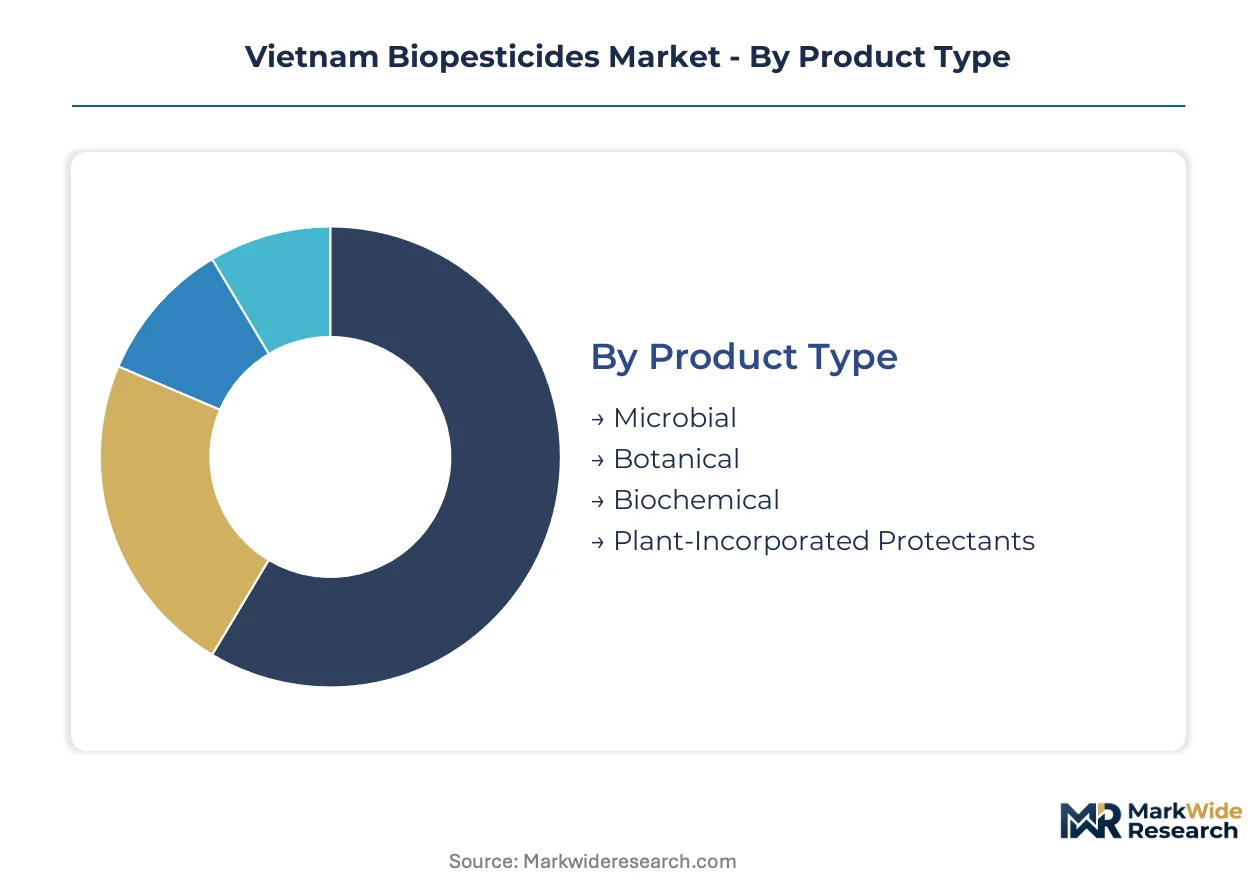
Segmentation reveals how Vietnam's biopesticide demand fragments across product technologies, application settings, and procurement channels. Each dimension exposes distinct margin profiles and technical service requirements that shape manufacturer go-to-market strategies.
Product Type:
After-sales technical support intensity varies sharply across product categories, with microbial formulations demanding sustained field guidance while biochemical products require minimal intervention.
- Microbial:Fermentation-derived bacterial and fungal agents including Bacillus thuringiensis dominate domestic manufacturing output. Mekong Delta rice cooperatives absorb the bulk of volume, driven by EU export residue compliance mandates and established provincial cooperative distribution networks.
- Botanical:Plant-extract formulations from neem, pyrethrum, and local herb species command premium positioning. Lam Dong and Binh Thuan vegetable exporters concentrate procurement here, navigating phytosanitary barriers in European destination markets where residue thresholds are most stringent.
- Biochemical:Naturally occurring compounds like pheromones and growth regulators disrupt pest physiology without direct toxicity. These agents suit high-value fruit orchards in the Central Highlands where application precision justifies specialized input costs.
- Plant-Incorporated Protectants:Genetically modified crops with built-in pest resistance traits. Research institutions and seed companies drive limited commercial activity pending regulatory clarity under Vietnam's biosafety framework.
By volume, Microbial leads. By growth pace, Botanical is ahead.
Application:
Cost tier stratification separates commodity rice protection from premium horticultural segments where input spending per hectare diverges by an order of magnitude.
- Agricultural Crop Protection:Field crops including rice, vegetables, and fruit orchards absorb the majority of biopesticide volume. Red River Delta vegetable contract farming for domestic retail chains specifies reduced chemical protocols, expanding addressable demand for certified bio-inputs.
- Turf and Ornamental:Golf courses and urban landscaping in Hanoi and Ho Chi Minh City generate concentrated demand for low-residue maintenance solutions. Municipal greening projects under national sustainability directives accelerate procurement shifts.
- Forest Management:Plantation forestry and watershed protection programs deploy biopesticides for invasive pest suppression. State forest enterprises in the Central Highlands and northern mountain provinces anchor public-sector demand.
- Food Storage:Post-harvest grain protection using microbial antagonists and botanical repellents. Mekong Delta rice milling cooperatives pilot these applications to replace chemical fumigants in export-bound shipments.
Agricultural Crop Protection captures the revenue base. Turf and Ornamental climbs the fastest as urban affluence expands.
End User:
Customer type determines procurement scale and technical sophistication requirements, from individual smallholders to aggregated cooperative purchasing.
- Farmers:Individual smallholders across Vietnam's rice belts and highland vegetable zones. Adoption hesitancy persists due to biopesticide performance variability with humidity and temperature fluctuations.
- Agricultural Cooperatives:Mekong Delta and Red River Delta farming collectives negotiate bulk procurement and shared technical extension. These entities increasingly embed biopesticide specifications into grower agreements under retail chain contracting programs.
- Distributors:Provincial cooperative unions and private agrochemical wholesalers rebalance portfolios toward certified bio-inputs. Legacy synthetic chemical inventory creates channel conflict during transition periods.
- Research Institutions:Universities and government agricultural stations conduct field efficacy trials and strain development. The Ministry of Agriculture and Rural Development relies on these partners for bio-input certification data.
Cooperative purchasing is expanding most quickly as aggregation overcomes fragmentation.
Distribution Channel:
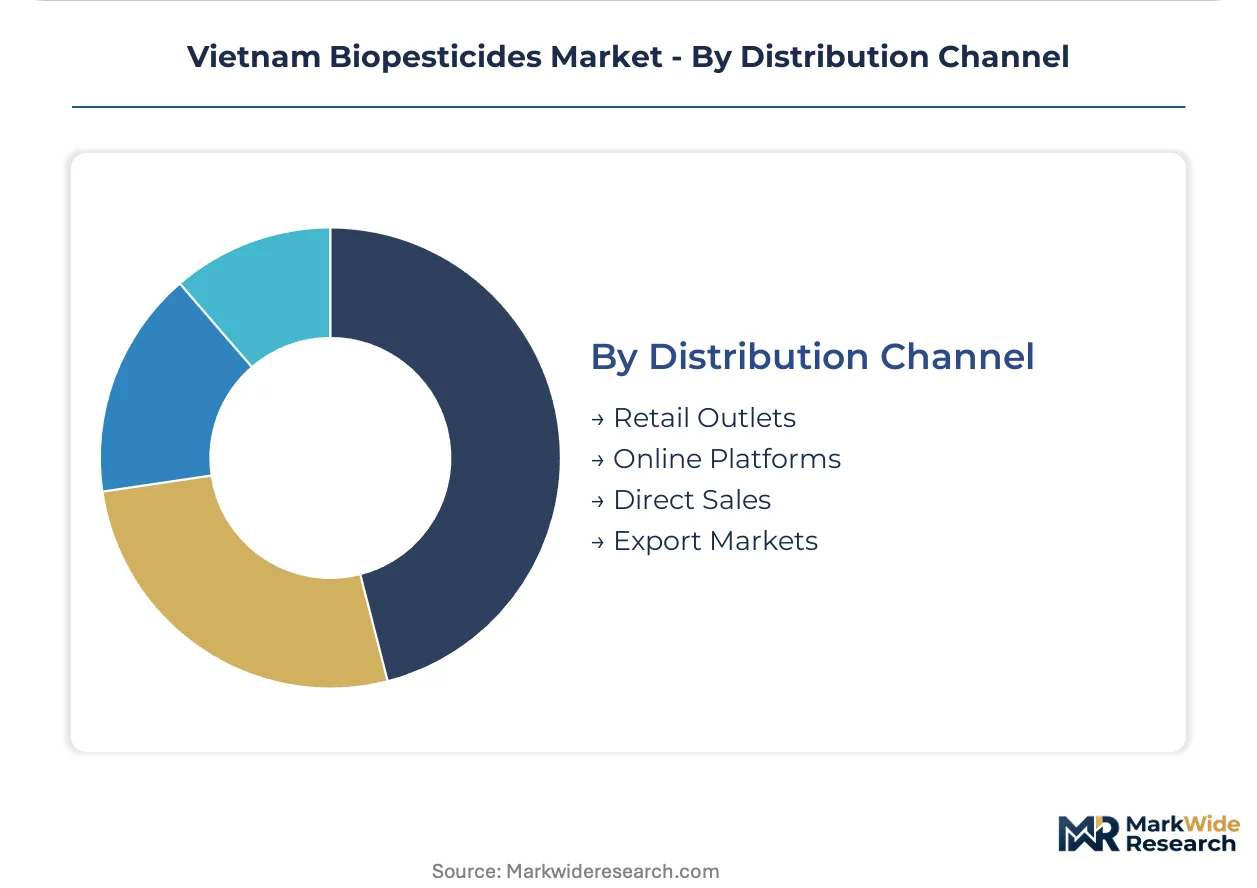
Supply concentration in provincial cooperative unions contrasts with emerging digital platforms that bypass traditional retail hierarchies.
- Retail Outlets:Provincial agricultural supply stores and district-level input shops. These channels carry substantial synthetic chemical stockpiles with established farmer relationships.
- Online Platforms:Digital agronomy platforms and e-commerce marketplaces connect manufacturers directly with end users. Precision application guidance bundled with product sales addresses the technical field support gap in remote provinces.
- Direct Sales:Large-scale formulators like Valent BioSciences LLC and Loc Troi Group maintain dedicated agronomist teams for Mekong Delta farming collectives. Relationship depth justifies bypassing distributor margins.
- Export Markets:Cross-border sales to neighboring ASEAN countries pending registration reciprocity agreements. Domestic manufacturers anticipate streamlined equivalence protocols to open regional channels.
Direct Sales commands the premium tier. Online Platforms gain share fastest as digital agronomy penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mekong Delta commands premium pricing power through EU export compliance premiums, while Red River Delta vegetable cooperatives absorb margin compression from domestic retail chain procurement mandates. This geographic asymmetry concentrates manufacturer technical service investments in southern rice belts while northern horticultural zones drive formulation innovation.
Mekong Delta
Rice farming cooperatives anchor regional demand through EU-bound export compliance requirements. Vietnam's Ministry of Agriculture and Rural Development accelerates bio-input certification timelines under green agriculture directives. Can Tho and An Giang provinces concentrate microbial fermentation capacity for Bacillus thuringiensis production.
Red River Delta
Vegetable contract farming for domestic retail chains mandates reduced chemical pesticide protocols. The Plant Protection Department enforces residue monitoring for produce bound for Hanoi and Hai Phong distribution centers. Bac Ninh and Hung Yen provinces cluster botanical formulation demand from high-value horticultural exporters.
Central Highlands
Coffee and fruit orchards generate concentrated demand for precision application biocontrol agents. National green agriculture program targets force input distributors to rebalance portfolios toward certified bio-inputs. Lam Dong and Dak Lak provinces host specialty botanical extract procurement for phytosanitary-compliant export shipments.
Southeast Region
Industrial vegetable zones around Ho Chi Minh City integrate biopesticide specifications into retail chain grower agreements. Provincial cooperative unions aggregate smallholder demand through centralized procurement platforms. Binh Duong and Dong Nai provinces concentrate direct sales agronomist teams from large-scale formulators.
North Central Coast
Expanding vegetable export zones drive adoption of microbial consortia formulations for broad-spectrum pest coverage. The Ministry of Agriculture and Rural Development relies on regional research stations for bio-input field efficacy data. Thanh Hoa and Nghe An provinces pilot digital agronomy platforms connecting manufacturers with remote farming communities.
Vietnam Biopesticides Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with strain development and fermentation capacity. The market structures around three tiers: multinational agricultural science conglomerates with microbial fermentation expertise, domestic integrated formulators with backward control over active ingredient supply, and specialized botanical extract houses serving export-oriented horticultural segments. Competitive moves concentrate on provincial cooperative distribution partnerships and compressed registration timeline compliance investments.
Within the domestic integrated tier, Loc Troi Group exemplifies backward integration into Bacillus thuringiensis production, while Valent BioSciences LLC represents multinational microbial fermentation platform deployment. Biotech Bio-Agriculture occupies a position among botanical formulation specialists navigating European phytosanitary barriers. These three archetypes anchor the competitive structure: domestic captives of active ingredient supply, global technology licensors, and export-compliance formulation houses.
| Leading Market Players |
|---|
| Valent BioSciences LLC |
| Biotech Bio-Agriculture |
| Corteva Agriscience |
| Loc Troi Group |
| Vietnam Pesticide Joint Stock Company |
| Marrone Bio Innovations Inc. |
| Vipesco |
| Hai Agrochem Joint Stock Company |
| UPL |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic Bacillus thuringiensis fermentation compresses supplier margins while amplifying pricing power for integrated formulators. The Ministry of Agriculture and Rural Development's accelerated certification timelines force smaller players to absorb compliance costs, widening spreads between captive producers and import-dependent competitors.
Pricing Analysis
The customization-premium spread separates standard microbial concentrates from consortia formulations tailored to Mekong Delta rice cooperatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales technical bundling. Cost compression in the standard tier intensifies as provincial cooperative unions aggregate volume and squeeze distributor margins. Smallholder farmers in remote northern provinces exhibit highest price sensitivity, while export-oriented vegetable cooperatives in Lam Dong prioritize residue compliance over input cost.
Supply Chain Analysis
Extended payment terms from provincial cooperative unions strain working capital for smaller formulators without supply-chain finance facilities. Active ingredient supply draws from China, India, and domestic fermentation facilities in Can Tho and An Giang provinces. Raw material dependencies include bacterial culture media, botanical feedstock from Central Highlands herb cultivation, and specialized packaging for aqueous suspensions. Single-source vulnerability concentrates in premium microbial strains held by multinational technology licensors. Distribution runs through provincial cooperative unions with emerging digital platform bypasses in remote provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vietnam biopesticides market operates as a substitution defense against resurgent synthetic chemical innovation and generic agrochemical price erosion. Incumbents must navigate this threat while consolidating fragmented cooperative procurement channels.
For Market Incumbents: Entrench backward integration into Bacillus thuringiensis fermentation to neutralize import cost volatility. Lock in exclusive agronomist deployment contracts with Mekong Delta rice cooperatives facing EU residue mandates. Prioritize certification pre-investment ahead of Ministry of Agriculture and Rural Development timeline compressions to freeze out undercapitalized competitors.
For New Entrants and Emerging Players: Establish a beachhead in Red River Delta vegetable contract farming where domestic retail chains mandate reduced chemical protocols. Target digital agronomy platform partnerships to bypass entrenched provincial cooperative distribution. Lead with botanical extract formulations for high-value fruit exports where phytosanitary barriers limit incumbent synthetic portfolios.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated formulators with captive fermentation capacity and multi-year cooperative supply agreements. The five-to-ten-year viability window favors acquisition targets with Plant Protection Department registration pipelines and Lam Dong province export relationships. Watch for ASEAN registration reciprocity announcements as inflection signals for cross-border manufacturing scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive Bacillus thuringiensis supply insulates Loc Troi Group from currency volatility in imported concentrates. |
| Provincial Cooperative Union Partnership | Direct agronomist deployment with Mekong Delta collectives secures volume commitments ahead of EU compliance deadlines. |
| Digital Agronomy Platform Launch | Precision application guidance bundled with biopesticide sales addresses technical support gaps in remote rice provinces. |
| Botanical Extract R&D Investment | Neem and pyrethrum formulation development captures premium positioning in Lam Dong vegetable export zones. |
| ASEAN Registration Reciprocity Pursuit | Equivalence protocol alignment with neighboring markets opens manufacturing export channels for domestic formulators. |
Research Methodology
A spread of perspectives from biopesticide formulators, provincial cooperative procurement managers, Plant Protection Department regulators, and Mekong Delta rice cooperative agronomists converged on the working assumptions. Primary interviews combined with secondary validation from Ministry of Agriculture and Rural Development certification databases, customs import records for microbial concentrates, and EU phytosanitary alert archives. Bottom-up cooperative procurement volume estimates triangulated against top-down green agriculture program target allocations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product technology tier, application crop type, end-user procurement scale, and provincial regulatory cluster intensity. CAGRs derived from fitted growth curves applied to cooperative penetration rates and retail chain contracting expansion trajectories. Forecast inputs incorporated EU residue standard evolution and domestic fermentation capacity utilization trajectories.
Stress conditions across EU export demand volatility, microbial strain registration delays, and provincial cooperative payment term extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about green agriculture directive enforcement continuity and ASEAN regulatory harmonization pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
Global Biofortification Market