
 Global Feed Phytogenics Market | 2026-2036
Global Feed Phytogenics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Phytogenics Market Analysis
Synthetic antibiotic growth promoters is decoupling from mainstream compound feed economics as residue-compliance costs mount. Cargill, Incorporated leverages its oilseed processing infrastructure to secure backward integration into essential-oil precursors. DSM-Firmenich AG anchors European demand through its premix network and precision-delivery formulations. Phytobiotics Futterzusatzstoffe GmbH specializes in species-specific blends for monogastric systems, competing on technical service depth rather than commodity volume.
Feed phytogenics comprise bioactive plant-derived compounds—principally terpenoids, phenolics, and alkaloids—extracted through steam distillation or solvent methods and standardized to minimum inhibitory concentrations against pathogenic gut flora. Their primary commercial purpose is to improve feed conversion efficiency and reduce enteric disease incidence in livestock without triggering antimicrobial resistance. Essential oils command the largest share of product-type revenue due to established supply chains from citrus and oregano cultivation, while oleoresins represent the fastest-expanding category as extraction yields improve. Among applications, poultry leads in absolute volume consumed, though aquaculture exhibits the steepest trajectory as shrimp and salmon producers face tightening export-certification standards for antibiotic residues.
The European Food Safety Authority and REACH frameworks govern residue limits and chemical safety dossiers for phytogenic imports into the EU, while the FDA and USDA jointly oversee GRAS self-affirmation pathways and label claims in the United States. China's Ministry of Agriculture and Rural Affairs maintains a positive-list system for feed additives that restricts unapproved plant extracts from commercial distribution. Stakeholders must monitor divergence between EU and US approval pathways for novel botanical actives, as asynchronous regulatory timelines will fragment product launch sequences and tie up capital in multi-jurisdiction dossier preparation.
Market Dynamics
Antibiotic residue thresholds under the EU Green Deal and F-Gas Regulation are compressing synthetic additive margins and redirecting formulation budgets toward botanical alternatives. This regulatory compression is restructuring procurement priorities across integrated poultry and aquaculture operations.
Growth Catalysts
- EU Green Deal residue mandates:Tightening thresholds for synthetic feed additives are forcing compound feed manufacturers to reformulate with phytogenic actives to maintain export certification.
- Shrimp aquaculture certification standards:East Asian export-oriented operations face antibiotic-free requirements from EU and North American buyers, accelerating gut-health alternative adoption.
- Steam distillation yield improvements:Advances in essential-oil extraction efficiency from citrus peel and oregano biomass are lowering unit costs for standardized terpenoid concentrates.
Market Restraints
- Raw material geographic concentration:Premium oregano and citrus essential-oil precursors concentrate in Mediterranean and Brazilian cultivation belts, exposing buyers to climate and currency volatility.
- REACH dossier preparation costs:Novel botanical actives require extensive chemical safety documentation for EU market entry, tying up capital for 18-36 months before commercialization.
- Synthetic acidifier price competition:Buffered organic acids maintain cost advantages in price-sensitive Southeast Asian broiler operations, limiting phytogenic penetration in undifferentiated commodity feed.
Strategic Opportunities
- Vietnam's antibiotic-free poultry expansion:Integrators in the Mekong Delta are retrofitting feed mills for phytogenic inclusion, creating first-mover advantages for technical-service-oriented suppliers.
- Precision-delivery formulation technology:Microencapsulation systems that protect terpenoids from rumen degradation open ruminant applications previously dominated by ionophores.
- China's positive-list feed additive system:Ministry of Agriculture and Rural Affairs approvals for novel plant extracts create regulated pathways for standardized oleoresin commercialization.
Industry Challenges
- Multi-jurisdiction dossier synchronization:Asynchronous approval timelines between EFSA and FDA pathways fragment product launch sequences and strain regulatory affairs staffing.
- Standardized minimum inhibitory concentration protocols:Lack of harmonized laboratory methods for botanical bioactivity measurement complicates quality assurance and customer specification alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Phytogenics Market |
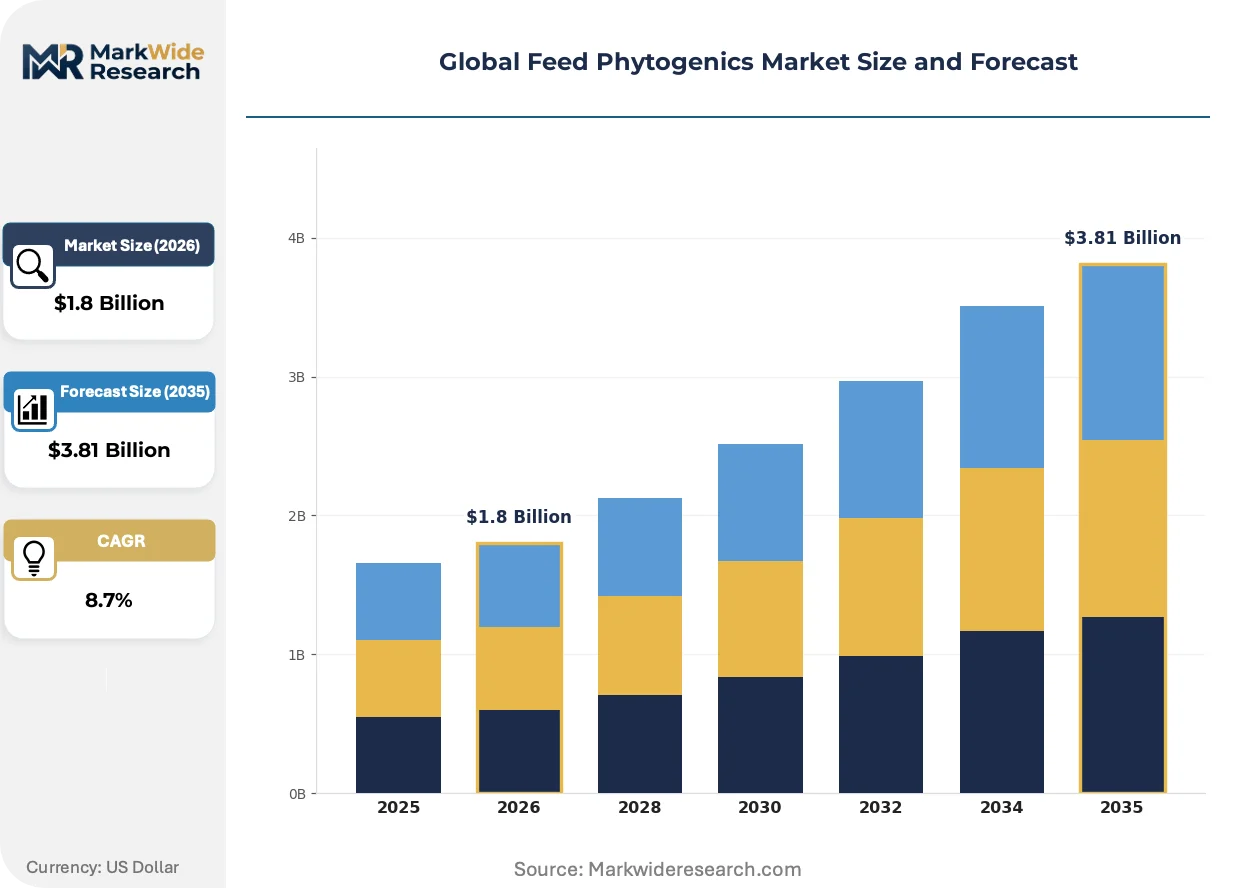
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Extracts, Spices, Oleoresins Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granule, Capsule End User: Farmers, Feed Manufacturers, Veterinary Clinics, Animal Breeders |
| Companies Covered | Cargill, Incorporated, Adisseo, DSM-Firmenich AG, IFF (Danisco Animal Nutrition), Archer Daniels Midland Company, Pancosma, Phytobiotics Futterzusatzstoffe GmbH, Alltech, Inc., Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Phytogenics Market Emerging Trajectories
Formulation science is converging with precision livestock monitoring to transform how bioactive plant compounds are dosed, tracked, and validated in commercial operations.
Microencapsulation technology using lipid matrices and spray-dried emulsions is electrifying the protection of volatile terpenoids through pelleting temperatures and rumen passage. Brazilian poultry integrators are retrofitting feed mills with inline addition systems for these heat-stable formulations. This capability is compressing the performance gap between phytogenics and synthetic growth promoters in high-throughput operations.
REACH and EU Green Deal frameworks are tightening chemical safety and residue documentation requirements for imported botanical feed additives. Dossier preparation costs now consume 12-18% of new product development budgets for European market entry. Premix manufacturers are responding by consolidating supplier relationships around established essential-oil processors with existing regulatory approvals.
Buyer procurement committees in East Asian aquaculture are unbundling feed additive specifications from compound feed contracts to source phytogenics directly from specialized suppliers. This disintermediation is visible in Vietnam's shrimp belt, where integrators now maintain separate approved vendor lists for gut-health actives independent of their feed mill relationships.
Global Feed Phytogenics Market Segmentation
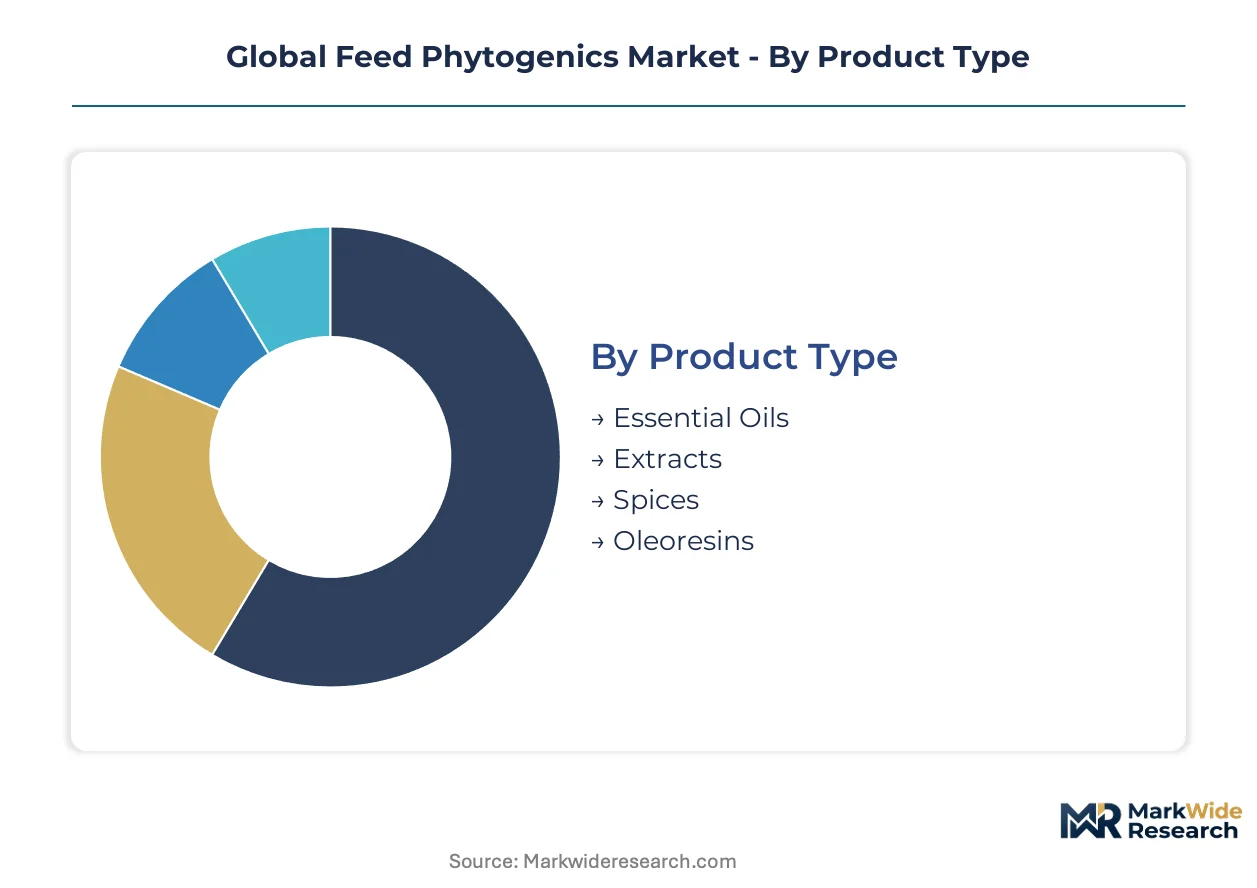
Feed phytogenics segmentation reveals how regulatory approval pathways and formulation requirements diverge across product categories. Certification burdens from EFSA, FDA, and China's Ministry of Agriculture and Rural Affairs reshape procurement priorities differently for each segment.
Product Type:
Essential oils and oleoresins face divergent REACH dossier requirements, with terpenoid concentrates demanding more extensive chemical safety documentation than spice-derived alkaloids.
- Essential Oils:Steam-distilled terpenoid concentrates from citrus peel and oregano biomass. Poultry integrators in Brazil absorb the largest volumes as antibiotic-free program adoption accelerates in São Paulo state.
- Extracts:Solvent-derived phenolic compounds requiring GRAS self-affirmation for US market entry. Feed manufacturers in Vietnam's Mekong Delta cluster specify these for shrimp aquaculture gut-health formulations.
- Spices:Ground or processed botanicals with simpler positive-list approvals in China. Farmers in India's Maharashtra belt source turmeric and ginger derivatives for backyard poultry operations.
- Oleoresins:Concentrated resin-oil suspensions gaining traction as extraction yields improve. Salmon producers in Norway deploy these for export-certification compliance with EU residue thresholds.
Essential oils sit at the top of the volume ranking, with oleoresins climbing the fastest.
Application:
Species-specific metabolism drives formulation differentiation, with monogastric systems tolerating higher terpenoid concentrations than ruminant digestive environments.
- Poultry:Broiler and layer operations dominate absolute consumption. Brazilian integrators retrofit feed mills with inline addition systems for heat-stable microencapsulated formulations.
- Swine:Post-weaning diarrhea control applications concentrate demand in Denmark and the Netherlands. EFSA residue mandates accelerate sow diet reformulation toward botanical actives.
- Ruminants:Rumen bypass requirements limit penetration to protected formulations. Precision-delivery technology from DSM-Firmenich AG opens dairy cattle applications previously blocked by terpenoid volatility.
- Aquaculture:Shrimp and salmon producers face the steepest certification pressure. Vietnam's export-oriented operations now maintain separate approved vendor lists for gut-health actives independent of compound feed contracts.
Poultry commands the largest absolute volume, though aquaculture expands most quickly under antibiotic-free export mandates.
Form:
Physical presentation determines heat stability through pelleting and storage shelf life, with powder and liquid formats splitting procurement between integrated mills and on-farm addition systems.
- Powder:Spray-dried emulsions dominate premix manufacturing. Cargill's oilseed processing infrastructure feeds captive supply chains for standardized powder production.
- Liquid:Bulk tank systems suit large feed mill operations. Phytobiotics Futterzusatzstoffe GmbH specializes in liquid terpenoid blends with species-specific technical service protocols.
- Granule:Extruded matrices protect actives through rumen passage. Ruminant applications in Germany and France drive adoption of lipid-matrix encapsulation.
- Capsule:Unit-dose formats target veterinary clinic dispensing and smallholder precision feeding. Animal breeders in Japan's Kagoshima prefecture specify capsules for Wagyu calf gut-health protocols.
Powder leads in manufacturing throughput, with granule gaining share fastest as ruminant applications unlock.
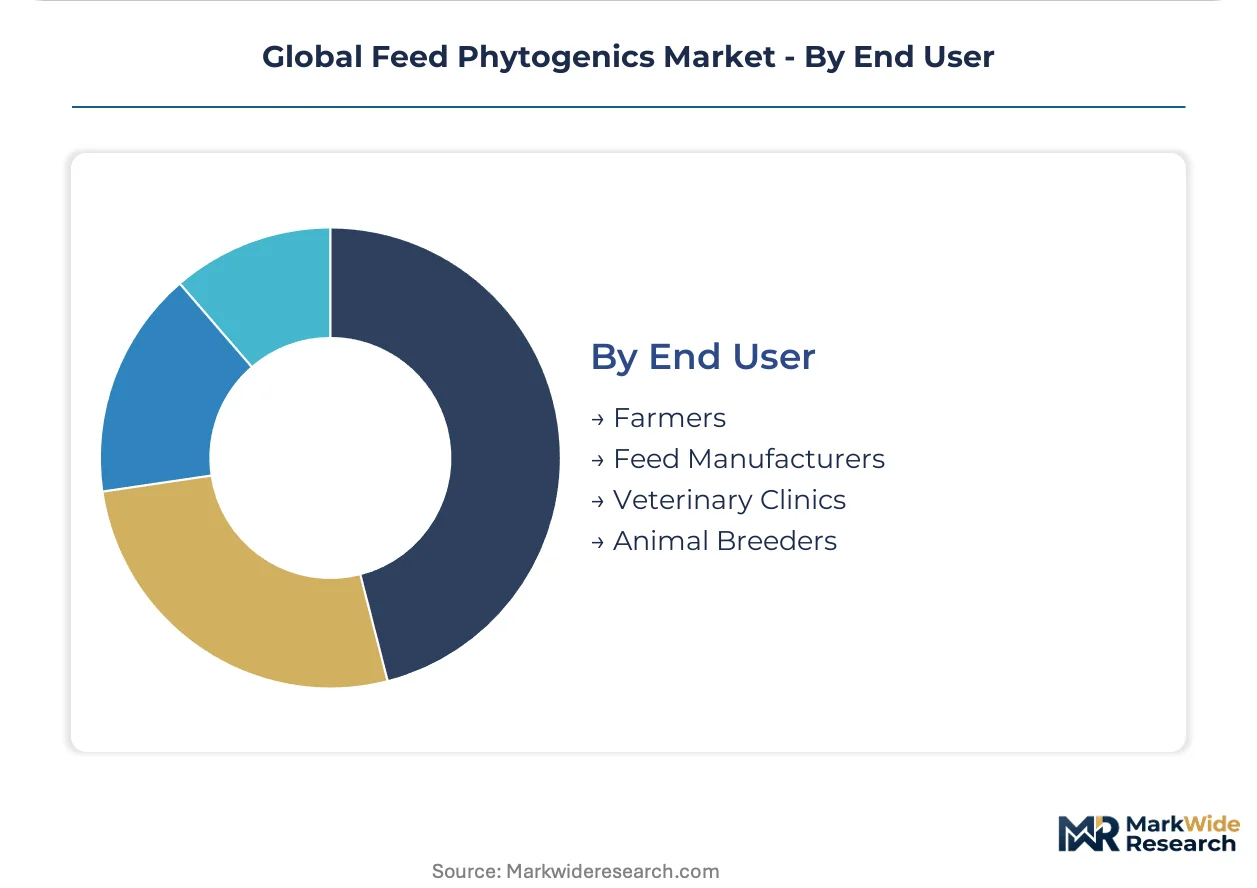
End User:
Procurement authority concentrates differently across value chain tiers, with feed manufacturers controlling specification decisions while farmers and breeders influence final inclusion rates through performance feedback.
- Farmers:Direct sourcing concentrates in Vietnam's Mekong Delta and Brazil's southern poultry belt. Disintermediation from compound feed contracts accelerates as technical knowledge diffuses.
- Feed Manufacturers:Premix networks in the EU and North America consolidate supplier relationships around established processors with existing regulatory approvals. Dossier preparation costs now consume substantial new product development budgets.
- Veterinary Clinics:Prescription and advisory roles dominate in Japan and South Korea. Capsule and precision-dose formats align with clinic-based distribution models.
- Animal Breeders:Genetic improvement operations in Denmark and the Netherlands specify phytogenics for gut-health trait selection in breeding stock.
Feed manufacturers retain the largest procurement volume, with farmers ascending fastest as technical capabilities spread to integrated operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's poultry integrators drive the largest absolute demand for phytogenic feed additives. The EU Green Deal and F-Gas Regulation are restructuring procurement priorities across export-oriented livestock operations worldwide.
Brazil
Antibiotic-free broiler programs in São Paulo and Paraná states absorb the largest essential oil volumes. ANVISA maintains residue monitoring protocols that align with EU export certification requirements. Feed mills in the southern poultry belt retrofit inline addition systems for heat-stable microencapsulated formulations.
United States
GRAS self-affirmation pathways accelerate novel botanical actives through commercialization pipelines. FDA and USDA joint oversight governs label claims and feed safety documentation. Cargill's oilseed processing infrastructure in the Midwest feeds captive supply chains for standardized terpenoid production.
Vietnam
Shrimp aquaculture exporters in the Mekong Delta face antibiotic-free mandates from EU and North American buyers. The Ministry of Agriculture and Rural Affairs implements positive-list restrictions on unapproved plant extracts. Integrators maintain separate approved vendor lists for gut-health actives independent of compound feed contracts.
Germany
EFSA chemical safety dossiers and REACH frameworks govern residue limits for imported botanical additives. Phytobiotics Futterzusatzstoffe GmbH anchors technical service depth for monogastric systems. Precision-delivery formulation networks in Bavaria and Lower Saxony consolidate around established processors with existing regulatory approvals.
China
Ministry of Agriculture and Rural Affairs positive-list approvals create regulated pathways for standardized oleoresin commercialization. Dual carbon goals compress synthetic additive margins in coastal livestock operations. Yangtze River Delta aquaculture clusters source gut-health alternatives to zinc oxide for export certification compliance.
Global Feed Phytogenics Market Vendor Landscape
Backward integration into essential-oil precursors dominates the current landscape as processors secure captive supply chains. The vendor base stratifies across three tiers: diversified agribusiness conglomerates with oilseed infrastructure, specialized phytogenic formulators with technical service capabilities, and regional essential-oil processors with cultivation relationships. Strategic archetypes include upstream-integrated suppliers controlling biomass sourcing, premix-network anchors with precision-delivery technology, and species-specific blend specialists competing on formulation depth rather than commodity volume. M&A activity and capacity expansion in extraction facilities represent the dominant competitive moves.
Within the upstream-integrated tier, Cargill, Incorporated exemplifies the agribusiness conglomerate archetype through its oilseed processing infrastructure. DSM-Firmenich AG occupies the premix-network anchor position with European precision-delivery capabilities. Phytobiotics Futterzusatzstoffe GmbH represents the specialized formulator archetype, competing on technical service protocols for monogastric systems rather than commodity scale.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Adisseo |
| DSM-Firmenich AG |
| IFF (Danisco Animal Nutrition) |
| Archer Daniels Midland Company |
| Pancosma |
| Phytobiotics Futterzusatzstoffe GmbH |
| Alltech, Inc. |
| Kemin Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EU-compliant phytogenic concentrates and commodity-grade botanical extracts manifests in divergent procurement economics and supply chain architectures. Premium terpenoid formulations command contracted offtake arrangements through established Mediterranean processors, while standard-grade spice derivatives flow through spot-market channels with volatile currency exposure.
Pricing Analysis
Input-cost pass-through from oregano and citrus biomass volatility anchors contract pricing for essential oil concentrates. Three-tier pricing structure across REACH-certified, GRAS-affirmed, and positive-list tiers reflects dossier preparation cost allocation and regulatory risk premiums. Pricing pressure stems from synthetic acidifier competition in Southeast Asian broiler markets. Price-sensitive buyers in undifferentiated commodity feed segments resist terpenoid premiums, while EU export-certified integrators absorb higher costs for residue compliance.
Supply Chain Analysis
Regional distribution centers in São Paulo, Ho Chi Minh City, and Rotterdam orchestrate hub-and-spoke patterns for heat-stable microencapsulated formulations. Mediterranean citrus peel processors and Brazilian oregano cultivators anchor upstream supply, with extraction yield improvements compressing unit costs. Single-source vulnerability concentrates in premium terpenoid precursors from specific cultivation belts. Distribution runs through premix manufacturer networks in the EU and North America, with direct sourcing accelerating among Vietnam's integrated shrimp operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where EU Green Deal compliance costs exceed Southeast Asian production economics, rewarding biomass sourcing and formulation capacity positioned for dual-market certification.
For Market Incumbents: Hedge regulatory asynchrony by maintaining parallel EFSA and FDA dossier pipelines, insulating launch sequences from approval timeline divergence. Backward integration into Brazilian and Mediterranean essential-oil precursors secures captive supply against climate volatility and currency swings. Capacity expansion in Vietnam's Mekong Delta captures antibiotic-free poultry program growth before local competitors consolidate technical service relationships. For New Entrants and Emerging Players: Direct-to-farmer digital platforms in Brazil's southern poultry belt bypass established premix networks, enabling disintermediated access to integrated operations with phytogenic inclusion expertise. White-space targets concentrate in precision-delivery ruminant formulations protected by lipid-matrix encapsulation, where DSM-Firmenich AG's incumbent position remains penetrable through species-specific technical protocols. China's positive-list approval pathway for novel oleoresins offers a regulated entry corridor with defined documentation requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH dossier costs exceed standalone processor margins, favoring acquisition of regional essential-oil operators with existing EU regulatory approvals. Long-term viability across the analysis window hinges on backward-integrated positioning that captures terpenoid standardization economics. The signal to watch is divergence between EFSA and FDA approval timelines for novel botanical actives, which will strain capital deployment for multi-jurisdiction entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Essential-Oil Precursors | Cargill's oilseed infrastructure secures captive terpenoid supply chains from Brazilian citrus biomass. |
| Precision-Delivery Formulation Technology | Microencapsulation systems from DSM-Firmenich AG unlock ruminant applications previously blocked by volatility. |
| REACH Dossier Consolidation | Premix manufacturers concentrate supplier relationships around established processors with existing EU approvals. |
| Direct Sourcing Platform Development | Vietnam's shrimp integrators now maintain separate vendor lists for gut-health actives independent of feed mills. |
| Positive-List Approval Navigation | China's Ministry of Agriculture and Rural Affairs creates regulated pathways for standardized oleoresin commercialization. |
Methodological Framework
Multiple input streams — primary interviews with feed formulators, regulatory affairs directors, and procurement leads at integrated poultry operations; secondary validation through EFSA safety opinions, FDA GRAS notifications, and customs trade data; plus bottom-up volume modeling reconciled against top-down market sizing — were synthesized to produce segmentation outputs.
Data-stream reconciliation across product-type, application, and form dimensions anchored the analytical framework over the projection horizon. Modeled segments included essential oils, oleoresins, extracts, and spices by species application, with ruminant bypass formulation technology treated as a distinct growth vector. CAGRs were derived from trajectory analysis of antibiotic-free program adoption rates and extraction yield improvement curves.
Regulatory approval delays, climate-driven biomass yield volatility, and synthetic acidifier price competition are the dominant revision risks that could compress or extend projected growth paths. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
China Biopesticides Market