
 Automated Microbiology Market | 2026-2036
Automated Microbiology Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Microbiology Market Analysis
Instrument leasing and reagent rental programs is reconfiguring capital deployment across the automated microbiology landscape, allowing mid-sized hospital laboratories to access high-throughput platforms without upfront equipment purchases. Danaher leverages its consumables-anchored business model to sustain recurring revenue streams across installed bases of automated culture systems. bioMérieux competes through specialized pathogen identification algorithms that differentiate its platform in European clinical networks. Thermo Fisher Scientific anchors broad geographic coverage through integrated supply chains spanning reagents, instruments, and informatics.
Automated microbiology encompasses instrumentation and software that execute specimen processing, incubation, detection, and identification of microbial organisms with minimal manual intervention, typically operating through robotic liquid handling, continuous monitoring sensors, and algorithm-driven colony recognition. These systems serve primarily to reduce turnaround time for clinical diagnostics and standardize reproducibility in high-volume testing environments. Among product categories, analyzers and identification systems command the largest installed base, while DNA sequencers represent the fastest-growing segment as laboratories adopt MALDI-TOF and next-generation sequencing for rapid species delineation. Clinical diagnostics applications generate the dominant revenue share, though food safety testing is expanding fastest among application areas due to regulatory mandates for pathogen surveillance in supply chains.
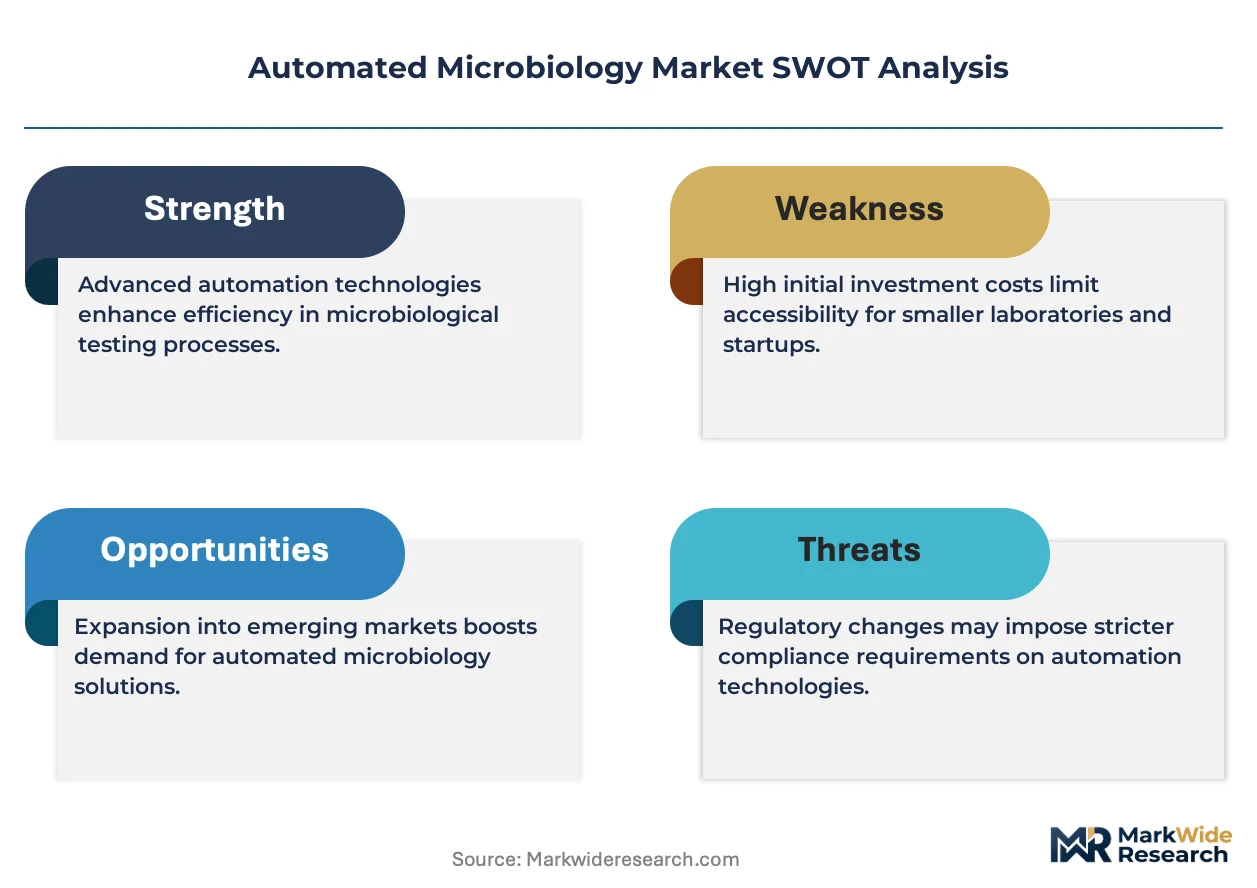
The FDA regulates automated microbiology devices as Class II or III medical products under 21 CFR requirements, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. ISO 15189 accreditation standards for medical laboratories further shape procurement criteria by mandating traceability and quality control protocols that favor validated automation platforms. Stakeholders must monitor evolving regulatory convergence between FDA and EMA expectations for antimicrobial resistance reporting features, as this will determine which instrument platforms gain preferred vendor status in integrated health systems.
Market Dynamics
Laboratory staffing shortages across clinical networks are forcing accelerated automation adoption, compressing capital deployment timelines from traditional five-year replacement cycles to immediate procurement decisions driven by walk-away system capabilities.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Stricter clinical evidence requirements for CE marking are filtering out non-validated platforms, concentrating procurement toward established automated systems with robust post-market surveillance infrastructure.
- Antimicrobial resistance surveillance mandates:Hospital-acquired infection tracking programs in Germany and the United States require rapid pathogen identification, pulling investment toward MALDI-TOF and continuous monitoring platforms.
- Food safety testing expansion:Supply chain pathogen surveillance regulations across processed food sectors are creating parallel demand streams outside clinical diagnostics, diversifying revenue bases for instrument manufacturers.
Market Restraints
- Consumables lock-in economics:Proprietary reagent cartridges and specialized culture media create captive supply arrangements that inflate lifetime ownership costs beyond initial instrument expenditure.
- Validation timeline compression:FDA 510(k) pathway requirements for antimicrobial susceptibility testing devices extend development cycles, delaying platform commercialization and freezing R&D allocation decisions.
- Technical interoperability gaps:Proprietary data formats between instrument manufacturers and laboratory information systems force costly middleware development or manual workflow interruptions.
Strategic Opportunities
- Mid-sized hospital laboratory penetration:Leasing and reagent rental programs are unlocking access for capital-constrained facilities in Spain and Italy previously excluded from high-throughput platform adoption.
- Next-generation sequencing convergence:Integration of MALDI-TOF with targeted NGS panels is creating hybrid identification workflows that compress species delineation from days to hours.
- ISO 15189 accreditation tailwinds:Medical laboratory quality standards mandating traceability and quality control protocols are favoring validated automation platforms over manual methods in competitive tenders.
Industry Challenges
- Specialized technician scarcity:Clinical microbiology training programs are producing insufficient personnel to operate and maintain complex automated platforms, forcing laboratories to outsource technical support.
- Legacy system integration friction:Existing laboratory information management architectures require expensive customization to accommodate real-time data streams from continuous monitoring sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Microbiology Market |
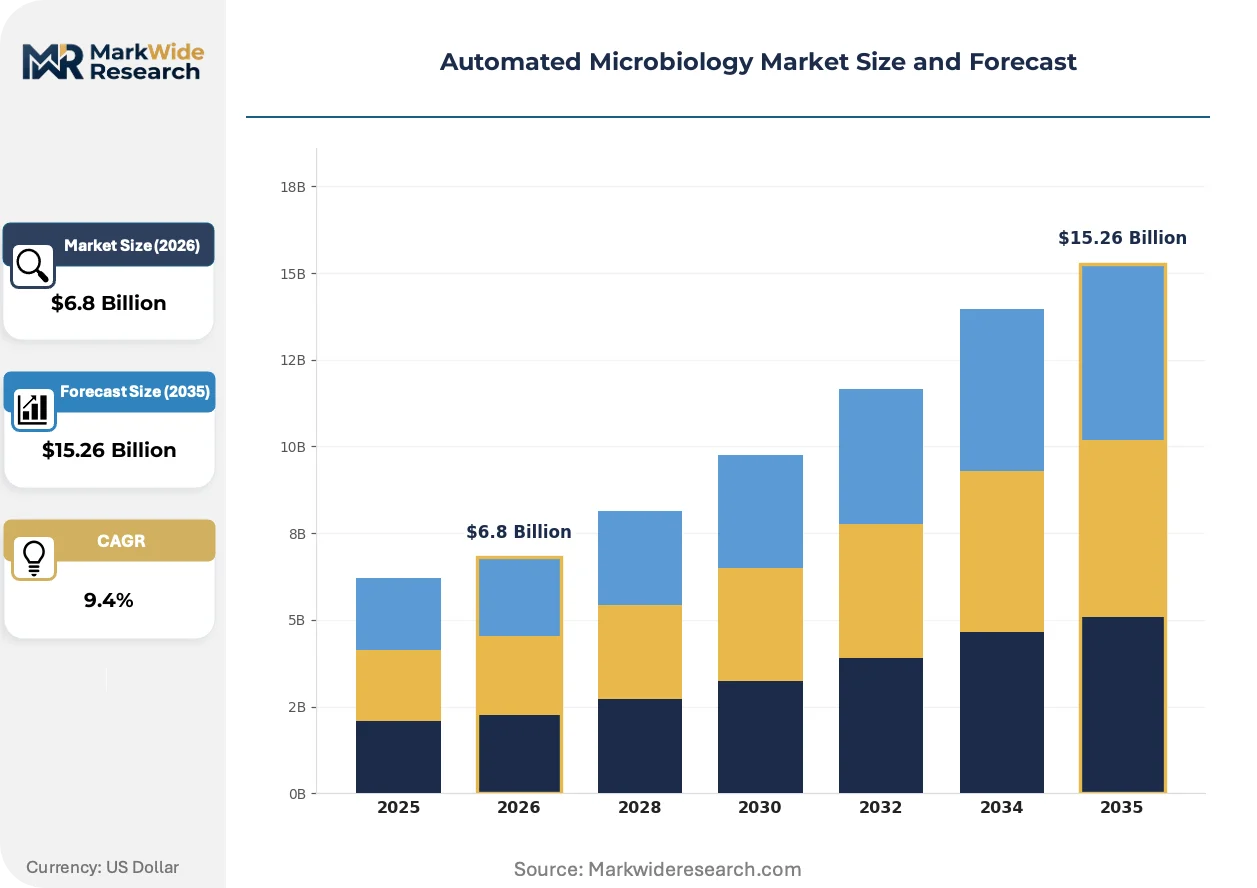
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Systems, Analyzers, DNA Sequencers, Identification Systems End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostics Centers Technology: Automation Software, Liquid Handling, PCR, Mass Spectrometry Application: Infectious Disease Testing, Food Safety Testing, Environmental Testing, Clinical Diagnostics |
| Companies Covered | Danaher, Bio-Rad Laboratories, Inc., Becton Dickinson and Company, Merck KGaA, Agilent Technologies, Inc., bioMérieux, QIAGEN, Abbott, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Microbiology Market Emerging Trajectories
Algorithm-driven colony recognition is displacing manual plate reading across high-volume clinical laboratories, compressing turnaround times while standardizing reproducibility in environments where technician availability cannot scale with testing demand.
Artificial intelligence classification engines are virtualizing the interpretive expertise of senior microbiologists, embedding pattern-recognition capabilities directly into automated culture systems. European clinical networks are deploying these platforms at accelerated pace, particularly in consolidated laboratory hubs serving multiple hospital sites. This virtualization is compressing the value chain between specimen acquisition and actionable result, eliminating traditional workflow bottlenecks at the interpretation stage.
The FDA's updated guidance on antimicrobial susceptibility testing devices is tightening performance validation thresholds, requiring manufacturers to demonstrate clinical correlation across expanded organism panels. Device developers must now allocate additional resources to prospective clinical studies, extending time-to-market for next-generation platforms. Automated system vendors with established 510(k) clearance pathways are consolidating preferred supplier status in integrated health systems.
Service unbundling is fragmenting traditional instrument-reagent-informatics packages, with purchasers negotiating standalone maintenance contracts and third-party reagent sourcing. Independent service organizations are capturing aftermarket revenue previously retained by original equipment manufacturers, particularly in Germany's dense network of clinical microbiology laboratories. This disintermediation is most visible among mid-sized facilities seeking operational flexibility over single-vendor dependency.
Automated Microbiology Market Segmentation
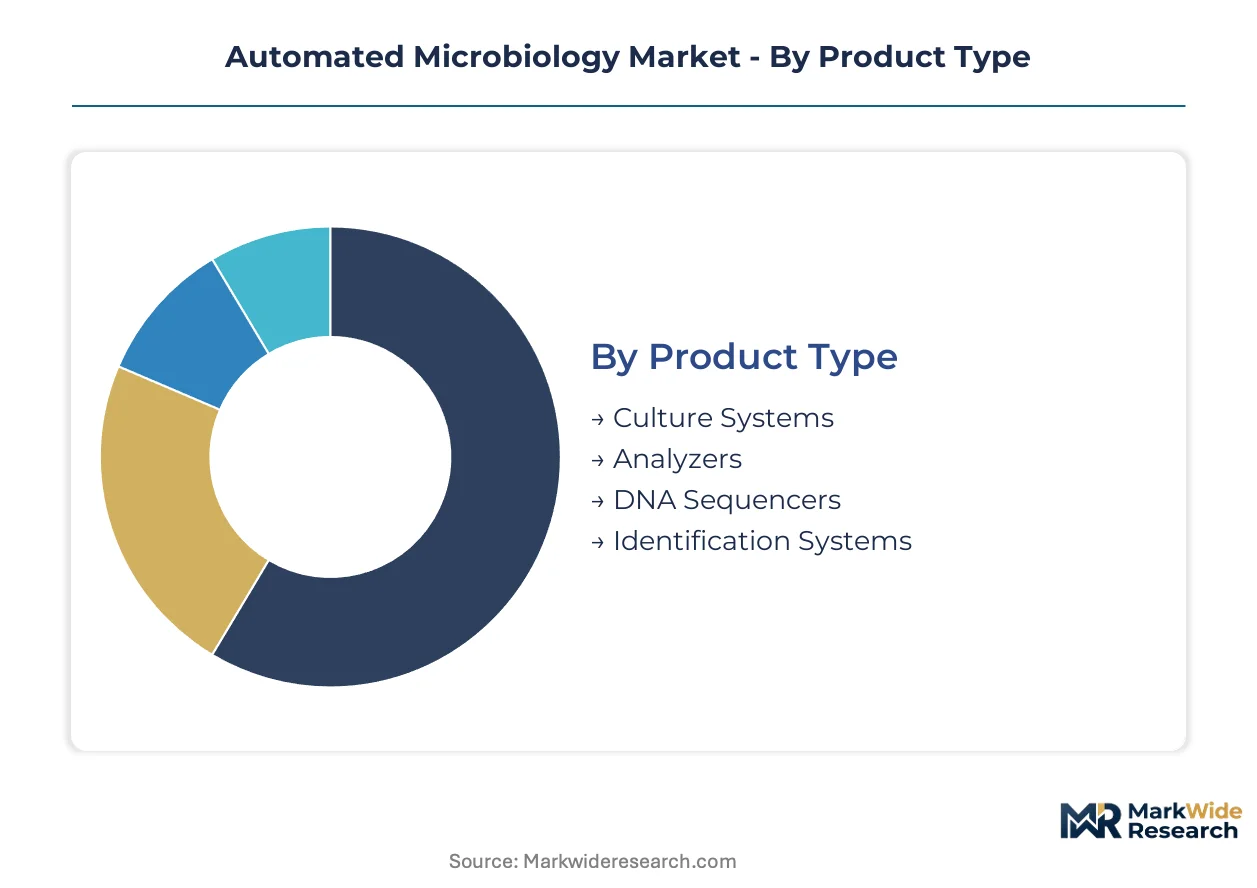
Automated microbiology systems fragment across four distinct classification axes, each revealing divergent procurement priorities and technology maturity curves. Product architecture separates legacy culture-based platforms from emerging molecular modalities, while end-user concentration in consolidated hospital networks reshapes vendor go-to-market strategies.
Product Type:
Mature incubation and detection hardware dominates installed bases, while emerging molecular platforms are capturing replacement cycles and greenfield expansion.
- Analyzers:Integrated specimen processing units combine robotic plate streaking, digital imaging, and algorithmic colony enumeration within single footprints. United States hospital laboratories prioritize these platforms to offset staffing shortages in high-throughput settings.
- Identification Systems:MALDI-TOF mass spectrometry platforms deliver species-level pathogen identification within minutes versus days for biochemical methods. German clinical networks deploy these systems to meet antimicrobial resistance surveillance mandates from the Robert Koch Institute.
- Culture Systems:Continuous monitoring incubators with automated growth detection sensors.
- DNA Sequencers:Next-generation sequencing platforms for resistance gene profiling and outbreak tracing.
Analyzers retain volume leadership; DNA Sequencers hold the steepest expansion curve.
End User:
Customer concentration follows diagnostic volume tiers, with high-test-throughput facilities commanding platform customization and dedicated field service.
- Clinical Laboratories:Hospital-affiliated and independent reference laboratories processing thousands of specimens daily. These facilities in Germany and the United States drive demand for walk-away automation to maintain turnaround time commitments amid technician scarcity.
- Pharmaceutical Companies:Quality control and clinical trial support operations requiring validated environmental monitoring and sterility testing. Manufacturing sites prioritize 21 CFR Part 11 compliant platforms with audit trail capabilities for FDA inspection readiness.
- Diagnostics Centers:Specialized outpatient facilities focused on rapid infectious disease screening.
- Research Institutions:Academic medical centers and public health laboratories developing novel detection methods.
Clinical Laboratories anchor procurement volume; Pharmaceutical Companies are expanding most quickly as manufacturing quality mandates tighten.
Technology:
Software and liquid handling infrastructure constitute mature automation layers, while mass spectrometry represents the frontier of identification speed.
- Mass Spectrometry:MALDI-TOF systems ionize microbial proteins for spectral fingerprint matching against curated databases. European laboratories favor these platforms for their minimal sample preparation and broad species coverage without nucleic acid extraction.
- Liquid Handling:Robotic pipetting workstations executing precise reagent dispensing and sample transfer. These systems form the backbone of automated culture preparation in high-volume United States reference laboratories seeking to eliminate manual pipetting errors.
- Automation Software:Middleware connecting instruments to laboratory information systems and quality control databases.
- PCR:Thermal cycling platforms for nucleic acid amplification in targeted pathogen detection.
Liquid Handling sustains the broadest installed base; Mass Spectrometry is gaining share fastest as species identification timelines compress.
Application:
Diagnostic urgency separates clinical from non-clinical use cases, with regulatory stringency varying sharply across verticals.
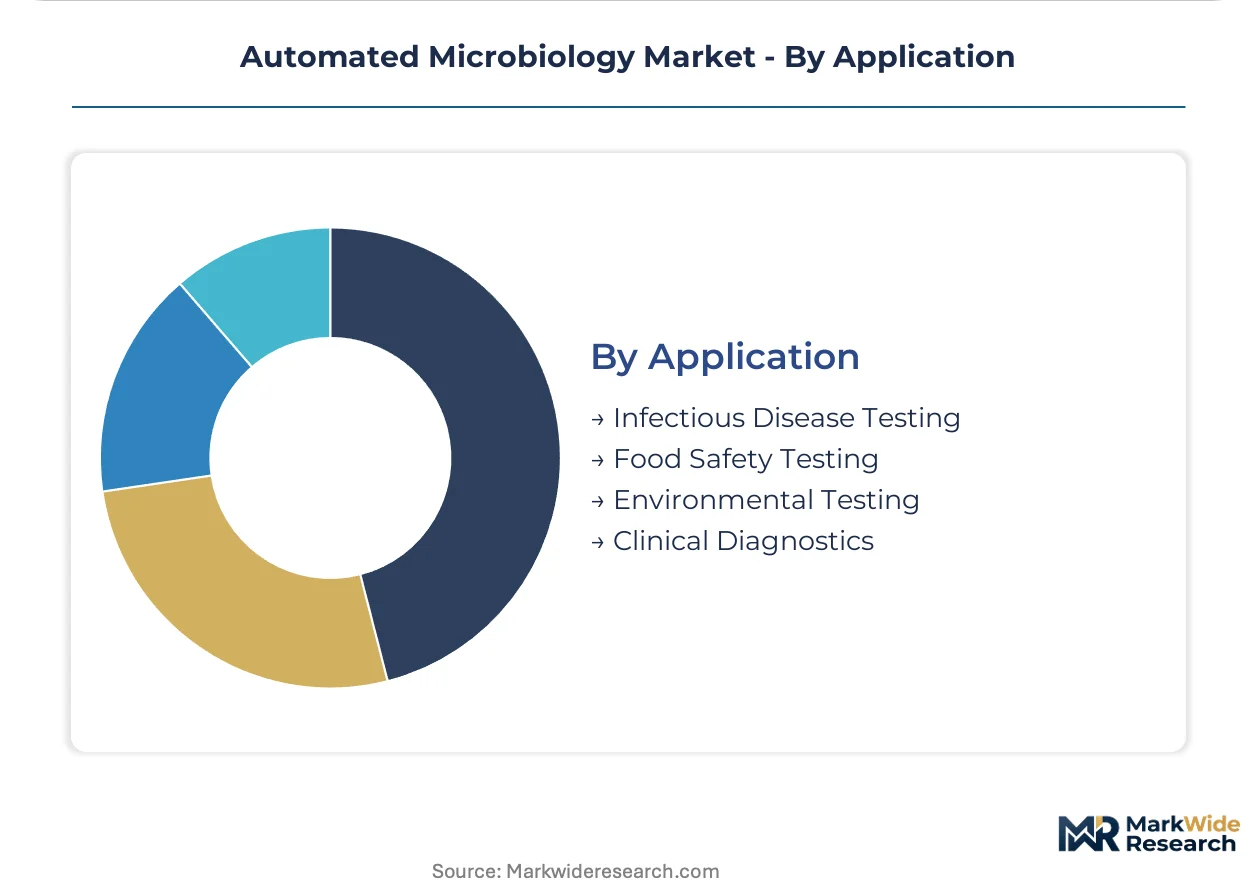
- Clinical Diagnostics:Blood culture, sterile site, and respiratory specimen processing for patient care decisions. United States health systems prioritize these applications to reduce hospital-acquired infection mortality and support antimicrobial stewardship programs.
- Food Safety Testing:Pathogen surveillance across meat, dairy, and ready-to-eat product supply chains. Processed food manufacturers in Germany deploy automated platforms to satisfy EU Regulation 2073/2005 microbiological criteria for Listeria and Salmonella.
- Infectious Disease Testing:Specialized tuberculosis, fungal, and mycobacterial detection workflows.
- Environmental Testing:Pharmaceutical cleanroom and water system monitoring for viable contamination.
Clinical Diagnostics commands the dominant revenue position; Food Safety Testing is climbing the fastest as supply chain traceability mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in automated microbiology systems tilt toward net-importing clinical laboratory networks in Europe and North America, while component manufacturing concentrates in German precision engineering clusters and United States reagent production hubs. Currency-adjusted procurement costs are diverging sharply across these markets as regulatory validation timelines extend.
United States
Hospital consolidation into integrated delivery networks is compressing vendor negotiation cycles for walk-away automation platforms. FDA 510(k) pathway requirements for antimicrobial susceptibility testing devices are extending validation timelines, freezing procurement decisions at mid-sized facilities. The Boston-Cambridge corridor anchors reagent manufacturing concentration, with specialized culture media production scaling to serve national reference laboratory chains.
Germany
Robert Koch Institute surveillance mandates for hospital-acquired infections are pulling investment toward MALDI-TOF mass spectrometry platforms in clinical microbiology laboratories. EU In Vitro Diagnostic Regulation clinical evidence requirements are filtering procurement toward established vendors with post-market surveillance infrastructure. The Rhine-Ruhr metropolitan region hosts dense clusters of automated system integration facilities serving consolidated laboratory hubs across North Rhine-Westphalia.
France
ANSM oversight of in vitro diagnostic device performance is tightening quality management system audits for automated platform vendors. Hospital automation procurement is accelerating in the Île-de-France region as staffing shortages intensify in Paris-affiliated clinical laboratories. The Lyon biocluster anchors specialized pathogen identification algorithm development, with academic-industry partnerships transferring diagnostic innovations into commercial platforms.
United Kingdom
NHS England diagnostic transformation programs are consolidating microbiology testing into regional hub laboratories, concentrating capital equipment procurement decisions. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines, creating parallel validation requirements for automated system manufacturers. The Cambridge-Oxford-London triangle maintains research instrumentation demand, with university hospitals piloting next-generation sequencing convergence workflows for outbreak tracing.
Japan
PMDA marketing authorization requirements for automated culture systems are mandating local clinical performance studies, extending market entry timelines for foreign manufacturers. Hospital laboratory staffing demographics are accelerating automation adoption in the Kanto region's aging technician workforce. Osaka-based precision engineering suppliers are capturing component contracts for robotic liquid handling modules serving domestic instrument assemblers.
Automated Microbiology Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagents, sensors, and liquid handling modules. The vendor base stratifies into three tiers: multinational conglomerates with full-stack portfolios, mid-sized specialists in identification technologies, and regional system integrators serving national laboratory networks. Competitive positioning hinges on consumables-anchored recurring revenue models versus instrument-centric capital sales. Consolidation pressure is intensifying through strategic partnerships between mass spectrometry specialists and automated culture system manufacturers.
Among diversified life science conglomerates, Danaher and Thermo Fisher Scientific occupy positions defined by integrated supply chains spanning reagents, instruments, and informatics. bioMérieux represents the specialized identification technology archetype, with algorithm-driven pathogen recognition capabilities differentiating its platform in European clinical networks. These three entities exemplify contrasting strategic postures: consumables-anchored recurring revenue, broad geographic coverage, and specialized diagnostic algorithms respectively.
| Leading Market Players |
|---|
| Danaher |
| Bio-Rad Laboratories, Inc. |
| Becton Dickinson and Company |
| Merck KGaA |
| Agilent Technologies, Inc. |
| bioMérieux |
| QIAGEN |
| Abbott |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
The Boston-Cambridge reagent manufacturing corridor concentrates specialized culture media production capacity, feeding downstream pricing power to instrument manufacturers who bundle consumables-anchored contracts with automated platform deployments.
Pricing Analysis
Industrial OEM buyers anchor consumables-locked pricing structures across automated microbiology platforms. Three-tier pricing stratifies across premium MALDI-TOF systems, standard continuous monitoring incubators, and economy-grade liquid handling modules, with differentiation resting on FDA 510(k) clearance tier and ISO 15189 validation depth. Pricing pressure stems from mid-sized hospital laboratories negotiating unbundled service contracts to escape proprietary reagent captivity. Reference laboratories exhibit lowest price sensitivity due to turnaround-time guarantees, while diagnostics centers face acute cost compression.
Supply Chain Analysis
Export-control restrictions on precision robotic components limit flows from German engineering clusters to non-allied markets, reshaping supplier geography. Manufacturing concentrates in Germany, the United States, and Japan, with reagent production drawing from Boston-Cambridge biotech corridors and Osaka precision machining hubs. Supply chains rest on rare-earth magnets for robotic actuators, specialized optical sensors for colony imaging, and proprietary culture media formulations. Single-source vulnerability concentrates in MALDI-TOF laser component sourcing. Distribution runs through consolidated hospital procurement networks and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of trained clinical microbiology technicians capable of operating complex automated platforms is compressing laboratory operational capacity, creating asymmetric value capture for vendors who virtualize interpretive expertise through embedded AI classification engines.
For Market Incumbents: Insulate installed-base revenue by deepening consumables-anchored contracts before service unbundling accelerates. Counter independent service organization encroachment through predictive maintenance software integration. Prioritize backward integration into specialized culture media production to defend margin position against third-party reagent sourcing.
For New Entrants and Emerging Players: Establish a beachhead in food safety testing applications, where regulatory mandates for supply chain pathogen surveillance outpace incumbent platform customization. Target processed food manufacturers in Spain and Italy with leasing programs that bypass capital-constrained procurement committees. Lead with MALDI-TOF integration partnerships rather than full-stack platform development.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with consumables-anchored business models and installed bases exceeding one thousand analyzers. Long-term viability favors platforms with FDA 510(k) clearance pathways already validated for antimicrobial susceptibility testing. Watch for inflection when EU In Vitro Diagnostic Regulation post-market surveillance obligations trigger vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU In Vitro Diagnostic Regulation compliance secures access to German clinical laboratory procurement. |
| Hospital System Partnership | Integrated delivery network contracts in the United States compress competitor access to high-volume reference laboratories. |
| Software Companion Development | AI-driven colony recognition algorithms differentiate platforms amid technician scarcity in European hubs. |
| Reimbursement Strategy | Antimicrobial stewardship program alignment accelerates hospital capital committee approval cycles. |
| Regulatory Approval Pathway | FDA 510(k) clearance for expanded organism panels defends preferred vendor status in consolidated networks. |
Methodological Framework
A spread of perspectives from hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and ISO 15189 accreditation records. Bottom-up instrument shipment tracking triangulated with top-down reagent consumption estimates across the analysis window.
Demand-supply balance modeling anchored forecast outputs, with segmentation across product architecture, end-user concentration, technology modality, and application vertical. CAGRs derived from logistic diffusion curves fitted to replacement cycle compression and greenfield adoption patterns. Inputs incorporated antimicrobial resistance surveillance mandate expansion, laboratory consolidation timelines, and food safety regulatory enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or reagent raw material costs would shift the trajectory. Forecasts embed assumptions about regulatory timeline convergence and technician training program output. Cross-checking against CMS Medicare laboratory spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Microbial Rennet Market