
 Silage Inoculant and Enzyme Market | 2026-2036
Silage Inoculant and Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Silage Inoculant and Enzyme Market Analytics
Asset-light leasing models for fermentation monitoring equipment are tilting competitive dynamics toward smaller feed additive suppliers. Lallemand leverages its yeast and bacteria strain libraries to sustain R&D intensity across multiple geographies. Chr. Hansen anchors its position through specialized microbial screening capabilities that dominate high-performance inoculant tiers. Cargill competes via backward integration into enzyme manufacturing and captive distribution networks serving agricultural cooperatives.
Silage inoculants and enzymes comprise defined microbial cultures—primarily homofermentative and heterofermentative lactic acid bacteria—and cellulolytic or hemicellulolytic enzymes applied at 100,000 to 1,000,000 colony-forming units per gram of fresh forage to accelerate pH decline and preserve nutritional value. Their primary commercial purpose centers on reducing dry matter losses during anaerobic storage while stabilizing crude protein and fiber digestibility for ruminant feed rations. Liquid inoculants occupy the largest volume share due to ease of tank-mix application and uniform coverage on harvested forage, though enzymatic additives represent the fastest-expanding margin pool as dairy nutritionists target fiber digestibility improvements. Corn silage applications lead value generation because of higher dry matter yields and widespread use in total mixed rations across industrialized dairy operations.
FDA Center for Veterinary Medicine guidelines govern microbial feed additive safety in the United States, while EU REACH and F-Gas Regulation frameworks constrain solvent-based formulation chemistries and packaging emissions. BIS feed-grade certification requirements in India and EFSA additive authorization processes in Europe collectively raise compliance costs for new market entrants. Stakeholders must monitor evolving residue testing protocols and strain registration timelines as regulatory divergence between major dairy regions intensifies product development complexity.
Market Dynamics
The EU Green Deal farm-to-fork targets are compressing product registration timelines and forcing reformulation investments across microbial feed additive portfolios.
Growth Catalysts
- Regulatory tightening in Europe:EFSA additive authorization processes and REACH solvent restrictions are accelerating replacement demand for compliant inoculant formulations.
- Consolidation of US dairy operations:Large-scale farms in Wisconsin and California prioritize fermentation consistency, creating concentrated demand for high-performance bacterial strains.
- Enzyme performance improvements:Cellulolytic additive advances are expanding fiber digestibility gains in corn silage-based total mixed rations.
Market Restraints
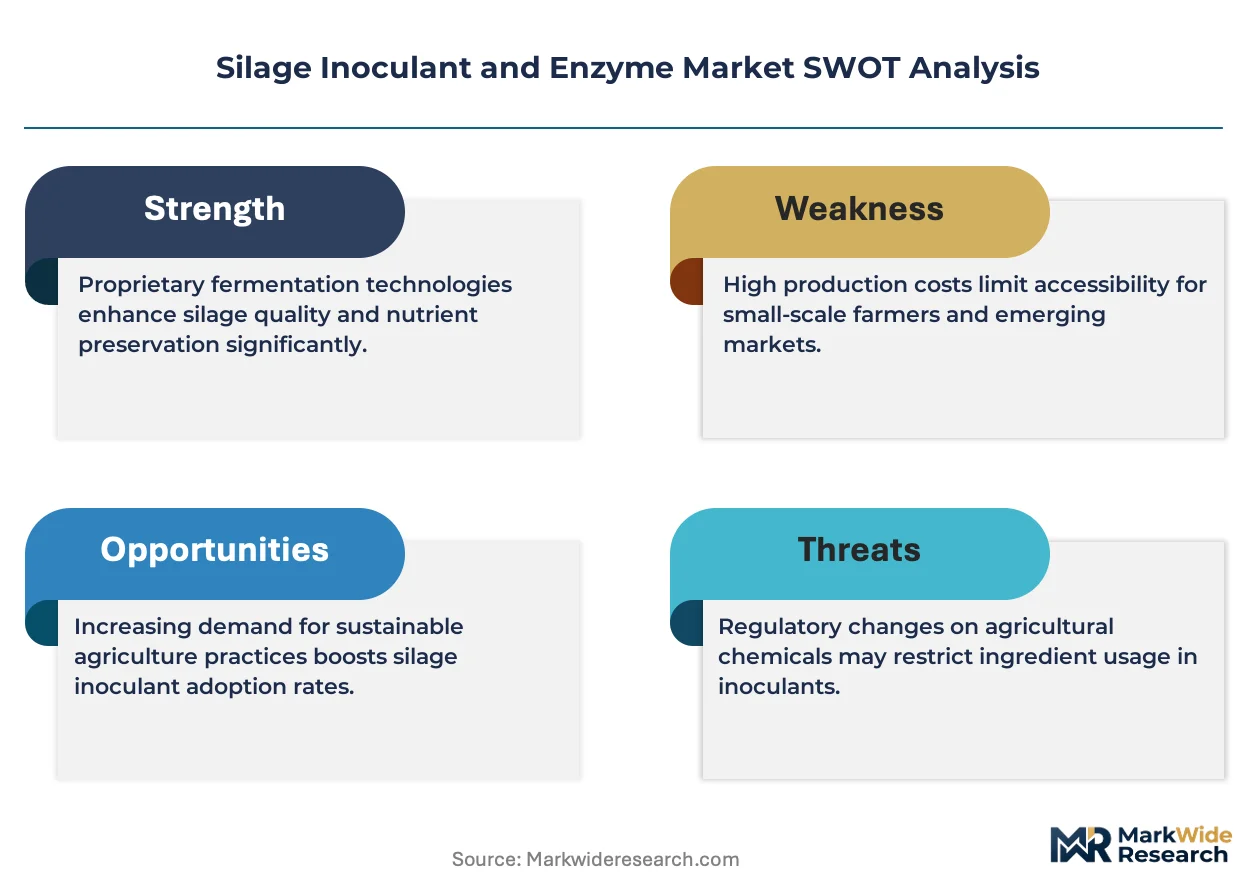
- Strain registration costs:EFSA and FDA Center for Veterinary Medicine approval timelines extend 18-36 months, freezing smaller developers from commercial launch.
- Raw material concentration:Specialist fermentation media suppliers cluster in Germany and Denmark, creating input vulnerability for non-European formulators.
- Application labor constraints:Uniform inoculant coverage requires calibrated tank-mix equipment that smaller Brazilian and Indian farms rarely maintain.
Strategic Opportunities
- Underpenetrated Indian dairy:BIS feed-grade certification expansion and cooperative modernization programs open channels for quality-tier inoculant suppliers.
- Monitoring-as-a-service models:Asset-light leasing of fermentation pH and temperature sensors enables smaller additive vendors to compete without capital intensity.
- EU F-Gas Regulation compliance:Solvent-free formulation mandates create first-mover advantage for aqueous-based enzymatic product developers.
Industry Challenges
- Microbial screening talent scarcity:Strain isolation and characterization expertise concentrates at specialized agricultural universities in the Netherlands and Wisconsin.
- Legacy equipment incompatibility:Precision application nozzles on older forage harvesters deliver uneven bacterial distribution, undermining claimed efficacy.
- Cross-border strain documentation:Divergent FDA and EFSA safety data requirements force duplicate toxicology studies, inflating R&D burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silage Inoculant and Enzyme Market |
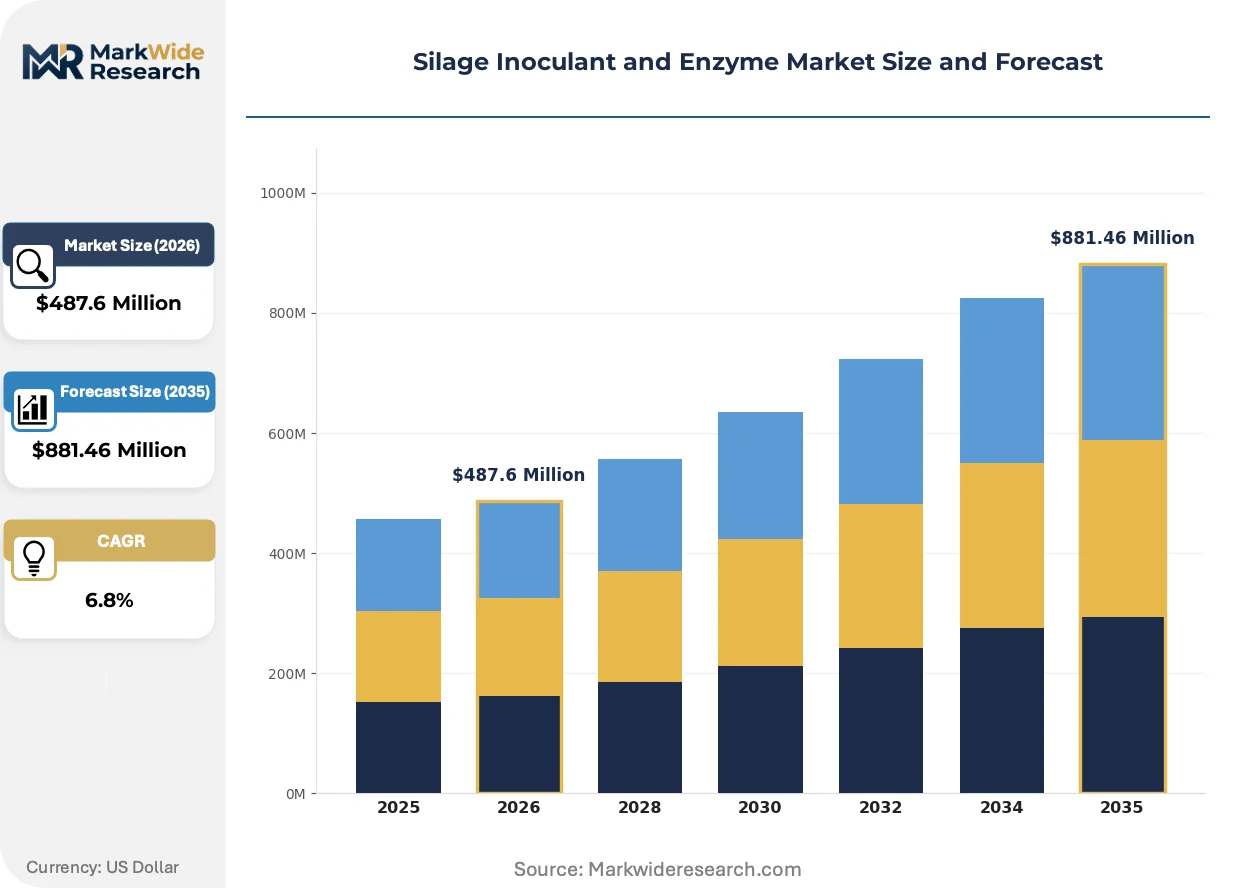
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Inoculants, Dry Inoculants, Enzymatic Additives, Fermentation Aids Application: Corn Silage, Grass Silage, Legume Silage, Forage Conservation End User: Dairy Farmers, Beef Farmers, Feed Manufacturers, Agricultural Cooperatives Distribution Channel: Online Retail, Direct Sales, Agricultural Supply Stores, Distributors |
| Companies Covered | Kemin Industries, Lallemand, Archer Daniels Midland, Volac International, Cargill, Chr. Hansen, Addcon Group, Biomin Holding, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silage Inoculant and Enzyme Market Evolving Landscape
Real-time fermentation monitoring is displacing post-ensiling quality testing as the primary value demonstration mechanism for additive suppliers.
Wireless sensor networks embedded in bunker silos and ag bags are digitizing pH decline curves and temperature stability metrics. Dairy nutritionists at 500-plus cow operations in California and the Netherlands now demand continuous data streams rather than periodic lab assays. This visibility is digitizing contract structures, with payment terms increasingly tied to measured dry matter preservation rather than guaranteed bacterial counts.
EU F-Gas Regulation constraints on propellant-based packaging are forcing aqueous formulation investments across solvent-dependent enzyme suppliers. The industrial consequence compresses shelf-life claims and requires cold-chain distribution investments. Corn silage enzyme applications face the steepest reformulation costs given their historical reliance on volatile organic solvent carriers.
Large cooperatives in Germany and Brazil are consolidating procurement authority previously dispersed across individual farm managers. Centralized tendering for seasonal inoculant volumes is replacing fragmented spot purchasing. This concentration is most visible in Minas Gerais dairy clusters and Bavarian farmer cooperatives, where technical committees now screen bacterial strain documentation before contract award.
Silage Inoculant and Enzyme Market Segmentation
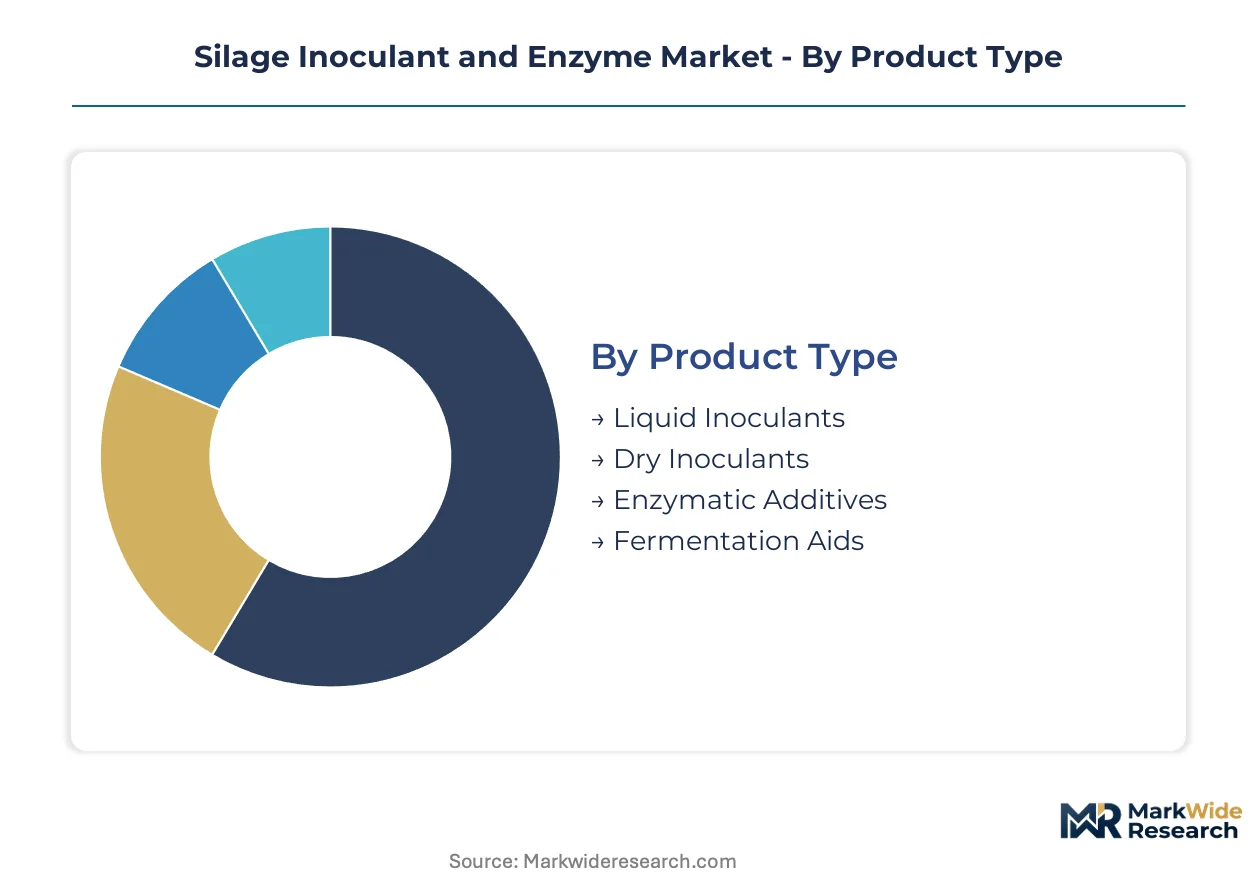
Segmentation in the silage inoculant and enzyme market reflects divergent technical requirements across farm scales, crop types, and regulatory environments. Each dimension carries distinct margin structures and competitive entry barriers that reshape supplier positioning.
Product Type:
Mature formulations dominate volume, while emerging aqueous and enzyme-based platforms are capturing margin expansion from regulatory pressure on solvent carriers.
- Liquid Inoculants:Homofermentative and heterofermentative lactic acid bacteria suspended in aqueous carriers, applied via tank-mix systems at 100,000 to 1,000,000 CFU per gram. Demand concentrates in Wisconsin and California dairy operations where calibrated application equipment ensures uniform coverage on high-volume corn silage harvests. Tank-mix compatibility and ease of integration with existing harvester infrastructure sustain preference among large-scale operators.
- Enzymatic Additives:Cellulolytic and hemicellulolytic enzyme cocktails targeting fiber digestibility improvements in total mixed rations. Dairy nutritionists in the Netherlands and California now specify these for corn silage-based diets where marginal milk yield gains justify premium pricing. EU F-Gas Regulation constraints on propellant-based packaging are accelerating aqueous formulation investments among suppliers serving European cooperatives.
- Dry Inoculants:Freeze-dried bacterial concentrates requiring reconstitution before application, favored in regions with limited cold-chain distribution infrastructure.
- Fermentation Aids:Blended acidifiers and microbial cultures targeting pH decline acceleration in challenging ensiling conditions.
Liquid inoculants handle the majority of throughput; enzymatic additives are gaining share fastest on fiber digestibility premiums.
Application:
Crop-specific fermentation kinetics create divergent performance benchmarks and customer loyalty patterns across silage types.
- Corn Silage:Higher dry matter yields and consistent starch content make this the dominant value pool, with industrialized dairy operations in the United States, Germany, and Brazil specifying inoculants for fermentation consistency. Large-scale total mixed ration formulation depends on predictable crude protein preservation and aerobic stability during feedout.
- Grass Silage:Variable sugar content and moisture levels demand heterofermentative strain dominance for aerobic stability, with German and Irish beef operations representing concentrated demand.
- Legume Silage:High buffering capacity and protein degradation risks require specialized homofermentative cultures, with French and Italian dairy cooperatives driving specification intensity.
- Forage Conservation:Catch-all category covering mixed-species and emergency forage preservation, common in smaller Brazilian and Indian operations with limited harvest timing flexibility.
Corn silage anchors revenue concentration; legume silage applications are expanding most quickly on protein preservation premiums in European premium dairy channels.
End User:
Customer scale and procurement sophistication fragment pricing power and technical service requirements across the value chain.
- Dairy Farmers:Operations exceeding 500 cows in California, Wisconsin, and the Netherlands now demand continuous fermentation monitoring data rather than guaranteed bacterial counts, digitizing contract structures around measured dry matter preservation outcomes.
- Agricultural Cooperatives:Centralized tendering authorities in Bavaria and Minas Gerais consolidate seasonal volumes, with technical committees screening strain documentation before award.
- Beef Farmers:Grass silage-dependent operations in Ireland and Argentina prioritize cost efficiency over premium strain performance.
- Feed Manufacturers:Industrial compounders seek standardized inoculant specifications for consistent total mixed ration production at scale.
Dairy farmers command the deepest technical engagement; agricultural cooperatives are consolidating procurement fastest through centralized tendering.
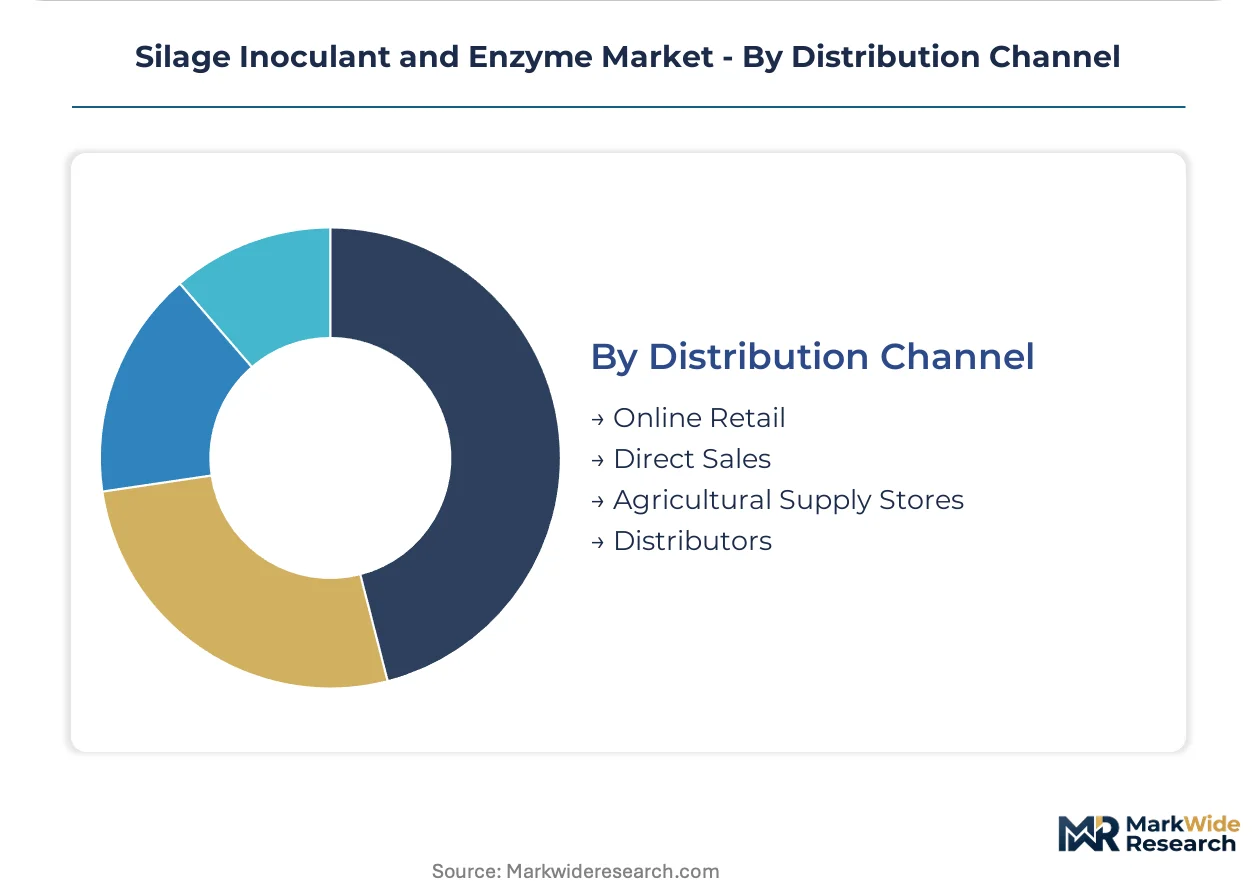
Distribution Channel:
Channel economics reflect capital intensity requirements and customer relationship durability across farm scales.
- Direct Sales:Technical specialists from Lallemand, Chr. Hansen, and Cargill maintain direct relationships with large cooperatives and industrial dairy operations, embedding strain customization and fermentation monitoring services.
- Agricultural Supply Stores:Fragmented retail networks in the United States and Brazil serve smaller operations with limited technical support, concentrating volume in generic liquid inoculant formulations.
- Distributors:Regional specialists bridge cold-chain logistics and local regulatory compliance for multinational suppliers entering Indian and Brazilian markets.
- Online Retail:Emerging channel for standardized dry inoculant products targeting hobby farms and smallholders with limited distributor access.
Direct sales capture the highest margin engagements; distributor networks are expanding fastest to bridge multinational suppliers into underpenetrated geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Farm-to-fork sustainability mandates and feed additive registration reforms are redirecting procurement flows across major dairy-producing territories. National regulators are tightening strain documentation requirements while large-scale operations consolidate seasonal inoculant volumes.
United States
Wisconsin and California dairy operations exceeding 500 cows now specify continuous fermentation monitoring data in procurement contracts. FDA Center for Veterinary Medicine guidelines govern microbial feed additive safety documentation, extending approval timelines for new bacterial strains. The Central Valley corridor anchors demand concentration where total mixed ration formulation depends on predictable crude protein preservation.
Germany
Bavarian agricultural cooperatives have centralized tendering authority previously dispersed across individual farm managers, with technical committees screening strain documentation before contract award. EU REACH solvent restrictions and F-Gas Regulation constraints on propellant-based packaging are forcing aqueous formulation investments among enzyme suppliers. The Lower Saxony grass silage belt represents concentrated demand for heterofermentative strain dominance.
Brazil
Minas Gerais dairy clusters are consolidating procurement through cooperative modernization programs that prioritize fermentation consistency in corn silage applications. ANVISA feed-grade certification requirements shape import pathways for multinational suppliers entering the market. São Paulo state industrial dairy operations drive specification intensity for fiber digestibility improvements in total mixed rations.
India
BIS feed-grade certification expansion and cooperative modernization programs in Maharashtra and Gujarat are opening channels for quality-tier inoculant suppliers. Smaller operations face application labor constraints as uniform coverage requires calibrated tank-mix equipment rarely maintained at farm level. The Punjab dairy belt shows emerging demand for dry inoculant formulations suited to limited cold-chain distribution infrastructure.
Netherlands
Specialized microbial screening capabilities concentrate at agricultural universities in Wageningen, creating talent scarcity for strain isolation and characterization expertise. EFSA additive authorization processes compress product registration timelines and force reformulation investments across microbial feed additive portfolios. Friesland dairy operations now demand digitized contract structures with payment terms tied to measured dry matter preservation rather than guaranteed bacterial counts.
Silage Inoculant and Enzyme Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply relationships. The vendor base organizes around three strategic archetypes: multinational agribusiness conglomerates with captive distribution networks, specialized microbial technology developers with strain libraries, and regional fermentation service providers with asset-light monitoring capabilities. Dominant competitive moves include backward integration into enzyme manufacturing and strategic partnerships for wireless sensor network deployment.
Within the specialized microbial tier, Lallemand and Chr. Hansen exemplify product-specialist positioning through proprietary strain development capabilities. Cargill represents the channel-controlling archetype with integrated manufacturing and distribution infrastructure serving agricultural cooperatives. These three anchors demonstrate how competitive positioning splits between technical performance differentiation and supply chain control.
| Leading Market Players |
|---|
| Kemin Industries |
| Lallemand |
| Archer Daniels Midland |
| Volac International |
| Cargill |
| Chr. Hansen |
| Addcon Group |
| Biomin Holding |
| DuPont |
| Others |
Value Network & Pricing Analysis
Specialist fermentation media suppliers cluster in Germany and Denmark, anchoring input costs for microbial strain production and concentrating margin capture among formulators with captive upstream relationships. This geographic tethering of bacterial culture inputs to Northern European fermentation infrastructure reshapes where pricing power accumulates across liquid inoculant and enzymatic additive tiers.
Pricing Analysis
Certification level creates the primary spread across product tiers, with EFSA-authorized and FDA Center for Veterinary Medicine-cleared strains commanding substantial premia over BIS-grade alternatives in emerging markets. Three-tier pricing structure separates registered performance strains from standard homofermentative formulations and economy dry inoculants. Cost compression in the economy tier is intensifying as Indian and Brazilian distributors push volume-based rebates. Large-scale dairy cooperatives in Bavaria and Minas Gerais exhibit lowest price sensitivity due to outcome-based contract structures, while smaller beef operations in Argentina and Ireland drive aggressive spot-market negotiation.
Supply Chain Analysis
EU REACH chemical restrictions and F-Gas Regulation packaging constraints limit solvent-based formulation flows into European markets, forcing aqueous reformulation investments. Manufacturing gravity centers on Germany, Denmark, and the United States for specialist fermentation capacity, with Brazil and India serving as formulation and packaging nodes for regional distribution. Raw material dependencies include yeast extract, peptone media, and cellulase enzyme concentrates. Single-source vulnerability concentrates in Danish fermentation equipment suppliers. Distribution runs through agricultural cooperatives and direct technical sales teams for large dairy operations, with fragmented retail networks serving smaller farm segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is crossing a platform-economics threshold as fermentation monitoring data becomes the interoperability layer binding additive suppliers to dairy nutrition software ecosystems. Wireless sensor networks and digitized pH decline curves are creating the infrastructure for outcome-based contracting that locks in multi-year supplier relationships.
For Market Incumbents: Build data-network moats by embedding continuous fermentation monitoring into standard service bundles, raising switching costs for dairy operations exceeding 500 cows. Deepen backward integration into enzyme manufacturing to capture margin pools from fiber digestibility premiums. Defend against asset-light monitoring-as-a-service entrants by acquiring regional sensor network providers in California and the Netherlands. For New Entrants and Emerging Players: Pursue underpenetrated Indian dairy cooperatives in Maharashtra and Gujarat where BIS certification expansion is lowering regulatory barriers. Target dry inoculant segments in Punjab and Rajasthan where cold-chain gaps disadvantage liquid formulation incumbents. Lead with distributor partnerships that bridge last-mile logistics rather than capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across fermentation monitoring services as sensor leasing models displace equipment ownership. Long-term viability favors suppliers with strain libraries and digitized outcome demonstration capabilities over pure formulation players. Acquisition targets should show proprietary microbial screening relationships with Wageningen or Wisconsin agricultural universities. Watch for inflection when payment terms tied to measured dry matter preservation exceed guaranteed bacterial count contracts in tender documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Manufacturing | Cargill's captive enzyme production secures margin capture from fiber digestibility premiums in California dairy rations. |
| Sensor Network Partnership Deployment | Asset-light pH monitoring leasing enables smaller vendors to compete with Chr. Hansen's embedded technical service teams. |
| Aqueous Formulation Transition | EU F-Gas Regulation compliance creates first-mover positioning for solvent-free enzymatic additive developers serving Bavarian cooperatives. |
| Strain Library Expansion | Lallemand's microbial culture collections sustain R&D intensity across homofermentative and heterofermentative product pipelines. |
| Cooperative Procurement Consolidation | Centralized tendering in Minas Gerais and Lower Saxony concentrates volume and raises technical documentation barriers. |
Research Methodology
A standing panel of dairy nutritionists, fermentation equipment specialists, agricultural cooperative procurement managers, and regulatory affairs directors at feed additive suppliers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EFSA additive authorization databases, FDA Center for Veterinary Medicine guidance documents, BIS feed-grade certification records, and ANVISA regulatory filings. Bottom-up strain registration timelines and top-down corn silage volume projections were triangulated to anchor market sizing.
Scenario bracketing around regulatory divergence intensity and cooperative consolidation pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, crop application, farm scale tier, and regional regulatory cluster. CAGRs were derived from weighted average growth across these segments, with inputs including dairy herd expansion rates in Wisconsin and California, EU Green Deal implementation timelines, and Brazilian cooperative modernization program commitments.
Sensitivities concentrate around EFSA authorization delays, FDA strain approval timeline extensions, and cold-chain infrastructure buildout pace in India. Cross-checking against USDA National Agricultural Statistics Service silage production data and customs records for fermentation equipment imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
North America Bioherbicides Market