
 Europe Soft Drinks Packaging Market | 2026-2036
Europe Soft Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soft Drinks Packaging Market Foresight
European aluminum can producers is broadening output to serve shifting carbonated and still beverage portfolios. Amcor PLC leverages extensive film and container expertise across multiple substrate categories. Ball Corporation anchors its position through dedicated beverage can capacity concentrated in Central and Eastern European manufacturing locations. Crown Holdings Incorporated competes through specialized metal packaging solutions tailored to premium and craft soft drink positioning.
Europe soft drinks packaging encompasses primary and secondary containment systems engineered to preserve carbonation, prevent light-induced degradation, and enable efficient ambient and chilled distribution of non-alcoholic beverages. Aluminum cans typically employ 3104-H19 alloy with internal epoxy-based lining systems to prevent metal-ion migration, while PET bottles integrate acetaldehyde scavenger technologies to maintain organoleptic stability. Bottles and cans retain dominant volume positions, though cartons are gaining structural share in ambient-stable juice and functional drink segments where aseptic filling extends shelf life without refrigeration. Paperboard demand is accelerating fastest among material categories as brand owners pursue fiber-based alternatives to satisfy EU packaging waste reduction mandates.
The EU Packaging and Packaging Waste Regulation, REACH chemical compliance frameworks, and F-Gas Regulation governing refrigeration-dependent distribution collectively dictate material substitution timelines and recycling infrastructure investments across member states. EFSA migration limit specifications for food-contact recycled plastics directly influence rPET adoption velocity in bottle manufacturing. Stakeholders must monitor evolving extended producer responsibility fee structures and deposit-return scheme expansions as these mechanisms increasingly determine format economics and regional competitive positioning.
Market Dynamics
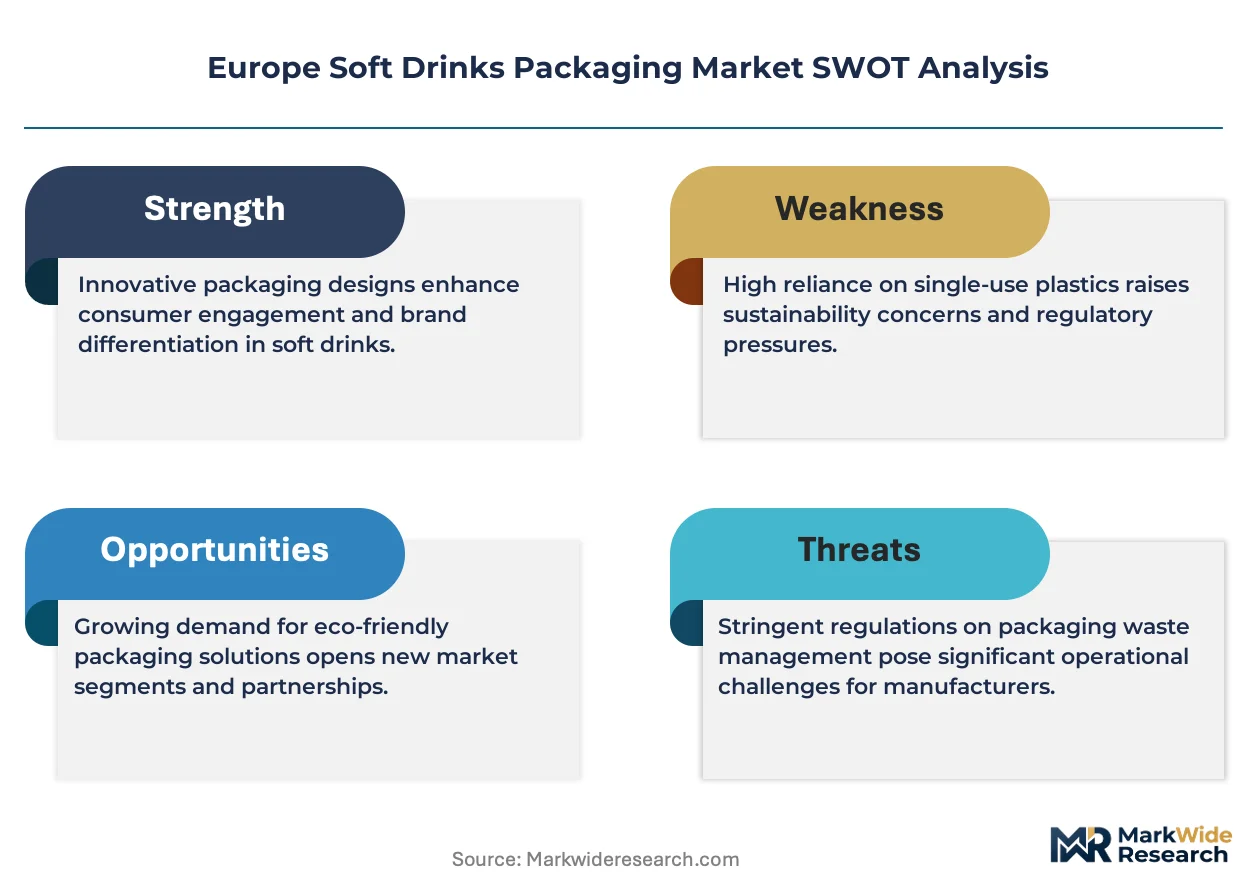
The EU Single-Use Plastics Directive is compressing format timelines across Western European bottling operations, forcing simultaneous transitions in material specifications, recycling infrastructure, and deposit-return scheme participation.
Growth Catalysts
- REACH chemical compliance:Migration limit specifications for food-contact recycled plastics are accelerating rPET adoption in French and German bottle manufacturing.
- Aluminum alloy 3104-H19:Internal epoxy-based lining systems in lightweight cans are displacing heavier formats in premium carbonated water portfolios.
- Central and Eastern Europe:Dedicated beverage can capacity expansion is anchoring volume uptake for craft and functional drink positioning.
Market Restraints
- Primary aluminum ingot volatility:Energy-intensive smelting costs in European smelters are compressing can producer margins.
- rPET flake supply concentration:Collection infrastructure gaps in Southern European member states limit feedstock availability for bottle-grade production.
- Aseptic carton technical limitation:Oxygen barrier performance in fiber-based formats restricts carbonated beverage application.
Strategic Opportunities
- Poland and Romania:Underpenetrated deposit-return scheme coverage creates first-mover positioning for format conversion.
- Ambient-stable functional drinks:Extended shelf life without refrigeration opens carton penetration in convenience channels.
- EU Green Deal packaging waste targets:Mandatory recycled content thresholds generate structural demand pull for rPET and fiber-based alternatives.
Industry Challenges
- Migration testing expertise:EFSA compliance timelines for novel food-contact materials strain analytical laboratory capacity.
- Legacy filling line retrofit:Carbonated beverage producers face capex intensity for aseptic carton conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soft Drinks Packaging Market |
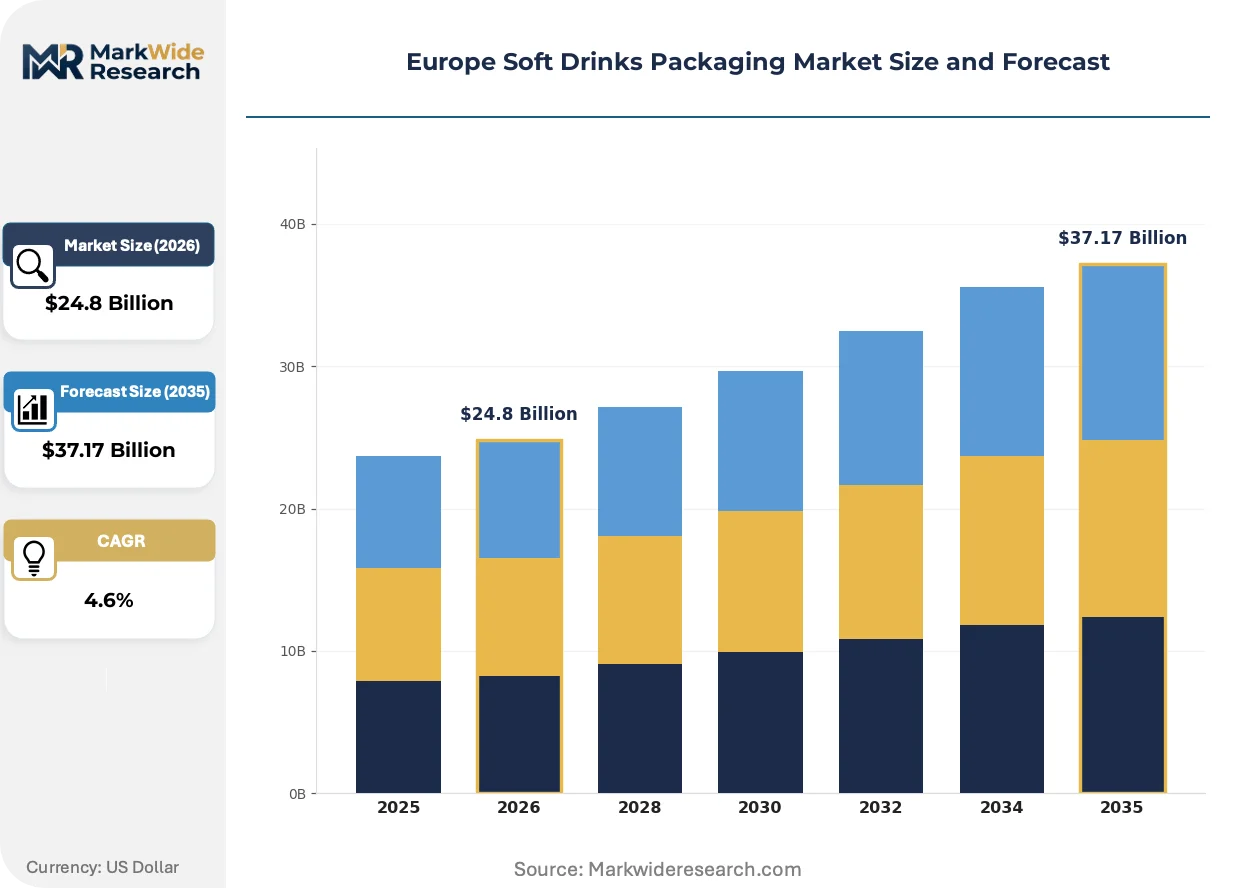
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Cartons, Pouches Material: Plastic, Glass, Metal, Paperboard Closure Type: Screw Cap, Snap-On, Crown Cap, Tetra Pak End User: Retailers, Wholesalers, Food Service, Online Stores |
| Companies Covered | Amcor PLC, Ball Corporation, Crown Holdings Incorporated, Tetra Pak International, Graham Packaging Company, Ardagh Group SA, Berry Global, CAN-PACK SA, Owens-Illinois Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soft Drinks Packaging Market Shifts & Advancements
Material convergence and regulatory compression are reshaping specification decisions across European bottling and canning operations, with fiber-based alternatives and recycled content mandates driving parallel innovation tracks.
Acetaldehyde scavenger technologies in PET bottle manufacturing are unifying organoleptic stability requirements across still and lightly carbonated portfolios. Mid-tier beverage producers in Italy and Spain are adopting these additive systems at accelerated procurement cycles. This unifying specification trend is compressing differentiation windows between premium and standard bottle tiers.
The F-Gas Regulation governing refrigeration-dependent distribution is constraining cold-chain infrastructure expansion across Southern European markets. Industrial consequence includes accelerated shelf-stable format preference in ambient juice and functional drink segments. German retailers are responding with expanded aseptic carton facings in non-refrigerated beverage aisles.
Buying consortium consolidation among French and German private-label retailers is compressing supplier negotiation cycles and unbundling legacy service contracts. Packaging converters face direct specification ownership shifts from brand marketers to retail procurement functions. This pattern is most visible in discount channel volume commitments across the Benelux region.
Europe Soft Drinks Packaging Market Segmentation
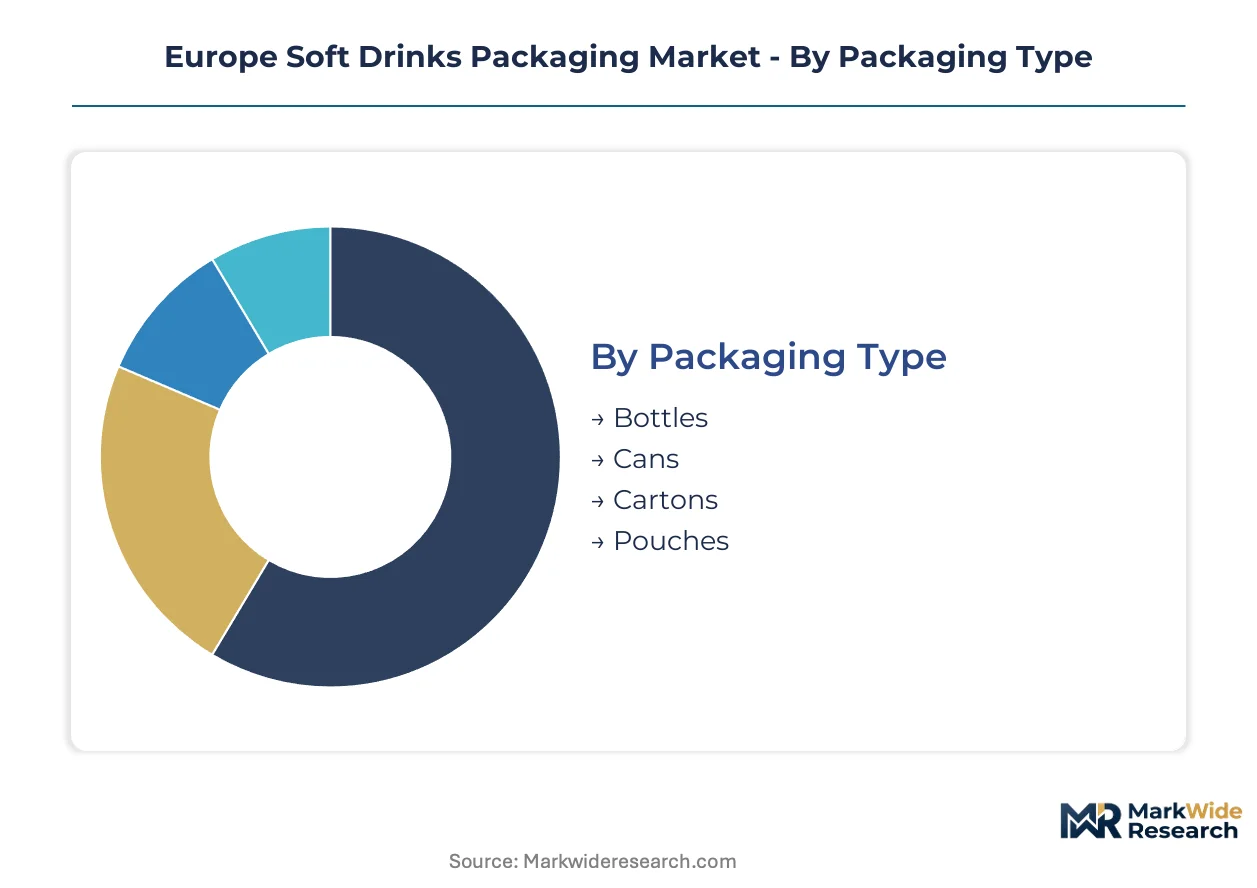
Packaging specification decisions in European soft drinks reflect divergent cost structures, regulatory compliance burdens, and carbonation preservation requirements across format categories. Material and closure selections increasingly pivot on EU Green Deal recycled content mandates and deposit-return scheme participation rather than legacy performance criteria alone.
Packaging Type:
Beverage producers prioritize carbonation retention, shelf-life extension, and filling line compatibility when selecting primary containment formats.
- Bottles:PET and glass variants dominate carbonated and still beverage portfolios, with acetaldehyde scavenger additives ensuring organoleptic stability in recycled PET applications. German and French bottlers are converting lightweight PET specifications to meet EFSA migration limits for food-contact recycled plastics.
- Cans:Aluminum 3104-H19 alloy formats with internal epoxy linings prevent metal-ion migration while enabling premium carbonated water positioning. Central European canning capacity expansion is capturing craft and functional drink volume migration from heavier glass alternatives.
- Cartons:Aseptic fiber-based formats extend shelf life without refrigeration, gaining facings in German ambient retail aisles for juice and functional drinks.
- Pouches:Flexible laminated structures serve single-serve and on-the-go consumption occasions, though oxygen barrier limitations restrict carbonated beverage application.
Volume sits with bottles; growth tilts toward cans.
Material:
Raw material procurement strategies balance virgin resin costs, recycled feedstock availability, and extended producer responsibility fee structures.
- Plastic:PET and rPET specifications anchor bottle manufacturing, with EFSA compliance timelines dictating adoption velocity for recycled content grades. Collection infrastructure gaps in Southern Europe constrain flake supply for bottle-grade production.
- Metal:Aluminum can sheet demand concentrates in Central and Eastern European manufacturing locations, where energy-intensive smelting costs compress producer margins.
- Glass:Heavyweight returnable and single-use formats retain share in premium mineral water and craft positioning, though logistics costs disadvantage against lightweight alternatives.
- Paperboard:Fiber-based demand is climbing the fastest among material categories as brand owners pursue EU packaging waste reduction compliance through aseptic carton conversion.
Plastic retains volume leadership; paperboard offers the steepest expansion trajectory.
Closure Type:
Sealing performance and consumer convenience determine specification ownership between brand marketers and retail procurement functions.
- Screw Cap:Standardized PET bottle closures enable resealability for multi-serve consumption, dominating retail and online channel formats.
- Snap-On:Press-fit designs serve single-serve convenience applications with reduced material weight versus threaded alternatives.
- Crown Cap:Traditional metal closures retain craft and heritage positioning in glass bottle portfolios, particularly in German and Belgian markets.
- Tetra Pak:Integrated carton-closure systems enable aseptic filling with extended ambient shelf life, expanding in juice and functional drink segments.
Screw caps command volume; Tetra Pak closures are gaining share fastest in ambient-stable categories.
End User:
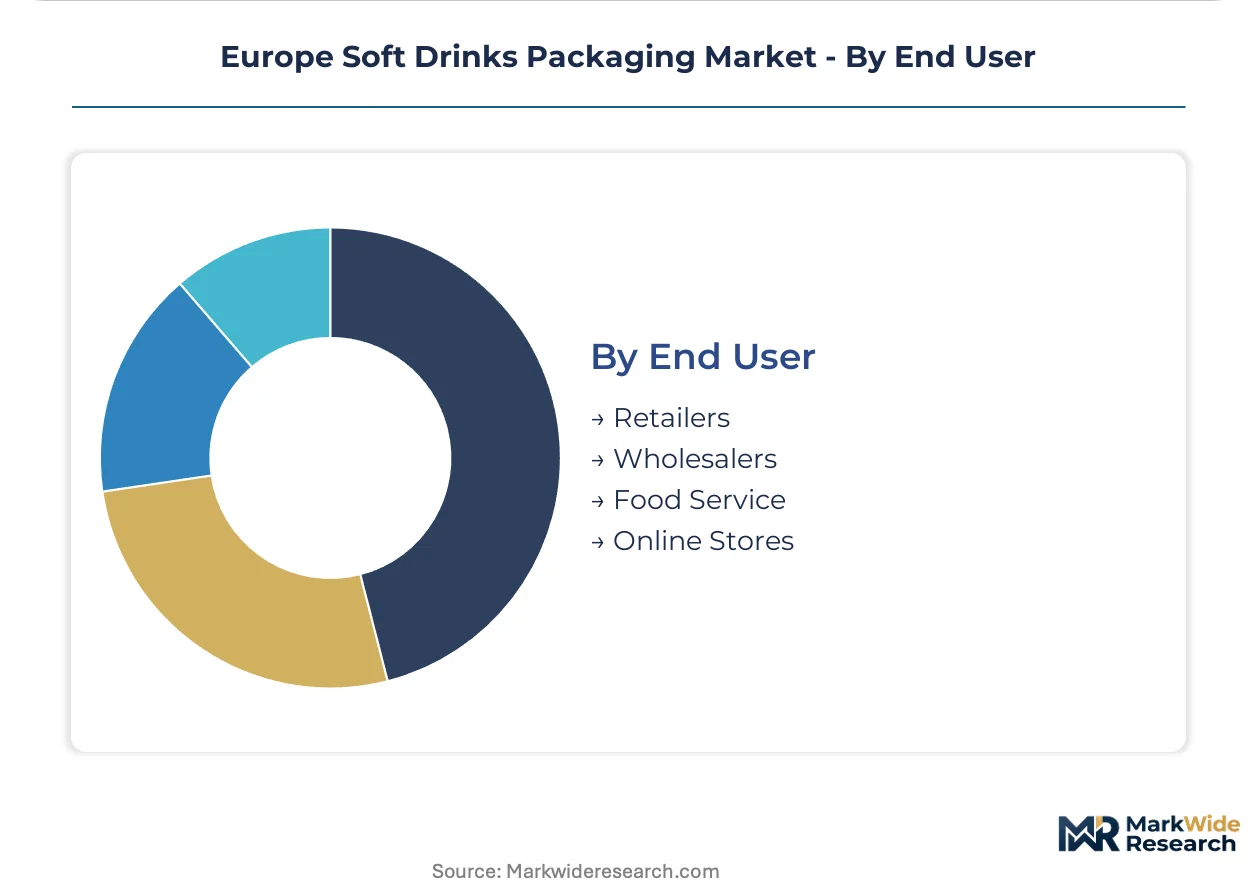
Channel-specific packaging requirements reflect temperature control, handling intensity, and private-label specification ownership patterns.
- Retailers:Supermarket and discount channel buyers in France and Germany are consolidating procurement consortiums, shifting specification ownership from brand marketers to retail functions.
- Wholesalers:Bulk distribution intermediaries require pallet-optimized secondary packaging for food service and vending channel supply.
- Food Service:On-premise consumption drives single-serve format preference, with portion control and branding visibility prioritizing can and bottle formats over cartons.
- Online Stores:E-commerce channel growth demands enhanced secondary packaging for shipping durability, particularly for glass bottle formats in direct-to-consumer fulfillment.
Retailers anchor volume concentration; online stores represent the most rapidly expanding demand channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity in Iceland and Norway supplies feedstock for Central European can manufacturing, while rPET collection infrastructure concentrates in German and French urban corridors. These raw-material geographies shape packaging investment flows across the continent.
Germany
Premium carbonated water brands and discount retail consolidation drive format demand. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that accelerate rPET adoption in bottle manufacturing. The Rhine-Ruhr industrial corridor hosts concentrated beverage can capacity serving domestic and export markets.
France
Private-label retailer consortiums compress supplier negotiation cycles and shift specification ownership. EFSA migration limit specifications for food-contact recycled plastics dictate rPET adoption velocity in bottle production. The Paris basin anchors aseptic carton innovation for ambient-stable juice portfolios.
Italy
Mid-tier beverage producers accelerate acetaldehyde scavenger procurement for PET bottle standardization. REACH chemical compliance frameworks unify material specifications across still and carbonated portfolios. Northern Italian manufacturing clusters concentrate glass-to-aluminum conversion for craft positioning.
Poland
Underpenetrated deposit-return scheme coverage creates first-mover positioning for format conversion investments. EU Green Deal packaging waste targets generate structural demand pull for rPET infrastructure development. The Silesian industrial region attracts Central European beverage can capacity expansion.
Spain
Ambient-stable functional drink segments favor aseptic carton penetration in convenience channels. The F-Gas Regulation constrains cold-chain infrastructure expansion and accelerates shelf-stable format preference. Catalan manufacturing bases serve Southern European distribution networks.
Europe Soft Drinks Packaging Market Competitive Landscape
Global majors compete with regional champions across substrate specialization and geographic coverage. The vendor base organizes around three strategic archetypes: integrated multi-material converters, dedicated metal packaging specialists, and fiber-based aseptic system providers. Competitive positioning depends on backward integration into raw material supply and regulatory compliance infrastructure. M&A activity targets rPET collection assets and aseptic filling technology licenses.
Within the integrated converter tier, Amcor PLC exemplifies multi-substrate capability spanning film and rigid container categories. Ball Corporation and Crown Holdings Incorporated anchor metal-focused positioning through beverage can manufacturing concentration. These three companies represent divergent responses to EU Single-Use Plastics Directive compliance requirements.
| Leading Market Players |
|---|
| Amcor PLC |
| Ball Corporation |
| Crown Holdings Incorporated |
| Tetra Pak International |
| Graham Packaging Company |
| Ardagh Group SA |
| Berry Global |
| CAN-PACK SA |
| Owens-Illinois Inc. |
| Others |
Supply & Pricing Matrix
Aluminum LME spot pricing volatility cascades through European can manufacturing into three distinct procurement tiers. Brand owners with long-term offtake agreements capture cost stability, while spot-market buyers absorb margin compression from energy-intensive smelting operations.
Pricing Analysis
Extended producer responsibility fee bundling separates full-service packaging converters from unbundled material suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects rPET certification grade and deposit-return scheme participation. Pricing pressure stems from primary aluminum ingot energy costs, with discount channel buyers in Germany and France exhibiting highest price sensitivity.
Supply Chain Analysis
Regional distribution centers in Germany, Poland, and the Netherlands anchor hub-and-spoke patterns for beverage can and bottle fulfillment. Raw material flows draw from Icelandic and Norwegian aluminum smelting alongside German and French rPET collection corridors. Single-source vulnerability concentrates in Southern European flake supply, with distribution running through Rhine-Ruhr logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive erects a cost-of-compliance barrier that favors incumbents with established rPET infrastructure and EFSA migration testing capabilities. New entrants face capital intensity for laboratory certification and collection asset ownership.
For Market Incumbents: Anchor market position through backward integration into rPET collection assets in underpenetrated Polish and Romanian corridors. Defend against fiber-based format substitution by accelerating aseptic carton filling line partnerships in German retail channels.
For New Entrants and Emerging Players: Direct-to-procurement-platform routes enable specification influence with consolidated French and German retail consortiums. Target ambient-stable functional drink segments in Spain and Italy where aseptic carton penetration remains below Northern European benchmarks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with captive rPET flake supply in Central European manufacturing locations. Monitor EU Green Deal packaging waste target enforcement as inflection signal for mandatory recycled content threshold acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Collection Asset Acquisition | Backward integration into Polish and Romanian feedstock secures EFSA-compliant supply for bottle-grade production. |
| Aseptic Carton Filling Partnership | Technology licensing with Tetra Pak International enables ambient-stable juice penetration in German discount channels. |
| Aluminum Can Capacity Expansion | Silesian manufacturing base captures craft beverage volume migration from glass in Central European markets. |
| Deposit-Return Scheme Infrastructure | First-mover positioning in underpenetrated member states locks in format economics before regulatory mandate expansion. |
| EFSA Migration Testing Laboratory Investment | In-house analytical capacity compresses compliance timelines for novel food-contact recycled plastic specifications. |
Research Methodology
Document review covered EU regulatory filings, EFSA migration limit specifications, and beverage industry trade association reports, complemented by interviews with packaging procurement managers at French and German retailers, technical directors at aluminum can manufacturers, sustainability officers at soft drink brand owners, and laboratory compliance specialists. Secondary validation drew from customs trade data, extended producer responsibility fee schedules, and deposit-return scheme operator disclosures. Bottom-up volume modeling triangulated against top-down material flow analysis.
Market sizing outputs reflect segmentation across packaging type, material substrate, closure system, and end-user channel throughout the projection horizon. CAGRs derive from regression analysis of historical format adoption curves and regulatory compliance timeline acceleration. Industry-specific inputs incorporated smelting energy cost indices, rPET flake spot pricing, and retail procurement consortium consolidation patterns.
Inputs from EFSA migration testing laboratories and deposit-return scheme operators were available through the study window; gaps in Southern European collection infrastructure data introduce uncertainty bands for rPET adoption velocity assumptions. Forecasts reflect documented scenario parameters; decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Europe Beverage Container Market