
 Blow Molded Plastic Bottles Market | 2026-2036
Blow Molded Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Blow Molded Plastic Bottles Market Analysis
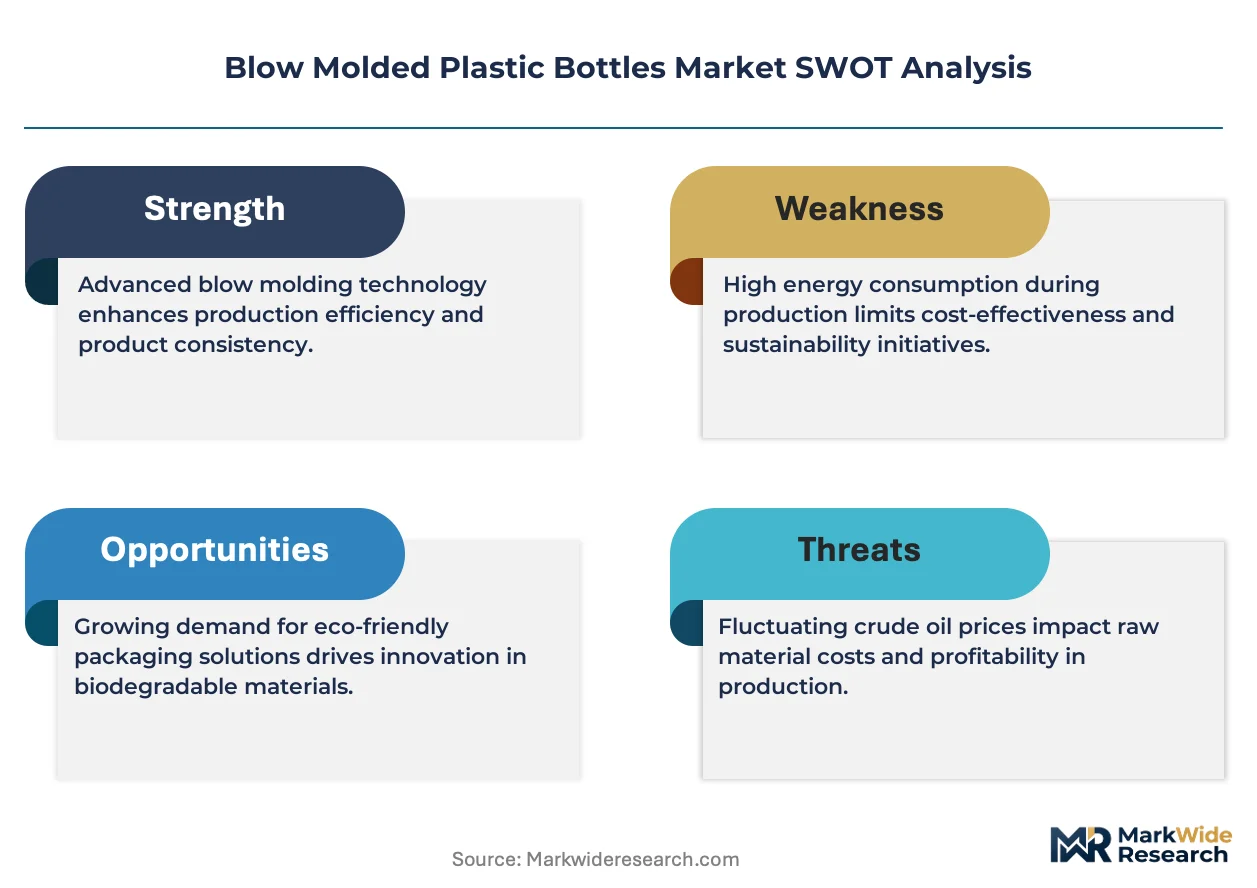
The EU Green Deal's packaging waste reduction targets is realigning converter investment toward rPET and bio-based resin systems. Berry Global leverages integrated recycling infrastructure across European operations to secure post-consumer feedstock. Amcor plc anchors its position through pharmaceutical-grade barrier technology. Graham Packaging specializes in large-format dairy and juice containers for North American retailers.
Blow molded plastic bottles are hollow thermoplastic containers formed by extruding or injecting molten resin into a parison, then inflating it within a cooled mold cavity to achieve wall thicknesses between 0.25 and 2.0 millimeters. These vessels store and dispense liquids, powders, and semi-solids across consumer and industrial supply chains. Polyethylene Terephthalate dominates beverage and pharmaceutical applications due to clarity, barrier performance, and established recycling streams. High-Density Polyethylene leads in household products and milk packaging where chemical resistance and cost efficiency matter most. The 500ml to 1L capacity band captures premium personal care and functional beverage growth.
FDA food-contact regulations and EPA emissions standards govern resin selection and plant permitting across United States manufacturing. EFSA and REACH compliance in Europe restricts certain additives and mandates recyclability disclosures on consumer labels. India's BIS certification requirements for food-grade plastics create entry barriers for imported converters. Stakeholders must monitor evolving extended producer responsibility schemes and resin certification protocols to maintain market access and brand positioning.
Market Dynamics
The EU Green Deal's mandatory recycled-content quotas are forcing converters to reconfigure resin procurement and retrofit extrusion lines for rPET compatibility, compressing legacy virgin-PET economics.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recyclability disclosures and recycled-content minimums are redirecting beverage bottler procurement toward post-consumer rPET supply chains.
- Pharmaceutical barrier technology:Multi-layer co-extrusion and plasma coating advances are expanding oxygen and moisture protection for sensitive drug formulations.
- India BIS certification expansion:Food-grade plastic standards are formalizing quality tiers that favor domestic converters with certified in-house testing laboratories.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps and contamination rates limit food-grade flake availability, forcing converters to absorb premium pricing or blend downgrades.
- HDPE resin concentration:Gulf Coast petrochemical complexes supply disproportionate North American volumes, exposing converters to hurricane-disruption risk and freight cost volatility.
- Glass substitution in premium spirits:Weighted bottles and brand heritage positioning sustain glass dominance in super-premium alcohol segments resistant to plastic conversion.
Strategic Opportunities
- India pharmaceutical packaging:Domestic drug manufacturing expansion and export-oriented contract research organizations are driving demand for USFDA-compliant barrier bottles.
- Digital printing integration:Direct-to-object inkjet systems are collapsing minimum order quantities and enabling mass customization for craft beverage and personal care launches.
- Extended Producer Responsibility schemes:France and Germany's modulated eco-fee structures reward higher recycled content, creating margin incentives for rPET-heavy product lines.
Industry Challenges
- Food-contact certification timelines:EFSA novel food evaluations and FDA food contact notifications extend new barrier additive approvals to 18-24 months, delaying product launches.
- Blow molding technician shortage:Specialized parison programming and mold maintenance skills are aging out of the workforce faster than vocational programs replenish supply.
- Legacy extrusion line retrofit costs:Converting single-stage equipment for rPET processing requires screw and die modifications that strain mid-cap converter capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow Molded Plastic Bottles Market |
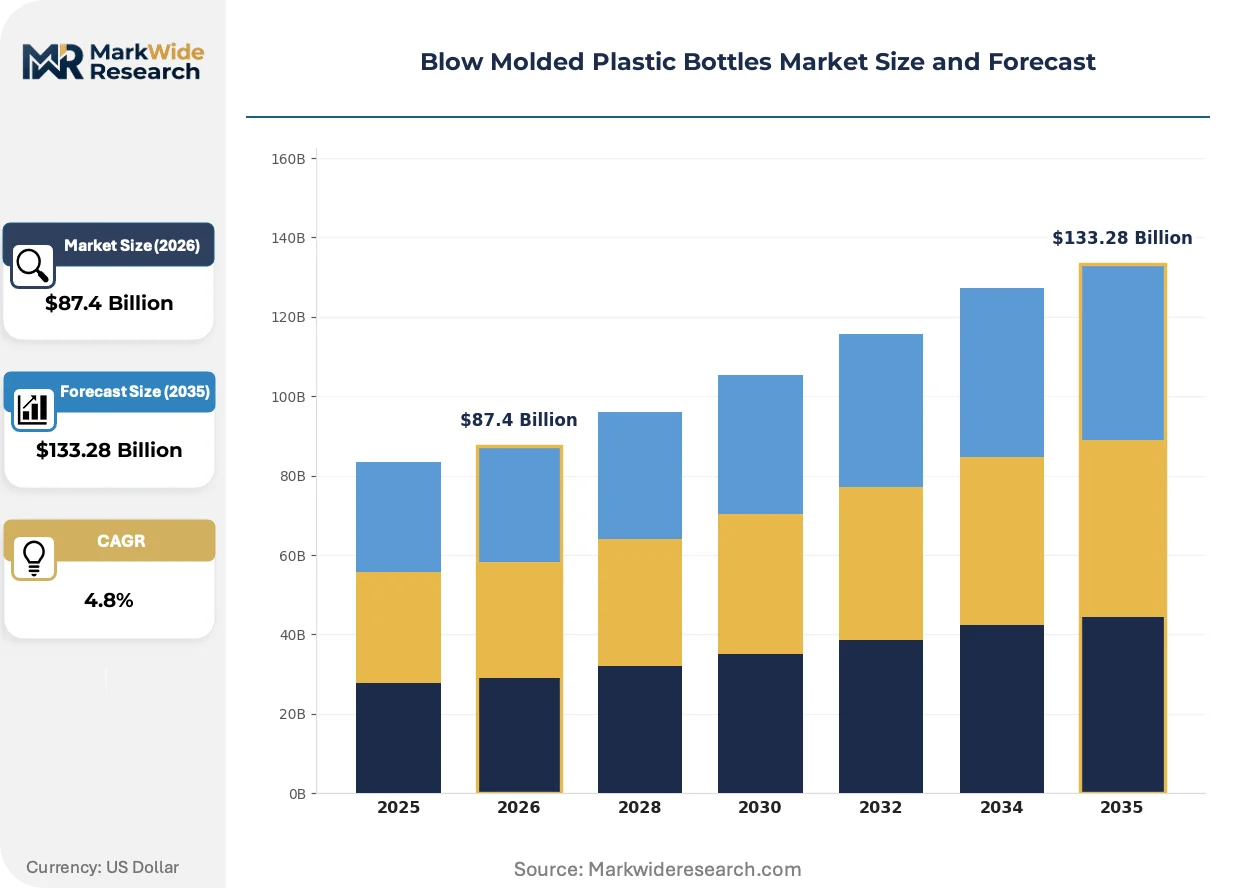
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polyvinyl Chloride End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Capacity: Less than 500ml, 500ml to 1L, 1L to 3L, More than 3L Closure Type: Screw Cap, Snap-On, Dispensing, Tamper-Evident |
| Companies Covered | Amcor plc, Berry Global, Graham Packaging, Alpha Packaging, Plastipak Holdings, ALPLA, Comar, Altium Packaging, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow Molded Plastic Bottles Market Emerging Trajectories
Material science advances and regulatory mandates are converging to redefine converter competitiveness, with sustainability verification and digital manufacturing emerging as decisive capability differentiators.
Lightweighting through finite element analysis-optimized wall thickness is decentralizing production economics across the converter base. Small and mid-cap blow molders are adopting simulation software previously accessible only to integrated multinationals, enabling regional players to compete for national retail private-label contracts. This capability diffusion is compressing the cost advantage historically held by high-volume producers with captive resin operations.
REACH restrictions on intentionally added microplastics are forcing reformulation of masterbatch additives and surface coatings across European operations. The ECHA restriction proposal covers glitter, abrasive beads, and certain film-forming polymers used in decorative bottle finishes. Cosmetic and personal care brands are accelerating shifts to mineral-based alternatives and plant-derived film formers to maintain market access.
Direct-store-delivery consolidation among dairy processors is reshaping bottle specification patterns. Large-format milk and juice containers are standardizing neck finishes and label substrates to accommodate rapid line changeovers at regional filling plants. This specification convergence is visible across Midwest US dairy cooperatives and German discount retail supply chains, where throughput efficiency outweighs brand differentiation in procurement criteria.
Blow Molded Plastic Bottles Market Segmentation
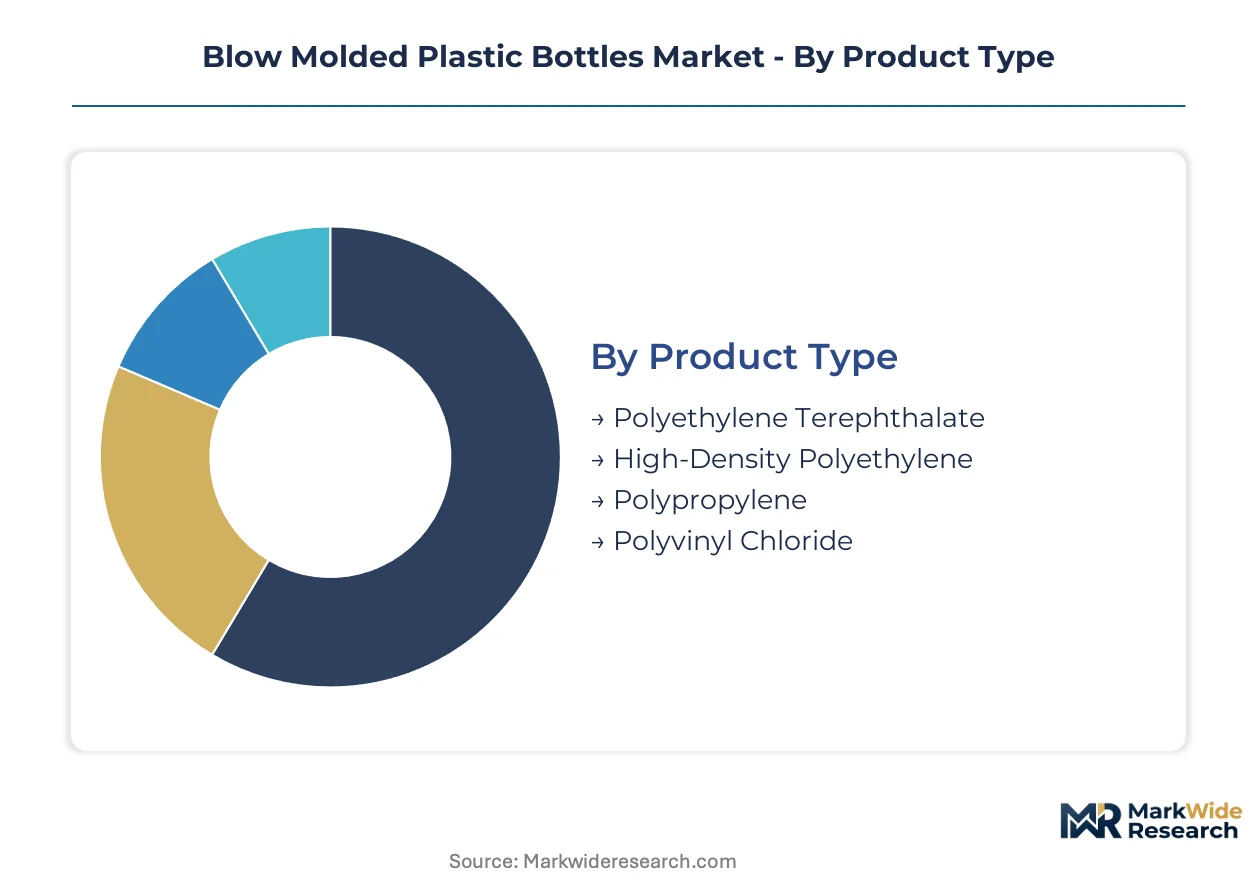
Blow molded plastic bottles serve divergent functional requirements across packaging tiers, from commodity beverage containers to pharmaceutical-grade barrier vessels. Segmentation reveals how resin selection, capacity bands, and closure systems align with specific regulatory and performance demands.
Product Type:
Standardization dominates commodity beverage and household applications, while pharmaceutical and barrier-food formats demand customized multi-layer configurations and additive packages.
- Polyethylene Terephthalate:Amorphous thermoplastic polyester delivers optical clarity and oxygen barrier performance critical for carbonated beverages and sensitive drug formulations. Beverage bottlers in Germany and the United States are expanding rPET procurement under EU Green Deal recycled-content mandates and state-level bottle bill expansions.
- High-Density Polyethylene:Semi-crystalline olefin provides chemical resistance and stress-crack durability for milk, detergent, and industrial chemical packaging. Gulf Coast petrochemical concentration exposes converters to hurricane-related supply disruptions and freight cost volatility.
- Polypropylene:Higher thermal tolerance suits hot-fill applications and microwaveable food containers where dimensional stability under heat matters.
- Polyvinyl Chloride:Declining share in food-contact applications due to EFSA and FDA scrutiny of plasticizer migration, retained in non-food industrial and chemical containment.
Most installed capacity flows through Polyethylene Terephthalate. Expansion is steepest in High-Density Polyethylene as dairy and household product converters seek alternatives to supply-constrained rPET.
End User:
Volume scale concentrates in high-velocity consumer categories, whereas margin capture favors regulated segments with certification barriers and technical specification complexity.
- Food & Beverage:Carbonated soft drinks, bottled water, juices, and dairy products drive unit demand. EU Green Deal packaging rules and India's BIS certification expansion are redirecting procurement toward verified recycled-content and food-grade certified supply chains.
- Pharmaceuticals:Oral solid dose, liquid formulations, and ophthalmic products require USFDA and EMA compliance with extractables testing and barrier performance validation. Domestic drug manufacturing growth in India and contract research organization expansion are accelerating demand for USFDA-compliant barrier bottles.
- Personal Care:Shampoos, lotions, and cosmetics prioritize aesthetic differentiation through decoration and ergonomic design over functional barrier requirements.
- Household Products:Bleach, cleaners, and automotive chemicals leverage HDPE chemical resistance with cost-optimized single-layer construction.
Food & Beverage commands the largest production footprint. Pharmaceuticals is gaining share fastest as serialization mandates and biologics growth tighten packaging specifications.
Capacity:
Small-format production rewards flexibility and rapid changeover capability, while large-format lines favor dedicated high-volume contracts with retail and dairy cooperatives.
- 500ml to 1L:Premium personal care and functional beverage segments concentrate here, where brand differentiation justifies higher per-unit packaging investment. Digital printing integration is collapsing minimum order quantities for craft beverage launches.
- 1L to 3L:Standard milk, juice, and edible oil formats dominate this band with specification convergence across Midwest US dairy cooperatives and German discount retail supply chains.
- Less than 500ml:Travel-size personal care, pharmaceutical unit-dose, and sample formats serve portability and regulatory compliance needs.
- More than 3L:Institutional food service, industrial chemicals, and bulk household products require reinforced wall structures and integrated handles.
1L to 3L holds the majority of active molding capacity. 500ml to 1L is climbing the fastest on premium personal care and functional beverage proliferation.
Closure Type:
Security and dispensing functionality segment by product viscosity, consumption occasion, and regulatory tamper-evidence requirements.
- Screw Cap:Universal threading standards enable cross-brand interchangeability and retail supply chain efficiency across beverage and household categories.
- Tamper-Evident:Ring-break and shrink-band designs satisfy FDA and EMA pharmaceutical packaging security mandates and food safety verification.
- Dispensing:Pump, flip-top, and trigger mechanisms serve high-viscosity personal care and cleaning products with controlled dosing requirements.
- Snap-On:Low-cost attachment for single-serve dairy and juice formats where resealability is secondary to production speed.
Screw Cap accounts for the broadest installed base. Tamper-Evident is expanding most quickly on pharmaceutical serialization mandates and food safety enforcement tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blow molded plastic bottle manufacturing scaled first in post-war United States and Germany, where automated extrusion technology met mass-market beverage distribution. Today production clusters concentrate near petrochemical feedstock and major consumer markets across three continents.
United States
Gulf Coast resin supply and Midwest dairy cooperatives anchor North American demand for HDPE milk containers and large-format juice bottles. EPA emissions standards and FDA food-contact regulations govern plant permitting and additive selection. Wisconsin and Minnesota dairy processing belts standardize neck finishes and label substrates to accelerate line changeovers at regional filling plants.
Germany
Discount retail supply chains and beverage export logistics drive specification convergence in 1L to 3L formats. EU Green Deal recycled-content mandates and EFSA compliance requirements redirect converter investment toward rPET processing. The Ruhr industrial corridor hosts integrated recycling infrastructure securing post-consumer feedstock for beverage bottlers.
India
Domestic drug manufacturing expansion and export-oriented contract research organizations accelerate demand for USFDA-compliant pharmaceutical barrier bottles. BIS certification requirements for food-grade plastics favor converters with certified in-house testing laboratories. Maharashtra and Gujarat pharmaceutical clusters concentrate sterile filling operations and barrier technology deployment.
China
Yangtze River Delta beverage bottlers and Pearl River Delta personal care manufacturers absorb substantial PET and HDPE resin volumes. GB standards and SAMR food-contact regulations parallel FDA and EFSA frameworks. Shandong Province chemical resistance applications sustain HDPE demand for industrial and household product segments.
Blow Molded Plastic Bottles Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier technology certification and rPET processing capability. The vendor base arranges into three tiers: integrated multinationals with captive recycling infrastructure, regional specialists serving single end-use categories, and mid-cap converters competing on private-label flexibility. Strategic moves concentrate on extrusion line retrofitting for recycled-content compatibility and pharmaceutical-grade barrier additive portfolios.
Within the integrated multinational tier, Amcor plc and Berry Global occupy positions defined by geographic reach and regulatory compliance breadth. ALPLA anchors European rPET supply chain integration. Graham Packaging exemplifies North American large-format dairy and juice specialization. These fabricators represent strategic archetypes rather than discrete market positions, with competitive differentiation flowing from resin procurement scale and barrier technology validation timelines.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Graham Packaging |
| Alpha Packaging |
| Plastipak Holdings |
| ALPLA |
| Comar |
| Altium Packaging |
| AptarGroup |
| Others |
Supply Flow & Price Mechanics
rPET flake price indices cascading through European converter procurement are compressing virgin-PET margins while amplifying premiums for food-grade certified recyclate. Beverage bottlers in Germany absorb elevated resin costs under EU Green Deal mandates, forcing specification downgrades or volume renegotiations with dairy and household product buyers less tolerant of pass-through pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier certification grade and volume commitment scale. Premium pharmaceutical-grade multi-layer bottles command substantial markups over commodity beverage formats due to USFDA extractables validation and EMA compliance documentation. Pricing pressure stems from rPET feedstock scarcity forcing converters to absorb premium flake costs or dilute food-contact claims. Private-label beverage bottlers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Food-contact certification and pharmaceutical-grade barrier validation gate access to margin-rich segments, filtering converter participation by technical capability and regulatory compliance breadth. Raw material supply concentrates in Germany, the United States, and India, with Gulf Coast petrochemical complexes anchoring North American HDPE resin flows. Converter operations draw from PET resin, HDPE pellet, and masterbatch additive inputs. Single-source vulnerability runs through rPET flake supply where collection infrastructure gaps persist. Distribution runs through direct-store-delivery dairy cooperatives, beverage bottler consolidation centers, and pharmaceutical contract packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in blow molded plastic bottles rests on rPET processing capability premiums and pharmaceutical barrier certification tier shifts, rewarding converters who absorb upfront retrofit costs for recycled-content compatibility and multi-layer co-extrusion validation.
For Market Incumbents: Anchor market position through backward integration into post-consumer PET collection infrastructure and captive food-grade flake washing operations. Defend against specialty barrier technology entrants by accelerating EMA and USFDA validation timelines for novel oxygen-scavenging additives. Prioritize extrusion line retrofit completion ahead of EU Green Deal recycled-content enforcement escalations. For New Entrants and Emerging Players: Launch via digital printing-enabled mass customization services targeting craft beverage and personal care brands with collapsed minimum order quantities. Target India pharmaceutical packaging white space where domestic drug manufacturing expansion outpaces certified converter capacity. Pursue USFDA-compliant barrier bottle specialization as the most penetrable premium tier given certification backlog at incumbent facilities. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap converters possessing installed rPET processing capability and pending pharmaceutical-grade barrier validations. Long-term viability favors asset-light regional players with flexible extrusion footprints and digital printing integration rather than commodity-scale virgin-PET operators facing structural margin compression. Watch rPET flake price convergence with virgin resin as the inflection signal for recycled-content economics normalization.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Extrusion Line Retrofit | EU Green Deal compliance secures beverage bottler procurement contracts under mandatory recycled-content quotas. |
| Pharmaceutical Barrier Certification | USFDA and EMA validation opens oral solid dose and biologics packaging segments with extended product lifecycles. |
| Digital Printing Integration | Direct-to-object inkjet collapses minimum order quantities for craft beverage and personal care brand launches. |
| Post-Consumer Collection Infrastructure | Captive flake supply hedges against rPET feedstock scarcity premiums and contamination rate volatility. |
| Extended Producer Responsibility Alignment | France and Germany modulated eco-fee structures reward higher recycled content with margin incentives. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blow molding plant managers, beverage bottler procurement leads, pharmaceutical packaging engineers, and resin distributor technical sales directors with secondary validation against customs trade data, FDA food contact notifications, EFSA scientific opinions, and SEC converter filings. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers across resin consumption and end-use shipment patterns.
Comparable historical periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning resin chemistry, end-use application, capacity band, and closure system. CAGRs derived from regression-adjusted trend extrapolation incorporating rPET adoption curves, pharmaceutical packaging specification tightening, and regional regulatory enforcement phasing. Industry-specific inputs included EU Green Deal implementation timelines, India BIS certification expansion rates, and blow molding equipment replacement cycles.
Several conditions sit outside the modeled scope, including force majeure disruptions to Gulf Coast petrochemical supply, abrupt EFSA additive restrictions, and trade policy shifts affecting resin tariff structures. Forecasts reflect documented assumptions regarding rPET collection infrastructure buildout and pharmaceutical serialization mandate adherence. A model refresh is warranted upon material change in EU Green Deal enforcement severity or rPET flake price parity achievement with virgin resin.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Spain Plastic Bottles Market