
 Stackable Beaker Market | 2026-2036
Stackable Beaker Market Size, Share, and Industry Trends Forecast 2026-2036
Stackable Beaker Market Analytics
Recurring calibration and certification services for labware fleets is hardening into a standard contract term rather than an optional add-on. DWK Life Sciences leverages its European manufacturing footprint to sustain long-term supply agreements with institutional buyers. Thermo Fisher Scientific anchors its position through deep integration with laboratory information management systems. Borosil dominates price-sensitive segments in South Asia through localized borosilicate glass production.
Stackable beakers are cylindrical vessels designed with interlocking rims or tapered profiles enabling vertical nesting, typically manufactured from borosilicate glass, polypropylene, or melamine resins with volume calibrations accurate to within five percent. Their primary purpose is to maximize storage density in fume hoods, autoclaves, and shelving units while maintaining chemical compatibility across aqueous and organic reagent classes. Polypropylene beakers lead volume shipments due to disposability demands in molecular biology workflows, while glass variants command margin pools in analytical chemistry where thermal shock resistance proves essential. The 250ml and 500ml sizes capture the bulk of institutional procurement as these volumes align with standard solution preparation protocols.
The U.S. FDA enforces biocompatibility testing under ISO 10993 for plastic labware contacting cell cultures, while the EPA regulates chemical leachate thresholds under TSCA for vessels used in environmental sample analysis. The EU REACH framework restricts phthalate plasticizers in polypropylene formulations, forcing reformulation of legacy product lines destined for European laboratories. Stakeholders must monitor evolving material compliance thresholds as regulatory divergence between North American and European testing protocols complicates unified product certification strategies.
Market Dynamics
Academic laboratories and pharmaceutical R&D facilities are consolidating procurement around calibrated, traceable labware fleets, forcing suppliers to bundle certification services with physical product sales. This shift from transactional purchasing to lifecycle contracting is compressing vendor margins while raising barriers for uncertified competitors.
Growth Catalysts
- ISO 10993 biocompatibility mandates:The U.S. FDA requires plastic labware contacting cell cultures to meet stringent testing protocols, driving replacement cycles for non-compliant inventory.
- High-throughput molecular biology workflows:Genomics and proteomics facilities are scaling disposable polypropylene beaker consumption to match automated liquid-handling throughput.
- China's pharmaceutical R&D expansion:Domestic biotech clusters in Shanghai and Suzhou are importing certified glass beakers for analytical chemistry applications.
Market Restraints
- Borosilicate glass energy costs:European natural gas price volatility has squeezed margins for heat-resistant glass manufacturing concentrated in Germany and Czechia.
- REACH phthalate restrictions:The EU framework bans legacy plasticizers in polypropylene formulations, forcing costly reformulation of established product lines.
- Melamine resin substitution threat:Cost-conscious educational institutions in South Asia are migrating to melamine alternatives for non-reactive classroom demonstrations.
Strategic Opportunities
- India's laboratory infrastructure buildout:Central government funding for IISER and AIIMS campuses is creating demand for ISO-certified borosilicate glassware.
- Digital inventory integration:RFID-embedded beakers enabling real-time tracking within laboratory information management systems are capturing premium positioning.
- Autoclavable polymer innovation:Next-generation polypropylene copolymers withstand repeated sterilization cycles, opening surgical and clinical research applications.
Industry Challenges
- Metrology technician scarcity:Accurate volume calibration to within five percent requires specialized personnel that institutional buyers struggle to retain.
- Dual certification complexity:Divergent U.S. EPA leachate testing and EU REACH substance restrictions force parallel validation workflows for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stackable Beaker Market |
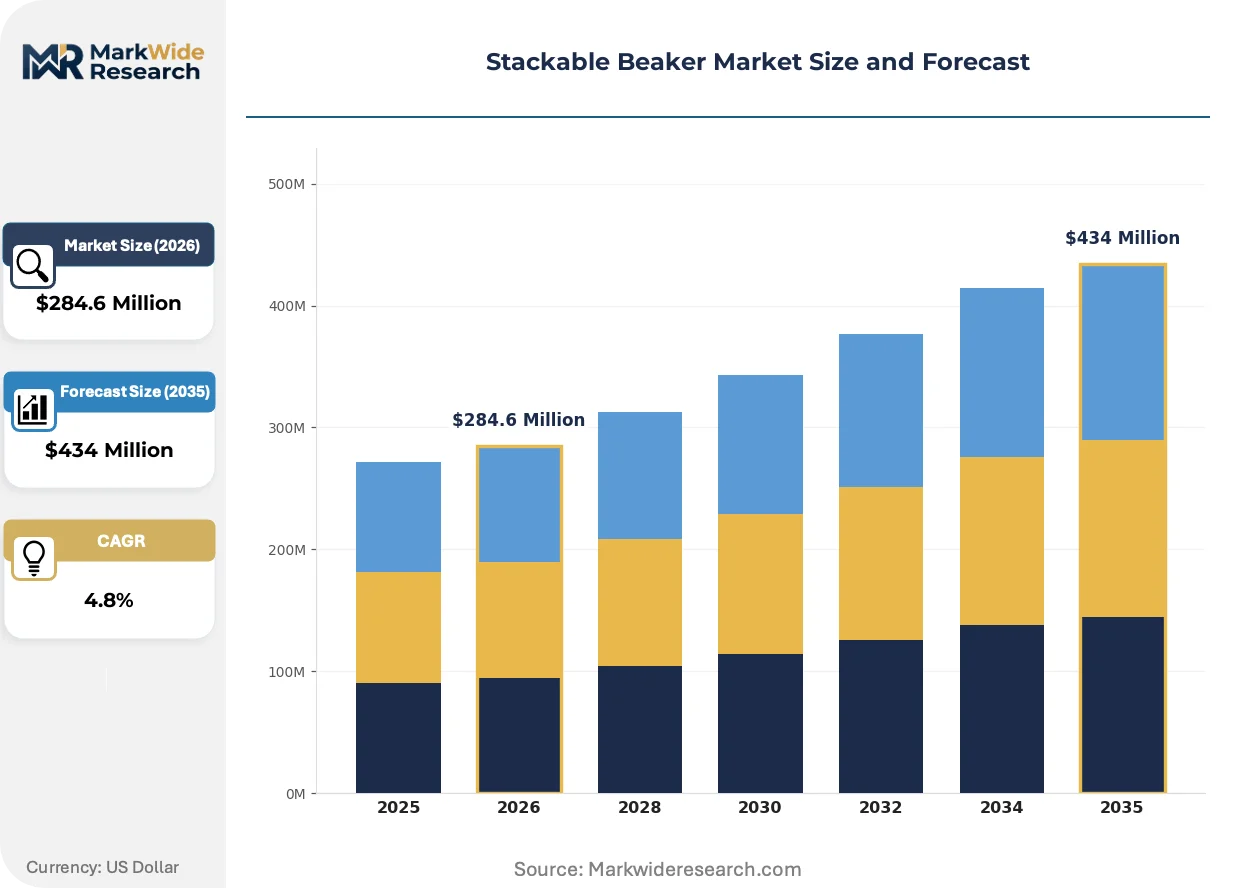
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $434 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Melamine, Polypropylene Size: 50ml, 100ml, 250ml, 500ml End User: Laboratories, Educational Institutions, Research Facilities, Home Use Application: Chemical Analysis, Biology Experiments, Cooking, Crafting |
| Companies Covered | Corning Incorporated, DWK Life Sciences, Thermo Fisher Scientific, Pyrex, Sartorius AG, Thomas Scientific, Kimble Chase, Borosil, Bel-Art Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stackable Beaker Market Evolving Landscape
Material science advances and digital traceability requirements are converging to redefine how laboratories source, track, and retire consumable vessels. Suppliers are racing to embed compliance documentation directly into product design.
Graduated polypropylene beakers with laser-etched volume markings are absorbing demand from traditional molded-scale alternatives in molecular biology facilities. Academic core labs and CROs are standardizing on these vessels to eliminate parallax reading errors during high-throughput screening. The technology is absorbing market share previously held by glass in applications where thermal shock resistance is secondary to disposability.
The EU REACH framework is tightening restrictions on phthalate plasticizers and short-chain chlorinated paraffins in laboratory plastics. Manufacturers serving European pharmaceutical and environmental testing labs must reformulate resin compositions or surrender market access. German analytical chemistry departments are accelerating validation of alternative polymer grades to maintain compliance continuity.
Consolidated procurement through group purchasing organizations is displacing direct vendor relationships for mid-sized research institutions. University systems in the United States are centralizing labware acquisition through shared services entities that mandate calibrated-certificate inclusion. This behavioral shift is most pronounced in public university clusters where state procurement rules favor pre-qualified supplier pools.
Stackable Beaker Market Segmentation
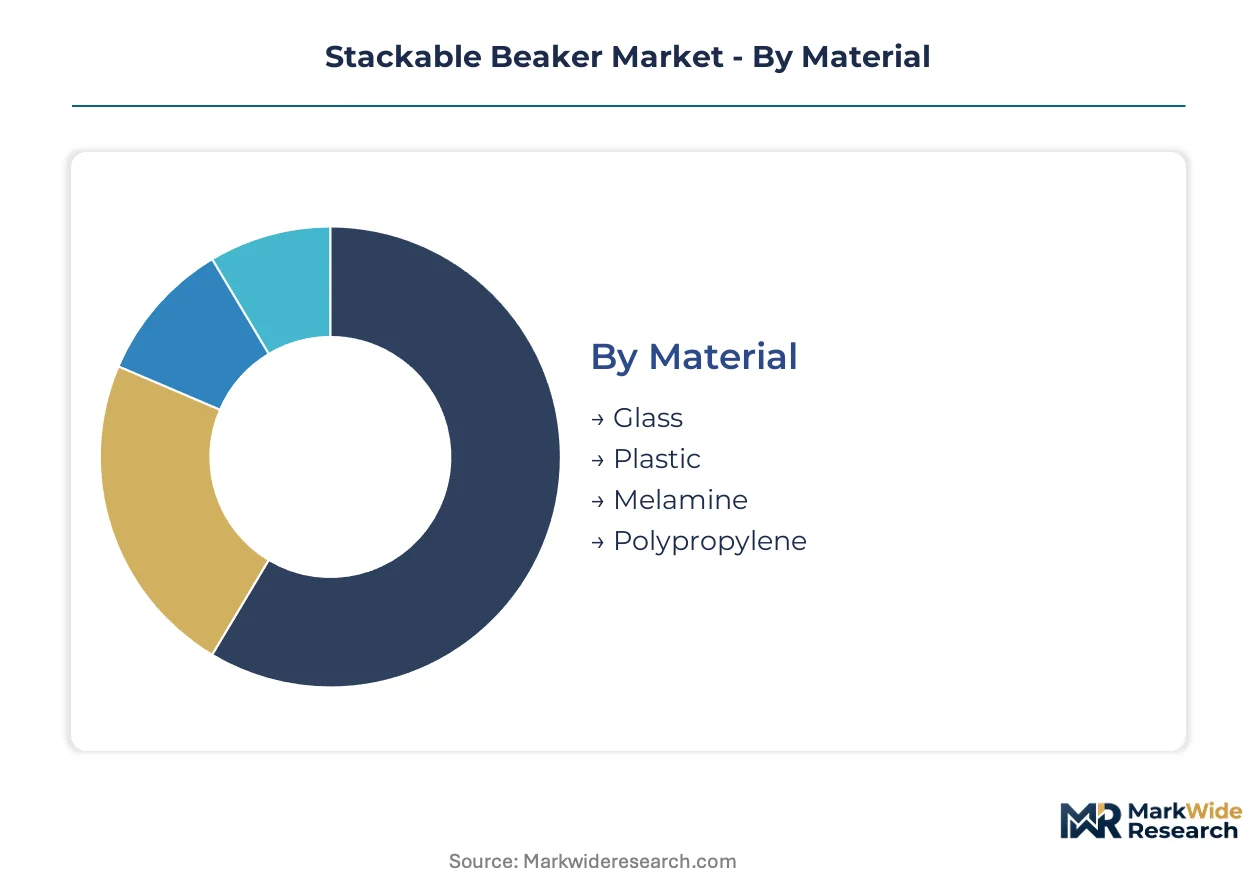
Material composition and volume calibration precision dictate procurement patterns across pharmaceutical, academic, and clinical workflows. Segmentation reveals where disposable polymer solutions displace traditional glassware and which vessel specifications align with automated liquid-handling systems.
Material:
Standalone beakers dominate analytical chemistry where thermal shock resistance mandates dedicated glass vessels, while embedded polymer systems integrate with automated workflow platforms.
- Glass:Borosilicate formulations withstand repeated autoclave cycles and thermal shock from direct flame heating. German analytical chemistry departments and U.S. pharmaceutical QC labs specify glass for titration and gravimetric analysis where volumetric accuracy within five percent is mandatory. FDA biocompatibility exemptions for glass accelerate replacement cycles in cell culture applications where plastic leachate risks contaminate outcomes.
- Polypropylene:Copolymer grades resist acids, bases, and organic solvents while enabling cost-effective disposability. Genomics facilities in Shanghai and Boston scale polypropylene consumption to match automated liquid-handling throughput, with 250ml and 500ml sizes aligning with standard reagent preparation protocols. REACH phthalate restrictions force European suppliers to reformulate resin compositions or surrender market access.
- Plastic:General-purpose thermoplastics serve educational demonstrations and non-reactive solution preparation where thermal stability is secondary to cost.
- Melamine:Formaldehyde resin formulations occupy price-sensitive classroom segments in South Asia for non-reactive chemistry demonstrations.
Polypropylene leads volumes today; glass is gaining share fastest in certified analytical applications.
Size:
Volume selection tracks solution preparation scale, with mid-range capacities capturing institutional procurement and specialized small formats serving microfluidic workflows.
- 250ml:The workhorse specification for standard solution preparation in academic core labs and CRO titration workflows. German university systems and U.S. public research institutions standardize on this capacity for reagent batching that feeds downstream analytical instruments.
- 500ml:Bulk preparation vessels for media formulation and buffer production in bioprocessing facilities. China's expanding pharmaceutical R&D clusters in Suzhou import certified 500ml glass beakers for scale-up chemistry where traceability documentation accompanies each vessel.
- 50ml:Micro-scale vessels for precious reagent handling and pediatric clinical sample processing.
- 100ml:Intermediate capacity for educational demonstrations and small-batch qualitative analysis.
250ml leads volumes today; 500ml is gaining share fastest in bioprocessing expansion.
End User:
Customer type determines certification requirements, with regulated laboratories mandating calibrated-certificate inclusion while educational buyers prioritize cost containment.
- Laboratories:Pharmaceutical QC, environmental testing, and clinical diagnostics facilities require ISO-certified volumetric accuracy and batch traceability. U.S. group purchasing organizations now mandate calibration documentation as standard contract terms rather than optional add-ons.
- Research Facilities:Academic core labs and CROs standardize on laser-etched graduated vessels to eliminate parallax reading errors during high-throughput screening campaigns.
- Educational Institutions:Secondary schools and undergraduate chemistry programs in India and Southeast Asia migrate toward melamine alternatives for classroom demonstrations.
- Home Use:Hobbyist crafters and home brewing enthusiasts drive marginal demand for decorative and utilitarian nesting vessels.
Laboratories lead volumes today; research facilities are gaining share fastest through CRO consolidation.
Application:
Use case specificity determines material selection, with reactive chemistry demanding thermal resistance and biological workflows prioritizing disposability.
- Chemical Analysis:Gravimetric determination, titration, and sample digestion require borosilicate thermal shock resistance. German and Czech glass manufacturers anchor supply for European analytical chemistry departments despite natural gas price volatility squeezing margins.
- Biology Experiments:Cell culture media preparation and molecular biology workflows favor disposable polypropylene to eliminate cross-contamination. FDA ISO 10993 biocompatibility mandates drive replacement cycles for non-compliant plastic inventory.
- Cooking:Precision kitchen applications for molecular gastronomy and recipe development utilize nested storage efficiency.
- Crafting:Resin mixing and pigment blending drive demand for graduated vessels in artisanal manufacturing.
Chemical analysis leads volumes today; biology experiments are expanding most quickly through genomics facility buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration tracks regulatory cost differentials, with European glass producers absorbing REACH compliance burdens while Asian polymer fabricators capture volume through reformulation flexibility. Laboratories in high-compliance jurisdictions pay premiums for certified traceability; price-sensitive educational buyers in emerging markets favor uncertified alternatives.
United States
Pharmaceutical R&D clusters in Boston and San Francisco drive calibrated glassware procurement for analytical chemistry workflows. FDA ISO 10993 biocompatibility mandates accelerate replacement cycles for plastic labware inventory in cell culture applications. University systems in California and Texas centralize procurement through shared services entities that mandate calibration documentation as standard contract terms.
Germany
Analytical chemistry departments at Max Planck institutes and technical universities specify borosilicate beakers for gravimetric analysis requiring thermal shock resistance. ECHA REACH restrictions on phthalate plasticizers force polymer suppliers to reformulate resin compositions for European market access. Glass manufacturing concentrates in Bavaria and Saxony despite natural gas price volatility compressing margins for heat-resistant production.
China
Domestic biotech clusters in Shanghai and Suzhou import certified glass beakers for scale-up chemistry applications requiring traceability documentation. The National Medical Products Administration aligns biocompatibility testing protocols with international standards for labware contacting pharmaceutical preparations. Yangtze River Delta pharmaceutical R&D facilities expand automated liquid-handling platforms that consume disposable polypropylene vessels at high throughput.
India
Central government funding for IISER and AIIMS campuses creates institutional demand for ISO-certified borosilicate glassware in research infrastructure buildouts. The Bureau of Indian Standards mandates calibration accuracy thresholds for laboratory vessels used in official testing protocols. Educational institutions in Maharashtra and Karnataka migrate toward melamine alternatives for undergraduate chemistry demonstrations where cost containment dominates specification.
Japan
Precision manufacturing quality culture sustains premium positioning for calibrated labware in pharmaceutical QC and clinical diagnostics applications. The Ministry of Economy, Trade and Industry promotes standardization of laboratory information management systems that integrate RFID-embedded consumables for real-time inventory tracking. Industrial R&D facilities in Osaka and Nagoya specify autoclavable polymer grades for surgical and clinical research sterilization protocols.
Stackable Beaker Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium analytical chemistry applications consolidating around certified suppliers while educational markets fragment across price-driven alternatives. The vendor landscape organizes into three functional tiers: multinational life science conglomerates bundling labware with instrumentation, regional glass specialists leveraging localized manufacturing, and polymer converters serving disposable workflow demand. Dominant competitive moves include strategic partnerships with group purchasing organizations and geographic expansion through distribution licensing.
Among diversified life science conglomerates, Thermo Fisher Scientific and Corning Incorporated occupy positions exemplifying deep integration with laboratory information management systems. DWK Life Sciences represents the European manufacturing archetype, sustaining long-term supply agreements through regional production proximity. Borosil anchors the price-sensitive specialist tier, serving South Asian educational and institutional segments through localized borosilicate glass fabrication.
| Leading Market Players |
|---|
| Corning Incorporated |
| DWK Life Sciences |
| Thermo Fisher Scientific |
| Pyrex |
| Sartorius AG |
| Thomas Scientific |
| Kimble Chase |
| Borosil |
| Bel-Art Products |
| Others |
Value Network & Pricing Analysis
Academic and pharmaceutical procurement consolidation around group purchasing organizations concentrates buyer power into fewer contract negotiations. This concentration forces tiered pricing structures that separate ISO-certified premium vessels from uncertified economy alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta polymer fabrication hubs are reshaping price floors for disposable polypropylene beakers. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and calibration documentation inclusion. Cost compression in economy-tier melamine alternatives is intensifying because educational institutions in South Asia prioritize cost containment over traceability. Research facilities demonstrate least price sensitivity due to mandated calibration requirements.
Supply Chain Analysis
Specialized metrology technicians in Germany and Czechia glass manufacturing regions constrain calibration throughput for certified vessels. Geographic supply concentrates in Germany for borosilicate glass, China for polypropylene resin conversion, and India for localized educational glassware. Raw material dependencies draw from high-purity silica sand, propylene feedstocks, and phthalate-free plasticizer formulations. Single-source vulnerability sits with European natural gas pricing for heat-resistant glass production. Distribution runs through laboratory supply distributors and group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stackable beaker procurement is shifting toward premium specifications as ISO 10993 biocompatibility mandates eliminate non-compliant inventory from regulated laboratories.
For Market Incumbents: Cement long-term supply agreements with institutional buyers through bundled calibration certification services. Defend against melamine substitution in educational segments by demonstrating total cost of ownership advantages in durability. Capacity addition in Indian borosilicate manufacturing anchors regional cost positioning against European energy volatility. For New Entrants and Emerging Players: Capture white-space demand in India's IISER and AIIMS campus buildouts where ISO-certified glassware procurement outpaces established supplier relationships. Target RFID-embedded beaker segments where laboratory information management system integration commands premium positioning. Pursue distribution licensing partnerships with existing laboratory supply channels rather than direct institutional sales. For Investors and Strategic Acquirers: Life science conglomerates seeking consumables portfolio expansion are the most active acquirer in this space. Five-to-ten-year viability rests on regulatory compliance service capabilities rather than commodity vessel production. Acquisition target archetypes include regional calibration service providers and polymer reformulation specialists. Signal to monitor: divergence between U.S. EPA leachate testing and EU REACH substance restrictions forcing parallel validation workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Bundling | Group purchasing organizations now mandate ISO-certified documentation as standard contract terms. |
| Polymer Reformulation Investment | REACH phthalate restrictions force resin composition changes for European pharmaceutical lab access. |
| RFID Embedding Development | Laboratory information management system integration enables real-time consumable tracking premiums. |
| Regional Manufacturing Expansion | Indian government funding for research infrastructure creates certified glassware demand clusters. |
| Autoclavable Polymer Innovation | Next-generation polypropylene copolymers open surgical sterilization applications in clinical research. |
Research Methodology
Bottom-up laboratory procurement modeling reconciled against top-down resin and glass production tracking forms the analytical core. Primary interviews with laboratory procurement managers, metrology calibration technicians, polymer R&D directors, and group purchasing organization contract officers combined with secondary validation from FDA ISO 10993 guidance documents, ECHA REACH substance restriction updates, customs trade data, and university shared services procurement disclosures. Triangulation between end-use consumption patterns and manufacturing capacity utilization ensures statistical integrity.
Input-output matrices map material flow from silica sand and propylene feedstocks through fabrication to institutional end-use across the analysis window. Segmentation dimensions include material composition, volume capacity, end-user type, and application specificity. CAGRs derive from regression analysis against pharmaceutical R&D expenditure trends and academic research infrastructure investment cycles. Forecast inputs incorporate natural gas pricing volatility for European glass manufacturing and polymer reformulation cost curves for REACH compliance.
Regulatory divergence between U.S. EPA and EU testing protocols, energy price volatility in borosilicate production regions, and metrology technician scarcity are the dominant revision risks. Forecasts reflect documented assumptions on procurement consolidation trajectories and compliance timeline adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Bottled Water Packaging Market