
 Cardboard Flask Market | 2026-2036
Cardboard Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Cardboard Flask Market Outlook
Aftermarket customization revenue is reconfiguring margin pools across the cardboard flask value chain. Tetra Pak International S.A. leverages its aseptic coating heritage to anchor premium insulated formats. SIG Combibloc Group AG competes through precision die-cutting capabilities that reduce material waste. Elopak AS specializes in gable-top adaptations for spirits brands seeking shelf differentiation.
A cardboard flask is a rigid paperboard container engineered with polymer or aluminum barrier layers to hold alcoholic and non-alcoholic beverages, typically featuring heat-sealed seams and pour spouts rated for liquid containment up to 90 days. The primary commercial purpose centers on replacing glass and plastic bottles in outdoor, event, and travel contexts where weight reduction and shatter resistance command priority. Double wall configurations capture the dominant share of food service procurement due to superior thermal retention during transport. Custom shapes represent the fastest-expanding category as liquor marketers commission asymmetric silhouettes for limited-release campaigns. Insulated variants retain concentrated margin pools where restaurants and caterers pay premiums for temperature stability across multi-hour events.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications jointly determine barrier material approvals and recyclability claims across the Atlantic trade corridor. BIS certification requirements in India restrict uncoated fiber ingress for alcoholic beverages, redirecting export-oriented producers toward laminated constructions. Stakeholders must monitor how extended producer responsibility fee structures in the EU and pending state-level packaging legislation in California reshape total cost of ownership for brand owners evaluating format conversions.
Market Dynamics
Extended producer responsibility fee structures across the Atlantic trade corridor are forcing brand owners to internalize end-of-life costs previously externalized to municipal waste systems, compressing the total cost of ownership calculus for format conversion decisions.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightened material compliance timelines accelerate fiber-based liquor packaging pilots in Germany as beverage brands seek pre-approved formats ahead of enforcement deadlines.
- Insulated double-wall configurations:Restaurants and caterers in North America expand procurement of temperature-stable variants for multi-hour outdoor events where thermal retention commands premium pricing.
- Aluminum barrier lamination:BIS certification requirements in India redirect export-oriented producers toward laminated constructions that satisfy food-contact substance notifications for alcoholic beverages.
Market Restraints
- Polymer resin input volatility:Heat-seal coating formulations depend on ethylene-based polymers subject to petrochemical price swings that compress margin predictability for converters.
- Barrier technology concentration:Aseptic coating expertise resides with a limited supplier base in Scandinavia, creating single-source risk for brands seeking 90-day liquid containment ratings.
- Glass bottle substitution resilience:Premium spirits segments retain glass for perceived quality signaling, limiting cardboard flask penetration in high-margin gift and collector categories.
Strategic Opportunities
- Custom asymmetric silhouettes:Liquor marketers commission limited-release campaigns using die-cut shapes that command shelf differentiation and social media amplification.
- California state-level packaging legislation:Pending extended producer responsibility frameworks create first-mover advantage for brands with pre-certified recyclable formats ahead of 2027 implementation.
- Gable-top spirits adaptations:Outdoor music festivals and sporting venues adopt pour-spout configurations that reduce serving labor and eliminate breakage liability.
Industry Challenges
- Heat-seal technician scarcity:Precision calibration of polymer barrier layers requires specialized operators whose training pipelines lag demand from expanding converter capacity.
- Multi-material separation infrastructure:Municipal recycling systems lack fiber-aluminum-polymer de-lamination capabilities, complicating recyclability claims and EPR fee calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardboard Flask Market |
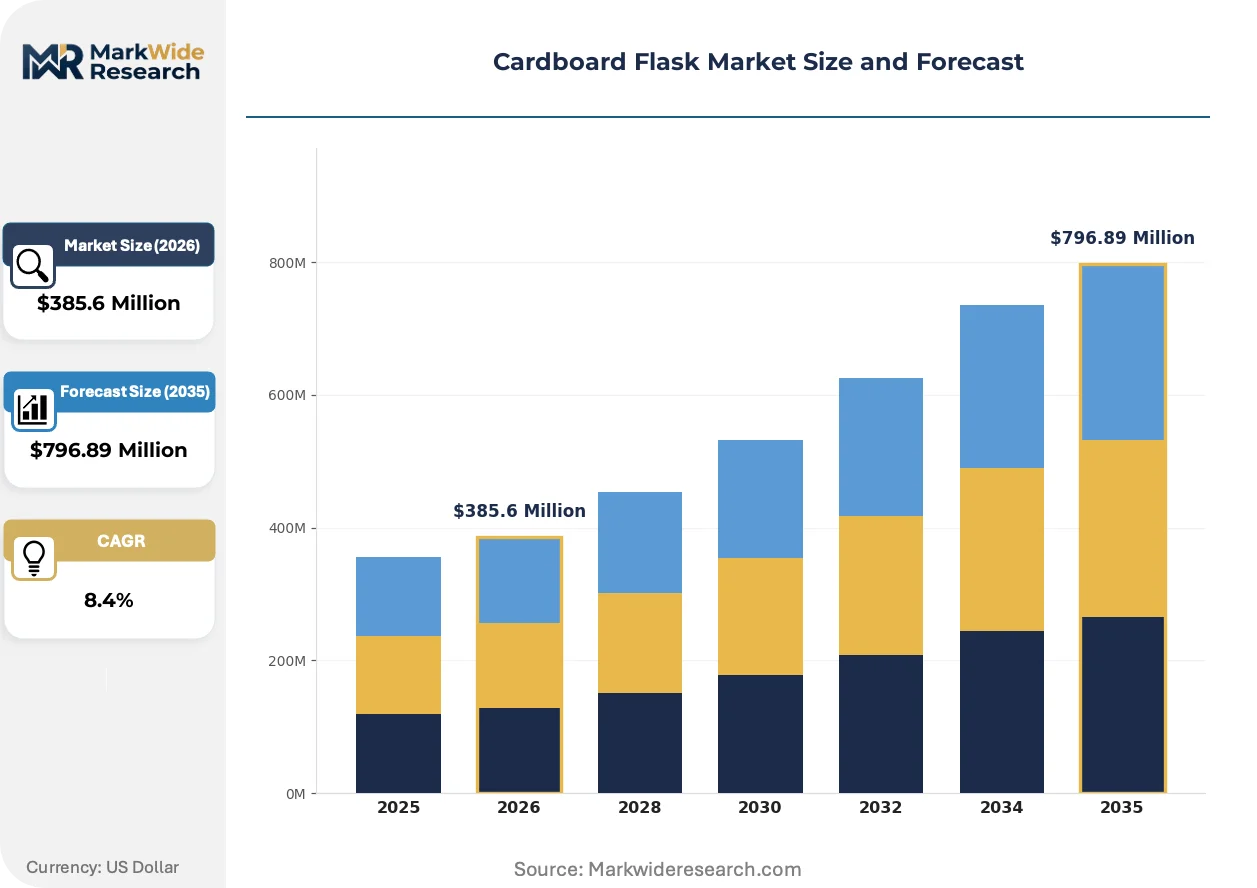
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Custom Shapes Application: Food & Beverage, Party Supplies, Promotional Items, Retail Packaging Feature: Recyclable, Biodegradable, Lightweight, Customizable End User: Restaurants, Caterers, Event Planners, Retailers |
| Companies Covered | Sanex Packaging Connections, DPS Packaging, Pirsq, Green Indya Enterprises, Paxlander, Bell Printers, Tetra Pak International S.A., SIG Combibloc Group AG, Elopak AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardboard Flask Market Strategic Shifts
Barrier coating chemistry and forming equipment are converging to collapse the performance gap between fiber-based containers and conventional glass or plastic formats. Three developments dominate competitive positioning.
Water-based polymer dispersion coatings are collapsing the cost premium historically attached to aseptic liquid containment. Outdoor equipment retailers and festival operators adopt these formats for private-label hydration and spirits portfolios, compressing the payback period for converter equipment upgrades from five years to under three.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from European food-contact applications. Converters pivot to cellulose nanofibril alternatives, with German beverage brands absorbing 15-20% material cost premiums to maintain EU market access ahead of 2025 enforcement milestones.
Bulk purchasing consortia among independent restaurants are consolidating procurement of insulated variants previously sourced through fragmented distributor networks. Caterers in Texas and Florida coordinate direct mill relationships, compressing channel margins and accelerating specification of double-wall configurations for destination wedding and corporate event verticals.
Cardboard Flask Market Segmentation
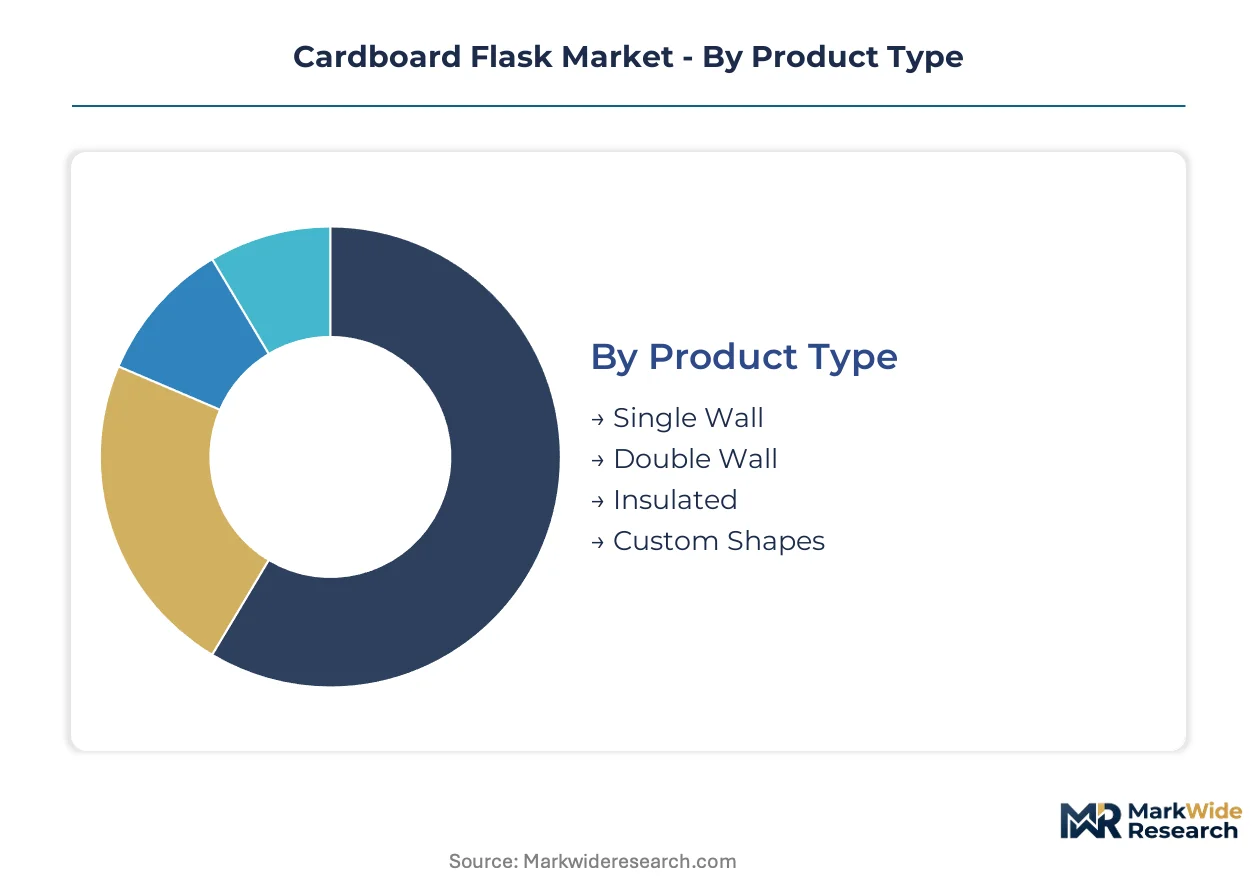
Cardboard flask procurement patterns diverge sharply across thermal performance tiers, use-case contexts, and buyer sophistication levels. Format selection directly determines barrier material requirements, equipment amortization schedules, and extended producer responsibility fee exposure for brand owners.
Product Type:
Cost tier stratification separates commodity converters from premium insulated specialists through material stack complexity and calibration precision.
- Single Wall:One-layer fiberboard construction with basic polymer heat-seal coating achieves lowest unit economics for high-volume spirits sampling campaigns. Demand concentrates in Texas and Florida where independent restaurants source direct from mills to compress distributor margins.
- Double Wall:Dual fiberboard layers with trapped air space deliver thermal retention without aluminum barrier lamination. Restaurants and caterers across Germany and the US expand procurement for multi-hour outdoor events where temperature stability commands premium positioning.
- Insulated:Aseptic coating heritage from Scandinavian suppliers enables 90-day liquid containment ratings. Margin pools concentrate here as North American food service operators absorb material cost premiums for liability reduction in festival and sporting venue deployments.
- Custom Shapes:Die-cut asymmetric silhouettes commissioned by liquor marketers for limited-release campaigns. German beverage brands pilot fiber-based formats at scale to preempt EU Packaging and Packaging Waste Regulation enforcement timelines.
Double wall configurations command the established base. The steepest expansion runs through custom shapes.
Application:
Application context dictates barrier specification stringency, from casual single-serve to regulated alcoholic beverage containment.
- Food & Beverage:Primary commercial deployment centers on alcoholic and non-alcoholic liquid containment with FDA food-contact substance notification compliance. BIS certification requirements in India redirect export-oriented producers toward laminated constructions satisfying 90-day shelf stability.
- Party Supplies:Short-duration use permits lighter coating specifications and compressed lead times. Outdoor music festivals in California adopt pour-spout configurations ahead of pending state-level extended producer responsibility frameworks.
- Promotional Items:Branded sampling formats prioritize unit cost minimization over thermal performance. REACH substance restrictions on per- and polyfluoroalkyl substances eliminate legacy grease-resistant chemistries from European promotional deployments.
- Retail Packaging:Shelf differentiation drives gable-top adaptations and custom print finishes. Retailers coordinate bulk purchasing consortia to consolidate procurement previously fragmented across distributor networks.
Food and beverage applications anchor volume. Retail packaging is climbing the fastest as spirits brands seek glass substitution in gift categories.
Feature:
Environmental claim verifiability is reshaping coating chemistry selection and recyclability certification requirements.
- Recyclable:Multi-material separation infrastructure limitations complicate fiber-aluminum-polymer de-lamination claims. Municipal recycling system gaps force conservative labeling and elevated EPR fee calculations across the Atlantic trade corridor.
- Biodegradable:Cellulose nanofibril alternatives absorb 15-20% material cost premiums as converters pivot from legacy chemistries. German beverage brands absorb these premiums to maintain EU market access ahead of enforcement milestones.
- Lightweight:Weight reduction metrics command priority in outdoor, event, and travel contexts where transport cost and shatter resistance outweigh perceived quality signaling.
- Customizable:Precision die-cutting capabilities reduce material waste while enabling asymmetric silhouettes. SIG Combibloc Group AG competes through this capability to capture limited-release campaign specifications.
Recyclable features command the established base. Biodegradable specifications are gaining share fastest as REACH deadlines approach.
End User:
Customer type determines order scale, specification complexity, and direct mill relationship potential.
- Restaurants:Bulk purchasing consortia among independent operators consolidate procurement of insulated variants. Texas and Florida caterers coordinate direct mill relationships to compress channel margins for destination wedding verticals.
- Caterers:Multi-hour event thermal retention requirements drive double-wall specification at premium pricing. FDA food-contact substance notifications govern barrier material selection for alcoholic beverage service.
- Event Planners:Outdoor music festivals and sporting venues prioritize pour-spout configurations that reduce serving labor and eliminate breakage liability. Gable-top spirits adaptations capture this demand.
- Retailers:Private-label hydration and spirits portfolios compress payback periods for converter equipment upgrades. Water-based polymer dispersion coatings enable adoption timelines under three years.
Restaurants command the established base. Event planners represent the steepest expansion trajectory as festival operators seek liability reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys fiber-based liquor packaging for regulatory pre-emption while Texas and Florida restaurants source direct from mills. India redirects export capacity toward laminated constructions. Scandinavian suppliers anchor premium insulated supply. California festival operators pilot pour-spout formats ahead of state legislation.
United States
Restaurants and caterers across Texas and Florida coordinate bulk purchasing consortia to compress distributor margins for destination wedding verticals. Pending extended producer responsibility frameworks in California create first-mover advantage for pre-certified recyclable formats ahead of 2027 implementation. FDA food-contact substance notifications govern barrier material selection for alcoholic beverage service nationwide.
Germany
Beverage brands pilot fiber-based liquor packaging at scale to preempt EU Packaging and Packaging Waste Regulation enforcement timelines. REACH substance restrictions on per- and polyfluoroalkyl substances eliminate legacy grease-resistant chemistries, forcing converters toward cellulose nanofibril alternatives. The Rhine-Ruhr industrial cluster concentrates aseptic coating expertise among Scandinavian-heritage suppliers serving premium insulated demand.
India
BIS certification requirements redirect export-oriented producers toward laminated constructions satisfying food-contact substance notifications for alcoholic beverages. Domestic demand concentrates in Maharashtra and Gujarat where beverage brands test fiber-based formats for regulatory compliance. The country's national packaging regulator maintains strict uncoated fiber ingress restrictions for spirits applications.
Sweden
Aseptic coating heritage concentrates among limited suppliers whose 90-day liquid containment ratings command premium positioning across Atlantic trade corridors. Stockholm and Malmö industrial zones anchor barrier technology development for insulated variants. Extended producer responsibility fee structures in adjacent EU markets amplify demand for pre-certified formats from Swedish converters.
Canada
Outdoor equipment retailers adopt water-based polymer dispersion coatings for private-label hydration portfolios, compressing payback periods for converter equipment upgrades. Health Canada food-contact notifications align with FDA frameworks, enabling cross-border format standardization. Ontario-based caterers coordinate procurement of double-wall configurations for multi-hour corporate events.
Cardboard Flask Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Aseptic coating expertise resides with Scandinavian specialists whose heritage technology commands premium positioning, while volume converters compete through precision die-cutting and material waste reduction. Three archetypes dominate: barrier technology specialists, precision forming fabricators, and integrated packaging conglomerates. Competitive moves center on strategic partnerships for regulatory pre-certification and capacity expansion in insulated formats.
Among heritage-technology specialists, Tetra Pak International S.A. and SIG Combibloc Group AG occupy positions defined by aseptic coating lineage and precision forming capabilities respectively. Elopak AS sits within the gable-top adaptation tier, representing specialists in spirits-format shelf differentiation. These three exemplify how Scandinavian-origin expertise anchors premium insulated supply while competing through distinct technical specializations rather than overlapping capability claims.
| Leading Market Players |
|---|
| Sanex Packaging Connections |
| DPS Packaging |
| Pirsq |
| Green Indya Enterprises |
| Paxlander |
| Bell Printers |
| Tetra Pak International S.A. |
| SIG Combibloc Group AG |
| Elopak AS |
| Others |
Value Chain & Pricing Dynamics
Atlantic trade corridor freight volatility transmits cost pressure through Scandinavian aseptic coating supply into downstream price differentiation between insulated premium formats and commodity single-wall alternatives.
Pricing Analysis
Long-term offtake contracts dominate insulated variant procurement as North American food service operators lock in Scandinavian supply capacity ahead of EU Packaging and Packaging Waste Regulation enforcement. Price differentiation rests on certification grade and volume scale, with FDA food-contact substance notification tiers commanding material premiums. Cost compression in single-wall configurations is intensifying because Texas and Florida restaurants coordinate direct mill relationships that bypass distributor markups. Independent caterers exhibit highest price sensitivity, while liquor marketers commissioning custom asymmetric silhouettes absorb premiums for shelf differentiation.
Supply Chain Analysis
Tariff exposure between Germany and Scandinavian barrier technology suppliers dominates supply chain risk calculus for EU-facing producers. Manufacturing gravity centers on Sweden, Germany, and India, with aseptic coating expertise concentrated in Stockholm and Malmö industrial zones. Raw material dependencies draw from ethylene-based polymer resins, cellulose nanofibril alternatives, and aluminum barrier laminations. Single-source vulnerability persists where 90-day liquid containment ratings hinge on limited Scandinavian coating heritage. Distribution runs through bulk purchasing consortia among independent restaurants and direct mill relationships for large-format caterers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU Packaging and Packaging Waste Regulation pre-certification creates defensive moats for incumbent converters with established Scandinavian supply relationships.
For Market Incumbents: Harden barrier technology exclusivity through captive supply of aseptic coating capacity in Rhine-Ruhr industrial clusters. Deepen upstream control over cellulose nanofibril alternatives ahead of REACH per- and polyfluoroalkyl substance enforcement. Water-based polymer dispersion coating adoption by outdoor equipment retailers threatens margin pools in private-label hydration tiers. For New Entrants and Emerging Players: California festival operators and sporting venues represent the most penetrable entry point for pour-spout gable-top configurations ahead of pending state-level extended producer responsibility frameworks. German beverage brands piloting fiber-based liquor packaging at scale offer partnership pathways for laminated construction specialists. Precision die-cutting capabilities reduce material waste and enable asymmetric silhouette commissions from liquor marketers. For Investors and Strategic Acquirers: Scandinavian-heritage barrier technology specialists with 90-day liquid containment ratings anchor long-term viability across the Atlantic trade corridor. Acquisition focus should center on converters with pre-certified recyclable formats and established FDA food-contact substance notification pathways. Watch for BIS certification requirement expansion in India as signal for laminated construction demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EU Packaging and Packaging Waste Regulation compliance locks in brand owner relationships ahead of enforcement deadlines. |
| Backward Integration into Coating Chemistry | Cellulose nanofibril alternative development absorbs REACH-driven material cost premiums for European market access. |
| Direct Mill Relationship Expansion | Texas and Florida caterer consortia compress channel margins and accelerate double-wall specification adoption. |
| Custom Die-Cut Capability Acquisition | Asymmetric silhouette precision captures limited-release campaign specifications from liquor marketers. |
| Water-Based Polymer Dispersion Scale-Up | Outdoor equipment retailer private-label portfolios compress converter equipment upgrade payback periods. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with converter operations directors, brand owner packaging specification leads, food service procurement managers, and regulatory affairs specialists; and secondary validation through EU Packaging and Packaging Waste Regulation filings, FDA food-contact substance notification databases, BIS certification records, and Scandinavian industrial cluster production disclosures. Bottom-up volume triangulation across product type, application, feature, and end user segments converged with top-down macroeconomic anchoring.
Forecast inputs span thermal performance tier adoption curves, barrier material substitution rates, and extended producer responsibility fee structure implementation across the Atlantic trade corridor. Segmentation dimensions modeled include product type complexity, application regulatory stringency, feature environmental claim verifiability, and end user order scale sophistication. CAGRs were derived from trend extrapolation anchored in operating data rather than analyst projection.
Macroeconomic conditions sit as an overlay; deviation in petrochemical input costs, freight rate volatility, or regulatory enforcement timing would shift the trajectory. Forecasts reflect assumptions around REACH substance restriction adherence and municipal recycling infrastructure development. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Beverage Aluminum Cans Market