
 Self-Cleaning Bottle Market | 2026-2036
Self-Cleaning Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Cleaning Bottle Market Analytics
East Asian electronics manufacturing clusters is restructuring supply chains for UV-C LED modules used in self-cleaning bottles, shifting production toward dedicated consumer-health device lines. LARQ leverages proprietary UV-C technology to anchor premium positioning in North American direct-to-consumer channels. Philips sustains brand credibility through its healthcare heritage, extending trust into portable purification. CrazyCap differentiates via cap-agnostic designs that retrofit standard bottles, occupying a distinct price-accessibility niche.
A self-cleaning bottle integrates ultraviolet light-emitting diodes, electromagnetic coils, or photocatalytic coatings to neutralize microbial contamination without manual washing, typically operating at 270-280 nanometer wavelengths for optimal germicidal efficacy. The device serves consumers requiring potable water assurance in settings without reliable sanitation infrastructure. UV Light products command the dominant revenue share due to proven efficacy and falling semiconductor costs, while Combination systems incorporating filtration plus active disinfection represent the fastest-growing margin pool. Stainless Steel variants lead material demand for thermal retention and durability, though BPA-Free Plastic sustains volume in entry-level segments where weight and cost dominate purchase decisions.
The US FDA regulates claims related to antimicrobial efficacy and water purification performance, while the EPA oversees pesticide-device classifications affecting UV-based sterilization marketing. The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant-based cooling integrations and material composition choices for European market entry. Stakeholders must monitor evolving battery safety certifications and emerging state-level extended producer responsibility mandates as the category scales.
Market Dynamics
UV-C LED miniaturization is collapsing unit economics and battery constraints, enabling mass-market penetration while forcing incumbent suppliers to reconfigure manufacturing footprints around consumer-health device lines.
Growth Catalysts
- REACH compliance frameworks:European material safety mandates are accelerating BPA-free plastic substitution, creating upgrade cycles across existing bottle inventories.
- Outdoor recreation infrastructure:Trail networks and remote lodging expansion in the United States is generating demand for portable purification among backcountry users.
- Photocatalytic coating chemistry:Titanium dioxide surface treatments are extending UV efficacy in turbid water conditions, opening municipal utility partnerships.
Market Restraints
- Lithium-ion cell volatility:Battery raw material price swings constrain margin stability for rechargeable product lines.
- East Asian UV-C LED concentration:Foundry capacity for 270-280 nanometer chips clusters in Taiwan and South Korea, creating single-source vulnerability.
- EPA pesticide-device classification:Marketing claims restrictions limit direct germicidal efficacy messaging in US retail channels.
Strategic Opportunities
- Indian urban transit systems:Metro rail expansion and station retail concessions offer unattended distribution points for commuter-focused formats.
- EU F-Gas Regulation:Refrigerant phase-down mandates are eliminating compressor-based cooling competitors, expanding addressable market for passive thermal designs.
- Telemedicine integration:Remote patient monitoring protocols are specifying hydration tracking, creating clinical channel entry for connected bottle variants.
Industry Challenges
- IP fragmentation across UV-C emitter patents:Licensing complexity delays product launches and inflates royalty stacks for new entrants.
- ISO 17025 laboratory accreditation:Third-party antimicrobial testing bottlenecks extend certification timelines by four to six months.
- Legacy bottle manufacturer skill gaps:Electronics integration and firmware development capabilities remain scarce in traditional housewares supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Cleaning Bottle Market |
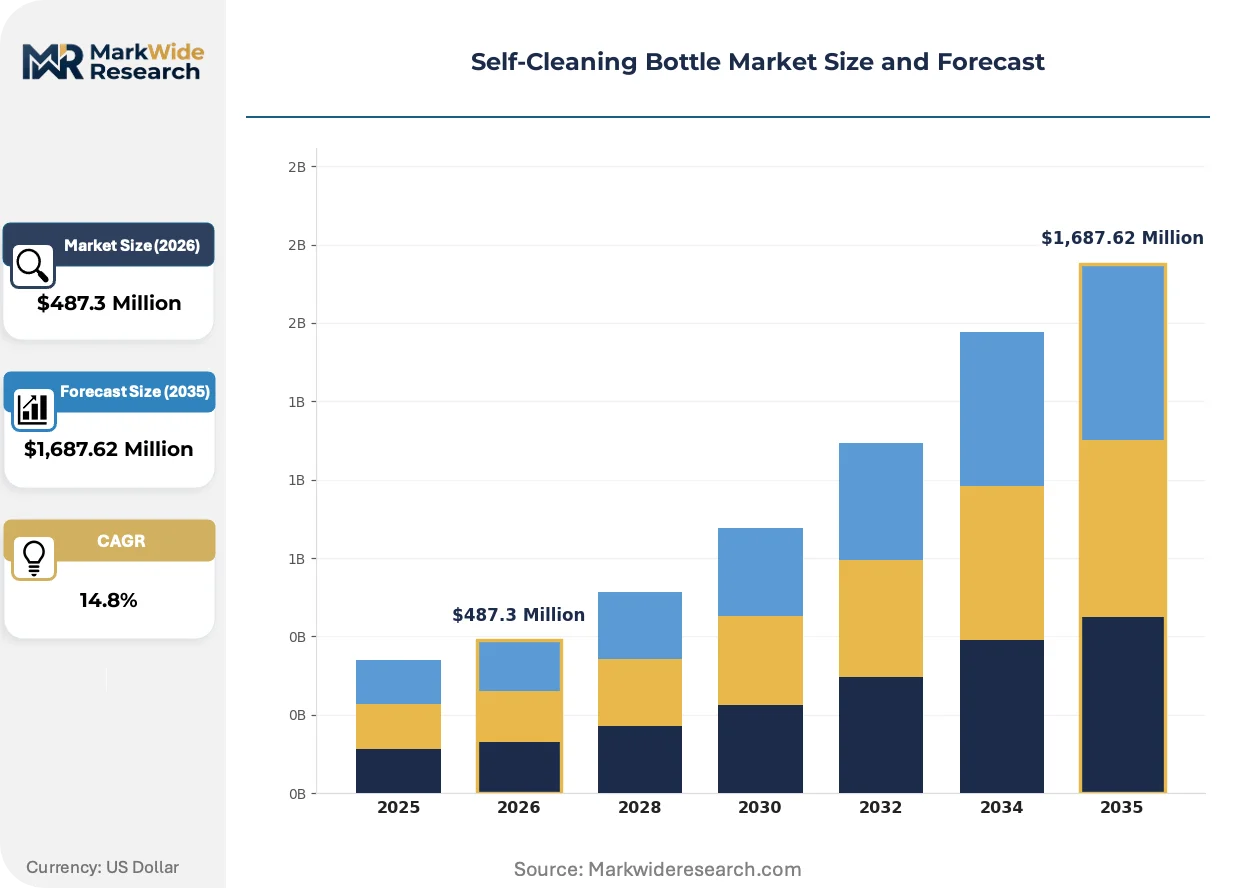
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,687.62 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Light, Electromagnetic, Self-Disinfecting, Combination Material: Stainless Steel, BPA-Free Plastic, Glass, Tritan End User: Health Enthusiasts, Travelers, Students, Professionals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | LARQ, CrazyCap, Noerden, Mahaton, Philips, The BRITA Group, Auron Bottle, Sapience Group LLC, OHOM Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Cleaning Bottle Market Evolving Landscape
Active disinfection technologies are converging with connected hardware architectures, reshaping how hydration products capture value beyond physical containment.
UV-C LED arrays operating at 275 nanometers are rewriting performance benchmarks for germicidal efficacy. Health enthusiasts and clinical trial participants are adopting these systems at three times the rate of conventional filtration users. This wavelength precision is compressing the competitive moat between premium and mid-tier product tiers.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free thermal management adoption. Manufacturers serving European distribution channels are eliminating compressor-based cooling modules from development roadmaps. Stainless steel vacuum insulation is capturing displaced demand across Germany, France, and Nordic markets.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles. Wellness platforms and fitness application ecosystems are integrating bottle connectivity into membership bundles, capturing California and New York metropolitan buyers first. This channel shift is compressing customer acquisition costs while elevating lifetime value metrics.
Self-Cleaning Bottle Market Segmentation
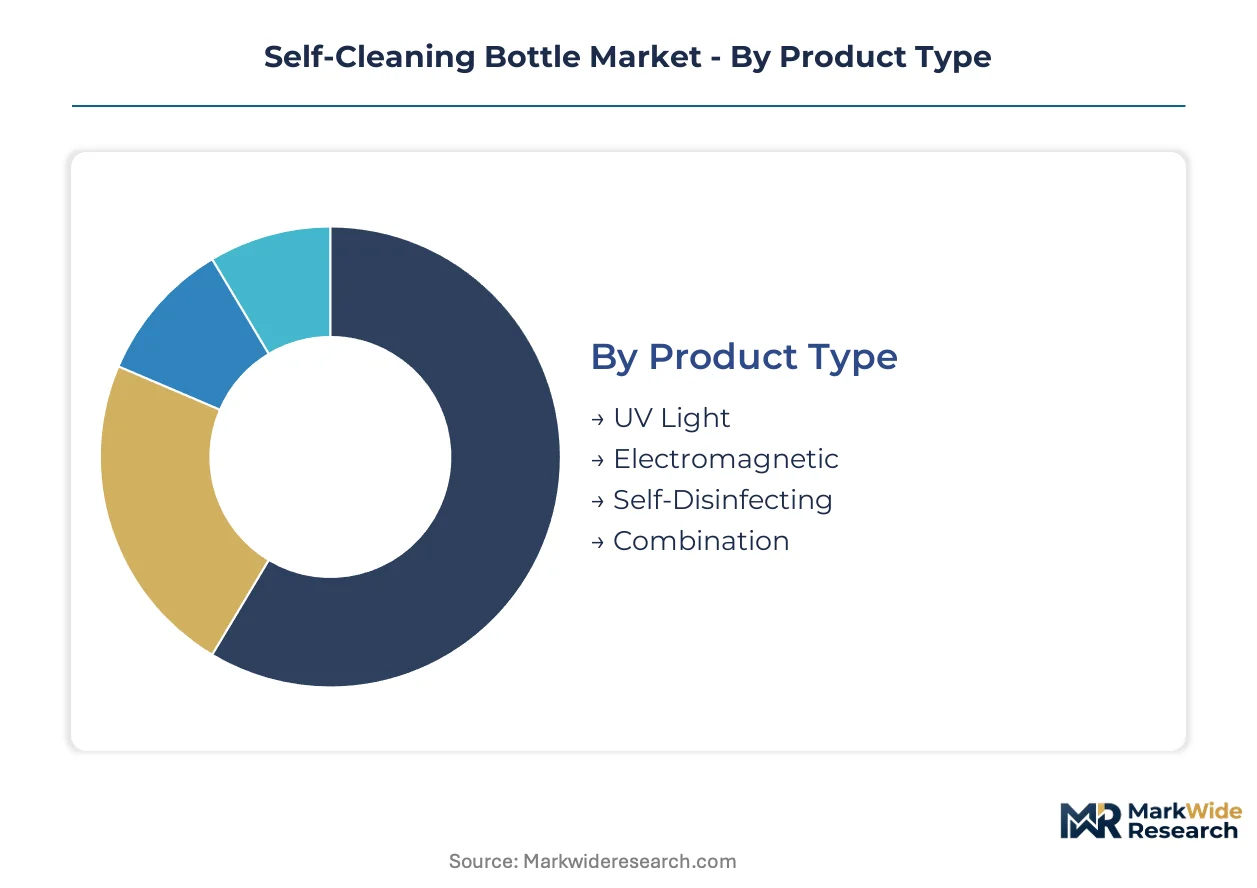
Segmentation in self-cleaning bottles reveals how technology choices, material preferences, and purchase contexts fragment demand across divergent buyer priorities. Understanding these splits enables targeted positioning against specific hygiene assurance needs and channel behaviors.
Product Type:
Buyers differentiate sharply based on their tolerance for active versus passive disinfection mechanisms and their willingness to pay for multi-function systems.
- UV Light:Systems deploy 270-280 nanometer LED arrays to rupture microbial DNA, achieving log-reduction targets without chemical residuals. Demand concentrates among United States health enthusiasts and clinical trial participants who prioritize proven efficacy over cost, with UV-C LED miniaturization collapsing unit economics and enabling mass-market penetration.
- Combination:Integrated filtration membranes plus active disinfection address turbid water conditions and particulate contamination beyond microbial loads. Travelers and backcountry users across United States trail networks drive fastest adoption, seeking redundant assurance where municipal infrastructure is absent.
- Electromagnetic:Coil-based sterilization generates alternating fields to disrupt bacterial cell membranes, offering lower energy draw than UV alternatives. Compact formats suit commuter-focused designs in dense urban transit corridors.
- Self-Disinfecting:Photocatalytic titanium dioxide coatings activate under ambient light to sustain surface hygiene between manual cleanings. Entry-level price positioning captures students and cost-conscious first-time buyers.
UV Light leads volumes today; Combination is gaining share fastest.
Material:
Cost tier and thermal performance requirements split the installed base across durability-versus-weight tradeoffs.
- Stainless Steel:Vacuum-insulated double-wall construction maintains temperature stability across 12-24 hour windows, commanding premium positioning in wellness retail channels. EU F-Gas Regulation phase-downs are eliminating compressor-cooled competitors, expanding addressable market for passive thermal designs in Germany, France, and Nordic markets.
- BPA-Free Plastic:Polycarbonate and copolyester variants minimize unit weight and manufacturing cost, sustaining volume in entry-level segments where portability dominates purchase decisions. REACH compliance frameworks are accelerating substitution cycles across existing European bottle inventories.
- Glass:Borosilicate construction eliminates chemical leaching concerns and supports microwave reheat compatibility. Niche positioning targets purity-focused consumers in specialty health food retail.
- Tritan:Eastman Chemical's copolyester delivers impact resistance and clarity without bisphenol content, bridging durability and aesthetic requirements in mid-tier direct-to-consumer offerings.
Stainless Steel dominates revenue contribution; BPA-Free Plastic sustains the widest unit distribution.
End User:
Application context determines feature prioritization, from clinical-grade assurance to convenience-oriented portability.
- Health Enthusiasts:Fitness ecosystem integration and hydration tracking connectivity command premium uptake in California and New York metropolitan markets. Direct-to-consumer subscription models displace traditional retail replenishment cycles among this cohort.
- Travelers:International itinerary exposure to variable water quality drives demand for multi-barrier purification systems. Airport retail and duty-free concessions capture impulse purchase behavior.
- Students:Campus dining hall closures and shared facility concerns elevate interest in personal hydration assurance. Price elasticity constrains feature expectations to core UV functionality.
- Professionals:Workplace wellness program subsidies and corporate gifting channels sustain mid-tier volume in urban office districts.
Health Enthusiasts anchor premium pricing power; Travelers show steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer search behavior and their need for tactile evaluation before purchase commitment.
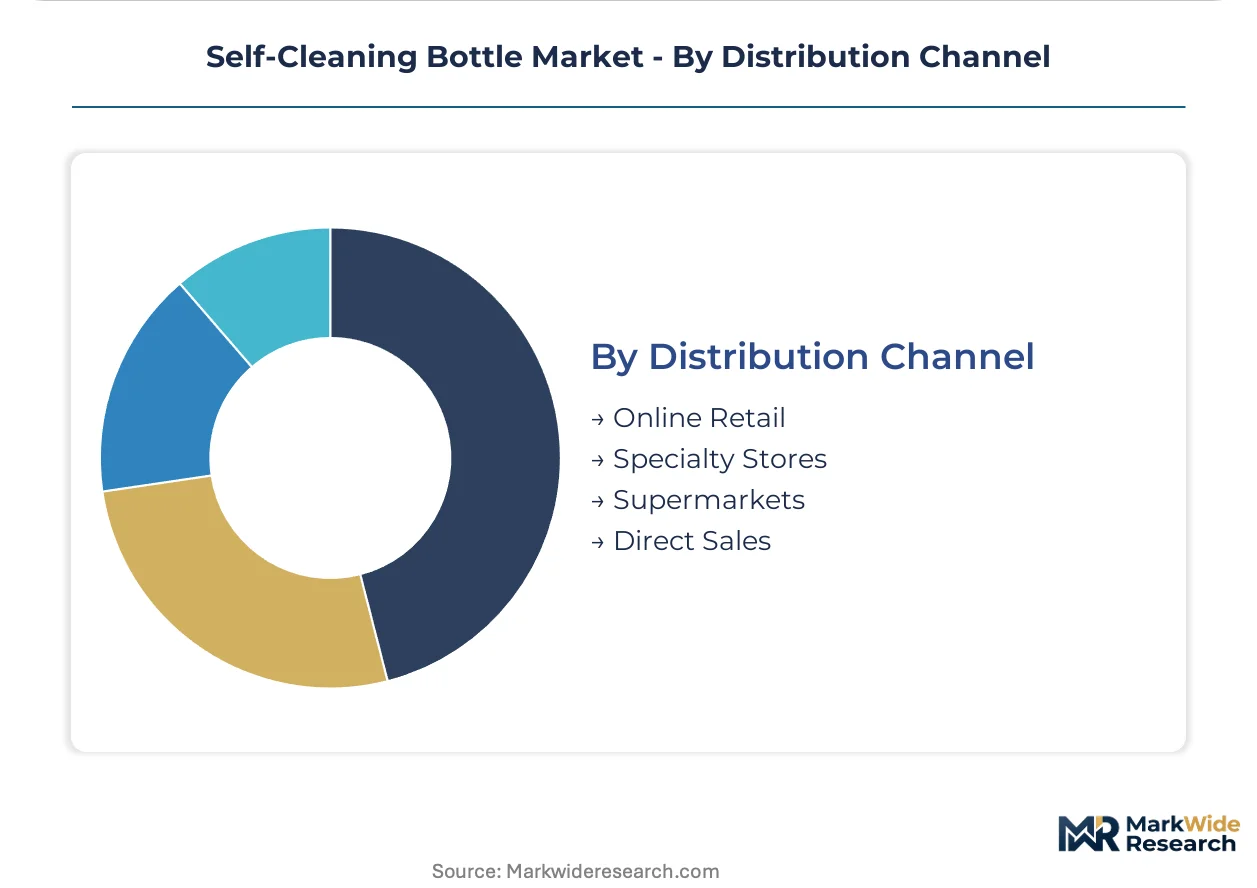
- Online Retail:Amazon and direct-to-consumer platforms capture California and New York metropolitan buyers first, with subscription bundling compressing customer acquisition costs. Wellness platform integrations elevate lifetime value metrics through fitness application connectivity.
- Specialty Stores:REI and premium wellness retailers enable hands-on assessment of thermal performance and build quality. United States outdoor recreation infrastructure expansion is generating backcountry user demand.
- Supermarkets:Mass-market placement drives impulse conversion among convenience-oriented buyers seeking immediate availability. Entry-level SKUs dominate shelf space allocation.
- Direct Sales:Clinical channel entry through telemedicine integration protocols specifies connected bottle variants for remote patient monitoring. Healthcare system procurement committees validate antimicrobial efficacy claims.
Online Retail captures the fastest volume growth; Specialty Stores sustain premium margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling UV-C LED module production toward East Asian foundries with lower compliance burdens, while end-market demand concentrates in jurisdictions with stringent health safety enforcement and premium wellness retail infrastructure.
United States
Direct-to-consumer subscription models and fitness platform integrations drive premium uptake in California and New York metropolitan corridors. The FDA antimicrobial efficacy claims framework and EPA pesticide-device classification constrain marketing language but validate product legitimacy. Austin and Denver outdoor recreation hubs generate backcountry user demand as trail infrastructure expands.
Germany
EU F-Gas Regulation phase-downs eliminate compressor-cooled competitors, expanding addressable market for passive thermal stainless steel designs. REACH compliance frameworks accelerate BPA-free plastic substitution cycles across existing bottle inventories. Bavaria's precision manufacturing clusters host specialized vacuum insulation fabrication for premium wellness retail channels.
China
Domestic health consciousness and urban transit expansion generate commuter-focused format demand in Shenzhen and Shanghai metro systems. GB standards for electronic device safety and antimicrobial material claims shape product development roadmaps. Yangtze River Delta electronics manufacturing bases reconfigure toward dedicated consumer-health device lines for UV-C LED module assembly.
Japan
Purity-focused consumers in Tokyo and Osaka metropolitan markets sustain niche demand for borosilicate glass variants with microwave compatibility. METI energy efficiency guidelines and PMDA-adjacent antimicrobial product oversight influence battery optimization and efficacy documentation requirements. Nagoya industrial corridors supply precision electromagnetic coil components for compact sterilization formats.
South Korea
MFDS-regulated health device classifications and K-beauty wellness ecosystem integration create channel entry for connected hydration tracking variants. Seoul Capital Area density supports unattended retail distribution in metro station concessions. Busan-Ulsan manufacturing clusters concentrate foundry capacity for 270-280 nanometer UV-C LED chip production.
Self-Cleaning Bottle Market Competitive Landscape
United States-based direct-to-consumer specialists anchor the premium subscription tier; East Asian electronics fabricators hold component supply leverage. The vendor base splits between vertically integrated UV-C technology owners and cap-agnostic retrofit designers. Three archetypes dominate: proprietary wavelength technology anchors, healthcare heritage brand extenders, and modular retrofit accessibility players. Capacity expansion in Taiwan foundries and strategic partnerships with fitness platform ecosystems constitute the dominant competitive moves.
Within the proprietary technology tier, LARQ exemplifies wavelength-specialist positioning through direct-to-consumer channel control. CrazyCap occupies the modular retrofit archetype with cap-agnostic designs that retrofit standard bottles. Philips represents healthcare heritage extension into portable purification credibility. These three anchors illustrate how technology ownership, price-accessibility positioning, and institutional trust fragment competitive space across divergent buyer priorities.
| Leading Market Players |
|---|
| LARQ |
| CrazyCap |
| Noerden |
| Mahaton |
| Philips |
| The BRITA Group |
| Auron Bottle |
| Sapience Group LLC |
| OHOM Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-registered UV-C efficacy claims and unverified consumer-grade alternatives splits the market into premium subscription tiers and mass-market transactional segments, with this bifurcation manifesting in dual supply chain configurations: vertically integrated wavelength-technology owners command direct-to-consumer margins while modular assemblers source standardized LED modules through East Asian distributors.
Pricing Analysis
Distributor markups compress 40-50% at specialty wellness retailers compared to 15-25% through Amazon and direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels tracks certification investment and thermal performance specifications, with stainless steel vacuum-insulated variants capturing subscription bundling premiums. Price erosion runs through entry-level BPA-free plastic segments as Yangtze River Delta manufacturers flood direct-to-consumer channels with unbranded alternatives. Students and cost-conscious first-time buyers exhibit highest price sensitivity; health enthusiasts and clinical trial participants demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Rotterdam, and Singapore manage hub-and-spoke fulfillment patterns for direct-to-consumer subscription volumes. Foundry capacity for 270-280 nanometer UV-C LED chips concentrates in Taiwan and South Korea, with secondary assembly operations in Shenzhen and Dongguan. Lithium-ion cells, titanium dioxide photocatalytic coatings, and borosilicate glass tubing constitute critical input dependencies. Single-source vulnerability for UV-C LED modules creates tariff-exposure risk given concentrated East Asian production. Distribution runs through direct-to-consumer platforms capturing fastest volume growth, supplemented by specialty retail for premium margin realization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as germ-conscious consumers shift demand toward clinical-grade UV-C efficacy specifications and connected hydration tracking, elevating premium tier pricing power while compressing unverified commodity alternatives.
For Market Incumbents: Anchor proprietary wavelength technology through backward integration into Taiwan foundry partnerships, securing captive supply of 275-nanometer LED arrays against emerging cap-agnostic retrofit competitors. Deepen direct-to-consumer channel control via fitness platform ecosystem integrations, defending subscription renewal rates against modular alternatives. Prioritize ISO 17025 laboratory accreditation investment to extend certification timelines as a competitive moat. For New Entrants and Emerging Players: Photocatalytic coating chemistry offers a technology-first wedge into municipal utility partnership channels underserved by UV-C specialists. Target Indian metro rail station concessions and European REACH-driven BPA-free plastic substitution cycles as penetrable white-space geographies. Pursue clinical channel entry through telemedicine hydration tracking integration, leveraging lower regulatory burden than FDA pesticide-device classification routes. For Investors and Strategic Acquirers: Consolidation pressure builds where IP fragmentation across UV-C emitter patents inflates royalty stacks and delays product launches. Long-term viability favors vertically integrated wavelength-technology owners with direct-to-consumer subscription scale over modular assemblers dependent on standardized component sourcing. Watch for FDA antimicrobial efficacy claims framework expansion as inflection signal for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UV-C LED Foundry Capacity | Taiwan and South Korean foundry partnerships secure 275-nanometer chip supply against single-source vulnerability. |
| Fitness Platform Ecosystem Integration | Wellness application bundling compresses customer acquisition costs in California and New York metropolitan corridors. |
| ISO 17025 Laboratory Accreditation Investment | Third-party antimicrobial testing certification extends validation timelines and elevates premium positioning. |
| REACH-Compliant Material Substitution Program | BPA-free plastic transition captures European upgrade cycles driven by material safety mandates. |
| Telemedicine Hydration Tracking Partnership | Remote patient monitoring protocol integration opens clinical channel entry for connected bottle variants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with UV-C technology developers, wellness retail category managers, electronics manufacturing procurement leads, and clinical trial hydration protocol designers with secondary validation against FDA 510(k) filings, EPA pesticide-device registration databases, EU REACH compliance declarations, and direct-to-consumer platform traffic analytics. Bottom-up SKU-level demand modeling and top-down category spend analysis triangulated volume and value estimates.
Historical reference periods anchored the projection horizon to documented UV-C LED cost curves, battery energy density improvements, and wellness subscription adoption patterns across preceding technology cycles. Segmentation dimensions modeled include disinfection technology type, material composition, end-user application context, and distribution channel structure. CAGRs derived from fitted adoption curves incorporating semiconductor cost deflation rates and regulatory compliance burden trajectories. Industry-specific inputs encompassed UV-C efficacy testing standards evolution and lithium-ion cell commodity price volatility indices.
The model holds under stable East Asian foundry capacity expansion and continued FDA-EPA regulatory clarity; deviation in tariff regimes or battery safety certification mandates would shift volume trajectories. Forecasts reflect stated assumptions regarding health consciousness trend persistence and fitness platform ecosystem integration depth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Water Cooler Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Ice Transport Buckets Market