
 Biotainer Market | 2026-2036
Biotainer Market Size, Share, and Industry Trends Forecast 2026-2036
Biotainer Market Analysis
Contract development and manufacturing organizations (CDMOs) is rotating toward single-use biotainer systems as biopharma outsources more fill-finish operations. Nalge Nunc International dominates North American laboratory-grade supply through decades of brand authority in precision-molded polymers. Kisker Biotech GmbH & Co. KG anchors European demand with specialized cryogenic-grade containers engineered for cell therapy logistics. Cellon S.A differentiates through ISO-certified cleanroom manufacturing that serves GMP-critical bioprocessing workflows.
A biotainer is a sterile, single-use or multi-use containment vessel engineered from pharmaceutical-grade thermoplastics such as polypropylene or polyethylene, designed to store, transport, or process biological materials without cross-contamination. These vessels typically withstand gamma irradiation sterilization and temperature ranges from cryogenic conditions through standard incubation, serving biopharma manufacturing, clinical diagnostics, and academic research where aseptic integrity determines experimental or therapeutic validity. Single-use bags command the largest volume share as biopharma facilities prioritize elimination of cleaning validation burdens, while cryogenic storage applications generate premium pricing due to specialized multi-layer film constructions required for vapor-phase liquid nitrogen compatibility. Polypropylene leads material selection for its thermal stability and leachables profile, though polyethylene gains ground in cost-sensitive diagnostic segments where shorter contact durations reduce extractables concerns.
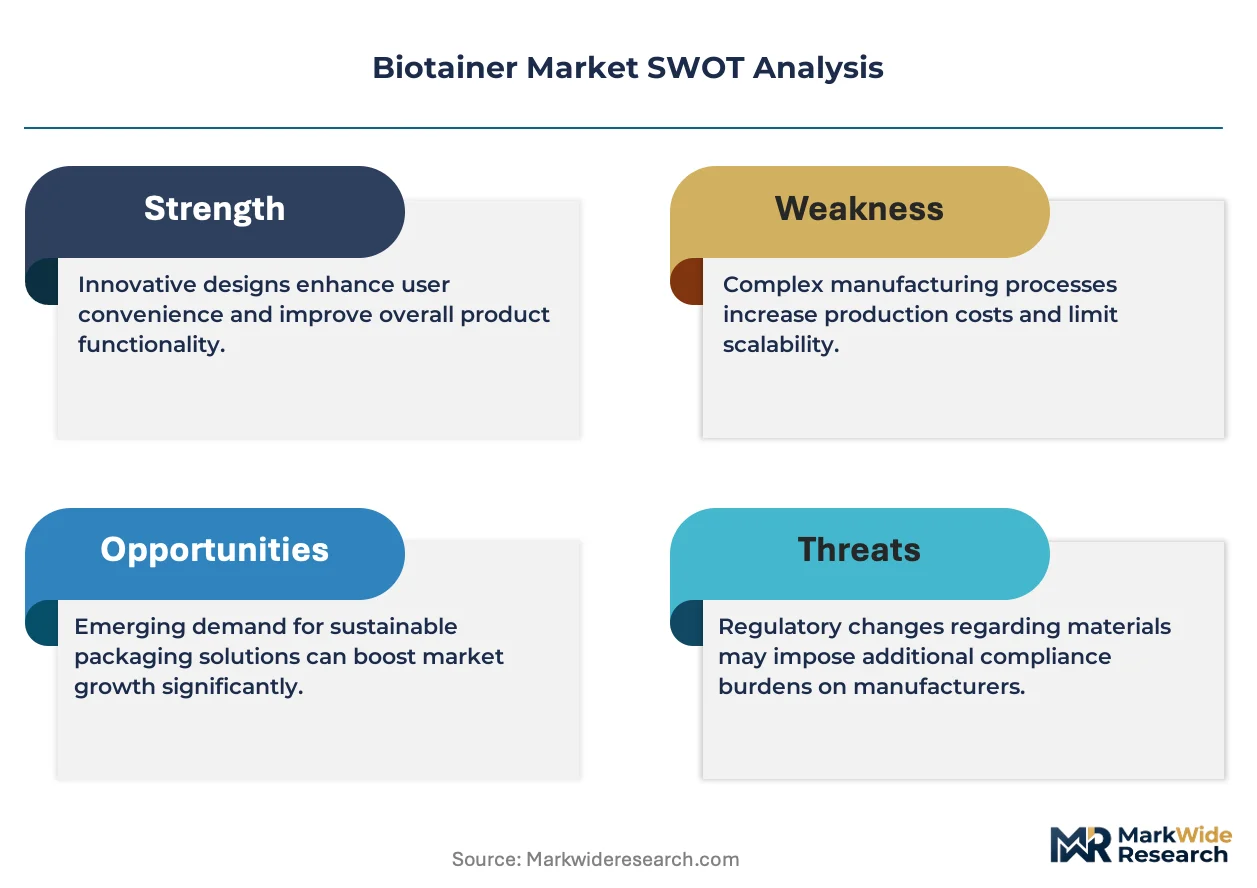
FDA sterilization validation guidelines and EMA Annex 1 revisions on containment strategy are tightening material qualification requirements for direct-contact bioprocessing equipment. ISO 15378 primary packaging standards and USP Class VI biological reactivity testing shape supplier certification barriers that filter subscale competitors from GMP-tier procurement lists. Stakeholders must monitor evolving EMA and FDA guidance on extractables and leachables risk assessment, as regulatory alignment between these frameworks will determine which material platforms and testing protocols become de facto market access requirements.
Market Dynamics
Single-use containment systems are displacing stainless steel infrastructure across biopharma manufacturing, driven by FDA and EMA sterilization validation requirements that eliminate cross-contamination risks in multi-product facilities. This structural shift concentrates procurement power among CDMOs and cell therapy developers.
Growth Catalysts
- EMA Annex 1 revisions:The updated containment strategy requirements mandate closed-system processing for sterile drug products, compelling biopharma manufacturers to adopt single-use biotainer systems for fill-finish operations.
- Cell therapy logistics:Cryogenic-grade biotainer demand accelerates as autologous and allogeneic cell therapies require vapor-phase liquid nitrogen storage from manufacturing sites through clinical administration.
- Germany:Specialized production clusters anchored by precision-molded polymer suppliers concentrate European supply chain capabilities for GMP-critical bioprocessing workflows.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings for pharmaceutical-grade thermoplastics compress margins for precision-molded container manufacturers serving cost-sensitive diagnostic segments.
- Gamma irradiation capacity concentration:Sterilization service providers cluster in Germany and the United States, creating geographic bottlenecks for biotainer suppliers requiring validated irradiation protocols.
- Extractables testing burden:USP Class VI biological reactivity and ISO 10993 biocompatibility validation timelines extend product commercialization cycles for new material platforms.
Strategic Opportunities
- India:CDMO expansion under the PLI scheme for pharmaceuticals creates unmet demand for single-use containment systems in outsourced bioprocessing operations.
- Closed-system aseptic connectors:Integration of sterile welding technologies with multi-layer film biotainers enables point-of-use fluid transfer without cleanroom infrastructure.
- ISO 15378 certification:Primary packaging material standards for medicinal products create procurement barriers that favor certified suppliers in GMP-tier supply chains.
Industry Challenges
- Cleanroom manufacturing scale-up:ISO-certified production facilities require substantial capital investment for particle-controlled environments that meet GMP Annex 1 environmental monitoring requirements.
- Legacy equipment integration:Stainless steel bioreactor and filling line interfaces demand customized adapter development for single-use biotainer compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotainer Market |
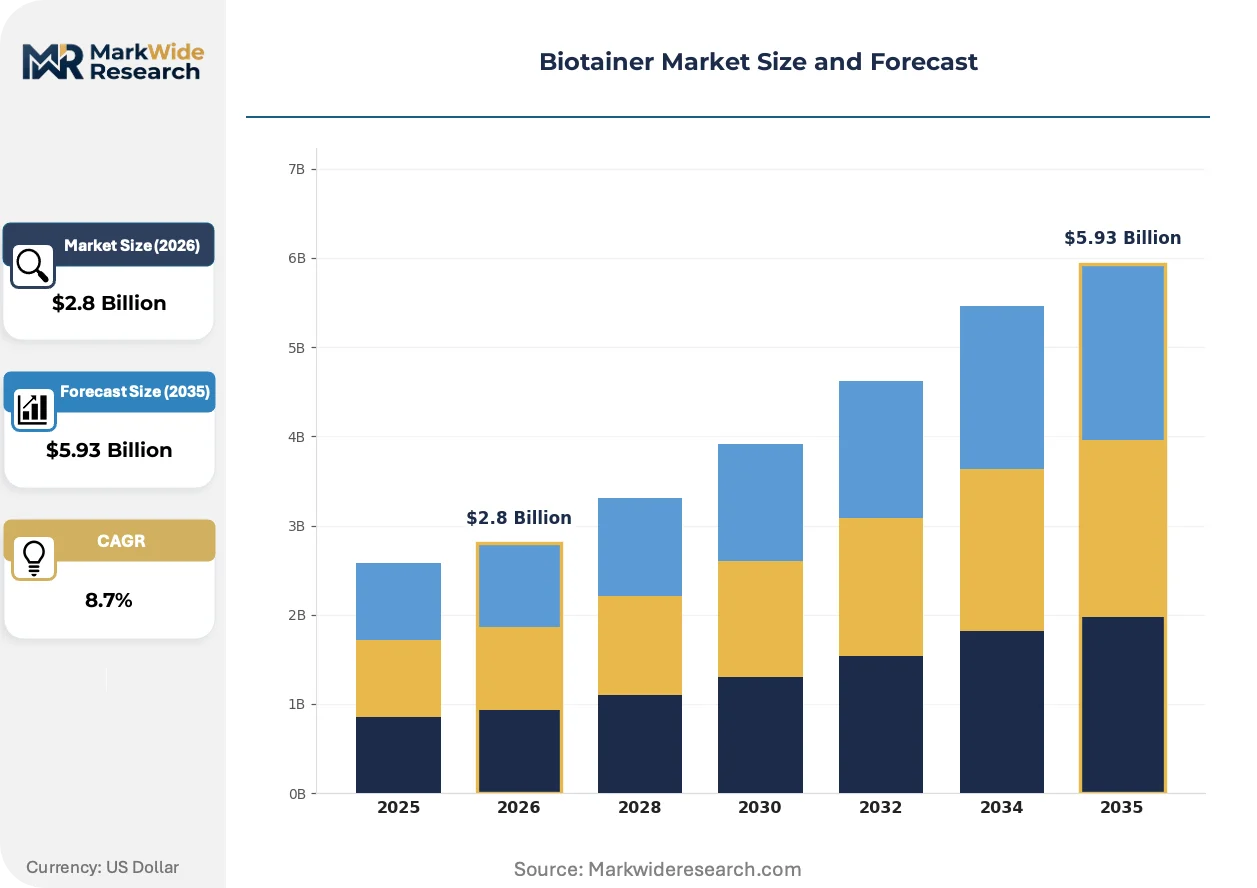
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Bags, Multi-Use Containers, Transport Vessels, Storage Solutions Material: Polypropylene, Polyethylene, PVC, Nylon End User: Biopharmaceuticals, Research Laboratories, Hospitals, Diagnostic Centers Application: Cryogenic Storage, Sample Transportation, Laboratory Processing, Cell Culture |
| Companies Covered | E3 Cortex, CP Lab Safety, Nalge Nunc International, Biofluid Focus Inc., Cellon S.A, Sani-Tech West, Inc., Kisker Biotech GmbH & Co. KG, Teknova Medical Systems Ltd., DD Biolab S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotainer Market Emerging Trajectories
Multi-layer film engineering is redefining temperature performance boundaries for biological storage, enabling vapor-phase liquid nitrogen compatibility without sacrificing mechanical integrity during transport.
Multi-layer coextruded films with ethylene vinyl alcohol barrier layers are fragmenting the cryogenic storage segment by replacing traditional glass vials in cell therapy logistics. Cell therapy developers and blood banks are adopting these systems at accelerating rates for autologous treatment workflows. The technology is fragmenting supplier hierarchies by enabling film converters to bypass established molded-container incumbents.
EMA Annex 1 revisions on contamination control strategy are tightening material qualification requirements for direct-contact bioprocessing equipment. Suppliers must now document extractables and leachables risk assessments across the entire product lifecycle. Cryogenic-grade biotainers face the steepest compliance burden due to multi-layer film complexity and extended contact duration with biological materials.
CDMO procurement patterns are consolidating supplier relationships around full-system providers capable of delivering biotainers, tubing assemblies, and sterile connectors under unified quality agreements. This behavior is displacing component-level sourcing strategies that previously fragmented purchasing across specialized vendors. The shift is most visible in Germany and Switzerland, where contract manufacturers prioritize single-source accountability for GMP-critical supply chains.
Biotainer Market Segmentation
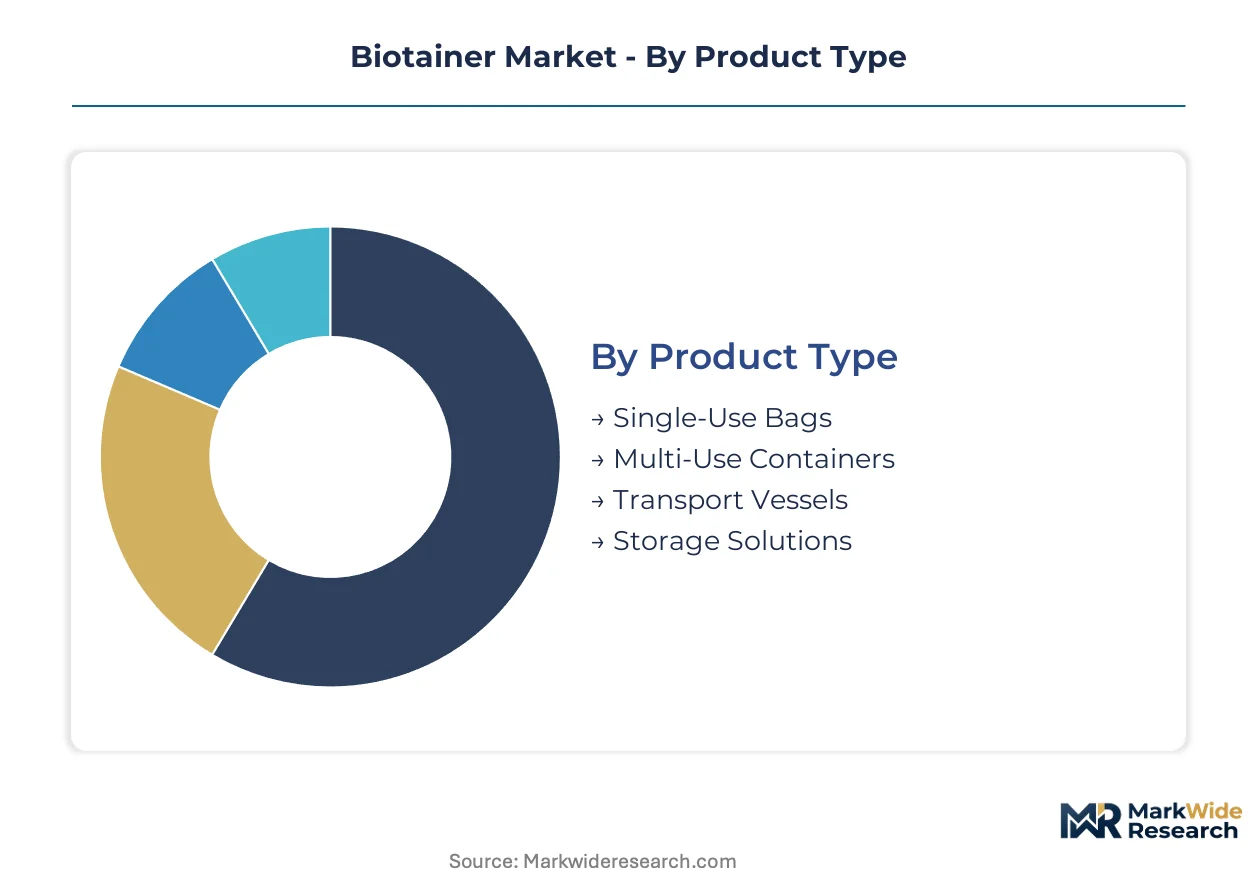
Material selection and sterilization compatibility dictate procurement decisions across biopharma manufacturing. Product configuration determines whether facilities eliminate cleaning validation burdens or retain multi-use infrastructure for cost efficiency.
Product Type:
Premium pricing concentrates in cryogenic-compatible formats where multi-layer film engineering commands margin premiums over standard laboratory vessels.
- Single-Use Bags:Constructed from multi-layer coextruded films with ethylene vinyl alcohol barrier layers, these systems eliminate CIP/SIP validation requirements. CDMOs in Germany prioritize single-use bags for multi-product fill-finish operations where cross-contamination risks dominate facility design decisions.
- Multi-Use Containers:Precision-molded polypropylene vessels withstand repeated gamma irradiation cycles and autoclave sterilization. Academic research institutions favor multi-use formats for cost-sensitive cell culture workflows where batch volumes remain modest.
- Transport Vessels:Insulated shippers with phase-change materials maintain cold chain integrity for clinical sample logistics.
- Storage Solutions:Racks, cassettes, and modular systems organize biotainer inventories within vapor-phase liquid nitrogen dewars.
The dominant share belongs to Single-Use Bags, while Transport Vessels are closing the gap fastest.
Material:
Resin grade determines leachables profiles and regulatory qualification timelines for direct-contact bioprocessing applications.
- Polypropylene:Pharmaceutical-grade homopolymer delivers thermal stability from cryogenic conditions through 121°C autoclave cycles. EMA Annex 1 containment strategy requirements favor polypropylene for closed-system bioprocessing where extractables documentation spans extended contact durations.
- Polyethylene:Linear low-density formulations reduce material costs for diagnostic segments with shorter biological contact times. Diagnostic centers in cost-sensitive markets specify polyethylene for sample collection vessels where USP Class VI testing burdens remain lighter.
- PVC:Plasticized formulations offer flexibility for tubing and connector applications despite phthalate-related regulatory scrutiny.
- Nylon:Polyamide resins provide puncture resistance for transport applications requiring mechanical durability.
Polypropylene retains the largest procurement volume, though Polyethylene is expanding most quickly in emerging diagnostic markets.
End User:
Facility certification level separates GMP-tier pricing from standard laboratory supply economics.
- Biopharmaceuticals:Commercial manufacturing operations demand ISO 15378-certified primary packaging with full extractables and leachables risk assessments. Cell therapy developers require cryogenic-grade biotainers compatible with vapor-phase liquid nitrogen storage from manufacturing sites through clinical administration.
- Research Laboratories:Academic and government facilities prioritize cost efficiency over comprehensive validation documentation. Research laboratories in Germany source precision-molded containers from regional polymer specialists for cell culture workflows.
- Hospitals:Clinical settings utilize biotainers for blood component storage and therapeutic cell preparation.
- Diagnostic Centers:High-throughput testing facilities specify single-use containment for sample processing efficiency.
Biopharmaceuticals command the dominant revenue share, while Diagnostic Centers are gaining share fastest.
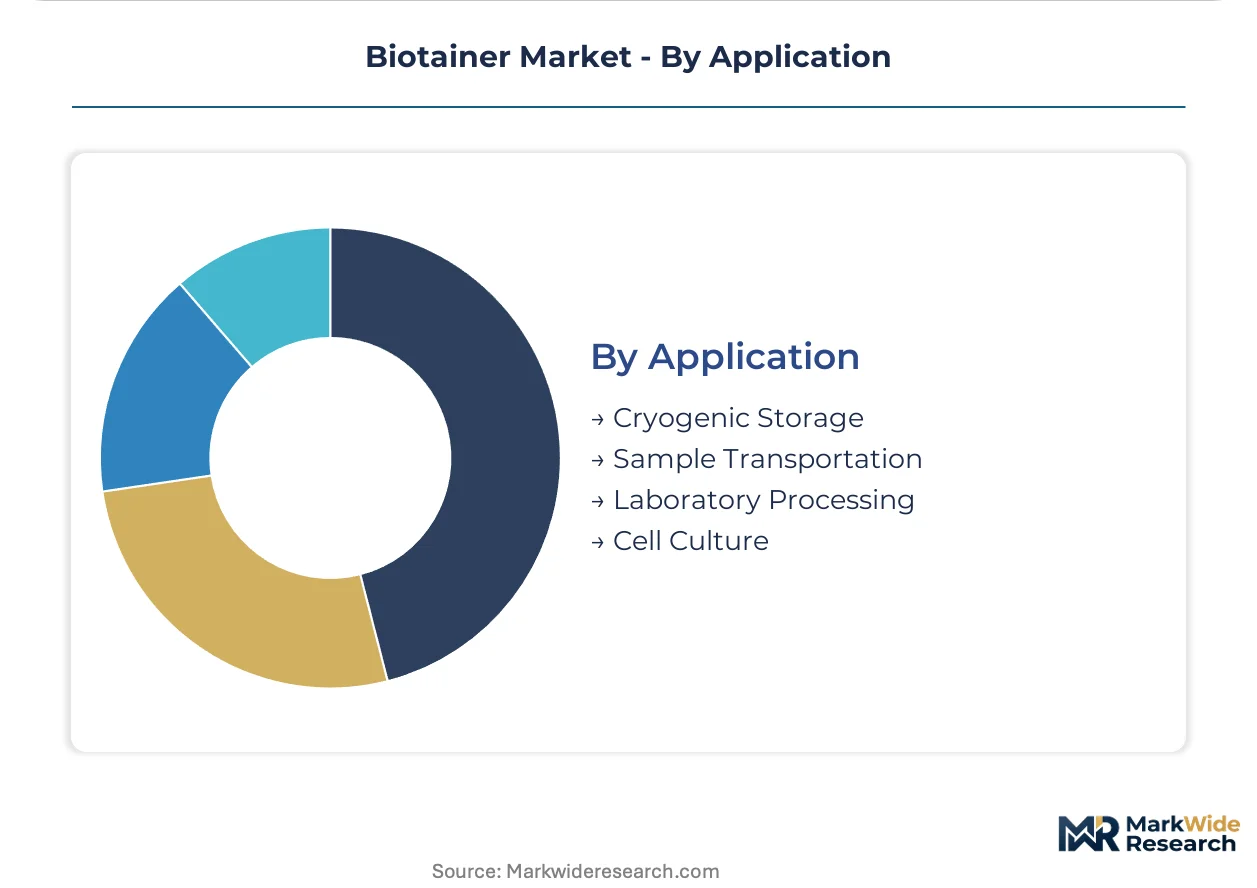
Application:
Temperature performance requirements fragment pricing tiers from ambient laboratory processing through cryogenic logistics.
- Cryogenic Storage:Multi-layer film constructions with aluminum foil barriers maintain integrity at minus 196°C vapor-phase liquid nitrogen temperatures. Autologous cell therapy workflows demand cryogenic-grade biotainers for patient-specific material preservation across manufacturing and clinical sites.
- Sample Transportation:Validated shippers with temperature monitoring integrate biotainers for clinical logistics. Blood banks specify transport vessels with phase-change materials for donor sample integrity during interstate distribution.
- Laboratory Processing:Aseptic manipulation of biological materials within controlled environments.
- Cell Culture:Expansion of therapeutic cell populations in incubated conditions.
Cryogenic Storage holds the dominant position, while Sample Transportation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in biotainer distribution, connecting precision polymer manufacturers to North Sea shipping lanes that serve biopharma clusters across Northern Europe.
United States
FDA sterilization validation requirements drive single-use adoption among CDMOs operating multi-product facilities. The IRA's domestic biomanufacturing incentives accelerate capacity buildout in Massachusetts and North Carolina. Greater Boston anchors cryogenic-grade biotainer demand as cell therapy developers cluster around vapor-phase liquid nitrogen logistics infrastructure.
Germany
EMA Annex 1 containment strategy revisions compel closed-system processing adoption across sterile drug manufacturing. The country's central bank monitors pharmaceutical export credit flows that sustain regional polymer processing investments. Kisker Biotech anchors specialized production in North Rhine-Westphalia, serving GMP-critical bioprocessing workflows for European cell therapy developers.
India
CDMO expansion under the PLI scheme for pharmaceuticals generates unmet demand for single-use containment in outsourced bioprocessing. CDSCO material compliance standards tighten import requirements for direct-contact pharmaceutical equipment. Maharashtra's biotech corridor concentrates sterile manufacturing investments that require validated irradiation protocols for biotainer supply chains.
China
NMPA biocompatibility testing requirements extend commercialization timelines for new material platforms entering domestic biopharma procurement lists. Dual carbon goals pressure polymer processors to reduce energy intensity in precision-molded container manufacturing. Yangtze River Delta biotech parks concentrate demand for multi-layer film biotainers serving cell therapy logistics.
Switzerland
Swissmedic sterility assurance guidelines exceed baseline EMA requirements for direct-contact primary packaging in parenteral drug manufacturing. The country's pharmaceutical export dominance sustains premium pricing for ISO 15378-certified containment systems. Basel's contract manufacturing ecosystem prioritizes single-source supplier accountability for GMP-critical biotainer procurement.
Biotainer Market Vendor Landscape
Concentration sits with precision-molded polymer specialists and multi-layer film converters serving distinct temperature performance tiers. The vendor base spans laboratory-grade suppliers, cryogenic-grade specialists, and integrated system providers. Two strategic archetypes dominate: regional polymer processors leveraging geographic proximity to biopharma clusters, and full-system providers bundling biotainers with tubing assemblies under unified quality agreements. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers respond to CDMO procurement consolidation.
Among German fabricators, Kisker Biotech GmbH & Co. KG exemplifies the cryogenic-grade specialist archetype, while Cellon S.A represents ISO-certified cleanroom manufacturing capabilities serving GMP-critical workflows. Nalge Nunc International occupies a position anchoring North American laboratory-grade supply through established precision-molded polymer expertise. These three entities illustrate how geographic specialization and certification tiering fragment competitive positioning across temperature performance and regulatory compliance vectors.
| Leading Market Players |
|---|
| E3 Cortex |
| CP Lab Safety |
| Nalge Nunc International |
| Biofluid Focus Inc. |
| Cellon S.A |
| Sani-Tech West, Inc. |
| Kisker Biotech GmbH & Co. KG |
| Teknova Medical Systems Ltd. |
| DD Biolab S.L. |
| Others |
Supply Flow & Price Mechanics
Multi-layer film substitution for traditional glass vials in cell therapy logistics simultaneously concentrates supply geography around specialized polymer converters in Germany and compresses pricing economics for precision-molded incumbents facing stranded equipment investments. This material transition rewards film engineering specialists while eroding margin buffers for legacy container manufacturers anchored in molded-polypropylene infrastructure.
Pricing Analysis
Volume-discount tiering structures separate GMP-certified cryogenic-grade biotainers from laboratory-standard vessels and economy diagnostic formats. Price differentiation rests on ISO 15378 certification status and extractables documentation depth, with biopharma manufacturers absorbing premium multiples for closed-system compliance. Cost compression in diagnostic polyethylene segments intensifies as Indian CDMOs source unvalidated alternatives, while cell therapy developers show minimal price sensitivity for vapor-phase liquid nitrogen compatibility.
Supply Chain Analysis
Gamma irradiation capacity clustering in Germany and the United States creates a sterilization chokepoint that constrains biotainer throughput for Asian CDMO expansion. Pharmaceutical-grade polypropylene resin draws from petrochemical complexes in Germany, Belgium, and the United States, with feedstock price volatility transmitting directly to molded-container margins. Single-source vulnerability concentrates in EVOH barrier film supply from Japanese and Korean specialty chemical producers. Distribution runs through cold-chain logistics providers integrated with cell therapy manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use containment penetration in outsourced bioprocessing remains below saturation thresholds, with EMA Annex 1 enforcement creating sustained adoption tailwinds across European sterile manufacturing. This early-cycle expansion rewards suppliers capable of unifying quality agreements across biotainer, tubing, and connector portfolios.
For Market Incumbents: Secure backward integration into gamma irradiation services or captive polymer compounding to defend margin structures against resin volatility. Kisker Biotech's regional clustering model demonstrates how geographic proximity to Port of Hamburg distribution infrastructure neutralizes logistics cost pressure from film-converter competition. For New Entrants and Emerging Players: Anchor in India's PLI-supported CDMO corridor where validated irradiation protocols remain undersupplied relative to sterile manufacturing expansion. Target cryogenic-grade multi-layer film production as the most penetrable tier, leveraging partnerships with Yangtze River Delta biotech parks for initial volume validation before European GMP qualification. For Investors and Strategic Acquirers: EMA Annex 1 alignment with FDA extractables guidance reshapes the acquisition landscape toward full-system providers capable of unified quality agreements. Long-term viability favors suppliers with ISO 15378 certification and in-house film extrusion capabilities. Watch for CDSCO import compliance tightening as the signal indicating Indian market access barriers rising for uncertified competitors.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Primary packaging standards create procurement barriers filtering subscale competitors from GMP-tier supply chains. |
| Backward Integration into Gamma Irradiation | Captive sterilization capacity neutralizes geographic bottlenecks constraining biotainer throughput for Asian CDMOs. |
| Multi-Layer Film Extrusion Capacity | EVOH barrier layer production enables vapor-phase liquid nitrogen compatibility without glass vial mechanical fragility. |
| Unified Quality Agreement Structuring | Single-source accountability for biotainer-tubing-connector bundles displaces fragmented component-level procurement. |
| Regional Production Clustering | Proximity to Port of Hamburg distribution infrastructure reduces cold-chain logistics cost for European cell therapy developers. |
Methodological Framework
Desk research of FDA sterilization validation guidelines, EMA Annex 1 revision drafts, and ISO 15378 primary packaging standards preceded structured interviews with biopharma manufacturing executives, CDMO procurement directors, and cell therapy logistics specialists. Secondary validation drew from USP Class VI biological reactivity testing protocols, customs data on pharmaceutical-grade thermoplastic imports, and SEC filings of precision-molded polymer suppliers. Bottom-up volume estimates from individual facility adoption rates triangulated against top-down market sizing from regulatory filing analysis.
Variance decomposition across product type, material grade, end-user certification tier, and application temperature requirement shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by EMA Annex 1 compliance deadlines and PLI scheme implementation timelines. Cryogenic storage penetration rates and single-use bag displacement of stainless steel infrastructure served as primary demand-side inputs.
Material uncertainties — polypropylene resin price volatility, gamma irradiation capacity expansion delays, and EMA-FDA extractables guidance divergence — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as CDSCO import standard evolution and dual carbon goals pressure polymer processor energy intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
PET Bottle Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Aluminium Cup Market