
 Square Media Bottle Market | 2026-2036
Square Media Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Square Media Bottle Market Analytics
Specialty laboratory distribution is fragmenting as direct-to-biopharma channels erode traditional distributor margins. Sartorius AG leverages captive demand from its filtration and bioprocessing divisions to sustain pull-through for proprietary bottle formats. Merck KGaA anchors European supply through Sigma-Aldrich's institutional procurement contracts. DURAN Group GmbH differentiates via borosilicate glass technical leadership and ISO 4796 compliance pedigree.
Square media bottles are rigid rectangular containers engineered for sterile liquid storage, typically manufactured from borosilicate glass or pharmaceutical-grade polyethylene terephthalate glycol with dimensional tolerances matching automated filling lines. Their flat-sided geometry maximizes shelf density and label adhesion while enabling complete drainage during aseptic decanting operations. Plastic formats lead volume due to disposability trends in single-use bioprocessing, though glass retains premium positioning for light-sensitive and high-temperature applications. The 500ml and 1L size brackets capture the dominant share of cell culture media workflows, while screw cap configurations dominate closure demand owing to torque-seal validation requirements.
FDA 21 CFR Part 211 and EMA GMP Annex 1 govern container closure integrity for pharmaceutical applications, with both agencies tightening particulate contamination limits that favor certified cleanroom-manufactured bottles. ISO 15378 and USP Class VI testing protocols shape material qualification timelines and supplier approval processes. Stakeholders must monitor evolving extractables and leachables study requirements as polymer formulations diversify.
Market Dynamics
Single-use bioprocessing adoption is compressing equipment amortization cycles and forcing container suppliers to validate extractables profiles against tightening pharmacopeial standards. FDA and EMA convergence on particulate limits is accelerating material substitution timelines.
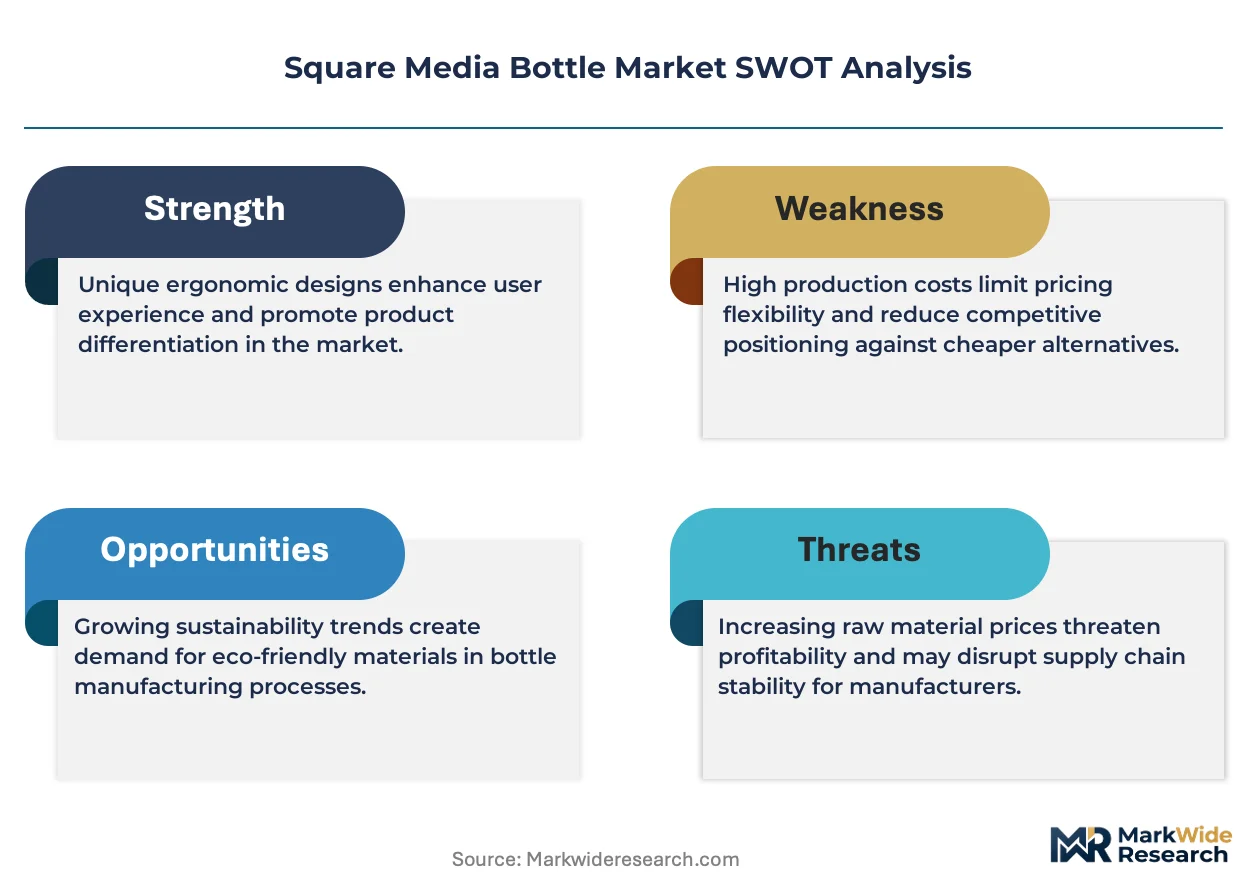
Growth Catalysts
- EMA Annex 1 revisions:The 2022 update mandates enhanced container closure integrity testing, driving certified cleanroom bottle demand across European biopharmaceutical manufacturing.
- Cell therapy commercialization:Autologous manufacturing workflows require sterile, single-use media storage formats that eliminate cross-contamination risks during patient-specific batch processing.
- Polyethylene terephthalate glycol reformulation:Advanced polymer stabilization chemistries extend shelf life for light-sensitive cell culture media, expanding plastic bottle applicability into premium applications.
Market Restraints
- High-purity resin supply concentration:Pharmaceutical-grade PETG pellet production clusters in Germany and the United States, exposing converters to petrochemical feedstock volatility and logistics bottlenecks.
- Borosilicate glass thermal shock limitations:DURAN and SCHOTT formulations face constrained adoption in rapid temperature-cycling workflows despite superior chemical inertness.
- ISO 15378 certification timelines:Primary packaging material qualification cycles extend 18-24 months, freezing new supplier entry and entrenching incumbent relationships.
Strategic Opportunities
- Indian biopharma contract manufacturing:CDMO capacity expansion in Hyderabad and Bengaluru creates demand for validated single-use containers as domestic facilities pursue US FDA and EMA inspections.
- Closed-system aseptic transfer integration:Convergence between square media bottles and rapid transfer port technologies enables isolator-compatible filling without laminar flow cabinet exposure.
- China NMPA biologics pathway acceleration:Streamlined IND approval timelines for biosimilars and innovative biologics expand cell culture media production infrastructure requiring compliant storage formats.
Industry Challenges
- Extractables study standardization gaps:Divergent USP Class VI, ISO 10993, and BPOG testing protocols force redundant qualification expenditures across customer portfolios.
- Automation line retrofit requirements:Square bottle dimensional tolerances must match legacy cylindrical bottle handling equipment, constraining geometry innovation without capital-intensive line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Square Media Bottle Market |
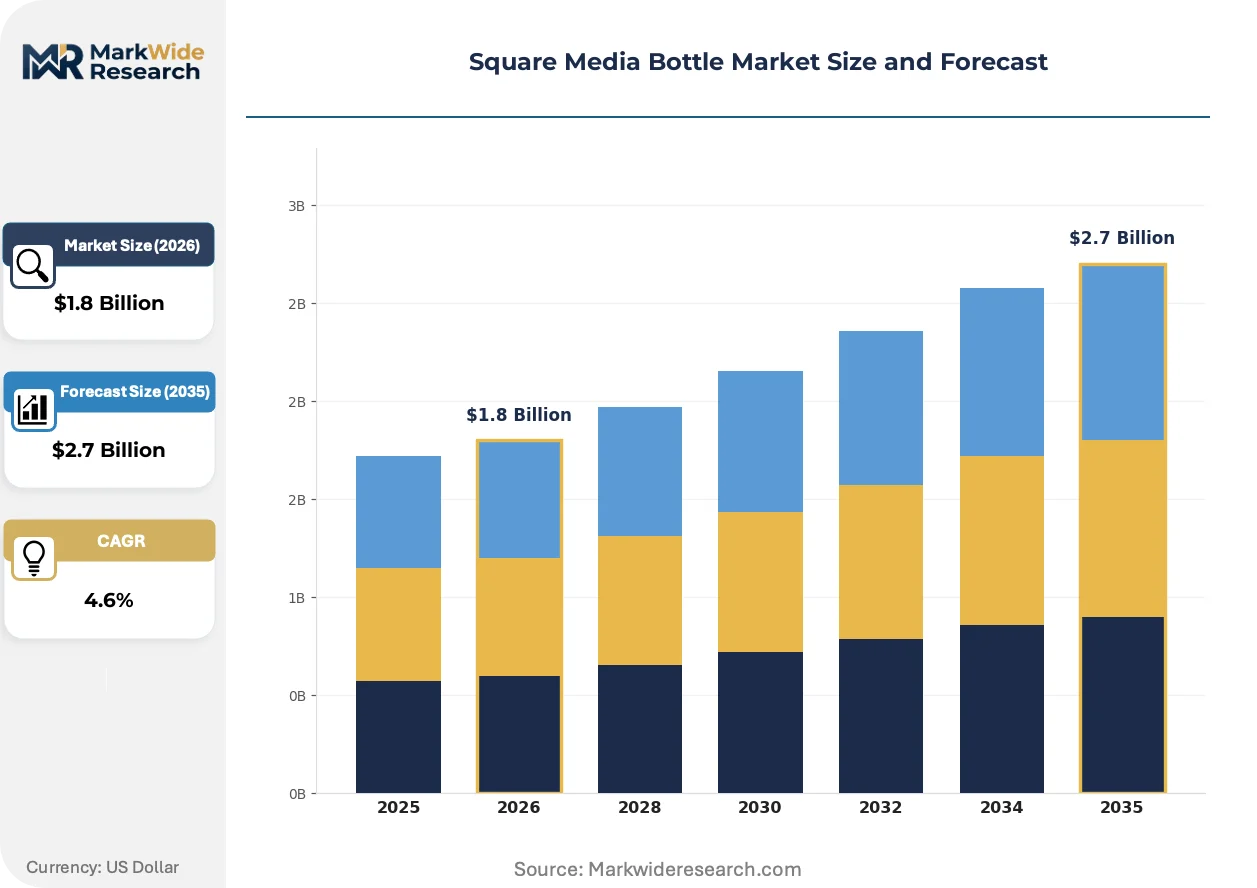
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Polyethylene, Aluminum Size: 250ml, 500ml, 1L, 2L Cap Type: Screw Cap, Snap Cap, Flip Top, Cork Application: Cosmetics, Beverages, Cleaning Solutions, Others |
| Companies Covered | Sartorius AG, Thomas Scientific, Merck KGaA, Suzhou KB Healthcare Technologies, Zhejiang Aijiren Technology, VWR International, DURAN Group GmbH, ALPHA PACKAGING, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Square Media Bottle Market Evolving Landscape
Material science breakthroughs and regulatory harmonization pressures are compressing traditional supplier qualification timelines while enabling novel barrier technologies. Container-closure system integration is becoming the primary vector of differentiation.
Multilayer coextrusion barrier films with ethylene vinyl alcohol interlayers are rendering obsolete single-layer PETG formats for oxygen-sensitive media applications. Contract manufacturers in Switzerland and Singapore are qualifying these structures for 24-month shelf life extensions. The technology is rendering obsolete premium glass positioning in mid-tier bioprocessing workflows.
REACH Annex XVII restrictions on bisphenol A migration are accelerating non-BPA polymer catalyst adoption across European converter operations. German and French pharmaceutical packaging suppliers face reformulation deadlines that compress material validation windows. Small-volume gene therapy producers are most affected, diverting procurement toward pre-validated alternative resin streams.
Direct manufacturer-to-biopharma procurement contracts are displacing traditional laboratory distribution intermediaries for high-volume media bottle purchases. Sigma-Aldrich's institutional contracts face erosion as Sartorius and Thermo Fisher Scientific deploy field application scientists to secure multi-year supply agreements. This pattern concentrates in the United States and Germany where biopharma procurement centralization is most advanced.
Square Media Bottle Market Segmentation
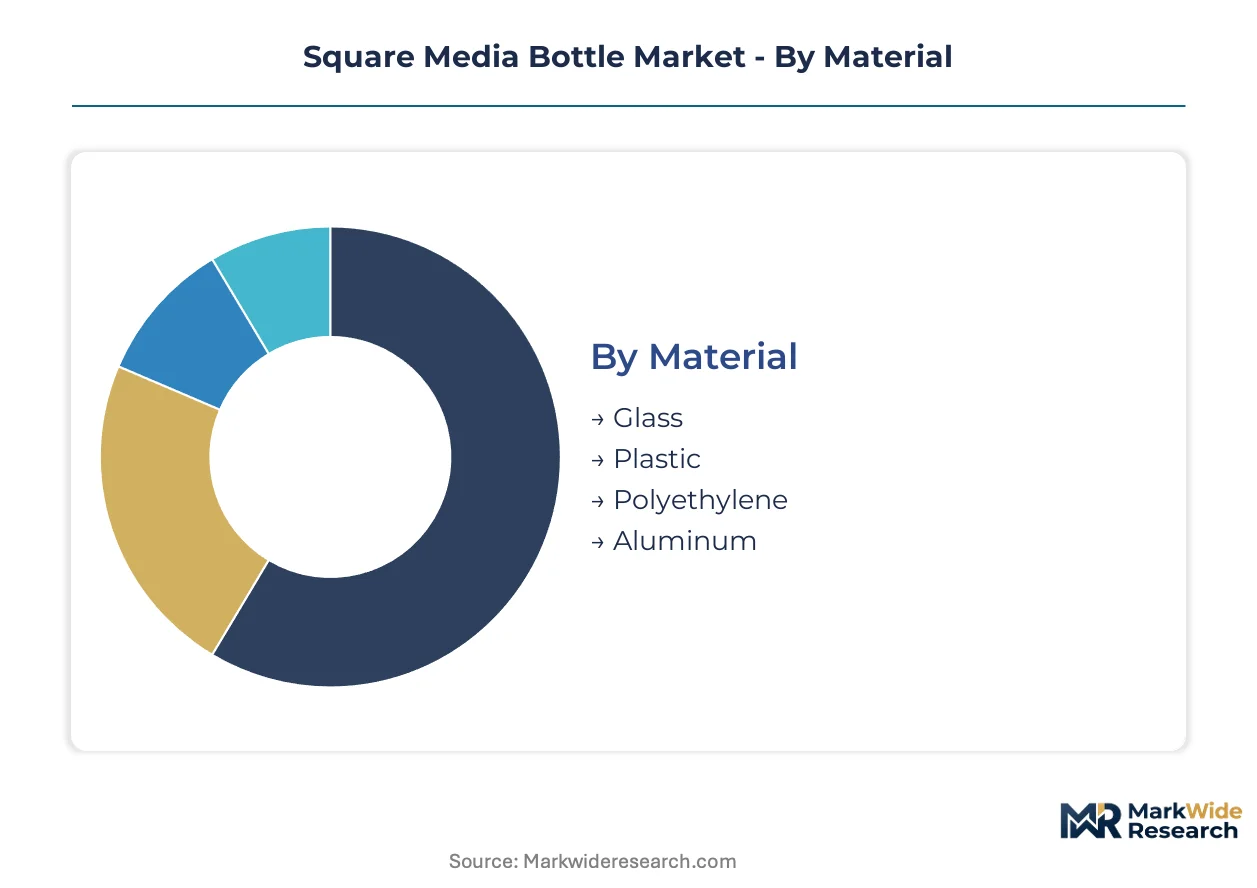
Segmentation in square media bottles reveals distinct procurement rhythms across material grades and sterile processing requirements. Biopharmaceutical manufacturers specify container formats based on media sensitivity, automation compatibility, and regulatory validation cycles rather than commodity pricing alone.
Material:
Glass formats rotate through qualification cycles lasting 36-48 months for new supplier entry, while plastic alternatives compress to 12-18 months for established resin streams. Aluminum niche applications move slowest due to extractables study complexity.
- Glass:Borosilicate formulations from DURAN and SCHOTT dominate light-sensitive and high-temperature applications. Cell therapy producers in Germany and the United States specify glass for autologous media storage despite thermal shock constraints in rapid-cycling workflows.
- Plastic:Pharmaceutical-grade PETG leads single-use bioprocessing adoption with disposability eliminating cross-contamination risks. Contract manufacturers in Hyderabad and Singapore are qualifying multilayer coextrusion variants for oxygen-sensitive media with 24-month shelf life extensions.
- Polyethylene:Lower-cost alternative for non-sterile industrial applications with limited biopharma penetration due to leachables profile variability.
- Aluminum:Barrier-coated formats serve specialty chemical transport with minimal cell culture media adoption.
Plastic anchors the volume base while glass retains premium positioning; multilayer PETG coextrusion gains share at the steepest rate as oxygen barrier performance improves.
Size:
Procurement scale divides sharply between R&D-scale batches and commercial manufacturing volumes, with automation line retrofit costs constraining format migration.
- 500ml:Dominates cell culture media workflows with dimensional tolerances matching legacy automated filling equipment. Biopharma procurement centralization in the United States and Germany concentrates demand for this bracket.
- 1L:Standard for commercial-scale batch processing with torque-seal validation requirements driving screw cap pairing. CDMO capacity expansion in China NMPA-regulated facilities expands 1L qualification programs.
- 250ml:R&D and pilot-scale applications with higher per-unit pricing and lower volume velocity.
- 2L:Bulk media storage for large-scale bioreactor feeding with limited isolator compatibility constraining adoption.
500ml and 1L together constitute the procurement core, while 2L climbs fastest among CDMOs scaling biosimilar production.
Cap Type:
Closure selection tracks directly with container closure integrity testing requirements under FDA 21 CFR Part 211 and EMA GMP Annex 1.
- Screw Cap:Torque-seal validation protocols and established automation handling secure dominant share in pharmaceutical applications. EMA Annex 1 2022 revisions mandate enhanced testing that favors proven screw cap geometries.
- Snap Cap:Rapid-access formats for non-sterile laboratory workflows with limited GMP adoption.
- Flip Top:Ergonomic dispensing for cosmetics and consumer applications outside core biopharma demand.
- Cork:Heritage wine and spirits packaging with negligible square media bottle penetration.
Screw cap maintains volume leadership while snap cap captures incremental share in research-scale single-use workflows.
Application:
End-use specification determines material grade, sterilization method, and documentation burden across divergent regulatory pathways.
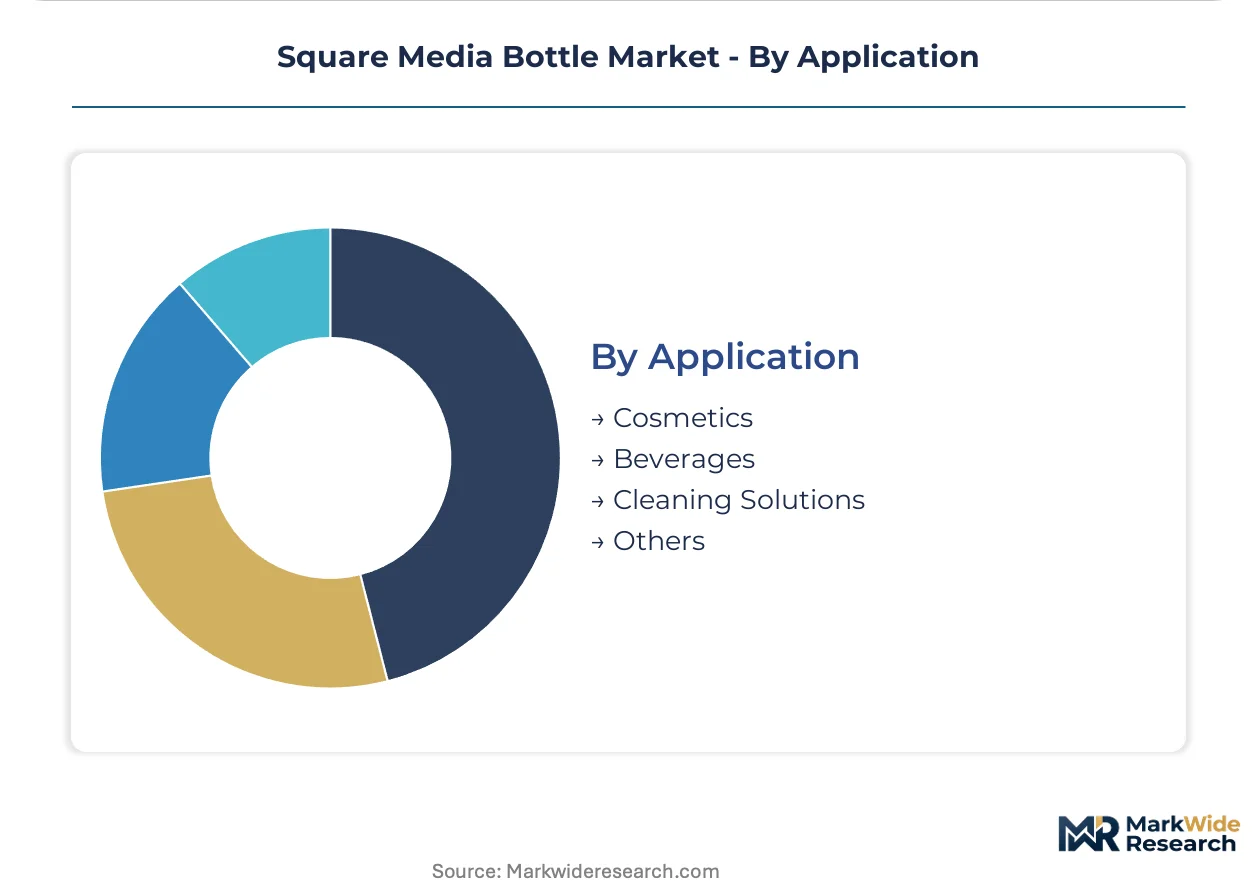
- Cosmetics:REACH Annex XVII compliance for BPA-free formulations drives European converter reformulation. Premium skincare serums specify glass for aesthetic and chemical stability requirements.
- Beverages:Niche functional drink applications with square format adoption constrained by carbonation pressure handling limitations.
- Cleaning Solutions:Industrial chemical compatibility favors polyethylene and aluminum formats with minimal certification overhead.
- Others:Veterinary diagnostics and agricultural biotechnology applications with fragmented procurement and lower validation standards.
Cosmetics and cleaning solutions split the non-pharma volume base, while cosmetics expands most quickly on clean beauty positioning and sustainable packaging mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution dominance for sterile container logistics. Automated filling line density in the Rhine-Ruhr corridor shapes regional procurement specifications. Cross-border ISO 15378 certification mutual recognition accelerates supplier qualification cycles.
United States
FDA 21 CFR Part 211 enforcement tightens container closure integrity requirements for cell therapy producers. The Boston-Cambridge biotech cluster drives demand for 500ml single-use formats in autologous manufacturing workflows. CDMO capacity expansion in Research Triangle Park accelerates screw cap validation programs for commercial-scale batches.
Germany
EMA GMP Annex 1 2022 revisions mandate enhanced particulate testing for cleanroom-manufactured bottles. REACH Annex XVII BPA restrictions force polymer reformulation across converter operations in North Rhine-Westphalia. The Rhine-Main biopharma corridor concentrates demand for DURAN borosilicate formats in light-sensitive media applications.
China
NMPA streamlined IND pathways for biosimilars expand cell culture media production infrastructure. Yangtze River Delta contract manufacturers qualify multilayer PETG coextrusion for oxygen-sensitive formulations. Suzhou industrial park clusters drive 1L bottle procurement for large-scale bioreactor feeding operations.
India
CDSCO alignment with US FDA inspection standards pressures Hyderabad CDMOs toward validated single-use containers. The PLI scheme for pharmaceuticals incentivizes domestic sterile packaging capacity. Bengaluru's biotech corridor adopts screw cap configurations for isolator-compatible aseptic transfer integration.
Switzerland
Swissmedic's stringent extractables documentation requirements favor pre-qualified resin streams from established suppliers. Basel's pharmaceutical manufacturing density concentrates demand for premium barrier-coated formats. Geneva-based contract manufacturers pioneer 24-month shelf life extensions through advanced multilayer structures.
Square Media Bottle Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. German and US-based incumbents anchor the premium segment through ISO 15378 certification pedigrees. Mid-scale Asian fabricators compete on volume conversion efficiency for standard-grade formats. Strategic moves center on backward integration into pharmaceutical-grade resin compounding and captive filtration-bioprocessing system bundling.
Within the European premium tier, DURAN Group GmbH and Merck KGaA exemplify certification-driven positioning. Sartorius AG occupies a distinct anchor position through captive demand pull from adjacent bioprocessing divisions. These three represent divergent archetypes: technical materials leadership, institutional procurement anchoring, and integrated system bundling respectively.
| Leading Market Players |
|---|
| Sartorius AG |
| Thomas Scientific |
| Merck KGaA |
| Suzhou KB Healthcare Technologies |
| Zhejiang Aijiren Technology |
| VWR International |
| DURAN Group GmbH |
| ALPHA PACKAGING |
| Berlin Packaging |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's pharmaceutical cold chain corridor shapes cost dynamics across European distribution, concentrating supply power among German and Dutch converters while forcing downstream price differentiation between validated cleanroom formats and standard laboratory grades. This logistics architecture amplifies volume-discount leverage for biopharma procurement centralization in the United States and Germany.
Pricing Analysis
Volume-discount tiering structures stratify across premium ISO 15378-certified cleanroom formats, standard pharmaceutical-grade PETG, and economy polyethylene alternatives for non-GMP applications. Price differentiation hinges on certification pedigree and automation line validation status, with screw cap configurations commanding sustained premiums under EMA Annex 1 torque-seal requirements. Cost compression in standard-grade plastic formats is intensifying as Asian converters scale multilayer coextrusion capacity. CDMOs in India and China exhibit highest price sensitivity, while cell therapy producers in Germany and the United States prioritize qualification reliability over per-unit cost.
Supply Chain Analysis
Pharmaceutical-grade PETG pellet production clusters in Germany, the United States, and South Korea, anchoring converter operations to petrochemical feedstock volatility. Raw material dependencies center on high-purity resin streams, borosilicate glass cullet from SCHOTT and DURAN, and multilayer barrier film substrates. Single-source vulnerability concentrates in German resin compounding for oxygen-sensitive media applications. Distribution runs through direct manufacturer-to-biopharma contracts displacing traditional laboratory distribution intermediaries for high-volume purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use bioprocessing adoption sits in early-cycle expansion, with cell therapy commercialization and EMA Annex 1 regulatory tightening creating durable tailwinds for validated container demand across the next decade.
For Market Incumbents: Entrench certification moats through accelerated ISO 15378 renewal cycles and captive resin compounding investments in North Rhine-Westphalia. Threat from Asian multilayer coextrusion specialists demands backward integration into pharmaceutical-grade PETG production to defend margin position. Channel control through field application scientist deployment secures multi-year supply agreements against distributor erosion. For New Entrants and Emerging Players: Mid-market CDMOs in Hyderabad and Bengaluru represent the most penetrable entry point, with PLI scheme incentives reducing capital barriers for domestic sterile packaging capacity. Gene therapy producers in Switzerland face compressed material validation windows from REACH Annex XVII BPA deadlines, creating urgency for pre-qualified alternative resin streams. Go-to-market through rapid transfer port technology bundling enables isolator-compatible positioning without legacy automation retrofit burdens. For Investors and Strategic Acquirers: Resin compounding specialists with pharmaceutical-grade certification pedigree offer the strongest acquisition target archetype, given 18-24 month qualification timelines freezing new supplier entry. Long-term viability frames around biologics capacity expansion in China NMPA-regulated facilities and Indian CDMO FDA alignment. Signal to watch is CDSCO inspection standard convergence accelerating domestic sterile container demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PETG supply secures margin control against German and US feedstock concentration. |
| Multilayer Coextrusion Qualification | 24-month shelf life extensions displace premium glass in oxygen-sensitive media workflows. |
| Rapid Transfer Port Integration | Isolator-compatible filling eliminates laminar flow cabinet exposure for cell therapy producers. |
| Direct-to-Biopharma Contracting | Field application scientist deployment erodes Sigma-Aldrich institutional procurement dominance. |
| CDMO Capacity Partnership | Hyderabad and Bengaluru facility expansions create validated single-use container pull-through. |
Research Methodology
Operator-level perspectives from bioprocessing engineers, regulatory affairs leads at EMA-notified bodies, CDMO procurement directors, and sterile packaging quality managers anchored the qualitative base. Secondary validation drew from FDA 21 CFR Part 211 enforcement actions, EMA GMP Annex 1 revision commentaries, USP Class VI testing protocols, and ISO 15378 certification registries. Bottom-up demand modeling triangulated against top-down pharmaceutical production capacity estimates across the analysis window.
Scenario-bracketing framed projections across material substitution timelines, regulatory harmonization pace, and biologics capacity expansion trajectories. Segmentation dimensions encompassed material grade, size bracket, cap configuration, and application workflow. CAGRs derived from elasticity-adjusted volume forecasts incorporating automation line retrofit constraints and qualification cycle duration. Industry-specific inputs included extractables study standardization gaps and closed-system aseptic transfer adoption curves.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, freight corridor congestion, or biopharma capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding EMA-FDA regulatory convergence and single-use technology penetration rates. Cross-checking against BPOG extractables study benchmarks and CDSCO inspection readiness disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Bottle Shippers Market