
 Dispensing Carboy Market | 2026-2036
Dispensing Carboy Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Carboy Market Outlook
Preventive maintenance contracts and calibration service bundles are broadening what laboratories and pharmaceutical manufacturers purchase alongside physical vessels. Thermo Fisher Scientific leverages its global service infrastructure to anchor long-term customer relationships through certified maintenance programs. DWK Life Sciences differentiates with specialized glassware expertise and regional distribution density across European research hubs. Cole-Parmer competes through digital catalog integration and same-day fulfillment capabilities that reduce procurement friction for routine consumables.
A dispensing carboy is a rigid container, typically manufactured from borosilicate glass, HDPE, or fluoropolymer-lined materials, designed with integrated spigots or tube connectors for controlled liquid withdrawal without atmospheric exposure; wall thicknesses range from 3 mm to 6 mm depending on chemical compatibility requirements, and port configurations accommodate aseptic tubing sets for closed-system transfers in pharmaceutical and analytical environments. Cylindrical formats dominate laboratory workflows due to uniform thermal distribution during temperature-controlled storage, while multi-outlet designs command premium positioning in bioprocessing applications where parallel sampling reduces contamination risk. HDPE carboys sustain volume leadership in industrial chemical handling because of impact resistance and lower unit economics, though glass variants retain margin concentration in analytical standards preparation where extractables testing demands inert surfaces.
FDA container closure integrity guidance and EMA Annex 1 sterile manufacturing revisions are elevating documentation requirements for dispensing vessel qualification, particularly in parenteral drug production where particulate control is mandatory. ISO 15378 pharmaceutical packaging standards and USP Class VI biological reactivity testing further constrain material selection, creating compliance barriers for unqualified suppliers. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA on extractables and leachables protocols, as divergence in testing thresholds could fragment procurement specifications and reshape supplier qualification timelines.
Market Dynamics
Closed-system sterile filling requirements are compressing procurement timelines for pharmaceutical manufacturers, forcing vessel suppliers to pre-qualify materials against evolving FDA and EMA extractables protocols before contract bidding.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:Parenteral drug producers must demonstrate container closure integrity with documented validation, expanding demand for pre-qualified fluoropolymer-lined dispensing carboys in German and Swiss biologics clusters.
- Bioprocessing parallel sampling architectures:Multi-outlet carboy configurations reduce contamination risk during upstream cell culture media preparation, accelerating adoption in contract manufacturing organizations running perfusion bioreactor workflows.
- Preventive maintenance contract bundling:Thermo Fisher Scientific and DWK Life Sciences anchor long-term relationships through certified calibration programs, converting one-time vessel sales into recurring service revenue streams.
Market Restraints
- High-purity borosilicate glass supply concentration:Schott AG and Corning control premium pharmaceutical-grade tubing feedstock, creating input cost volatility for glass carboy manufacturers during energy price spikes.
- Fluoropolymer liner technical limitations:PFA and PTFE barrier layers degrade under repeated gamma irradiation cycles, constraining sterilization protocol flexibility for multi-use bioprocessing applications.
- ISO 15378 certification friction:Smaller regional suppliers face 18-24 month qualification timelines to meet pharmaceutical packaging material standards, freezing marginal competitors out of sterile drug production contracts.
Strategic Opportunities
- Indian biologics manufacturing expansion:CDSCO's accelerated approval pathways for biosimilars are attracting contract development organizations to Hyderabad and Bengaluru, creating demand for aseptic dispensing vessels with regional service support.
- Single-use system convergence with reusable carboys:Hybrid configurations combining gamma-stable HDPE shells with disposable liner inserts bridge cost and contamination control requirements in mid-scale bioprocessing.
- Digital catalog integration:Same-day fulfillment capabilities through integrated e-procurement platforms reduce inventory carrying costs for routine laboratory consumables in academic and industrial research settings.
Industry Challenges
- Extractables testing protocol fragmentation:Divergent FDA and EMA thresholds for organic compound migration force manufacturers to maintain dual validation datasets, extending product development cycles.
- Legacy stainless steel infrastructure integration:Pharmaceutical facilities with established fixed-tank systems face capital-intensive retrofitting to accommodate closed-system carboy transfers without disrupting validated workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Carboy Market |
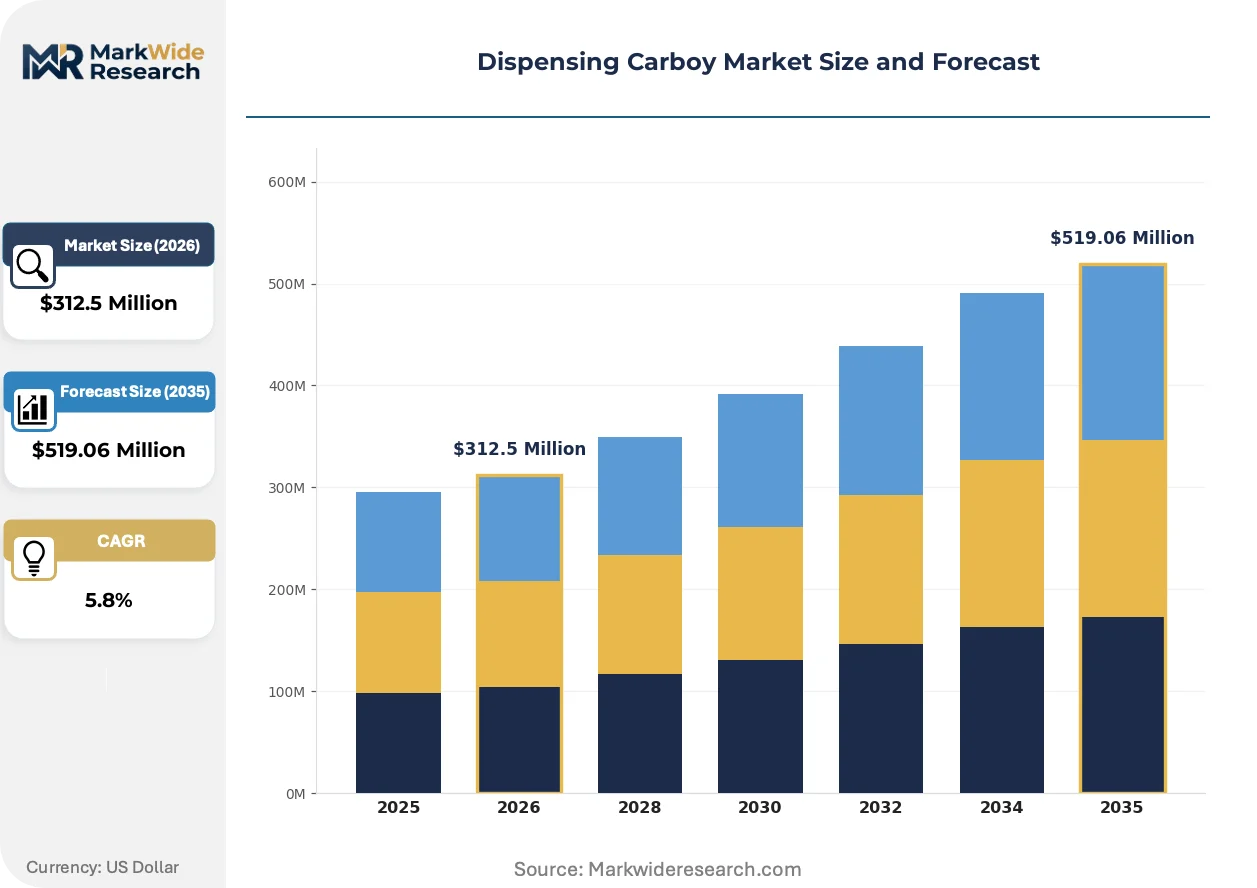
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Tapered, Square, Multi-Outlet Material: Polyethylene, Glass, Stainless Steel, HDPE Application: Laboratory, Industrial, Pharmaceutical, Food & Beverage Size: 5L, 10L, 20L, 50L |
| Companies Covered | Thermo Fisher Scientific, DWK Life Sciences, Cole-Parmer, Corning Incorporated, Berry Global, Nalgene, Saint-Gobain, Foxx Life Sciences, Dynalon Labware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Carboy Market Strategic Shifts
Material science advances and regulatory harmonization pressures are compressing traditional vessel qualification timelines while expanding the functional boundaries of what dispensing carboys must demonstrate.
Fluoropolymer-lined HDPE carboys are absorbing gamma irradiation stability requirements previously reserved for stainless steel systems. Biologics contract manufacturers in Germany and Switzerland are adopting these hybrid vessels for cell culture media storage, collapsing the historical trade-off between chemical inertness and impact resistance. This convergence is absorbing margin from pure glass alternatives in mid-tier applications while opening volume expansion in vaccine adjuvant handling.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of traditional PTFE barrier coatings used in pharmaceutical-grade carboys. European manufacturers must now validate alternative fluoropolymer chemistries or shift to ceramic-coated glass for high-purity applications, compressing supplier R&D budgets and extending material qualification timelines. German chemical handling facilities face the most immediate compliance pressure given their concentration of parenteral drug production.
Consolidated procurement through integrated laboratory supply platforms is displacing fragmented distributor relationships. Research institutions and mid-sized pharmaceutical manufacturers now expect real-time inventory visibility and automated reorder triggers embedded within their enterprise resource planning systems. This behavioral shift is most pronounced in North American academic medical centers, where procurement departments are centralizing vendor management to reduce maverick spending on routine consumables.
Dispensing Carboy Market Segmentation
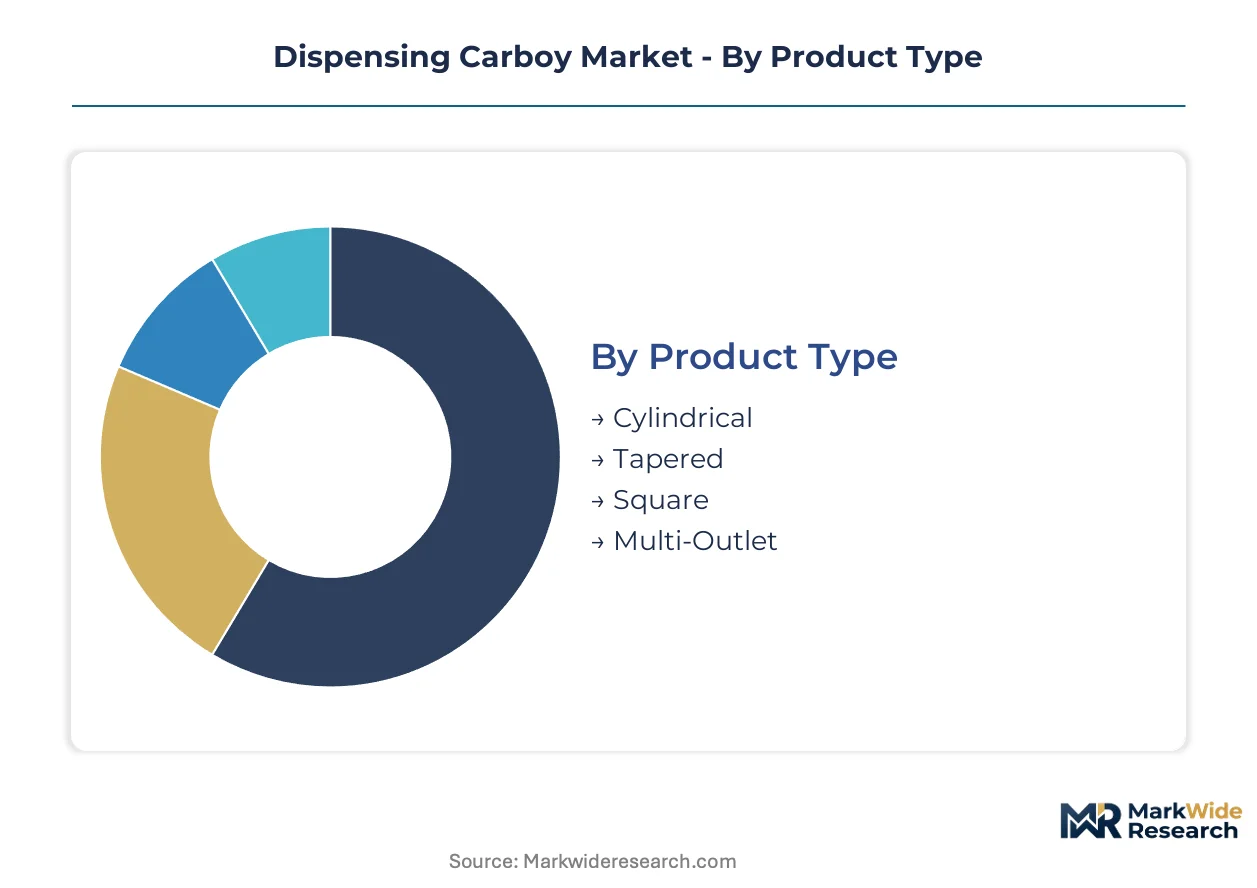
Dispensing carboy procurement diverges sharply between standardized laboratory consumables and engineered vessels for sterile drug manufacturing. Material certification requirements and port configuration complexity create distinct pricing tiers that reshape supplier qualification strategies across end-use categories.
Product Type:
Customization intensity spans from commodity cylindrical formats to engineered multi-outlet architectures for closed-system bioprocessing.
- Cylindrical:Uniform wall thickness distribution enables consistent thermal transfer during temperature-controlled storage. Academic medical centers and contract research organizations in Germany standardize on these formats for routine media preparation, though gamma sterilization protocol rigidity limits reuse cycles in multi-shift operations.
- Multi-Outlet:Parallel port configurations accommodate aseptic tubing sets for simultaneous sampling and transfer without atmospheric breach. Biologics contract manufacturers in Swiss manufacturing clusters adopt these vessels for perfusion bioreactor feed operations, where EMA Annex 1 container closure integrity documentation is mandatory.
- Tapered:Sloped base geometry improves drainage efficiency in viscous liquid handling. Specialty chemical producers favor this profile for surfactant and polymer intermediate storage where complete evacuation reduces cross-contamination risk.
- Square:Rectilinear footprint maximizes cubic utilization in space-constrained cleanroom environments. Bioprocessing facilities with fixed stainless steel infrastructure deploy these for buffer preparation to optimize floor space without workflow revalidation.
Leading the category by volume: Cylindrical. Expanding most quickly: Multi-Outlet.
Material:
Cost tier stratification separates commodity thermoplastics from certified inert surfaces required for parenteral drug contact.
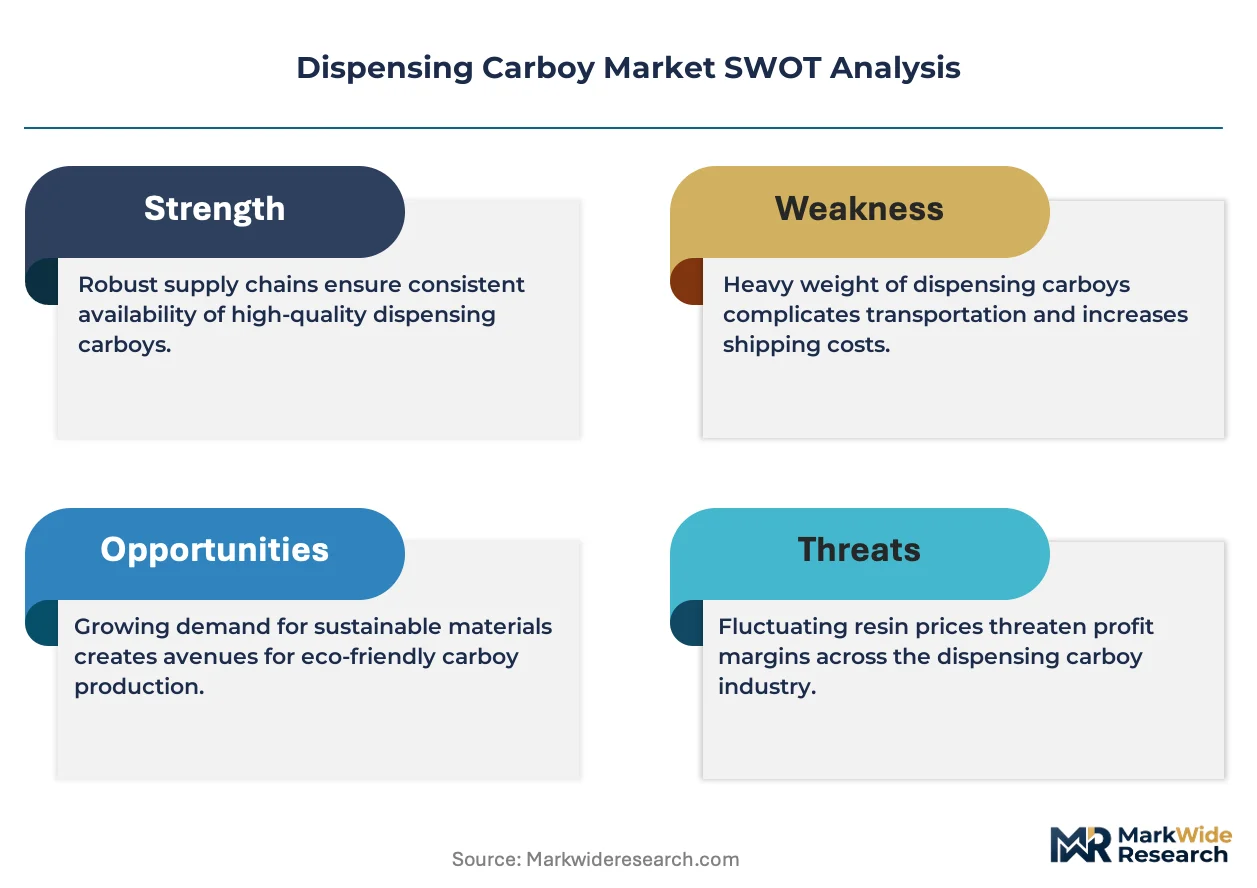
- HDPE:High-density polyethylene delivers impact resistance and chemical compatibility at unit economics that sustain high-volume industrial deployment. Pharmaceutical-grade variants with USP Class VI certification are displacing glass in vaccine adjuvant handling where breakage risk outweighs extractables concerns.
- Glass:Borosilicate construction provides absolute chemical inertness for analytical standards and reference material preparation. German and Swiss quality control laboratories maintain this preference despite Schott AG and Corning feedstock concentration creating supply vulnerability.
- Polyethylene:Lower-density variants serve non-pharmaceutical chemical handling where sterilization validation is unnecessary. Agricultural and coatings manufacturers in India source these for solvent and reagent storage under CDSCO-exempt industrial chemical frameworks.
- Stainless Steel:316L electropolished vessels anchor permanent infrastructure in large-scale parenteral manufacturing. Legacy facilities resist conversion to disposable alternatives due to capital depreciation schedules and validated cleaning protocol investment.
Highest certification burden: Glass. Steepest volume expansion trajectory: HDPE.
Application:
Customer type determines regulatory overlay intensity and service bundling expectations.
- Pharmaceutical:Sterile filling operations demand pre-qualified vessels with documented extractables profiles and container closure integrity validation. FDA and EMA protocol divergence forces manufacturers to maintain dual certification datasets, extending procurement timelines.
- Laboratory:Research workflows prioritize catalog breadth and same-day fulfillment over material traceability. North American academic medical centers consolidate procurement through integrated supply platforms to reduce maverick spending on routine consumables.
- Industrial:Chemical handling emphasizes mechanical durability and chemical resistance certification. REACH Annex XVII compliance pressure on fluoropolymer coatings is forcing reformulation of barrier layers in European manufacturing facilities.
- Food & Beverage:Migration testing under EU 10/2011 and FDA food contact notification requirements constrains material selection. Flavor and fragrance compound producers specify fluoropolymer-lined vessels to prevent organoleptic contamination.
Most stringent qualification: Pharmaceutical. Fastest service model evolution: Laboratory.
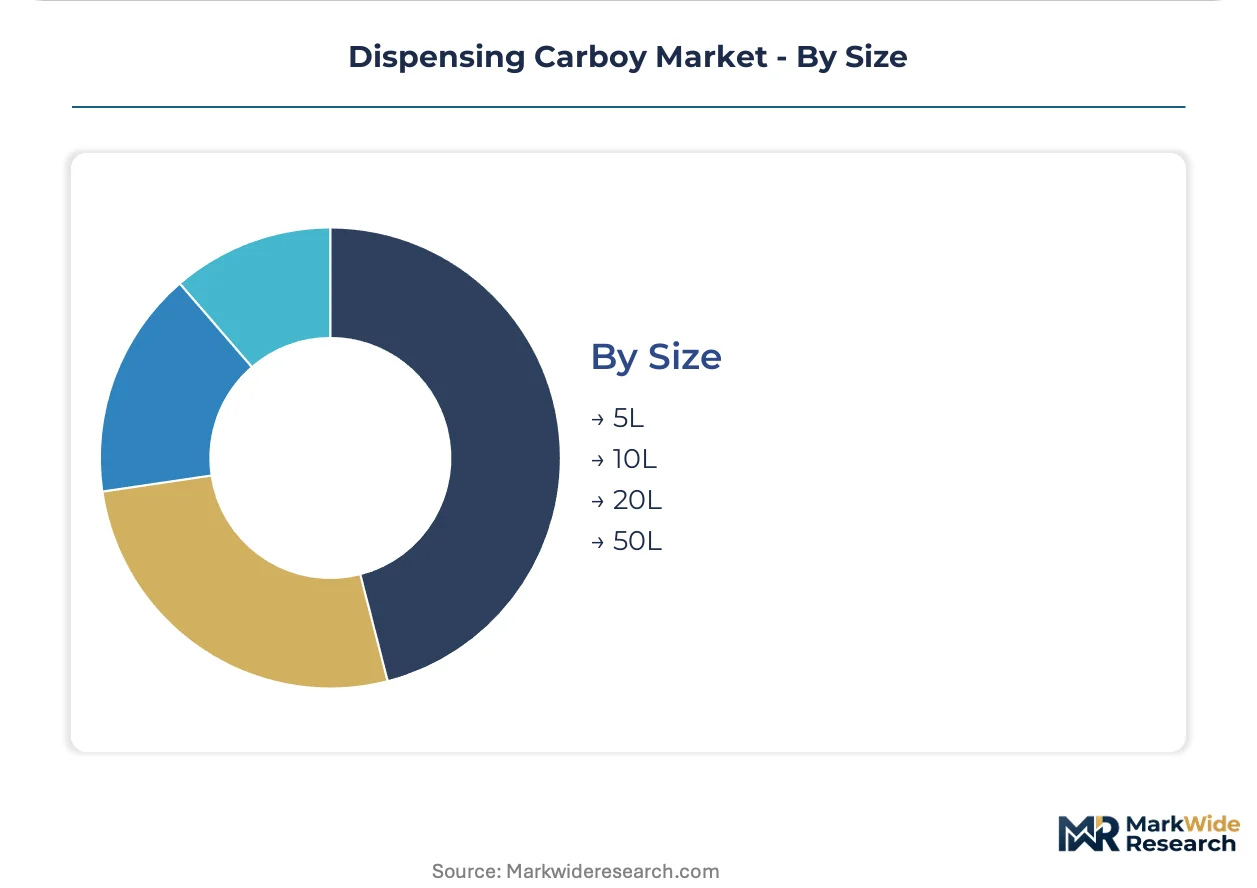
Size:
Volume scale correlates with automation compatibility and capital equipment integration requirements.
- 20L:Intermediate capacity bridges manual handling and automated liquid transfer systems. Mid-scale bioprocessing operations in Indian CDMO clusters adopt this format for seed train expansion media preparation.
- 10L:Standard reference volume for analytical method development and stability testing protocols. Quality control laboratories standardize on this capacity to minimize compound consumption during validation studies.
- 5L:Bench-scale formats dominate early-stage formulation development where material scarcity constrains batch size. Discovery biology groups prioritize compact footprint over transfer efficiency.
- 50L:Bulk capacity requires mechanical handling equipment and dedicated containment infrastructure. Commercial vaccine manufacturing lines specify this scale for adjuvant and excipient staging.
Dominant procurement volume: 20L. Gaining share fastest: 50L.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Germany and Switzerland outpaces domestic consumption, while India and the United States absorb vessel imports to feed expanding biologics production. This geographic split shapes material qualification timelines and service bundling expectations.
United States
FDA container closure integrity guidance drives pre-qualification demand for fluoropolymer-lined vessels among parenteral drug manufacturers. The agency's extractables testing protocols force suppliers to maintain dual validation datasets alongside EMA requirements. Greater Boston's contract manufacturing cluster sources multi-outlet carboys for perfusion bioreactor workflows.
Germany
EMA Annex 1 sterile manufacturing revisions compress procurement timelines for biologics producers in Baden-Württemberg and Bavaria. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances pressure reformulation of PTFE barrier coatings. The Rhine-Main biotech corridor concentrates specialized vessel procurement through preventive maintenance contracts.
Switzerland
Swissmedic alignment with EMA protocols accelerates adoption of pre-qualified closed-system carboys in Basel's pharmaceutical manufacturing hub. The country's precision engineering tradition elevates expectations for port configuration tolerances in multi-outlet designs. Contract manufacturers around Lake Geneva specify gamma-stable hybrid vessels for cell culture media storage.
India
CDSCO accelerated approval pathways for biosimilars attract contract development organizations to Hyderabad and Bengaluru. The regulator's evolving stance on sterile manufacturing equipment creates qualification uncertainty for imported vessels. Karnataka's biotech parks drive demand for 20L formats in seed train expansion media preparation.
China
NMPA harmonization efforts with FDA extractables protocols reshape supplier qualification requirements for domestic biologics manufacturers. The regulator's emphasis on container closure documentation elevates procurement scrutiny in Shanghai and Suzhou pharmaceutical zones. Yangtze River Delta contract manufacturers adopt hybrid HDPE-glass configurations to balance cost and compliance.
Dispensing Carboy Market Competitive Environment
Capital-heavy producers compete with asset-light designers and distributors across tiered pricing strata. Thermo Fisher Scientific and Corning Incorporated anchor the premium segment through captive manufacturing infrastructure, while catalog distributors occupy the high-velocity consumables tier. The market structure stratifies across three archetypes: integrated life science conglomerates, specialized glassware fabricators, and digital-first laboratory supply platforms. Consolidation pressure manifests through service bundling and preventive maintenance contract expansion rather than capacity-driven M&A.
Among integrated life science conglomerates, Thermo Fisher Scientific exemplifies the service-anchored archetype through certified calibration programs that convert vessel sales into recurring revenue. DWK Life Sciences occupies a position within specialized glassware expertise, leveraging regional distribution density across European research hubs. Cole-Parmer represents the digital fulfillment vector, anchoring procurement friction reduction through same-day catalog integration. These three patterns illustrate how competitive positioning diverges across premium engineering, regional density, and transactional velocity without requiring uniform strategic moves.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| DWK Life Sciences |
| Cole-Parmer |
| Corning Incorporated |
| Berry Global |
| Nalgene |
| Saint-Gobain |
| Foxx Life Sciences |
| Dynalon Labware |
| Others |
Value Chain & Pricing Dynamics
Skilled glassblowing workforce concentration in Thuringia and Saxony drives labor-cost differentials that widen pricing-tier spreads between artisan-certified borosilicate vessels and mass-molded HDPE alternatives. German manufacturing clusters command premium positioning through specialized port-configuration tolerances, while Asian thermoplastic processors capture volume tiers via automated extrusion economies.
Pricing Analysis
Margin tightening in pharmaceutical-grade glass traces to Schott AG and Corning feedstock concentration, which amplifies energy-price pass-through volatility. Three-tier pricing structure across premium certified, standard laboratory, and economy industrial levels separates extractables-tested vessels from routine chemical handling formats. Cost-down pressure on fluoropolymer-lined hybrids accelerates because REACH Annex XVII compliance forces reformulation R&D recovery. Academic medical centers exhibit highest price sensitivity through consolidated procurement platforms, while parenteral drug manufacturers absorb premium positioning to secure EMA Annex 1 documentation.
Supply Chain Analysis
Returns and refurbishment flows for gamma-degraded fluoropolymer liners create reverse-logistics complexity that specialized service providers monetize through preventive maintenance contracts. Manufacturing concentrates in Germany, China, and the United States, with German facilities anchoring precision multi-outlet fabrication and Chinese plants scaling HDPE commodity output. Raw material dependencies rest on high-purity borosilicate tubing, pharmaceutical-grade HDPE resin, and PFA barrier coatings. Single-source vulnerability in premium glass feedstock elevates supply risk during energy market disruptions. Distribution runs through integrated laboratory supply platforms and regional distributor networks serving bioprocessing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in pharmaceutical-grade borosilicate glass prop pricing power for qualified vessel manufacturers, with Schott AG and Corning feedstock bottlenecks limiting rapid capacity response to biologics demand surges.
For Market Incumbents: Anticipate fluoropolymer liner degradation limitations eroding gamma-sterilization protocol flexibility by accelerating hybrid vessel R&D with ceramic-coated alternatives. Anchor customer relationships through preventive maintenance contract bundling that converts capital sales into recurring calibration revenue streams. Defend against asset-light digital distributors by deepening regional service infrastructure density in German and Swiss biologics clusters. For New Entrants and Emerging Players: Enter via CDSCO-aligned contract development organizations in Hyderabad and Bengaluru, where accelerated biosimilar approval pathways outpace qualified vessel supply. Target 20L format seed-train expansion media preparation as the most penetrable application tier, given capital-light automation compatibility. Pursue same-day fulfillment partnerships with academic medical center procurement platforms to reduce incumbent catalog friction. For Investors and Strategic Acquirers: Re-rating potential sits with specialized glassware fabricators possessing ISO 15378 certification and captive European distribution density, given EMA-FDA protocol divergence extending qualification timelines. Long-term viability favors asset-light designers with digital channel integration over capital-heavy commodity molders facing resin price volatility. Monitor CDSCO sterile manufacturing equipment guidance evolution as inflection signal for Indian manufacturing capacity allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Liner Reformulation | REACH Annex XVII compliance forces alternative barrier chemistry validation in German facilities. |
| Preventive Maintenance Contract Expansion | Certified calibration programs convert vessel sales into recurring revenue at Thermo Fisher Scientific scale. |
| Hybrid Vessel Configuration Development | Gamma-stable HDPE shells with disposable liners bridge cost and contamination control requirements. |
| Digital Catalog Platform Integration | Same-day fulfillment capabilities reduce procurement friction for North American academic medical centers. |
| Regional Service Infrastructure Density | European research hub proximity anchors long-term relationships against asset-light distributors. |
Study Parameters
Document review covered FDA container closure integrity guidance, EMA Annex 1 sterile manufacturing revisions, ISO 15378 pharmaceutical packaging standards, and USP Class VI biological reactivity protocols, complemented by interviews with bioprocessing engineers, regulatory affairs specialists, laboratory procurement managers, and aftermarket service directors. Secondary validation drew from customs trade data, SEC filings of listed life science conglomerates, and pharmaceutical manufacturing facility databases. Bottom-up vessel shipment analysis triangulated against top-down biologics production capacity expansion estimates.
Segment-level projections across material type, product configuration, application tier, and geographic manufacturing cluster fed into analytical framework spanning the projection horizon. CAGRs derived from regression against biologics contract manufacturing organization capacity buildouts and sterile filling operation expansion trajectories. Industry-specific inputs encompassed extractables testing protocol evolution and REACH Annex XVII fluoropolymer restriction implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA-FDA regulatory harmonization delays or gamma sterilization protocol abandonment. Practitioners should monitor CDSCO sterile equipment qualification stance and Schott AG capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Can Sleeves Market