
 Skep Bottle Market | 2026-2036
Skep Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Skep Bottle Market Analytics
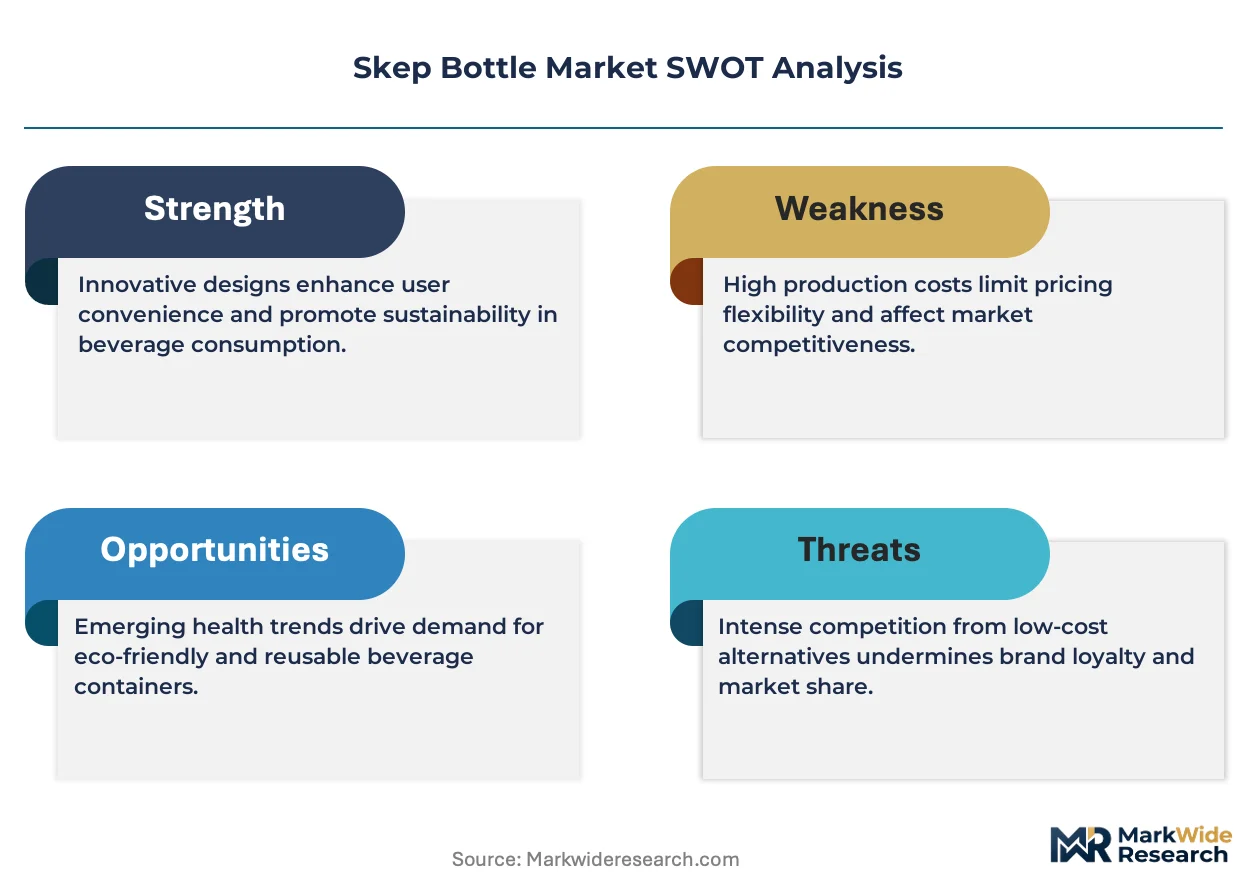
ISO 22000 food safety management certification is unwinding competitive barriers for Skep Bottle suppliers seeking entry into institutional channels. Berry Global leverages captive resin compounding operations to sustain margin control across North American beverage packaging contracts. Amcor anchors its position through pharmaceutical-grade blow-molding expertise repurposed for premium reusable formats. Silgan Holdings competes via metal closure integration that extends supply chain scope beyond pure bottle manufacturing.
Skep bottles constitute rigid container systems engineered from PET, HDPE, glass, or stainless steel substrates, typically featuring threaded neck finishes compatible with sports-cap or straw-lid configurations for active-consumption scenarios. Wall thickness, thread pitch, and blow-stretch ratios determine pressure tolerance and thermal retention performance across usage environments. Plastic variants lead volume throughput due to cost scalability, while stainless steel segments command premium positioning through vacuum-insulation technology and extended lifecycle claims. Reusable usage types are gaining structural momentum as hospitality procurement shifts away from single-use mandates, though customizable formats occupy the highest margin pool through minimum-order-quantity premiums and brand-licensing arrangements.
FDA Title 21 CFR food-contact substance notifications govern polymer selection and additive migration limits for Skep Bottles distributed in the United States, while EU REACH and F-Gas Regulation frameworks constrain fluorinated barrier coatings and propellant choices for insulated European products. California's Proposition 65 warning-label requirements add a state-level compliance layer that shapes decoration decisions and material substitutions for brands serving the West Coast. Stakeholders must monitor evolving extended-producer-responsibility legislation across multiple jurisdictions to anticipate deposit-system expansions that could restructure channel economics and regional manufacturing footprints.
Market Dynamics
ISO 22000 certification requirements are restructuring supplier qualification protocols across institutional procurement channels, forcing mid-tier manufacturers to absorb compliance costs or exit food-service contracts entirely.
Growth Catalysts
- EU F-Gas Regulation phase-down:Fluorinated propellant restrictions on insulated bottle production are accelerating vacuum-insulation technology R&D investment among German and Austrian suppliers.
- California Proposition 65 enforcement:Warning-label mandates for bisphenol trace contaminants are compelling material substitutions toward Tritan copolyester and glass-lined stainless steel formats.
- Gym operator branded hydration programs:Fitness chains in Germany and the United States are deploying minimum-order-quantity premium contracts to secure exclusive bottle designs with member retention tie-ins.
Market Restraints
- PET resin price volatility:Feedstock cost swings tied to crude oil futures are compressing margin stability for high-volume blow-molding operations serving discount retail channels.
- Chinese stainless steel supply concentration:Vacuum-insulation manufacturing depends on 304-grade sheet metal sourcing from Zhejiang and Guangdong provinces, creating geopolitical exposure.
- Migration testing bottlenecks:FDA Title 21 CFR food-contact substance notification timelines stretch 180-270 days, delaying new polymer formulation launches.
Strategic Opportunities
- Deposit-return system expansion:Germany's DRS infrastructure investments are creating closed-loop collection economics that favor reusable bottle formats with embedded RFID tracking.
- Hotel amenity program conversion:Hospitality procurement teams are replacing single-use plastic with customizable stainless steel formats carrying property branding.
- Dual-wall ceramic coating convergence:Vacuum-insulation technology paired with ceramic interior linings is opening premium positioning against pure metal competitors.
Industry Challenges
- Blow-molding technician scarcity:Pharmaceutical-grade PET processing expertise resides with aging workforces at Amcor and Berry Global facilities, constraining talent mobility.
- Extended producer responsibility integration:Multi-jurisdictional take-back mandate compliance requires ERP system overhauls for mid-cap suppliers lacking IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skep Bottle Market |
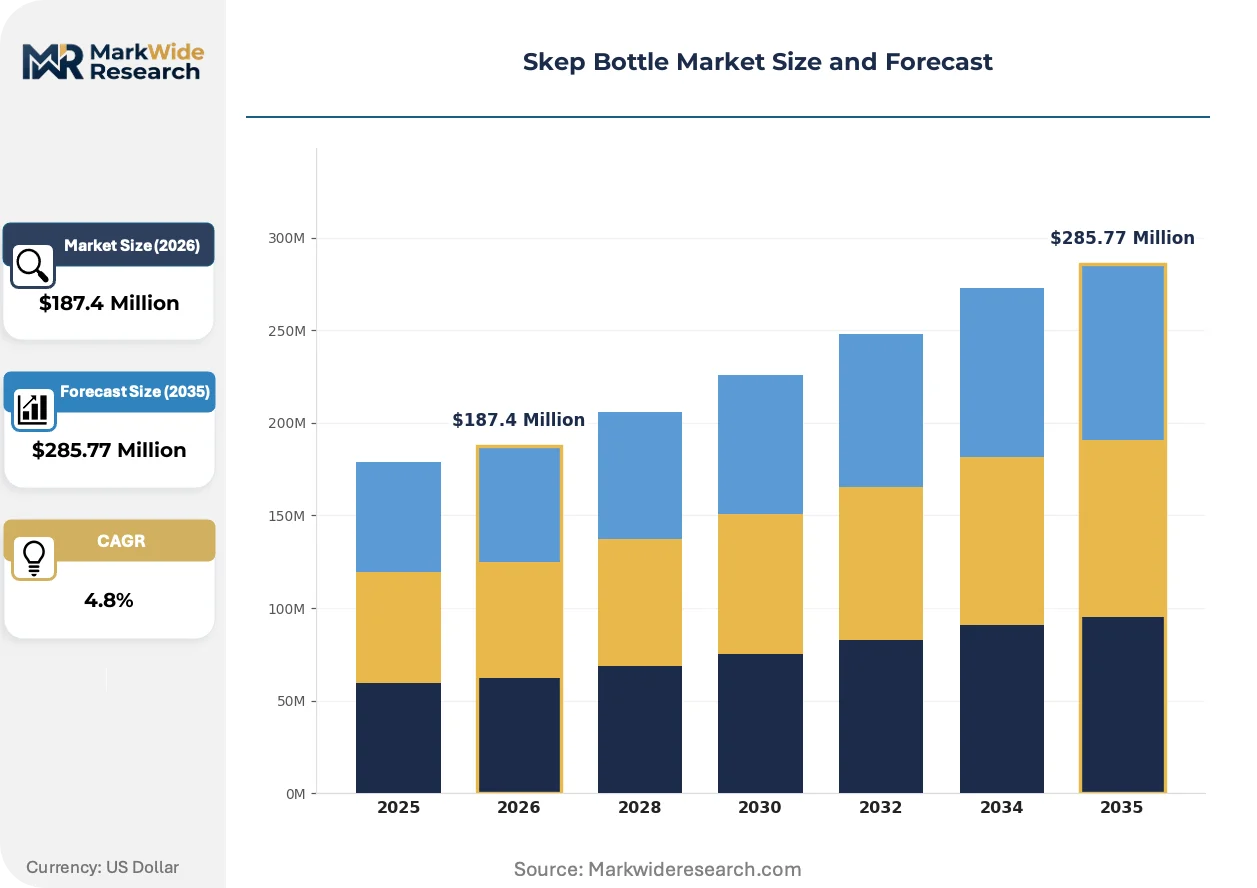
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Stainless Steel, Aluminum Usage Type: Single-use, Reusable, Insulated, Customizable End User: Households, Restaurants, Gyms, Events Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Direct Sales |
| Companies Covered | Berry Global, Amcor, Silgan Holdings, Graham Packaging, Alpha Packaging, Plastipak, Alpla, Comar, CKS Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skep Bottle Market Evolving Landscape
Material science advances and regulatory stringency are compressing product development cycles while opening premium positioning through functional differentiation rather than decoration alone.
Ceramic interior coating technology is supplanting unlined stainless steel in vacuum-insulation applications. Premium hospitality procurement teams are specifying ceramic-lined formats for flavor-neutral claims within eighteen-month replacement cycles. This shift is compressing pure-metal supplier margins while enabling 40-60% price premiums for dual-substrate manufacturers with coating line investments.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier coatings from European-insulated bottle production. Manufacturers are pivoting toward plasma-enhanced chemical vapor deposition alternatives with comparable thermal performance. German and Austrian suppliers face the steepest reformulation timelines given their concentration in high-performance outdoor segments.
Direct-to-gym subscription models are displacing traditional wholesale distribution for branded hydration programs. Fitness operators in Germany and California are contracting multi-year bottle refresh cycles with embedded RFID loyalty tracking. This channel compression is most visible among boutique studio chains seeking member lifetime value metrics over unit margin extraction.
Skep Bottle Market Segmentation
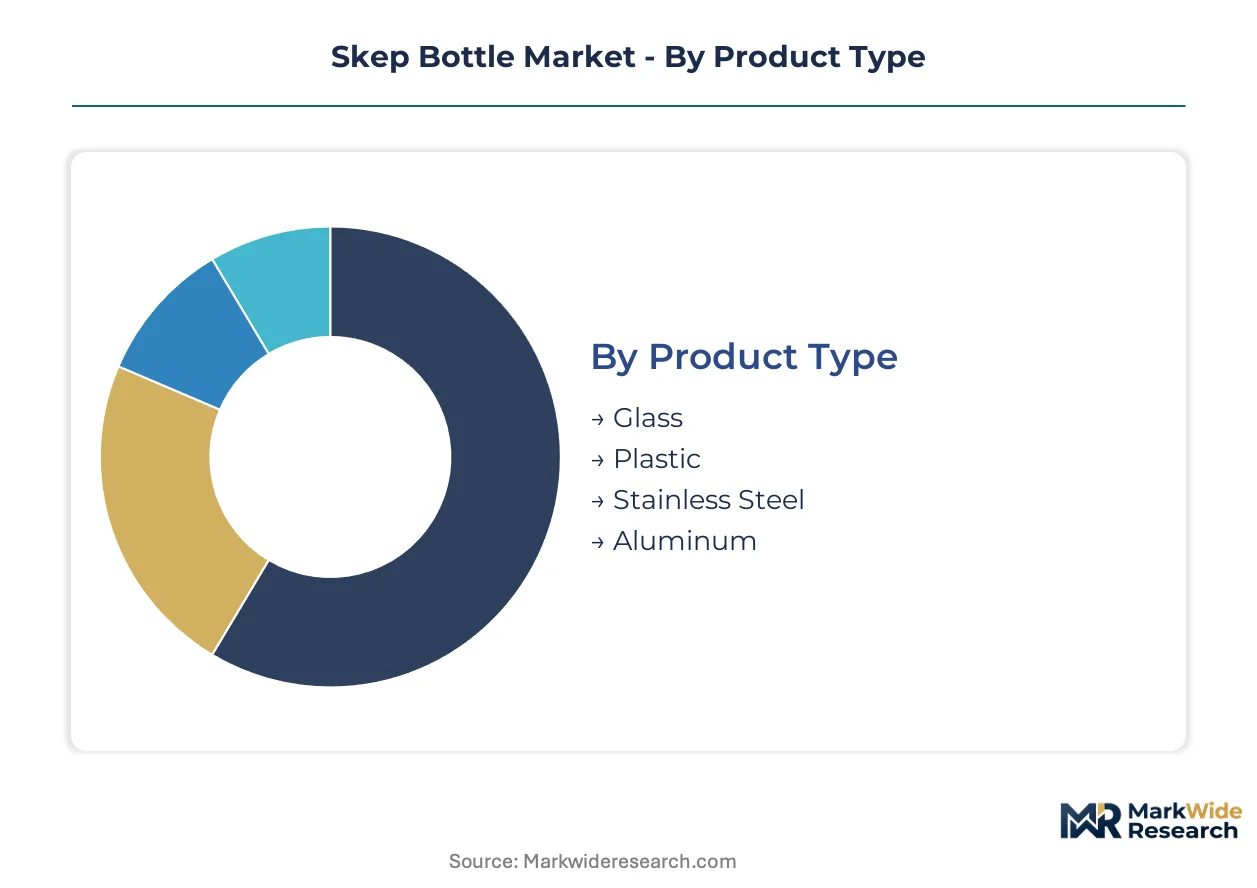
Skep Bottle procurement patterns diverge sharply across material substrates and usage scenarios. Gym operators and hospitality buyers impose distinct performance specifications that reshape supplier priorities within each segment cluster.
Product Type:
Plastic variants face the most acute substitution pressure from stainless steel and glass as EPR mandates and deposit-return systems expand across Germany and California.
- Plastic:PET and HDPE blow-molded formats dominate unit economics through Berry Global's captive resin compounding. FDA Title 21 CFR food-contact notifications constrain additive migration limits, compressing formulation flexibility for discount retail channels.
- Stainless Steel:Vacuum-insulation technology commands premium positioning through 304-grade sheet metal sourcing concentrated in Zhejiang and Guangdong provinces. German fitness chains specify these formats for branded hydration programs with embedded RFID loyalty tracking.
- Glass:Borosilicate and soda-lime compositions satisfy California Proposition 65 compliance without bisphenol contamination risks. Hospitality procurement teams in Germany favor glass for flavor-neutral claims within hotel amenity conversions.
- Aluminum:Lightweight extruded formats serve single-use event applications where weight minimization overrides thermal retention requirements.
Plastic anchors the volume base while stainless steel gains share at the steepest rate.
Usage Type:
Cost tier stratification separates capital-intensive insulated production from commodity single-use formats.
- Reusable:Multi-cycle designs align with Germany's DRS infrastructure investments and closed-loop collection economics. RFID-embedded formats enable gym operator subscription models with member retention tie-ins.
- Insulated:Dual-wall vacuum technology paired with ceramic interior linings opens 40-60% price premiums against pure metal competitors. EU F-Gas Regulation phase-down is accelerating plasma-enhanced chemical vapor deposition R&D among Austrian suppliers.
- Customizable:Minimum-order-quantity premiums and brand-licensing arrangements occupy the highest margin pool. Boutique fitness studios in California contract multi-year refresh cycles for exclusive designs.
- Single-use:Blow-molded PET serves event and hospitality applications facing elimination under municipal single-use mandates.
Reusable formats command the widest procurement attention while customizable segments extract the highest per-unit margins.
End User:
Application-specific requirements fragment demand across performance tiers and compliance thresholds.
- Gyms:Branded hydration programs with member lifetime value metrics drive multi-year contracts for stainless steel and customizable formats. ISO 22000 certification gates institutional procurement.
- Restaurants:Food-service channels prioritize FDA-compliant plastic and glass for high-turnover beverage service.
- Households:Retail purchasing concentrates in plastic and entry stainless steel through big-box and online channels.
- Events:Temporary deployment favors lightweight aluminum and single-use plastic under tight procurement budgets.
Gym operators anchor premium demand growth while household channels sustain the broadest volume throughput.
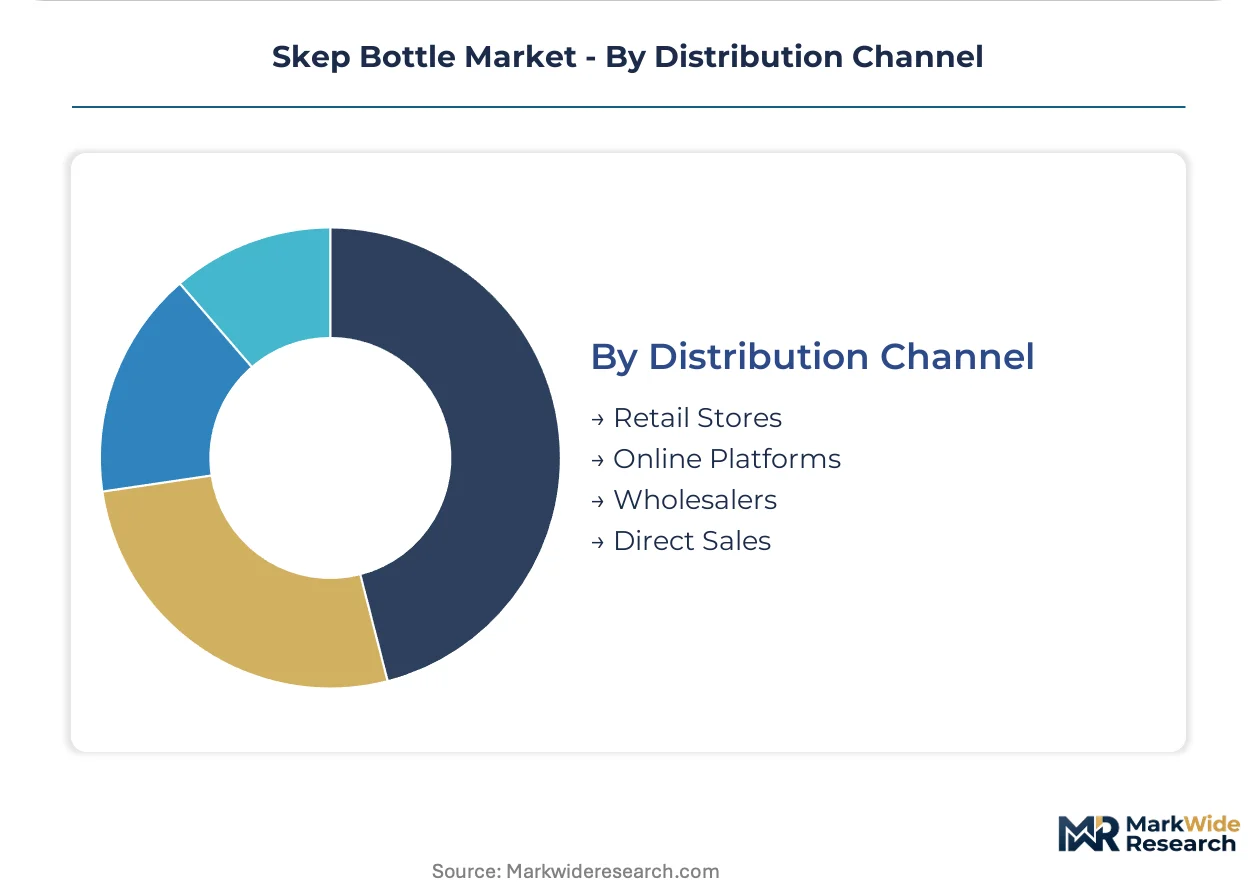
Distribution Channel:
Customer type concentration shapes margin capture across direct and intermediated routes.
- Direct Sales:Gym operators and hospitality groups contract manufacturer-direct for customizable formats with embedded loyalty technology.
- Online Platforms:D2C subscription models displace wholesale distribution for branded refresh cycles.
- Retail Stores:Big-box and specialty fitness outlets move standard reusable formats with limited customization.
- Wholesalers:Event and restaurant procurement flows through distributor networks for single-use and standard reusable inventory.
Direct sales capture the steepest margin expansion while online platforms climb fastest in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gym operators and hospitality procurement teams concentrate demand in markets with mature fitness infrastructure and stringent sustainability mandates. Germany and the United States anchor premium segment volume through branded hydration programs and hotel amenity conversions. Regulatory divergence across jurisdictions forces suppliers to maintain multiple compliance certifications simultaneously.
United States
California's Proposition 65 enforcement drives material substitutions toward Tritan copolyester and glass-lined formats among West Coast suppliers. FDA Title 21 CFR food-contact substance notifications govern polymer selection for national distribution, stretching notification timelines to 180-270 days. Los Angeles and San Francisco fitness chains deploy direct-to-gym subscription models with embedded RFID loyalty tracking.
Germany
Fitness culture convergence with EU Green Deal mandates accelerates reusable bottle procurement through institutional channels. The F-Gas Regulation phase-down compels vacuum-insulation manufacturers toward plasma-enhanced chemical vapor deposition alternatives. Bavarian and North Rhine-Westphalian suppliers dominate high-performance outdoor segments with ceramic-lined dual-wall production.
China
Zhejiang and Guangdong provinces concentrate 304-grade stainless steel sheet metal sourcing for vacuum-insulation manufacturing. The country's national packaging regulator enforces GB standards for food-contact materials that diverge from FDA and EU frameworks. Shenzhen and Ningbo industrial clusters face geopolitical exposure as Western buyers diversify supply origins.
Japan
METI circular economy guidelines incentivize closed-loop collection systems for reusable beverage containers in Tokyo and Osaka metropolitan areas. JIS standards for thermal retention performance exceed baseline ISO requirements, filtering import competition. Domestic hospitality groups specify ceramic-coated formats for premium hotel amenity programs.
United Kingdom
Post-Brexit REACH alignment creates dual regulatory tracking burden for suppliers serving both UK and EU markets. London fitness studio chains contract multi-year refresh cycles for customizable stainless steel formats with property branding. Midlands manufacturing clusters specialize in blow-molded PET for event and single-use applications facing municipal elimination mandates.
Skep Bottle Market Competitive Landscape
Player mix skews toward diversified packaging conglomerates with captive resin operations and mid-tier specialists with ISO 22000 certification. Consolidation pressure intensifies as institutional procurement gates institutional contracts behind food safety management credentials. Three archetypes dominate: vertically integrated resin compounders, pharmaceutical-grade blow-molding repurposers, and metal closure integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek geographic coverage and technology access.
Within the diversified packaging tier, Berry Global exemplifies captive resin compounding operations that sustain margin control across North American beverage contracts. Amcor anchors pharmaceutical-grade blow-molding expertise repurposed for premium reusable formats. Silgan Holdings occupies a position defined by metal closure integration that extends supply chain scope beyond pure bottle manufacturing.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Silgan Holdings |
| Graham Packaging |
| Alpha Packaging |
| Plastipak |
| Alpla |
| Comar |
| CKS Packaging |
| Others |
Value Network & Pricing Analysis
One-hundred-eighty to two-hundred-seventy day FDA notification timelines compress supplier working-capital cycles and amplify pricing power for incumbents with pre-cleared resin formulations. This lead-time band concentrates procurement leverage among Berry Global and Amcor, forcing mid-tier competitors toward spot-market resin exposure.
Pricing Analysis
Cost-plus contracts indexed to crude-oil futures govern PET blow-molding supply to discount retail channels. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-lined stainless steel from unlined metal and commodity plastic. Pricing pressure stems from Chinese 304-grade sheet metal cost volatility. Gym operators show lowest price sensitivity due to member-retention bundling, while event procurement teams face acute budget constraints.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for Zhejiang and Guangdong stainless steel sourcing. Vacuum-insulation manufacturing rests on Chinese sheet metal, German ceramic-coating equipment, and Austrian plasma-deposition technology. Single-source vulnerability concentrates in 304-grade supply. Distribution runs through direct manufacturer contracts for customizable formats and wholesaler networks for single-use inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated gym operators and hospitality groups with multi-year contract leverage, fragmenting supplier pricing autonomy.
For Market Incumbents: Fortify ISO 22000 certification moats to gate institutional procurement against uncertified mid-tier rivals. Deepen captive resin compounding to buffer margin compression from feedstock volatility. Prioritize ceramic-coating line investments to capture 40-60% price premiums before Austrian competitors scale plasma-enhanced deposition capacity. For New Entrants and Emerging Players: Differentiate on RFID-embedded loyalty integration for boutique fitness studio chains in California and Germany. Target hotel amenity conversion programs seeking flavor-neutral ceramic-lined formats. Pursue direct-to-gym subscription models displacing traditional wholesale distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum-insulation manufacturing due to coating line and plasma-deposition equipment requirements. Five-to-ten year viability favors suppliers with backward-integrated resin operations or captive ceramic-coating capabilities. Monitor EU F-Gas Regulation enforcement timelines as inflection signal for Austrian and German supplier restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Line Investment | Enables 40-60% price premiums against unlined stainless steel competitors in hospitality procurement. |
| ISO 22000 Certification Acquisition | Gates food-service contracts as California and EU enforcement tightens supplier qualification protocols. |
| RFID Loyalty Integration | Captures gym operator subscription models with member retention metrics over unit margin extraction. |
| Plasma-Enhanced Deposition R&D | Substitutes fluorinated barrier coatings eliminated under REACH Annex XVII restrictions. |
| Direct-to-Gym Distribution Buildout | Displaces wholesale intermediation for branded hydration programs with embedded refresh cycles. |
Research Methodology
A spread of perspectives from blow-molding operations managers, gym procurement directors, hospitality supply chain leads, and FDA regulatory consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA Title 21 CFR filings, EU REACH substance registrations, customs trade data, and SEC packaging sector disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Segmentation dimensions modeled span material substrate, usage type, end-user application, and distribution channel across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporated PET resin price elasticity coefficients and gym operator contract renewal rates.
Material uncertainties — geopolitical disruption to Chinese stainless steel supply, accelerated EU F-Gas Regulation phase-down timelines, and municipal single-use mandate expansion — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Sugarcane Bottles Market