
 Latin America Flexible Plastic Packaging Market | 2026-2036
Latin America Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Flexible Plastic Packaging Market Insights
Buyer concentration across Latin American food processors is broadening as multinational CPG brands regionalize sourcing while mid-sized local cooperatives fragment procurement into smaller batch orders. Amcor PLC leverages its integrated film extrusion and converting footprint across Brazil and Argentina to capture volume from both tiers. Berry Global Inc. anchors its position through specialized healthcare-grade clean-room films that meet ANVISA's stringent pharmaceutical packaging protocols. Sealed Air Corporation differentiates via vacuum skin and modified-atmosphere technologies targeted at protein exporters in southern Brazil and Chilean salmon operations.
Latin America flexible plastic packaging encompasses polymer-based structures—typically multilayer laminates of polyethylene, polypropylene, or polyester ranging from 20 to 150 micrometers—that conform to product geometry during filling, sealing, or shrink operations. These materials provide moisture barriers, oxygen exclusion, and mechanical protection for perishable goods distributed through extended tropical supply chains. Stand-up pouches with spout closures command premium positioning in personal care and beverage applications where shelf differentiation and dispensing convenience justify higher unit economics. Rollstocks dominate high-volume food manufacturing where form-fill-seal automation minimizes labor and maximizes throughput across Brazil's processed meat and dairy sectors. Polyethylene remains the baseline material for cost-driven commodity applications, while polyester multilayer structures capture margin in pharmaceutical blister and sachet formats requiring thermal stability and print fidelity.
ANVISA governs pharmaceutical and medical device packaging integrity through stability testing and extractables protocols that restrict acceptable polymer grades and adhesive systems. Brazil's CONAMA resolutions and emerging state-level extended producer responsibility statutes are redirecting converter R&D toward mechanically recyclable monomaterial structures and post-consumer recycled content verification. Mexico's PROFEPA and SEMARNAT enforce progressively tighter limits on volatile organic compound emissions from solvent-based lamination, accelerating water-based and solventless adhesive migration across the northern border industrial zone. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks while calibrating capital allocation between compliance-driven retrofit and next-generation circular material platforms.
Market Dynamics
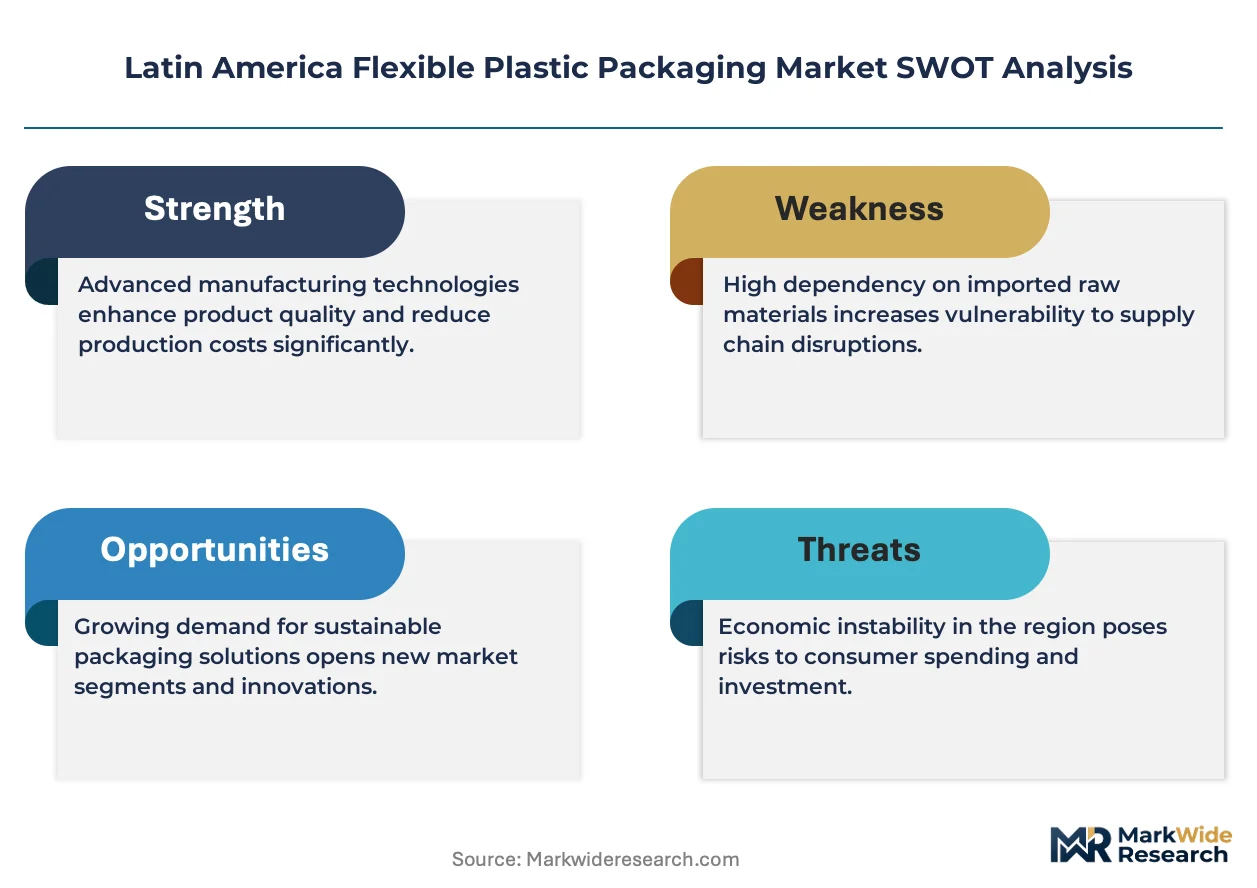
Extended producer responsibility mandates across Brazil and Mexico are forcing converters to reengineer multilayer structures into mechanically recyclable monomaterials, compressing margins while opening premium positioning for certified circular film suppliers.
Growth Catalysts
- ANVISA pharmaceutical protocols:Brazil's stability testing and extractables requirements restrict acceptable polymer grades, creating captive demand for healthcare-grade clean-room film capabilities among domestic converters.
- Modified-atmosphere packaging:Protein exporters in southern Brazil and Chilean salmon operations are vacuum skin packaging to extend shelf life through extended tropical supply chains.
- São Paulo industrial corridor concentration:Petrochemical feedstock access and converting infrastructure clustering around consumer goods headquarters generates procurement gravity for high-barrier rollstocks.
Market Restraints
- Ethylene feedstock volatility:Polyethylene pricing tracks naphtha and ethane import exposure, squeezing converter margins on commodity film contracts with limited pass-through mechanisms.
- Solvent-based lamination regulatory friction:Mexico's PROFEPA and SEMARNAT volatile organic compound emission limits are forcing costly adhesive system conversions in northern border industrial zones.
- Paper and molded fiber substitution:E-commerce and quick-service food channels are piloting fiber-based alternatives for secondary packaging, threatening polyethylene pouch volumes in non-barrier applications.
Strategic Opportunities
- Colombia's underpenetrated dairy sector:Processed cheese and yogurt manufacturers are migrating from rigid containers to spouted stand-up pouches, creating first-mover advantage for aseptic filling integration.
- Post-consumer recycled content mandates:Emerging state-level extended producer responsibility statutes in Brazil are generating certified recycled polyethylene demand that outstrips domestic mechanical recycling capacity.
- Water-based adhesive convergence:Solventless lamination technology married to digital print workflows is enabling short-run customization for regional brand launches without volatile organic compound compliance burdens.
Industry Challenges
- Polymer scientist and adhesive formulator talent scarcity:Formulation chemistry expertise for high-barrier multilayer structures concentrates among retiring specialists, constraining R&D velocity for circular material transitions.
- Clean-room certification timeline compression:ANVISA pharmaceutical packaging audits require 18-24 month validation cycles, locking working capital in qualification batches before commercial volume release.
- Legacy form-fill-seal line incompatibility:Monomaterial films with reduced thermal stability demand sealing jaw retrofits and temperature profile revalidation, fragmenting converter capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Flexible Plastic Packaging Market |
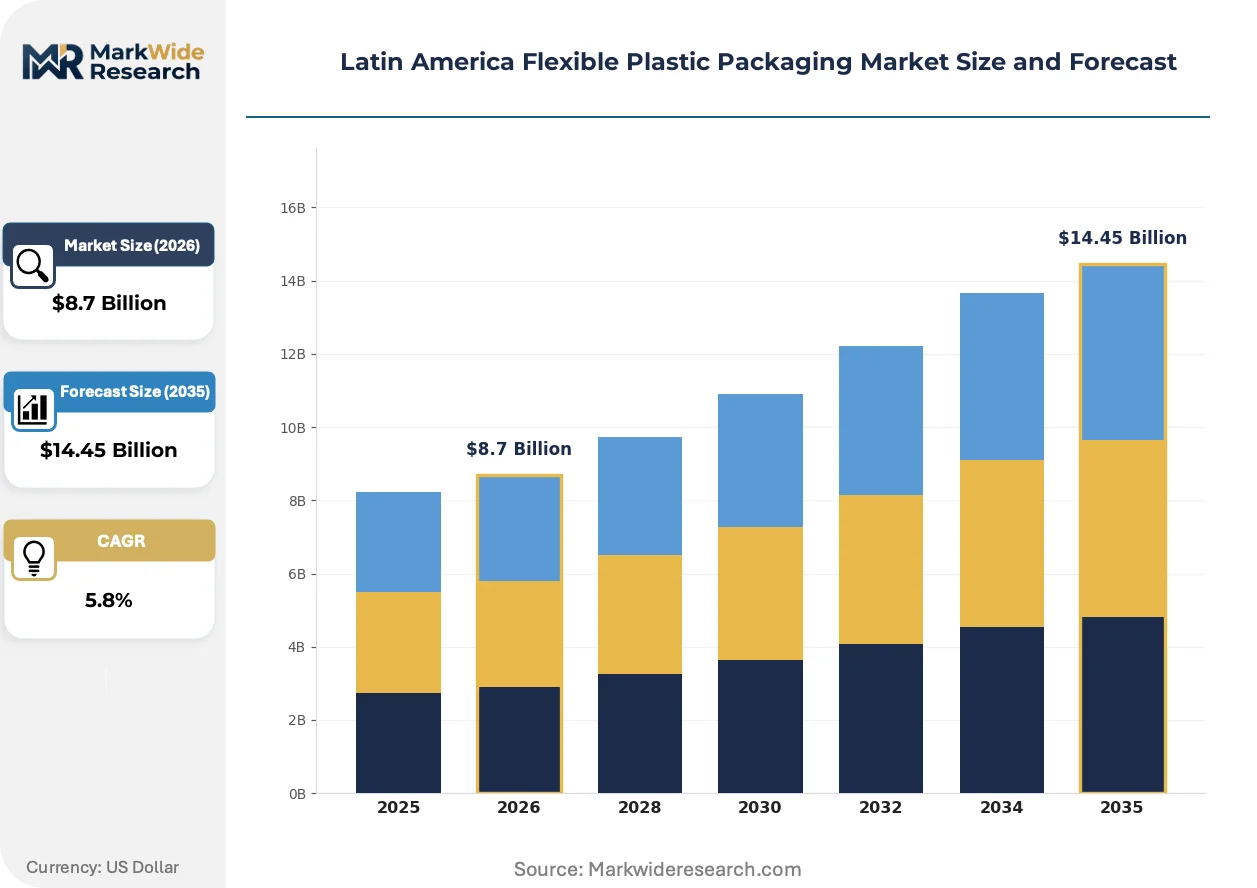
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Pouches, Shrink Films, Rollstocks Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Food & Beverages, Personal Care, Pharmaceuticals, Household Products Closure Type: Zipper, Spout, Flip Top, Others |
| Companies Covered | Amcor PLC, Berry Global Inc., Sonoco Products Company, ALPLA Group, Huhtamaki Oyj, Sealed Air Corporation, Mondi PLC, ProAmpac Holdings Inc., Printpack Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Flexible Plastic Packaging Market Trends and Innovations
Digital print and solventless lamination technologies are collapsing minimum order quantities and changeover times, enabling regional brand proliferation that challenges multinational volume concentration in Latin American flexible packaging.
Monomaterial polyethylene laminates with enhanced barrier coatings are rewriting procurement specifications for frozen food and snack applications. Mid-sized cooperatives in Brazil's interior states are adopting these structures to meet supermarket chain sustainability scorecards without sacrificing shelf life performance. This material transition is compressing demand for legacy nylon and EVOH coextruded films in cost-sensitive segments.
Brazil's CONAMA resolutions and emerging state-level extended producer responsibility frameworks are redirecting converter capital toward mechanical recycling infrastructure and post-consumer recycled content verification systems. The regulatory pressure is most acute in São Paulo's industrial corridor, where multinational CPG headquarters are inserting circularity clauses into supply agreements ahead of statutory deadlines. Converters without certified recycling partnerships are losing preferred supplier status in formal tender processes.
Fragmented batch procurement from mid-sized food cooperatives is displacing consolidated annual contracts as the dominant sourcing pattern. These buyers are aggregating demand through regional purchasing consortiums to access digital print short-run capabilities previously reserved for multinational volumes. The behavioral shift is most visible in Mexico's central highlands dairy and meat processing clusters, where seasonal product launches now justify tooling investments in quick-changeover pouch formats.
Latin America Flexible Plastic Packaging Market Segmentation
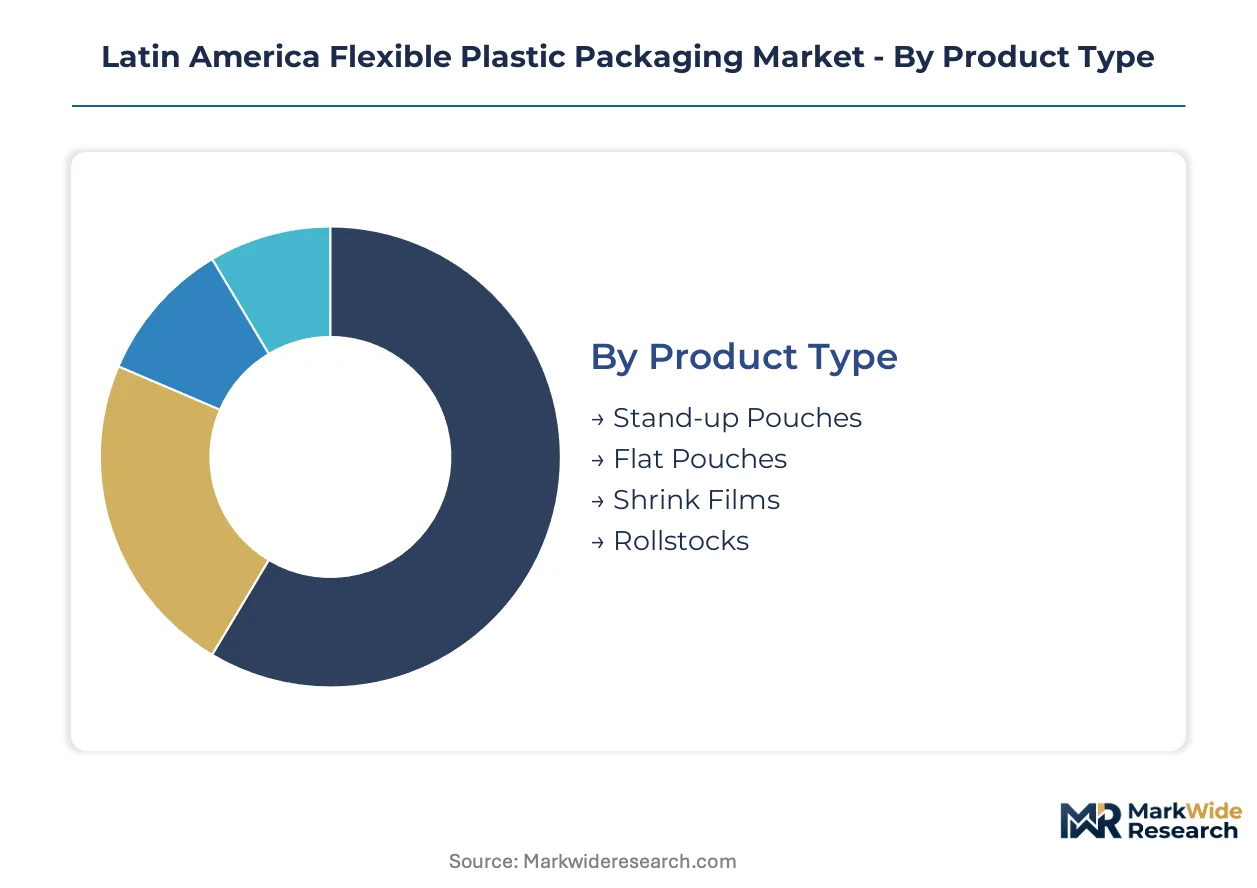
Flexible plastic packaging segmentation in Latin America reflects divergent supply chain configurations across tropical logistics corridors and regulatory jurisdictions. Material choices and format specifications cluster around São Paulo's petrochemical infrastructure while closure innovations respond to fragmented cooperative procurement patterns in Mexico's central highlands and Colombia's dairy belt.
Product Type:
Converter capacity concentrates most heavily in rollstock extrusion and pouch converting equipment, with São Paulo's industrial corridor hosting the densest cluster of multilayer lamination lines serving Brazil's processed meat sector.
- Rollstocks:Continuous web formats wound onto cores for automated form-fill-seal operations, typically 20-80 micrometer multilayer structures combining polyethylene sealant layers with polyester or oriented polypropylene substrates. Demand concentrates in Brazil's processed meat and dairy manufacturing corridors where high-speed automation minimizes labor costs across extended tropical supply chains. ANVISA pharmaceutical protocols are compressing adoption timelines for healthcare-grade clean-room rollstock validation.
- Stand-up Pouches:Three-dimensional flexible containers with gusseted bases enabling vertical shelf presentation, constructed from 80-150 micrometer laminates incorporating barrier coatings for oxygen and moisture exclusion. Personal care and beverage applications in São Paulo and Mexico City command premium positioning where dispensing convenience and brand differentiation justify higher unit economics against rigid alternatives.
- Flat Pouches:Two-dimensional sealed envelopes without dimensional stability, dominant in commodity snack and frozen vegetable applications where cost minimization supersedes shelf presence. Mid-sized cooperatives in Brazil's interior states aggregate procurement through regional consortiums to access short-run digital print capabilities.
- Shrink Films:Oriented polymer webs that contract around product geometry upon heat application, primarily serving secondary bundling and retail-ready multipack formats. Protein exporters in southern Brazil leverage printed shrink sleeves for brand visibility in export cold chains.
Today's leader: Rollstocks. Tomorrow's challenger: Stand-up Pouches.
Material:
Petrochemical feedstock access through São Paulo's coastal refining infrastructure shapes material cost structures, with polyethylene and polypropylene commanding volume dominance while specialty grades capture margin in regulated pharmaceutical applications.
- Polyethylene:Baseline polymer for cost-driven commodity applications, spanning low-density grades for sealant layers to linear low-density formulations for puncture resistance in frozen food contact. Ethylene feedstock volatility tied to naphtha and ethane import exposure squeezes converter margins on annual contracts with limited pass-through mechanisms.
- Polypropylene:Oriented and cast grades provide stiffness and thermal stability for retort and hot-fill applications, with biaxially oriented variants serving as print substrates for high-graphics stand-up pouches. Mexico's PROFEPA volatile organic compound limits are accelerating water-based adhesive migration for polypropylene lamination in northern border zones.
- Polyester:Polyethylene terephthalate films deliver thermal stability and print fidelity for pharmaceutical blister and sachet formats requiring ANVISA stability testing compliance. Premium positioning in healthcare applications offsets higher material costs against commodity polyethylene structures.
- Polyvinyl Chloride:Specialized shrink and blister applications persist in pharmaceutical and medical device packaging where clarity and thermoformability meet specific regulatory allowances, though circular economy pressures constrain growth in food contact segments.
Polyethylene retains volume leadership. Polyester gains fastest in regulated healthcare applications.
Application:
End-use demand fragments across distinct regulatory and logistics requirements, with food manufacturing anchoring volume while pharmaceutical packaging commands premium qualification timelines and clean-room certification investments.
- Food & Beverages:Dominant end-use spanning processed meat, dairy, snacks, and beverages distributed through tropical retail and export cold chains. Modified-atmosphere and vacuum skin technologies from southern Brazil to Chilean salmon operations extend shelf life where logistics infrastructure creates spoilage risk.
- Pharmaceuticals:ANVISA stability testing and extractables protocols restrict acceptable polymer grades and adhesive systems, creating captive demand for healthcare-grade clean-room film capabilities. Validation cycles of 18-24 months lock working capital before commercial volume release.
- Personal Care:Spouted stand-up pouches for shampoos, conditioners, and liquid soaps command premium positioning where dispensing convenience and shelf differentiation justify investment in multilayer barrier structures.
- Household Products:Detergents, cleaners, and disinfectants utilize flexible formats for refill and concentrate applications, with chemical resistance requirements favoring specific polyethylene and polypropylene coextrusion configurations.
Food & Beverages anchors procurement gravity. Pharmaceuticals commands steepest margin expansion trajectory.
Closure Type:
Closure innovation responds to fragmented cooperative procurement seeking shelf differentiation without multinational-scale volume commitments, with digital print and quick-changeover tooling enabling regional brand proliferation.
- Spout:Integrated dispensing fitments welded into pouch headers, enabling controlled pouring and resealability for beverages, sauces, and personal care liquids. Colombia's underpenetrated dairy sector is migrating yogurt and processed cheese formats from rigid containers to spouted stand-up pouches.
- Zipper:Interlocking plastic profiles providing resealability for snacks, frozen foods, and household products, with slider variants commanding premium positioning in club store multipacks.
- Flip Top:Hinged cap structures for single-hand dispensing in personal care and household applications, typically injection-molded polypropylene components ultrasonically welded to flexible pouch headers.
- Others:Tear notches, laser scoring, and fitment combinations for specific application requirements including child-resistant and senior-friendly accessibility standards.
Zipper closures dominate commodity volume. Spout configurations expand most quickly in premium dairy and beverage migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands procurement gravity through São Paulo's petrochemical corridor while Mexico's northern border industrial zone accelerates adhesive system conversions under tightening environmental enforcement.
Brazil
ANVISA pharmaceutical protocols generate captive demand for healthcare-grade clean-room film capabilities among domestic converters. CONAMA resolutions and emerging state-level extended producer responsibility statutes redirect capital toward mechanical recycling infrastructure. São Paulo's industrial corridor clusters multilayer lamination lines around processed meat and dairy manufacturing headquarters.
Mexico
PROFEPA and SEMARNAT volatile organic compound emission limits force costly adhesive system conversions in solvent-based lamination operations. Extended producer responsibility frameworks tighten material traceability requirements across packaging supply chains. The northern border industrial zone accelerates water-based and solventless adhesive migration to maintain cross-border manufacturing competitiveness.
Argentina
Petrochemical feedstock access through Buenos Aires province refineries shapes polyethylene and polypropylene cost structures for regional converters. The national pharmaceutical regulator enforces stability testing protocols that restrict acceptable polymer grades for medical device packaging. Córdoba's dairy processing belt drives spouted stand-up pouch adoption for yogurt and cheese formats.
Chile
Salmon exporters deploy vacuum skin and modified-atmosphere packaging technologies to extend shelf life through extended tropical supply chains. The national environmental regulator enforces progressively tighter limits on industrial emissions from converting operations. Santiago's metropolitan manufacturing zone concentrates high-barrier film demand from protein processing and premium beverage bottling operations.
Colombia
Processed cheese and yogurt manufacturers migrate from rigid containers to spouted stand-up pouches, creating first-mover advantage for aseptic filling integration. Emerging extended producer responsibility frameworks generate certified recycled polyethylene demand that outstrips domestic mechanical recycling capacity. Bogotá's dairy belt and Medellín's personal care manufacturing corridor anchor flexible packaging procurement growth.
Latin America Flexible Plastic Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's flexible plastic packaging landscape. The market structure concentrates around multinational integrated converters with captive film extrusion capabilities alongside regional mid-tier players serving fragmented cooperative procurement. Three archetypes dominate: integrated petrochemical-to-convert operators, healthcare-grade clean-room specialists, and digital-print-enabled short-run providers. Competitive moves center on monomaterial R&D partnerships with brand owners and backward integration into post-consumer recycled content verification systems.
Within the integrated multinational tier, Amcor PLC and Berry Global Inc. exemplify scale-driven positioning across Brazil and Argentina manufacturing footprints. Sealed Air Corporation occupies a differentiated position through vacuum skin and modified-atmosphere technology specialization for protein export applications. These three anchors represent contrasting strategic postures: full-value-chain integration versus healthcare certification depth versus application-specific technology leadership.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Inc. |
| Sonoco Products Company |
| ALPLA Group |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Mondi PLC |
| ProAmpac Holdings Inc. |
| Printpack Inc. |
| Others |
Pricing and Supply Chain Analysis
Solventless lamination migration across Mexico's northern border industrial zone is compressing cost economics for mid-tier converters while redistributing supply concentration toward integrated operators with captive adhesive capabilities. This technology transition simultaneously erodes price floors for commodity film contracts and deepens procurement gravity around São Paulo's petrochemical corridor where feedstock access anchors margin structures.
Pricing Analysis
Capacity additions in Brazil's São Paulo state are reshaping price floors for high-barrier rollstocks as new multilayer lamination lines enter commissioning phases. Contract-based long-term offtake dominates procurement relationships between multinational CPG brands and integrated converters, with price differentiation hinging on clean-room certification tier and volume scale commitments. Pricing pressure stems from ethylene feedstock volatility tied to naphtha import exposure, squeezing margins on annual contracts with limited pass-through mechanisms. Mid-sized cooperatives in Brazil's interior states exhibit highest price sensitivity, while ANVISA-compliant pharmaceutical packaging commands premium positioning with least elasticity.
Supply Chain Analysis
Regional distribution centers in São Paulo, Buenos Aires, and Mexico City anchor hub-and-spoke patterns for flexible film logistics across Latin American converting networks. Supply concentrates in Brazil, Mexico, and Argentina where petrochemical infrastructure feeds extrusion and lamination operations. Raw material dependencies center on polyethylene resin, polypropylene substrates, and specialty adhesive formulations. Single-source vulnerability persists for healthcare-grade clean-room films where ANVISA validation cycles lock buyers into qualified supplier relationships. Distribution runs through converter-direct models for multinational CPG accounts alongside regional distributor networks serving fragmented cooperative procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement gravity is shifting toward premium specifications. ANVISA pharmaceutical protocols and extended producer responsibility mandates are filtering out undifferentiated commodity suppliers.
For Market Incumbents: To counter margin compression from monomaterial reengineering requirements, deepen backward integration into post-consumer recycled content verification systems and accelerate clean-room certification investments ahead of regulatory deadline clustering. Prioritize capacity consolidation in São Paulo's industrial corridor to defend procurement relationships with multinational CPG headquarters. For New Entrants and Emerging Players: Begin with Colombia's underpenetrated dairy sector where spouted stand-up pouch migration from rigid containers creates first-mover opportunity for aseptic filling integration. Target water-based adhesive specialization for Mexico's northern border zone to capture solvent-based lamination conversion demand. Position through digital print-enabled short-run capabilities serving regional purchasing consortiums. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters lacking certified recycling partnerships or clean-room capabilities. Long-term viability over the next decade favors integrated operators with captive film extrusion and verified circular material platforms. Monitor ANVISA audit queue lengths as inflection indicator for healthcare-grade capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial R&D Partnership | Enables compliance with Brazil's CONAMA extended producer responsibility frameworks ahead of statutory deadlines. |
| Clean-room Certification Investment | Unlocks ANVISA pharmaceutical packaging volume with 18-24 month validation lock-in against competitors. |
| Post-consumer Recycled Content Verification | Secures preferred supplier status as supermarket sustainability scorecards tighten procurement specifications. |
| Water-based Adhesive Conversion | Maintains cross-border manufacturing competitiveness under Mexico's PROFEPA volatile organic compound limits. |
| Digital Print Capability Expansion | Captures fragmented cooperative procurement through short-run regional brand launches without volume minimums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at converting facilities, procurement leads at Brazilian and Mexican food processors, technical R&D directors at adhesive suppliers, and distribution channel partners across São Paulo and Mexico City. Secondary validation drew from customs and trade data, ANVISA regulatory filings, CONAMA resolution texts, and SEC disclosures from listed packaging conglomerates. Bottom-up volume estimates triangulated against top-down petrochemical feedstock consumption patterns.
Historical reference periods anchored the projection horizon through verified shipment data and capacity utilization rates across the analysis window. The analytical framework modeled segmentation dimensions including product format, material grade tier, end-use application, and closure type alongside regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating ethylene feedstock price trajectories and supermarket sustainability scorecard adoption rates.
Several conditions sit outside the modeled scope, including unforeseen polymer science breakthroughs, abrupt ANVISA protocol revisions, and trade policy disruptions affecting naphtha import economics. Forecasts reflect documented assumptions about regulatory timeline adherence and mechanical recycling infrastructure buildout rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market