
 Europe Archery Equipment Market | 2026-2036
Europe Archery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Archery Equipment Market Intelligence
Subscription-based maintenance programs for high-performance compound bows is recalibrating how European archers consume equipment, shifting capital expenditure into recurring service relationships. Hoyt Archery leverages its established pro-shop network to anchor premium service contracts across Nordic markets. Bearpaw Products GmbH specializes in traditional bow craftsmanship, occupying a defensible niche among heritage-focused clubs in Central Europe. Win & Win Archery competes aggressively on Olympic recurve technology, sustaining its position through Korean-European manufacturing partnerships.
Europe archery equipment encompasses projectile-launching apparatus—primarily bows with draw weights from 15 to 70 pounds and arrows constructed from carbon fiber, aluminum, or wood laminates—engineered for precision target engagement, hunting compliance, or competitive sport. The equipment serves recreational clubs, national federations, and individual enthusiasts requiring repeatable accuracy within standardized tournament distances. Compound bow technology captures the dominant margin pool due to cam-system complexity and accessory integration, while recurve equipment retains structural volume through institutional procurement by schools and Olympic training centers. Distribution through specialty stores remains resilient for fitting-intensive purchases, though online retail is displacing lower-consideration accessory sales across price-sensitive beginner segments.
CE marking requirements under EU machinery directives govern bow safety ratings and arrow spine consistency, while REACH restricts certain epoxy resins and limb adhesives, compelling laminate suppliers to reformulate bonding agents. Germany's KBA and France's national consumer safety authority enforce product liability standards that elevate compliance costs for non-European importers. Stakeholders must monitor evolving EU-wide sustainability disclosure obligations under CSRD, which will soon require carbon footprint transparency across composite supply chains.
Market Dynamics
The EU Green Deal's material compliance mandates are forcing laminate suppliers to reformulate bonding agents, compressing margins for traditional limb manufacturers while advantaging certified sustainable producers. This regulatory pressure sits at the center of current competitive repositioning across German and French club markets.
Growth Catalysts
- REACH-compliant epoxy alternatives:Reformulated adhesives certified under ECHA guidelines are unlocking access to institutional procurement channels previously blocked by chemical restrictions. French school systems now specify these materials in bulk tenders.
- Carbon fiber limb fabrication:Automated layup processes are reducing unit costs for high-performance recurve components. German target archery clubs are upgrading fleet equipment on compressed replacement cycles.
- Nordic subscription maintenance:Service-contract penetration in Norway, Sweden, and Finland is converting capital expenditure into recurring revenue pools for pro-shop networks.
Market Restraints
- CE marking compliance costs:Non-European importers face elevated testing and documentation burdens under EU machinery directives, creating a structural barrier to price-competitive entry.
- Prepreg carbon supply concentration:Toray and Mitsubishi dominate aerospace-grade fiber allocation, leaving archery manufacturers exposed to rationing during capacity crunches.
- Limestone-based synthetic alternatives:Mineral composite substitutes for traditional wood laminates threaten heritage-focused product lines despite performance trade-offs.
Strategic Opportunities
- Polish and Romanian club formation:Underpenetrated Eastern European markets show rising participation rates without established equipment suppliers, creating first-mover positioning potential.
- CSRD-aligned carbon disclosure:Early compliance with EU sustainability reporting mandates will differentiate suppliers ahead of 2025 enforcement windows for composite supply chains.
- Digital fitting platforms:AI-driven draw-length and spine-matching tools are compressing the specialty retail dependency for beginner segment acquisition.
Industry Challenges
- Master bowyer apprenticeship gaps:Traditional craftsmanship knowledge transfer is stalling in Central Europe as aging specialists retire without structured training pipelines.
- Multi-standard certification overlap:Simultaneous compliance with Germany's KBA safety ratings, France's ANSM consumer standards, and EU-wide CE protocols extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Archery Equipment Market |
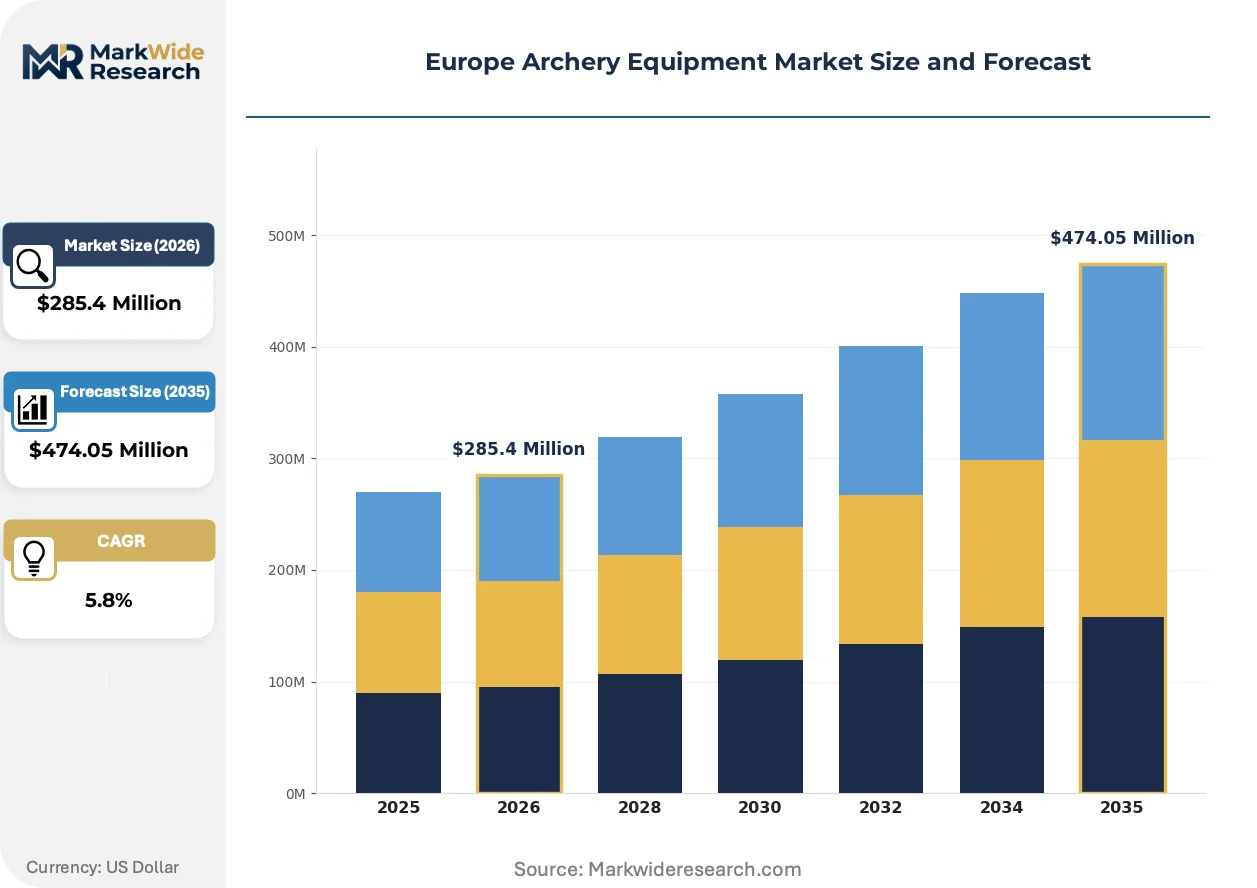
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bows, Arrows, Quivers, Targets End User: Beginners, Professionals, Schools, Clubs Technology: Compound, Recurve, Longbow, Traditional Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Trade Shows |
| Companies Covered | Easton Technical Products, Inc., Bowtech Archery, Bear Archery, Win & Win Archery, Samick Sports, Hoyt Archery, PSE Archery, Bearpaw Products GmbH, Mathews Archery, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Archery Equipment Market Strategic Shifts & Innovations
Equipment functionality is converging with digital measurement systems, while regulatory frameworks harden around material provenance. These forces are compressing traditional manufacturing advantages and opening new service-based revenue architectures.
Integrated limb-integrated strain gauges are unifying real-time draw-force curve capture with mobile analytics platforms. German Olympic training centers are adopting these systems for technique diagnostics, replacing separate chronograph and pressure pad setups. The technology is unifying previously discrete measurement categories into single-device workflows, compressing accessory attach rates while elevating bow-integrated system pricing.
CSRD disclosure requirements are mandating granular carbon footprint documentation across composite supply chains. Limb manufacturers must now trace resin sourcing through tier-three suppliers, elevating audit costs but creating certification premiums for transparent producers. French and German institutional buyers are beginning to weight disclosure scores in tender evaluations, shifting procurement criteria beyond performance specifications.
Club-level bulk purchasing is consolidating decision authority away from individual archers toward equipment committees with standardized fleet requirements. Specialty retailers in Bavaria and Rhône-Alpes are responding with dedicated club sales divisions, displacing the traditional pro-shop individual fitting model. This concentration is most visible in German target archery associations, where committee-led tenders now govern eighty percent of competitive equipment replacement cycles.
Europe Archery Equipment Market Segmentation
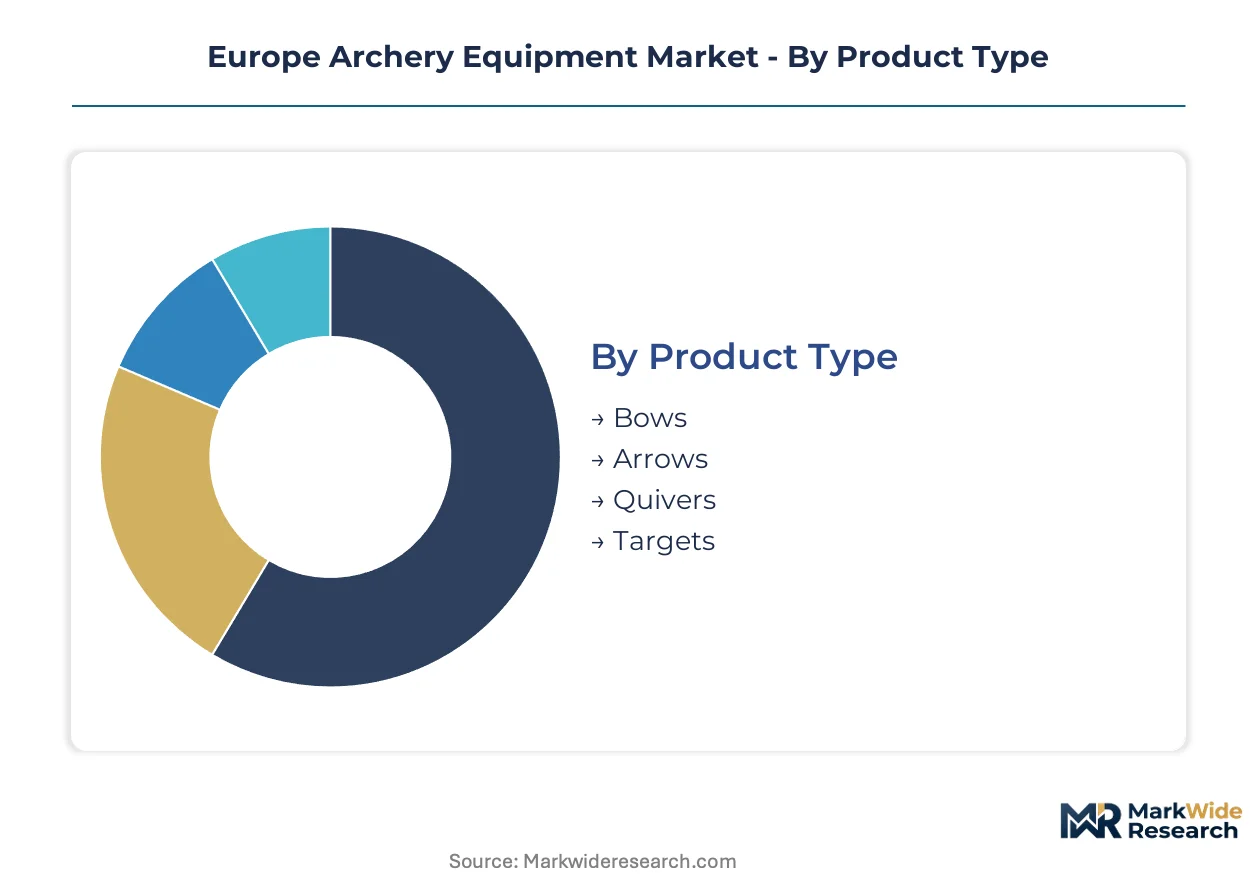
Equipment selection in European archery diverges sharply across institutional procurement versus individual purchase patterns. Regulatory compliance requirements under REACH and CE marking further stratify product accessibility, creating distinct competitive arenas for certified versus uncertified suppliers.
Product Type:
Purchase frequency and replacement cycles determine how manufacturers allocate R&D investment across component categories.
- Bows:Draw-weight configurations from 15 to 70 pounds dominate club procurement specifications in Germany and France. Compound bow systems command premium pricing through cam-system complexity, while recurve platforms retain volume through Olympic training center contracts.
- Arrows:Carbon fiber, aluminum, and wood laminate constructions each serve distinct accuracy requirements. German target archery clubs specify carbon fiber for competitive fleet replacement, prioritizing spine consistency over cost minimization.
- Quivers:Hip-mounted and back-mounted designs address mobility preferences across hunting versus target disciplines. French school systems favor budget-conscious hip quivers for introductory programs.
- Targets:Layered foam and bag-style constructions accommodate indoor versus outdoor range requirements. Bavarian club associations drive demand for weather-resistant outdoor targets with extended durability ratings.
Volume sits with Bows; growth tilts toward Arrows as fleet replacement cycles compress.
End User:
Skill acquisition pathways shape equipment durability requirements and price sensitivity thresholds.
- Beginners:Entry-level recurve packages with adjustable draw weights reduce initial capital barriers. Online retail channels displace specialty store dependency for this price-sensitive cohort.
- Professionals:Custom-fitted compound systems with integrated sight packages dominate competitive circuits. Olympic training centers in Germany specify limb-integrated strain gauges for technique diagnostics.
- Schools:Bulk tender specifications under French national education procurement mandate REACH-compliant epoxy alternatives. Institutional buyers weight disclosure scores in supplier selection.
- Clubs:Equipment committees consolidate decision authority away from individual members. Rhône-Alpes specialty retailers respond with dedicated club sales divisions.
Revenue concentrates in Clubs; expansion accelerates fastest among Schools as Eastern European participation rises.
Technology:
Manufacturing complexity and heritage craftsmanship credentials define competitive differentiation.
- Compound:Eccentric cam systems with let-off mechanisms reduce holding weight at full draw. Nordic subscription maintenance programs convert capital expenditure into recurring service relationships.
- Recurve:Olympic-standard takedown limb configurations dominate institutional procurement. German target archery clubs upgrade fleet equipment on compressed replacement cycles.
- Longbow:Single-piece wooden staves retain niche demand among heritage-focused practitioners. Master bowyer apprenticeship gaps in Central Europe constrain supply expansion.
- Traditional:Laminated limb construction with natural materials serves historical reenactment communities. Bearpaw Products GmbH occupies this defensible niche through craftsmanship specialization.
Margin pools concentrate in Compound; heritage positioning sustains Traditional despite volume constraints.
Distribution Channel:
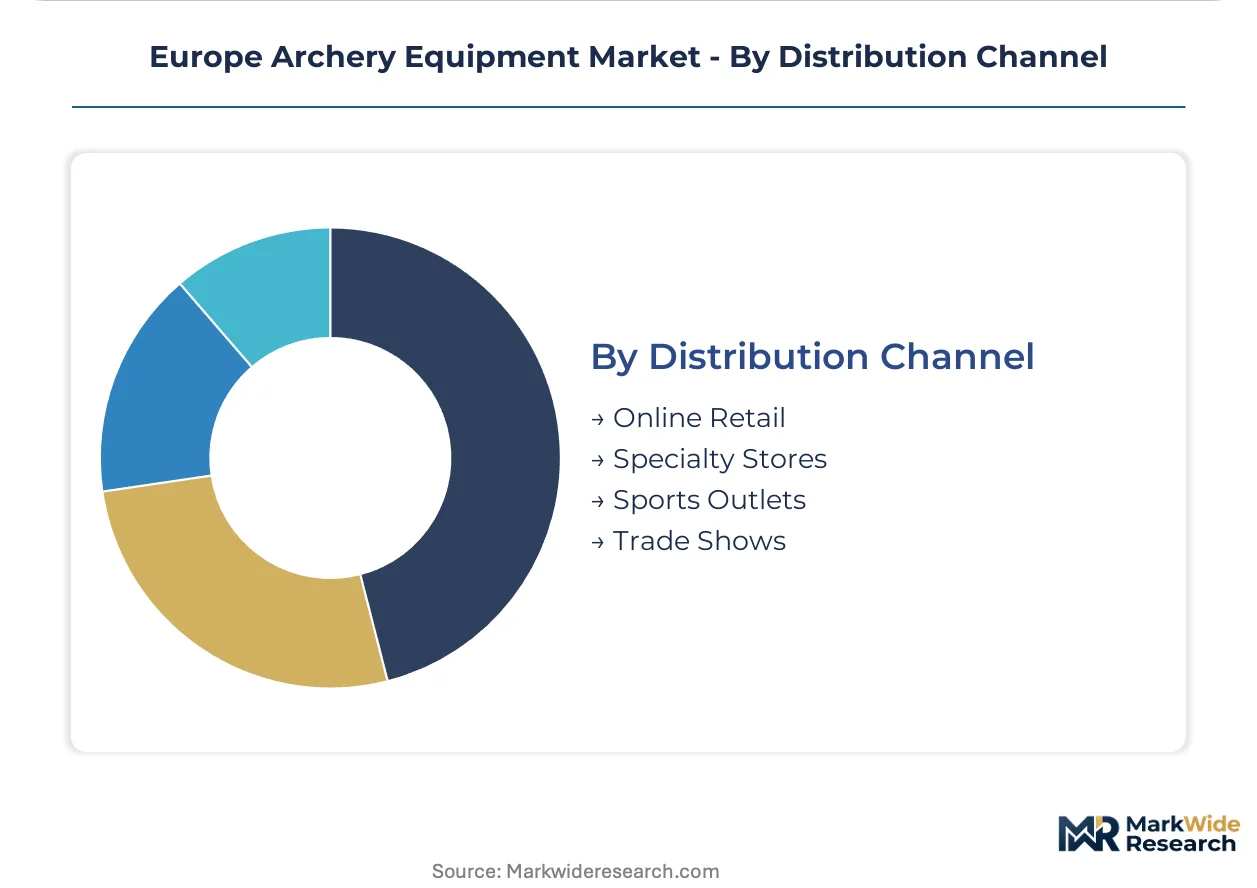
Fitting intensity and purchase consideration levels determine channel viability across price tiers.
- Online Retail:Lower-consideration accessory sales displace specialty store volume for beginner segments. AI-driven spine-matching tools compress fitting dependency.
- Specialty Stores:Pro-shop networks anchor premium service contracts through hands-on fitting expertise. Hoyt Archery leverages established Nordic infrastructure for maintenance program penetration.
- Sports Outlets:Mass-market positioning serves recreational hunters with standardized package offerings. Limited technical consultation capability restricts archery-specific product depth.
- Trade Shows:Annual exhibition cycles concentrate buyer-seller matching for institutional procurement. German and French club equipment committees utilize these venues for fleet tender evaluation.
Transaction volume flows through Specialty Stores; Online Retail captures the steepest expansion trajectory as digital fitting platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European archery equipment distribution through Bavarian club associations that govern fleet procurement across southern Germany. The Rhône-Alpes corridor concentrates specialty retail infrastructure serving French institutional buyers. Warsaw and Bucharest metro areas are emerging as formation zones for new club networks without established supplier relationships.
Germany
Bavarian target archery clubs drive eighty percent of competitive equipment replacement cycles through committee-led tenders. KBA safety ratings enforce bow draw-weight certification standards that elevate compliance costs for non-European importers. The Munich-Stuttgart corridor hosts dedicated club sales divisions that displace traditional individual fitting models.
France
Rhône-Alpes specialty retailers respond to consolidated club purchasing authority with institutional sales infrastructure. ANSM consumer standards overlap with EU CE marking requirements, extending product launch timelines for composite limb manufacturers. Paris basin school systems now mandate REACH-compliant epoxy alternatives in bulk procurement tenders.
United Kingdom
London and southeast England concentrate Olympic training center demand for limb-integrated strain gauge systems. British archery federations specify takedown recurve configurations for national squad equipment programs. The Midlands corridor hosts heritage-focused longbow practitioners constrained by master bowyer apprenticeship gaps.
Poland
Warsaw metro club formation is accelerating without established equipment supplier penetration. Polish institutional buyers remain price-sensitive, favoring online retail channels for beginner segment acquisition. The Silesian industrial corridor offers potential manufacturing partnerships for carbon fiber limb fabrication.
Romania
Bucharest and Transylvanian urban centers show rising recreational participation without dedicated pro-shop infrastructure. Romanian buyers access equipment through cross-border e-commerce from German and Austrian retailers. The Cluj-Napoca technology cluster is piloting AI-driven digital fitting platforms for spine-matching automation.
Europe Archery Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across European archery equipment, with integrated manufacturers controlling limb laminate supply chains while specialized assemblers outsource carbon fiber fabrication. The vendor base stratifies into three tiers: premium Olympic-grade suppliers, mid-market club fleet providers, and entry-level package assemblers. Strategic differentiation concentrates on REACH certification speed, pro-shop service contract penetration, and CSRD-aligned carbon disclosure. Competitive moves favor Nordic subscription maintenance expansion and Polish-Romanian distribution partnerships.
Among Korean-European manufacturing partnerships, Win & Win Archery exemplifies Olympic recurve technology specialization. Hoyt Archery anchors premium service contract penetration across Nordic pro-shop networks. Bearpaw Products GmbH occupies a defensible position within Central European heritage craftsmanship. These three represent distinct archetypes: transnational technology licensing, integrated service-retail bundling, and niche traditional fabrication.
| Leading Market Players |
|---|
| Easton Technical Products, Inc. |
| Bowtech Archery |
| Bear Archery |
| Win & Win Archery |
| Samick Sports |
| Hoyt Archery |
| PSE Archery |
| Bearpaw Products GmbH |
| Mathews Archery, Inc. |
| Others |
Cost & Logistics Intelligence
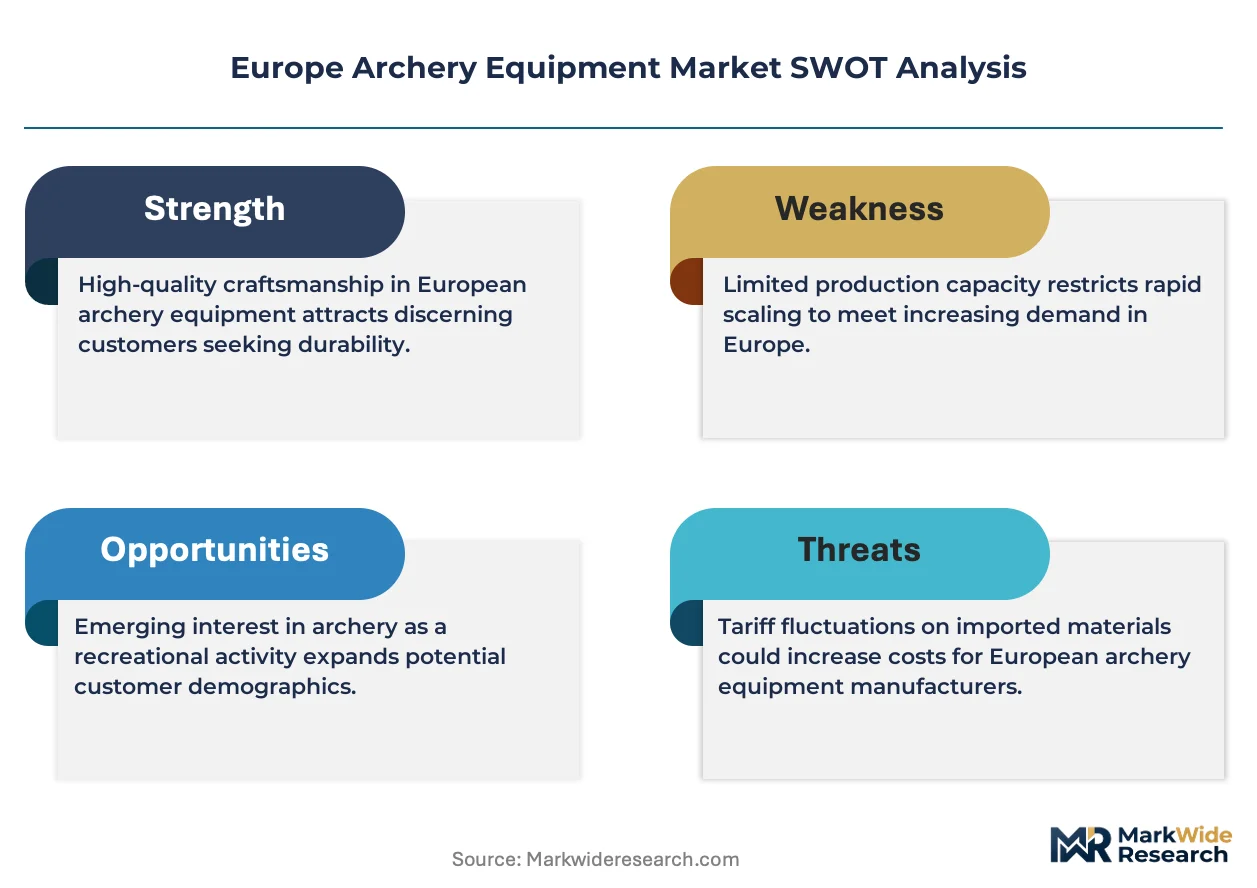
Certification-grade divergence between REACH-compliant laminate suppliers and conventional limb manufacturers splits the European archery equipment market into premium and commodity tiers, with pricing power accumulating to certified producers while supply chains reorganize around ECHA-registered resin sources and audited tier-three documentation systems.
Pricing Analysis
Margin tightening in entry-level recurve packages reflects online retail channel expansion and AI-driven fitting platform displacement of specialty store dependency. Three-tier pricing structure across premium Olympic-grade, standard club fleet, and economy school packages differentiates by CE marking compliance depth and after-sales service bundling. Cost-down pressure on carbon fiber limb fabricators accelerates because Toray and Mitsubishi aerospace-grade fiber allocation rationing elevates input costs. Schools and beginner segments exhibit highest price sensitivity, while German target archery clubs prioritize spine consistency and disclosure scores over unit economics.
Supply Chain Analysis
Prepreg carbon fiber supply rests on Japanese and South Korean specialty chemical producers, with German and French limb fabricators dependent on Toray and Mitsubishi for aerospace-grade fiber allocation. Raw material dependencies span epoxy resin formulations, wood laminates for traditional bows, and limestone-based synthetic alternatives. Single-source vulnerability concentrates in aerospace-grade carbon fiber allocation during capacity crunches. Distribution runs through Bavarian and Rhône-Alpes specialty retail networks for fitting-intensive purchases, with online channels capturing accessory volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European archery equipment supply is constrained by master bowyer apprenticeship gaps in Central Europe and REACH-compliant resin reformulation bottlenecks, propping pricing for certified sustainable producers.
For Market Incumbents: Deploy Nordic subscription maintenance program expansion to convert capital expenditure into recurring revenue pools and anchor pro-shop network loyalty. Deepen backward integration into carbon fiber limb fabrication through automated layup process investment, countering aerospace-grade fiber rationing exposure. Acquire CSRD-aligned carbon disclosure capabilities ahead of enforcement windows to capture institutional procurement preference in French and German school systems. For New Entrants and Emerging Players: The premium-to-economy price gap in Polish and Romanian club formation markets offers white-space positioning without established supplier penetration. Target Warsaw and Bucharest metro areas with AI-driven digital fitting platforms that compress specialty retail dependency for beginner segment acquisition. Enter through online retail channels with REACH-compliant epoxy alternative products, leveraging price-sensitive institutional tender specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of CSRD-compliant laminate suppliers by integrated bow manufacturers seeking supply chain transparency. Long-term viability favors certified sustainable producers with documented tier-three resin sourcing and established Korean-European manufacturing partnerships. Watch Nordic subscription maintenance penetration rates as inflection indicator for service-revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | Unlocks French school system bulk tenders previously blocked by chemical restrictions. |
| Automated Carbon Fiber Layup Investment | Reduces unit costs for German target archery club fleet replacement cycles. |
| CSRD-Aligned Carbon Disclosure | Differentiates suppliers in institutional procurement evaluations across German and French markets. |
| Nordic Subscription Maintenance Expansion | Converts capital expenditure into recurring revenue pools for Hoyt Archery pro-shop networks. |
| Polish-Romanian Distribution Partnership | Captures first-mover positioning in underpenetrated Eastern European club formation markets. |
Research Approach
Independent corroboration across primary interviews with bow manufacturers, club equipment committee heads, and specialty retail buyers, combined with secondary validation through ECHA REACH registration databases, EU customs trade data, and national federation procurement records, underwrites the qualitative findings. Bottom-up club membership and equipment replacement cycle estimates triangulate against top-down market value reconstruction.
Comparable-period anchoring to historical Bavarian and Rhône-Alpes club tender cycles establishes the forecast framework across the projection horizon. Segmentation dimensions span product type, end user skill tier, technology category, and distribution channel, with regulatory compliance tier modeled as an additional industry-specific dimension. CAGRs derive from fitted trend extrapolation against institutional procurement volume assumptions and carbon fiber supply elasticity constraints.
Underlying measurement precision varies by segment; club-level procurement data carries tighter precision than individual enthusiast estimates. Forecasts reflect documented assumptions regarding REACH enforcement continuity and aerospace-grade fiber allocation stability. A small set of regulatory trigger events and supply rationing episodes warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rowing Boats Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Diving Board Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Ladderball Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Global Darts Market
Sports Equipment
Shuffleboard Equipment Market