

Bicycle Drivetrain Cassette Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Drivetrain Cassette Market Insights
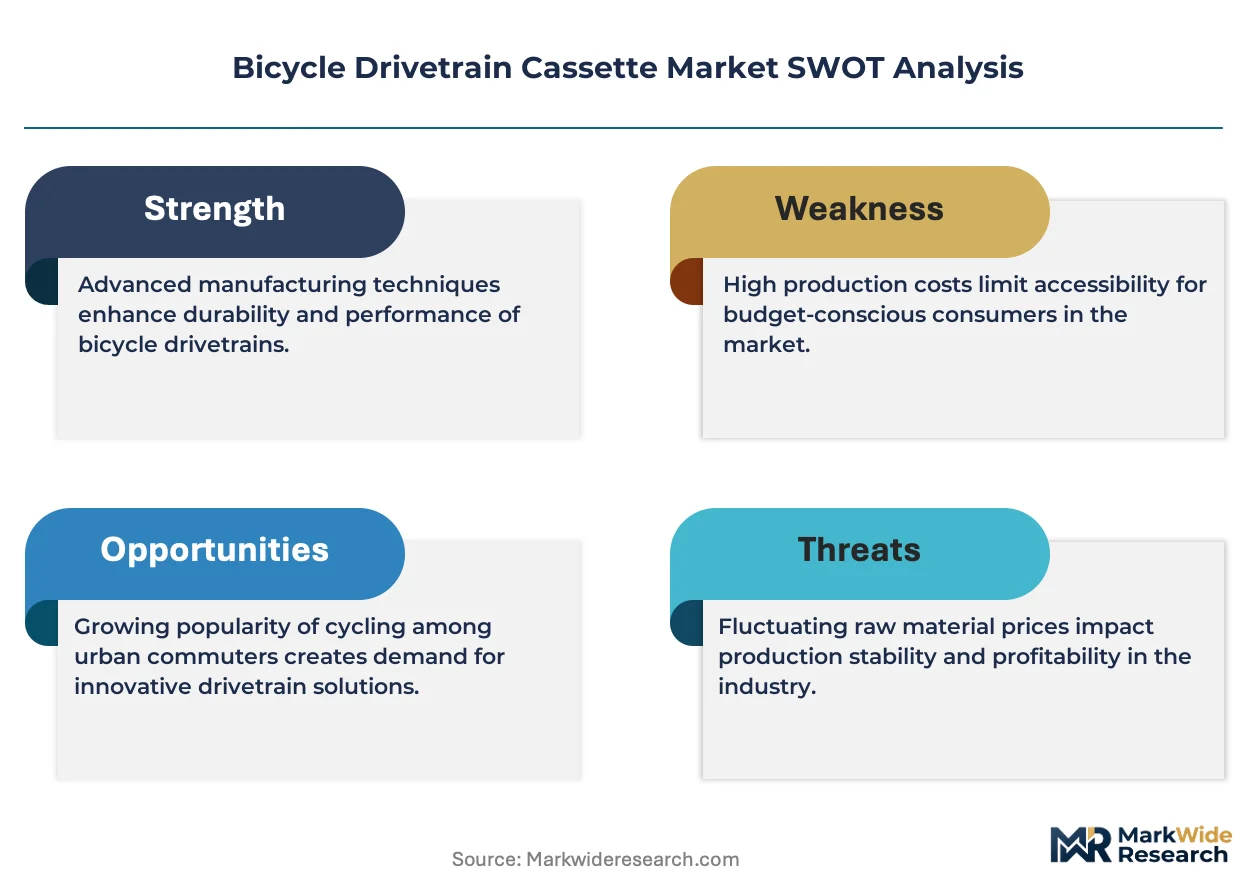
Wide-range 12-speed specification tiers is rotating demand toward higher-margin products with tighter tolerances. SRAM leverages in-house manufacturing to control alloy sourcing for its Eagle platform. Shimano anchors road cycling distribution through proprietary Hyperglide+ interface dominance. Campagnolo differentiates via Italian machining heritage and limited production runs for premium builds.
A bicycle drivetrain cassette is a cluster of sprockets mounted on the rear hub freehub body, typically engineered from heat-treated steel or titanium with precision-cut shift ramps and gates to manage chain engagement across gear ratios. Multi-speed cassettes command the largest volume position as mountain biking and gravel applications expand gear range requirements. Carbon fiber and titanium technology segments attract margin-focused suppliers serving professional cyclist end users where gram reduction justifies premium positioning. Standard cassettes and freewheel categories retain residual demand from commuting and rental fleet channels where cost sensitivity overrides performance specifications.
ISO 4210 frame and component safety standards govern fatigue testing protocols that cassette manufacturers must satisfy for OEM supply contracts to European bicycle assemblers. The US Consumer Product Safety Commission enforces recall mechanisms that elevate liability exposure for aftermarket suppliers lacking traceable metallurgical documentation. Japan's Ministry of Economy, Trade and Industry (METI) coordinates industrial standards through JIS certification that shapes export eligibility for Asian component producers. Stakeholders must monitor evolving e-bike torque ratings that strain traditional cassette spline interfaces beyond legacy design thresholds.
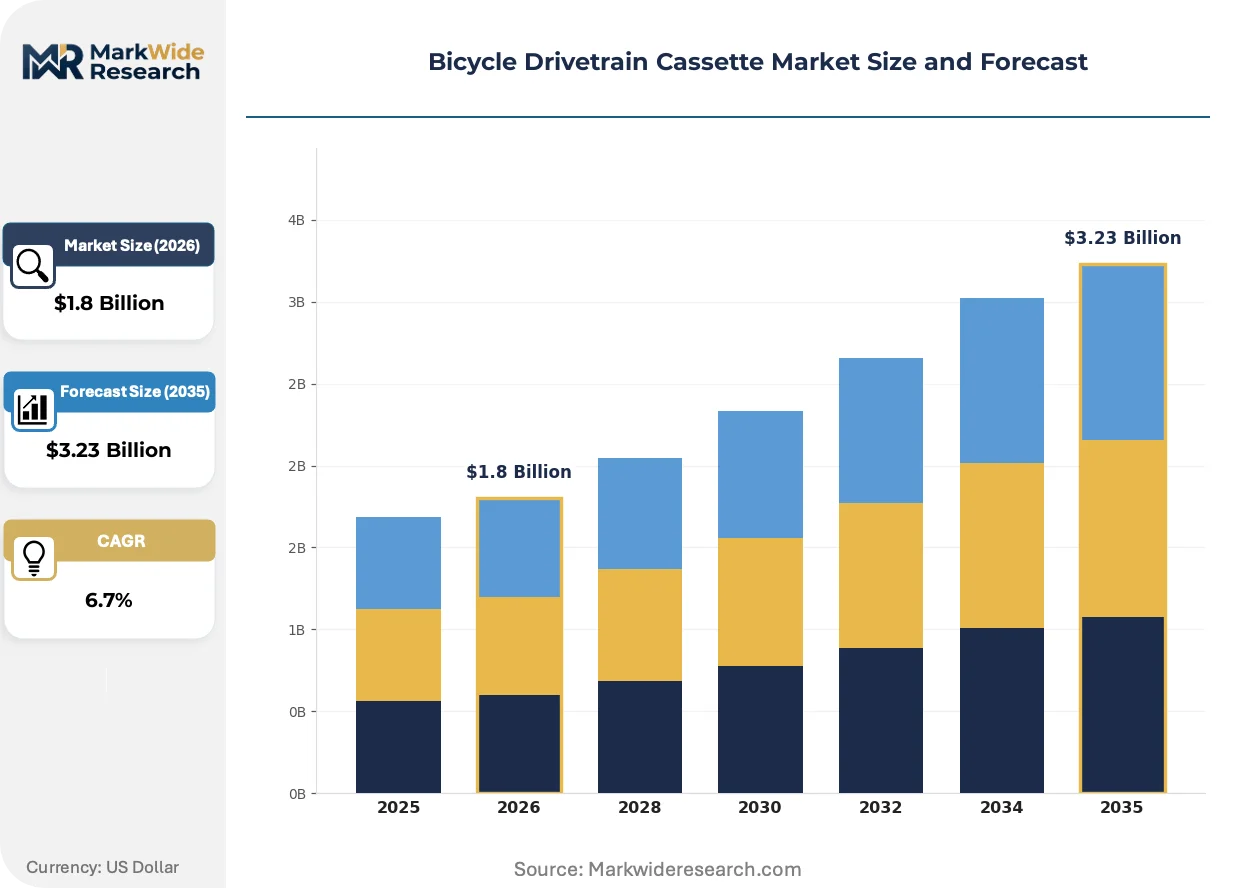
Market Dynamics
The shift toward 12-speed drivetrain architectures is fragmenting supplier hierarchies as precision machining requirements exceed legacy tooling capabilities. Component manufacturers must now balance heat-treatment expertise against alloy sourcing constraints while serving divergent road, gravel, and mountain bike specifications.
Growth Catalysts
- EN 15194 E-bike torque classifications:German regulators expanded power-assist thresholds, forcing cassette spline redesigns that open replacement cycles for multi-speed systems across urban mobility fleets.
- Titanium machining advances:Swiss and Italian suppliers refined CNC protocols for hollow dome cassettes, cutting weight penalties that previously limited adoption outside professional racing.
- Gravel racing discipline expansion:North American and European event calendars multiplied, creating sustained demand for wide-range gearing that bridges road and mountain bike categories.
Market Restraints
- Heat-treated steel billet concentration:Japanese and Taiwanese specialty mills control premium alloy supply, exposing OEMs to lead time volatility when sourcing certified material for Eagle and XTR-tier products.
- ISO 4210 fatigue testing protocols:European frame safety standards mandate destructive load cycles that extend certification timelines, compressing margins for aftermarket suppliers lacking in-house metallurgical labs.
- Single-speed belt drive substitution:Gates Carbon Drive systems capture urban commuter segments where maintenance simplicity outweighs gear range flexibility, particularly in Dutch and Danish municipal procurement.
Strategic Opportunities
- Indian domestic cycling infrastructure:Smart Cities Mission investments in Bengaluru and Pune create replacement demand as road bike adoption accelerates among urban professionals.
- CSRD supply chain disclosure mandates:European corporate sustainability reporting rules reward traceable alloy sourcing, favoring suppliers with documented conflict-mineral-free titanium supply.
- Direct-to-consumer assembly channel:Online bike retailers require pre-configured cassette-wheel bundles, opening margin capture for suppliers who integrate hub and drivetrain logistics.
Industry Challenges
- Heat-treatment metallurgist scarcity:Precision steel hardening expertise concentrates in aging workforces across Solingen and Sakai, constraining capacity expansion for new market entrants.
- Hyperglide+ interface licensing complexity:Proprietary shift-gate geometries require patent navigation for third-party cassette manufacturers seeking Shimano hub compatibility.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Drivetrain Cassette Market Trends and Innovations
Material science advances and regulatory pressure on component durability are converging to redefine manufacturing priorities. Suppliers now compete on traceable metallurgy and modular platform architectures rather than pure gear-count escalation.
Carbon-reinforced polymer cassette spiders are fragmenting traditional aluminum forging economics. Enduro and downhill racing teams adopted hybrid composite-steel constructions to damp drivetrain noise under torque spikes. The technology is fragmenting tier boundaries as mid-market brands license previously exclusive layup techniques from aerospace suppliers.
REACH substance restrictions on hexavalent chromium plating forced European manufacturers to migrate toward tungsten-carbide physical vapor deposition. The industrial consequence is elevated capital intensity for coating equipment, compressing supplier margins during the transition window. Road cycling OEMs in Italy and Spain face the steepest compliance curves as legacy supply contracts expire.
Buyer concentration among direct-to-consumer assemblers is compressing traditional distributor margins. Canyon, YT Industries, and comparable brands now specify cassette-wheel-shifter bundles in single procurement events, bypassing component wholesalers. This pattern is most visible in German and Austrian markets where online bike sales penetration exceeds brick-and-mortar channels.
Bicycle Drivetrain Cassette Market Segmentation
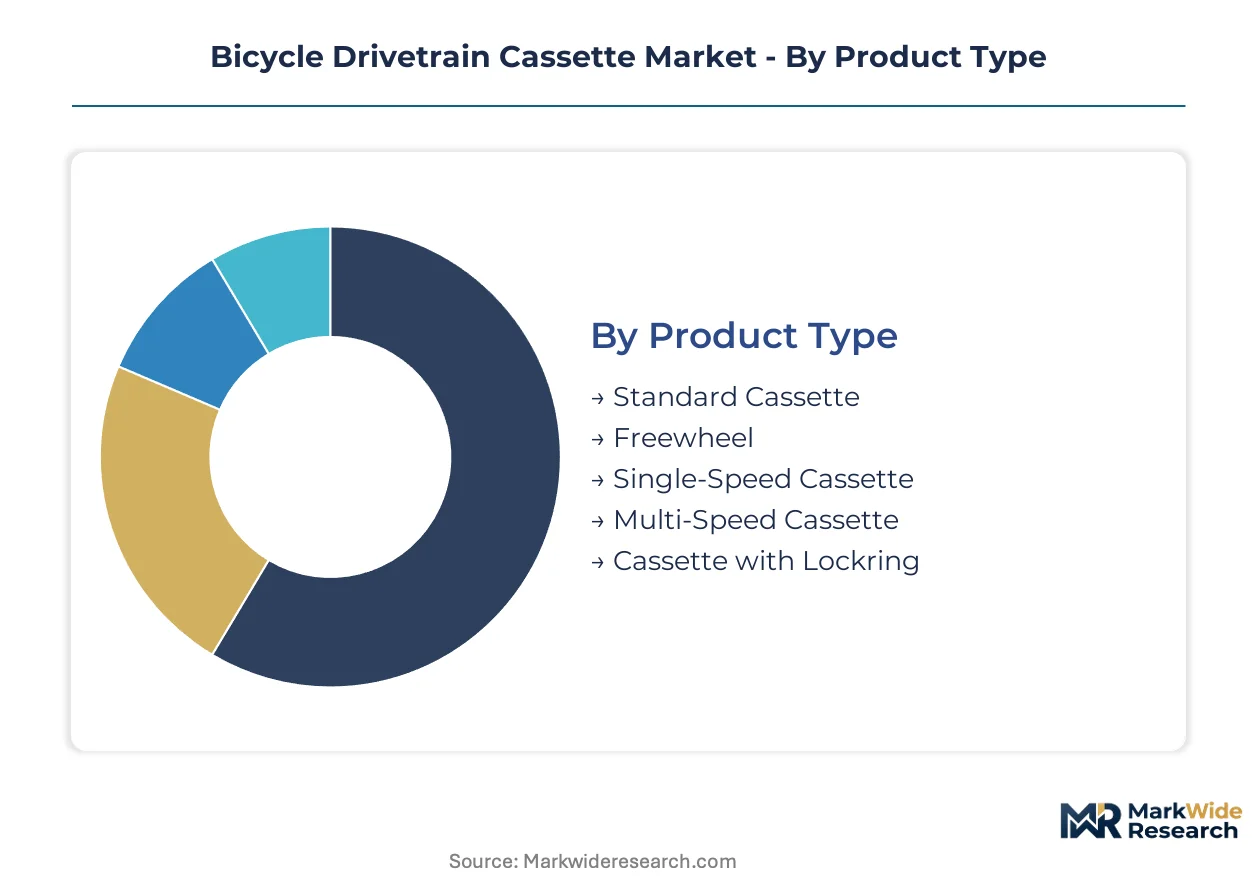
Cassette segmentation maps directly to procurement channel economics. OEM contracts for bicycle manufacturers demand certified fatigue testing and batch traceability, while aftermarket channels serve replacement cycles with shorter lead times and lower documentation burdens.
Product Type:
Channel mix varies sharply by product architecture. Multi-speed cassettes flow predominantly through OEM assembly contracts and direct-to-consumer bundle configurations, while single-speed and freewheel categories concentrate in municipal fleet procurement and entry-level retail.
- Multi-Speed Cassette:Clusters of 8 to 12 sprockets with precision-machined shift ramps and hyperglide interfaces. Demand concentrates in Germany and Austria where gravel racing adoption and e-bike torque requirements drive replacement cycles for wide-range systems.
- Standard Cassette:Modular sprocket stacks mounted via splined freehub bodies with lockring retention. Volume leadership sits with road cycling OEM supply chains in Italy and Spain, though growth pace lags as 12-speed architectures displace legacy 10-speed configurations.
- Freewheel:Integrated sprocket-and-clutch units threading directly onto hub shells. Residual demand persists in Indian and Southeast Asian commuter markets where cost sensitivity overrides serviceability preferences.
- Single-Speed Cassette:Reduced sprocket counts for fixed-gear and track applications. Urban cycling clusters in Copenhagen and Amsterdam sustain niche procurement through specialty distributors.
- Cassette with Lockring:Enhanced retention systems for high-torque e-bike applications. Expanding most quickly in German urban mobility fleets where EN 15194 torque classifications mandate reinforced spline interfaces.
By volume, Standard Cassette leads. By growth pace, Cassette with Lockring is ahead.
Technology:
Cost tier stratification separates aerospace-grade titanium and carbon fiber production from commodity steel stamping. Premium material segments command three-to-five-fold pricing multiples justified by gram reduction in professional racing applications.
- Steel:Heat-treated chromoly and tool-grade alloys dominate mass-market production. Japanese and Taiwanese specialty mills control billet supply, exposing OEMs to lead time volatility for XTR-tier and Eagle-tier certification requirements.
- Titanium:Hollow-dome CNC machining from aerospace-grade bar stock. Swiss and Italian suppliers refined protocols that cut weight penalties, expanding adoption beyond professional racing into premium consumer segments.
- Carbon Fiber:Reinforced polymer spiders hybridized with steel sprocket rings. Enduro and downhill teams in North America adopted composite-steel constructions to damp drivetrain noise under torque spikes.
- Aluminum:Forged spiders with hard-anodized surface treatments. Mid-market positioning erodes as carbon-reinforced polymers fragment traditional forging economics.
- Composite Materials:Multi-material laminates combining polymer matrices with metallic reinforcement. Gaining share fastest as layup techniques licensed from aerospace suppliers migrate down-tier.
Steel commands absolute volume. Titanium climbs the fastest on margin expansion.
Application:
Customer type fragmentation splits procurement between performance-oriented racing disciplines and utility-focused mobility segments. Racing applications demand iterative upgrade cycles, while commuting and touring prioritize durability over specification advancement.
- Mountain Biking:Wide-range 12-speed systems with reinforced splines for torque spikes. North American trail networks and European bike park infrastructure sustain replacement demand as enduro racing calendars expand.
- Road Cycling:Tighter-ratio cassettes optimized for cadence maintenance on paved gradients. Italian and Spanish OEM assembly contracts anchor volume, though gravel racing is displacing pure road specifications.
- Gravel Racing:Hybrid gearing bridging road and mountain bike categories. Event multiplication across Germany, Belgium, and the United States creates sustained demand for 11-42 and 10-50 range configurations.
- Commuting:Cost-optimized steel cassettes with extended service intervals. Gates Carbon Drive belt systems capture share in Dutch and Danish municipal procurement where maintenance simplicity outweighs gear flexibility.
- Touring:Durability-focused specifications with corrosion-resistant coatings. Long-haul route networks in France and Switzerland sustain niche demand for stainless steel and titanium constructions.
Mountain Biking holds volume leadership. Gravel Racing posts the steepest expansion trajectory.
End User:
Margin concentration follows end-user sophistication. Professional cyclists and specialty shops pay premiums for documented metallurgy and gram reduction, while rental fleets and recreational riders prioritize unit cost and service interval length.
- Professional Cyclists:UCI-registered teams and elite amateur competitors. Sponsorship contracts with SRAM, Shimano, and Campagnolo lock in specification roadmaps that cascade to consumer tiers.
- Bicycle Manufacturers:OEM assembly contracts requiring ISO 4210 fatigue certification and REACH-compliant coating documentation. German and Austrian direct-to-consumer assemblers now specify cassette-wheel-shifter bundles in single procurement events.
- Specialty Shops:High-service retail channels with workshop capabilities. Custom build specifications drive mix toward titanium and carbon fiber where margin capture justifies inventory carrying costs.
- Recreational Riders:Enthusiast consumers upgrading wear components. Online retailer penetration concentrates demand in pre-configured bundles, compressing traditional distributor margins.
- Rental Fleets:Municipal and commercial operators prioritizing service interval length over performance specifications. Residual demand for freewheel and standard steel cassettes persists where cost sensitivity overrides durability requirements.
Bicycle Manufacturers dominate volume. Professional Cyclists lead value capture per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese precision mills export heat-treated steel billets to German and Austrian bicycle assemblers, anchoring the primary trade corridor for high-performance cassette manufacturing. This flow concentrates procurement leverage among specialty metallurgy suppliers serving OEM certification requirements.
Germany
Urban cycling infrastructure investments in Berlin and Munich accelerate replacement cycles for multi-speed systems. EN 15194 torque classifications mandate reinforced spline interfaces for e-bike fleets. The Stuttgart industrial corridor hosts machining specialists refining CNC protocols for hollow-dome titanium production.
United States
Gravel racing expansion across Colorado and California creates sustained demand for wide-range gearing configurations. The Consumer Product Safety Commission enforces recall mechanisms that elevate liability exposure for aftermarket suppliers lacking traceable documentation. Portland and Boulder clusters concentrate specialty shops driving premium component mix.
Japan
Heat-treatment expertise concentrates in aging workforces across Sakai, constraining capacity expansion for new market entrants. METI coordinates JIS certification standards that shape export eligibility for Asian component producers. The Osaka-Kobe manufacturing belt anchors precision steel hardening capabilities for XTR-tier products.
Italy
Road cycling OEM assembly contracts in Veneto and Emilia-Romagna anchor volume for tighter-ratio cassette specifications. REACH substance restrictions on hexavalent chromium plating force manufacturers toward tungsten-carbide physical vapor deposition. The Vicenza machining corridor preserves limited production runs for premium builds leveraging heritage positioning.
India
Smart Cities Mission investments in Bengaluru and Pune generate replacement demand as road bike adoption accelerates among urban professionals. BIS standards govern component safety testing for domestic assembly contracts. The Tamil Nadu industrial belt concentrates cost-optimized steel production serving commuter market residual demand.
Bicycle Drivetrain Cassette Market Competitive Landscape
Listed leaders compete with private specialists across precision machining capabilities and metallurgical certification depth. The supplier hierarchy fragments as 12-speed drivetrain architectures exceed legacy tooling capabilities for new entrants. Three archetypes dominate: integrated drivetrain platform owners controlling proprietary interfaces, specialty metallurgy houses with captive heat-treatment expertise, and contract manufacturers serving direct-to-consumer assemblers with bundle logistics. Competitive moves concentrate on backward integration into alloy sourcing and strategic partnerships with online bike retailers for pre-configured wheel-cassette-shifter procurement.
Among Japanese precision component specialists, Shimano anchors proprietary interface dominance through established hub compatibility standards. SRAM represents the vertically integrated platform owner archetype with in-house manufacturing controlling alloy sourcing for wide-range systems. Campagnolo occupies the heritage-positioned tier, with Italian machining traditions supporting limited production economics for premium market segments.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Campagnolo |
| Box Components |
| e.thirteen |
| SunRace |
| MicroSHIFT |
| SR Suntour |
| Full Speed Ahead |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German bicycle assemblers and Taiwanese specialty mills lock in heat-treated steel billet access while anchoring price visibility for XTR-tier and Eagle-tier certification requirements. These arrangements insulate OEM procurement teams from spot market volatility in aerospace-grade titanium bar stock.
Pricing Analysis
The 12-speed-to-11-speed pricing gap exceeds three-to-five-fold multiples for titanium hollow-dome configurations against standard chromoly steel stacks. Three-tier pricing structure across premium, standard, and economy levels stratifies by metallurgical certification grade and documented batch traceability. Cost compression in mid-market steel tiers is intensifying because carbon-reinforced polymer spiders fragment traditional aluminum forging economics. Rental fleet operators exhibit highest price sensitivity, while professional cycling teams prioritize gram reduction over unit cost.
Supply Chain Analysis
Inventory lead times for certified heat-treated steel billets extend disproportionately against raw material availability due to constrained metallurgist capacity in Solingen and Sakai. Supply concentrates in Japan, Taiwan, and Germany for precision-machined sprocket production. Raw material dependencies center on aerospace-grade titanium bar stock, chromoly steel billets, and carbon fiber prepreg. Single-source vulnerability in Japanese specialty mill supply exposes OEMs to disruption. Distribution runs through direct-to-consumer assemblers in German and Austrian markets, bypassing traditional component wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where proprietary interface dominance by SRAM and Shimano is reshaping competitive positioning around ecosystem lock-in rather than component commoditization.
For Market Incumbents: Fortify backward integration into alloy sourcing to secure heat-treated steel billet supply against Japanese and Taiwanese mill concentration. Deepen captive heat-treatment capabilities in Solingen and Sakai corridors to defend margin position against emerging CNC specialists. Patent navigation around Hyperglide+ interface geometries remains essential for maintaining hub compatibility dominance. For New Entrants and Emerging Players: Lead with gravel racing specification gaps where wide-range 11-42 and 10-50 configurations bridge road and mountain bike categories with lower certification barriers. Indian Smart Cities Mission infrastructure investments in Bengaluru and Pune offer the most penetrable geography for cost-optimized steel cassette penetration. Direct-to-consumer bundle partnerships with online bike retailers provide the clearest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward specialty metallurgy houses with captive heat-treatment expertise and documented conflict-mineral-free titanium supply chains aligned with CSRD disclosure mandates. Long-term viability favors suppliers who control both CNC machining protocols and certified alloy sourcing. Watch for e-bike torque rating revisions under EN 15194 as the inflection signal requiring spline interface redesigns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Secures heat-treated steel billet supply against Japanese and Taiwanese mill concentration. |
| CSRD-Compliant Supply Chain Certification | Enables premium positioning through documented conflict-mineral-free titanium traceability. |
| Direct-to-Consumer Bundle Partnerships | Captures margin from Canyon and YT Industries specifying cassette-wheel-shifter procurement. |
| Gravel Racing Specification Development | Addresses 11-42 and 10-50 range demand from expanding event calendars in Germany and Belgium. |
| E-Bike Spline Interface Redesign | Meets EN 15194 torque classifications for German urban mobility fleet replacement cycles. |
Research Methodology
A spread of perspectives from drivetrain platform engineers, OEM procurement managers, specialty shop mechanics, and heat-treatment metallurgists converged on the working assumptions. Primary interviews with component certification specialists and secondary validation through ISO 4210 testing documentation, EN 15194 regulatory filings, JIS standards publications, and SEC filings from listed precision manufacturers anchored the data foundation. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, and application segments.
Segmentation dimensions modeled include product architecture, material technology tier, cycling discipline application, and end-user sophistication level across the projection horizon. CAGRs were derived from regression analysis against replacement cycle frequencies and e-bike fleet penetration curves. Forecast inputs incorporated gravel racing event calendar expansion and REACH substance restriction compliance timelines.
Forecasts assume regulatory continuity in European EN 15194 and REACH regimes, Japanese JIS certification standards, and Indian BIS safety testing protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.