
 Global Cycling Power Meters Market | 2026-2036
Global Cycling Power Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cycling Power Meters Market Analysis
Amateur riders is reorganizing demand patterns across the cycling power meters landscape as fitness enthusiasts seek laboratory-grade training data previously reserved for professionals. Garmin Ltd. leverages its ecosystem integration across GPS head units and wearable platforms to sustain repeat purchases within its installed base. SRAM anchors its position through proprietary crank-integrated designs that tighten compatibility with its drivetrain families. Wahoo Fitness competes aggressively on wireless connectivity standards and software subscription attach rates.
Cycling power meters are electromechanical devices that quantify mechanical power output in watts through strain deformation measurement, typically achieving accuracy within one to two percent across temperature ranges from negative ten to fifty degrees Celsius. These instruments serve competitive and recreational cyclists by quantifying training load, tracking performance progression, and enabling pacing optimization during events. Crank-based systems occupy the largest installed base due to proven durability and broad frame compatibility across road and mountain disciplines. Pedal-based configurations represent the fastest-growing architecture as riders prioritize transferability between bicycles and simplified installation protocols. Strain gauge technology dominates commercial production while optical sensing methods attract development investment for reduced calibration drift.
FCC certification governs wireless transmission protocols for devices sold in the United States, while CE marking under EU Radio Equipment Directive regulates electromagnetic compatibility across European member states. Japan's METI administers technical standards for precision measurement instruments that affect import eligibility and domestic manufacturing compliance. Stakeholders must monitor evolving interoperability mandates between proprietary ecosystems and open standards as regulatory pressure on repairability and battery replaceability intensifies across multiple jurisdictions.
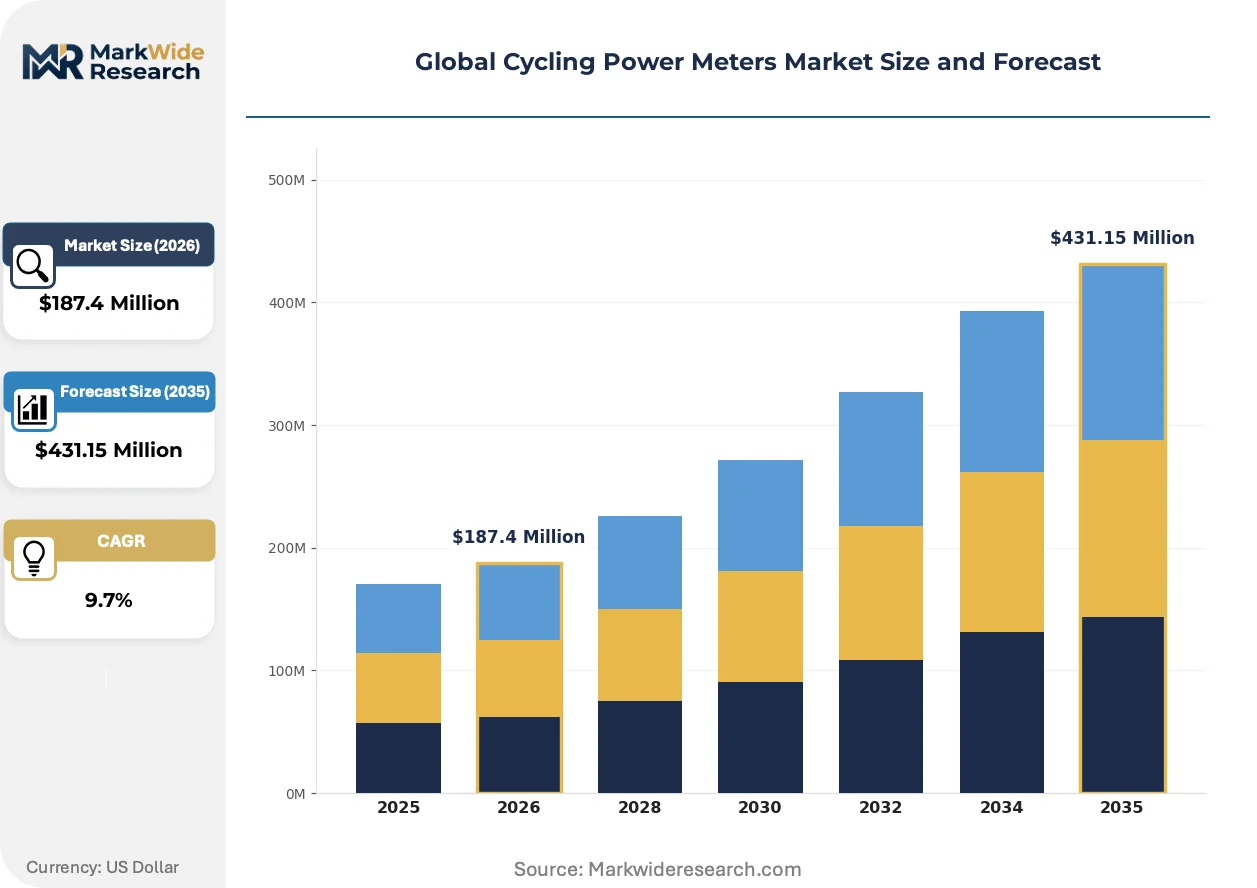
Market Dynamics
Amateur rider demand is forcing manufacturers to compress price points while preserving laboratory-grade accuracy specifications previously reserved for professional cyclists. This democratization pressure is restructuring product roadmaps and channel economics across the entire value chain.
Growth Catalysts
- Bluetooth ANT+ protocol convergence:Unified wireless standards eliminate compatibility friction between head units, wearables, and training platforms. Riders now expect seamless ecosystem integration as a baseline purchase criterion.
- German cycling infrastructure investment:Federal and municipal spending on dedicated bike lanes and competitive event calendars sustains replacement cycles and upgrade frequency among enthusiast populations.
- Strain gauge precision improvements:Temperature-compensated semiconductor designs now achieve sub-one-percent accuracy variance across negative ten to fifty degrees Celsius operating ranges.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium sourcing dependencies create input cost volatility for pedal-based spindle motor configurations.
- CE marking electromagnetic compatibility testing:EU Radio Equipment Directive compliance adds six to nine month certification timelines and five-figure euro validation costs per SKU variant.
- Optical sensing calibration drift:Photonic torque measurement methods still exhibit unacceptable zero-offset degradation compared to bonded foil strain gauge baselines.
Strategic Opportunities
- Japanese METI precision instrument standards:Domestic manufacturing compliance creates import substitution incentives for local assembly partnerships serving East Asian markets.
- Gravel and cyclocross discipline expansion:Multi-bike ownership patterns among amateurs drive demand for transferrable pedal-based systems over fixed crank installations.
- Direct-to-consumer subscription bundling:Hardware-software attach models bypass traditional bike shop margin structures while capturing recurring revenue streams.
Industry Challenges
- Embedded firmware cybersecurity certification:Connected power meters face escalating scrutiny under evolving FDA cybersecurity guidance for software-as-medical-device adjacent classifications.
- Strain gauge bonding technician scarcity:Precision adhesive application and thermal compensation tuning require specialized labor pools concentrated in German and Japanese manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cycling Power Meters Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal-based, Crank-based, Hub-based, Measurement Devices Technology: Strain Gauge, Optical, Inertial Measurement, Ultrasonic End User: Professional Cyclists, Amateur Riders, Triathletes, Fitness Enthusiasts Installation: Post-purchase, DIY, Professional Installation, Integrated Systems |
| Companies Covered | Garmin Ltd., Wahoo Fitness, SRAM, Stages Cycling, Favero Electronics, SRM, Shimano Inc., 4iiii Innovations, Rotor Bike Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cycling Power Meters Market Emerging Trajectories
Product architectures are fragmenting along portability versus integration trade-offs as rider segments diverge in their multi-bike usage patterns and data fidelity requirements. This schism is accelerating form factor experimentation and wireless protocol standardization efforts.
Spider-based power measurement is miniaturizing through MEMS strain gauge arrays that replace traditional bonded foil configurations. Amateur cyclists upgrading from entry-level units now access pro-tier accuracy at mid-market price points. Component suppliers are compressing module dimensions to fit compact road crank BCD patterns without frame clearance compromises.
FCC Part 15 certification requirements for unintentional radiators are tightening emission limits on 2.4 GHz band transmissions used by ANT+ and Bluetooth protocols. Manufacturers must redesign PCB antenna geometries and shielding topologies to maintain compliance. Pedal-based systems with metal spindle housings face particular susceptibility to field strength test failures.
Training platform subscription bundling is displacing standalone hardware transactions as the primary customer acquisition mechanism. Bike shops now compete with direct channels on software trial periods and data migration services rather than discount depth. Australia and Germany exhibit the highest attach rates for premium analytics tiers among English and German language markets respectively.
Global Cycling Power Meters Market Segmentation
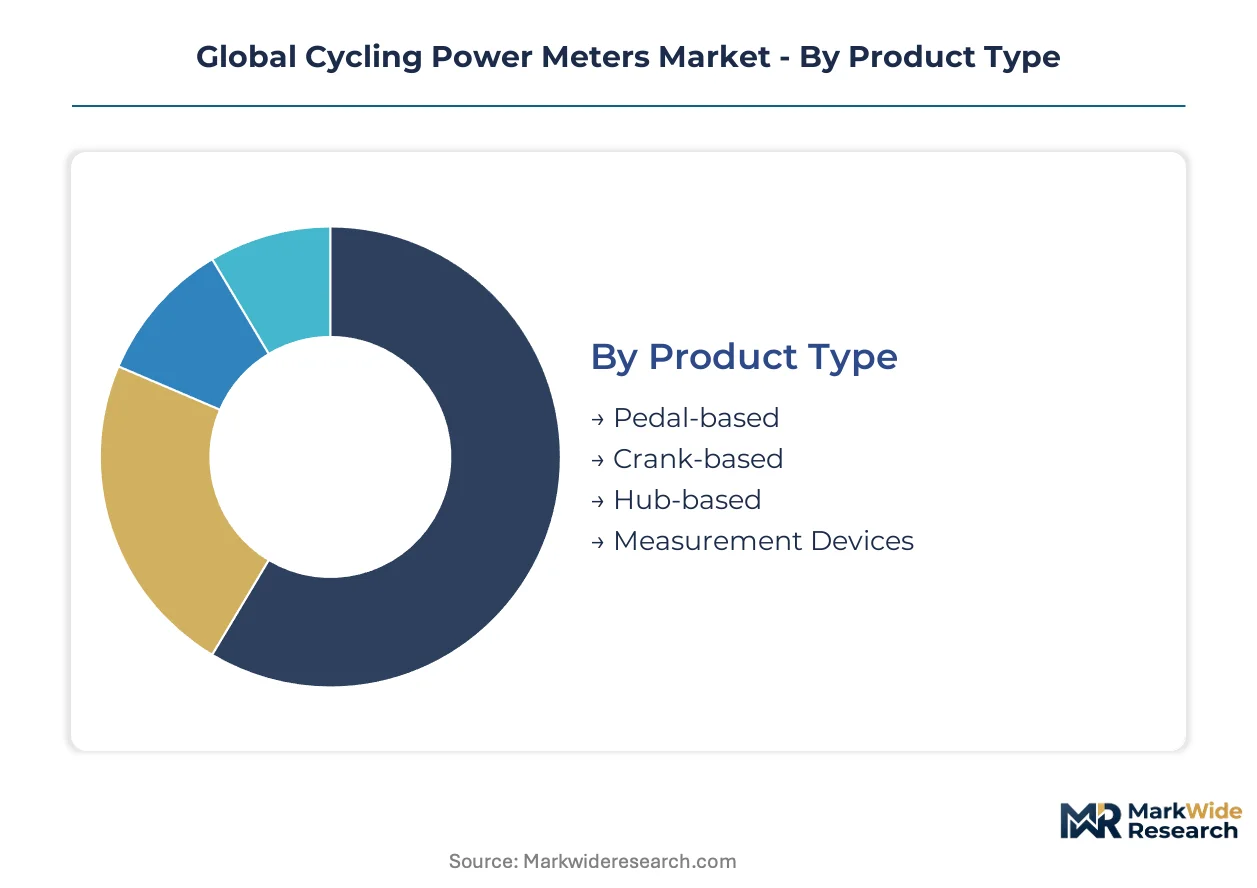
Cycling power meters fragment across four intersecting dimensions that reshape procurement economics and channel strategy. Product architecture and installation modality determine margin capture, while end-user identity and sensing technology govern replacement velocity and software attach rates.
Product Type:
Margin pools concentrate in crank-integrated systems where proprietary drivetrain lock-in sustains premium pricing, while pedal-based alternatives compete on transferability economics.
- Pedal-based:Spindle-integrated strain gauge arrays measure torque at the pedal-cleat interface. Demand clusters among amateur riders in Germany and Australia who maintain multiple bicycles across road, gravel, and cyclocross disciplines. Transferability between bikes eliminates redundant hardware purchases.
- Crank-based:Spider or chainring-integrated measurement modules achieve highest accuracy through direct drivetrain force capture. Professional cyclists and competitive amateurs in Japan prioritize this architecture for its proven durability across temperature extremes from negative ten to fifty degrees Celsius.
- Hub-based:Rear hub-integrated torque sensors serve niche touring and commuting applications where frame compatibility constraints exclude crank or pedal mounting.
- Measurement Devices:Handlebar-mounted optical and inertial units provide non-invasive power estimation for entry-level riders testing training analytics before hardware investment.
Crank-based systems hold installed capacity. Pedal-based configurations are rotating up the share rankings.
Technology:
Commercial deployment volumes favor strain gauge maturity, though development capital is concentrating on optical methods that promise reduced calibration maintenance.
- Strain Gauge:Bonded foil or semiconductor strain elements measure mechanical deformation under load. Temperature-compensated designs now achieve sub-one-percent accuracy variance across operating ranges. German and Japanese manufacturing clusters concentrate specialized bonding technician labor pools.
- Optical:Photonic torque measurement through polarized light or interferometric methods attracts R&D investment from component suppliers seeking to eliminate zero-offset drift. Current implementations still exhibit unacceptable baseline degradation compared to strain gauge benchmarks.
- Inertial Measurement:Accelerometer and gyroscope fusion algorithms estimate power output without direct force sensing. Fitness enthusiasts in Australia adopt these lower-cost entry points before upgrading to direct-measurement systems.
- Ultrasonic:Piezoelectric transducers measure torque through acoustic wave propagation time variations. Limited commercial deployment concentrates in industrial calibration equipment with cycling applications remaining experimental.
Strain gauge platforms dominate production volumes. Optical approaches are gaining share fastest among development-stage portfolios.
End User:
Amateur rider expansion is restructuring volume-mix economics as manufacturers compress price points while preserving laboratory-grade accuracy specifications.
- Amateur Riders:Fitness enthusiasts and club cyclists seeking training data previously reserved for professionals. This segment drives demand for mid-market pedal-based systems with Bluetooth ANT+ protocol convergence and software subscription bundling.
- Professional Cyclists:UCI-registered competitors and elite triathletes requiring certified accuracy for race pacing and training load management. Crank-based systems with documented calibration chains satisfy team equipment protocols.
- Triathletes:Multi-sport athletes prioritize transferability between road bikes and time trial configurations. Pedal-based systems dominate this application for rapid bike swaps during competition transitions.
- Fitness Enthusiasts:Indoor training platform users and recreational riders entering structured training programs. Price-sensitive demand concentrates in direct-to-consumer channels with hardware-software trial bundling.
Professional cyclists anchor premium tier margins. Amateur riders are climbing the fastest as volume expansion restructures channel economics.
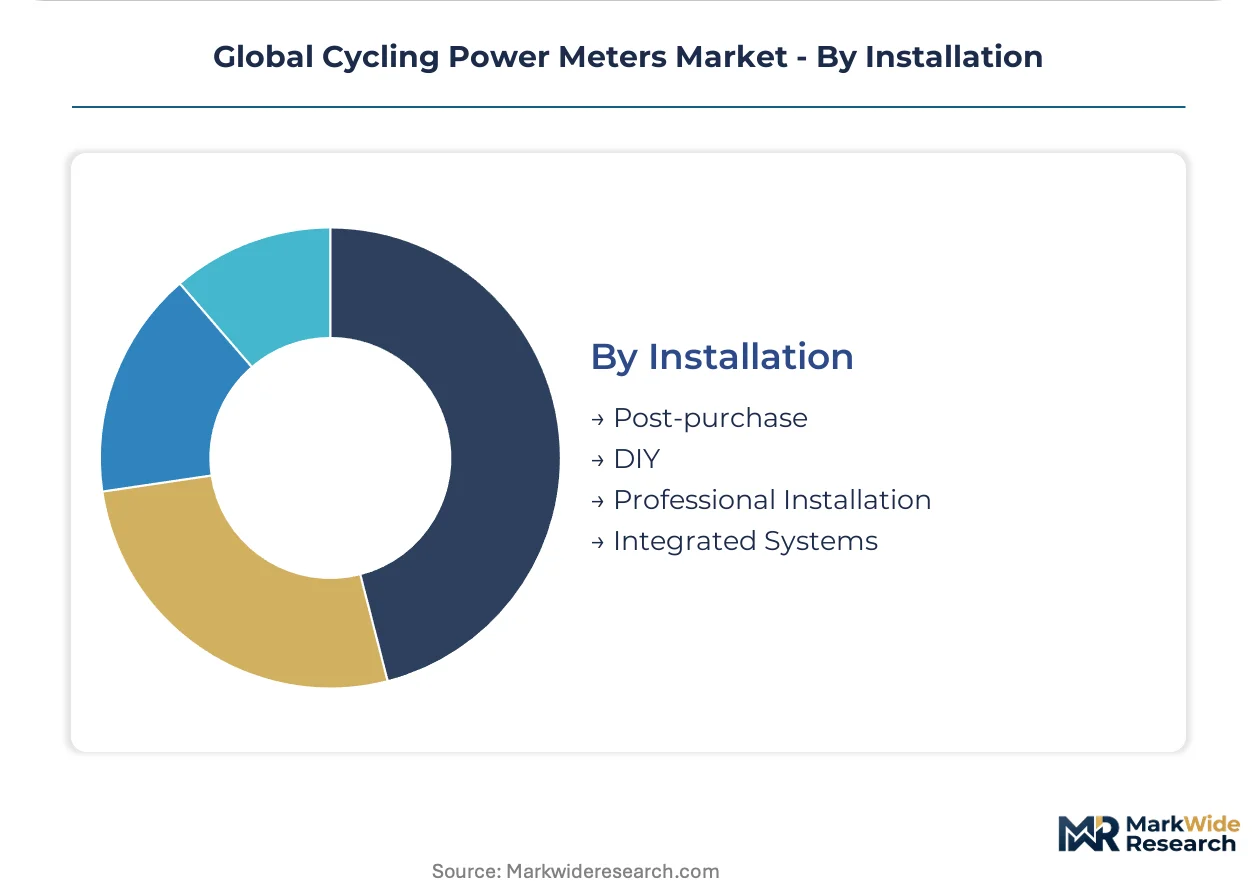
Installation:
Service revenue attachment varies sharply by installation modality, with professional fitting sustaining bike shop margin pools against direct-to-consumer compression.
- Professional Installation:Certified mechanic fitting ensures proper torque specifications, firmware pairing, and calibration verification. Bike shops in Germany and Japan capture service revenue and software migration fees through this channel.
- DIY:Consumer self-installation of pedal-based systems requires only standard hex keys and smartphone app guidance. This modality enables direct-to-consumer bypass of traditional retail margin structures.
- Post-purchase:Retrofit installation onto existing bicycles, distinct from factory-integrated OEM fitment. Amateur riders upgrading entry-level bikes drive this demand category.
- Integrated Systems:Factory-installed power measurement within complete bicycle purchases at point of sale. High-end road and triathlon bike manufacturers in Japan bundle crank-based systems as standard equipment.
Professional installation retains service value. DIY modalities are rotating up the share rankings as pedal-based simplicity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alps freight corridor underwrites Germany's centrality to European cycling equipment distribution, while Japan's Shinkansen network enables just-in-time component delivery to precision manufacturing clusters. Australia's east coast intermodal links connect Port Botany imports with domestic assembly operations serving Asia-Pacific demand.
Germany
Federal transport ministry spending on dedicated cycling infrastructure exceeds municipal budgets across most EU member states, sustaining replacement cycles among enthusiast populations. CE marking under the EU Radio Equipment Directive governs electromagnetic compatibility certification for wireless power meter sales. The Baden-Württemberg precision engineering cluster around Stuttgart concentrates strain gauge bonding technician labor pools serving crank-based system manufacturers.
Japan
METI-administered technical standards for precision measurement instruments create import eligibility barriers that protect domestic manufacturing compliance. The Chubu region around Nagoya hosts specialized semiconductor fabrication facilities producing temperature-compensated strain gauge arrays. Osaka-based component suppliers maintain captive supply relationships with bicycle OEMs integrating factory-installed power measurement systems.
Australia
State-level cycling infrastructure investment in New South Wales and Victoria sustains competitive event calendars that drive upgrade frequency among amateur riders. The Therapeutic Goods Administration (TGA) maintains jurisdiction over connected device cybersecurity standards affecting firmware update protocols. Melbourne's industrial suburbs concentrate direct-to-consumer fulfillment operations bypassing traditional bike shop margin structures.
United States
FCC Part 15 certification requirements for unintentional radiators impose emission limits on 2.4 GHz wireless transmissions used by ANT+ and Bluetooth protocols. The Pacific Northwest cycling corridor between Portland and Seattle generates concentrated demand for gravel discipline power measurement systems. Colorado's Front Range urban corridor supports specialized mechanic training programs for professional installation service revenue capture.
Global Cycling Power Meters Market Vendor Landscape
Listed leaders compete with private specialists across ecosystem integration and hardware-software attach models, producing a tiered structure where scale-driven platform players occupy premium positions alongside focused component fabricators. Garmin Ltd. leverages its GPS navigation heritage to sustain repeat purchases within its installed base, while SRAM anchors proprietary crank-integrated designs through drivetrain family compatibility. Wahoo Fitness competes aggressively on wireless connectivity standards and subscription bundling economics. Dominant competitive moves include direct-to-consumer channel expansion and hardware-software trial bundling that displaces traditional retail margin structures.
Within the ecosystem-integrated tier, Garmin Ltd. exemplifies platform leverage across head units and wearables, while SRAM represents proprietary hardware lock-in through drivetrain compatibility. Wahoo Fitness occupies a position defined by aggressive wireless protocol standardization and software subscription economics. These three anchors illustrate divergent strategic bets on whether rider loyalty attaches to measurement hardware, training software, or complete ecosystem integration.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Wahoo Fitness |
| SRAM |
| Stages Cycling |
| Favero Electronics |
| SRM |
| Shimano Inc. |
| 4iiii Innovations |
| Rotor Bike Components |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with Baden-Württemberg strain gauge bonding facilities lock in component access and price visibility for crank-based system manufacturers, insulating procurement teams from spot-market volatility in precision technician labor pools.
Pricing Analysis
Volume-discount tiering separates pro-tier crank-integrated systems from mid-market pedal-based alternatives and entry-level hub configurations. Price differentiation rests on calibration certification grade and Bluetooth ANT+ protocol stack maturity. Cost compression in the amateur rider tier is intensifying because manufacturers must preserve sub-one-percent accuracy specifications at compressed price points. Fitness enthusiasts exhibit highest price sensitivity while UCI-registered professionals accept premium positioning for documented calibration chains.
Supply Chain Analysis
Rare earth magnet sourcing through China's Baotou processing corridor creates single-source vulnerability for pedal-based spindle motor configurations. Strain gauge semiconductor fabrication concentrates in Japan's Chubu region and Germany's Stuttgart cluster. Neodymium and samarium dependencies feed from concentrated extraction operations. Distribution runs through Osaka-based component suppliers serving Japanese bicycle OEMs and Rhine-Alps freight corridors feeding European bike shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized strain gauge bonding technician scarcity in German and Japanese manufacturing clusters creates competitive moats for incumbents while raising entry barriers for new market participants lacking captive labor pool relationships.
For Market Incumbents: Secure exclusive technician training partnerships with Stuttgart and Nagoya technical institutes to defend against emerging optical sensing substitutes. Deepen backward integration into temperature-compensated semiconductor strain element production to reduce rare earth magnet exposure. Channel control through certified mechanic networks in Germany and Japan sustains service revenue attachment against direct-to-consumer compression. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission consultations opens European market access before full electromagnetic compatibility validation cycles conclude. Target Australian amateur riders with gravel discipline pedal-based systems where multi-bike ownership patterns favor transferability economics. Direct-to-consumer subscription bundling with indoor training platforms bypasses traditional bike shop margin structures. For Investors and Strategic Acquirers: Capital is best deployed toward component fabricators with captive strain gauge bonding capabilities and established METI compliance relationships in Japan. Long-term viability hinges on software-hardware attach rate sustainability as training platform economics displace standalone hardware transactions. Watch FCC Part 15 emission limit tightening as inflection indicator for antenna redesign capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Partnership | Secures specialized labor pools in Stuttgart and Nagoya clusters against competitor poaching. |
| Optical Sensing R&D Investment | Addresses zero-offset drift limitations that currently constrain photonic torque measurement adoption. |
| Direct-to-Consumer Platform Launch | Bypasses German and Australian bike shop margin structures through hardware-software trial bundling. |
| CE Marking Fast-Track Pathway | Compresses six-to-nine month EU Radio Equipment Directive timelines for pedal-based SKU variants. |
| Rare Earth Magnet Supply Agreement | Reduces neodymium cost volatility exposure for spindle motor configurations through long-term offtake. |
Methodological Framework
Cross-validation between component supplier production data and national cycling federation registration statistics anchors the qualitative findings on replacement cycle velocity. Primary interviews with strain gauge bonding technicians, bicycle OEM procurement managers, and certified mechanic network operators combined with secondary validation against METI precision instrument filings, FCC Part 15 certification databases, and EU customs trade records. Bottom-up SKU shipment aggregation and top-down national market sizing triangulate volume estimates.
Sensitivity analysis across amateur rider penetration rates and optical sensing technology maturation timelines informs the projection framework. Segmentation dimensions modeled include product architecture, sensing technology, end-user category, and installation modality across the analysis window. CAGRs derive from fitted growth curves against historical replacement patterns. Industry-specific inputs incorporate Bluetooth ANT+ protocol adoption curves and indoor training platform subscription attach rates.
Decision-makers should treat outputs as directional under assumptions of sustained German cycling infrastructure investment and stable rare earth magnet supply chains; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as FCC emission limit evolution and METI precision standard revisions unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Mouthguard Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Slam Ball Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Golf Ball Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Kids Sports Equipment and Accessories Market