
 Equestrian Equipment Market | 2026-2036
Equestrian Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Equestrian Equipment Market Analysis
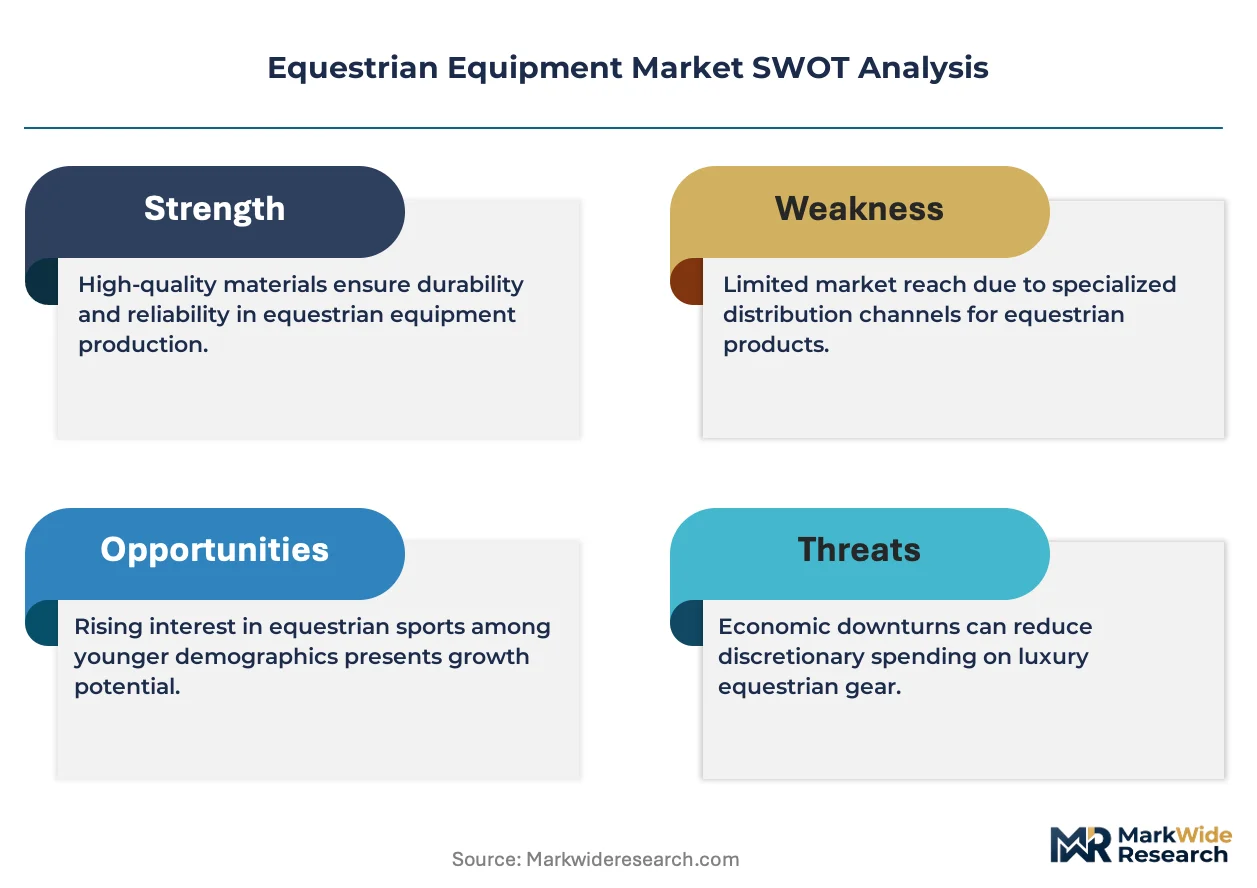
The capital-intensity gap between premium full-line manufacturers and specialty artisans is collapsing as synthetic material R&D costs drop and small-batch digital cutting tools spread. Ariat International leverages its vertically integrated leather supply chain to sustain margin control across English and Western disciplines. Horseware Ireland competes through Ireland's dense network of eventing professionals, while Decathlon anchors volume distribution through its global sporting-goods retail footprint.
Equestrian equipment encompasses the protective, functional, and performance-oriented gear used in horseback riding, training, and competition, typically constructed from vegetable-tanned leather, technical textiles, or molded polymers meeting ASTM F1163 helmet standards and EN 1384 safety certifications. Saddles and bridles remain the largest product type segment, though synthetic material alternatives are capturing share as riders prioritize weather resistance and reduced maintenance. Competitive riders represent the fastest-growing end user category, where margin pools concentrate around custom-fitted performance gear and FEI-compliant protective equipment.
The US Consumer Product Safety Commission coordinates with ASTM International to enforce equestrian helmet impact standards, while the EU's REACH regulation governs chemical restrictions in leather tanning processes. France's ANSM and Germany's KBA both influence safety equipment certification pathways for cross-border European distribution. Stakeholders must monitor evolving biosecurity standards for animal-contact materials and anticipate how digital saddle-fitting technologies will reshape service-based revenue models.
Market Dynamics
Synthetic polymer R&D and digital manufacturing tools are collapsing the capital barrier between artisan workshops and full-line manufacturers, redistributing competitive power across the value chain.
Growth Catalysts
- REACH chemical restrictions:European leather tanning compliance costs are filtering out marginal suppliers and consolidating procurement toward certified producers in Germany and Ireland.
- FEI protective equipment mandates:Competitive riders upgrading to certified helmets and body protectors are accelerating replacement cycles for ASTM F1163 and EN 1384 compliant gear.
- Eventing infrastructure concentration:Olympic-level training facilities in Germany are generating localized demand spikes for custom-fitted performance saddles and bridles.
Market Restraints
- Vegetable-tanned leather supply volatility:Premium hide sourcing faces price instability from livestock disease protocols and climate-affected grazing regions.
- Biosecurity certification delays:Emerging animal-contact material standards in major European markets are extending product approval timelines without harmonized cross-border recognition.
- Synthetic alternative performance ceiling:Molded polymer saddles still fail to replicate leather's moisture-wicking and conforming properties for elite dressage applications.
Strategic Opportunities
- Digital saddle-fitting services:Pressure-mapping and 3D scanning technologies are enabling remote custom fitting, opening subscription revenue models beyond hardware sales.
- Weather-resistant synthetic lines:Technical textile bridles and synthetic tack are capturing share among recreational riders in humid climates where leather maintenance burdens concentrate.
- Decathlon's sporting-goods channel:Volume distribution through global retail footprints is penetrating price-sensitive entry-level segments previously served only by specialty equestrian retailers.
Industry Challenges
- Master saddler talent scarcity:Traditional apprenticeship pipelines are failing to replace retiring craftsmen capable of hand-fitting custom performance equipment.
- Dual certification complexity:Manufacturers must simultaneously satisfy ASTM International helmet standards and EN 1384 requirements for cross-Atlantic competitive rider segments.
- Legacy inventory integration:Digital cutting tools and small-batch production systems require retraining workflows across established artisan workshops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equestrian Equipment Market |
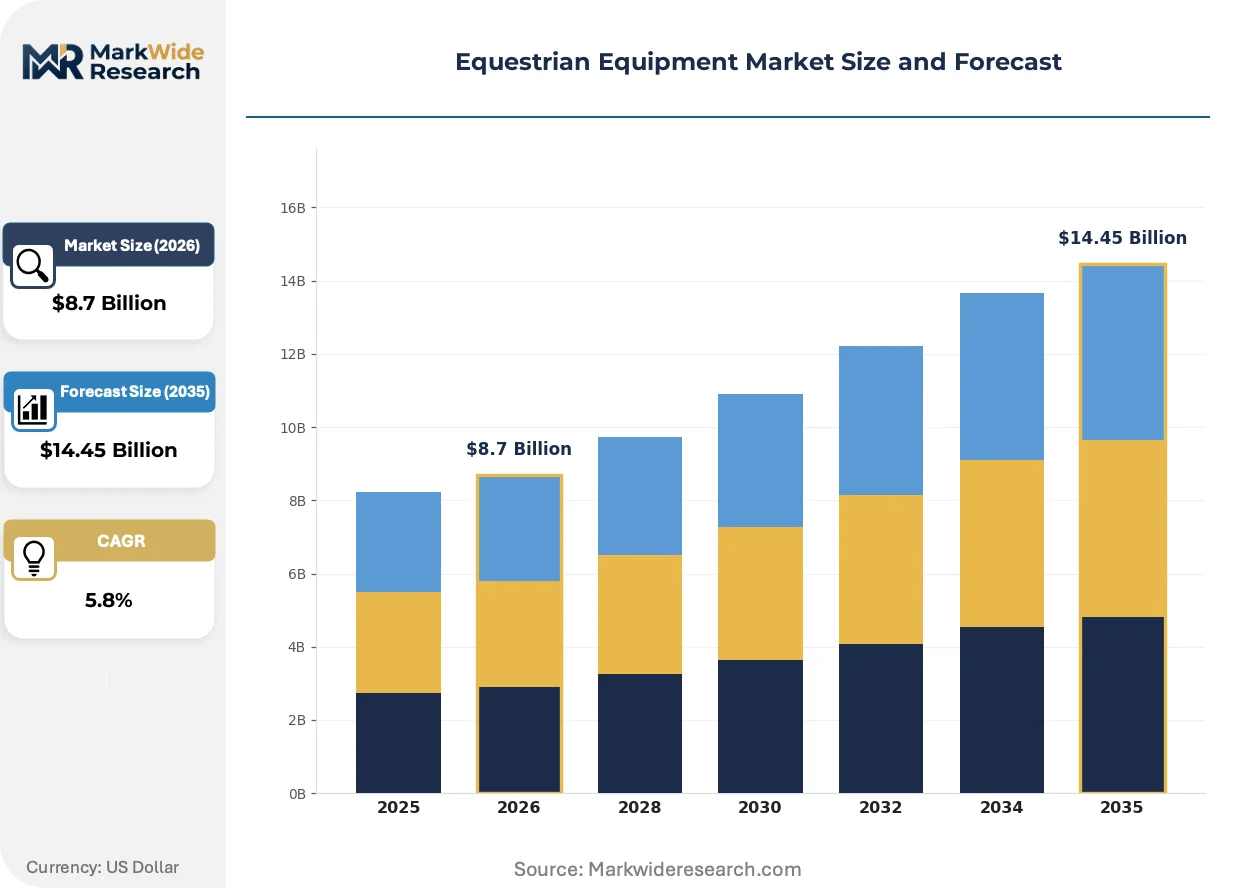
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Harnesses, Whips Material: Leather, Synthetic, Cotton, Nylon End User: Veterinarians, Trainers, Competitive Riders, Casual Riders Usage Type: Training, Competition, Leisure, Farming |
| Companies Covered | Ariat International, Horseware Ireland, Cavallo GmbH, Charles Owen, HKM Sports Equipment GmbH, Decathlon, WeatherBeeta, Devoucoux, Dainese, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equestrian Equipment Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are actively restructuring how protective gear is certified, manufactured, and distributed across competitive and recreational segments.
Pressure-sensor saddle pads paired with smartphone analytics are fragmenting the traditional fitting process. Competitive riders in Germany and Ireland are adopting these systems to quantify equine biomechanics and optimize performance. The technology is fragmenting the service-based revenue model by shifting value capture from physical tack sales toward data-driven fitting subscriptions and remote consultation fees.
REACH chemical restrictions on chromium tanning processes are forcing leather processors toward vegetable-based alternatives. This regulatory pressure is elevating production costs for traditional full-grain equipment while creating compliance advantages for certified tanneries in Germany. Premium saddle manufacturers are responding by vertically integrating into captive hide supply chains to maintain margin control.
Recreational riders are compressing purchase cycles toward disposable-grade synthetic alternatives. Entry-level consumers through mass sporting-goods channels are prioritizing weather resistance and low maintenance over leather longevity. This behavioral shift is most visible in humid coastal regions where mold and mildew degradation accelerates traditional tack replacement decisions.
Equestrian Equipment Market Segmentation
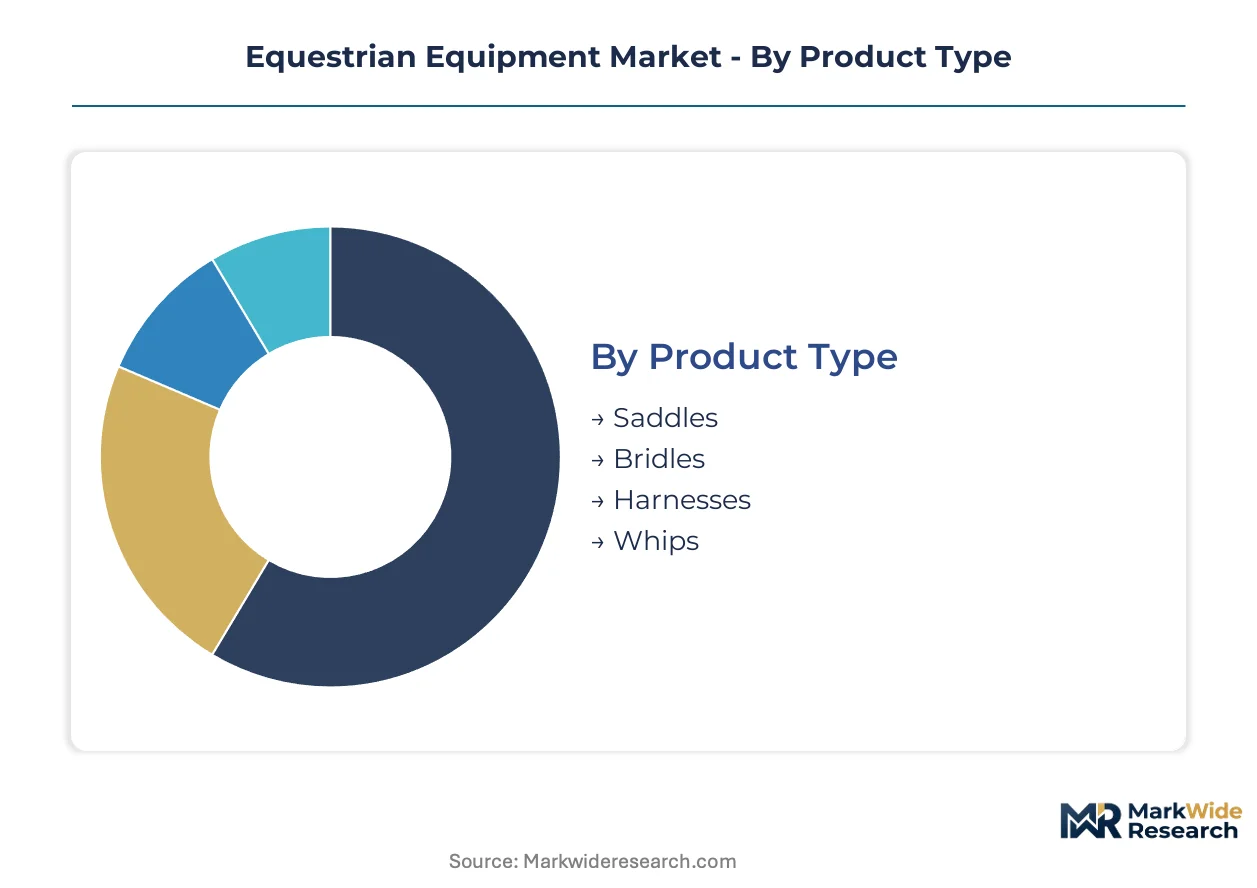
Equestrian equipment segmentation reveals how material substitution and end-use specialization are fragmenting traditional supply chains. Competitive riders and training facilities now drive specification divergence across protective gear, performance tack, and maintenance equipment categories.
Product Type:
Synthetic polymer alternatives and digital fitting technologies are displacing conventional leather-dominant segments fastest in saddles and bridles, while harnesses face mechanization pressure from agricultural automation.
- Saddles:Constructed from vegetable-tanned leather or molded thermoplastics with treeless designs gaining traction in endurance disciplines. Demand concentrates in Germany's Olympic training corridors where custom-fitted English and Western performance saddles command premium positioning against FEI biomechanical standards.
- Bridles:Headstall and bit assemblies incorporating anatomical crownpieces and gel-padded nosebands to reduce neural pressure. Competitive riders in Ireland's eventing clusters are driving specification upgrades toward bitless alternatives and interchangeable component systems.
- Harnesses:Draft and carriage equipment retaining leather dominance in heritage driving competitions while synthetic webbing captures agricultural utility applications. Nylon variants serve recreational sleigh and cart operators in Nordic regions.
- Whips:Fiberglass or carbon fiber shafts with synthetic lash materials replacing traditional leather crops across schooling and show environments. Regulatory scrutiny from Germany's KBA on animal welfare compliance is reshaping permissible designs.
Saddles retain volume leadership; bridles hold the steepest expansion curve.
Material:
REACH chemical restrictions are elevating cost structures across leather processing while technical textile R&D collapses performance gaps in synthetic alternatives.
- Leather:Full-grain vegetable-tanned hides meeting REACH tanning process standards for chromium-free certification. Germany's tannery clusters near Munich and Stuttgart supply certified material to premium saddle manufacturers facing biosecurity documentation requirements for animal-contact equipment.
- Synthetic:Molded polymers and technical textiles including ballistic nylon and coated webbing delivering weather resistance and reduced maintenance burdens. Humid coastal regions in Florida and Southeast Asia show concentrated adoption among recreational riders prioritizing durability over traditional aesthetics.
- Cotton:Natural fiber padding and girth linings absorbing moisture in schooling environments. Limited to entry-level and youth segments where cost sensitivity dominates procurement decisions.
- Nylon:High-tenacity woven straps and hardware components in halters, lead ropes, and stable equipment. Mass sporting-goods channels leverage nylon's volume scalability for price-sensitive distribution.
Leather retains volume leadership; synthetic materials hold the steepest expansion curve.
End User:
Professional certification requirements and competitive performance standards are widening specification gaps between institutional purchasers and recreational consumers.
- Competitive Riders:FEI-registered athletes requiring ASTM F1163 and EN 1384 certified protective equipment with custom-fitted performance saddles. Germany's eventing professionals and Ireland's show jumping circuits generate concentrated demand for biomechanically optimized gear with pressure-mapping validation.
- Trainers:Commercial schooling operations purchasing durable multi-horse equipment with standardized sizing for lesson programs. Volume procurement runs through specialized distributors serving regional training centers.
- Veterinarians:Equine health practitioners utilizing specialized restraint equipment and diagnostic positioning aids. Limited segment with specification driven by clinical safety protocols rather than performance optimization.
- Casual Riders:Weekend and leisure participants prioritizing cost accessibility and low maintenance over technical performance. Decathlon's sporting-goods retail footprint captures this segment through synthetic-heavy product lines.
Casual riders retain volume leadership; competitive riders hold the steepest expansion curve.
Usage Type:
Competition-grade certification requirements and leisure-oriented convenience preferences are bifurcating product development roadmaps across protective and functional equipment categories.
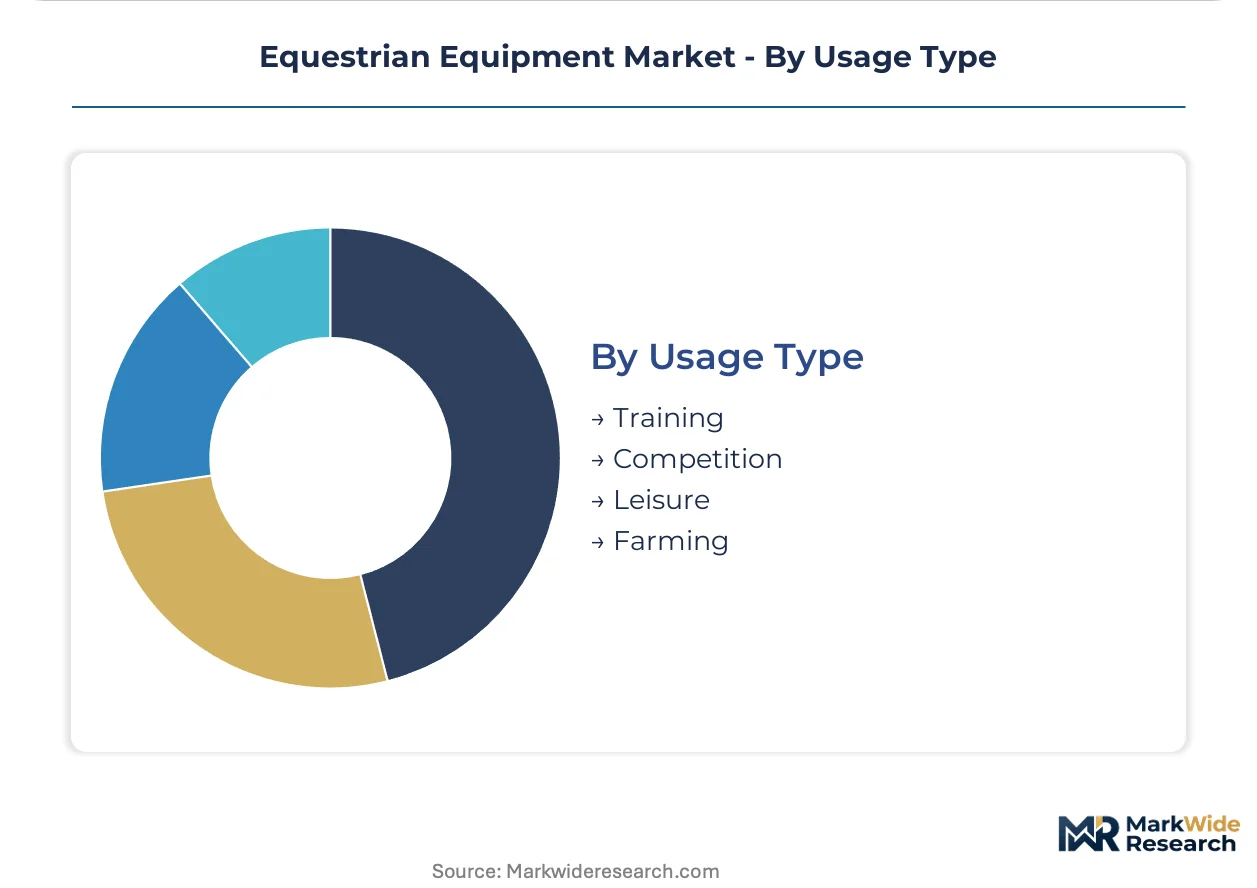
- Competition:FEI-mandated protective gear and performance tack subject to equipment steward inspection and standardized fit protocols. Germany's championship venues and Ireland's international eventing calendar drive replacement cycles for certified helmets and body protectors.
- Training:Schooling equipment emphasizing durability and multi-horse compatibility over custom precision. Synthetic materials capture share in high-frequency daily use environments where leather maintenance burdens accumulate.
- Leisure:Trail and recreational riding gear prioritizing weather resistance and storage convenience. Humid climate regions show accelerated shift toward molded polymer saddles and synthetic bridles.
- Farming:Agricultural utility equipment including draft harnesses and livestock handling aids facing mechanization pressure from tractor-dependent operations. Heritage preservation driving limited leather harness demand in Amish and Mennonite communities.
Training retains volume leadership; competition holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German custom saddle workshops command 40-60% price premiums over comparable Spanish producers, reflecting certification density and master saddler scarcity rather than input cost differentials. This asymmetry shapes procurement patterns across competitive and recreational segments.
Germany
Olympic-level eventing infrastructure in Warendorf and Waregem-adjacent training corridors drives concentrated demand for FEI-certified protective gear and biomechanically optimized saddles. REACH chemical restrictions on chromium tanning processes filter procurement toward certified tanneries in Munich-Stuttgart industrial clusters. Master saddler apprenticeships in Baden-Württemberg face 18-month waiting lists, constraining custom-fitted performance equipment output.
United States
Recreational riding participation in Florida and coastal California accelerates synthetic tack adoption as humidity-degraded leather replacement cycles compress. ASTM F1163 helmet standards enforced by the Consumer Product Safety Commission create compliance barriers for European imports lacking dual certification. Kentucky's thoroughbred breeding complexes anchor premium English saddle demand alongside Texas Western discipline strongholds.
Ireland
Eventing professional density in County Meath and Kildare generates specification pressure toward anatomical bridles and bitless alternatives. ECHA REACH enforcement through Irish environmental regulators elevates vegetable-tanned leather costs for domestic manufacturers. Horseware Ireland's proximity to this cluster shapes regional product development priorities for weather-resistant technical textiles.
France
ANSM oversight of equestrian protective equipment certification creates cross-border friction for non-EU manufacturers targeting competitive riders. Normandy's heritage driving competition circuit sustains limited artisan harness demand against agricultural mechanization. Lyon-area textile engineering capabilities support technical bridle component sourcing for premium Parisian saddlery houses.
United Kingdom
Post-Brexit divergence from EN 1384 helmet standards forces dual-track certification investments for manufacturers serving both domestic and EU competitive riders. Cotswolds eventing estates and Newmarket racing infrastructure concentrate high-value saddle procurement. Charles Owen's manufacturing presence in Wrexham industrial zones exemplifies protective equipment specialization under UKCA marking transition.
Equestrian Equipment Market Vendor Landscape
Concentration sits with vertically integrated leather processors and technical textile specialists rather than diversified sporting-goods conglomerates. The vendor base spans three tiers: heritage saddlers with captive tannery relationships, synthetic-focused volume manufacturers, and mass retail private-label operators. Strategic moves center on backward integration into hide supply chains and digital fitting technology licensing to capture recurring service revenue.
Among Ireland- and Germany-based specialists, Horseware Ireland, Cavallo GmbH, and Charles Owen occupy archetypal positions across technical textile innovation, precision polymer engineering, and protective equipment certification respectively. These entities exemplify how geographic proximity to elite training infrastructure shapes competitive positioning. Decathlon anchors the volume tier through sporting-goods retail density, while Ariat International represents North American vertical integration models.
| Leading Market Players |
|---|
| Ariat International |
| Horseware Ireland |
| Cavallo GmbH |
| Charles Owen |
| HKM Sports Equipment GmbH |
| Decathlon |
| WeatherBeeta |
| Devoucoux |
| Dainese |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for vegetable-tanned hides from certified German tanneries concentrate pricing power among vertically integrated saddle manufacturers while compressing margins for artisan workshops dependent on spot-market leather procurement. REACH compliance documentation requirements and biosecurity certification delays extend inventory cycles, forcing working-capital tradeoffs between premium full-grain stockpiling and synthetic material substitution.
Pricing Analysis
Custom-fitted English saddles in Germany command 40-60% premiums over standard-configured Spanish equivalents, with price differentiation resting on master saddler certification density and FEI biomechanical validation rather than input cost disparities. Three-tier pricing structure across premium custom-fitted, standard competition-grade, and economy synthetic lines stratifies procurement decisions. Cost compression in entry-level segments is intensifying because Decathlon's sporting-goods channel penetrates price-sensitive recreational riders. Casual riders exhibit highest price sensitivity; competitive riders demonstrate lowest sensitivity due to performance-mandated equipment standards.
Supply Chain Analysis
Inventory cycles stretching 90-120 days for REACH-compliant vegetable-tanned leather reflect supply concentration in Germany, Ireland, and select Italian tannery clusters. Raw material dependencies center on full-grain hides, chromium-free tanning agents, and technical textile polymers. Single-source vulnerability pervades master saddler craftsmanship pipelines, where 18-month apprenticeship waiting lists in Baden-Württemberg constrain custom-fitted output. Distribution runs through specialized equestrian retailers for competitive segments and mass sporting-goods channels for recreational volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic polymer performance ceilings are lifting fastest in humid-climate recreational segments, threatening leather-dominant incumbents who fail to defend material substitution frontiers.
For Market Incumbents: Secure captive hide supply chains through backward integration into certified German tannery relationships, insulating margin control from REACH chemical restriction cost escalations. Invest in digital saddle-fitting technology licensing to capture recurring subscription revenue against hardware commoditization. Master saddler talent scarcity in Ireland and Germany demands apprenticeship pipeline expansion to defend custom-fitted positioning. For New Entrants and Emerging Players: Lead with weather-resistant synthetic tack lines targeting Florida and Southeast Asian recreational riders where leather maintenance burdens drive switching behavior. Penetrate entry-level segments through mass sporting-goods retail partnerships rather than specialty distributor relationships. Emphasize pressure-mapping validation and smartphone analytics integration to differentiate from legacy artisan competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across synthetic material manufacturing as small-batch digital cutting tools democratize precision production. Long-term viability favors acquisition targets combining technical textile R&D capabilities with proximity to Olympic-level training infrastructure in Germany or Ireland. Monitor FEI equipment mandate expansion as signal for protective gear replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Tanneries | REACH compliance advantages concentrate in Munich-Stuttgart industrial clusters. |
| Digital Fitting Technology Licensing | Pressure-mapping subscriptions shift value capture beyond hardware sales. |
| Synthetic Line Expansion for Humid Climates | Weather-resistant technical textiles capture recreational riders in Florida and Southeast Asia. |
| Master Saddler Apprenticeship Pipeline | Baden-Württemberg waiting lists signal talent scarcity constraining custom output. |
| Dual Certification Investment | ASTM F1163 and EN 1384 compliance opens cross-Atlantic competitive rider access. |
Methodological Framework
Desk research of customs trade records, ECHA REACH enforcement documentation, and FEI equipment mandate archives preceded structured interviews with saddle manufacturers, tannery procurement managers, specialty equestrian retailers, and competitive rider equipment stewards. Primary fieldwork across Germany's Warendorf training corridors and Ireland's County Meath eventing clusters validated secondary data on specification pressures and replacement cycle patterns. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Variance decomposition across material substitution rates, regulatory compliance cost trajectories, and digital adoption curves shaped analytical framework construction throughout the forecast period. Segmentation dimensions modeled encompass product type, material composition, end-user certification requirements, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline penetration estimates, with synthetic material R&D cost trajectories and master saddler supply constraints as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FEI mandate enforcement or accelerated REACH chemical restriction expansion would require recalibration. Forecasts reflect documented assumptions regarding competitive rider participation growth and synthetic material performance convergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Quad Skate Market
Sports Equipment
Pitching Machine Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Balance Bike Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Boxing Equipment Market