
 Leisure Centers Market | 2026-2036
Leisure Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Leisure Centers Market Foresight
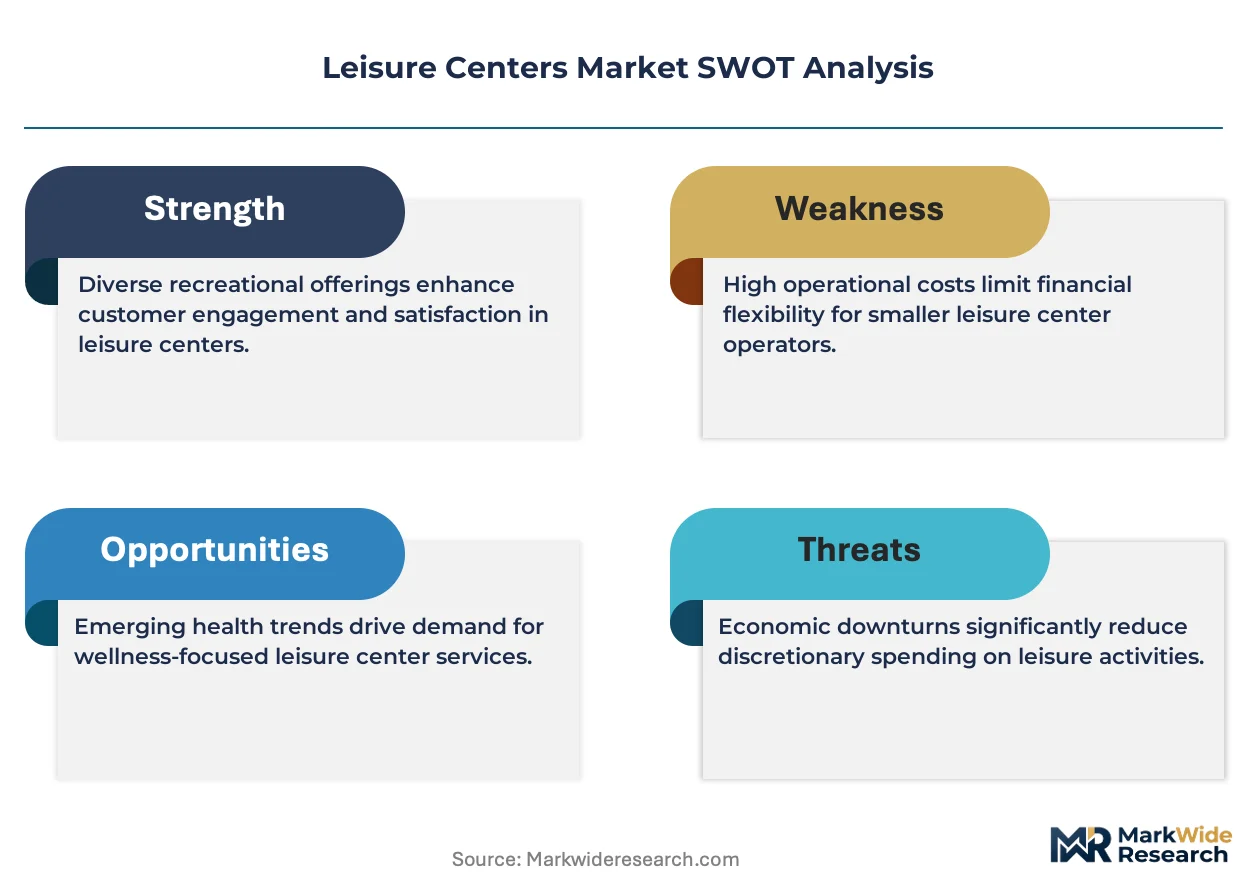
Premium amenity tier differentiation is collapsing the traditional mid-market positioning that once separated budget operators from luxury providers. Life Time Inc. anchors its competitive stance through vertically integrated real estate development combining fitness, workspace, and hospitality under single-roof formats. David Lloyd Leisure specializes in racquet sports integration with family-oriented club ecosystems across European suburban corridors. Virgin Active differentiates via design-forward studio concepts that compete directly with boutique fitness independents in London, Singapore, and Johannesburg.
A leisure center constitutes a purpose-built commercial or municipal facility housing programmed physical activity spaces, typically spanning 20,000 to 150,000 square feet with engineered HVAC loads of 25-50 watts per square foot to manage occupant density and pool evaporation rates. Its primary commercial function generates recurring membership revenue through access-controlled environments while delivering ancillary service income from personal training, food and beverage, and event programming. Fitness clubs and aquatic centers represent the mature revenue base where membership retention economics dominate capital planning, while sports complexes capture accelerating demand from youth travel team leagues and corporate wellness contracts that command premium per-hour facility rental rates. Recreation centers serve as the municipal margin pool where operating subsidies and grant financing obscure true profitability but secure long-term land access and community goodwill.
Facility design and operations in the United States face OSHA workplace safety standards and state-level health department pool chemistry protocols that dictate staffing ratios and certification requirements. The EU Green Deal building performance standards and national F-Gas Regulations in member states are forcing refrigeration and climate system retrofits that alter capital expenditure timelines for aquatic center operators. Stakeholders must monitor how municipal bond market conditions and zoning liberalization for mixed-use wellness districts reshape site acquisition economics against rising construction labor constraints.
Market Dynamics
Capital allocation for leisure center construction is bifurcating between retrofit-ready existing stock and purpose-built mixed-use wellness districts, as municipal bond markets and zoning liberalization reshape site economics against persistent construction labor shortages.
Growth Catalysts
- EU Green Deal building performance mandates:Energy efficiency retrofit requirements are accelerating capital deployment toward HVAC and pool evaporation recovery systems that meet F-Gas Regulation standards.
- Youth travel team league expansion:Tournament-grade sports complexes command premium hourly rental rates from amateur athletics organizations seeking broadcast-ready facilities.
- Public-private partnership proliferation:Municipal governments and school districts are transferring operational risk to private operators while retaining land access and community goodwill.
Market Restraints
- Construction labor scarcity:Skilled trades shortages in mechanical and aquatic system installation extend project timelines and inflate fixed-cost absorption.
- Refrigeration input cost volatility:F-Gas phase-down schedules under EU regulation compress refrigerant supply availability and inflate climate system replacement economics.
- Site concentration in urban cores:Land scarcity in high-density metropolitan corridors limits greenfield development and elevates per-square-foot land acquisition costs.
Strategic Opportunities
- Corporate wellness contract expansion:Employer-sponsored fitness access programs represent underpenetrated B2B revenue streams with higher retention economics than individual membership models.
- Heat pump and thermal storage convergence:Integration of electrified HVAC with thermal battery systems enables demand-response revenue participation and utility incentive capture.
- Suburban corridor saturation gaps:Secondary metropolitan rings in Germany and the United States lack racquet-sports-integrated family club formats that dominate European exurban positioning.
Industry Challenges
- Aquatics certification pipeline constraints:State health department pool operator licensure requirements create staffing bottlenecks that limit operating hour expansion.
- Legacy membership system integration:Migration from on-premise server architectures to cloud-based access control platforms demands capital expenditure and operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leisure Centers Market |
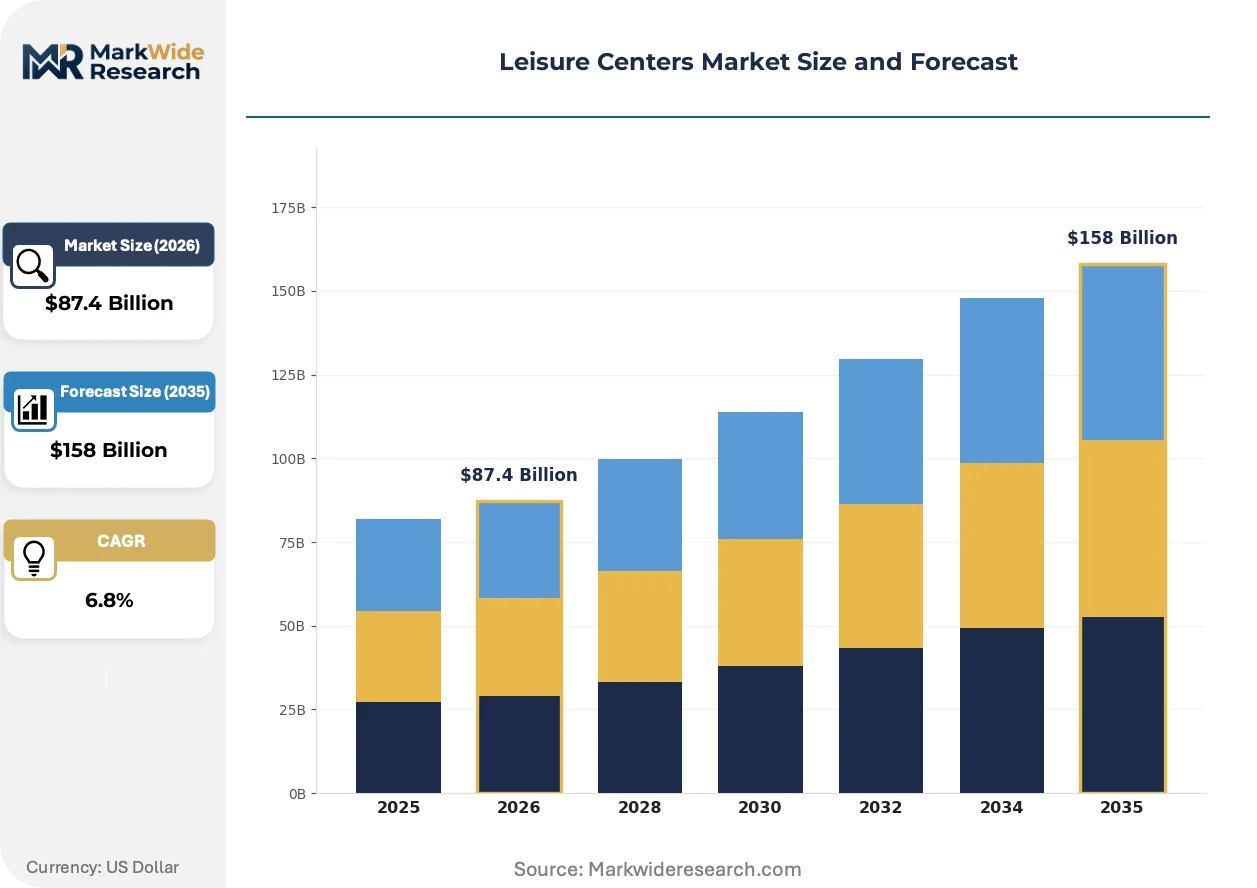
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Fitness Clubs, Aquatic Centers, Sports Complexes, Recreation Centers Service Offering: Membership Plans, Personal Training, Group Classes, Spa Services Age Group: Children, Teens, Adults, Seniors Activity Type: Swimming, Gymnastics, Aerobics, Team Sports |
| Companies Covered | Life Time Inc., David Lloyd Leisure, Virgin Active, Planet Fitness, LA Fitness, Equinox Holdings, Gold's Gym, Merlin Entertainments, YMCA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leisure Centers Market Shifts & Advancements
Facility design philosophy is pivoting from single-purpose athletic programming toward hybrid wellness-workspace-hospitality formats that maximize revenue per square foot through extended dwell-time engineering.
Smart building management systems incorporating real-time occupancy sensing and predictive HVAC load balancing are bifurcating operational economics between premium automated facilities and labor-dependent legacy sites. High-end operators in London and Singapore deploy these systems to compress energy intensity per member visit while budget competitors absorb margin erosion through reduced staffing. The technology is bifurcating competitive positioning by embedding fixed-cost advantages that compound across multi-site portfolios.
REACH chemical restriction expansions and F-Gas Regulation phase-down schedules are forcing aquatic center operators to accelerate refrigerant transition timelines and document substance inventories for regulatory filing. Pool dehumidification system manufacturers face compressed product development cycles to qualify alternative refrigerants with equivalent thermodynamic performance. German and French operators bear the heaviest compliance burden due to national implementation schedules preceding EU-wide harmonization.
Membership procurement is fragmenting away from annual contract lock-in toward flexible access subscriptions and day-pass aggregation platforms that disintermediate traditional sales channels. Boutique fitness independents and hotel wellness operators in Johannesburg and Singapore deploy these models to capture trial users before conversion to recurring revenue. The shift compresses customer acquisition cost recovery timelines and elevates retention marketing expenditure as a percentage of operating budgets.
Leisure Centers Market Segmentation
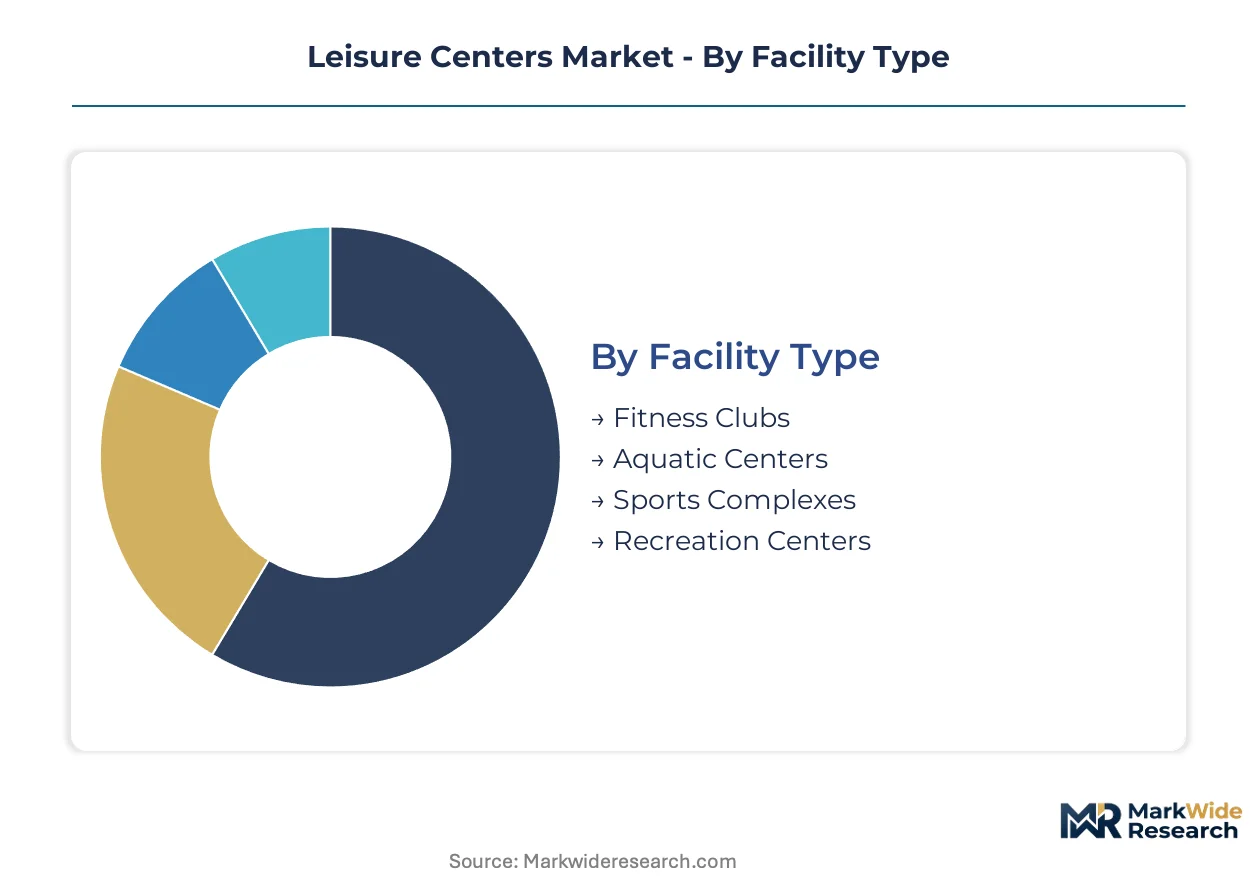
Segmentation in leisure centers reveals how capital allocation, membership economics, and regulatory compliance fragment across distinct operational models. Each dimension shapes facility design standards, staffing ratios, and revenue recognition patterns differently.
Facility Type:
Fitness clubs and aquatic centers flow through recurring membership channels with predictable cash conversion cycles, while sports complexes and recreation centers rely on event-based and municipal contract revenue streams with lumpier timing.
- Fitness Clubs:Engineered HVAC loads of 25-50 watts per square foot support high-occupancy training floors with engineered air turnover rates. Demand concentrates in the United States and Germany where employer-sponsored wellness subsidies and aging demographic profiles sustain utilization rates above industry benchmarks.
- Aquatic Centers:Pool evaporation recovery systems and F-Gas Regulation-compliant dehumidification infrastructure dominate capital planning. German and French operators face compressed refrigerant transition timelines under national implementation schedules preceding EU-wide harmonization.
- Sports Complexes:Tournament-grade facilities command premium hourly rentals from youth travel team leagues and corporate wellness contracts.
- Recreation Centers:Municipal margin pools where operating subsidies and grant financing obscure true profitability but secure long-term land access.
By volume, Fitness Clubs leads. By growth pace, Sports Complexes is ahead.
Service Offering:
Cost tier differentiation separates capital-intensive spa infrastructure from labor-dependent personal training, with membership plans anchoring baseline revenue and ancillary services capturing margin expansion.
- Membership Plans:Access-controlled recurring revenue models with annual contract lock-in or flexible subscription formats. Budget operators in suburban United States corridors rely on high-volume, low-price positioning while premium clubs in London and Singapore deploy day-pass aggregation platforms to capture trial users.
- Personal Training:One-to-one programming with certified staff generating per-session economics above base membership. Staffing bottlenecks from state health department licensure requirements limit operating hour expansion in aquatics-dependent facilities.
- Group Classes:Studio-based programming competing directly with boutique fitness independents in design-forward concepts.
- Spa Services:High-margin ancillary revenue requiring dedicated wet infrastructure and trained therapy staff.
Membership Plans generates the highest absolute revenue. Spa Services delivers the steepest margin per square foot.
Age Group:
Customer lifecycle positioning shapes programming intensity, with children and teens driving family club format economics and seniors commanding specialized low-impact infrastructure.
- Children:Youth programming anchors family-oriented club ecosystems across European suburban corridors with racquet sports integration and tournament league pipelines.
- Teens:Travel team league participation demands broadcast-ready facilities with premium per-hour rental structures.
- Adults:Core membership base for fitness clubs and aquatic centers where retention economics dominate capital planning.
- Seniors:Low-impact programming with specialized equipment and modified pool temperature protocols.
Adults represents the largest addressable population. Children is expanding most quickly through family membership bundling.
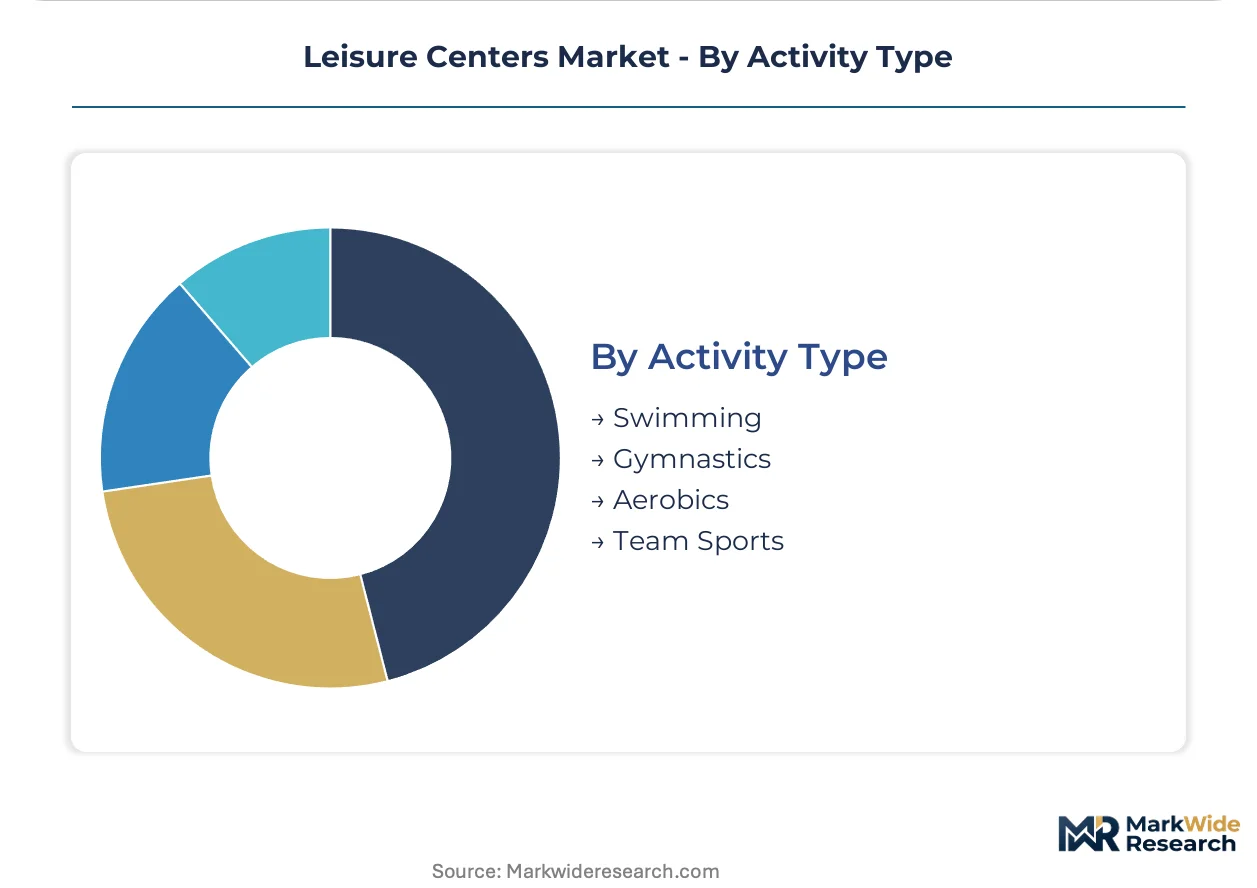
Activity Type:
Application-driven facility design concentrates investment in wet infrastructure for swimming versus dry-floor systems for gymnastics and team sports, with aerobics requiring minimal dedicated capital.
- Swimming:Purpose-built natatorium construction with engineered gutter systems, bulkhead flexibility for lane configuration, and OSHA-compliant pool chemistry monitoring stations. EU Green Deal building performance mandates accelerate HVAC and evaporation recovery retrofits.
- Team Sports:Hardwood or synthetic court surfaces with broadcast lighting and spectator seating for tournament-grade complexes. Corporate wellness contracts in the United States command premium rental rates for private league play.
- Gymnastics:Spring-floor systems, pit infrastructure, and spotting equipment with specialized liability coverage requirements.
- Aerobics:Minimal capital dry-floor programming convertible across multiple studio configurations.
Swimming absorbs the highest capital per participant. Team Sports captures the fastest rental rate appreciation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in leisure center infrastructure tilt toward capital equipment imports in emerging markets while mature economies export operational expertise through management contracts. Facility development capital originates disproportionately from United States, German, and Chinese institutional investors seeking yield in stabilized wellness real estate.
United States
Employer-sponsored wellness subsidies and aging demographic profiles sustain utilization rates above industry benchmarks across Texas and Florida suburban corridors. OSHA workplace safety standards and state health department pool chemistry protocols dictate staffing ratios and certification requirements. The Southeast region anchors family-oriented club expansion with racquet-sports-integrated formats targeting youth travel team leagues.
Germany
Municipal governments leverage public-private partnerships to transfer operational risk while retaining land access and community goodwill in Bavaria and North Rhine-Westphalia. EU Green Deal building performance standards and national F-Gas Regulations force accelerated HVAC and pool dehumidification retrofits. The Rhine-Ruhr metropolitan region concentrates tournament-grade sports complex development commanding premium hourly rentals.
China
Urban density patterns and dual carbon goals reshape capital allocation toward energy-efficient mixed-use wellness districts in Yangtze River Delta clusters. The country's national building performance regulator enforces stringent HVAC efficiency mandates for new commercial construction. Shanghai and Shenzhen lead design-forward studio concepts competing directly with boutique fitness independents for affluent professional segments.
United Kingdom
Flexible access subscriptions and day-pass aggregation platforms disintermediate traditional sales channels across Greater London and Manchester. REACH chemical restrictions and pending F-Gas phase-down schedules compress refrigerant transition timelines for aquatic center operators. The Southeast corridor lacks racquet-sports-integrated family club formats that dominate European exurban positioning.
Australia
Corporate wellness contracts from mining and professional services sectors command premium facility rental rates in Perth and Brisbane. The country's national building regulator enforces thermal performance standards for commercial aquatic facilities. New South Wales and Victoria concentrate smart building management system deployment with real-time occupancy sensing and predictive HVAC load balancing.
Leisure Centers Market Competitive Landscape
Concentration sits with vertically integrated real estate developers and specialized racquet-sports operators rather than pure-play fitness chains. The vendor base spans three distinct tiers: premium hospitality-integrated wellness resorts, mid-market family club ecosystems, and budget high-volume access models. Strategic archetypes include mixed-use district developers, suburban corridor specialists, and boutique studio disrupters. Dominant competitive moves encompass backward integration into captive real estate development and technology licensing for automated facility management systems.
Within the premium hospitality-integrated tier, Life Time Inc. and Equinox Holdings exemplify vertically structured operators combining fitness, workspace, and residential amenities under single-roof formats. David Lloyd Leisure anchors the European family club archetype through racquet-sports-centered suburban ecosystems. Virgin Active occupies a design-forward positioning competing with independent boutiques in London, Singapore, and Johannesburg. Budget volume operators including Planet Fitness and LA Fitness exemplify high-member-count, low-price-point models dependent on automated access control and minimal staffing ratios.
| Leading Market Players |
|---|
| Life Time Inc. |
| David Lloyd Leisure |
| Virgin Active |
| Planet Fitness |
| LA Fitness |
| Equinox Holdings |
| Gold's Gym |
| Merlin Entertainments |
| YMCA |
| Others |
Supply & Pricing Matrix
Scale economies in HVAC and aquatic system manufacturing concentrate supply capacity among German and Chinese equipment producers, compressing price floors for facility operators while elevating procurement leverage for multi-site portfolio owners. Municipal bond financing conditions and construction labor scarcity feed back into equipment specification choices, favoring retrofit-ready systems over purpose-built installations.
Pricing Analysis
Municipal governments and school districts anchor three-tier pricing structure across premium, standard, and economy levels through public-private partnership tender processes. Price differentiation stems from certification grade under EU Green Deal building performance standards and volume scale across multi-facility portfolios. Pricing pressure stems from F-Gas Regulation compliance costs compressing refrigerant availability. Budget operators in suburban United States corridors exhibit highest price sensitivity, while premium hospitality-integrated wellness resorts in London and Singapore absorb cost premiums for design-forward positioning.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for pool dehumidification systems and smart building management components. Manufacturing concentrates in Germany, China, and the United States for HVAC equipment, with France and Italy contributing specialized aquatic infrastructure. Raw material dependencies include copper refrigerant tubing, aluminum heat exchangers, and semiconductor sensors for occupancy detection. Single-source vulnerability sits with EU F-Gas phase-down schedules compressing alternative refrigerant qualification timelines. Distribution runs through direct OEM relationships for premium tier operators and regional equipment distributors for budget competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leisure center infrastructure sits in early-cycle expansion as municipal wellness mandates and employer-sponsored fitness subsidies penetrate secondary metropolitan rings. Public-private partnership proliferation accelerates capital deployment without full municipal balance-sheet commitment.
For Market Incumbents: Shield market position through backward integration into captive real estate development combining fitness, workspace, and hospitality under single-roof formats. Consolidate racquet-sports-integrated suburban ecosystems in European corridors where David Lloyd Leisure has established format dominance. Counter boutique fitness disrupters in London and Singapore through technology licensing for automated facility management systems that compress energy intensity per member visit.
For New Entrants and Emerging Players: Corporate wellness contract under-penetration offers white-space targeting in the United States mining and professional services sectors, where employer-sponsored fitness access programs command premium facility rental rates. Secondary metropolitan rings in Germany and the United States lack racquet-sports-integrated family club formats. Deploy heat pump and thermal storage convergence as entry wedge, enabling demand-response revenue participation and utility incentive capture that legacy operators have deferred.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated real estate developers with automated facility management system deployment over pure-play fitness chains dependent on labor-intensive operations. Long-term viability rests on portfolio operators capturing fixed-cost advantages from smart building management systems that compound across multi-site networks. Watch municipal bond market conditions as inflection indicator for greenfield development versus retrofit capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Public-Private Partnership Expansion | Municipal governments in Bavaria and Texas transfer operational risk while retaining land access and community goodwill. |
| HVAC Electrification Retrofit | EU Green Deal mandates force F-Gas-compliant dehumidification system replacement across German and French aquatic centers. |
| Smart Building Management Deployment | Real-time occupancy sensing in New South Wales and Victoria compresses energy intensity per member visit. |
| Corporate Wellness Contract Capture | Employer-sponsored programs in Perth and Brisbane command premium hourly rental rates above individual membership economics. |
| Racquet-Sports Integration Format | Suburban corridor saturation gaps in Southeast United States and Rhine-Ruhr region enable family club ecosystem expansion. |
Research Methodology
A spread of perspectives from facility operations directors, municipal procurement officers, HVAC equipment manufacturers, aquatic system installers, and commercial real estate developers converged on the working assumptions. Primary interviews combined with secondary validation from EU Green Deal regulatory filings, OSHA workplace safety standards documentation, municipal bond issuance disclosures, and F-Gas Regulation implementation schedules. Bottom-up facility count and utilization rate estimates triangulated against top-down construction spending data and wellness real estate investment flows.
Segmentation dimensions modeled include facility type, service offering, age group targeting, and activity type across the projection horizon. CAGRs derived from facility utilization rate trajectories, membership pricing elasticity estimates, and capital expenditure cycle timing. Industry-specific forecast inputs encompass public-private partnership proliferation rates and EU building performance mandate compliance deadlines.
Material uncertainties — municipal fiscal stress, refrigerant supply disruption, construction labor availability — sit outside the modeled envelope. Forecasts reflect assumptions about policy continuity and technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
North America Climbing Gears Market